
 Tritium Light Source Market | 2026-2036
Tritium Light Source Market Size, Share, and Industry Trends Forecast 2026-2036
Tritium Light Source Market Outlook
Aftermarket service revenue for tritium capsule replacement and recertification is reshaping margin distribution across the value chain. SRB Technologies dominates North American military and aviation refurbishment contracts through captive regulatory compliance capabilities. Trijicon anchors premium firearm optics demand with specialized tritium-phosphor vial integration that sustains luminosity across extreme operational temperatures. MB Microtec AG competes in European industrial safety marking through precision borosilicate glass encapsulation and ISO-certified manufacturing scale.
Tritium light sources are sealed glass tubes coated internally with phosphor and filled with radioactive hydrogen isotope gas, producing continuous visible illumination through beta decay without electrical input, primarily serving applications requiring fail-safe visibility in darkness, smoke, or power-loss conditions. Self-luminous signs command the largest product segment share due to mandatory egress marking in commercial aviation and maritime vessels where electrical backup systems introduce single-point failure risk. Defense end-user demand leads volume consumption as military specification sighting systems and navigation instruments require decade-long operational reliability without battery dependency. Fixed installations anchor the installation category, though portable devices in mining headlamps and tactical equipment represent the fastest-growing configuration as workforce mobility standards tighten.
US Nuclear Regulatory Commission licensing governs tritium possession thresholds and disposal protocols, directly constraining market entry for non-compliant manufacturers. EMA and national radiological protection authorities across Germany, France, and the United Kingdom enforce transport and workplace exposure limits that shape product design and regional supply chain configuration. Stakeholders must monitor evolving classification of tritium under EU REACH substance restrictions and corresponding adaptation of alternative radioluminescent formulations.
Market Dynamics
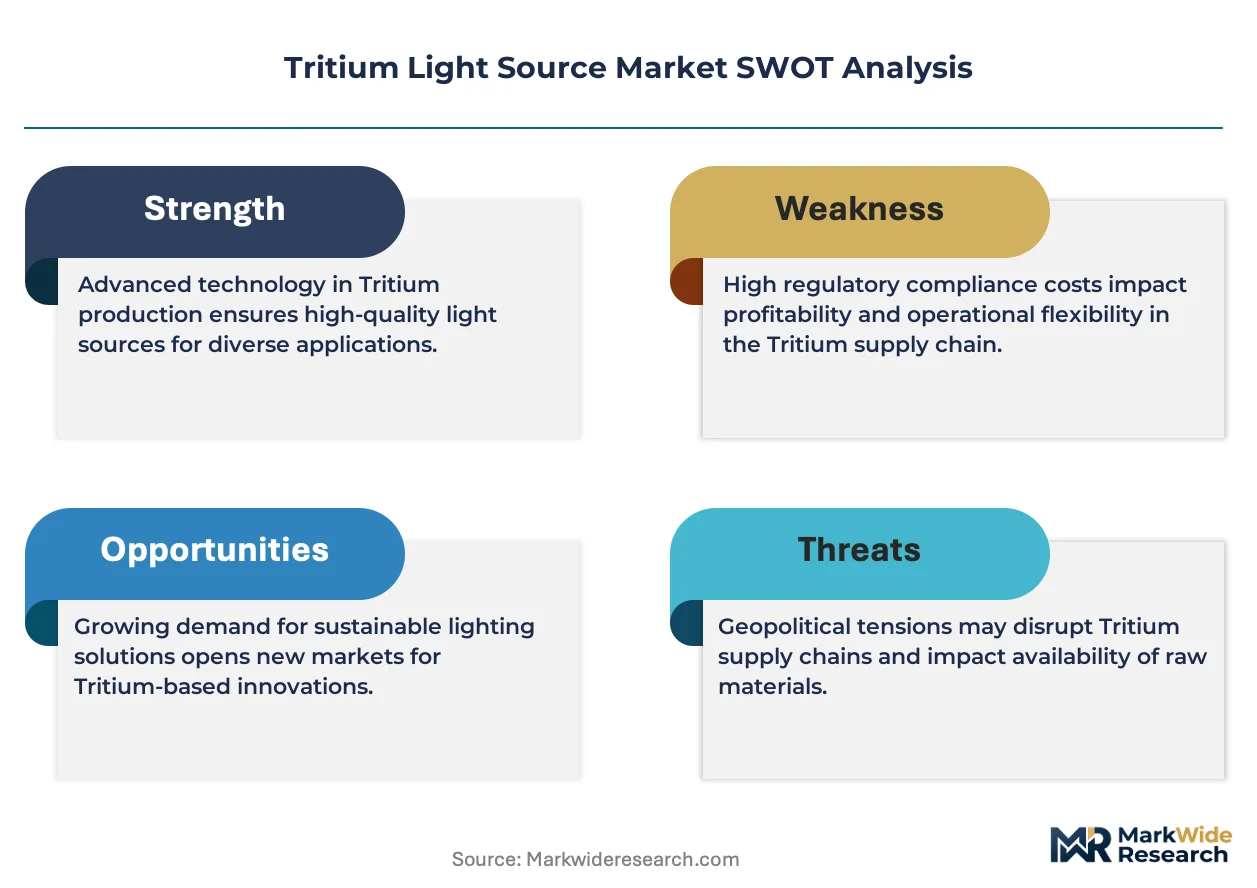
Defense procurement programs across NATO member states are expanding adoption of tritium-illuminated sighting systems and exit signage. Regulatory tightening around phosphorescent alternatives under EU REACH and F-Gas frameworks is redirecting specification toward sealed gaseous tritium light sources.
Growth Catalysts
- EU REACH substance restrictions:Regulatory tightening around phosphorescent alternatives under REACH and F-Gas frameworks is redirecting specification toward sealed gaseous tritium light sources for mandatory egress marking.
- Military modernization budgets:Defense procurement programs across NATO member states are expanding adoption of tritium-illuminated sighting systems requiring decade-long operational reliability without battery dependency.
- Borosilicate glass encapsulation:Precision glass manufacturing advances are enabling thinner-walled, higher-luminosity vials that reduce material content while maintaining structural integrity across temperature extremes.
Market Restraints
- Tritium supply concentration:Commercial tritium production concentrates at heavy water reactor facilities in Canada and Romania, creating geographic single-source vulnerability for global light source manufacturers.
- US Nuclear Regulatory Commission licensing:Possession thresholds and disposal protocols directly constrain market entry for non-compliant manufacturers, raising fixed compliance costs for new entrants.
- LED emergency lighting substitution:Battery-backed solid-state systems are capturing price-sensitive commercial building segments where electrical infrastructure reliability reduces the premium on self-luminous failure independence.
Strategic Opportunities
- Aviation aftermarket refurbishment:Commercial aircraft fleet renewal cycles are creating sustained demand for tritium exit sign recertification and capsule replacement services.
- Mining workforce mobility standards:Underground safety regulations in Australia and Chile are mandating personal illumination devices that operate without electrical ignition risk in explosive atmospheres.
- Dual-carbon regulatory alignment:China's MEE emissions frameworks are restricting phosphor manufacturing effluents, creating opening for imported sealed-source alternatives in industrial safety marking.
Industry Challenges
- Radiological handling certification:Technician licensing requirements for tritium capsule replacement are creating workforce bottlenecks that extend service lead times and inflate labor costs.
- Legacy inventory reconciliation:Decades of dispersed tritium device installation across military and aviation fleets complicates tracking, recertification scheduling, and regulatory audit compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tritium Light Source Market |
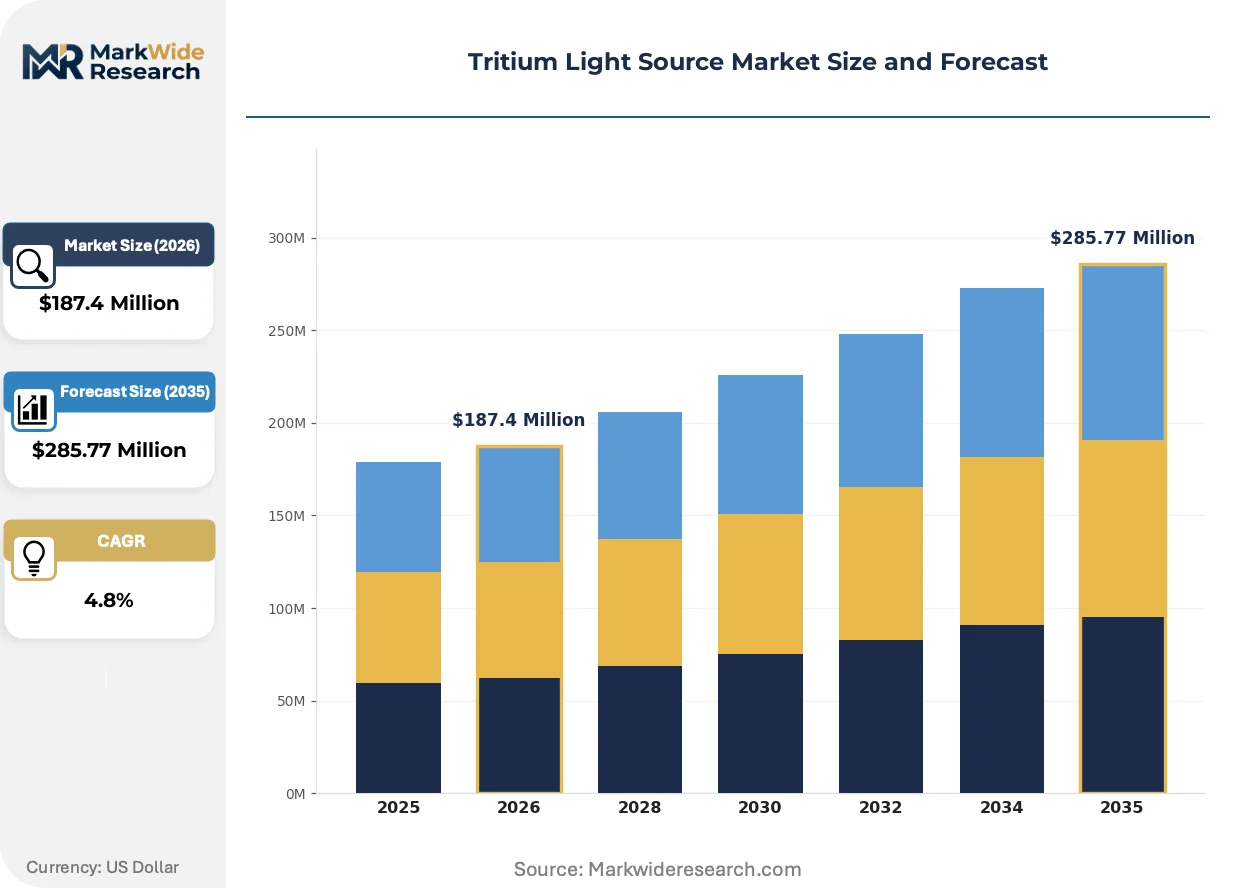
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Luminous Signs, Handheld Devices, Emergency Lighting, Industrial Applications End User: Aerospace, Defense, Mining, Commercial Application: Safety Marking, Navigation, Alarm Systems, Instrumentation Installation: Fixed Installations, Portable Devices, Surface-Mounted, Embedded Systems |
| Companies Covered | SRB Technologies, Trijicon, Betalight B.V., MB Microtec AG, Evenlite, Isolite Corporation, Cammenga Company, ITTSAN GTLS, Shield Source Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tritium Light Source Market Strategic Shifts
Product architecture is compressing around thinner-walled borosilicate encapsulation and precision phosphor deposition techniques that extend service intervals. Manufacturing process control and regulatory compliance automation are emerging as primary differentiation vectors.
Thin-walled borosilicate micro-vials with optimized phosphor deposition density are collapsing the historical trade-off between luminosity output and tritium gas inventory. Defense optics manufacturers are adopting these geometries for next-generation weapon sighting systems. The technology is collapsing material input requirements per unit of visible output, reshaping cost structures and regulatory exposure calculations.
EU F-Gas Regulation phase-down schedules are accelerating substitution away from tritium-containing fire suppression systems in enclosed spaces, but simultaneously tightening phosphorescent pigment manufacturing emissions standards. Industrial safety marking procurement is responding by specifying sealed gaseous sources that bypass wet chemistry processing entirely. German industrial facility operators are leading this specification pivot under BfS radiological workplace exposure guidelines.
Aftermarket service unbundling is separating hardware procurement from recertification and disposal liability. Aviation maintenance providers are contracting dedicated radiological service partners rather than maintaining in-house tritium handling capabilities. This pattern concentrates most visibly in United States commercial aviation hubs where FAA-approved repair station certification creates vendor stickiness and multi-year service lock-in.
Tritium Light Source Market Segmentation
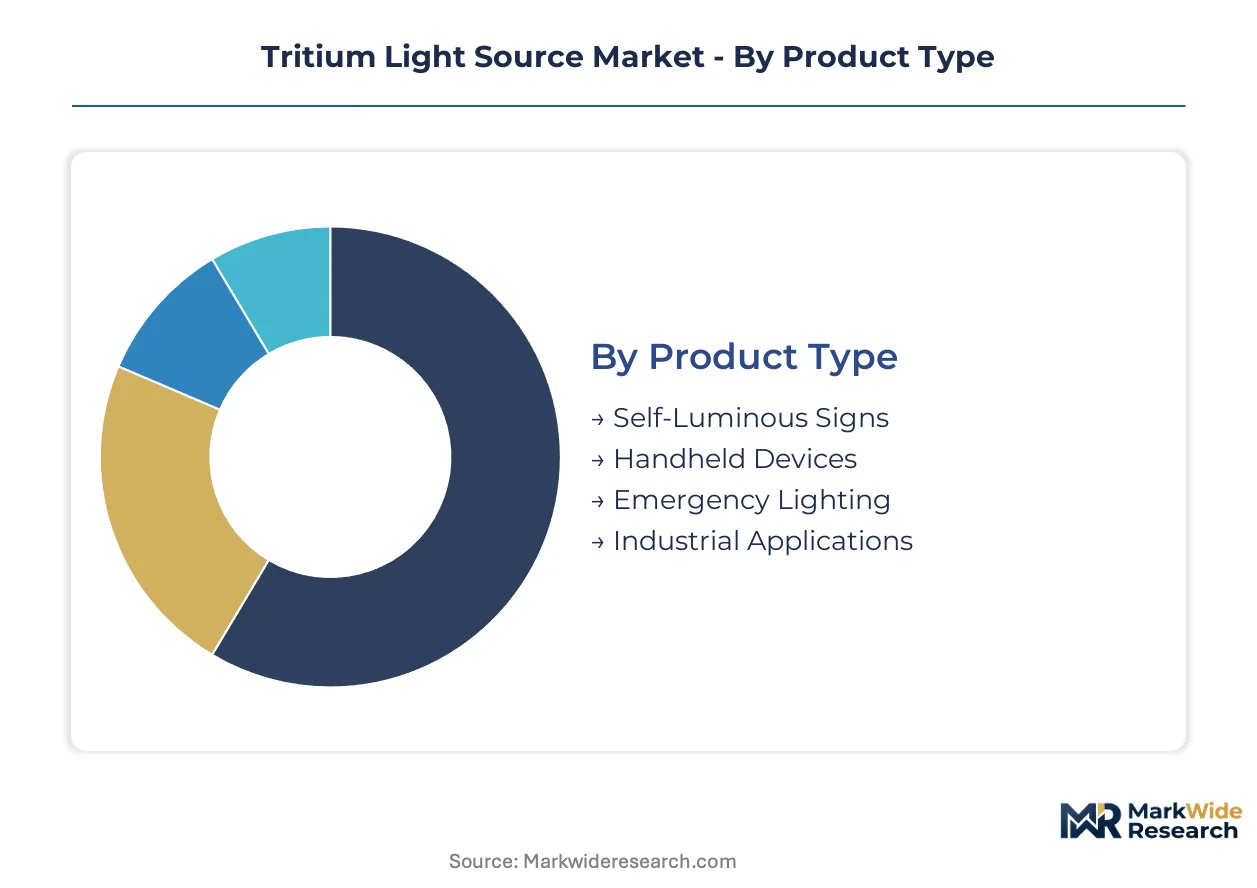
Product architecture and end-use requirements fragment the Tritium Light Source Market into distinct specification tiers. Each dimension carries unique regulatory exposure, procurement patterns, and service lifecycle economics that shape vendor positioning.
Product Type:
Cost tier stratification separates premium sealed-source systems from commodity alternatives, with material content and certification grade driving price multiples.
- Self-Luminous Signs:Borosilicate glass tubes with internal phosphor coating provide continuous egress illumination without electrical input. Commercial aviation fleet operators in the United States and Germany specify these for cabin emergency marking where FAA and BfS regulations mandate fail-safe visibility.
- Handheld Devices:Compact tritium vials integrate into personal illumination tools for explosive atmosphere environments. Australian and Chilean mining safety regulators are mandating these configurations underground where battery ignition risks are prohibited.
- Emergency Lighting:Standalone exit signage systems for commercial building infrastructure.
- Industrial Applications:Process instrumentation and control panel illumination for heavy manufacturing facilities.
Self-Luminous Signs hold installed capacity. Handheld Devices is rotating up the share rankings.
End User:
Application context determines performance specifications, with defense and aerospace procurement imposing the most stringent operational reliability standards.
- Defense:Weapon sighting systems and navigation instruments require decade-long luminosity maintenance across temperature extremes from -40°C to 70°C. NATO procurement programs in the United States, United Kingdom, and Germany are expanding specifications for tritium-illuminated combat optics.
- Aerospace:Commercial aircraft cabin signage and cockpit instrumentation demand FAA and EASA recertification protocols. United States and French aviation maintenance providers are unbundling hardware procurement from radiological service contracts.
- Mining:Personal safety equipment for underground workforce mobility.
- Commercial:Building egress marking and industrial facility safety systems.
Defense holds installed capacity. Mining is rotating up the share rankings.
Application:
Functional use case dictates vial geometry, luminosity output requirements, and replacement interval scheduling.
- Safety Marking:Exit signage and hazard warning systems for enclosed spaces. German industrial facility operators under BfS guidelines are specifying sealed gaseous sources to bypass phosphorescent pigment manufacturing emissions.
- Navigation:Marine and aviation compass illumination requiring omnidirectional visibility. Maritime vessel operators in the United States and United Kingdom mandate these for bridge instrumentation where electrical backup failure risks are unacceptable.
- Alarm Systems:Visual alert indicators for fire safety and emergency notification.
- Instrumentation:Dial and gauge illumination for process control equipment.
Safety Marking holds installed capacity. Navigation is rotating up the share rankings.
Installation:
Configuration determines regulatory handling classification and service accessibility economics.
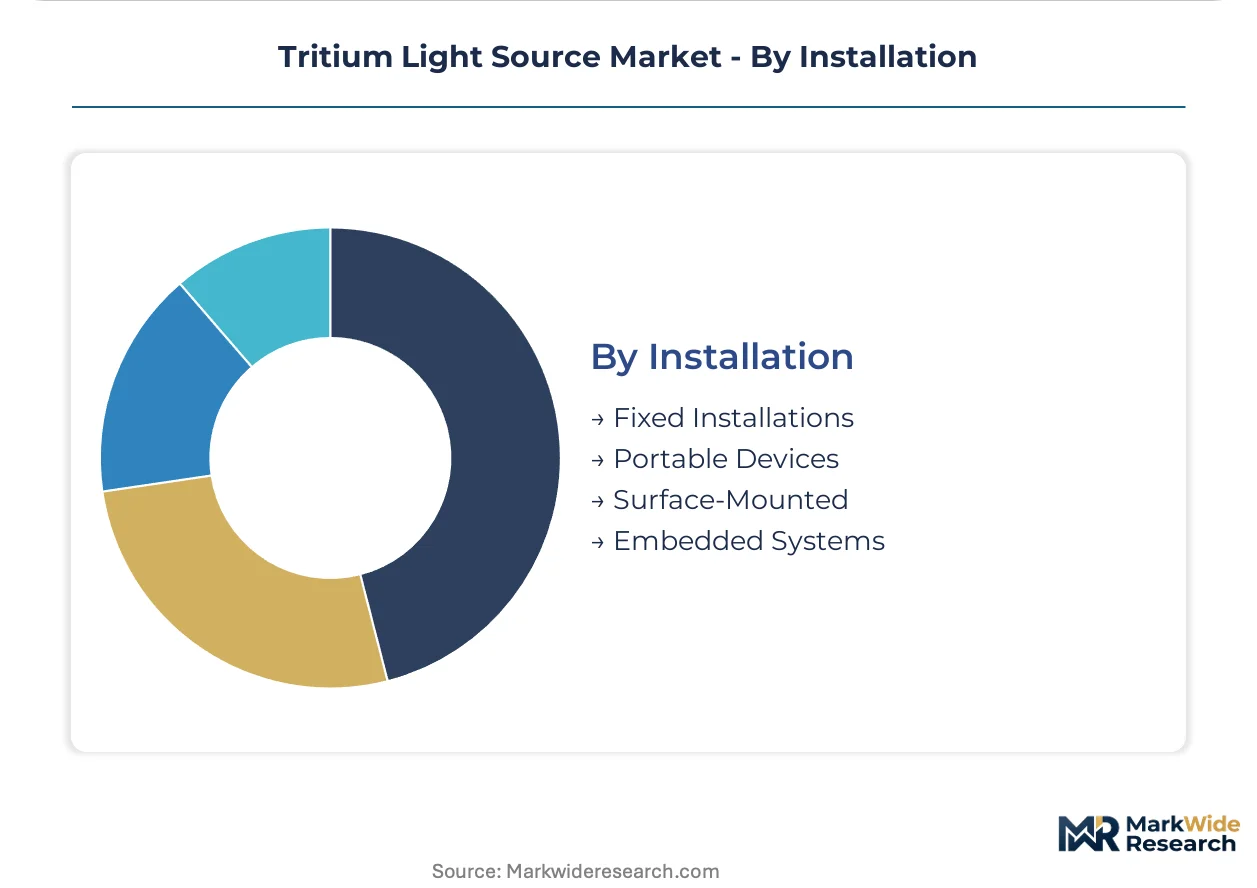
- Fixed Installations:Permanently mounted egress signage and infrastructure lighting in commercial buildings and transportation hubs. United States commercial aviation hubs concentrate refurbishment demand where FAA-approved repair station certification creates vendor concentration.
- Portable Devices:Personal equipment and tactical gear requiring field replacement capability. Mining workforce mobility standards in Australia are mandating these configurations for underground personal illumination.
- Surface-Mounted:Externally attached signage and instrumentation housings.
- Embedded Systems:Integrated vial placement within manufactured products.
Fixed Installations hold installed capacity. Portable Devices is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement elasticity varies sharply across geographies. United States buyers prioritize decade-long reliability over unit cost, while commercial building operators in price-sensitive markets substitute battery-backed LED systems where electrical infrastructure permits.
United States
Military modernization budgets sustain the largest installed base of tritium-dependent safety equipment. FAA regulations mandate fail-safe cabin emergency marking for commercial aviation fleets. Maintenance providers in Dallas-Fort Worth and Seattle-Tacoma aviation hubs concentrate refurbishment demand where repair station certification creates vendor concentration.
Germany
Industrial facility operators under BfS radiological workplace exposure guidelines are specifying sealed gaseous sources for safety marking. EU REACH substance restrictions redirect procurement away from phosphorescent alternatives. Manufacturing clusters in Bavaria and Baden-Württemberg anchor precision borosilicate glass encapsulation capacity.
United Kingdom
NATO defense procurement programs are expanding specifications for tritium-illuminated combat optics and navigation instruments. National radiological protection authorities enforce transport and workplace exposure limits shaping product design. Aerospace maintenance activity concentrates around London Gatwick and Manchester where EASA recertification protocols apply.
Australia
Mining workforce mobility standards are mandating personal illumination devices that operate without electrical ignition risk in explosive atmospheres. The country's national radiological protection regulator enforces possession thresholds and disposal protocols for underground safety equipment. Western Australia and Queensland mining belts drive portable device demand.
Canada
Commercial tritium production at heavy water reactor facilities creates geographic supply concentration for global light source manufacturers. Health Canada regulates possession thresholds and disposal protocols constraining market entry. Ontario's nuclear infrastructure sustains raw material availability for North American defense and aviation supply chains.
Tritium Light Source Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. The vendor base organizes around regulatory compliance expertise versus manufacturing throughput. Three archetypes dominate: captive regulatory service providers, precision glass encapsulation specialists, and defense optics integrators. Strategic moves center on unbundling aftermarket service contracts and compressing phosphor deposition process cycles.
Within the regulatory-captive tier, SRB Technologies exemplifies North American military and aviation refurbishment positioning through compliance infrastructure. Trijicon occupies a position in premium firearm optics demand. MB Microtec AG represents European industrial safety marking specialization through ISO-certified manufacturing scale.
| Leading Market Players |
|---|
| SRB Technologies |
| Trijicon |
| Betalight B.V. |
| MB Microtec AG |
| Evenlite |
| Isolite Corporation |
| Cammenga Company |
| ITTSAN GTLS |
| Shield Source Inc |
| Others |
Value Chain & Pricing Dynamics
Ontario's heavy water reactor facilities govern raw material availability for North American defense and aviation supply chains, concentrating upstream pricing power among tritium processors who negotiate long-term offtake agreements with light source manufacturers.
Pricing Analysis
Aftermarket service revenue for capsule replacement and recertification drives lifetime value beyond initial hardware transactions. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified aviation refurbishment from commercial building exit signage and mining personal illumination devices. Cost compression in commercial building segments intensifies because battery-backed LED systems capture price-sensitive procurement where electrical infrastructure reliability reduces the premium on self-luminous failure independence. Mining safety officers in Australia and Chile exhibit lowest price sensitivity due to regulatory mandates prohibiting electrical ignition risks in explosive atmospheres.
Supply Chain Analysis
Single-source vulnerability in commercial tritium production dominates supply chain risk assessment for global light source manufacturers. Manufacturing concentrates in Canada, Romania, and Germany, with heavy water reactor facilities in Ontario and Cernavodă feeding borosilicate glass encapsulation specialists in Bavaria and Baden-Württemberg. Raw material dependencies rest on gaseous tritium isotope, precision phosphor deposition chemicals, and borosilicate glass tubing rated for radiological containment. Distribution runs through defense procurement channels, FAA-approved aviation repair stations, and industrial safety equipment distributors serving mining and commercial building end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recertification and disposal service contracts expand faster than hardware sales as aviation maintenance providers unbundle radiological handling from in-house capabilities, creating sticky multi-year revenue streams.
For Market Incumbents: Pre-empt LED substitution threats in commercial building segments by bundling extended recertification contracts with initial hardware procurement. Captive regulatory compliance infrastructure in Dallas-Fort Worth and Seattle-Tacoma aviation hubs anchors customer lock-in. Backward integration into precision borosilicate glass encapsulation protects margin compression from German and Swiss glass specialists. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point where electrical infrastructure unreliability sustains demand for self-luminous egress marking but price-sensitive procurement favors lower-cost sealed-source alternatives over premium aviation-grade systems. Australian and Chilean mining workforce mobility standards mandate personal illumination devices without electrical ignition risk, creating regulatory-forced demand independent of price competition. Partner with established radiological service providers rather than building in-house tritium handling capabilities. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-captive service play because possession thresholds and disposal protocols under US Nuclear Regulatory Commission licensing and national radiological protection authorities across Germany, France, and the United Kingdom constrain market entry and sustain incumbent pricing power. Target acquisition profiles center on FAA-approved repair stations with established aviation maintenance contracts and captive tritium handling workforces. Monitor EU REACH substance restriction evolution as the signal to watch for alternative radioluminescent formulation disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Automation | Automated tracking systems reduce technician licensing bottlenecks extending service lead times under US NRC protocols. |
| Aftermarket Service Unbundling | Separate hardware procurement from recertification liability concentrates vendor stickiness in United States aviation hubs. |
| Precision Glass Encapsulation Scale-Up | Thinner-walled borosilicate micro-vials reduce material content while maintaining structural integrity across temperature extremes. |
| Phosphor Deposition Process Compression | Optimized deposition density collapses historical trade-off between luminosity output and tritium gas inventory. |
| Dual-Carbon Regulatory Alignment | China's MEE emissions frameworks restricting phosphor manufacturing effluents create openings for imported sealed-source alternatives. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with defense procurement officers, aviation maintenance directors, mining safety regulators, and borosilicate glass manufacturing specialists; and secondary validation against US Nuclear Regulatory Commission licensing databases, FAA repair station certification records, EU REACH substance restriction filings, and ECHA regulatory guidance documents. Bottom-up triangulation across product type, end-user segment, application function, and installation configuration reconciled with top-down macroeconomic drivers.
Forecast inputs considered defense modernization budget trajectories across NATO member states, commercial aviation fleet renewal cycles, mining workforce mobility regulatory evolution in Australia and Chile, and EU F-Gas Regulation phase-down schedules. Segmentation dimensions modeled encompass product architecture tiers, end-use reliability requirements, installation configuration regulatory handling classifications, and regional procurement pattern clusters. CAGRs were derived from installed base depreciation schedules, replacement interval economics, and specification shift elasticities.
Practitioners should monitor EU REACH tritium classification evolution, heavy water reactor facility operational status in Canada and Romania, and LED emergency lighting substitution rates in commercial building segments for early signals requiring forecast reassessment. Material shifts in regulatory substance restrictions, raw material production concentration, or alternative technology cost-performance ratios would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Bulb Market
Lighting
Circadian Lighting Market
Lighting
Gesture Control Light Market
Lighting
Display Light Control Film Market
Lighting
Lighting Control Components Market
Lighting
LED Eye Protection Lamp Market
Lighting
India Lighting Market
Lighting
Dimmer and Color Tunable Market
Lighting
Fluorescent Lighting Market
Lighting
Flexible Lighting Foils Market
Lighting
Ultraviolet Lamps Market
Lighting
Softbox Lighting Kit Market
Lighting
High-End Lighting Market
Lighting
Street and Roadway Lighting Market
Lighting
Global Work Lights Market
Lighting
Specialty Lighting Market