
 Field Inspection Tester Market | 2026-2036
Field Inspection Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Field Inspection Tester Market Analysis
Equipment leasing and asset-light service models are narrowing the competitive field for capital-intensive field inspection systems. SGS leverages its global certification network to bundle testing services with equipment deployment, reducing upfront barriers for mid-sized contractors. HUMBOLDT Mfg. CO. anchors its position through backward integration into calibration laboratories, ensuring traceability that rental fleets require. Cooper Technology specializes in geotechnical applications where leased instrumentation dominates project-based workflows across European infrastructure programs.
A field inspection tester comprises portable or fixed instrumentation designed to evaluate material properties, structural integrity, or environmental conditions against defined engineering parameters, typically operating with measurement resolutions of 0.1 mm displacement or 1 MPa stress accuracy for quality assurance and safety verification in civil and industrial settings. Ultrasonic and electromagnetic technologies now dominate non-destructive evaluation due to their compatibility with in-situ concrete and steel assessment without material extraction. Portable testers lead product-type demand in construction and energy end-use sectors where site mobility determines operational throughput, while inspection systems command premium positioning in manufacturing environments requiring automated compliance documentation.
FDA oversight of diagnostic instrument accuracy and OSHA workplace exposure standards directly shape product certification requirements for field-deployed testing equipment in the United States. The EU Green Deal and CE marking under the Construction Products Regulation mandate energy-efficient instrumentation and interoperable data formats for cross-border infrastructure projects across Germany, France, and Italy. Stakeholders must monitor evolving calibration reciprocity agreements between national metrology institutes to anticipate where localized service footprints will become mandatory for market access.
Market Dynamics
Equipment leasing models are compressing ownership economics for field inspection systems, forcing manufacturers to restructure revenue around service attach rates and calibration subscriptions rather than hardware margins alone.
Growth Catalysts
- OSHA workplace exposure standards:Mandates for documented structural integrity verification in US construction are expanding deployment of portable ultrasonic testers across bridge and roadway contractors.
- Germany's infrastructure renewal programs:Federal transport spending concentrates procurement of electromagnetic inspection systems for aging autobahn viaduct assessment.
- Ultrasonic phased-array technology:Advances in beam steering resolution enable single-device replacement of multiple conventional NDT instruments, accelerating site throughput.
Market Restraints
- Calibration laboratory concentration:Traceable metrology services cluster in Germany, Japan, and the United States, creating service-access friction for operators in peripheral markets.
- Specialized technician scarcity:Certification requirements for electromagnetic and ultrasonic equipment operation outpace vocational training pipeline expansion.
- CE marking reciprocity gaps:Divergent national interpretations of the Construction Products Regulation delay cross-border equipment deployment within the European Union.
Strategic Opportunities
- India's smart cities infrastructure:Municipal bond financing for urban transit expansion creates first-mover positioning for inspection-as-a-service providers.
- EU Green Deal procurement mandates:Energy-efficient instrumentation requirements favor suppliers with low-power portable designs certified under updated CE frameworks.
- 5G-enabled remote diagnostics:Real-time data transmission from field sensors to cloud analytics platforms collapses inspection cycle times for distributed asset networks.
Industry Challenges
- ISO 17025 calibration accreditation timelines:Laboratory certification delays of 12-18 months constrain rental fleet expansion into new geographic markets.
- Legacy analog system integration:Contractors with installed bases of mechanical gauges face workflow disruption when adopting digital documentation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Field Inspection Tester Market |
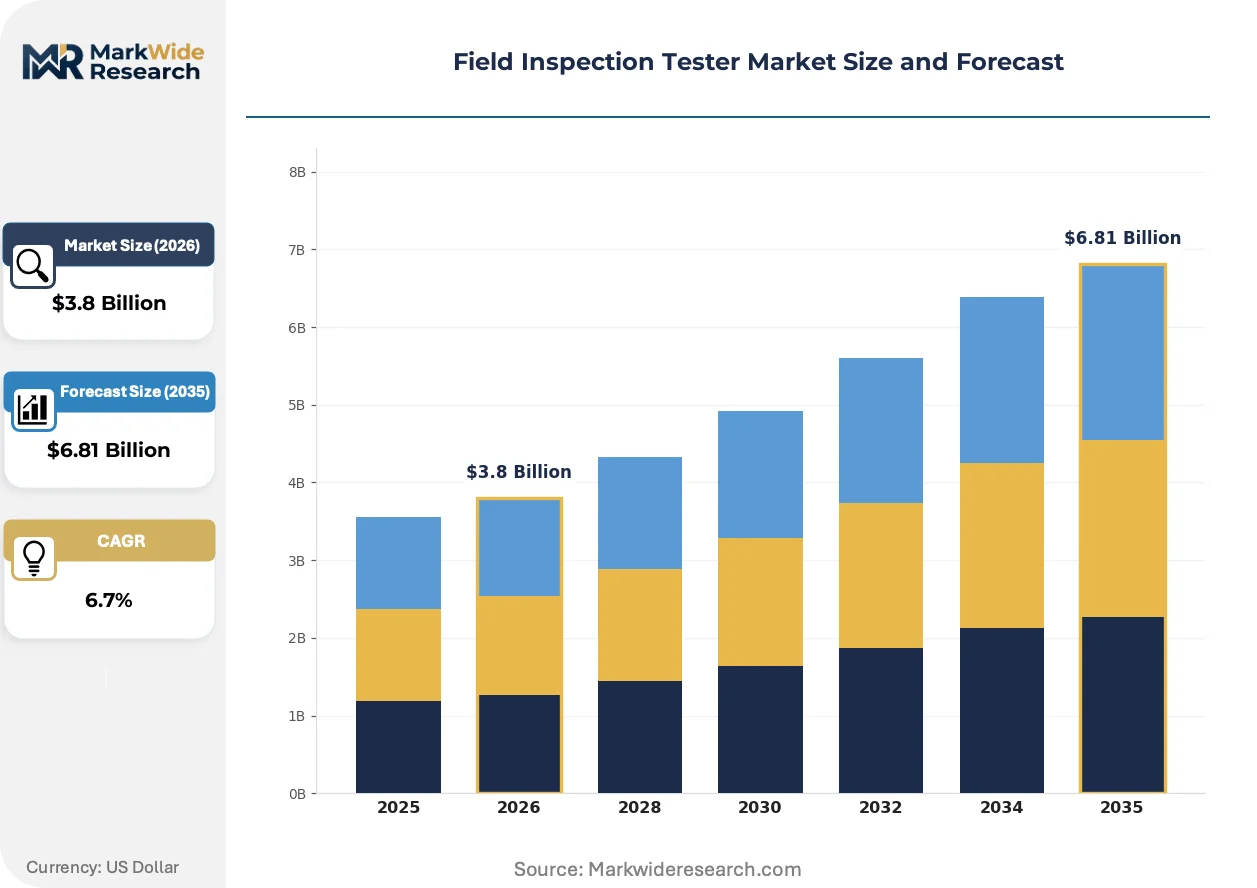
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Testers, Handheld Devices, Diagnostic Instruments, Inspection Systems Technology: Ultrasonic, Electromagnetic, Optical, Thermal Imaging End User: Manufacturing, Construction, Energy, Transportation Application: Quality Assurance, Safety Inspection, Compliance Testing, Maintenance Checks |
| Companies Covered | Controls Group, Roctest, UTEST Material Testing Equipment, ELE International, GEONOR, HUMBOLDT Mfg. CO., Lambda Calibration, Cooper Technology, SGS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Field Inspection Tester Market Emerging Trajectories
Digital thread architectures are threading inspection data directly into building information models, eliminating transcription errors and compressing project handover timelines for infrastructure developers.
Phased-array ultrasonic testing is collapsing the distinction between field screening and laboratory-grade analysis. European bridge inspectors now deploy portable units with 64-element arrays that previously required fixed installation. Site teams eliminate secondary laboratory dispatch for crack characterization, compressing assessment cycles from weeks to hours.
The EU Green Deal's embodied carbon tracking requirements are mandating interoperable data formats for construction materials testing. Equipment suppliers must embed XML-based reporting protocols to maintain CE marking eligibility for German and French public works tenders. Manufacturers with proprietary data silos face exclusion from infrastructure procurement frameworks.
Asset-light service contracts are displacing capital purchase for mid-sized contractors. Japanese construction firms now specify outcome-based inspection programs where providers bear equipment obsolescence risk. Rental penetration concentrates in geotechnical applications where project duration uncertainty favors operational expenditure treatment.
Field Inspection Tester Market Segmentation
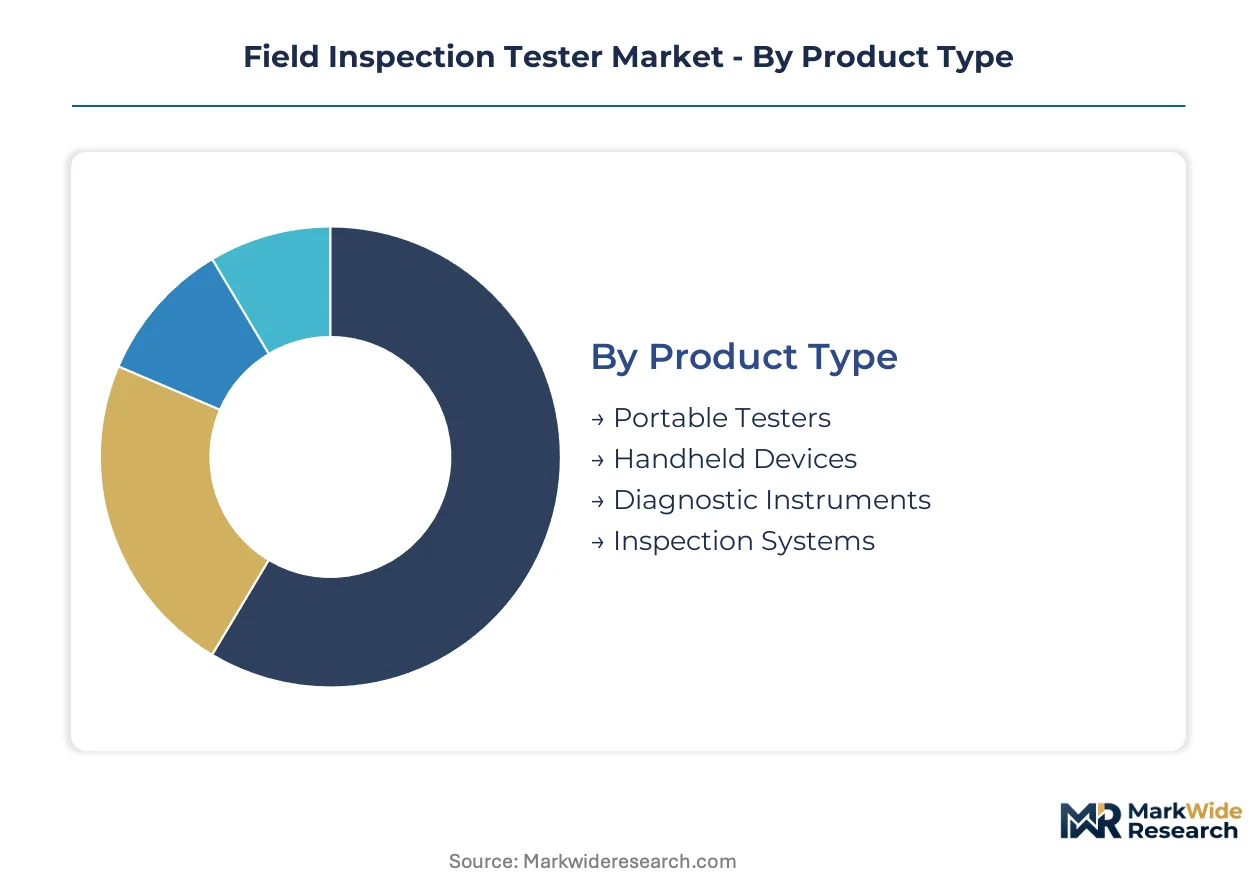
Field inspection tester procurement patterns diver sharply across deployment contexts, with mobility requirements and regulatory stringency dictating equipment specifications. Segmentation reveals how ultrasonic portability commands construction workflows while fixed inspection systems anchor manufacturing compliance documentation.
Product Type:
Cost tier differentiation separates capital-intensive fixed installations from operational-expenditure portable units that dominate project-based contracting.
- Portable Testers:Battery-powered units with 0.1 mm displacement resolution enable same-day mobilization across bridge and roadway sites. Demand concentrates with German and US contractors facing OSHA-mandated structural verification timelines where site-to-site transport determines crew utilization rates.
- Inspection Systems:Automated platforms integrate electromagnetic arrays with cloud documentation for manufacturing quality assurance. Japanese automotive suppliers deploy these for continuous weld monitoring where CE marking and FDA traceability requirements demand archived compliance records.
- Handheld Devices:Single-operator thermal imaging units serve rapid screening protocols in energy sector maintenance rotations.
- Diagnostic Instruments:Laboratory-grade ultrasonic phased-array systems bridge field screening with crack characterization previously requiring secondary dispatch.
Portable testers hold installed capacity. Inspection systems are rotating up the share rankings.
Technology:
Application severity determines sensor selection, with beam steering advances collapsing the distinction between rapid screening and laboratory-grade analysis.
- Ultrasonic:Phased-array configurations with 64-element beam steering replace multiple conventional NDT instruments for in-situ concrete and steel assessment. German autobahn viaduct programs specify these for aging infrastructure evaluation where material extraction is prohibited.
- Electromagnetic:Eddy current and magnetic flux leakage systems penetrate surface coatings for subsurface defect detection in pipeline and pressure vessel inspection. US energy sector procurement favors these for API compliance documentation.
- Optical:Laser triangulation and structured light systems capture dimensional deviation for manufacturing tolerance verification.
- Thermal Imaging:Infrared sensors detect heat signature anomalies in electrical distribution and building envelope assessment.
Ultrasonic equipment holds installed capacity. Electromagnetic systems are rotating up the share rankings.
End User:
Customer type dictates procurement modality, with asset-light rental penetration highest where project duration uncertainty favors operational expenditure treatment.
- Construction:Bridge and roadway contractors facing Germany's infrastructure renewal programs and US OSHA mandates drive portable ultrasonic and electromagnetic deployment. Leasing models dominate as municipal bond financing cycles create irregular equipment utilization.
- Manufacturing:Automotive and aerospace suppliers require automated inspection systems with XML-based reporting protocols for EU Green Deal embodied carbon tracking. CE marking eligibility hinges on interoperable data formats.
- Energy:Pipeline operators and power generation utilities specify handheld thermal and ultrasonic units for scheduled maintenance checks.
- Transportation:Railway and port authorities deploy fixed inspection systems for continuous structural monitoring.
Construction holds installed capacity. Manufacturing is rotating up the share rankings.
Application:
Volume concentration follows regulatory enforcement intensity, with documented compliance requirements expanding faster than discretionary maintenance spending.
- Quality Assurance:Manufacturing integration of inspection data into building information models eliminates transcription errors. European bridge inspectors now embed phased-array results directly into digital thread architectures.
- Safety Inspection:OSHA workplace exposure standards and EU Construction Products Regulation mandates compel documented structural integrity verification. US contractors upgrade testing protocols as federal transport spending expands.
- Compliance Testing:CE marking and FDA oversight requirements shape certification specifications for field-deployed equipment.
- Maintenance Checks:Predictive programs leverage 5G-enabled remote diagnostics for distributed asset networks.
Quality assurance holds installed capacity. Safety inspection is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and the United States where calibration laboratory density and regulatory enforcement intensity sustain premium positioning. Peripheral markets face service-access friction that compresses margins for equipment providers lacking localized metrology partnerships.
United States
Federal transport spending on bridge assessment and OSHA workplace exposure standards drive portable ultrasonic tester deployment across roadway contractors. FDA oversight of diagnostic instrument accuracy shapes certification requirements for field-deployed equipment. Infrastructure clusters in Texas and California anchor procurement volume where municipal bond financing accelerates testing protocol upgrades.
Germany
Federal infrastructure renewal programs concentrate electromagnetic inspection system procurement for aging autobahn viaduct evaluation. CE marking under the Construction Products Regulation mandates interoperable data formats for cross-border project eligibility. Industrial equipment demand clusters in Bavaria and North Rhine-Westphalia where metrology institute partnerships ensure calibration traceability.
Japan
Public works spending on seismic retrofitting and METI industrial standards sustain demand for laboratory-grade portable units. JIS certification requirements filter equipment eligibility for government tenders. Manufacturing inspection demand concentrates in the Chubu region around Nagoya where automotive suppliers deploy automated compliance documentation systems.
India
Municipal bond financing for smart cities infrastructure creates first-mover positioning for inspection-as-a-service providers. BIS standards and CEA electrical safety mandates shape equipment import requirements. Urban transit expansion in Maharashtra and Karnataka drives field inspection deployment where project duration uncertainty favors rental penetration over capital purchase.
United Kingdom
Network Rail structural assessment programs and HSE workplace safety mandates expand electromagnetic and ultrasonic testing deployment. Post-Brexit divergence from CE marking reciprocity creates certification complexity for cross-border equipment movement. Infrastructure spending concentrates in London and the Southeast where digital thread integration into building information models accelerates project handover timelines.
Field Inspection Tester Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensor arrays and calibration services to assembled solutions. The vendor base organizes around three strategic archetypes: certification-network bundlers leveraging global service footprints, backward-integrated manufacturers with captive metrology capabilities, and geotechnical specialists serving project-based European infrastructure workflows. Consolidation pressure concentrates among mid-sized contractors facing compressed ownership economics from leasing model proliferation. Dominant competitive moves include strategic partnerships with national metrology institutes and portfolio diversification into subscription-based calibration services.
Within the certification-network tier, SGS exemplifies the bundling archetype that reduces upfront barriers for mid-sized contractors through integrated testing services. HUMBOLDT Mfg. CO. occupies a position among backward-integrated manufacturers with laboratory calibration capabilities ensuring traceability that rental fleets require. Cooper Technology represents the geotechnical specialization vector where leased instrumentation dominates European project-based workflows. These three anchors illustrate how competitive positioning increasingly depends on service attach rates rather than hardware margins alone.
| Leading Market Players |
|---|
| Controls Group |
| Roctest |
| UTEST Material Testing Equipment |
| ELE International |
| GEONOR |
| HUMBOLDT Mfg. CO. |
| Lambda Calibration |
| Cooper Technology |
| SGS |
| Others |
Supply Flow & Price Mechanics
Tariff exposure on German and Japanese sensor arrays compresses margin structures across portable tester tiers while simultaneously forcing procurement diversification into Southeast Asian calibration component sources. This dual pressure widens price spreads between CE-marked premium units and standard-grade alternatives while reshaping supplier geography toward lower-duty jurisdictions.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command spreads based on ISO 17025 calibration certification and bundled service attach rates, while economy positioning targets price-sensitive municipal contractors. Cost compression in the standard tier is intensifying because leasing model proliferation transfers obsolescence risk to manufacturers. Municipal procurement teams exhibit highest price sensitivity; automotive OEM quality departments demonstrate lowest.
Supply Chain Analysis
Extended payment terms from German metrology institutes and supply-chain finance facilities anchored in Japanese component distributors shape working capital requirements for assembly operations. Manufacturing concentrates in Germany, Japan, and the United States for precision sensor fabrication. Production draws from piezoelectric ceramics, rare-earth magnetic alloys, and FPGA processing modules. Single-source vulnerability sits with German calibration laboratory accreditation bottlenecks. Distribution runs through certified dealer networks and direct rental fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service substitution threatens capital-sales incumbents, compelling defensive restructuring around recurring revenue architectures.
For Market Incumbents: Pre-empt portable tester commoditization by embedding subscription calibration services and 5G-enabled remote diagnostics into hardware offerings. Backward integration into captive metrology laboratories defends against SGS-style certification-network bundlers. ISO 17025 accreditation investments in India and Southeast Asia reduce geographic service-access friction. For New Entrants and Emerging Players: Establish a beachhead in India's smart cities inspection-as-a-service segment where municipal bond financing favors operational expenditure models. White-space concentrates in geotechnical leasing workflows across European infrastructure programs where project duration uncertainty exceeds incumbent coverage. Lead with XML-based reporting protocols that satisfy EU Green Deal interoperability mandates. For Investors and Strategic Acquirers: CE marking reciprocity negotiations between EU member states reshape the acquisition landscape by determining which calibration networks achieve cross-border scalability. Five-to-ten year viability favors backward-integrated manufacturers with captive laboratory assets over pure-play hardware vendors. Monitor BIS standard harmonization progress in India as inflection signal for service-model penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Subscription | Recurring revenue offsets hardware margin compression from leasing model proliferation. |
| 5G-Enabled Remote Diagnostics | Real-time data transmission collapses inspection cycle times for distributed bridge networks. |
| Backward Integration into Metrology | Captive ISO 17025 laboratories ensure traceability that rental fleets require for regulatory compliance. |
| XML-Based Reporting Protocols | Interoperable data formats maintain CE marking eligibility under EU Green Deal procurement mandates. |
| Geographic Expansion into India | Municipal bond financing for smart cities infrastructure creates first-mover positioning for service providers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of trade association filings, national metrology institute accreditation records, and infrastructure procurement databases. Primary interviews engaged calibration laboratory directors, construction equipment procurement managers, OEM quality assurance leads, and aftermarket service heads. Secondary validation drew from OSHA regulatory filings, EU Construction Products Regulation guidance documents, and customs trade data. Bottom-up equipment shipment analysis triangulates against top-down infrastructure spending attribution.
Forecast inputs span product type mobility tiers, technology sensor categories, end-user industry verticals, application compliance requirements, and regional regulatory cluster intensity across the analysis window. Segmentation modeling captures portable versus fixed installation splits, ultrasonic versus electromagnetic technology shares, and construction versus manufacturing demand concentrations. CAGRs derive from equipment replacement cycle analysis and public works spending trajectory correlation.
Stress conditions across tariff regime shifts, calibration accreditation timeline extensions, and municipal bond financing volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and infrastructure program continuity. Macroeconomic contraction, CE marking reciprocity breakdown, or disruptive non-destructive testing technology emergence would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Reverberation Chambers Market
Test and Measurement
Battery Resistance Tester Market
Test and Measurement
Pump Testers Market
Test and Measurement
Semiconductor Bond Testing Market
Test and Measurement
Scuff Tester Market
Test and Measurement
Oscilloscope Market
Test and Measurement
Paperless Recorders Market
Test and Measurement
Vibration Analyzer Market
Test and Measurement
Battery Test Equipment Market
Test and Measurement
Gloss Meters Market
Test and Measurement
In-Situ Layer-by-Layer AM Defect Monitoring Test Equipment Market
Test and Measurement
Mechanical Testing Equipment Market
Test and Measurement
Sound Meter Market
Test and Measurement
Flying Probe Testing for PCB Assembly Market
Test and Measurement
Test and Measurement Equipment Market
Test and Measurement
Ultrasonic Thickness Gauge Market