
 Global Non-Alcoholic Beverage Packaging Market | 2026-2036
Global Non-Alcoholic Beverage Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non-Alcoholic Beverage Packaging Market Foresight
ISO 22000 certification for food safety management systems is collapsing the supplier base as smaller converters fail audit frequency and traceability requirements. Ball Corporation leverages its captive aluminum supply and recycling infrastructure to dominate North American can capacity. Tetra Pak anchors its position through aseptic filling technology leadership and integrated carton-film-lid systems that lock in beverage brands.
Non-alcoholic beverage packaging encompasses the primary and secondary containment systems engineered to preserve organoleptic properties, carbonation stability, and shelf life across distribution temperatures ranging from refrigerated to ambient storage. These systems employ barrier polymers, metal alloys, or treated cellulose substrates processed through blow molding, draw-and-iron forming, or extrusion lamination to prevent gas permeation and light-induced degradation. Aluminum cans command the fastest expansion trajectory as carbonated soft drink and energy drink brands abandon virgin PET commitments, while cartons capture margin pools in premium juice and plant-based beverage segments where extended ambient shelf life commands price premiums. Plastic bottles retain volume dominance in bottled water applications where cost-per-unit and logistics efficiency override material sustainability concerns.
The US EPA and FDA jointly govern material migration limits and recycled content claims, while the EU Green Deal's packaging and packaging waste regulation mandates minimum recycled thresholds and extended producer responsibility fees that reshape converter economics. China's SAMR enforces GB standards for food-contact plastics that restrict additive chemistries and mandate batch testing protocols, creating compliance friction for imported formats. Stakeholders must monitor regulatory divergence between jurisdictions where recyclability definitions and chemical hazard classifications fragment harmonized product strategies.
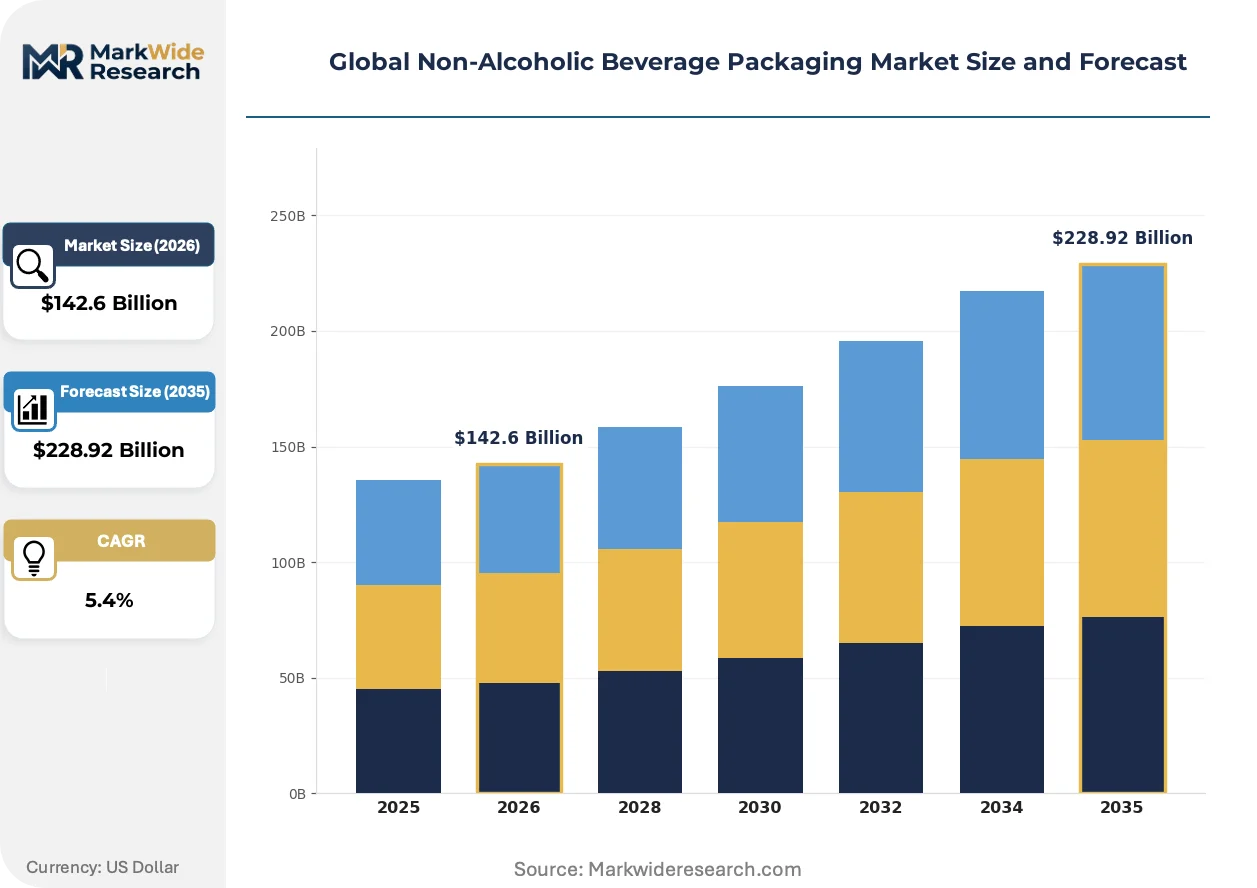
Market Dynamics
Aluminum can capacity expansion is compressing virgin PET commitments across carbonated soft drink and energy drink portfolios as brands confront EU Green Deal packaging waste directives and extended producer responsibility fees.
Growth Catalysts
- Aseptic carton technology:Ready-to-drink tea brands are driving fresh demand for aseptic carton formats that deliver extended ambient shelf life without refrigeration infrastructure.
- EU Green Deal packaging mandates:Minimum recycled content thresholds and material substitution requirements are forcing converter investments in circular feedstock systems.
- Southeast Asia bottled water acceleration:Indonesia, Vietnam, and Thailand are concentrating demand growth as per-capita consumption scales toward urban middle-class benchmarks.
Market Restraints
- Aluminum ingot price volatility:Smelter capacity constraints and energy cost spikes in China and Russia are transmitting raw material instability into can converter margins.
- ISO 22000 certification collapse:Smaller converters fail audit frequency and traceability requirements, consolidating supply around multi-site operators with captive laboratory infrastructure.
- Barrier polymer substitution limits:Oxygen scavenger and EVOH coextrusion technologies face technical ceilings in ultra-lightweight bottle applications below 8 grams.
Strategic Opportunities
- Refillable bottle infrastructure:Germany's DPG deposit-return system and emerging French consigne models create channel innovation for reusable glass and stainless-steel formats.
- Plant-based beverage premiumization:Oat, almond, and coconut milk brands command price premiums for aseptic carton systems with integrated straw and cap convenience features.
- Digital watermark traceability:HolyGrail 2.0 sorting technology convergence with blockchain verification opens closed-loop recycling economics for multilayer flexible packaging.
Industry Challenges
- Aseptic filling technician scarcity:Tetra Pak and Krones equipment demands specialized electromechanical skills that vocational pipelines in Vietnam and Indonesia have not scaled to match.
- Multilayer film delamination:Polymer incompatibility between PE tie layers and aluminum foil cores complicates mechanical recycling streams and delays FDA food-contact approvals for post-consumer content.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non-Alcoholic Beverage Packaging Market |
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $228.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Glass Bottles, Plastic Bottles, Aluminum Cans, Cartons, Pouches Beverage Type: Soft Drinks, Juices, Bottled Water, Ready-to-Drink Tea, Energy Drinks Sales Channel: Supermarkets, Convenience Stores, Online Retailers, Vending Machines, Specialty Stores Consumer Segment: Youth, Adults, Fitness Enthusiasts, Families, Professionals |
| Companies Covered | Crown Holdings, O-I Glass, Ball Corporation, Canpack Group, Silgan Holdings, Tetra Pak, Ardagh Group, SIG Combibloc Group, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non-Alcoholic Beverage Packaging Market Shifts & Advancements
Material substitution cascades and regulatory chemistry restrictions are rewriting converter technology roadmaps across primary containment systems.
Aluminum cans are displacing virgin PET bottles in carbonated soft drink and energy drink portfolios. Coca-Cola and PepsiCo procurement teams have accelerated can allocation to 60-70% of new product launches in North American markets. This material pivot is compressing blow molding capacity utilization and triggering resin supplier consolidation.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer barrier coatings from European paperboard cup and carton formats. Converter R&D teams are pivoting to aqueous barrier coatings and extruded PE liners that meet EFSA migration limits. Premium juice and dairy segments in Germany and France are absorbing 15-20% cost premiums for compliant substrate systems.
Beverage brands are consolidating supplier relationships around integrated format-filling-service bundles that compress switching costs. Small and mid-size regional bottlers in Thailand and Indonesia are abandoning multi-vendor procurement for single-source aseptic carton partnerships. This concentration pattern is most visible in Southeast Asia, where Tetra Pak and Greatview have captured 80% of new plant-based beverage line installations.
Global Non-Alcoholic Beverage Packaging Market Segmentation
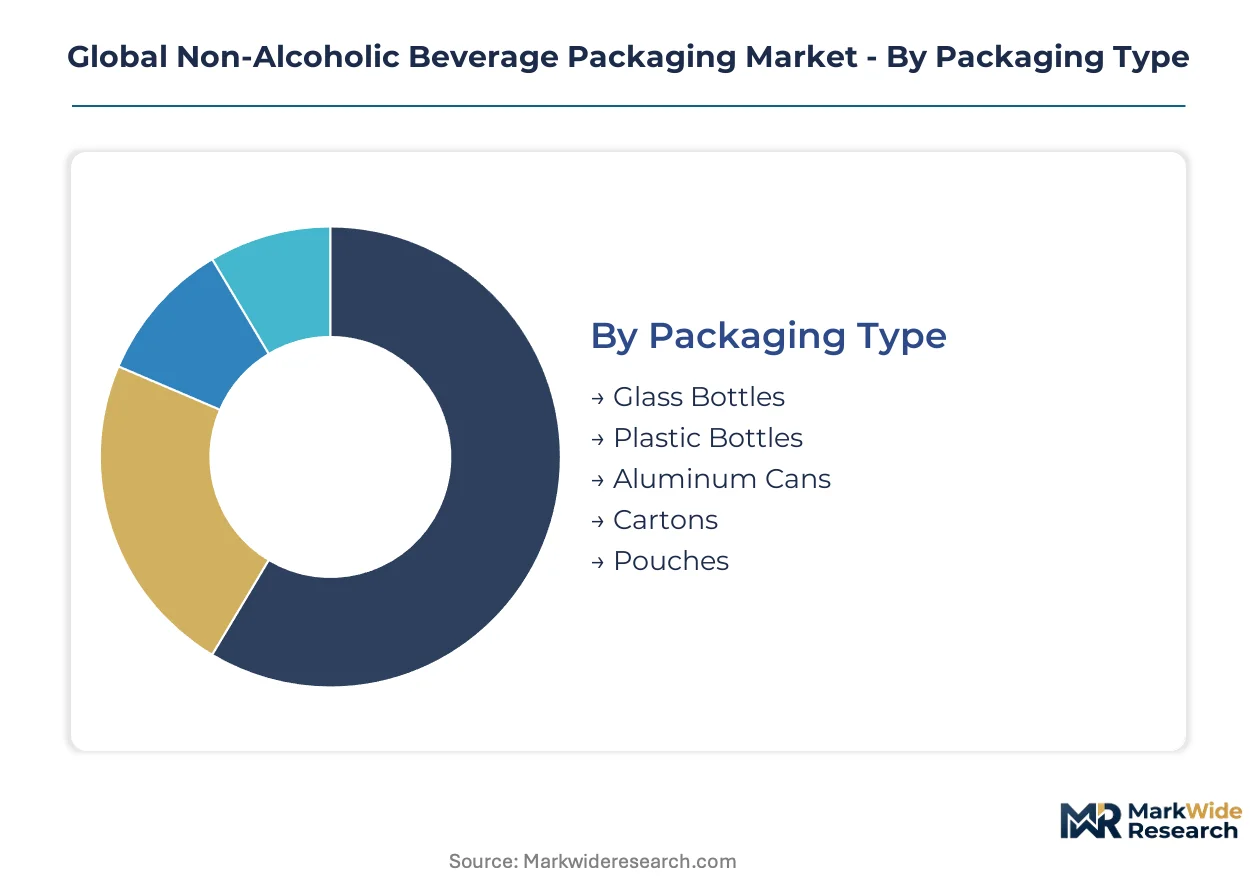
Packaging format selection in this market locks in shelf-life performance, logistics economics, and regulatory compliance trajectories across divergent beverage chemistries. Segmentation reveals where material substitution pressures concentrate and which technology platforms command margin premiums.
Packaging Type:
Aluminum can substitution is compressing virgin PET commitments across carbonated portfolios, while aseptic cartons face REACH-driven chemistry restrictions that force coating reformulations.
- Glass Bottles:Soda-lime silica construction delivers inert containment for premium mineral water and craft soft drink brands. Germany's DPG deposit-return system and France's consigne expansion sustain refillable infrastructure demand, though logistics weight limits geographic scalability.
- Plastic Bottles:Barrier polymers and EVOH coextrusion dominate bottled water applications where sub-8-gram lightweighting targets override material sustainability concerns. Indonesia, Vietnam, and Thailand concentrate volume acceleration as per-capita consumption scales toward urban middle-class benchmarks.
- Aluminum Cans:Draw-and-iron forming with captive recycling loops commands fastest expansion as Coca-Cola and PepsiCo procurement teams allocate 60-70% of North American new product launches to metal formats.
- Cartons:Aseptic filling technology with integrated straw-cap systems locks in plant-based beverage brands; Tetra Pak and Greatview captured 80% of Southeast Asian oat and almond milk line installations.
- Pouches:Multilayer flexible formats with spout fitments serve single-serve juice and sports drink segments where portability trumps shelf-life extension.
Plastic bottles retain volume leadership; aluminum cans hold the steepest expansion curve.
Beverage Type:
Carbonation stability requirements and cold-chain infrastructure availability segment containment needs across temperature-sensitive and ambient-stable product categories.
- Soft Drinks:Carbonation pressure retention demands metal or thick-walled PET formats; EU Green Deal extended producer responsibility fees accelerate aluminum conversion.
- Juices:Pasteurized and NFC variants split between aseptic cartons for ambient distribution and chilled PET for refrigerated retail.
- Bottled Water:Cost-per-unit minimization sustains virgin PET dominance despite brand-level recycled content pledges; Southeast Asian demand concentrates in Indonesia, Vietnam, and Thailand.
- Ready-to-Drink Tea:Aseptic carton technology captures ambient shelf-life premiums without refrigeration infrastructure; Tetra Pak filling systems anchor brand partnerships.
- Energy Drinks:Metal can preference aligns with carbonated formulation needs and youth-targeted convenience positioning.
Bottled water commands absolute volume; ready-to-drink tea posts the most rapid climb.
Sales Channel:
Route-to-market infrastructure determines format size, secondary packaging requirements, and direct-store-delivery versus warehouse economics.
- Supermarkets:Multi-pack bundling and shelf-ready secondary packaging dominate; Germany's DPG system mandates standardized crate formats for refillable glass.
- Convenience Stores:Single-serve cold vault placement favors slim cans and resealable PET; impulse velocity rewards compact footprint formats.
- Online Retailers:E-commerce shipment durability demands enhanced secondary protection; corrugated partition systems add cost but reduce damage rates.
- Vending Machines:Can and bottle diameter standardization enables machine interoperability; cashless payment integration accelerates format refresh cycles.
- Specialty Stores:Premium positioning supports glass and custom-shaped PET with higher unit economics and lower velocity thresholds.
Supermarkets anchor volume throughput; online retail expands most quickly.
Consumer Segment:
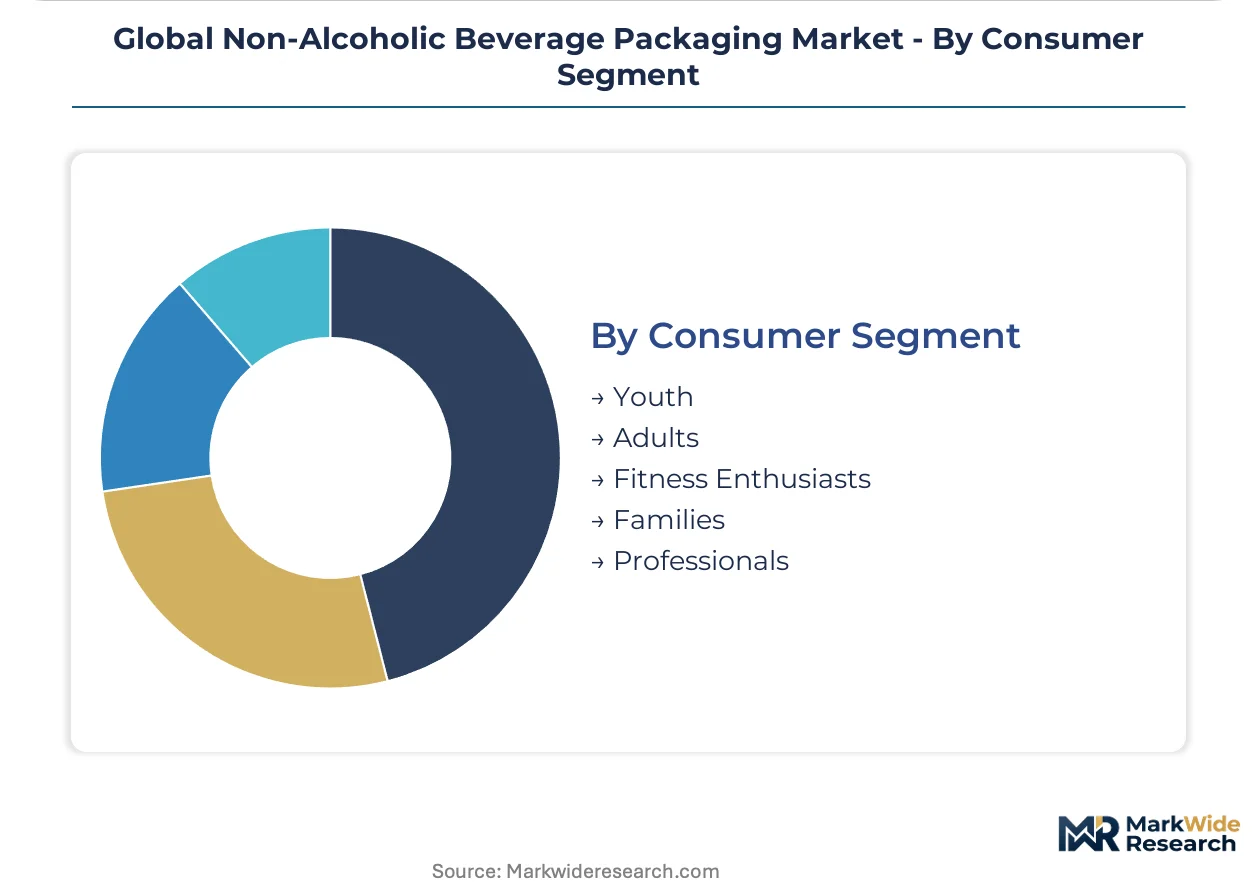
Usage occasion and health-positioning sensitivity segment packaging premium tolerance and sustainability attribute valuation.
- Youth:Convenience and portability priorities sustain single-serve can and pouch preference; social media shareability rewards distinctive format shapes.
- Adults:Balanced cost-quality tradeoffs favor standard PET and carton formats; private label acceptance runs higher than in youth cohorts.
- Fitness Enthusiasts:Functional beverage positioning commands premium for aseptic cartons with integrated straw systems and protein stability barriers.
- Families:Multi-serve value formats and bulk purchasing concentrate in supermarket channels; refillable glass deposit systems reduce per-liter cost.
- Professionals:Premium ready-to-drink tea and cold brew coffee in sleek cans command workplace convenience premiums.
Adults represent the broadest volume base; fitness enthusiasts generate the highest per-unit margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage brand procurement teams concentrate purchasing power in markets where deposit-return infrastructure and extended producer responsibility fees reshape format economics. The United States, Germany, China, Indonesia, and Brazil anchor regional demand clusters.
United States
Coca-Cola and PepsiCo procurement teams allocate 60-70% of new product launches to aluminum cans, compressing virgin PET commitments. The FDA and EPA jointly govern material migration limits and recycled content claims. Ball Corporation leverages captive aluminum supply in North American can capacity expansion.
Germany
The DPG deposit-return system sustains refillable glass infrastructure demand for mineral water and craft soft drink brands. EU Green Deal packaging waste directives mandate minimum recycled content thresholds. Bavaria and North Rhine-Westphalia concentrate converter investments in circular feedstock systems.
China
SAMR enforces GB standards for food-contact plastics that restrict additive chemistries and mandate batch testing protocols. Dual carbon goals accelerate aluminum can substitution in carbonated portfolios. Yangtze River Delta and Pearl River Delta clusters host multilayer film delamination R&D for mechanical recycling streams.
Indonesia
Per-capita bottled water consumption scales toward urban middle-class benchmarks, concentrating Southeast Asian demand growth. BIS-equivalent national standards create compliance friction for imported formats. Jakarta and Surabaya bottlers abandon multi-vendor procurement for single-source aseptic carton partnerships.
Brazil
ANVISA regulates food-contact material approvals with testing protocols that delay post-consumer content integration. Plant-based beverage premiumization drives aseptic carton line installations. São Paulo state anchors converter capacity for pouch and carton formats serving single-serve juice segments.
Global Non-Alcoholic Beverage Packaging Market Competitive Landscape
Player mix skews toward integrated material-converter systems and captive recycling infrastructure operators. Tiered concentration separates aluminum can fabricators with smelter partnerships from carton specialists with aseptic filling technology lock-ins. Strategic archetypes include backward-integrated metal converters, integrated carton-film-lid system providers, and multi-material platform operators. Capacity expansion and strategic partnerships dominate competitive moves as brands consolidate supplier relationships.
Within the integrated metal converter tier, Ball Corporation and Crown Holdings exemplify captive aluminum supply strategies. Tetra Pak occupies a position representing aseptic filling technology leadership with integrated carton systems. Among diversified packaging platforms, Amcor plc and Ardagh Group sit within multi-material operators spanning glass, metal, and flexible formats.
| Leading Market Players |
|---|
| Crown Holdings |
| O-I Glass |
| Ball Corporation |
| Canpack Group |
| Silgan Holdings |
| Tetra Pak |
| Ardagh Group |
| SIG Combibloc Group |
| Amcor plc |
| Others |
Supply & Pricing Matrix
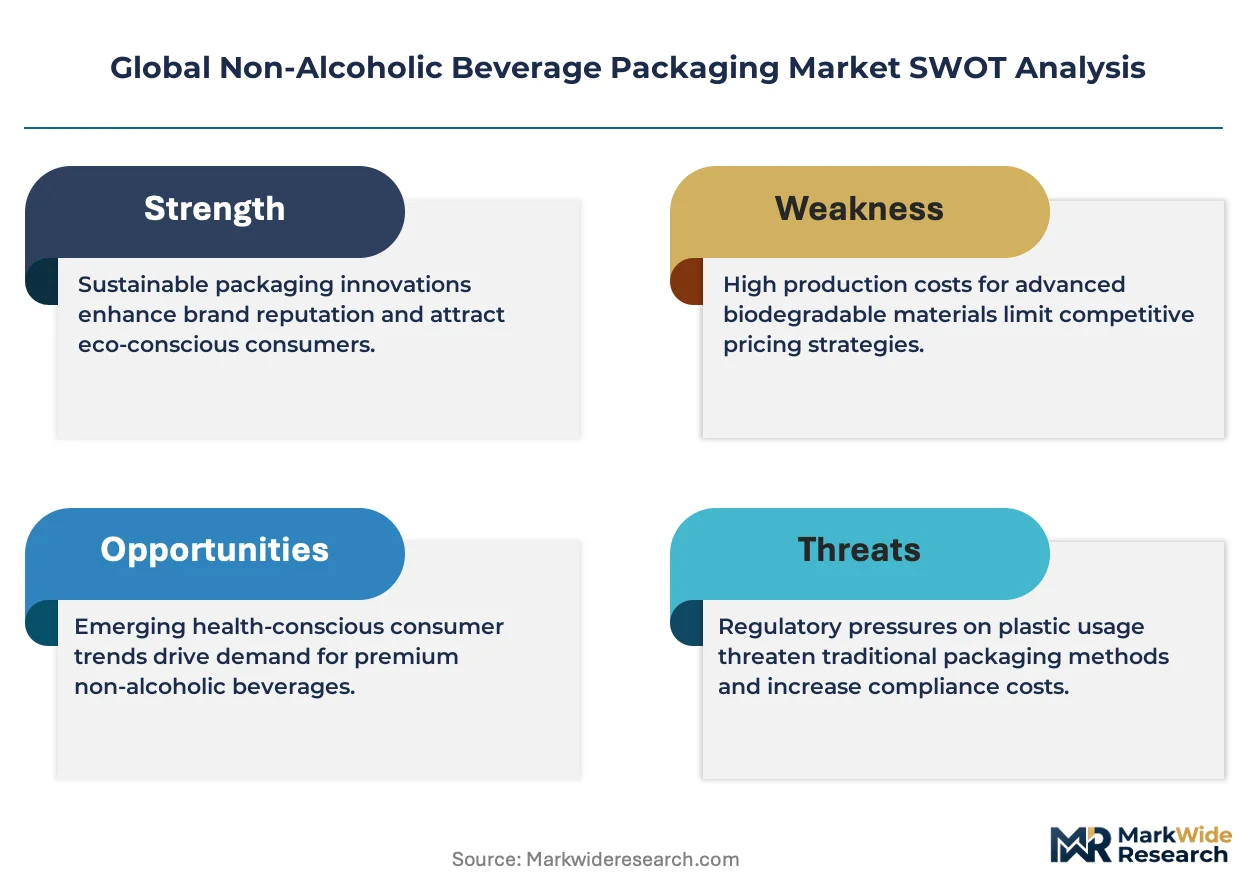
Ball Corporation's captive aluminum smelter partnerships and integrated recycling infrastructure compress unit economics below what fragmented PET converters can match, concentrating pricing power among three North American metal fabricators while establishing cost floors that virgin resin suppliers struggle to undercut. This scale asymmetry forces brand procurement teams into long-term offtake commitments that lock in volume allocations and limit spot-market flexibility.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange aluminum ingot prices dominate can converter agreements, with Tetra Pak and SIG Combibloc layering premium-mid-economy pricing differentiation based on aseptic filling technology tiers and integrated straw-cap convenience features. ISO 22000 certification tiers separate qualified suppliers from commodity converters, absorbing 15-20% cost premiums in European dairy and juice segments. Pricing pressure stems from EU Green Deal extended producer responsibility fees that compress margins on non-compliant substrate systems. Small regional bottlers in Indonesia and Vietnam exhibit highest price sensitivity, while Coca-Cola and PepsiCo procurement teams leverage volume scale to extract favorable terms.
Supply Chain Analysis
Port congestion on Shanghai-Rotterdam and Los Angeles-Long Beach trade lanes elevates inbound logistics costs for aluminum coil and barrier polymer feedstocks, with container availability swings transmitting directly into converter working capital cycles. Primary aluminum smelting concentrates in China, Russia, and Canada; EVOH barrier resin production anchors in Japan, South Korea, and the United States. Raw material dependencies span aluminum ingot, ethylene vinyl alcohol copolymer, and food-grade paperboard pulp. Single-source vulnerability runs through Russian smelter output exposed to sanctions risk. Distribution runs through direct-store-delivery networks for chilled PET and warehouse consolidation for ambient-stable carton formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized electromechanical skills for aseptic filling equipment maintenance represent the critical capability gap constraining Southeast Asian capacity expansion, with Tetra Pak and Krones technician training pipelines failing to match Indonesia and Vietnam plant installation rates.
For Market Incumbents: Shield margin pools in North American aluminum can fabrication by accelerating captive recycling infrastructure investments that virgin PET converters cannot replicate. Prioritize ISO 22000 certification maintenance to exclude smaller competitors from Coca-Cola and PepsiCo supplier panels. Defend against SIG Combibloc and Greatview encroachment in Southeast Asian plant-based beverage lines through exclusive aseptic technology licensing arrangements. For New Entrants and Emerging Players: Certification fast-track partnerships with Bureau Veritas or SGS in Vietnam and Indonesia compress qualification timelines for ISO 22000 and EU Green Deal compliance, opening white-space in regional oat and almond milk bottler supply chains. Target Indonesia's Surabaya and Jakarta corridors where per-capita bottled water consumption scales fastest and multi-vendor procurement abandonment creates single-source partnership opportunities. Pursue private-label ready-to-drink tea contracts with domestic brands lacking Tetra Pak relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors backward-integrated aluminum converters with captive smelter ties over multi-material generalists exposed to PET demand compression. Long-term viability across the analysis window rests on circular feedstock infrastructure and deposit-return system participation depth. Acquisition screening should prioritize converters with German DPG or emerging French consigne system integration. The signal to watch is EU Green Deal packaging waste directive enforcement intensity, which would accelerate aluminum substitution and strand virgin PET blow molding assets.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Filling Technology Licensing | Tetra Pak's integrated carton-film-lid systems lock in oat milk brand partnerships across Southeast Asia. |
| Captive Aluminum Recycling Infrastructure | Ball Corporation's closed-loop smelter partnerships compress unit costs below fragmented PET converter economics. |
| ISO 22000 Certification Investment | Food safety audit compliance excludes smaller converters and consolidates supply around multi-site operators. |
| Deposit-Return System Integration | Germany's DPG and France's consigne models sustain refillable glass demand against single-use alternatives. |
| Barrier Coating Reformulation R&D | REACH-driven fluoropolymer elimination forces aqueous coating pivots that premium juice brands absorb at 15-20% premiums. |
Research Methodology
Operator-level perspectives from beverage brand procurement directors, converter plant managers, aseptic filling equipment technicians, and EU regulatory affairs leads anchored the qualitative base. Secondary validation drew from FDA migration limit filings, EPA recycled content guidance, EU Green Deal packaging waste directive texts, and SAMR GB standard batch testing protocols. Bottom-up volume modeling triangulated against top-down macroeconomic consumption benchmarks across the analysis window.
Sensitivity analysis tested forecast outputs against aluminum ingot price volatility bands, EU extended producer responsibility fee implementation schedules, and Southeast Asian bottled water per-capita consumption trajectory assumptions. Segmentation dimensions spanned packaging format, beverage chemistry, sales channel infrastructure, and consumer health-positioning sensitivity. CAGRs derived from regression against historical format substitution patterns and regulatory compliance cost pass-through elasticities. Industry-specific inputs included aseptic line installation rates and deposit-return system participation thresholds.
Underlying assumptions cover sustained EU Green Deal enforcement intensity, aluminum smelter capacity stability in China and Russia, and vocational training pipeline scaling in Indonesia and Vietnam, with deviation risk concentrated in regulatory timeline acceleration or trade lane disruption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging
Club Store Packaging Tray Market
Packaging
India Plastic Packaging Market
Packaging
Retort Machine Market
Packaging
Isothermal Packaging Market
Packaging
Spain Flexible Plastic Packaging Market
Packaging
In-Mold Labelled Containers Market
Packaging
Global Glass Packaging Rectifier Diode Market
Packaging
Flatbed Die Cutters Market
Packaging
Reusable Ice Packs Market
Packaging
Table Tent Market
Packaging
PET Dome Lids Market
Packaging
Freezer Bags Market
Packaging
Pre-Made Bags Market
Packaging
India Metal Cans Market
Packaging
PE Coated Sack Kraft Paper Market
Packaging
Bag-In-Box Filler Market