
 Oman Container Glass Market | 2026-2036
Oman Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Container Glass Market Insights
The premium-commodity split in Oman container glass is rebalancing as brand owners demand heavier, decorated bottles for spirits and olive oil while bulk beverage producers shift to lightweight standardized formats. Majan Glass Company SAOG anchors the premium tier through its decorated and colored glass capabilities. Gulf Glass Industries competes aggressively on lightweight bottle runs for regional beverage exporters. Sohar Glass Manufacturing specializes in pharmaceutical amber glass that meets Gulf standard pharmacopeia requirements.
Container glass comprises silica sand, soda ash, limestone, and cullet melted at approximately 1,500°C to form rigid, chemically inert vessels for liquid and solid storage; its non-porous structure prevents gas exchange and contamination across repeated filling cycles. Bottles occupy the dominant volume position due to persistent demand from carbonated soft drink and water bottlers across Oman. Jars represent the fastest-growing category as domestic food preservation and gourmet packaging trends gain traction in Muscat retail channels. The extra-heavy weight class retains concentrated margin pools among premium cosmetic and spirits applications where wall thickness signals quality.
Oman's Ministry of Commerce, Industry and Investment Promotion and the Gulf Standardization Organization (GSO) jointly enforce food-contact material regulations and technical conformity requirements that shape local manufacturing specifications and import permissions. The country's national standards body applies GSO packaging standards alongside Omani technical regulations for pharmaceutical primary packaging. Stakeholders must monitor evolving Gulf recycling mandates and carbon-emission benchmarks that will reshape furnace fuel choices and cullet recovery infrastructure investments.
Market Dynamics
Lightweighting mandates from Gulf beverage exporters are compressing wall-thickness specifications across Oman's furnace operations, forcing simultaneous investment in decorating capabilities to capture premium spirits and olive oil contracts.
Growth Catalysts
- Gulf Standardization Organization food-contact protocols:Harmonized technical regulations streamline cross-border shipments to Saudi Arabia and UAE, reducing compliance duplication for Sohar-based manufacturers.
- Pharmaceutical amber glass demand:Domestic drug formulation facilities in Muscat and Salalah require Gulf-standard pharmacopeia packaging, creating captive offtake for specialized furnace runs.
- Returnable bottle pool expansion:Carbonated soft drink bottlers in Muscat are scaling refillable lightweight formats, extending asset life and cullet recovery rates.
Market Restraints
- Soda ash import dependency:Oman lacks domestic soda ash production, exposing furnace operators to freight cost volatility from Turkish and Kenyan suppliers.
- Natural gas price regime:Ministry of Energy pricing structures for industrial feedstock compress margin predictability during high-temperature melting campaigns.
- Aluminum can substitution:Regional beverage exporters in UAE are trialing aluminum formats for sparkling water, threatening glass volume at the commodity tier.
Strategic Opportunities
- Dhofar food preservation segment:Jars for date paste and honey remain underpenetrated relative to Muscat retail density, offering white space for decorated stock.
- Gulf recycling mandate alignment:Anticipated extended producer responsibility frameworks will reward early cullet recovery infrastructure investments with preferential licensing.
- Decorating technology convergence:Digital printing combined with organic coating chemistries enables short-run premium customization previously uneconomical at Omani scale.
Industry Challenges
- Furnace refractory engineering talent:Specialized glass-melter expertise concentrates in European and Turkish labor markets, complicating local hiring for 1,500°C furnace maintenance.
- Pharmaceutical packaging certification timelines:Gulf-standard pharmacopeia validation for amber glass requires extended stability testing, delaying new product qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Container Glass Market |
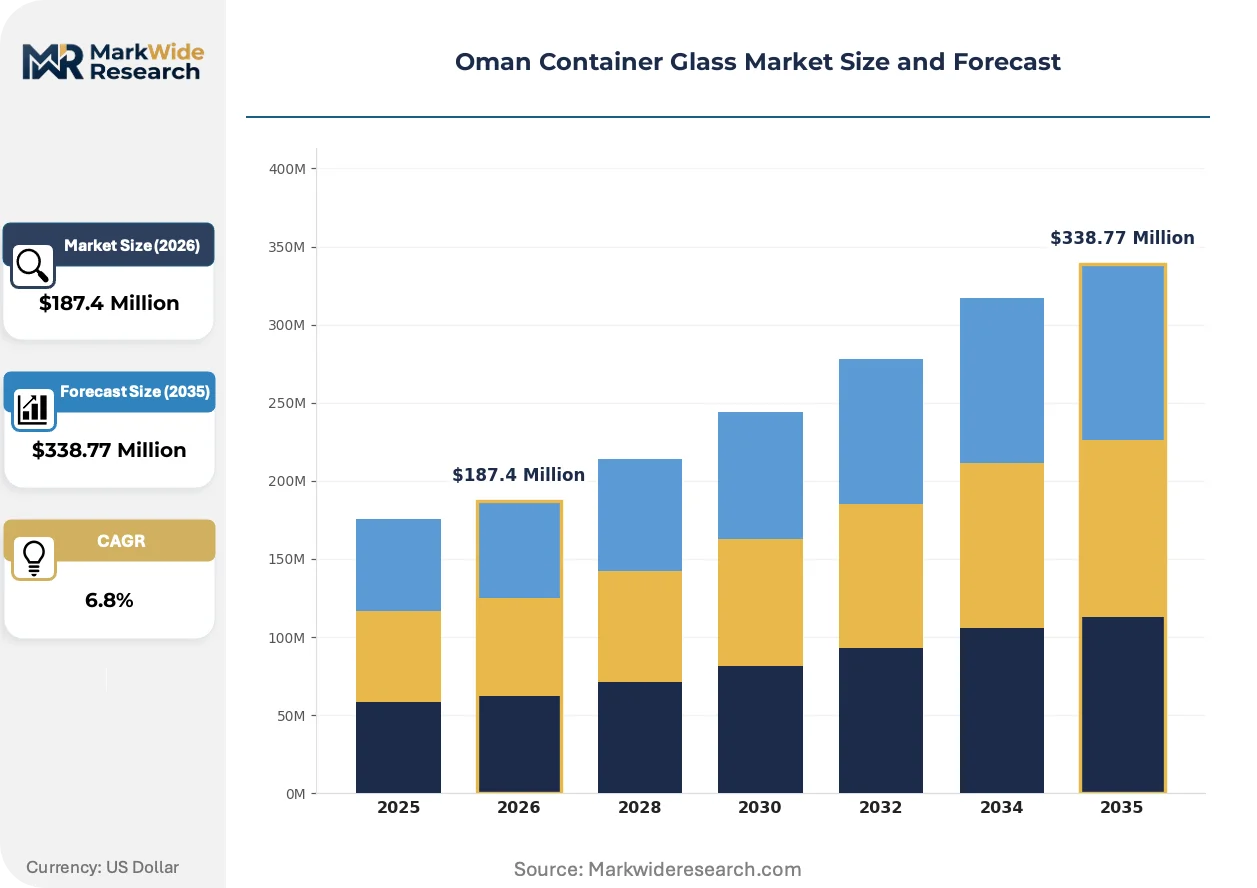
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Canisters End User: Food & Beverage, Pharmaceuticals, Personal Care, Household Shape: Round, Square, Rectangular, Custom Weight Class: Lightweight, Medium, Heavy, Extra Heavy |
| Companies Covered | Majan Glass Company SAOG, OMANCHEM Marine International EST, Pragati Glass Gulf LLC, Oman Glass Company, Gulf Glass Industries, Al Jazeera Glass, Muscat Glass Works, Sohar Glass Manufacturing, Al Maha Glass, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Container Glass Market Trends and Innovations
Digital decorating systems and cullet sorting automation are compressing minimum order quantities while Gulf regulatory alignment accelerates cross-border standardization.
Electrochemical glass strengthening is unifying durability performance across lighter wall-thickness designs. Beverage bottlers in Sohar are adopting ion-exchange surface treatment for returnable bottles, enabling 15% weight reduction without breakage-rate penalties. This technology is unifying premium and commodity tier specifications, eroding the historical performance gap that justified separate furnace configurations.
Gulf Standardization Organization technical regulations for food-contact materials are tightening migration testing protocols. Omani manufacturers must now document heavy metal leaching across repeated filling cycles to maintain export permissions to Saudi Arabia. Pharmaceutical amber glass producers face the steepest compliance burden, as Gulf-standard pharmacopeia requirements now incorporate European Pharmacopoeia 3.2.1 container guidelines.
Buyer concentration among Muscat-based beverage bottlers is compressing supplier negotiation cycles. Three bottling groups now account for the majority of lightweight bottle offtake, shifting procurement toward multi-year framework agreements with indexed raw material pass-throughs. This pattern is most visible in carbonated soft drink packaging, where volume scale now dictates furnace allocation priority over spot order flexibility.
Oman Container Glass Market Segmentation
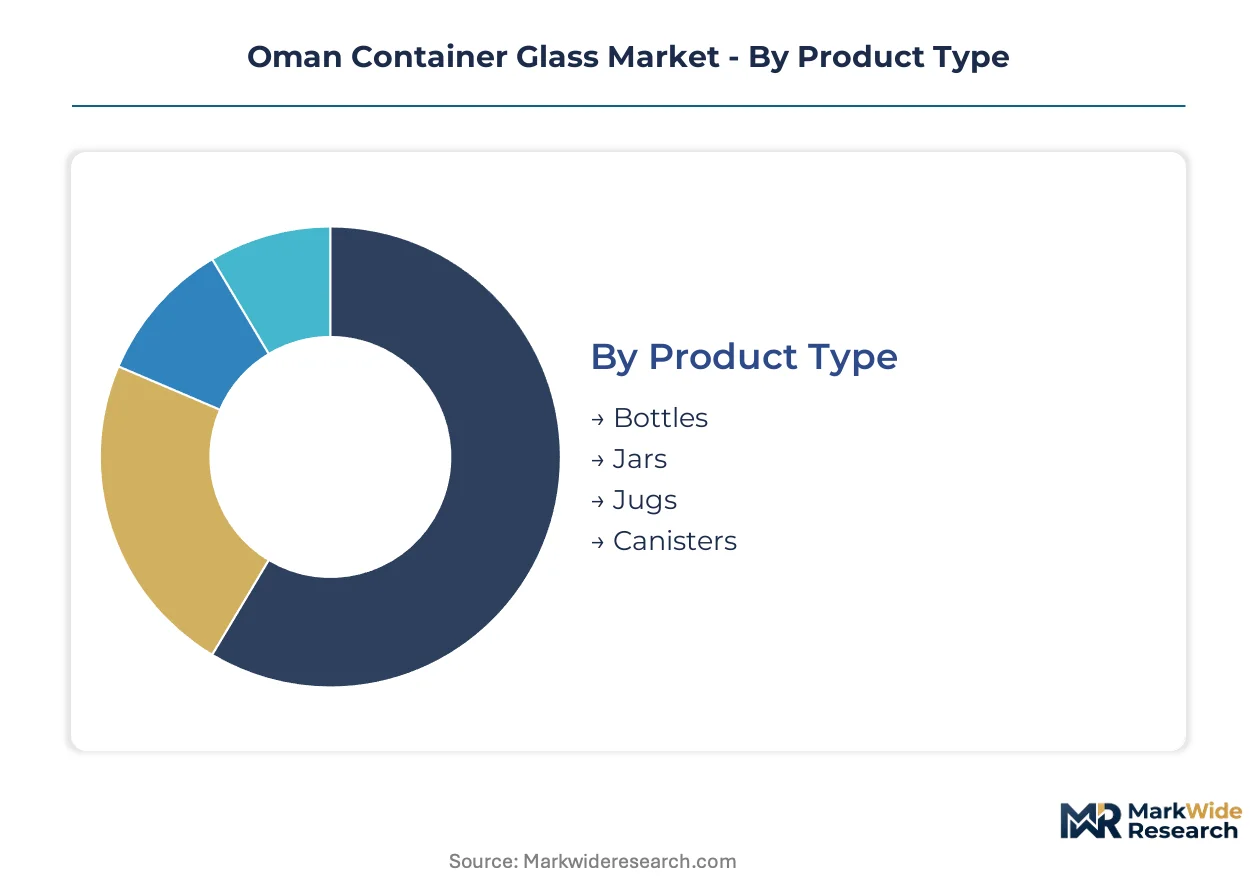
Segmentation in Oman's container glass market reveals how furnace allocation and regulatory compliance burden distribute across product specifications. Each dimension carries distinct certification requirements from Oman's Ministry of Commerce, Industry and Investment Promotion and the Gulf Standardization Organization.
Product Type:
Bottles and jars face divergent approval pathways under Gulf Standardization Organization food-contact protocols, while jugs and canisters navigate lighter technical documentation for non-consumable applications.
- Bottles:Silica-soda-lime compositions dominate carbonated soft drink and water packaging, with Muscat bottlers driving demand for returnable lightweight formats that extend cullet recovery cycles.
- Jars:Wider-mouth vessels with thicker heel sections serve date paste and honey preservation in Dhofar retail channels, where domestic food processing trends outpace Muscat penetration rates.
- Jugs:Large-format containers for bulk liquid distribution carry simpler GSO conformity requirements than food-contact bottles.
- Canisters:Cylindrical or rectangular storage vessels for dry goods face minimal migration testing protocols.
Bottles sit at the top of the volume ranking, with jars climbing the fastest.
End User:
Customer type determines whether Gulf Standardization Organization or Gulf-standard pharmacopeia frameworks apply, with pharmaceutical buyers imposing the steepest qualification timelines.
- Food & Beverage:Carbonated soft drink bottlers in Muscat and Sohar command furnace priority through multi-year framework agreements with indexed raw material pass-throughs.
- Pharmaceuticals:Amber glass for domestic drug formulation facilities requires European Pharmacopoeia 3.2.1 container guideline alignment, extending stability testing and delaying new product qualification.
- Personal Care:Premium cosmetic applications favor extra-heavy wall thickness as a quality signal, concentrating margin pools among decorated stock producers.
- Household:Standardized formats for cleaning products compete on cost efficiency with lower decorating investment.
Food & Beverage dominates furnace allocation by volume, while Pharmaceuticals commands the highest certification barrier.
Shape:
Geometric complexity shapes tooling investment and minimum order quantity economics across Oman's furnace base.
- Round:Symmetrical designs minimize stress concentration and maximize packing density for beverage distribution.
- Square:Flat-panel surfaces enable larger label real estate for brand differentiation in retail channels.
- Rectangular:Space-efficient stacking profiles suit food preservation and household storage applications.
- Custom:Proprietary molds for premium spirits and olive oil require dedicated furnace runs and extended lead times.
Round shapes anchor production volume, with Custom formats expanding most quickly among premium contract wins.
Weight Class:
Wall-thickness specifications directly correlate to fuel consumption per unit and natural gas exposure under Ministry of Energy pricing structures.
- Lightweight:Electrochemical ion-exchange strengthening enables 15% material reduction without breakage penalties, unifying performance across returnable bottle pools.
- Medium:Balanced specifications serve regional beverage exporters seeking cost-positioned standardized formats.
- Heavy:Reinforced heel and shoulder sections support multiple reuse cycles in established returnable systems.
- Extra Heavy:Thick-walled constructions signal quality in spirits and olive oil segments where wall thickness substitutes for brand recognition.
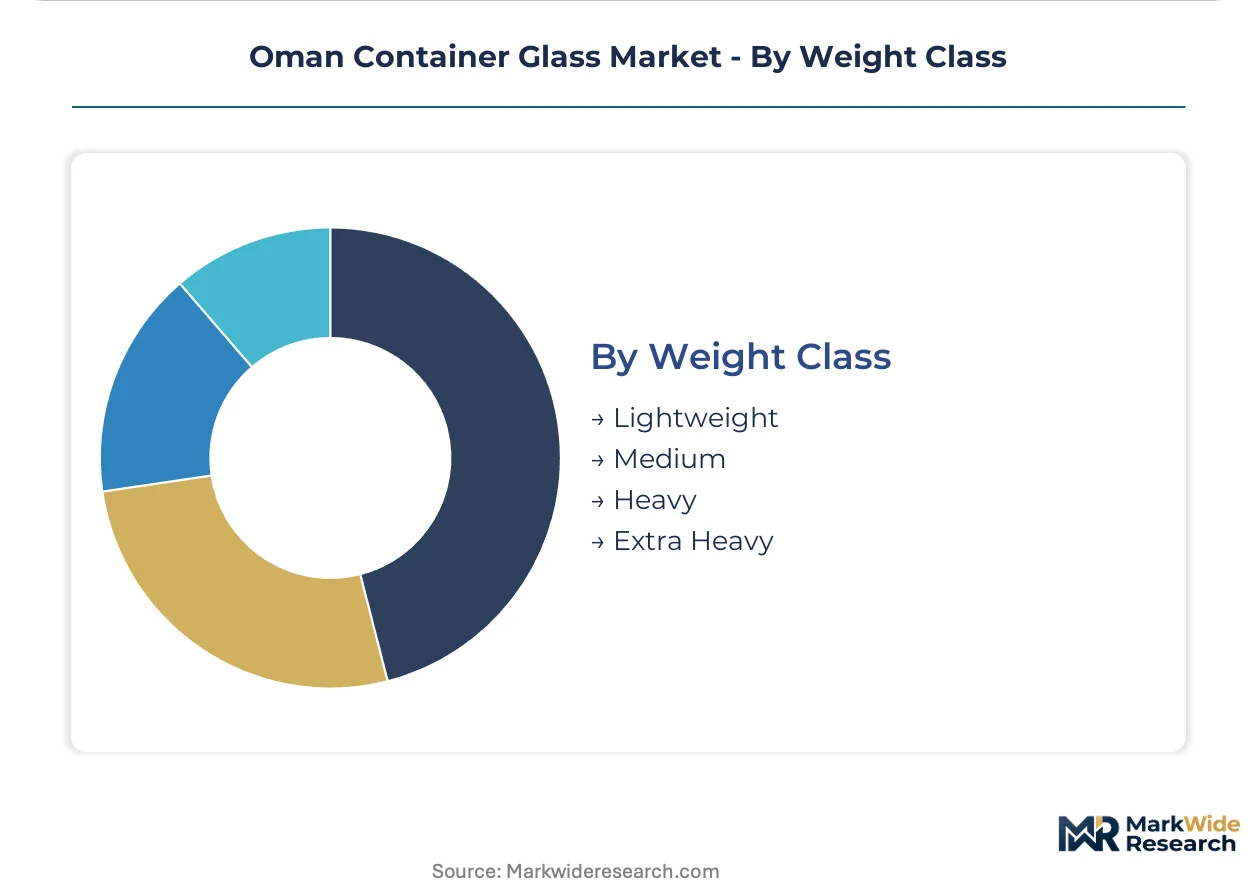
Lightweight specifications dominate new furnace investment, with Extra Heavy retaining concentrated margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized glass-melter expertise concentrates in European and Turkish labor markets, complicating local hiring for 1,500°C furnace maintenance across Oman's industrial zones.
Muscat Governorate
Carbonated soft drink bottlers command furnace priority through multi-year framework agreements with indexed raw material pass-throughs. The Ministry of Commerce, Industry and Investment Promotion enforces updated technical regulations on food-contact materials that shape local manufacturing specifications. Three bottling groups now account for the majority of lightweight bottle offtake in the capital region.
Al Batinah North Governorate
Sohar-based manufacturers benefit from harmonized Gulf Standardization Organization technical regulations that streamline cross-border shipments to Saudi Arabia and UAE. The Sohar industrial port complex hosts specialized pharmaceutical amber glass production meeting Gulf-standard pharmacopeia requirements. Sohar Glass Manufacturing anchors this northern corridor with dedicated furnace runs for domestic drug formulation facilities.
Dhofar Governorate
Domestic food processing trends for date paste and honey preservation outpace Muscat penetration rates, creating white space for decorated jar stock. The Ministry of Commerce, Industry and Investment Promotion applies GSO packaging standards alongside Omani technical regulations for regional food exporters. Salalah's emerging pharmaceutical packaging demand complements Muscat and Sohar in the southern tier.
Ad Dakhiliyah Governorate
Mid-country distribution hubs facilitate cullet recovery logistics connecting returnable bottle pools across the northern and southern production zones. National recycling mandates under development will reshape collection infrastructure investments in this central corridor. Nizwa's strategic position supports reverse logistics for lightweight returnable formats.
Oman Container Glass Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Oman's container glass sector. The market structure consolidates around integrated furnace operators with captive decorating capabilities and regional trading houses sourcing standardized formats. Three archetypes dominate: premium decorated specialists, lightweight commodity scale players, and pharmaceutical amber glass certified producers. Competitive moves center on multi-year supply agreements with indexed pricing and early cullet recovery infrastructure positioning.
Among Omani-registered producers, Majan Glass Company SAOG and Gulf Glass Industries exemplify divergent strategic positions within the premium-commodity split. Majan Glass Company SAOG anchors the premium tier through decorated and colored glass capabilities. Gulf Glass Industries occupies the commodity vector competing aggressively on lightweight bottle runs for regional beverage exporters. Sohar Glass Manufacturing represents the specialized pharmaceutical archetype with amber glass production meeting Gulf-standard pharmacopeia requirements.
| Leading Market Players |
|---|
| Majan Glass Company SAOG |
| OMANCHEM Marine International EST |
| Pragati Glass Gulf LLC |
| Oman Glass Company |
| Gulf Glass Industries |
| Al Jazeera Glass |
| Muscat Glass Works |
| Sohar Glass Manufacturing |
| Al Maha Glass |
| Others |
Pricing and Supply Chain Analysis
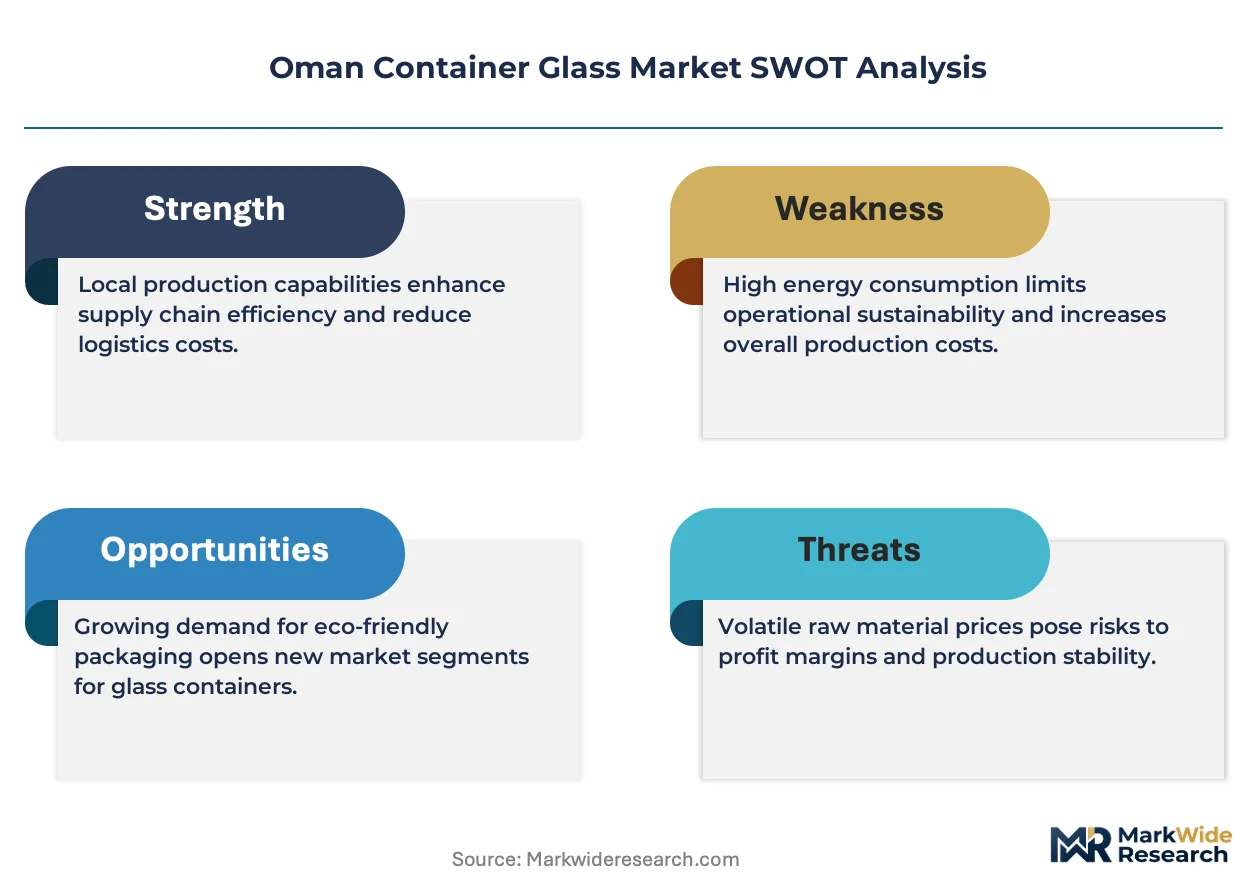
Soda ash freight costs from Turkish and Kenyan suppliers cascade through Oman's furnace operations, concentrating margin pressure on commodity lightweight bottles while insulating premium decorated stock through brand-owner willingness to absorb pass-throughs.
Pricing Analysis
Decorating services remain unbundled from base glass supply, enabling three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on Gulf Standardization Organization certification grade and volume scale under multi-year framework agreements. Cost compression in commodity tiers is intensifying because aluminum can substitution trials in UAE threaten glass volume. Regional beverage exporters exhibit highest price sensitivity; premium spirits bottlers show least.
Supply Chain Analysis
Regional distribution centers in Sohar industrial port and Muscat governate anchor hub-and-spoke patterns serving domestic drug formulation facilities and carbonated soft drink bottlers. Manufacturing concentrates in Oman with raw material dependencies on Turkey, Kenya, and Saudi Arabia for soda ash, silica sand, and limestone. Single-source vulnerability on soda ash imports creates exposure to freight rate volatility. Distribution runs through dedicated logistics contracts with indexed fuel pass-throughs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oman's container glass market functions as a regulatory compounder where Gulf Standardization Organization food-contact protocol harmonization is accelerating cross-border shipment volumes and compressing compliance duplication costs.
For Market Incumbents: Deepen backward integration into cullet recovery infrastructure to preempt extended producer responsibility frameworks and defend furnace allocation priority against aluminum can substitution. Anchor multi-year supply agreements with indexed raw material pass-throughs to lock in Muscat bottler offtake. Invest in electrochemical ion-exchange strengthening capabilities to unify premium and commodity tier specifications. For New Entrants and Emerging Players: Enter via Dhofar's underpenetrated date paste and honey jar segment where domestic food processing trends outpace Muscat retail density. Target pharmaceutical amber glass certification as the most penetrable niche given Gulf-standard pharmacopeia validation barriers that delay incumbent product qualification cycles. Pursue digital decorating technology partnerships to enable short-run premium customization previously uneconomical at Omani scale. For Investors and Strategic Acquirers: Consolidation pressure builds where furnace refractory engineering talent concentrates in European and Turkish labor markets, complicating local hiring for 1,500°C maintenance. Long-term viability favors asset-heavy producers with captive decorating capabilities and early cullet recovery infrastructure positioning. Watch Gulf recycling mandate alignment timelines as the inflection signal for preferential licensing advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Cullet Recovery Infrastructure Investment | Extended producer responsibility frameworks will reward early movers with preferential licensing from Oman's Ministry of Commerce. |
| Electrochemical Strengthening Adoption | Ion-exchange surface treatment enables 15% weight reduction without breakage penalties, unifying furnace configurations. |
| Digital Decorating Capability Buildout | Short-run premium customization for spirits and olive oil contracts becomes economically viable at Omani production scale. |
| Pharmaceutical Amber Glass Certification | European Pharmacopoeia 3.2.1 alignment captures captive offtake from Muscat and Salalah drug formulation facilities. |
| Multi-Year Framework Agreement Structuring | Indexed raw material pass-throughs with Muscat bottling groups secure furnace allocation priority over spot orders. |
Research Methodology
Multiple input streams — furnace operator production data, beverage bottler procurement records, and Gulf Standardization Organization regulatory filings — were reconciled through bottom-up and top-down triangulation. Primary interviews with plant managers at Sohar and Muscat manufacturing facilities, procurement leads at downstream bottling groups, and regulatory affairs specialists at Oman's Ministry of Commerce were cross-validated against secondary sources including customs trade data, GSO technical regulation updates, and SEC filings from regional glass producers. This approach enabled segmentation modeling across product type, end user, weight class, and regional production hub dimensions.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include bottle versus jar format, food-contact versus pharmaceutical certification tier, lightweight versus extra-heavy weight class, and governor-level demand clustering. CAGRs were derived from trend extrapolation of furnace capacity utilization, raw material cost trajectories, and regulatory compliance burden indices. Industry-specific forecast inputs incorporated natural gas pricing structures from Oman's Ministry of Energy and anticipated Gulf recycling mandate implementation timelines.
The model holds under stable Gulf Standardization Organization harmonization and predictable soda ash import cost regimes; deviation in Turkish freight rates or accelerated aluminum substitution would shift volume trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Philippines Container Glass Market
Glass Packaging
Cosmetic and Perfume Glass Bottle Market
Glass Packaging
Morocco Container Glass Market
Glass Packaging
Panama Container Glass Market
Glass Packaging
Austria Container Glass Market
Glass Packaging
Argentina Container Glass Market
Glass Packaging
Kenya Container Glass Market
Glass Packaging
France Glass Packaging Market
Glass Packaging
South Africa Container Glass Market
Glass Packaging
Bulgaria Container Glass Market
Glass Packaging
Egypt Container Glass Market
Glass Packaging
Mexico Glass Packaging Market
Glass Packaging
United States Glass Packaging Market
Glass Packaging
Benelux Container Glass Market
Glass Packaging
Mason Jars Market
Glass Packaging
Russia Container Glass Market