
 Europe 3D Printing in Healthcare Market | 2026-2036
Europe 3D Printing in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Europe 3D Printing in Healthcare Market Insights
The EU Medical Device Regulation is restructuring the cost-of-entry calculus for additive manufacturing in European healthcare, forcing manufacturers to recalibrate quality management systems and clinical evidence portfolios. Materialise NV anchors its competitive position through end-to-end software-to-print workflows that span pre-surgical planning and certified medical device production. EOS GmbH dominates industrial metal additive manufacturing with laser powder bed fusion systems calibrated for cobalt-chrome and titanium orthopedic implants. Stratasys Ltd leverages polymer expertise across hospitals and research institutions with biocompatible materials cleared for patient contact.
Europe 3D Printing in Healthcare encompasses the layer-by-layer fabrication of anatomical models, surgical guides, prosthetics, and implants from biocompatible polymers, metals, and living cell suspensions, typically achieving 50-500 micron resolution depending on the modality employed. The primary purpose is to reduce surgical time, improve patient outcomes through personalized geometry, and enable distributed manufacturing at or near the point of care. Customized implants and surgical tools represent mature revenue pools where regulatory clearance pathways are established, while bioprinting for tissue engineering occupies an emerging position with significant R&D intensity but limited commercial scale. Fused Deposition Modeling and Selective Laser Sintering lead technology adoption in hospital settings due to lower capital barriers and material versatility, whereas Stereolithography competes in dental and high-resolution anatomical modeling where surface finish determines clinical utility.
EMA and notified bodies under the EU MDR framework govern pre-market conformity assessment for additively manufactured medical devices, while REACH and the EU Green Deal impose material traceability and sustainability obligations on powder and resin supply chains. National health technology assessment bodies in France, Germany, and Italy increasingly evaluate cost-effectiveness of patient-specific implants against standard-of-care alternatives, shaping reimbursement and hospital procurement priorities. Stakeholders must monitor evolving harmonized standards for process validation and post-market surveillance as regulatory stringency tightens across member states.
Market Dynamics
The EU Medical Device Regulation is compressing time-to-market for additively manufactured implants while elevating documentation burdens, forcing manufacturers to rebuild quality management systems around process validation rather than component testing.
Growth Catalysts
- Point-of-care manufacturing:Hospitals in Germany and France are installing industrial-grade systems for same-day surgical guide production, cutting logistics lead times from weeks to hours.
- REACH-compliant material innovation:Powder suppliers are certifying cobalt-chrome and titanium alloys with full batch traceability, satisfying ECHA documentation requirements for implant-grade feedstock.
- Bioprinting research corridors:Netherlands-based consortia are converging academic tissue engineering with industrial-scale extrusion systems, accelerating translation from laboratory to clinical protocol.
Market Restraints
- Capital intensity barriers:Laser powder bed fusion systems require seven-figure euro investments, restricting hospital adoption to tertiary academic centers with dedicated research budgets.
- Notified body capacity constraints:EU MDR designation bottlenecks are extending conformity assessment timelines to 18-24 months for novel implant geometries.
- Polymer substitution pressure:Conventional CNC-machined PEEK implants retain cost advantages for standardized geometries, limiting addressable market for patient-specific polymer printing.
Strategic Opportunities
- Italy's underpenetrated orthopedic sector:Regional hospital networks in Lombardy and Emilia-Romagna lack point-of-care manufacturing infrastructure, creating first-mover openings for equipment vendors.
- EU Green Deal material circularity:Powder recycling protocols and closed-loop metal recovery systems qualify for sustainability-linked procurement preferences in public hospital tenders.
- AI-integrated surgical planning:Machine learning segmentation of CT/MRI datasets is converging with automated print file generation, compressing pre-operative workflow from days to minutes.
Industry Challenges
- Additive manufacturing technician scarcity:Hospital biomedical engineering departments lack personnel trained in laser parameter optimization and in-process monitoring for medical-grade builds.
- Post-processing certification complexity:Heat treatment, surface finishing, and sterilization validation for metal implants require specialized equipment rarely found in clinical settings.
- Legacy PACS integration friction:Hospital imaging archives use proprietary DICOM implementations that resist direct pipeline connection to pre-surgical planning software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe 3D Printing in Healthcare Market |
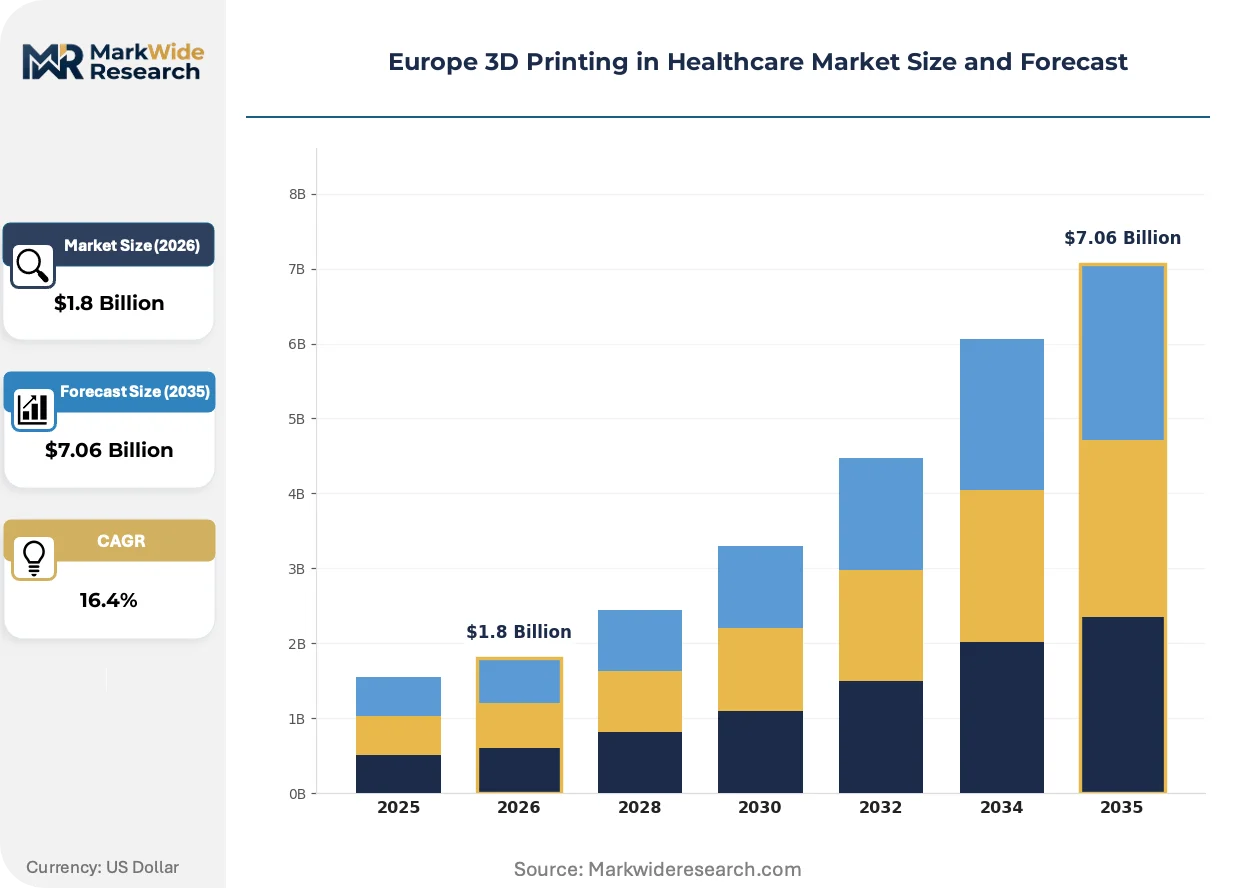
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioprinting, Prototyping, Customized Implants, Surgical Tools Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, PolyJet Application: Orthopedics, Dental, Cardiovascular, Tissue Engineering End User: Hospitals, Research Institutions, Clinics, Academic Facilities |
| Companies Covered | Stratasys Ltd, Materialise NV, EOS GmbH, Renishaw PLC, EnvisionTEC GmbH, 3D Systems Corporation, General Electric, SLM Solutions, CELLINK EUROPE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe 3D Printing in Healthcare Market Trends and Innovations
Process automation and regulatory digitization are compressing the gap between anatomical scan and sterilized implant, while procurement models shift toward risk-sharing arrangements that reward clinical outcomes over device throughput.
Closed-loop quality systems with in-situ melt pool monitoring and layer-wise defect detection are automating real-time parameter adjustment during metal builds. German orthopedic manufacturers are deploying these systems across cobalt-chrome hip implant production, eliminating post-build destructive testing for geometrically simple components. This automation is compressing unit economics for high-volume implant families while preserving lot traceability.
EMA's evolving guidance on patient-specific device master files is harmonizing documentation requirements across notified bodies, reducing redundant clinical evidence generation for geometric variants of approved base designs. French and German regulators are piloting digital submission formats that accept parametric design histories rather than static drawings. Small implant manufacturers in Belgium and Switzerland are restructuring regulatory affairs teams to capture these streamlined pathways.
Hospital procurement departments are unbundling device supply from surgical planning services, creating separate contracting vehicles for software licenses, print consumables, and finished implant verification. Academic medical centers in the Netherlands and Sweden are leading this disaggregation, negotiating outcome-based fees for complex cranio-maxillofacial reconstructions. France's regional health agencies are incorporating these models into 2025-2027 hospital financing frameworks.
Europe 3D Printing in Healthcare Market Segmentation
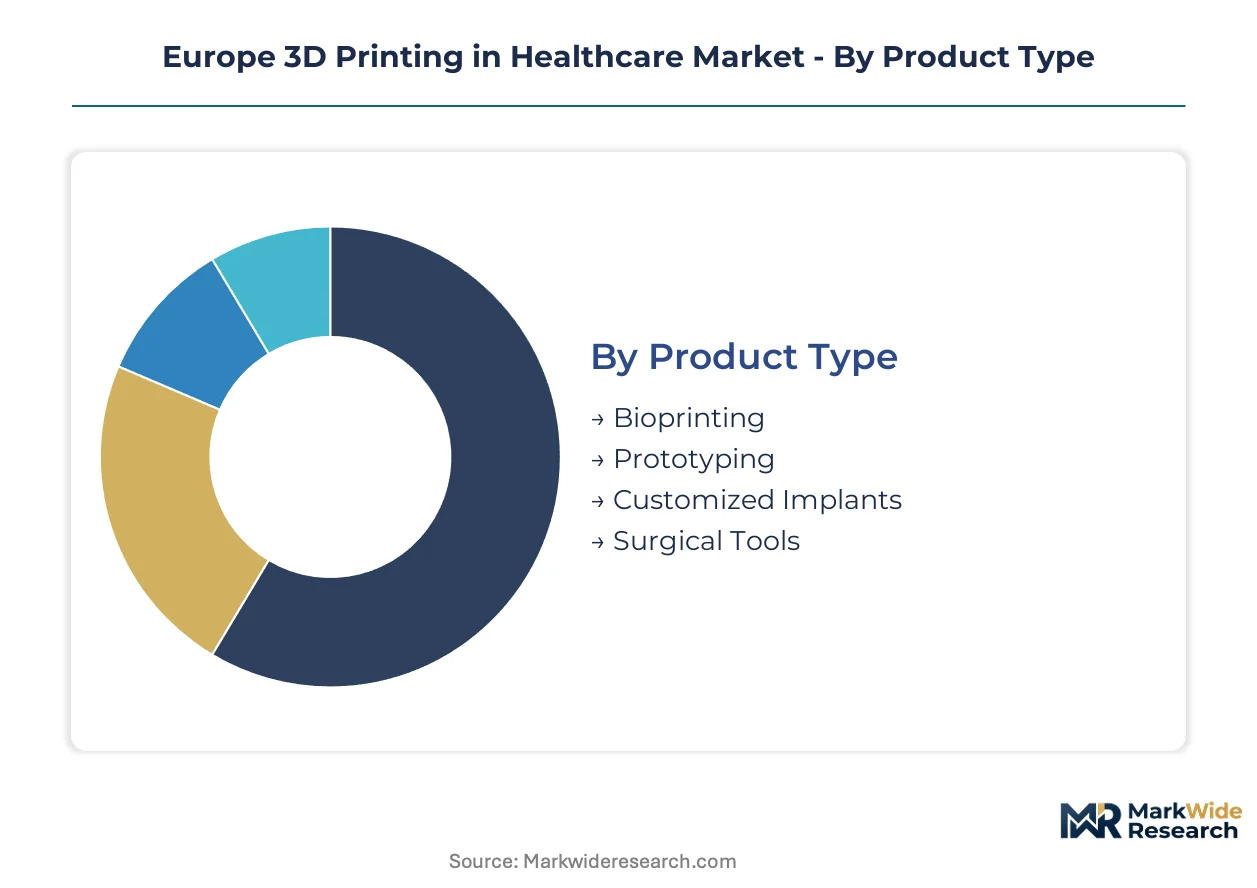
Segmentation in Europe's 3D printing healthcare market reveals divergent buyer priorities across clinical workflows, material specifications, and regulatory maturity. Understanding these distinctions shapes equipment procurement strategies and partnership structures for vendors navigating heterogeneous national health systems.
Product Type:
Buyers in this category differentiate by regulatory pathway complexity and reimbursement certainty rather than technical capability alone.
- Customized Implants:Patient-specific geometries fabricated from cobalt-chrome and titanium alloys command premium positioning in German and French orthopedic centers. Demand concentrates in hip and knee reconstruction units where EU MDR-certified master files accelerate hospital procurement cycles.
- Surgical Tools:Sterilizable drill guides and cutting jigs produced via laser powder bed fusion reduce operative time in cranio-maxillofacial procedures. Netherlands hospitals are expanding point-of-care manufacturing for these instruments, driven by same-day turnaround requirements that external suppliers cannot match.
- Bioprinting:Living cell deposition systems remain confined to academic consortia in Belgium and the Netherlands, limited by EMA guidance gaps on engineered tissue classification.
- Prototyping:Pre-surgical anatomical models serve training and patient communication functions across Italian and Spanish hospital networks with lower capital budgets.
Volume sits with customized implants; growth tilts toward surgical tools as point-of-care manufacturing diffuses beyond tertiary centers.
Technology:
Capital expenditure thresholds and material versatility determine adoption patterns across hospital biomedical engineering departments.
- Fused Deposition Modeling:Thermoplastic extrusion systems achieve 50-400 micron resolution with biocompatible PLA and ABS formulations cleared for patient contact. German rehabilitation clinics deploy these for low-cost prosthetic sockets where surface finish requirements are modest.
- Selective Laser Sintering:Polyamide powder bed fusion produces durable surgical guides with isotropic mechanical properties. French dental laboratories favor this modality for orthodontic appliance production given established CE marking pathways for polyamide Class IIa devices.
- Stereolithography:Photopolymer vat polymerization delivers sub-100 micron precision for vascular models and dental restorations where surface aesthetics determine clinical acceptance.
- PolyJet:Multi-material jetting enables gradient hardness in anatomical models but carries elevated consumable costs that restrict adoption to research institutions in Sweden and Switzerland.
Installed base concentrates in Fused Deposition Modeling; capability expansion is climbing the fastest in Selective Laser Sintering as powder recyclability improves.
Application:
Reimbursement coding specificity and clinical evidence requirements separate commercially viable applications from research-phase categories.
- Orthopedics:Hip, knee, and spinal implant applications leverage established DRG reimbursement structures in Germany, France, and Italy. Patient-specific instrumentation reduces revision rates in complex deformity corrections, generating health economic data that supports hospital technology assessment submissions.
- Dental:Crown, bridge, and clear aligner production operates under lighter regulatory burden with self-certified CE marking for many device categories. Dutch and Belgian dental chains are consolidating intraoral scanning with chairside manufacturing workflows.
- Cardiovascular:Patient-specific valve models and congenital defect simulations serve pre-surgical planning in French and German cardiac centers, though implantable cardiovascular devices remain experimental.
- Tissue Engineering:Scaffold fabrication for bone and cartilage regeneration occupies preclinical and early clinical stages across Netherlands and UK academic partnerships, awaiting EMA advanced therapy medicinal product classification clarity.
Revenue gravity centers on orthopedics; regulatory momentum is expanding most quickly in dental as notified bodies streamline conformity assessment for digital workflows.
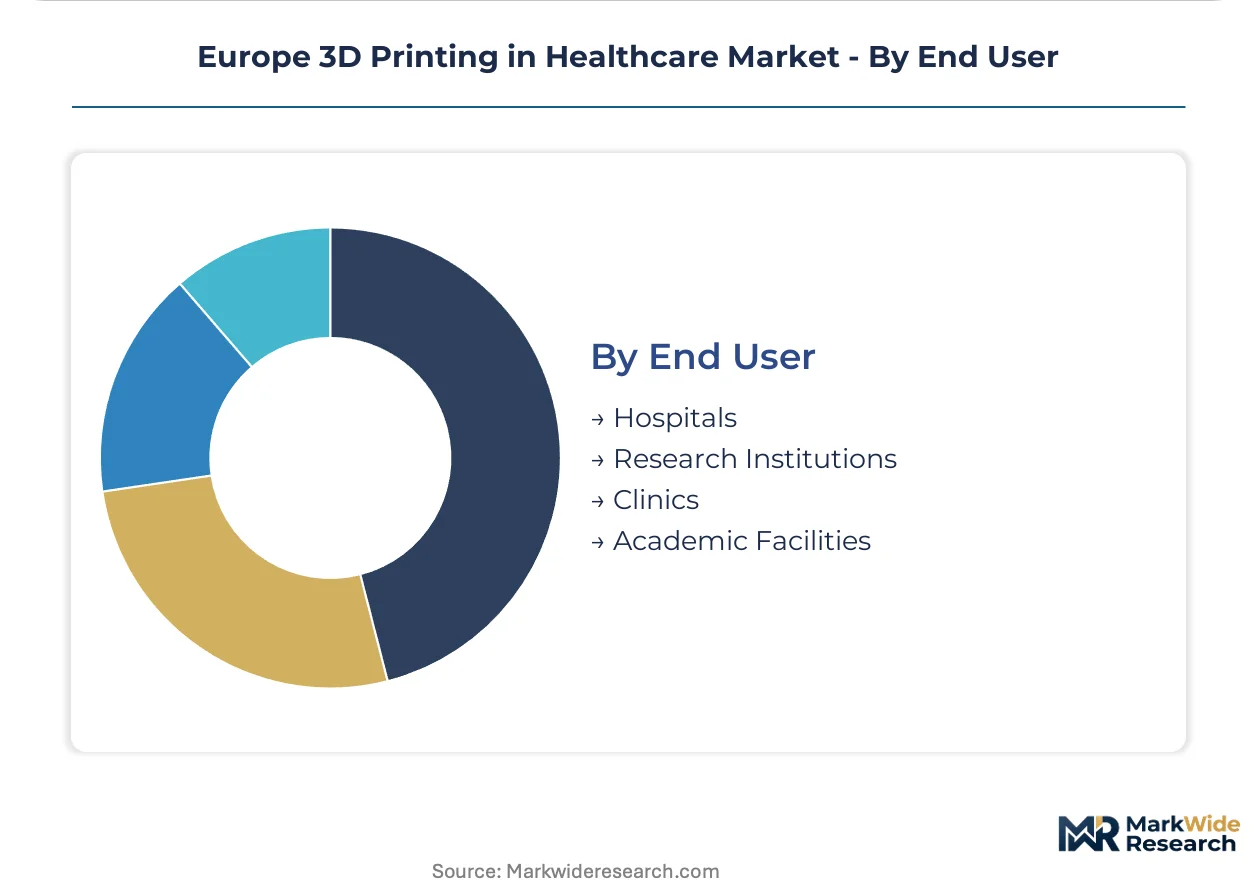
End User:
Procurement authority and technical staffing capacity distinguish institutional buyers in this fragmented customer landscape.
- Hospitals:Tertiary academic medical centers in Germany, France, and the Netherlands maintain dedicated additive manufacturing laboratories with biomedical engineers trained in process validation. These facilities negotiate direct purchasing agreements with equipment vendors and material suppliers, bypassing distributor markups.
- Research Institutions:University hospitals and national research centers in Belgium and Switzerland concentrate bioprinting and regenerative medicine applications where publication priorities outweigh commercial timelines.
- Clinics:Private orthopedic and dental practices in Italy and Spain access 3D printing through service bureau partnerships rather than capital investment, preferring per-case fees for surgical guides and models.
- Academic Facilities:Medical schools and training hospitals utilize polymer prototyping systems for anatomical education, prioritizing low-cost material options over clinical-grade certifications.
Capital deployment concentrates in hospitals; service-based access models are gaining share fastest among independent clinics seeking patient-specific capabilities without fixed cost absorption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement budgets for point-of-care manufacturing concentrate in Germany and the Netherlands, while regulatory harmonization under EU MDR is redistributing commercial activity toward France and Belgium. National reimbursement frameworks and research infrastructure quality determine where equipment vendors prioritize direct sales versus distributor partnerships.
Germany
Tertiary orthopedic centers in Munich and Berlin are installing laser powder bed fusion systems for same-day surgical guide production. The EU MDR notified body BfArM enforces stringent process validation requirements for cobalt-chrome implant certification. The Baden-Württemberg precision engineering corridor hosts concentrated metal powder supply chains serving Stuttgart-area medical device manufacturers.
Netherlands
Academic medical centers in Utrecht and Eindhoven operate bioprinting consortia translating tissue engineering research toward clinical protocols. ECHA REACH compliance mandates full batch traceability for titanium and polymer feedstocks used in implant production. The Brainport Eindhoven cluster integrates industrial-scale extrusion systems with university hospital surgical departments.
France
Regional health agencies in Île-de-France and Auvergne-Rhône-Alpes are incorporating outcome-based procurement into 2025-2027 hospital financing frameworks. ANSM maintains accelerated pathways for patient-specific device master files when clinical evidence demonstrates reduced revision rates. The Lyon biotech corridor concentrates cranio-maxillofacial reconstruction centers with dedicated additive manufacturing laboratories.
Belgium
Walloon and Flemish university hospitals leverage EU research funding for scaffold fabrication in bone regeneration applications. The federal medicines agency enforces CE marking conformity assessment timelines that notified bodies are extending to 18-24 months for novel implant geometries. Leuven and Liège host medical device regulatory affairs specialists restructuring documentation for parametric design submissions.
Switzerland
Swissmedic maintains bilateral recognition agreements with EU MDR frameworks that streamline market access for orthopedic implant manufacturers. Zurich and Basel academic centers concentrate polymer prototyping systems for anatomical education and pre-surgical planning. The Swiss precision manufacturing base supplies high-purity metal powders to adjacent German and French hospital networks.
Europe 3D Printing in Healthcare Market Competitive Landscape
German producers anchor the industrial metal printing tier; Belgian and Dutch specialists hold positions in software-to-print workflows and bioprinting research platforms. The vendor base separates into three strategic archetypes: end-to-end solution providers spanning pre-surgical planning through certified device production, pure-play hardware manufacturers of laser powder bed fusion systems, and material-science-focused developers of biocompatible polymers and living cell suspensions. Dominant competitive moves include vertical integration into powder recycling protocols and strategic partnerships between equipment vendors and hospital procurement departments for outcome-based contracting.
Among Germany-based fabricators, EOS GmbH and SLM Solutions occupy positions within the industrial metal printing archetype, while Materialise NV represents the software-to-print workflow tier. Stratasys Ltd exemplifies polymer system specialists serving hospital and research institution segments. These named entities illustrate how competitive positioning stratifies across hardware certification depth, regulatory affairs capabilities, and point-of-care manufacturing partnership structures rather than geographic coverage alone.
| Leading Market Players |
|---|
| Stratasys Ltd |
| Materialise NV |
| EOS GmbH |
| Renishaw PLC |
| EnvisionTEC GmbH |
| 3D Systems Corporation |
| General Electric |
| SLM Solutions |
| CELLINK EUROPE |
| Others |
Pricing and Supply Chain Analysis
Captive powder recycling systems in German precision engineering clusters anchor both supply security and pricing power for orthopedic implant manufacturers serving EU MDR-certified hospital networks. This backward integration into titanium and cobalt-chrome feedstock recovery insulates producers from ECHA REACH documentation volatility while compressing unit economics for high-volume implant families.
Pricing Analysis
High-volume standardized geometries trade on thin margins against CNC-machined PEEK alternatives, while patient-specific cobalt-chrome implants command premium positioning through EU MDR master file certification. Price differentiation separates CE-marked Class IIb devices from self-certified surgical guides, with tertiary academic centers showing lowest sensitivity due to research budget insulation. Cost compression in polymer FDM systems is intensifying as Chinese equipment vendors enter rehabilitation clinic procurement cycles.
Supply Chain Analysis
EU Green Deal local-content mandates for sustainable procurement are reshaping sourcing patterns toward closed-loop metal recovery systems qualifying for public hospital tenders. Powder supply concentrates in Germany's Baden-Württemberg corridor, the Netherlands' Brainport Eindhoven cluster, and Switzerland's precision manufacturing base. Feedstock draws from certified titanium sponge, cobalt-chrome alloy ingots, and biocompatible photopolymer resins. Single-source vulnerability sits with laser optics and in-situ monitoring sensors. Distribution runs through direct vendor-hospital agreements bypassing distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Medical Device Regulation has erected a cost-of-compliance barrier that rewards incumbents with validated quality management systems while filtering out undercapitalized entrants lacking clinical evidence portfolios.
For Market Incumbents: Lock in notified body relationships before capacity constraints extend EU MDR conformity assessment timelines further. Deepen backward integration into REACH-certified powder supply chains to capture sustainability-linked procurement preferences in German and French public hospital tenders. Defend against polymer substitution pressure by expanding automated surgical planning software bundling that external CNC suppliers cannot replicate. For New Entrants and Emerging Players: Direct-to-clinic digital sales platforms offer the lowest-friction route into Italy's underpenetrated Lombardy and Emilia-Romagna orthopedic networks lacking point-of-care manufacturing infrastructure. Target service bureau partnerships with independent Spanish and Italian clinics seeking per-case surgical guide access without capital absorption. Lead with FDM-based anatomical modeling where CE marking pathways remain streamlined. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by industrial metal printing specialists seeking software-to-print workflow capabilities. Five-to-ten year viability favors targets with EU MDR master file repositories and hospital procurement department relationships. Watch ANSM and BfArM guidance evolution on parametric design submissions as the signal for regulatory arbitrage window closure.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Master File Expansion | Accelerates hospital procurement cycles for geometric variants of approved base designs. |
| Point-of-Care Manufacturing Partnership | Positions equipment vendors within French outcome-based 2025-2027 hospital financing frameworks. |
| REACH-Compliant Powder Recycling | Qualifies suppliers for EU Green Deal sustainability-linked public tender preferences. |
| AI-Integrated Surgical Planning | Compresses pre-operative workflow from days to minutes in Netherlands academic centers. |
| Bioprinting Research Consortium | Translates Netherlands tissue engineering toward clinical protocol ahead of EMA classification clarity. |
Research Methodology
EMA guidance documents, EU MDR harmonized standards, and hospital procurement databases formed the secondary backbone, cross-referenced with primary interviews involving biomedical engineering directors, orthopedic surgeons, notified body auditors, and GPO contracts managers. Bottom-up and top-down triangulation validated segment-level estimates against equipment vendor shipment disclosures and national health technology assessment publications.
Bottom-up modeling built from installed base counts, utilization rates, and consumable attach rates across technology modalities, while top-down analysis anchored aggregate market evolution to macro healthcare expenditure trends and regulatory implementation timelines. Segmentation dimensions spanned product type, technology, application, and end-user procurement authority. CAGRs were derived from logistic diffusion curves fitted to point-of-care manufacturing adoption patterns and bioprinting research funding trajectories.
The model holds under stable EU MDR implementation schedules and REACH enforcement continuity; deviation in notified body designation timelines or ECHA substance restriction expansions would shift commercialization trajectories. Forecasts reflect documented assumptions regarding reimbursement coding evolution and hospital capital budget allocation priorities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Smart Bed Market
Medical Devices
Otoacoustic Emissions Hearing Screener Market
Medical Devices
Global Gel Stent Market
Medical Devices
Global Nebulizers Market
Medical Devices
Global Neurovascular Thrombectomy Devices Market
Medical Devices
Pre-Filled Hemostasis Agents Market
Medical Devices
Italy Minimally Invasive Surgery Devices Market
Medical Devices
Global Organs-On-Chips Market
Medical Devices
At-Home Laser Hair Removal Devices Market
Medical Devices
Absorbable Nasal Implant Market
Medical Devices
Global Ultrasound Devices Market
Medical Devices
Prosthetic Liners Market
Medical Devices
Ultrasonic Aspirator Market
Medical Devices
Global Microscopy Device Market
Medical Devices
Europe Renal Denervation Devices Market
Medical Devices
Dosing Units Market