
 Hemorrhage Control System Market | 2026-2036
Hemorrhage Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Hemorrhage Control System Market Foresight
Market Context
The FDA's updated premarket notification pathway for hemostatic devices is realigning the cost-of-entry calculus for trauma care suppliers. Baxter International leverages its plasma-derived hemostat portfolio to sustain leadership in surgical bleeding control. Medtronic anchors its position through integrated operating room systems that bundle hemorrhage management with patient monitoring. Z-Medica specializes in combat-ready granular hemostatic agents that dominate military procurement channels.
Technical Definition and Structural Segments
Hemorrhage control systems comprise mechanical tourniquets, topical hemostatic agents, pressure bandages, and active clotting dressings engineered to arrest bleeding within three to five minutes of application in trauma, surgical, and emergency settings. Tourniquets occupy the largest product category due to military standardization and civilian first responder training mandates. Smart systems and wearable technologies represent the fastest-expanding technology segment as biosensor-integrated devices enable real-time perfusion monitoring during transport. Hospitals command the dominant end-user channel, while emergency medical services generate higher growth velocity driven by pre-hospital trauma protocol upgrades.
Regulatory Frame and Outlook
The FDA, EMA, and ISO 13485 quality management standards collectively shape device approval timelines, clinical evidence requirements, and post-market surveillance obligations for hemorrhage control manufacturers. The EU Medical Device Regulation's stricter conformity assessment procedures are extending market access timelines for chemical hemostatic agents classified as Class III devices. Stakeholders must monitor evolving battlefield trauma protocols and civilian Stop the Bleed campaign expansions to anticipate procurement volume shifts and product specification changes.
Market Dynamics
The convergence of military trauma protocol modernization and civilian Stop the Bleed campaign expansion is compressing procurement cycles while elevating performance specifications for hemostatic technologies across emergency medical services and hospital systems.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated premarket notification reviews for hemostatic dressings are shortening validation timelines and enabling faster commercialization of next-generation clotting agents.
- Granular hemostat chemistry advances:Kaolin-impregnated and chitosan-based formulations demonstrate superior efficacy in coagulopathic bleeding scenarios, driving replacement of legacy cotton gauze in military and civilian trauma kits.
- Emergency medical services protocol upgrades:Pre-hospital hemorrhage control mandates in major metropolitan trauma systems are expanding tourniquet and hemostatic agent carriage requirements for paramedic units.
Market Restraints
- Chitosan raw material concentration:Supply of pharmaceutical-grade chitosan concentrates in Southeast Asian processing facilities, creating vulnerability to marine harvest variability and regional climate disruptions.
- EU MDR Class III conformity assessment:Chemical hemostatic agents face extended notified body review timelines and heightened clinical evidence requirements, delaying market access for novel formulations.
- Mechanical tourniquet commoditization:Windlass and pneumatic designs face price compression from low-cost manufacturing entrants, squeezing margin structures for premium device producers.
Strategic Opportunities
- Smart tourniquet-biosensor convergence:Integration of photoplethysmography and pressure sensors enables real-time limb perfusion monitoring during extended field care, opening premium positioning in critical care transport.
- Rural and frontier EMS networks:Underpenetrated volunteer and tribal emergency services in the Mountain West and Great Plains regions present volume expansion potential for cost-optimized hemorrhage control kits.
- Department of Defense multi-year procurement vehicles:Indefinite delivery/indefinite quantity contracts for combat casualty care equipment provide revenue visibility and volume guarantees for qualified suppliers.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies face capacity constraints at contract research organizations, extending development timelines for novel hemostatic matrices.
- Legacy inventory amortization:Civilian hospital systems carrying depreciated stocks of conventional pressure bandages resist accelerated replacement cycles despite superior efficacy data for advanced hemostats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemorrhage Control System Market |
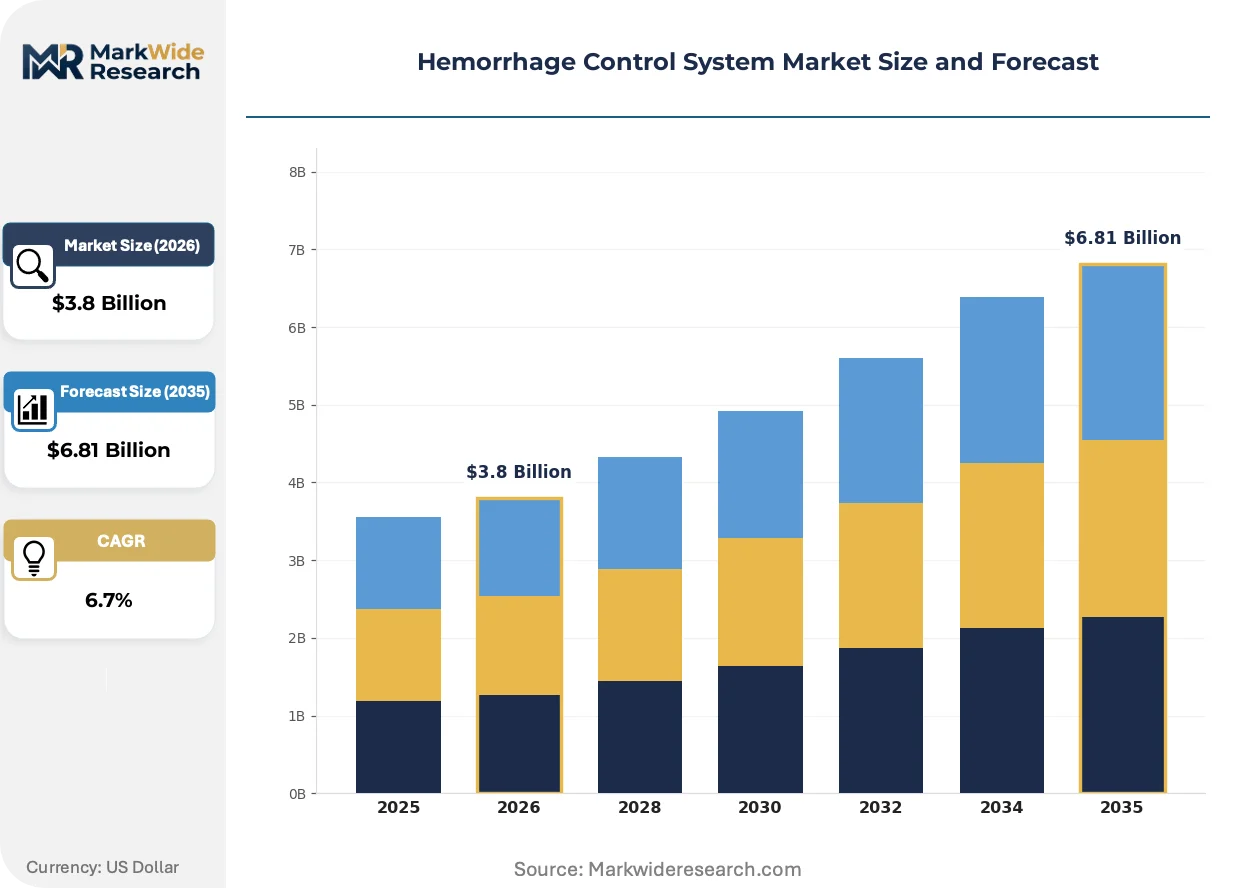
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tourniquets, Hemostatic Agents, Pressure Bandages, Dressing End User: Hospitals, Clinics, Emergency Medical Services, Military Application: Trauma Care, Surgical Procedures, Emergency Response, First Aid Technology: Mechanical Devices, Chemical Agents, Smart Systems, Wearable Technologies |
| Companies Covered | Baxter International Inc., Integra LifeSciences Holdings Corporation, Medtronic plc, B. Braun Melsungen AG, Ethicon, Stryker Corporation, Teleflex Incorporated, Z-Medica LLC, Becton, Dickinson and Company (BD), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemorrhage Control System Market Shifts & Advancements
Active clotting technologies are displacing passive mechanical compression across trauma care workflows, while connected device architectures enable data capture that feeds quality improvement and reimbursement justification.
Resorbable hemostatic matrices derived from oxidized regenerated cellulose and gelatin-thrombin combinations are rewriting surgical bleeding management protocols by eliminating foreign body removal requirements. Academic medical centers and Level I trauma centers are standardizing these products across orthopedic and cardiovascular service lines. The technology is compressing operative time and reducing transfusion dependency, forcing conventional mechanical hemostat suppliers to demonstrate equivalent clinical-economic value.
EMA's Medical Device Coordination Group guidance on hemostatic agent biocompatibility testing is elevating documentation requirements for substances in contact with circulating blood. Manufacturers must now submit extended pyrogenicity and hemolysis data packages, extending preparation phases for CE marking applications. Surgical hemostat portfolios face the steepest compliance burden, with reformulation timelines stretching eighteen to twenty-four months for legacy products.
Hospital value analysis committees are consolidating hemorrhage control purchasing through integrated delivery network contracts that bundle tourniquets, hemostatic dressings, and pressure bandages under single-source agreements. This channel compression disadvantages standalone device suppliers without comprehensive trauma kit portfolios. The concentration is most pronounced in the Southeastern United States, where large health systems operate centralized distribution for dozens of affiliated facilities.
Hemorrhage Control System Market Segmentation
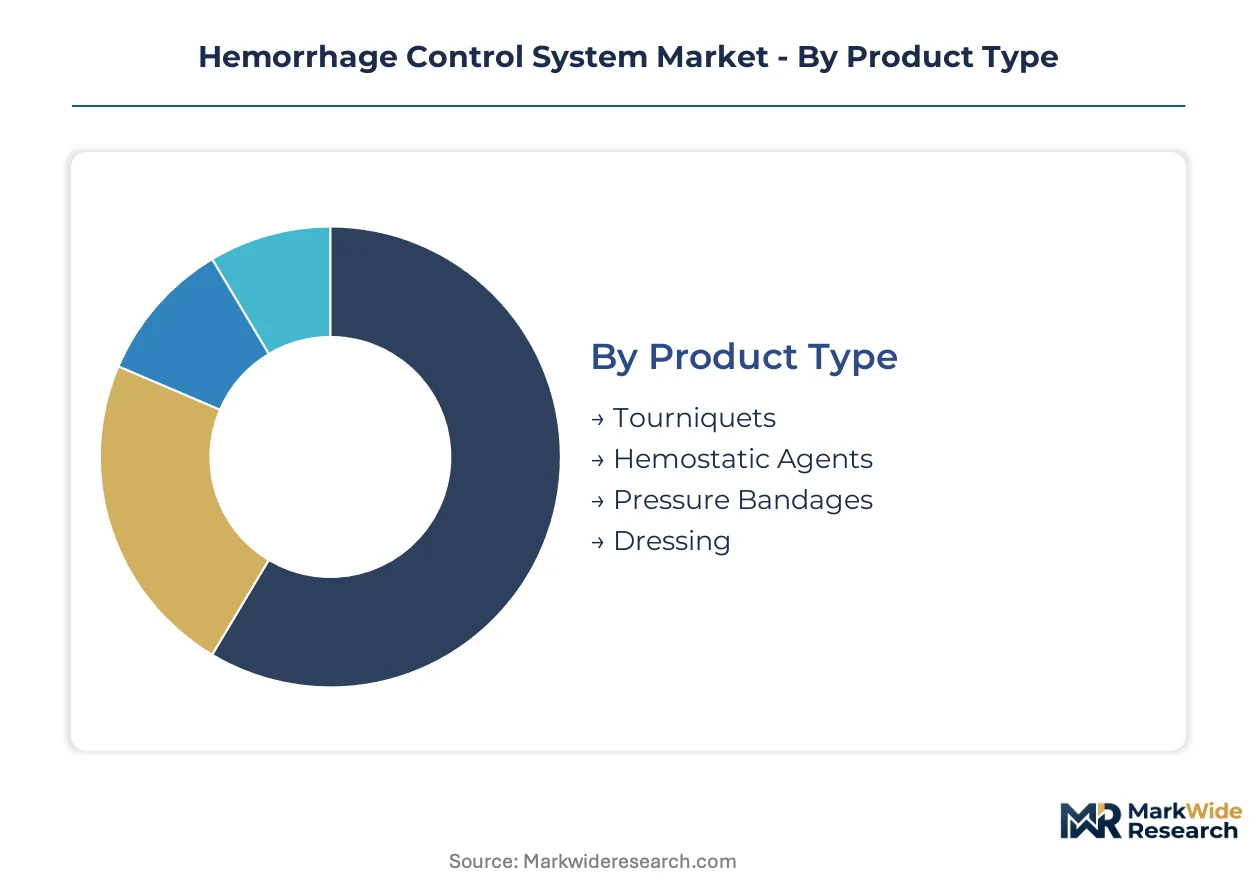
Hemorrhage control system procurement patterns diverge sharply across clinical settings and operational environments, requiring suppliers to align product specifications with distinct performance thresholds and regulatory pathways. Understanding these segment boundaries enables targeted portfolio positioning and channel investment decisions.
Product Type:
Material composition and deployment mechanics differentiate product categories, with military standardization and civilian protocol adoption driving divergent specification requirements.
- Tourniquets:Windlass and pneumatic mechanical designs dominate military trauma kits and civilian first responder protocols, with NATO standardization mandating specific load-bearing and application speed benchmarks. United States Department of Defense contracts and civilian Stop the Bleed campaign expansions concentrate demand in North American procurement channels.
- Hemostatic Agents:Kaolin-impregnated gauze and chitosan-based granular formulations demonstrate superior efficacy in coagulopathic bleeding scenarios, displacing legacy cotton gauze across emergency medical services and surgical suites. FDA 510(k) pathway streamlining accelerates validation timelines for novel clotting chemistries.
- Pressure Bandages:Elastic wrap systems with integrated pressure bars enable single-operator application in field conditions, serving as standard issue across military and civilian emergency response inventories.
- Dressing:Active clotting dressings incorporating oxidized regenerated cellulose or gelatin-thrombin combinations eliminate foreign body removal requirements in surgical settings, compressing operative time and reducing transfusion dependency.
Tourniquets lead on scale; hemostatic agents lead on momentum.
End User:
Procurement authority and reimbursement mechanisms shape purchasing behavior across institutional buyers, with volume concentration and growth velocity diverging significantly.
- Hospitals:Level I trauma centers and academic medical centers standardize resorbable hemostatic matrices across orthopedic and cardiovascular service lines, with value analysis committees consolidating purchasing through integrated delivery network contracts.
- Emergency Medical Services:Pre-hospital hemorrhage control mandates in major metropolitan trauma systems expand tourniquet and hemostatic agent carriage requirements for paramedic units, generating higher growth velocity than hospital channels.
- Clinics:Outpatient surgical centers and urgent care facilities adopt cost-optimized hemorrhage control kits for procedural bleeding management, with purchasing decisions influenced by group purchasing organization contracts.
- Military:NATO member states expand battlefield trauma kit inventories through multi-year indefinite delivery/indefinite quantity contracts, with combat casualty care equipment specifications dictating product development priorities.
Hospitals anchor volume concentration; emergency medical services expand most quickly.
Application:
Clinical context determines performance specifications, with time-to-hemostasis requirements and environmental constraints driving technology selection.
- Trauma Care:Civilian trauma centers and military field hospitals demand three-to-five-minute bleeding arrest capabilities, with protocol standardization across Stop the Bleed campaigns and battlefield trauma guidelines creating procurement volume.
- Surgical Procedures:Operating room integration requires hemostatic technologies compatible with patient monitoring systems, with Medtronic and Baxter bundling hemorrhage management into comprehensive surgical platforms.
- Emergency Response:First responder deployment in unpredictable environments necessitates ruggedized, temperature-stable formulations with extended shelf life and minimal training requirements.
- First Aid:Commercial and industrial safety programs drive demand for layperson-accessible hemorrhage control kits, with automated external defibrillator placement models informing distribution strategies.
Surgical procedures lead on scale; trauma care leads on momentum.
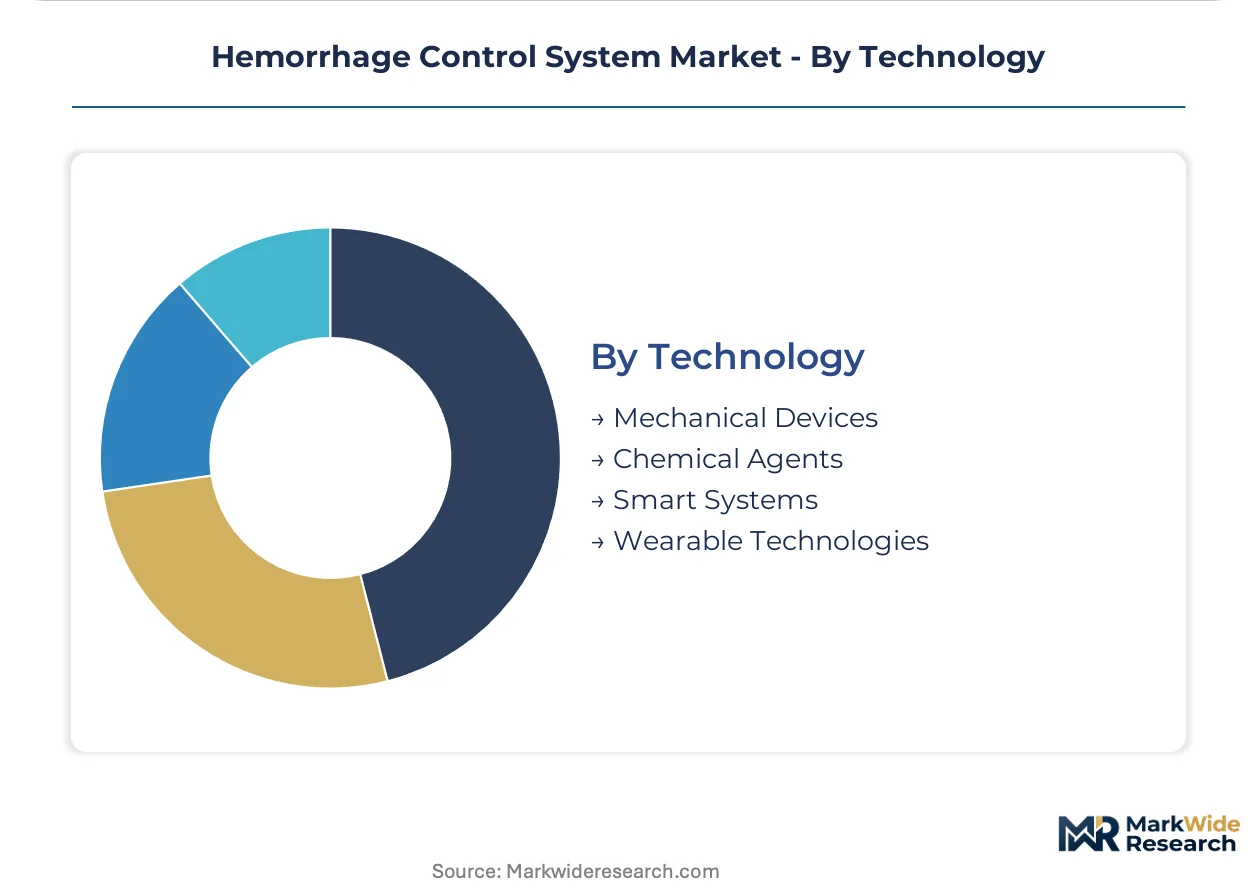
Technology:
Underlying mechanism of action and device architecture determine regulatory classification, reimbursement coding, and competitive differentiation potential.
- Mechanical Devices:Tourniquets and pressure bandages face commoditization pressure from low-cost manufacturing entrants, squeezing margin structures for premium device producers despite sustained volume.
- Chemical Agents:Chitosan and kaolin formulations encounter EU MDR Class III conformity assessment delays, with extended notified body review timelines and heightened clinical evidence requirements slowing market access for novel chemistries.
- Smart Systems:Biosensor-integrated devices enabling real-time perfusion monitoring during critical care transport represent the steepest expansion trajectory, with photoplethysmography and pressure sensor convergence opening premium positioning opportunities.
- Wearable Technologies:Continuous hemorrhage monitoring patches and automated compression garments target extended field care scenarios, with data capture capabilities feeding quality improvement and reimbursement justification workflows.
Mechanical devices lead on scale; smart systems lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trauma surgeon density and combat medic training infrastructure concentrate demand in specific national healthcare systems. Military procurement budgets and civilian Stop the Bleed campaign reach determine market penetration depth.
United States
Department of Defense indefinite delivery contracts and Level I trauma center network upgrades drive procurement volume. FDA 510(k) pathway streamlining accelerates validation timelines for novel hemostatic chemistries. Boston and Baltimore medical corridors anchor surgical hemostat manufacturing clusters serving domestic and NATO military customers.
Germany
Bundeswehr combat casualty care modernization and civilian emergency physician staffing mandates expand tourniquet carriage requirements. EU MDR Class III conformity assessment procedures extend notified body review timelines for chemical hemostatic agents. Baden-Württemberg precision engineering clusters produce windlass tourniquet components for European military standardization.
United Kingdom
NHS ambulance service hemorrhage control protocol upgrades and military field hospital equipment refresh cycles generate dual-channel demand. MHRA post-Brexit regulatory alignment with FDA standards accelerates transatlantic product registration. London trauma system procurement consolidates purchasing through integrated care boards.
Israel
Defense Forces combat medic training scale and civilian terror response preparedness elevate tourniquet penetration in emergency services. Ministry of Health medical device registration requirements emphasize battlefield validation data for trauma products. Tel Aviv metropolitan hospitals pioneer smart tourniquet-biosensor integration in critical care transport.
Australia
Rural and remote ambulance service network expansion and mining industry first aid mandates create distributed demand patterns. TGA medical device conformity assessment procedures align with ISO 13485 quality management standards. Melbourne biomedical manufacturing precincts export hemostatic agents to Southeast Asian defense customers.
Hemorrhage Control System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology segments, creating tiered market structure. Baxter International and Medtronic leverage integrated surgical platform bundling to defend hospital procurement relationships. Three archetypes dominate: diversified medical technology conglomerates with trauma care divisions, specialized hemostatic agent manufacturers, and military-focused tactical medical suppliers. Competitive moves concentrate on portfolio diversification through adjacent technology licensing and geographic expansion into underpenetrated EMS networks.
Within the diversified conglomerate tier, Baxter International Inc., Medtronic plc, and Stryker Corporation represent scale-driven positioning across surgical and emergency care channels. Z-Medica LLC exemplifies the military-specialist archetype through combat-focused product development priorities. B. Braun Melsungen AG and Ethicon occupy intermediate positions with European manufacturing footprints and broad trauma care portfolios. These named entities anchor competitive dynamics without exhaustively mapping market participation.
| Leading Market Players |
|---|
| Baxter International Inc. |
| Integra LifeSciences Holdings Corporation |
| Medtronic plc |
| B. Braun Melsungen AG |
| Ethicon |
| Stryker Corporation |
| Teleflex Incorporated |
| Z-Medica LLC |
| Becton, Dickinson and Company (BD) |
| Others |
Supply & Pricing Matrix
Backward integration into pharmaceutical-grade chitosan extraction anchors margin structures for premium hemostatic agent producers while compressing price floors for mechanical tourniquet assemblers dependent on outsourced polymer components. This sourcing divergence separates suppliers who command formulation IP from those exposed to commodity windlass fabrication cycles.
Pricing Analysis
Bundled trauma kit contracts versus standalone device procurement splits pricing power across the market. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status and NATO specification compliance. Cost compression in windlass tourniquets intensifies because Southeast Asian manufacturing entrants replicate load-bearing designs without performance certification investment. Civilian first responder programs exhibit highest price sensitivity; Department of Defense IDIQ vehicles show lowest.
Supply Chain Analysis
Domestic-content mandates in U.S. Department of Defense procurement reshape sourcing toward North American hemostatic gauze finishing facilities. Raw material supply concentrates in Thailand and Vietnam for chitosan, Germany for precision windlass components, and Massachusetts for oxidized regenerated cellulose matrices. Single-source vulnerability concentrates in marine-derived chitosan harvests exposed to regional climate disruption. Distribution runs through integrated delivery network central warehouses and military logistics depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
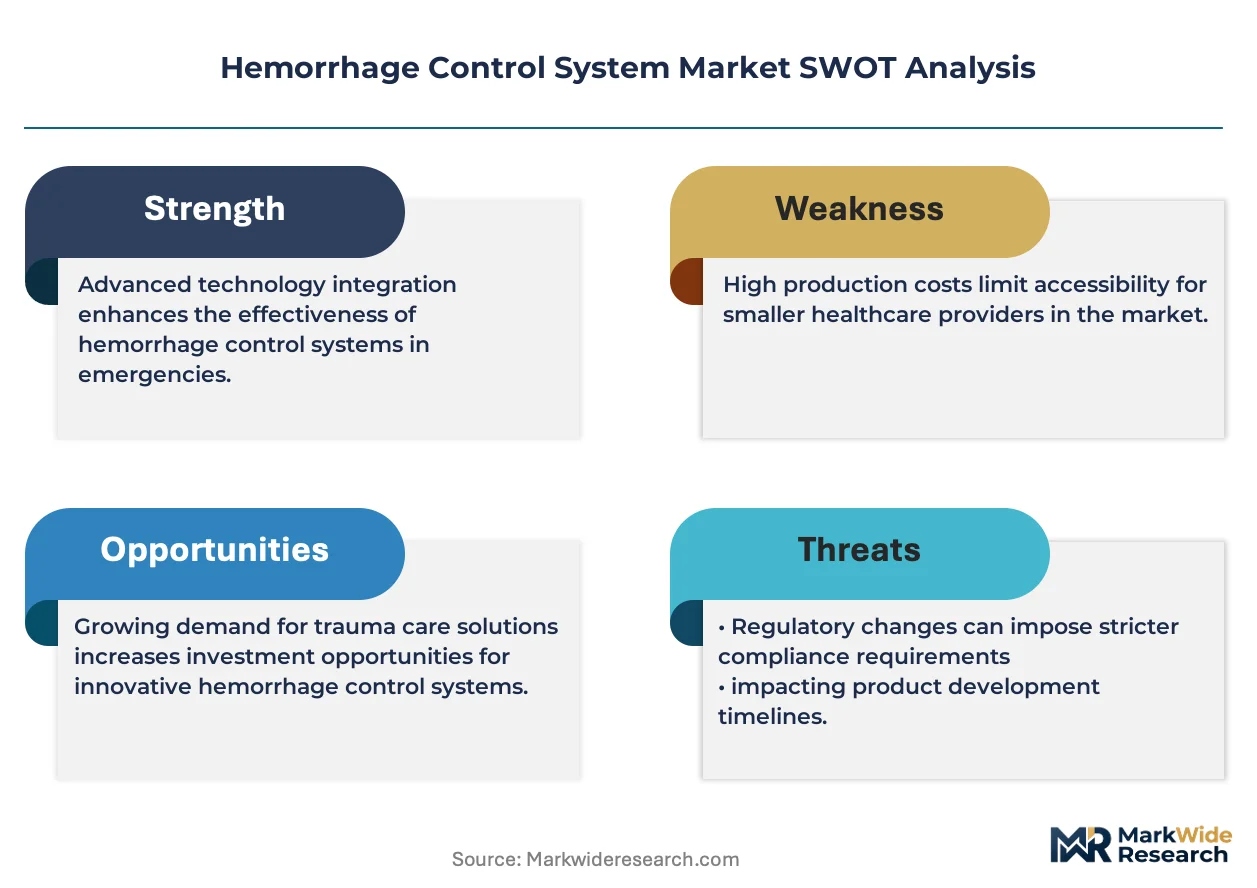
Margin expansion in hemorrhage control systems rests on smart tourniquet premiumization offsetting mechanical device commoditization, with biosensor integration enabling value-based pricing in critical care transport.
For Market Incumbents: Extend surgical hemostat portfolios into resorbable matrices to defend against oxidized regenerated cellulose displacement in orthopedic service lines. Lock in GPO contracts before hospital value analysis committees consolidate purchasing. Prioritize FDA 510(k) pathway familiarity as a certification moat against EU MDR-delayed entrants. For New Entrants and Emerging Players: Direct-to-EMS procurement platforms bypass incumbent distributor relationships in rural and frontier networks. Target volunteer fire departments and tribal emergency services in the Mountain West with cost-optimized kit configurations. Lead with Stop the Bleed campaign alignment to secure municipal training contract attachments. For Investors and Strategic Acquirers: Roll-up economics work for military-focused tactical medical suppliers because Department of Defense IDIQ contract vehicles provide revenue visibility that financial sponsors can leverage across portfolio companies. Five-to-ten-year viability hinges on smart system patent estates. Watch FDA breakthrough device designations for hemostatic agent startups as acquisition timing signals.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerated review timelines for kaolin-impregnated gauze variants compress competitive windows. |
| CE Marking Pathway | EU MDR Class III conformity assessment delays favor incumbents with notified body relationships. |
| Hospital System Partnership | Integrated delivery network bundling contracts lock out standalone device suppliers. |
| Software Companion Development | Perfusion monitoring apps for smart tourniquets enable reimbursement coding separation. |
| Reimbursement Strategy | CPT code alignment for pre-hospital hemorrhage control drives EMS procurement volume. |
Research Methodology
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combining trauma surgeons, biomedical engineers, GPO contracts managers, and military procurement officers with secondary validation against FDA 510(k) filings, EMA MDCG guidance documents, hospital procurement databases, and NATO standardization agreements. Bottom-up product volume estimates and top-down healthcare expenditure allocation triangulate market sizing.
Granularity extends to tourniquet mechanism type, hemostatic agent chemistry class, end-user institutional category, and regional regulatory cluster across the analysis window. CAGRs derive from logistic adoption curve fitting for smart system penetration and linear replacement modeling for mechanical device refresh cycles. Military procurement budget forecasts and civilian trauma center capital expenditure plans inform demand-side inputs.
The model assumes a particular technology adoption path; alternative pathways for biosensor-integrated devices would alter the outlook if reimbursement coding lags hardware development. Forecasts reflect assumptions regarding FDA review velocity, EU notified body capacity, and chitosan supply stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Diagnostic Catheter Market
Medical Devices
Asia-Pacific Antimicrobial Coating for Medical Devices Market
Medical Devices
Next Generation Infusion Pump Market
Medical Devices
Global Ileostomy Market
Medical Devices
Nano Healthcare Technology for Medical Equipment Market
Medical Devices
Cardiac Resynchronization Therapy (CRT) Devices Market
Medical Devices
Global Transcranial Magnetic Stimulators Market
Medical Devices
Absorbable PGLA Surgical Sutures Market
Medical Devices
Asia Pacific Apheresis Market
Medical Devices
Organ Care Market
Medical Devices
China Diabetes Devices Market
Medical Devices
Partial Ossicular Replacement Prosthesis Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Interface Devices Market
Medical Devices
Orthodontic Headgear Market
Medical Devices
Italy Minimally Invasive Surgery Devices Market
Medical Devices
Fluorescence-Guided Surgery Systems Market