
 US Pulse Oximeters Market | 2026-2036
US Pulse Oximeters Market Size, Share, and Industry Trends Forecast 2026-2036
US Pulse Oximeters Market Insights
Aftermarket service revenue is tilting toward remote patient monitoring platforms as hospitals seek recurring subscription models over capital equipment purchases. Masimo leverages its hospital installed base to sustain long-term sensor contracts across intensive care units. Nonin Medical specializes in ruggedized fingertip designs that dominate emergency medical services channels. GE HealthCare anchors enterprise-wide monitoring contracts through integrated IT infrastructure.
A pulse oximeter measures blood oxygen saturation and pulse rate noninvasively using red and infrared light wavelengths transmitted through or reflected from vascularized tissue, typically achieving accuracy within 2% at SpO2 levels above 70%. Fingertip devices serve home care and retail pharmacy channels where convenience and low cost prioritize portability over clinical precision. Tabletop and handheld configurations retain margin pools in hospital settings where multi-parameter integration and alarm management justify premium positioning. Wrist-worn variants are gaining traction in sleep studies and telemedicine applications where continuous overnight monitoring replaces intermittent spot checks.
FDA 510(k) clearance requirements shape device accuracy claims and limit market entry for uncertified imports. The Centers for Medicare & Medicaid Services reimbursement codes for remote patient monitoring directly influence provider procurement decisions and patient cost exposure. Stakeholders must track evolving FDA guidance on pulse oximeter performance across diverse skin pigmentations as equity-focused standards reshape product design requirements and competitive differentiation.
Market Dynamics
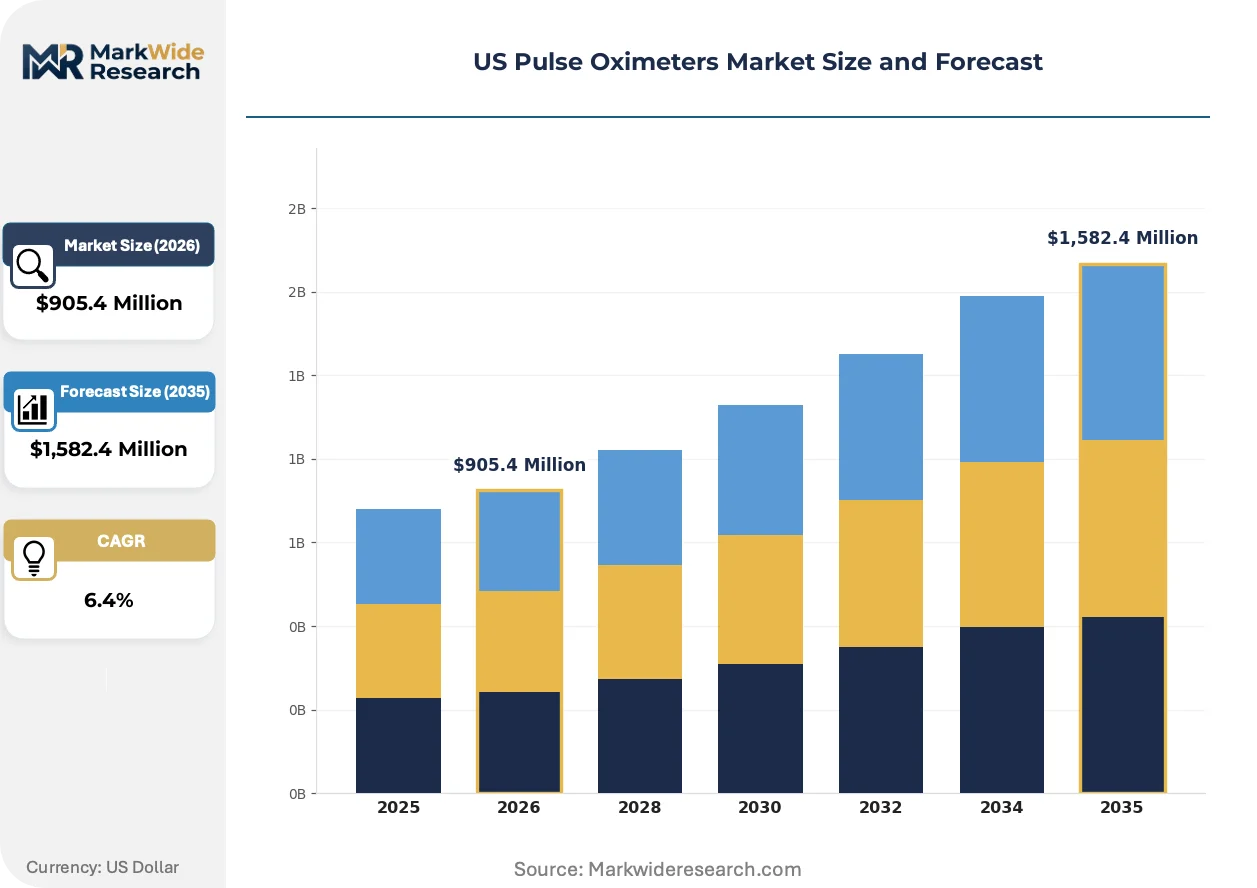
Remote patient monitoring reimbursement codes from CMS are restructuring procurement economics, tilting hospital purchasing toward subscription-based sensor contracts and away from capital equipment ownership models.
Growth Catalysts
- COPD Prevalence Clusters:Medicare beneficiaries in Florida, Texas, and Arizona generate sustained device utilization through remote patient monitoring programs targeting chronic respiratory disease management.
- FDA 510(k) Streamlining:Over-the-counter clearance pathways accelerate direct-to-consumer distribution for fingertip and wrist-worn pulse oximeters in retail pharmacy channels.
- Aging-in-Place Infrastructure:Home healthcare expansion drives adoption of portable monitoring devices among elderly populations managing multiple chronic conditions outside institutional settings.
Market Restraints
- Optical Sensor Accuracy Limitations:Melanin interference with red and infrared light absorption creates measurement variability across darker skin pigmentation, constraining clinical confidence in diverse patient populations.
- Import Certification Barriers:Uncertified Asian manufacturers face FDA enforcement actions that limit low-cost supply penetration and protect domestic pricing tiers.
- Reimbursement Code Fragmentation:Inconsistent state-level Medicaid coverage for remote patient monitoring creates patchy demand patterns outside Medicare Advantage networks.
Strategic Opportunities
- Sleep Study Integration:Wrist-worn continuous monitoring devices capture overnight oxygen saturation data previously requiring polysomnography lab visits, opening telemedicine channels.
- Equity-Focused Design Standards:Evolving FDA guidance on skin pigmentation performance validation creates first-mover advantages for manufacturers investing in multi-ethnic clinical trials.
- IT Infrastructure Bundling:Enterprise-wide monitoring contracts incorporating pulse oximetry into hospital electronic health record systems lock in long-term sensor replacement revenue.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Shortage of specialists combining optical physics expertise with regulatory compliance knowledge delays product development timelines and increases R&D overhead.
- Legacy Alarm Integration Complexity:Multi-parameter bedside monitors from incumbent vendors use proprietary communication protocols that complicate third-party pulse oximeter connectivity and limit interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Pulse Oximeters Market |
| Market Size in 2026 | $905.4 Million |
| Market Size in 2035 | $1,582.4 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Fingertip, Wrist-worn, Tabletop, Neonatal Technology: Optical Sensors, Reflectance, Transmission, Photodiode, OLED Display Application: Home Care, Emergency Care, Sports & Fitness, Sleep Studies, Telemedicine End User: Hospitals, Ambulatory Care Centers, Clinics, Home Healthcare Services |
| Companies Covered | Masimo, ICU Medical, Philips Respironics, Medtronic, Nonin Medical, GE HealthCare, Koninklijke Philips, Drägerwerk, Nihon Kohden, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Pulse Oximeters Market Trends and Innovations
Digital health convergence and regulatory pressure on measurement equity are compressing product development cycles while expanding the addressable population for continuous monitoring applications.
Reflectance-based pulse oximetry is collapsing the distinction between spot-check fingertip devices and continuous monitoring systems by enabling accurate measurements from forehead, chest, and wrist placement. Emergency medical services units are adopting these sensors for patient transport where finger perfusion is compromised. The technology is collapsing the traditional segmentation between acute care and ambulatory monitoring hardware categories.
FDA draft guidance on pulse oximeter accuracy across skin pigmentation is mandating expanded clinical validation datasets before 510(k) clearance approval. Device manufacturers must now submit performance data from subjects representing the full Fitzpatrick skin type spectrum. Hospital procurement committees are prioritizing vendors with documented equity compliance, reshaping competitive qualification criteria.
Subscription-based sensor replacement models are displacing capital purchase arrangements in integrated delivery networks seeking to align device costs with patient monitoring revenue. Health systems in Arizona and Florida are piloting per-patient-per-month pricing for remote COPD management programs. This shift concentrates purchasing authority with centralized supply chain offices rather than individual clinical departments.
US Pulse Oximeters Market Segmentation
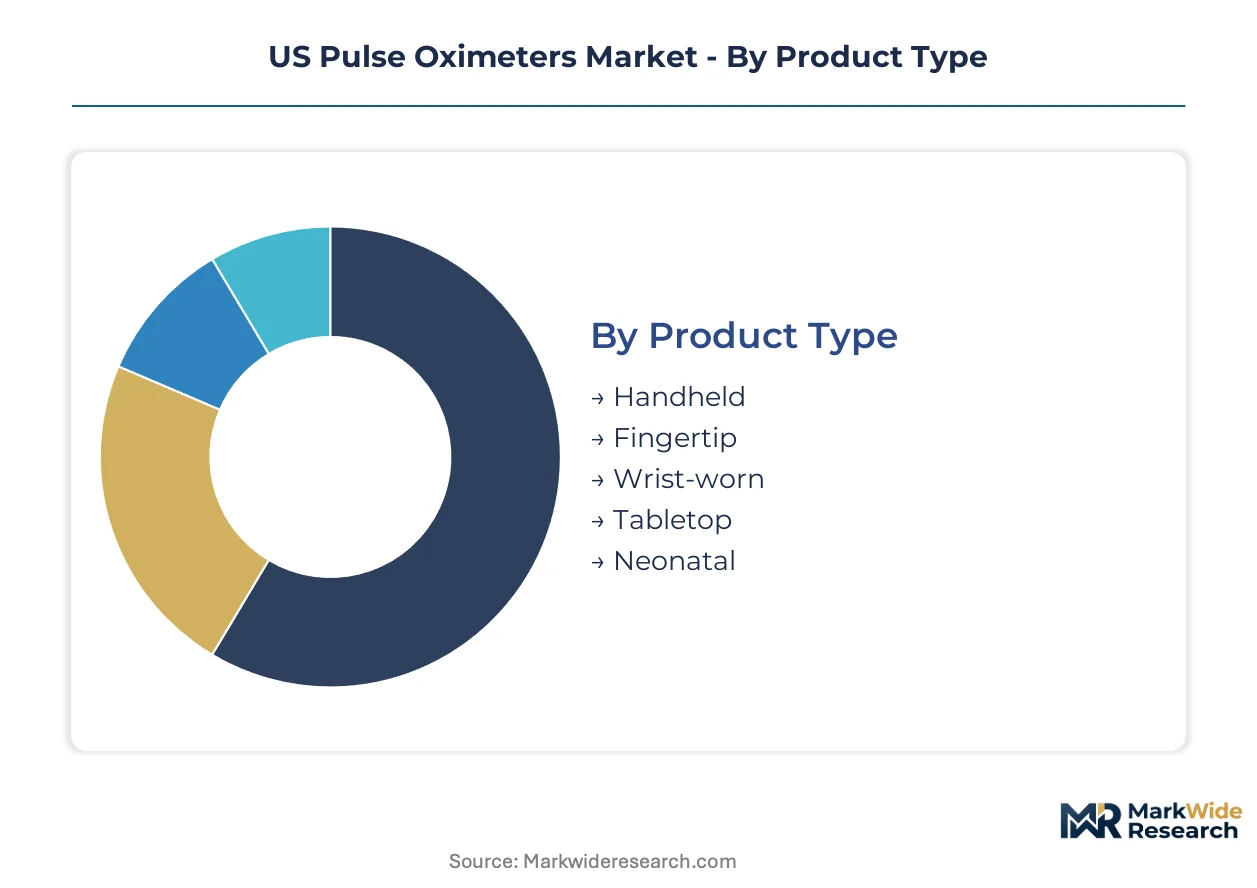
Segmentation in the US pulse oximeter market determines service contract structures and sensor replacement cadences. Product durability varies sharply across use environments, from hospital bedside units to consumer wrist-worn devices. Each segment carries distinct regulatory pathways and reimbursement eligibility under CMS codes.
Product Type:
After-sales-service intensity diverges dramatically across form factors, with hospital-grade tabletop units requiring quarterly calibration and fingertip devices generating no recurring revenue.
- Fingertip:Clip-on designs using dual-wavelength LEDs dominate retail pharmacy and direct-to-consumer channels. Medicare-reimbursed remote patient monitoring programs in Florida, Texas, and Arizona drive bulk procurement for COPD management among aging beneficiaries.
- Tabletop:Multi-parameter monitors integrate pulse oximetry with ECG and blood pressure modules in intensive care settings. Hospital procurement committees prioritize FDA 510(k) clearance and alarm interoperability with existing bedside infrastructure.
- Handheld:Portable units serve ambulatory care and emergency transport where rapid deployment matters. Battery life and shock resistance differentiate commercial offerings.
- Wrist-worn:Continuous monitoring capabilities capture overnight oxygen saturation data for sleep studies and telemedicine applications. Reflectance-based sensors enable placement when finger perfusion is compromised.
- Neonatal:Specialized sensors accommodate low perfusion states and fragile skin in neonatal intensive care units. Wrap-around designs prevent pressure injury while maintaining measurement accuracy.
Fingertip devices hold the largest share; momentum sits with wrist-worn configurations.
Technology:
Cost tiers separate validated clinical-grade sensors from consumer wellness devices lacking FDA clearance.
- Optical Sensors:Red and infrared LED pairs transmit through vascularized tissue to calculate oxygen saturation. Transmission-mode configurations retain margin pools in hospital settings where precision justifies premium positioning.
- Reflectance:Forehead and chest placement expands monitoring options when peripheral circulation is inadequate. Emergency medical services units in Texas and Arizona adopt these sensors for patient transport scenarios.
- Transmission:Traditional finger-based measurement remains the clinical gold standard for spot-check applications. FDA validation requirements constrain uncertified import penetration.
- Photodiode:Light detection components determine signal-to-noise ratios and measurement stability across skin pigmentation variations. Manufacturers investing in multi-ethnic clinical trials gain procurement preference.
- OLED Display:High-contrast screens improve readability in low-light clinical environments and direct sunlight for emergency responders. Display durability affects total cost of ownership calculations.
Optical sensors hold the largest share; reflectance technology is climbing the fastest.
Application:
Volume concentrates in chronic disease management programs where CMS reimbursement codes directly influence provider procurement decisions.
- Home Care:Aging-in-place infrastructure drives adoption of portable monitoring devices among elderly populations managing multiple chronic conditions outside institutional settings. Medicare Advantage networks in Florida prioritize remote patient monitoring for COPD beneficiaries.
- Emergency Care:Ruggedized designs withstand field conditions while delivering rapid assessment capabilities. Emergency medical services channels demand rapid response times and battery reliability.
- Sports & Fitness:Consumer wellness applications track recovery metrics and altitude acclimation. Direct-to-consumer distribution bypasses clinical validation requirements.
- Sleep Studies:Overnight continuous monitoring replaces intermittent spot checks previously requiring polysomnography lab visits. Telemedicine channels expand access to sleep apnea diagnosis.
- Telemedicine:Remote consultation platforms integrate pulse oximetry data into electronic health record systems. Subscription-based sensor replacement models align device costs with per-patient-per-month pricing.
Home care holds the largest share; sleep studies are expanding most quickly.
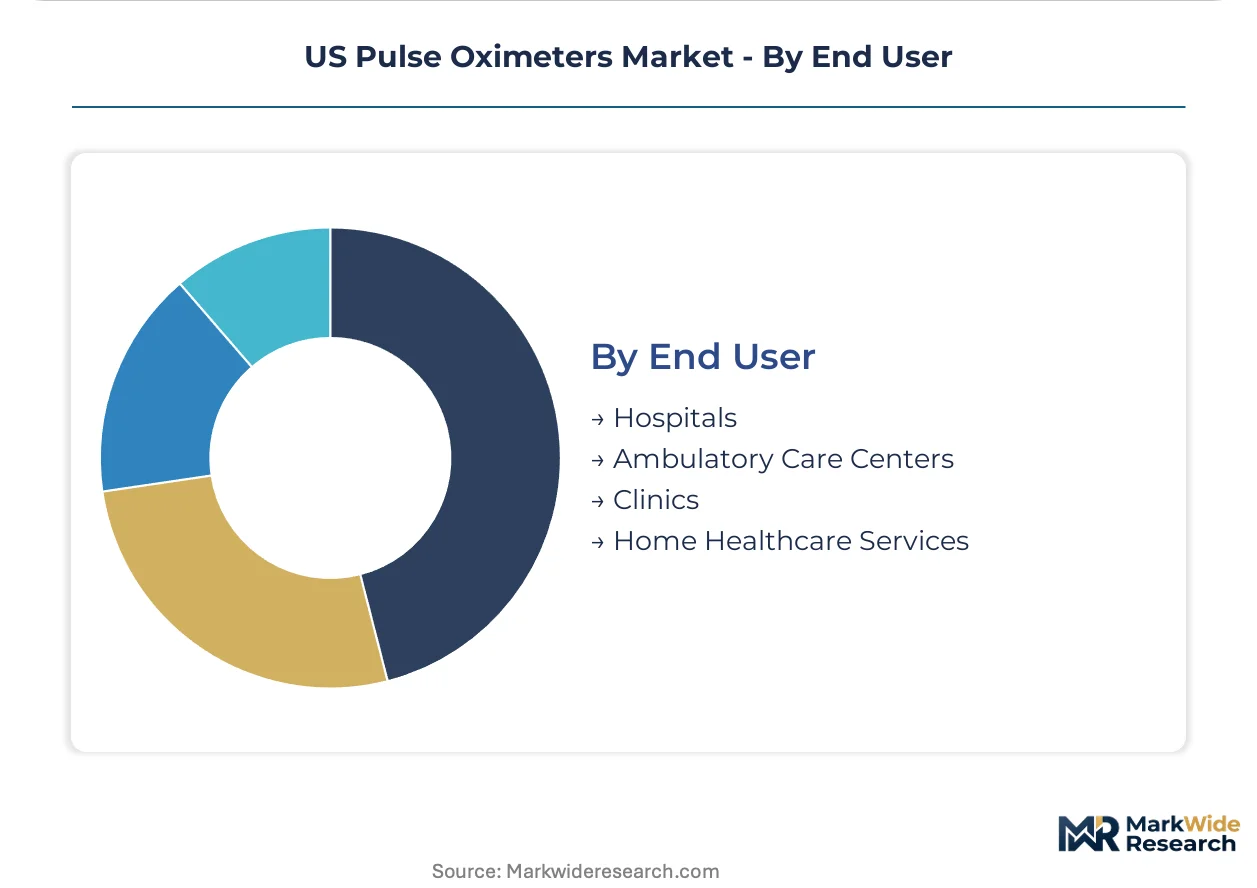
End User:
Customer type determines purchasing authority concentration, from centralized hospital supply chain offices to individual home healthcare agencies.
- Hospitals:Enterprise-wide monitoring contracts lock in long-term sensor replacement revenue through integrated IT infrastructure. GE HealthCare and Masimo compete on alarm management and electronic health record connectivity.
- Home Healthcare Services:Medicare-reimbursed programs target chronic respiratory disease management among beneficiaries in high-COPD-prevalence states. Subscription pricing models displace capital equipment ownership.
- Ambulatory Care Centers:Same-day surgical procedures require pre-operative screening and post-operative monitoring. Workflow efficiency drives preference for rapid-read devices.
- Clinics:Primary care integration of remote patient monitoring expands point-of-care diagnostic capabilities. Reimbursement code fragmentation across state Medicaid programs creates patchy demand patterns.
Hospitals hold the largest share; home healthcare services are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across US sub-regions, with Medicare Advantage networks in Sun Belt states driving volume procurement while Northeast academic medical centers prioritize premium-tier accuracy specifications regardless of cost.
Florida
Remote patient monitoring programs for COPD beneficiaries generate sustained device utilization across Medicare Advantage networks. FDA 510(k) clearance requirements shape procurement criteria for home healthcare agencies serving aging populations. Miami-Dade and Tampa Bay metropolitan areas concentrate distribution infrastructure for fingertip and wrist-worn devices.
Texas
Emergency medical services channels demand ruggedized handheld units for patient transport scenarios where finger perfusion is compromised. CMS reimbursement codes for remote patient monitoring directly influence provider purchasing decisions in Dallas-Fort Worth and Houston medical corridors. Reflectance-based sensor adoption accelerates among EMS units operating in rural border regions.
Arizona
High COPD prevalence among Medicare beneficiaries drives subscription-based sensor replacement models in Phoenix and Tucson healthcare systems. Per-patient-per-month pricing pilots align device costs with chronic disease management revenue streams. FDA draft guidance on skin pigmentation performance validation shapes vendor qualification criteria in diverse patient populations.
California
Sleep study integration and telemedicine applications expand demand for wrist-worn continuous monitoring devices in Los Angeles and San Francisco Bay Area health systems. State-level Medicaid coverage variations create patchy demand patterns outside Medicare networks. Academic medical centers prioritize equity-focused design standards in procurement committees.
New York Metro
Enterprise-wide monitoring contracts lock in long-term sensor replacement revenue through integrated IT infrastructure in Manhattan and Long Island hospital systems. Alarm interoperability requirements with existing bedside infrastructure constrain vendor selection. Biomedical engineering talent scarcity delays product development timelines for regional device manufacturers.
US Pulse Oximeters Market Competitive Landscape
Capability concentration sits with sensor technology specialists; scale advantage sits with diversified medical technology conglomerates. The market structures around three tiers: hospital-installed-base incumbents with long-term service contracts, ruggedized portable specialists dominating emergency channels, and integrated IT infrastructure providers anchoring enterprise agreements. Dominant competitive moves include subscription-based sensor replacement models displacing capital purchases and equity-focused clinical trials reshaping FDA clearance pathways.
Within the hospital-installed-base tier, Masimo exemplifies recurring revenue capture through intensive care unit sensor contracts. Among diversified technology conglomerates, GE HealthCare occupies a position anchoring enterprise-wide monitoring infrastructure. On the portable-specialist vector, Nonin Medical represents ruggedized design leadership serving emergency medical services channels.
| Leading Market Players |
|---|
| Masimo |
| ICU Medical |
| Philips Respironics |
| Medtronic |
| Nonin Medical |
| GE HealthCare |
| Koninklijke Philips |
| Drägerwerk |
| Nihon Kohden |
| Others |
Pricing and Supply Chain Analysis
Malaysian contract manufacturers producing optical sensor modules capture margin pools downstream through FDA-validated sensor replacement contracts with integrated delivery networks. This upstream concentration in Southeast Asian electronics manufacturing directly shapes where pricing power accumulates in the US pulse oximeter value chain.
Pricing Analysis
Sensor replacement subscriptions drive lifetime value, displacing capital equipment purchases in hospital procurement. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared clinical units from direct-to-consumer wellness devices. Cost compression in the economy tier stems from uncertified Asian imports facing FDA enforcement. Home healthcare agencies exhibit highest price sensitivity; intensive care units prioritize accuracy specifications regardless of cost.
Supply Chain Analysis
Export-control restrictions on advanced photodiode technology limit flows from certain Asian suppliers to domestic manufacturers. Component sourcing draws from Malaysia, Taiwan, and Mexico for optical sensors, printed circuit boards, and injection-molded housings. Single-source vulnerability concentrates in red and infrared LED supply from specialized semiconductor foundries. Distribution runs through group purchasing organizations and direct hospital contracts rather than retail distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US pulse oximeter market tracks Medicare reimbursement cycles, with remote patient monitoring program expansions driving cyclical recovery in sensor replacement demand.
For Market Incumbents: Build switching-cost moats through electronic health record integration that locks hospital systems into proprietary sensor protocols. Defensive moves center on multi-ethnic clinical trials for FDA equity compliance and exclusive GPO contracts with Sun Belt health systems. The threat of reflectance-based sensors from emergency medical specialists demands backward integration into optical physics R&D. For New Entrants and Emerging Players: Pursue white-space opportunities in sleep study telemedicine platforms where wrist-worn continuous monitoring replaces lab-based polysomnography. The most penetrable segment sits in Medicare Advantage networks across Arizona and Florida seeking per-patient-per-month pricing models. Go-to-market execution targets direct contracts with home healthcare agencies bypassing hospital supply chain gatekeepers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed sensor technology specialists holding FDA 510(k) clearances but lacking IT infrastructure scale. Long-term viability in this market hinges on recurring revenue capture through subscription sensor replacement rather than episodic device sales. Watch FDA final guidance on skin pigmentation validation as the inflection indicator for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Masimo and GE HealthCare lock sensor replacement revenue through EHR-integrated enterprise contracts. |
| FDA Submission | 510(k) clearance with multi-ethnic clinical datasets opens Medicare-reimbursed procurement channels. |
| Software Companion Development | Remote patient monitoring platforms bundle pulse oximetry data into subscription-based chronic disease management. |
| Reimbursement Strategy | CPT code alignment with CMS remote patient monitoring programs determines provider purchasing authority. |
| CE Marking Pathway | European regulatory validation creates export optionality for US manufacturers facing domestic pricing pressure. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) databases, CMS reimbursement filings, and hospital procurement records. Primary interviews engaged biomedical engineers, hospital purchasing committee members, GPO contracts managers, and remote patient monitoring program directors. Secondary validation drew from FDA premarket notification databases, Medicare claims data, and medical device trade flow records. Bottom-up demand modeling triangulated against top-down market sizing across product type, technology, application, and end user dimensions.
Forecast inputs incorporate COPD prevalence projections, Medicare Advantage enrollment patterns, and FDA regulatory timeline assumptions across the analysis window. Segmentation modeling spans product type, technology platform, clinical application, and end user category with additional dimensioning by state-level reimbursement policy clusters. CAGRs derived from regression analysis of historical volume trends against demographic and regulatory drivers. Industry-specific inputs include remote patient monitoring program adoption curves and sleep study telemedicine penetration rates.
Sensitivities concentrate around FDA final guidance timing on skin pigmentation standards and CMS reimbursement code expansions for remote patient monitoring. Forecasts reflect documented assumptions regarding Medicare policy continuity and optical sensor technology substitution rates. Material shifts in FDA equity validation requirements or state Medicaid coverage harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Artificial Organs and Bionics Market
Medical Devices
North America Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Liver-On-Chip Market
Medical Devices
Physiotherapy Laser Wrist Watch Market
Medical Devices
Snare Devices Market
Medical Devices
Sinus Dilation Devices Market
Medical Devices
Germany Anesthesia Devices Market
Medical Devices
Waterproof Orthotics Market
Medical Devices
Balloon Inflation Devices Market
Medical Devices
Sweden Minimally Invasive Surgery Devices Market
Medical Devices
Global Transcatheter Pulmonary Valve Market
Medical Devices
ePTFE Vascular Prosthesis Market
Medical Devices
Catheter Coatings Market
Medical Devices
Laser Therapy Devices Market
Medical Devices
Biodegradable Stents Market
Medical Devices
Vascular Guidewires Market