
 US Solar Films Market | 2026-2036
US Solar Films Market Size, Share, and Industry Trends Forecast 2026-2036
US Solar Films Market Insights
Perovskite tandem integration is broadening efficiency benchmarks for cadmium telluride architectures. First Solar leverages captive semiconductor refining to control feedstock costs across its Ohio and Alabama footprint. Qcells anchors Southeast manufacturing through its Dalton, Georgia facility, while Silfab Solar specializes in automated passivation for bifacial thin-film modules.
US solar films comprise photovoltaic-active layers deposited on flexible or rigid substrates, typically incorporating CdTe, CIGS, or amorphous silicon absorbers with thicknesses below ten micrometers, engineered to convert irradiance into direct current across curved building envelopes and utility-scale arrays. Thin-film CdTe dominates utility procurement due to lower temperature coefficients and favorable levelized cost trajectories in high-insolation climates. Flexible CIGS films occupy emerging building-integrated segments where weight constraints and architectural integration override silicon efficiency premiums.
FERC Order 2023 interconnection reforms and IRA domestic content thresholds administered by the Treasury Department are reshaping qualification criteria for federal tax credits. The EPA's greenhouse gas reporting protocols and state-level renewable portfolio standards in California, Texas, and New York further constrain technology selection toward domestically sourced thin-film supply. Stakeholders must monitor Treasury guidance on transformative mineral processing waivers versus actual domestic polysilide and precursor chemical capacity.
Market Dynamics
IRA domestic content bonuses are restructuring thin-film supply chain economics, forcing module manufacturers to qualify federal tax credits through captive semiconductor refining and domestic precursor chemical production rather than imported feedstock.
Growth Catalysts
- Utility-scale procurement acceleration:Southwestern interconnection queue reforms under FERC Order 2023 favor CdTe thin-film deployments for their lower temperature coefficients and faster permitting timelines in high-insolation zones.
- Perovskite tandem integration:Laboratory efficiency breakthroughs in cadmium telluride-perovskite stacked architectures are compressing the efficiency gap with crystalline silicon, opening new procurement categories for bifacial utility arrays.
- State renewable portfolio mandates:California, Texas, and Arizona RPS obligations with domestic sourcing preferences are redirecting utility procurement toward thin-film modules qualifying for bonus credit structures.
Market Restraints
- Tellurium supply concentration:Refining capacity concentrates in East Asian and Canadian mining operations, exposing CdTe manufacturers to geopolitical feedstock disruption and price volatility.
- Interconnection queue bottlenecks:FERC procedural delays in grid access studies extend project commissioning timelines beyond thin-film module warranty start dates, compressing revenue recognition windows.
- Crystalline silicon cost compression:Chinese polysilicon oversupply and automated wafer slicing advances maintain silicon's levelized cost advantage in moderate-climate installations.
Strategic Opportunities
- Building-integrated photovoltaics expansion:Flexible CIGS films for curved commercial envelopes and residential roofing segments remain underpenetrated where weight constraints and architectural integration override efficiency premiums.
- IRA transformative mineral processing waivers:Treasury guidance on domestic content thresholds creates qualification pathways for thin-film precursor chemicals manufactured in Ohio, Alabama, and Georgia.
- Agrivoltaic dual-use arrays:Semi-transparent thin-film modules enable crop cultivation beneath utility-scale installations, opening new land-access arrangements in agricultural states facing land-use conflicts.
Industry Challenges
- Semiconductor refining talent scarcity:Cadmium and tellurium purification expertise concentrates in legacy mining regions, constraining domestic workforce expansion for new Ohio and Alabama facilities.
- Domestic content certification complexity:Treasury documentation requirements for transformative mineral waivers demand supply chain traceability systems that thin-film manufacturers must build from fragmented precursor chemical sourcing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Solar Films Market |
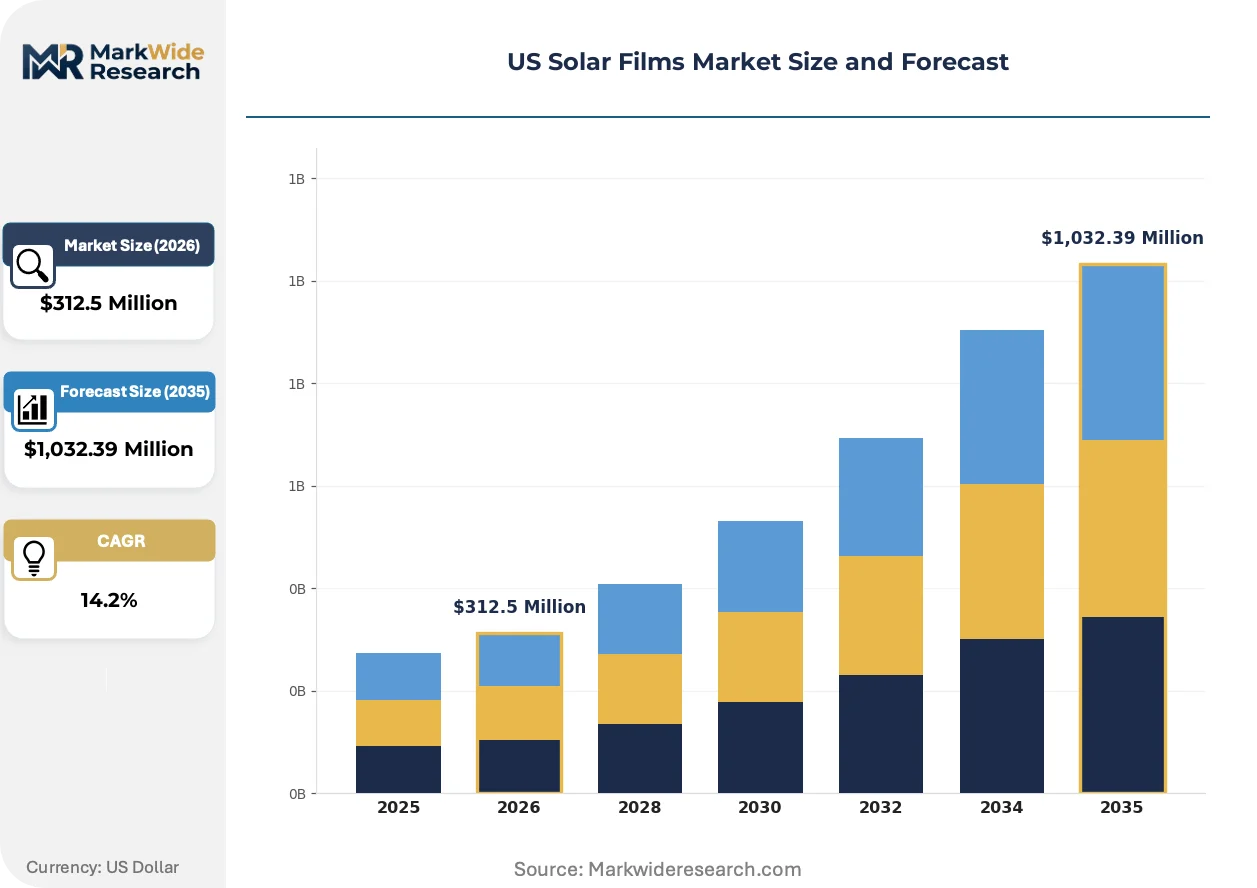
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,032.39 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin-Film, BIPV, Flexible Films, Rigid Films Technology: CIGS, CdTe, Organic Photovoltaics, Amorphous Silicon End User: Residential, Commercial, Industrial, Utilities Installation Type: On-Grid, Off-Grid, Rooftop, Ground-Mounted |
| Companies Covered | Jinko Solar, Mission Solar, First Solar, Solar4America, Heliene, Qcells, Silfab Solar, GAF Energy, Canadian Solar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Solar Films Market Trends and Innovations
Technology convergence between thin-film absorber engineering and tandem cell architectures is compressing efficiency benchmarks while regulatory pressure on domestic sourcing reshapes manufacturing location decisions.
Perovskite-cadmium telluride tandem cells are electrifying utility-scale procurement by stacking wide-bandgap perovskite top layers atop CdTe bottom cells to capture high-energy photons otherwise lost to thermalization. Arizona and Texas utilities are piloting these bifacial configurations for desert installations where spectral splitting maximizes annual energy yield. The technology is electrifying competitive positioning by enabling thin-film manufacturers to bid into premium efficiency tiers previously reserved for silicon heterojunction modules.
FERC Order 2023 interconnection reforms are compressing study timelines for transmission-ready solar projects, directly benefiting thin-film deployments that qualify for fast-track queue positions through standardized inverter configurations. The reforms reduce commercial operation date uncertainty, improving project finance terms for CdTe arrays in California and Texas. Utility procurement teams are responding by consolidating module specifications around domestically manufactured thin-film products that satisfy IRA bonus credit thresholds.
Buyer concentration among independent power producers is consolidating procurement decisions into long-term master supply agreements that displace spot-market module purchasing. These structured offtake arrangements favor thin-film manufacturers with captive polysilide refining and multi-year tellurium supply contracts. The shift is most visible in Texas, where IPP consolidation around utility-scale portfolios has compressed supplier qualification timelines and locked in domestic content-compliant sourcing strategies.
US Solar Films Market Segmentation
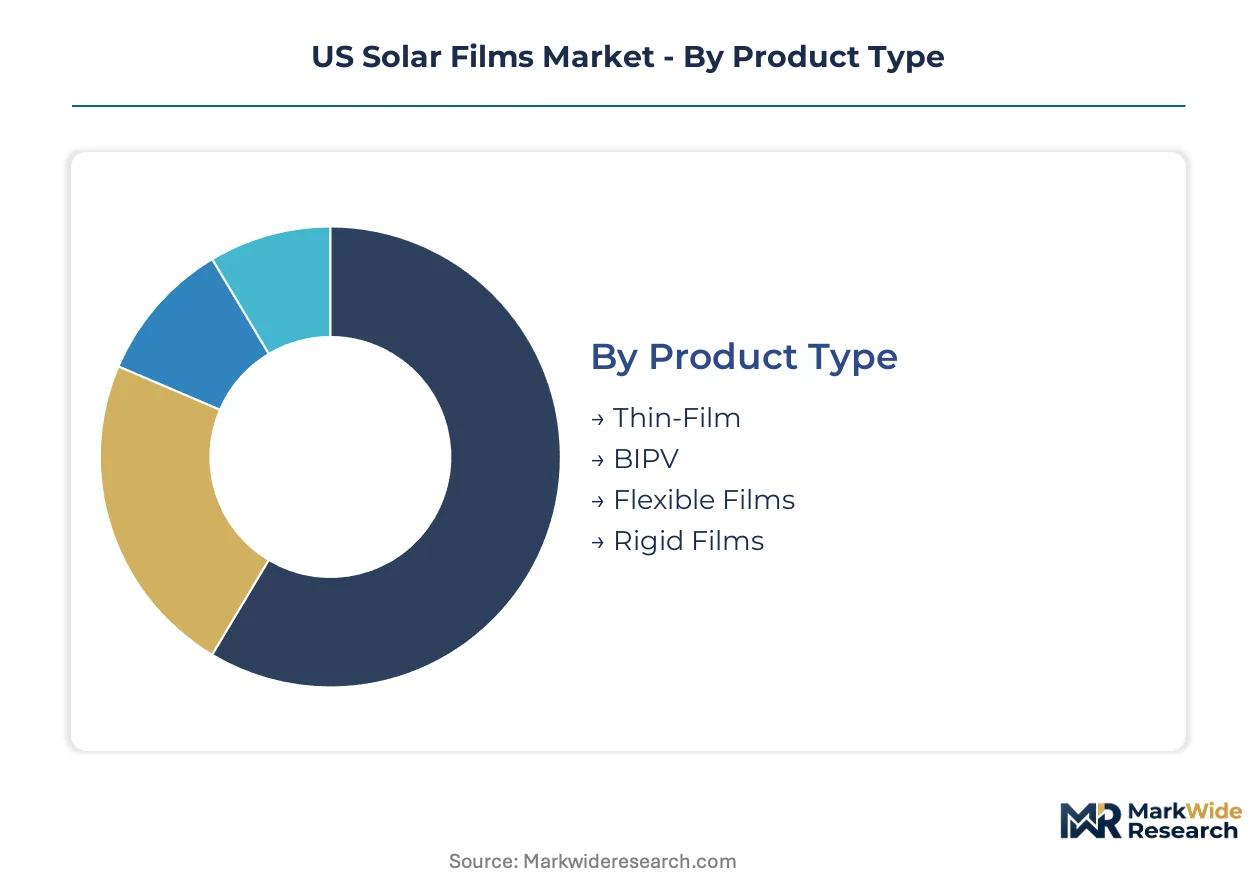
Thin-film solar procurement in the US fragments across four structural dimensions: product architecture, semiconductor chemistry, customer scale, and grid integration mode. Each dimension carries distinct IRA domestic content thresholds and FERC interconnection requirements that reshape supplier qualification pathways.
Product Type:
CdTe thin-film modules require EPA hazardous substance reporting for cadmium content, while BIPV systems trigger local fire code and structural engineering certifications that vary by municipality.
- Thin-Film:Photovoltaic-active layers deposited on glass or metal substrates with absorber thicknesses below ten micrometers, engineered for utility-scale deployment in high-insolation zones. Procurement concentrates in California, Texas, and Arizona where IRA domestic content bonuses favor CdTe modules with captive tellurium refining.
- BIPV:Building-integrated photovoltaic systems that replace conventional envelope materials while generating electricity, subject to IEC 61215 structural load testing and local AHJ fire resistance ratings. Demand clusters in New York and Massachusetts commercial retrofits where aesthetic integration overrides efficiency premiums.
- Flexible Films:Polymer-substrate CIGS modules weighing under three kilograms per square meter, qualifying for accelerated depreciation under MACRS 5-year schedules.
- Rigid Films:Glass-glass laminated thin-film constructions with enhanced durability warranties for desert utility installations.
Leading the category by volume: Thin-Film. Expanding most quickly: BIPV.
Technology:
Cost tiers stratify sharply: CdTe benefits from decades of manufacturing scale, while perovskite tandems command premium pricing for laboratory-validated efficiency gains.
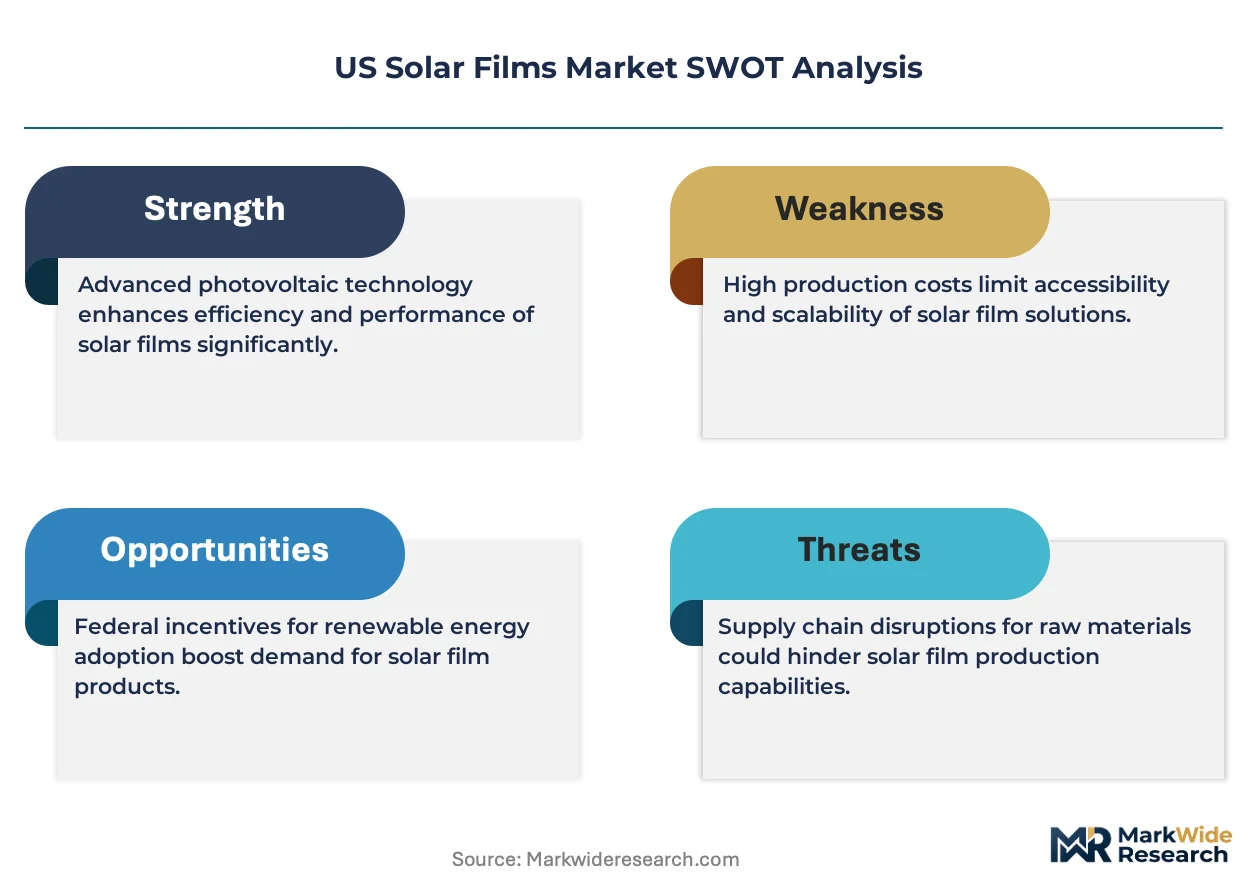
- CIGS:Copper-indium-gallium-selenide absorber deposited through co-evaporation or sputtering, achieving 20%+ laboratory efficiency with superior low-light performance. Residential and commercial rooftop installations in the Northeast favor CIGS for its temperature stability and flexible form factors.
- CdTe:Cadmium telluride deposited via vapor transport deposition, dominating utility procurement through First Solar's vertically integrated Ohio and Alabama manufacturing. Southwestern IPPs specify CdTe for its favorable temperature coefficient and streamlined supply chain traceability under Treasury domestic content rules.
- Organic Photovoltaics:Carbon-based donor-acceptor heterojunction cells with sub-15% efficiency but ultra-low manufacturing capex, piloting in building-integrated segments.
- Amorphous Silicon:Hydrogenated silicon thin-film with degraded outdoor stability, now confined to consumer electronics and calculator applications.
Highest margin capture: CdTe. Steepest efficiency improvement trajectory: CIGS.
End User:
Customer scale determines financing structure and offtake contract duration, with utilities demanding 25-year master supply agreements and residential segments relying on solar loan products.
- Residential:Distributed rooftop installations under 20kW AC capacity, typically financed through PACE bonds or third-party ownership leases. California NEM 3.0 export compensation reforms are compressing payback periods and shifting demand toward battery-coupled thin-film systems.
- Commercial:Behind-the-meter installations from 20kW to 2MW, optimizing demand charge reduction for retail and warehouse facilities in Texas and Florida.
- Industrial:Large on-site generation for manufacturing facilities with 24/7 load profiles, qualifying for IRA investment tax credits with domestic content adders.
- Utilities:Front-of-meter procurement through RFP processes, with Arizona and Texas utilities consolidating specifications around CdTe modules for desert solar farms.
Dominant revenue concentration: Utilities. Fastest contract volume growth: Commercial.
Installation Type:
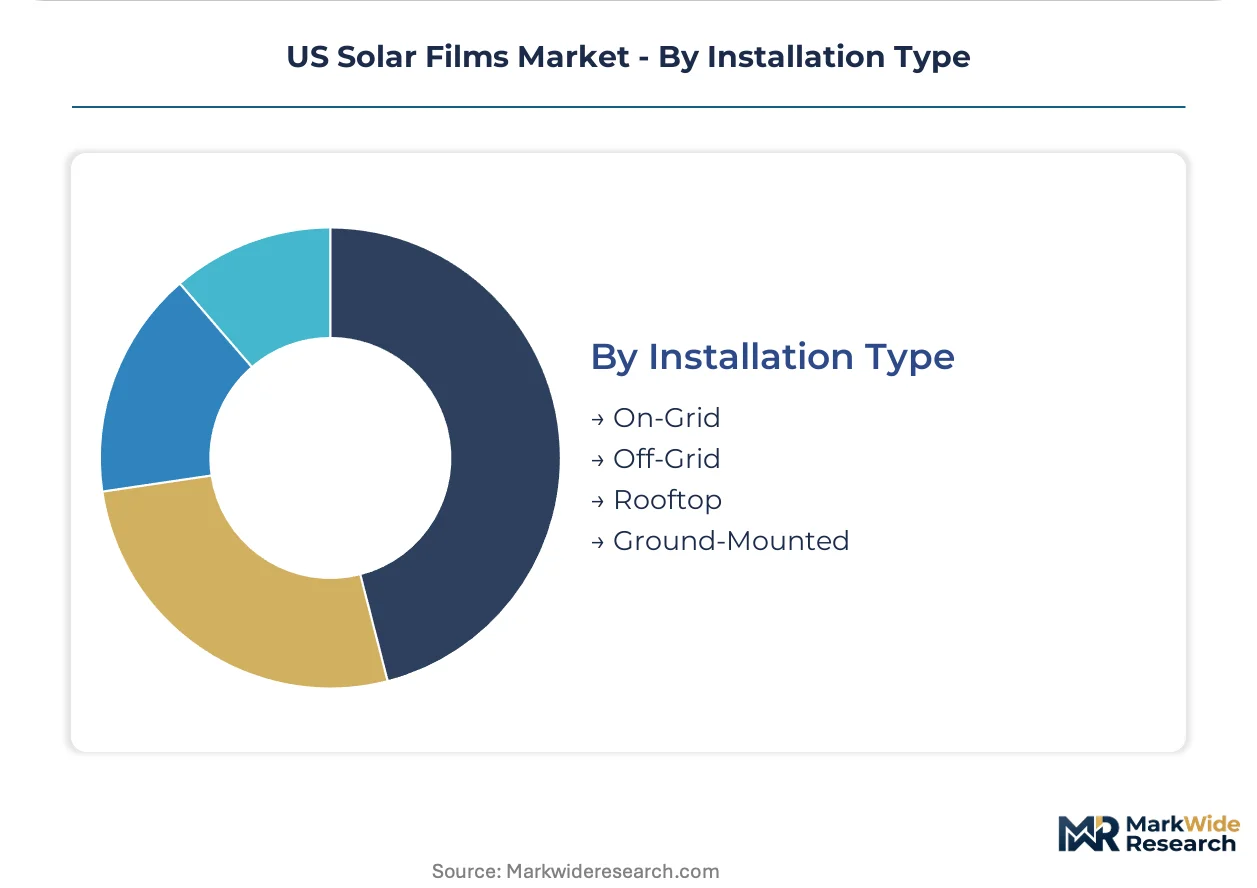
Grid integration mode dictates interconnection study complexity under FERC Order 2023, with on-grid utility-scale projects facing 18-24 month queue timelines versus 3-6 months for behind-the-meter commercial systems.
- On-Grid:Interconnected utility-scale arrays feeding transmission infrastructure, requiring FERC interconnection agreements and NERC reliability compliance. Texas ERCOT and California CAISO queue reforms are standardizing study timelines for thin-film projects with modular inverter configurations.
- Off-Grid:Standalone systems with battery storage, prevalent in rural Arizona and New Mexico agricultural operations beyond distribution feeder reach.
- Rooftop:Building-mounted installations leveraging existing structural elements, subject to local permitting and fire code variations.
- Ground-Mounted:Tracking or fixed-tilt arrays on dedicated land, dominating utility procurement in the Southwest where land availability and insolation align.
Greatest installed capacity: Ground-Mounted. Fastest interconnection timeline improvement: Rooftop.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The IRA's domestic content bonus zones are concentrating thin-film manufacturing investment across Ohio, Alabama, and Georgia. State-level renewable portfolio mandates and FERC interconnection reforms further reshape deployment geography.
Southwest
California, Arizona, and Texas utility-scale procurement dominates CdTe deployment. California's RPS obligations with domestic sourcing preferences redirect IOU procurement toward thin-film modules. Arizona's Palo Verde hub anchors utility pilot programs for perovskite tandem configurations.
Southeast
Georgia and the Carolinas host expanding manufacturing footprints serving regional utility demand. Georgia's Dalton facility anchors Southeast production capacity. Duke Energy's Carolinas RFPs specify domestic content compliance for thin-film qualification.
Midwest
Ohio's semiconductor refining corridor supplies captive tellurium feedstock for CdTe production. Indiana and Illinois utility procurement is accelerating through MISO queue reforms. Toledo-area glass substrate suppliers integrate with adjacent module assembly.
Mountain West
Colorado and Nevada land availability supports ground-mounted utility arrays with favorable insolation profiles. Nevada's permitting reforms compress commercial operation timelines for desert installations. Xcel Energy's Colorado RFPs specify thin-film for high-temperature performance.
Northeast
New York and Massachusetts BIPV demand clusters around commercial retrofit segments. New York's NEM reforms shift residential demand toward battery-coupled systems. Boston-area building code harmonization streamlines CIGS flexible film approvals.
US Solar Films Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated CdTe producers commanding utility procurement while CIGS fabricators serve building-integrated niches. The vendor base concentrates around three strategic archetypes: captive-refining integrated manufacturers, regional contract assemblers, and technology licensors. Capacity expansion and domestic content certification represent the dominant competitive moves reshaping supplier qualification.
Among US-based integrated producers, First Solar and Mission Solar exemplify the captive-refining archetype, while Qcells occupies a position bridging Korean parent technology with Southeast US manufacturing scale. Canadian Solar represents the North American contract assembly model leveraging global cell supply with domestic module finishing.
| Leading Market Players |
|---|
| Jinko Solar |
| Mission Solar |
| First Solar |
| Solar4America |
| Heliene |
| Qcells |
| Silfab Solar |
| GAF Energy |
| Canadian Solar |
| Others |
Pricing and Supply Chain Analysis
Vertically integrated CdTe manufacturers with captive tellurium refining anchor pricing discipline through long-term offtake contracts rather than spot-market volatility, while IPP procurement consolidation reinforces supply security premiums over transactional module purchasing. IRA domestic content bonuses amplify this structure by rewarding captive semiconductor production with federal tax credit eligibility that spot importers cannot match.
Pricing Analysis
Short lead-time premiums dominate utility procurement as FERC Order 2023 queue reforms compress commercial operation date certainty, rewarding manufacturers with Ohio and Alabama production footprints that bypass ocean freight delays. Three-tier pricing structure across premium domestic-content-qualified, standard tariff-compliant, and economy spot-import tiers stratifies by Treasury certification status rather than module efficiency alone. Pricing pressure stems from Chinese polysilicon oversupply bleeding into thin-film competitive benchmarks through crystalline silicon cost compression. Utility-scale IPPs exhibit lowest price sensitivity due to long-term PPA rate base protection, while commercial behind-the-meter segments face acute sensitivity from California NEM 3.0 export compensation cuts.
Supply Chain Analysis
Dual-sourcing mandates from Southwestern utilities require CdTe manufacturers to qualify both Ohio and Alabama refining corridors simultaneously, preventing single-facility dependency despite geographic concentration. Tellurium feedstock concentrates in Canadian mining operations and East Asian refining capacity, while cadmium sourcing draws from zinc smelter byproduct recovery in the US and Mexico. Single-source vulnerability in semiconductor precursor chemicals exposes domestic content compliance to Treasury transformative mineral waiver timing. Distribution runs through master supply agreements with consolidated IPPs rather than fragmented EPC spot purchasing, locking in multi-year volume commitments that stabilize feedstock planning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where IRA domestic content thresholds administered by Treasury erect barrier-to-entry moats favoring manufacturers with captive refining investments over module assemblers dependent on imported feedstock.
For Market Incumbents: Anticipate crystalline silicon-perovskite tandem cost compression by accelerating Ohio and Alabama capacity additions that lock in tellurium supply contracts before feedstock competition intensifies. Prioritize Treasury documentation systems for transformative mineral waivers as the defensive lever against emerging CIGS entrants exploiting flexible-film BIPV white space. Monitor FERC interconnection queue reform implementation delays as the primary threat to revenue recognition timelines. For New Entrants and Emerging Players: Launch via building-integrated photovoltaic channels targeting Massachusetts and New York commercial retrofits where aesthetic integration premiums override efficiency benchmarks and domestic content compliance is achievable through Georgia contract assembly partnerships. Exploit underpenetrated agrivoltaic dual-use segments in agricultural states facing land-use conflicts, where semi-transparent thin-film modules command specialty pricing unavailable to opaque silicon alternatives. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale CIGS technology licensors with proven co-evaporation IP and established UL certification pathways in the Northeast corridor, where BIPV retrofit demand outruns domestic manufacturing capacity. Long-term viability hinges on five-to-ten-year IRA extension certainty beyond current statutory windows. Watch Treasury guidance on transformative mineral processing waivers as the inflection signal determining which precursor chemical investments achieve domestic content qualification.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Tellurium Refining Expansion | Ohio and Alabama corridor investments secure IRA bonus credit eligibility against imported feedstock competitors. |
| Perovskite Tandem Licensing Program | Arizona utility pilot programs validate laboratory efficiency gains for premium utility procurement tiers. |
| BIPV Fire Certification Acceleration | Massachusetts and New York AHJ approvals unlock commercial retrofit segments with architectural premium pricing. |
| Agrivoltaic Dual-Use Partnerships | Agricultural land-access arrangements in Texas and Colorado resolve utility-scale siting constraints. |
| Treasury Waiver Documentation Systems | Supply chain traceability platforms satisfy transformative mineral processing audit requirements for domestic content. |
Research Methodology
Document review covered FERC interconnection filings, Treasury IRA guidance releases, and EPA hazardous substance reporting protocols, complemented by interviews with utility procurement officers, CdTe plant managers, IPP project developers, and thin-film EPC contractors. Secondary validation drew from EIA generation capacity databases, IEA technology roadmaps, and SEC filings from publicly traded solar manufacturers. Bottom-up module shipment data triangulated against top-down utility RFP award tracking.
Cross-referencing historical deployment patterns with expert panel input on IRA implementation timing shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include semiconductor chemistry, product architecture, customer scale, and grid integration mode, with regional regulatory clusters capturing state RPS variation. CAGRs derived from installer survey data on technology switching costs and utility procurement cycle analysis, incorporating tellurium price elasticity and FERC queue reform implementation pace as industry-specific forecast inputs.
Treasury guidance delays, tellurium supply disruption, and crystalline silicon cost compression are the dominant revision risks to modeled outcomes. Deviation in Treasury transformative mineral waiver interpretation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
South America Rooftop Solar Market
Solar Power Systems
DSC Solar Technologies Market
Solar Power Systems
Hairy Solar Panels Market
Solar Power Systems
Solar Transparent Backsheet Market
Solar Power Systems
Residential Solar Inverter Market
Solar Power Systems
Global Solar Panel Tracking Mount Market
Solar Power Systems
Solar Crimp Set Market
Solar Power Systems
Solar Laminator Market
Solar Power Systems
Solar-Powered EV Charging Stations Market
Solar Power Systems
Residential Solar Market
Solar Power Systems
India Solar Energy Market
Solar Power Systems
US Solar PV Market
Solar Power Systems
Indonesia Renewable Energy Market
Solar Power Systems
PV Array Combiner Box Sales Market
Solar Power Systems
Solar Freezer Market
Solar Power Systems
Colombia Solar Energy Market