
 Germany Big Data Analytics in Energy Market | 2026-2036
Germany Big Data Analytics in Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Big Data Analytics in Energy Market Insights
The EU Green Deal is repositioning the cost-of-entry calculus for energy analytics vendors by embedding carbon-accounting requirements into grid operations. Siemens AG leverages its industrial automation heritage to anchor smart metering deployments across German distribution networks. SAP SE competes through native ERP-to-analytics pipelines that sustain enterprise energy management contracts. Bosch Software Innovations GmbH specializes in edge-layer protocols that dominate factory-floor data ingestion for industrial operators.
Germany Big Data Analytics in Energy encompasses the collection, processing, and algorithmic interpretation of high-velocity operational data from generation, transmission, and consumption nodes, typically involving petabyte-scale time-series ingestion with sub-second latency requirements for grid-balancing decisions. Its primary purpose is to optimize asset utilization, reduce curtailment losses, and enable automated dispatch in increasingly renewable-heavy electricity systems. Machine Learning applications command the deepest margin pools as German TSOs prioritize forecast accuracy for wind and solar intermittency. Predictive Analytics segments are maturing fastest in asset optimization use cases where industrial operators already maintain sensor-rich environments. Cloud-Based deployment lags On-Premises in critical infrastructure but captures growing share among renewable energy providers with distributed generation portfolios.
The Federal Network Agency and KBA shape grid-code compliance and data sovereignty requirements that determine which analytics architectures qualify for critical infrastructure certification. Germany's implementation of the EU AI Act through sector-specific ordinances is forcing vendors to document algorithmic transparency in automated trading and dispatch systems. Stakeholders must monitor how the country's national implementation of CSRD extends carbon disclosure obligations to Scope 2 analytics and whether this creates procurement preference for vertically integrated platform providers.
Market Dynamics
The Federal Network Agency's grid-code compliance mandates are compressing deployment timelines for analytics vendors serving German transmission system operators, forcing architectural decisions before algorithmic maturity benchmarks are met.
Growth Catalysts
- EU Green Deal carbon-accounting mandates:Grid operators must embed emissions tracking into dispatch decisions, creating procurement pull for integrated analytics platforms that combine operational and carbon data streams.
- North Rhine-Westphalia industrial corridor demand:Energy-intensive manufacturing clusters require sub-second load balancing, driving real-time ingestion infrastructure investments across the Ruhr region's steel and chemical complexes.
- Machine Learning forecast accuracy:German TSOs prioritize wind and solar intermittency prediction, deepening margin pools for vendors delivering sub-five-percent mean absolute percentage error in renewable generation forecasting.
Market Restraints
- Critical infrastructure certification costs:Federal Office for Information Security evaluation cycles extend eighteen to twenty-four months, freezing vendor roadmaps and inflating pre-revenue burn rates for new entrants.
- On-Premises deployment preference:German utilities resist cloud migration for SCADA-adjacent workloads due to data sovereignty requirements, limiting addressable market for SaaS-native analytics providers.
- Specialized talent scarcity:The intersection of power systems engineering and MLOps expertise concentrates in Munich and Berlin, constraining scaling velocity for vendors outside these clusters.
Strategic Opportunities
- CSRD Scope 2 disclosure expansion:Germany's national implementation extends carbon analytics obligations to mid-cap industrials, opening procurement channels previously locked behind enterprise-scale vendor relationships.
- Edge-layer protocol convergence:Factory-floor data ingestion standards are consolidating around OPC UA over TSN, enabling analytics vendors to collapse integration costs for industrial energy management deployments.
- Baden-Württemberg automotive electrification:Battery cell manufacturing investments by Porsche and Mercedes-Benz suppliers are creating demand for predictive quality analytics tied to energy-intensive electrode coating processes.
Industry Challenges
- Algorithmic transparency documentation:Germany's EU AI Act sector ordinances require explainability logs for automated trading and dispatch systems, forcing vendors to rearchitect black-box ML pipelines into interpretable decision trees.
- Legacy SCADA integration friction:Proprietary protocols from Siemens and ABB dominate existing German distribution networks, complicating API standardization for overlay analytics platforms.
- Cross-border data flow restrictions:Schrems II rulings complicate model training on German grid data using offshore compute, fragmenting vendor cloud strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Big Data Analytics in Energy Market |
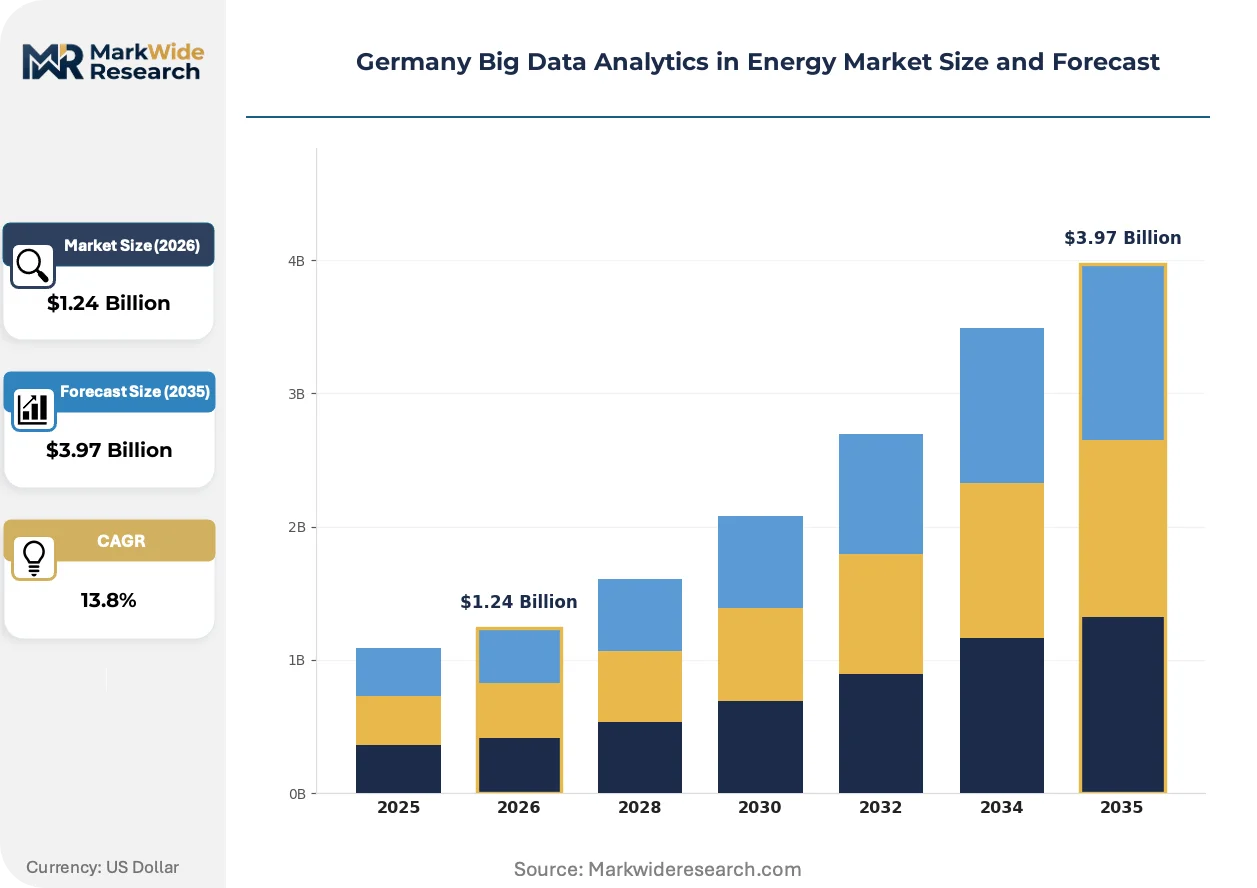
| Market Size in 2026 | $1.24 Billion |
| Market Size in 2035 | $3.97 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Demand Forecasting, Grid Management, Energy Trading, Asset Optimization Technology: Machine Learning, Predictive Analytics, Data Mining, Visualization Tools End User: Utility Companies, Renewable Energy Providers, Industrial Operators, Research Institutions Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | SAS Institute Inc., Cisco Systems, Inc., Siemens AG, ABB Ltd, E.ON SE, SAP SE, Oracle Corporation, Bosch Software Innovations GmbH, IBM Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Big Data Analytics in Energy Market Trends and Innovations
Digital twin architectures are collapsing the latency between physical asset behavior and predictive model updates, compressing the feedback loops that previously separated operational technology from enterprise analytics.
Digital twin platforms are unifying geospatial, meteorological, and SCADA time-series data into single simulation environments for German TSOs. TenneT and 50Hertz are deploying these systems for congestion forecasting across HVDC interconnectors. This convergence is unifying previously siloed planning and operations teams under shared model governance, reducing handoff errors in grid balancing decisions.
The EU AI Act's sector-specific implementation through German ordinances is mandating human-in-the-loop checkpoints for automated dispatch algorithms. Industrial consequence includes frozen procurement cycles as utilities await federal guidance on compliance documentation formats. Grid-scale battery operators are most affected, responding by staffing algorithmic audit functions ahead of vendor platform selections.
Energy-as-a-service contracting is displacing capital-heavy software licensing among Mittelstand manufacturers. Systems integrators are capturing analytics procurement decisions previously owned by CIO offices, shifting vendor engagement models from technical specification to outcome guarantees. This pattern concentrates in Bavaria's automotive supplier tier, where CFO-driven cost-per-kWh targets override traditional feature-checklist evaluations.
Germany Big Data Analytics in Energy Market Segmentation
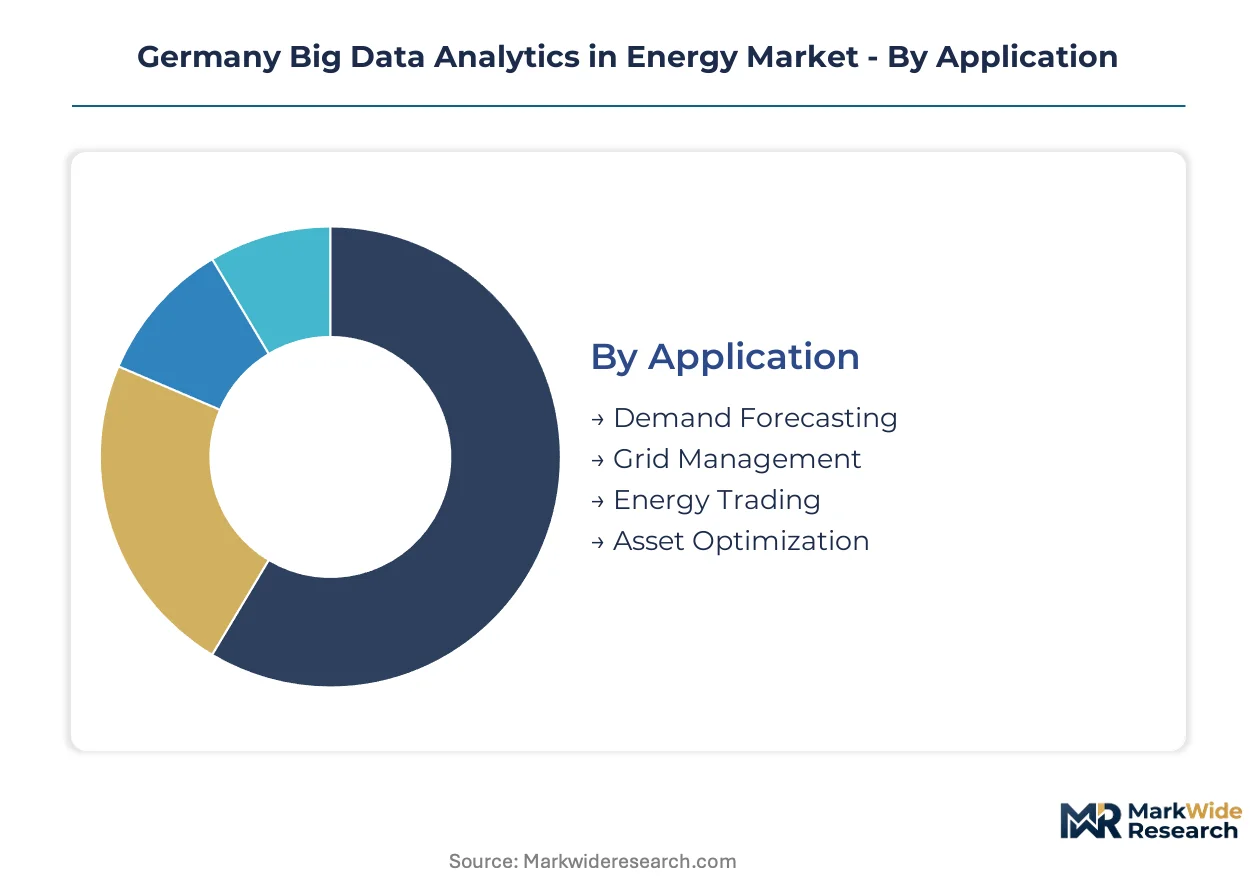
Segmentation reveals how German energy analytics procurement concentrates around grid stability imperatives and carbon-accounting compliance. The technology stack, deployment architecture, and end-user profile together determine vendor qualification for critical infrastructure contracts.
Application:
Algorithmic sophistication varies sharply by operational layer, with real-time control applications demanding sub-second latency while planning functions tolerate batch processing.
- Demand Forecasting:Time-series models ingest meteorological data, industrial production schedules, and historical load curves to predict consumption patterns across transmission zones. German TSOs prioritize forecast accuracy for wind and solar intermittency, deepening margin pools for vendors delivering sub-five-percent mean absolute percentage error.
- Grid Management:Real-time state estimation and congestion forecasting algorithms stabilize voltage and frequency across the German transmission network. North Rhine-Westphalia's steel and chemical complexes drive sub-second load balancing requirements that compress deployment timelines for analytics vendors.
- Energy Trading:Automated bidding algorithms optimize dispatch schedules against day-ahead and intraday market prices.
- Asset Optimization:Predictive maintenance models extend asset life for generation and distribution infrastructure.
Grid Management leads on scale; Demand Forecasting leads on momentum.
Technology:
Capability maturity diverges between established statistical methods and emerging neural architectures, with regulatory pressure forcing explainability trade-offs.
- Machine Learning:Deep learning architectures process petabyte-scale sensor streams for pattern recognition in renewable generation forecasting. The EU AI Act's German sector ordinances mandate human-in-the-loop checkpoints, forcing vendors to rearchitect black-box pipelines into interpretable decision trees.
- Predictive Analytics:Statistical models and survival analysis predict equipment failure probabilities from vibration, thermal, and electrical signature data. Industrial operators in Baden-Württemberg's automotive supplier tier deploy these for energy-intensive electrode coating quality control.
- Data Mining:Unsupervised learning extracts operational insights from historical SCADA archives.
- Visualization Tools:Dashboard interfaces translate complex analytics into dispatch center decision support.
Machine Learning captures the steepest expansion trajectory; Predictive Analytics holds the deepest incumbent penetration.
End User:
Procurement authority varies by organizational scale, with enterprise utilities centralizing analytics decisions while Mittelstand manufacturers delegate to systems integrators.
- Utility Companies:Transmission and distribution operators deploy enterprise-scale platforms for grid-wide optimization. Federal Network Agency grid-code compliance mandates compress vendor selection timelines before algorithmic maturity benchmarks are met.
- Industrial Operators:Energy-intensive manufacturers implement site-level analytics for load scheduling and demand response. Bavaria's automotive supplier tier increasingly procures through energy-as-a-service contracts that shift vendor engagement from feature specifications to outcome guarantees.
- Renewable Energy Providers:Wind and solar asset operators optimize generation forecasting and curtailment minimization.
- Research Institutions:Fraunhofer networks and technical universities validate algorithms for TSO acceptance.
Utility Companies dominate current spend; Industrial Operators are gaining share fastest.
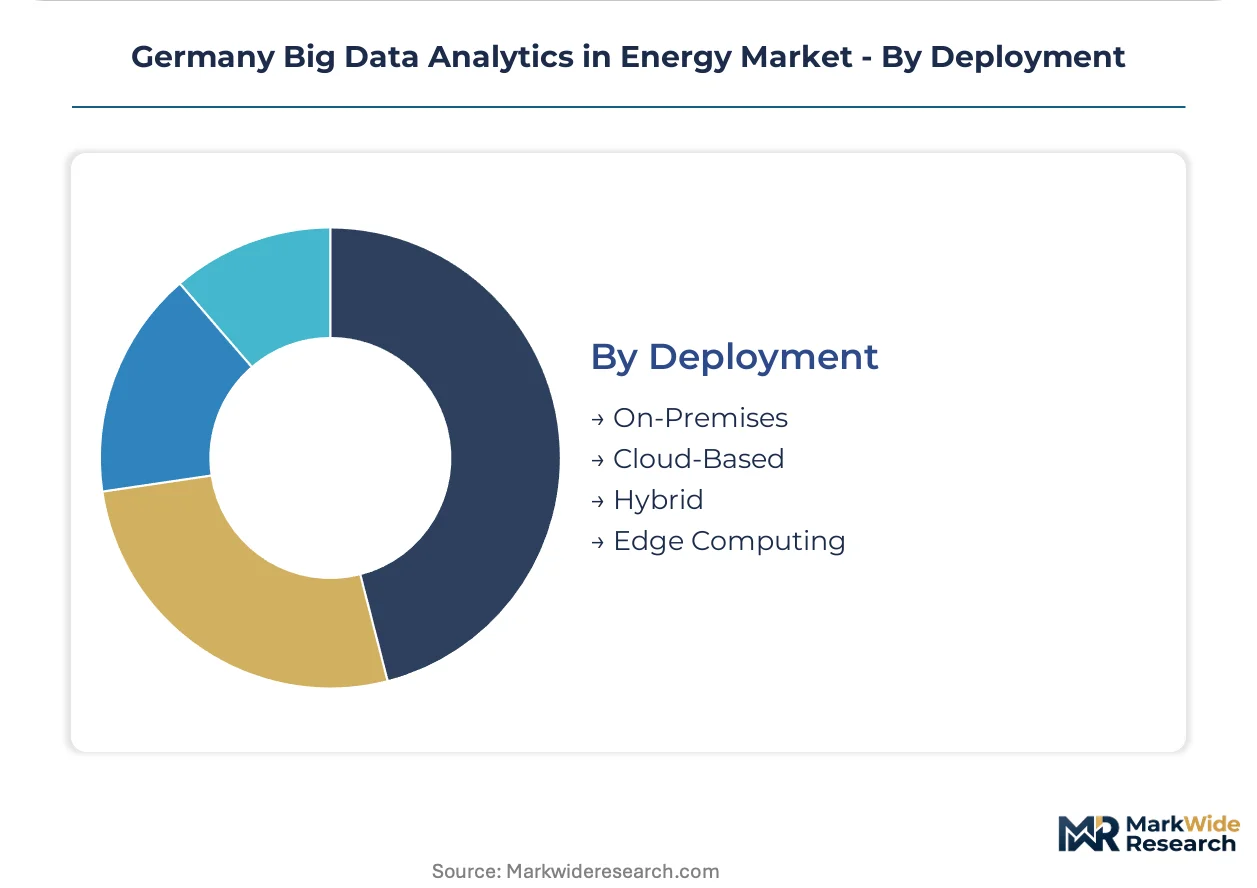
Deployment:
Data sovereignty requirements and latency constraints fragment architecture preferences across the operational technology stack.
- On-Premises:Air-gapped infrastructure hosts SCADA-adjacent workloads subject to Federal Office for Information Security certification. German utilities resist cloud migration for critical control functions, limiting addressable market for SaaS-native providers despite higher total cost of ownership.
- Edge Computing:Distributed processing nodes execute inference locally on factory floors and substations. OPC UA over TSN protocol convergence in North Rhine-Westphalia's industrial corridor enables analytics vendors to collapse integration costs for real-time energy management.
- Cloud-Based:Elastic compute supports model training and non-critical analytics for renewable portfolios.
- Hybrid:Tiered architectures partition sensitive control data from scalable analytics workloads.
On-Premises retains the largest installed base; Edge Computing shows the most rapid adoption acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's energy analytics sector traces its industrial lineage to the Ruhr Valley's coal-to-gas transition and the subsequent Energiewende policy framework that mandated grid digitization from the 2010s onward.
North Rhine-Westphalia
Steel and chemical complexes along the Rhine-Ruhr corridor generate sub-second load balancing requirements that compress deployment timelines for grid analytics vendors. The Federal Network Agency's grid-code compliance mandates force architectural decisions before algorithmic benchmarks mature. Dortmund and Duisburg host the densest concentration of industrial SCADA integration projects.
Baden-Württemberg
Automotive electrification investments by Porsche and Mercedes-Benz suppliers create demand for predictive quality analytics in electrode coating processes. The state's implementation of EU AI Act sector ordinances mandates human-in-the-loop checkpoints for automated dispatch systems. Stuttgart and Karlsruhe anchor the tightest cluster of power systems engineering and MLOps talent.
Bavaria
Automotive supplier tier manufacturers increasingly procure through energy-as-a-service contracts that shift vendor engagement from feature specifications to outcome guarantees. The Federal Office for Information Security certification cycles extend eighteen to twenty-four months for critical infrastructure workloads. Munich concentrates the highest density of vendor headquarters and research institution partnerships.
Lower Saxony
Offshore wind generation clusters in the North Sea require forecast accuracy for intermittency prediction that deepens margin pools for machine learning vendors. TenneT's HVDC interconnector projects deploy digital twin architectures for congestion forecasting. Cuxhaven and Wilhelmshaven serve as primary deployment sites for marine-scale analytics infrastructure.
Hesse
Financial services and data center operators drive cloud-based analytics adoption despite utility resistance to migration for SCADA-adjacent workloads. The state's central location enables cross-border data flow management strategies that navigate Schrems II restrictions. Frankfurt's fiber density supports model training infrastructure for renewable portfolio operators.
Germany Big Data Analytics in Energy Market Competitive Landscape
The competitive structure tilts toward industrial automation heritage players with pre-existing utility relationships. Market concentration reflects the dominance of three strategic archetypes: diversified technology conglomerates with native energy verticals, specialized software vendors with ERP-to-analytics pipelines, and edge-layer protocol specialists with factory-floor integration expertise. Dominant competitive moves include strategic partnerships between analytics providers and transmission system operators, plus technology licensing arrangements that embed vendor platforms into multi-year grid modernization frameworks.
Within the industrial automation tier, Siemens AG and ABB Ltd exemplify archetypes that leverage decades of SCADA deployment relationships to anchor smart metering and grid management contracts. SAP SE and Oracle Corporation occupy positions as enterprise software incumbents sustaining analytics procurement through native ERP integration. Bosch Software Innovations GmbH represents the edge-computing specialist archetype, while IBM Corporation and Cisco Systems, Inc. anchor the IT infrastructure provider segment serving hybrid deployment architectures.
| Leading Market Players |
|---|
| SAS Institute Inc. |
| Cisco Systems, Inc. |
| Siemens AG |
| ABB Ltd |
| E.ON SE |
| SAP SE |
| Oracle Corporation |
| Bosch Software Innovations GmbH |
| IBM Corporation |
| Others |
Pricing and Supply Chain Analysis
The EU Green Deal's carbon-accounting mandates gate both qualified supply and premium-tier pricing access for analytics vendors serving German energy markets. Federal Network Agency certification requirements compress procurement timelines while embedding emissions-tracking capabilities as table stakes for grid-code compliance, forcing price differentiation around algorithmic transparency documentation rather than raw computational throughput.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the German market by certification grade and deployment architecture. Premium tiers command position through Federal Office for Information Security compliance and native ERP integration, while standard tiers compete on forecast accuracy benchmarks. Cost compression in economy tiers is intensifying because renewable energy providers with distributed portfolios resist capital-heavy licensing. Mittelstand manufacturers through energy-as-a-service contracts demonstrate highest price sensitivity, whereas transmission system operators prioritize total cost of ownership over upfront licensing.
Supply Chain Analysis
Specialized semiconductor supply for edge-computing nodes rests on Taiwanese foundry capacity and German automotive-grade sensor fabrication. Cloud compute infrastructure draws from Irish and Frankfurt data center clusters subject to Schrems II cross-border restrictions. Single-source vulnerability concentrates in proprietary SCADA protocol licensing from dominant industrial automation vendors. Distribution runs through systems integrators capturing procurement decisions previously owned by CIO offices, particularly across Bavaria's automotive supplier tier.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's energy analytics sector offers margin expansion through energy-as-a-service contracting models that shift revenue from perpetual licenses to recurring outcome guarantees. Cost-down pressure on cloud infrastructure and edge hardware procurement supports premium-tier margin capture for vendors with pre-certified deployment architectures.
For Market Incumbents: Lock in multi-year grid modernization frameworks with transmission system operators before EU AI Act sector ordinances finalize compliance documentation formats. Deepen vertical integration into edge-layer protocol stacks to defend against specialized software vendors encroaching on factory-floor deployments. Prioritize algorithmic audit function staffing partnerships with Baden-Württemberg automotive suppliers facing human-in-the-loop checkpoint mandates.
For New Entrants and Emerging Players: Begin with CSRD Scope 2 disclosure expansion targeting mid-cap industrials previously locked behind enterprise-scale vendor relationships. The most penetrable segment sits in North Rhine-Westphalia's steel and chemical complexes requiring sub-second load balancing without legacy SCADA integration burdens. Lead with outcome-based contracting that guarantees cost-per-kWh reductions rather than feature-checklist competition.
For Investors and Strategic Acquirers: Roll-up economics work for edge-computing specialists with OPC UA over TSN protocol expertise because factory-floor data ingestion standards are consolidating around time-sensitive networking. Long-term viability over a five-to-ten year window favors vendors with hybrid deployment architectures partitioning sensitive control data from scalable analytics workloads. Watch for inflection when Federal Network Agency publishes final algorithmic transparency documentation templates.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Audit Function Buildout | EU AI Act German ordinances mandate explainability logs for automated dispatch systems. |
| Edge-Layer Protocol Certification | OPC UA over TSN convergence collapses integration costs for industrial energy management. |
| CSRD Scope 2 Analytics Expansion | Carbon disclosure obligations extend procurement channels to mid-cap Mittelstand manufacturers. |
| Digital Twin Architecture Deployment | TenneT and 50Hertz deploy unified simulation environments for HVDC interconnector congestion forecasting. |
| Energy-as-a-Service Contracting | Bavaria's automotive supplier tier shifts vendor engagement from specifications to outcome guarantees. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both procurement pattern data and regulatory implementation timelines. Primary engagement covered utility planning officers at German transmission system operators, IPP project developers optimizing renewable portfolios, EPC contractors integrating analytics into grid infrastructure, and grid operators navigating Federal Network Agency compliance mandates. Secondary validation drew from Bundesnetzagentur regulatory filings, TenneT and 50Hertz infrastructure investment disclosures, Fraunhofer research institution publications, and EU Green Deal implementation progress reports. Bottom-up segment sizing triangulated against top-down market boundary analysis.
Historical reference periods anchored volume and value projections across the modeling period, with segmentation dimensions spanning application layer, technology maturity, end-user procurement authority, and deployment architecture sensitivity to data sovereignty requirements. CAGRs were derived from algorithmic adoption curves weighted by regulatory mandate implementation schedules and industrial capital expenditure cycles. Forecast inputs incorporated renewable generation capacity additions, SCADA modernization investment pipelines, and machine learning talent concentration patterns across Munich and Berlin clusters.
Caveats apply where Federal Network Agency grid-code amendments or EU AI Act sector ordinance finalizations could materially shift the outlook. Forecasts reflect assumptions around certification timeline stability and cross-border data flow regime continuity. A small set of named triggers warrants ongoing watch: algorithmic transparency documentation format releases, Schrems II ruling evolutions affecting offshore model training, and energy-as-a-service contract standardization across German automotive supplier tiers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
GCC Well Testing Services Market
Energy Analytics and Software
Europe Big Data Analytics in Energy Market
Energy Analytics and Software
Italy Big Data Analytics in Energy Market
Energy Analytics and Software
China Big Data Analytics in Energy Market
Energy Analytics and Software
Energy Intelligence Solutions Market
Energy Analytics and Software
Solar Analyzer Market
Energy Analytics and Software
Africa Big Data Analytics in Energy Market
Energy Analytics and Software
Big Data Analytics in Energy Market
Energy Analytics and Software
Carbon and Energy Software Market
Energy Analytics and Software
Netherlands Big Data Analytics in Energy Market
Energy Analytics and Software
Energy and Utilities Analytics Market
Energy Analytics and Software
AI in Energy Market
Energy Analytics and Software
Global Wind Turbine Condition Monitoring System Market
Energy Analytics and Software
Oil Condition Monitoring Market
Energy Analytics and Software
Canada Big Data Analytics in Energy Market
Energy Analytics and Software
France Big Data Analytics in Energy Market