
 China Satellite Connectivity Market | 2026-2036
China Satellite Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
China Satellite Connectivity Market Insights
China's low-earth orbit constellation manufacturing base is fragmenting as provincial governments in Hubei and Shanghai compete for satellite production clusters. China Aerospace Science and Technology Corporation anchors national launch capacity through its Long March rocket family and integrated spacecraft production. CHANG GUANG SATELLITE TECHNOLOGY CO LTD specializes in commercial remote sensing constellations with high-resolution optical payloads. China Telecom extends terrestrial backhaul integration by bundling satellite links with its fiber network reach.
China satellite connectivity encompasses space-based signal transmission systems operating across L-band through Ka-band frequencies, with orbital altitudes spanning 300 to 35,786 kilometers depending on service architecture. These systems provide uninterrupted communications coverage for vessels, aircraft, and ground stations beyond cellular range. LEO technology captures the fastest expansion trajectory due to reduced latency profiles demanded by maritime and aerospace end users. Broadband Internet application segments concentrate margin pools where government subsidies intersect with remote sensing demand from agricultural monitoring programs. Geostationary technology maintains mature revenue streams in video broadcasting despite latency constraints.
NMPA and MIIT jointly govern satellite terminal type-approval and orbital slot coordination, creating compliance barriers for non-domestic equipment vendors. GB standards for electromagnetic compatibility and radio frequency emissions shape product design requirements for terrestrial gateway manufacturers. Stakeholders must monitor SAMR procurement guidelines that increasingly favor domestic constellation operators in government telecommunications contracts.
Market Dynamics
LEO constellation deployment is fragmenting manufacturing capacity across provincial industrial zones while NMPA spectrum reforms force terminal vendors through recertification cycles. This dual pressure compresses margins for equipment suppliers and accelerates vertical specialization among launch integrators.
Growth Catalysts
- Rural broadband mandates:Western provinces including Xinjiang and Tibet deploy satellite backhaul to meet universal service obligations under MIIT connectivity targets.
- Maritime connectivity expansion:Fishing fleets and cargo vessels beyond cellular range drive L-band terminal demand through port authority installation programs.
- GB standard harmonization:Electromagnetic compatibility rules for gateway equipment reduce technical barriers for domestic component suppliers.
Market Restraints
- Launch capacity bottlenecks:Long March vehicle allocation prioritizes national security payloads, constraining commercial constellation deployment schedules.
- Ka-band rain fade:Southern monsoon regions experience signal degradation that limits high-throughput service reliability during peak agricultural monitoring seasons.
- Orbital slot scarcity:ITU coordination queues for geostationary positions extend licensing timelines beyond typical investor return horizons.
Strategic Opportunities
- Aerospace integration:Domestic airline fleets seek continuous connectivity for passenger broadband and cockpit datalink applications.
- Dual carbon alignment:Satellite-enabled precision agriculture supports MEE emissions monitoring for western livestock and crop operations.
- Inter-satellite optical links:Laser cross-connect technology reduces ground gateway dependency for remote sensing constellation operators.
Industry Challenges
- RF engineer scarcity:Ka-band and phased-array antenna design expertise concentrates in Shanghai and Beijing, limiting provincial cluster development.
- Legacy system interoperability:C-band broadcast infrastructure requires gateway hardware capable of multi-band translation without full replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Satellite Connectivity Market |
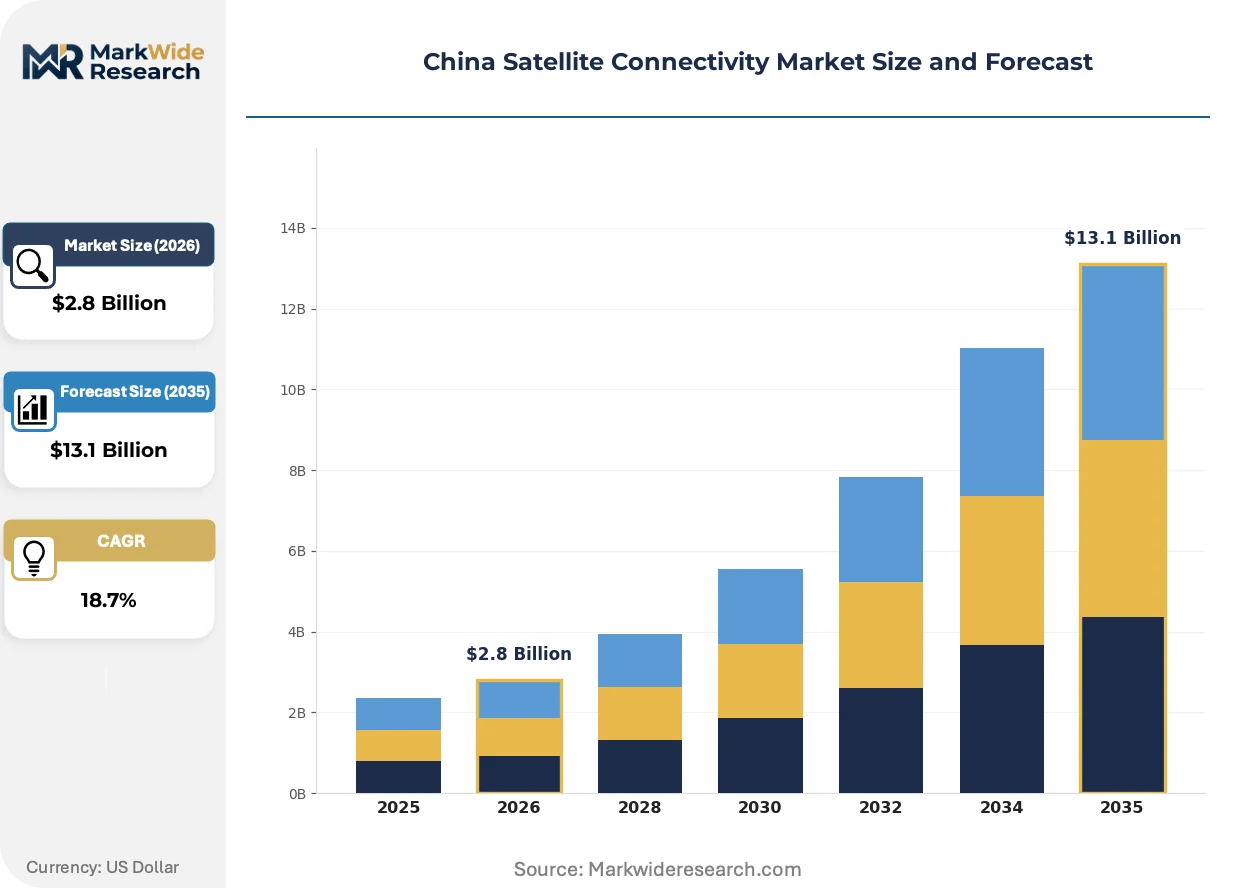
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13.1 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Broadband Internet, Remote Sensing, Disaster Management, Navigation End User: Aerospace, Maritime, government, Telecommunications Technology: LEO, MEO, Geostationary, VHF/UHF Service Type: Data Services, Voice Communication, Video Services, IoT Connectivity |
| Companies Covered | Kenbotong Technology Co Ltd, AKD Communication Technology Co Ltd, China Satellite Communications Co Ltd, CHANG GUANG SATELLITE TECHNOLOGY CO LTD, Diadem Technologies Inc, China Aerospace Science and Technology Corporation, Antesky Science Technology Inc, China Telecom, China Telecom Satellite Communications Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Satellite Connectivity Market Trends and Innovations
Software-defined payload architectures are redefining satellite manufacturing economics while regulatory pressure on spectrum efficiency accelerates terminal miniaturization. These shifts compress product lifecycles and reward modular design approaches.
Phased-array flat-panel antennas are digitizing terminal form factors for maritime and mobility applications. Ship operators in Hainan and Fujian ports are replacing parabolic dishes with electronically steered arrays that maintain lock during vessel motion. This digitization is compressing installation timelines from weeks to days and enabling service bundling with vessel management software platforms.
NMPA and MIIT joint type-approval reforms are tightening electromagnetic emission thresholds for terrestrial gateway equipment. Domestic manufacturers must now submit to combined testing protocols that previously ran sequentially, extending certification cycles by several months. High-throughput terminal categories face the steepest compliance burden as Ka-band power density limits intersect with GB radiation safety standards.
Remote education institutions in Gansu and Qinghai are unbundling connectivity procurement from hardware ownership. County-level education bureaus now lease satellite broadband as a managed service rather than purchasing terminals outright, shifting capital burden to operators. This purchasing pivot favors constellation providers with integrated ground segment capabilities over pure satellite manufacturers.
China Satellite Connectivity Market Segmentation
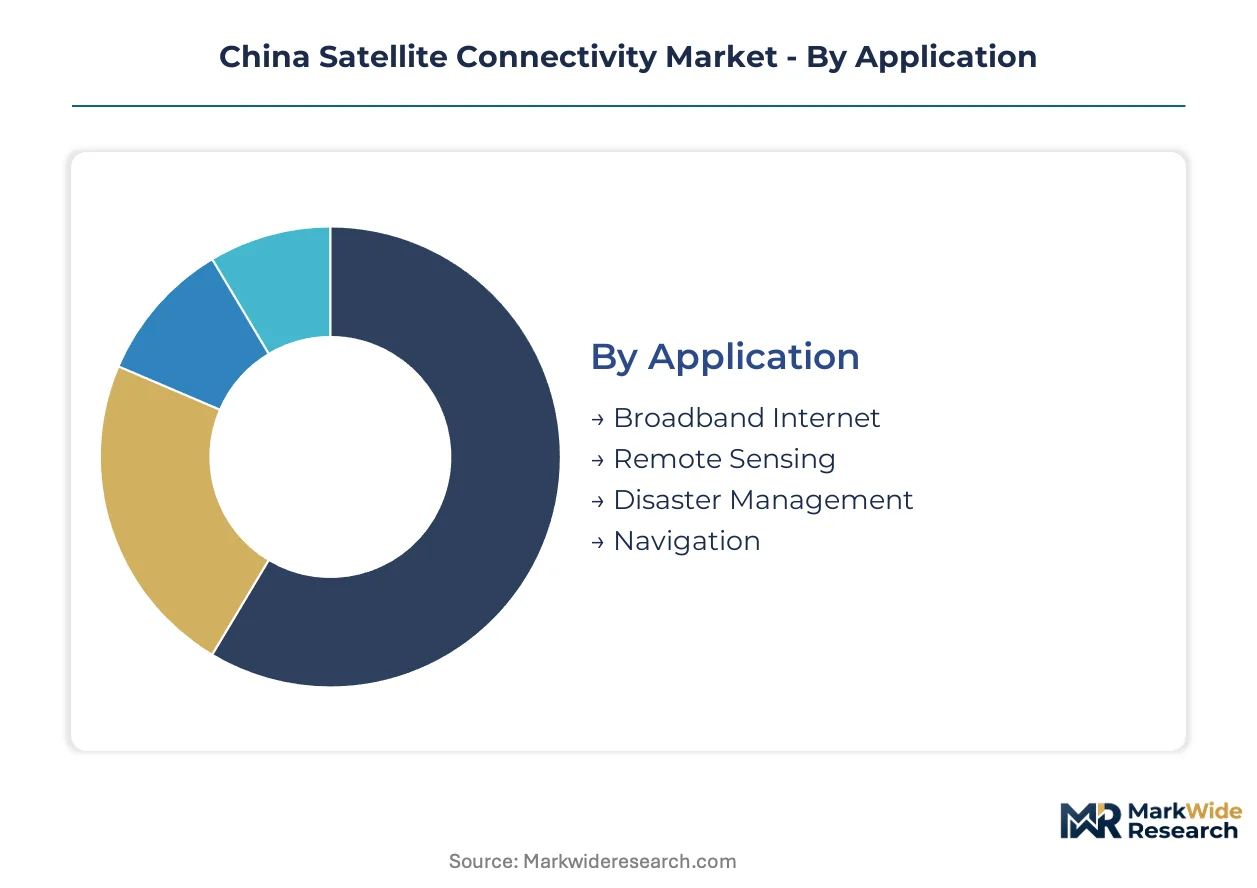
Orbital altitude, service architecture, and end-use requirements fragment the China satellite connectivity landscape into distinct commercial battlegrounds. Procurement patterns diverge sharply between government-backed rural broadband programs and commercial maritime deployments.
Application:
Cost tier differentiation separates capital-intensive infrastructure plays from recurring-revenue service models across the four application verticals.
- Broadband Internet:High-throughput Ka-band and LEO constellations deliver consumer and enterprise data services. Western provinces including Xinjiang and Tibet deploy these systems to satisfy MIIT universal service obligations where fiber deployment remains uneconomical.
- Remote Sensing:Optical and synthetic aperture radar payloads capture agricultural, environmental, and urban monitoring data. County-level education bureaus in Gansu and Qinghai lease managed connectivity services bundled with imagery analytics, shifting procurement from hardware ownership to subscription models.
- Disaster Management:Rapid-deploy terminals restore communications during seismic events and flooding. Emergency response coordination through SAMR procurement channels prioritizes domestic constellation operators with integrated ground segment capabilities.
- Navigation:BeiDou augmentation and precision positioning services support transportation and construction sectors. Dual carbon alignment requirements from MEE drive adoption for emissions monitoring in western livestock and crop operations.
Broadband Internet holds installed capacity. Remote Sensing is rotating up the share rankings.
End User:
Customer type determines pricing architecture and contract duration, with government accounts demanding longest lock-in periods.
- Aerospace:Passenger broadband and cockpit datalink applications require low-latency LEO connectivity. Domestic airline fleets are expanding continuous connectivity deployments as NMPA type-approval reforms streamline terminal certification for electronically steered arrays.
- Maritime:Fishing fleets and cargo vessels beyond cellular range drive L-band terminal demand. Port authority installation programs in Hainan and Fujian are replacing parabolic dishes with phased-array flat-panel antennas that maintain lock during vessel motion.
- Government:National security payloads and rural broadband mandates absorb Long March launch capacity. SAMR procurement guidelines increasingly favor domestic constellation operators in telecommunications contracts.
- Telecommunications:China Telecom bundles satellite links with fiber network reach for terrestrial backhaul extension. Inter-satellite optical links reduce ground gateway dependency for remote sensing constellation operators.
Maritime holds installed capacity. Aerospace is rotating up the share rankings.
Technology:
Maturity curves separate proven geostationary platforms from emerging LEO architectures competing on latency performance.
- LEO:Constellations operating at 300-2,000 kilometers altitude deliver sub-50 millisecond latency. Reduced latency profiles demanded by maritime and aerospace end users are climbing the fastest expansion trajectory despite launch capacity bottlenecks.
- MEO:Medium-earth orbit systems balance coverage footprint with signal delay. Navigation and specialized data services concentrate demand where geostationary latency proves prohibitive but full LEO constellation deployment remains capital-constrained.
- Geostationary:Fixed-position satellites at 35,786 kilometers maintain mature revenue streams in video broadcasting. ITU coordination queues for orbital slots extend licensing timelines beyond typical investor return horizons.
- VHF/UHF:Lower frequency bands penetrate atmospheric interference for emergency and military applications. Legacy system interoperability requirements demand gateway hardware capable of multi-band translation without full infrastructure replacement.
Geostationary holds installed capacity. LEO is rotating up the share rankings.
Service Type:
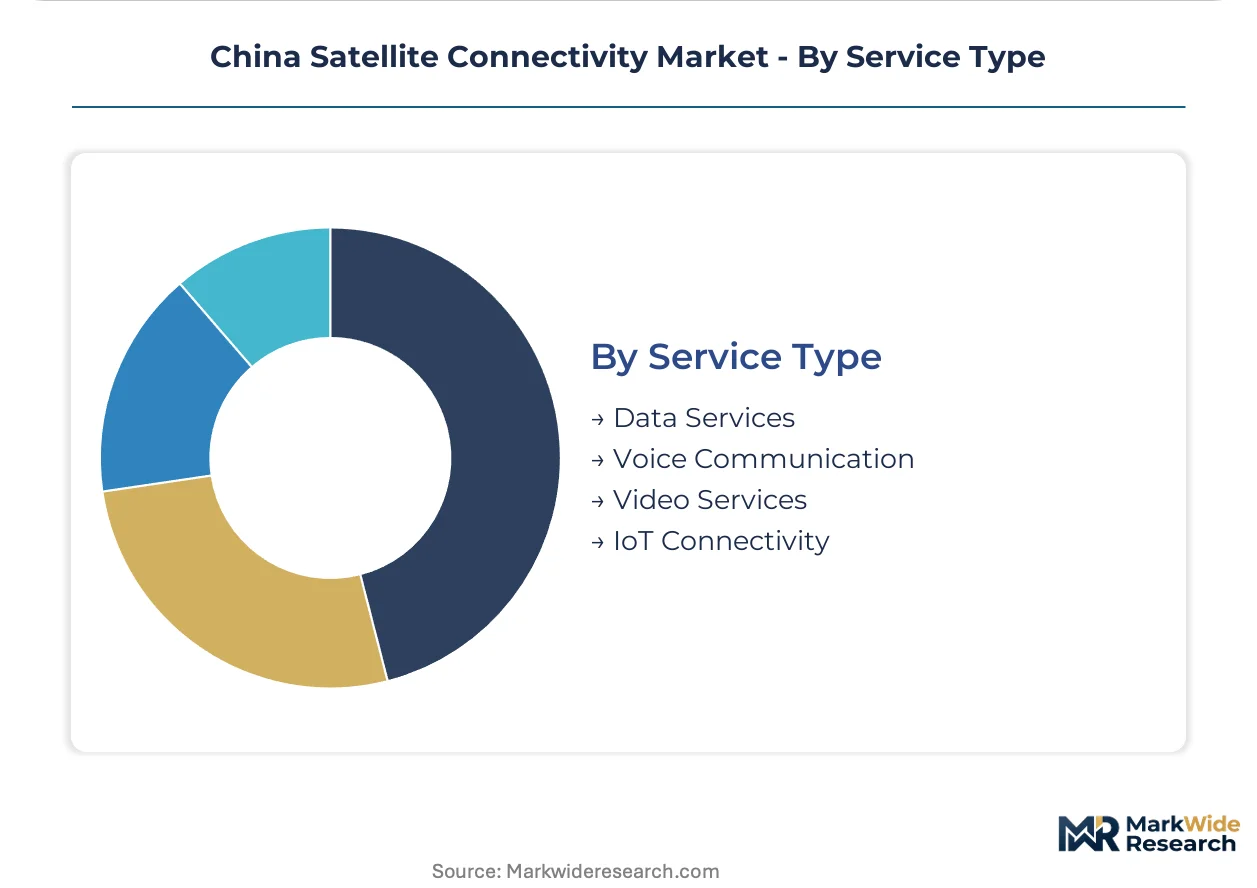
Margin structure varies by payload efficiency, with data services capturing premium pricing against commoditized voice transmission.
- Data Services:Broadband internet and machine-to-machine transmission dominate revenue contribution. Software-defined payload architectures compress product lifecycles and reward modular design approaches for high-throughput applications.
- Voice Communication:Traditional telephony services persist in maritime and remote government installations. L-band spectrum allocation maintains relevance where data demand remains secondary to reliable audio connectivity.
- Video Services:Broadcasting distribution and surveillance feeds leverage geostationary capacity. Southern monsoon regions experience Ka-band rain fade that limits high-throughput service reliability during peak agricultural monitoring seasons.
- IoT Connectivity:Sensor networks for precision agriculture and environmental monitoring expand addressable market. Satellite-enabled emissions tracking supports MEE dual carbon compliance for western provincial operations.
Data Services holds installed capacity. IoT Connectivity is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT universal service obligations and NMPA spectrum reforms are reshaping provincial deployment patterns across China's western and coastal regions. Provincial governments compete for satellite manufacturing clusters while rural broadband mandates accelerate terminal installation in remote prefectures.
Xinjiang
Pastoral connectivity programs and border surveillance networks drive terminal demand across the Tarim Basin. MIIT rural broadband mandates prioritize Kashgar and Hotan prefectures for satellite backhaul installation. The Urumqi industrial zone hosts ground gateway manufacturing facilities serving Central Asian cross-border links.
Tibet
Remote education institutions and monastic connectivity programs absorb L-band capacity in Lhasa and Shigatse prefectures. SAMR procurement guidelines favor domestic constellation operators for government telecommunications contracts. The Lhasa satellite ground station anchors regional downlink capacity for high-throughput services.
Hubei
Wuhan's optical valley industrial park attracts constellation component suppliers seeking proximity to fiber backhaul interconnection points. NMPA electromagnetic compatibility testing protocols compress certification timelines for gateway equipment manufacturers. The provincial government offers tax incentives for satellite payload assembly operations.
Shanghai
Phased-array antenna design expertise concentrates in Zhangjiang Hi-Tech Park alongside maritime terminal integration facilities. GB standards for radio frequency emissions shape product requirements for Ka-band equipment destined for southern monsoon regions. The Yangshan deep-water port drives vessel management software bundling with satellite connectivity services.
Fujian
Fishing fleet modernization programs and cargo vessel digitalization drive L-band terminal replacement cycles in Xiamen and Fuzhou ports. Port authority installation mandates require electronically steered arrays capable of maintaining lock during vessel motion. The provincial maritime safety administration coordinates with constellation operators on coastal coverage optimization.
China Satellite Connectivity Market Competitive Landscape
State-owned aerospace conglomerates and commercial remote sensing specialists split the market along mission-critical versus commercial service lines. China Aerospace Science and Technology Corporation anchors national launch capacity through Long March vehicle allocation. China Telecom extends terrestrial backhaul integration by bundling satellite links with fiber network reach. Competitive moves concentrate on vertical specialization among launch integrators and spectrum-efficient terminal miniaturization.
Within the state-owned tier, China Satellite Communications Co Ltd and China Telecom Satellite Communications Co Ltd occupy positions as integrated service providers with captive ground segment capabilities. CHANG GUANG SATELLITE TECHNOLOGY CO LTD exemplifies the commercial remote sensing constellation archetype, specializing in high-resolution optical payload deployment. Kenbotong Technology Co Ltd and AKD Communication Technology Co Ltd represent equipment manufacturing specialists subject to NMPA-MIIT joint type-approval cycles.
| Leading Market Players |
|---|
| Kenbotong Technology Co Ltd |
| AKD Communication Technology Co Ltd |
| China Satellite Communications Co Ltd |
| CHANG GUANG SATELLITE TECHNOLOGY CO LTD |
| Diadem Technologies Inc |
| China Aerospace Science and Technology Corporation |
| Antesky Science Technology Inc |
| China Telecom |
| China Telecom Satellite Communications Co Ltd |
| Others |
Pricing and Supply Chain Analysis
Launch vehicle undercapacity across Hubei and Shanghai industrial zones compresses constellation deployment timelines while concentrating pricing power among Long March integrators. NMPA-MIIT joint certification cycles extend vendor cost structures, forcing equipment suppliers to absorb compliance overhead or cede share to state-backed competitors with captive approval pathways.
Pricing Analysis
Western province premiums for Xinjiang and Tibet deployments run above coastal benchmarks due to logistics complexity and sparse terrestrial backhaul alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by terminal certification grade and after-sales service bundling. Cost compression in standard-tier L-band equipment is intensifying because Hubei manufacturing clusters are absorbing RF engineering talent from coastal competitors. County-level education bureaus in Gansu and Qinghai exhibit highest price sensitivity, while aerospace integrators prioritize latency performance over unit cost.
Supply Chain Analysis
Tariff exposure between China and US semiconductor sources dominates phased-array antenna component sourcing, particularly for GaN power amplifiers and beamforming ASICs. Manufacturing gravity centers on Hubei for payload assembly, Shanghai for terminal integration, and Xinjiang for ground gateway deployment. Raw material dependencies span rare earth magnets for reaction wheels, high-purity silicon for solar arrays, and specialized aluminum-lithium alloys for bus structures. Single-source vulnerability concentrates in Ka-band MMIC fabrication where domestic foundry capacity lags design requirements. Distribution runs through MIIT-licensed system integrators to provincial telecom operators and county-level procurement bureaus.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
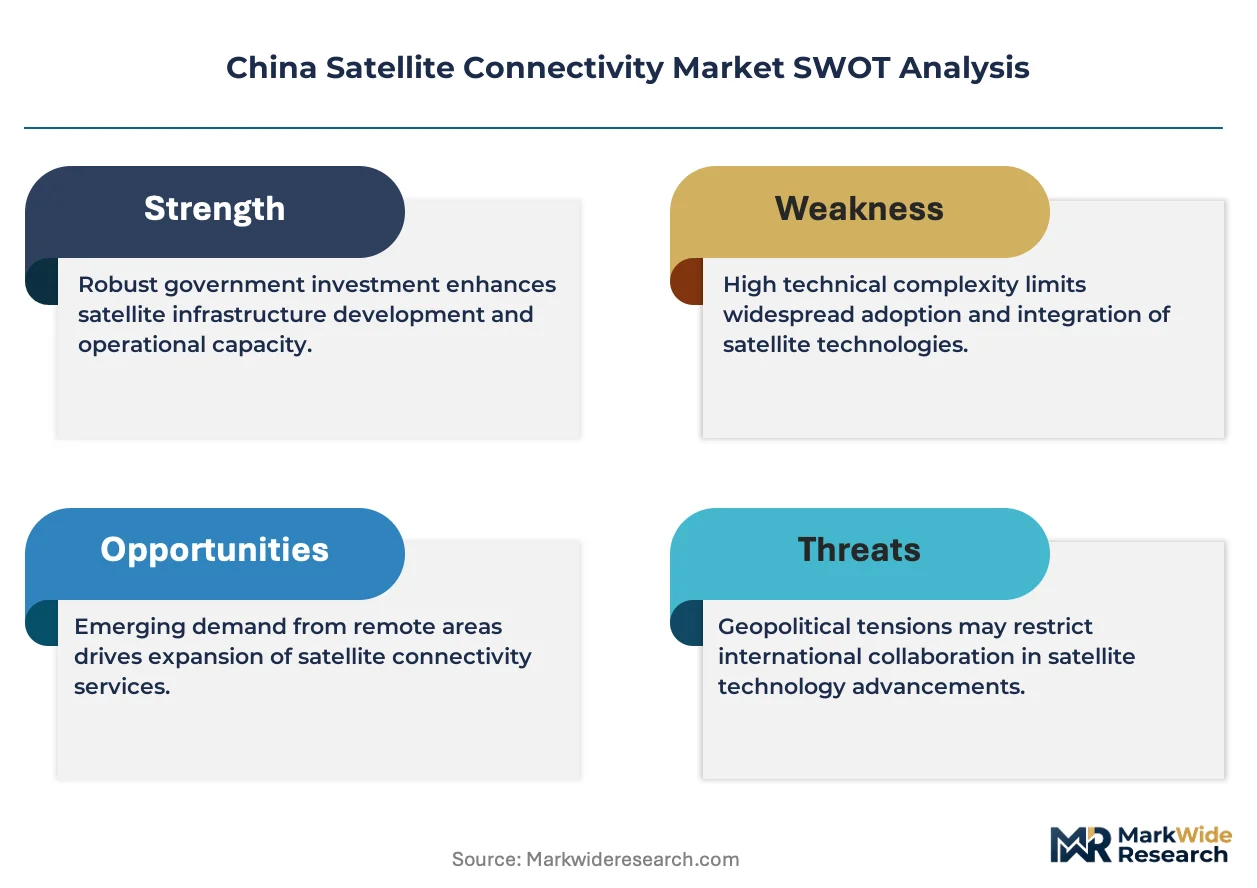
Ka-band phased-array design expertise concentrates in Shanghai and Beijing, leaving constellation operators dependent on a shallow talent pool for terminal miniaturization. This capability gap widens as LEO deployment schedules accelerate and NMPA emission thresholds tighten.
For Market Incumbents: Insulate Long March launch allocation through exclusive payload integration contracts with China Aerospace Science and Technology Corporation. Deepen backward integration into satellite bus manufacturing by acquiring Hubei-based component suppliers facing recertification cost pressure from NMPA-MIIT protocol changes. For New Entrants and Emerging Players: Establish a beachhead in managed connectivity services for remote education institutions in Qinghai and Gansu, where procurement is shifting from hardware ownership to subscription models. Target maritime terminal replacement cycles in Fujian and Hainan ports by bundling phased-array hardware with vessel management software platforms. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among constellation operators with integrated ground segment capabilities serving government telecommunications contracts. Long-term viability hinges on orbital slot coordination advantages and MIIT rural broadband mandate alignment. Acquisition candidates should demonstrate NMPA type-approval momentum and western province installation traction. Monitor SAMR procurement guideline shifts favoring domestic operators as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Inter-Satellite Optical Link Deployment | Laser cross-connect technology reduces Xinjiang ground gateway dependency for remote sensing operators. |
| Phased-Array Terminal Certification | NMPA streamlined approval for electronically steered arrays accelerates aerospace fleet installations. |
| Provincial Manufacturing Cluster Expansion | Hubei tax incentives attract satellite payload assembly operations seeking fiber backhaul proximity. |
| Managed Connectivity Service Launch | Subscription models shift capital burden from county education bureaus to constellation operators. |
| Dual Carbon Alignment Program | MEE emissions monitoring contracts open precision agriculture revenue streams in western provinces. |
Research Methodology
A spread of perspectives from constellation program directors, MIIT regulatory officers, NMPA certification engineers, and county-level procurement managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against MIIT connectivity target disclosures, SAMR procurement guidelines, GB standard documentation, and customs data for satellite component trade flows. Bottom-up terminal installation tracking across Xinjiang, Tibet, and Gansu triangulated against top-down market sizing from operator capacity announcements.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation by orbital altitude, service architecture, application vertical, and end-user category. CAGRs derived from installed capacity buildout curves, launch manifest scheduling, and provincial universal service obligation funding allocations. Industry-specific inputs included Long March vehicle allocation priorities, ITU coordination queue status, and phased-array antenna yield rates from Shanghai manufacturing facilities.
Sensitivities concentrate around NMPA spectrum reform implementation pace, MIIT rural broadband mandate funding continuity, and launch vehicle availability for commercial constellation deployment. Forecasts reflect documented assumptions on regulatory timeline stability and provincial industrial policy persistence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Global Dish Antennas Market
Satellite
France Satellite-Based Earth Observation Market
Satellite
Satellite Broadband Market
Satellite
Asia-Pacific Satellite Launch Vehicle Market
Satellite
North America Mobile Satellite Services Market
Satellite
ASEAN Satellite Communications Market
Satellite
Global Broadband Satellite Services Market
Satellite
Military Satellite Market
Satellite
All-Electric Satellites Market
Satellite
Advanced Satellite Market
Satellite
South Korea Satellite Imagery Services Market
Satellite
Canada Satellite-Based Earth Observation Market
Satellite
North America Satellite Attitude and Orbit Control System Market
Satellite
Medium and Large Satellite Market
Satellite
US Remote Sensing Technology Market
Satellite
Global Commercial Satellite Broadband Market