
 Europe Residential Real Estate Market | 2026-2036
Europe Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Residential Real Estate Market Foresight
REACH is broadening the cost-of-entry calculus for residential developers across Europe, as chemical compliance in building materials now extends to insulation foams, sealants, and interior finishes. Vonovia SE leverages its vertically integrated maintenance platform to manage retrofit liabilities at scale. LEG Immobilien AG anchors its competitive position through concentrated exposure to German university cities with durable rental demand. Heimstaden Bostad AB sustains portfolio growth through standardized unit refurbishment protocols that reduce per-door compliance costs.
Europe residential real estate encompasses privately owned and leased dwelling units ranging from detached single-family structures to mid-rise multi-family buildings, typically constructed with reinforced concrete frames, masonry cavity walls, and thermal insulation meeting national U-value thresholds between 0.20 and 0.35 W/m²K, serving the fundamental purpose of providing shelter while functioning as collateralized income-producing assets for institutional and retail capital. Single-family homes retain the deepest liquidity pools across Southern European markets where generational wealth transfer sustains owner-occupancy preference. Condominiums and multi-family units represent the fastest-growing structural categories as urban densification policies restrict greenfield sprawl near transit nodes. The luxury price band captures disproportionate margin concentration in London, Paris, and Monaco, while medium-tier transactions generate the highest absolute volume across Berlin, Madrid, and Milan.
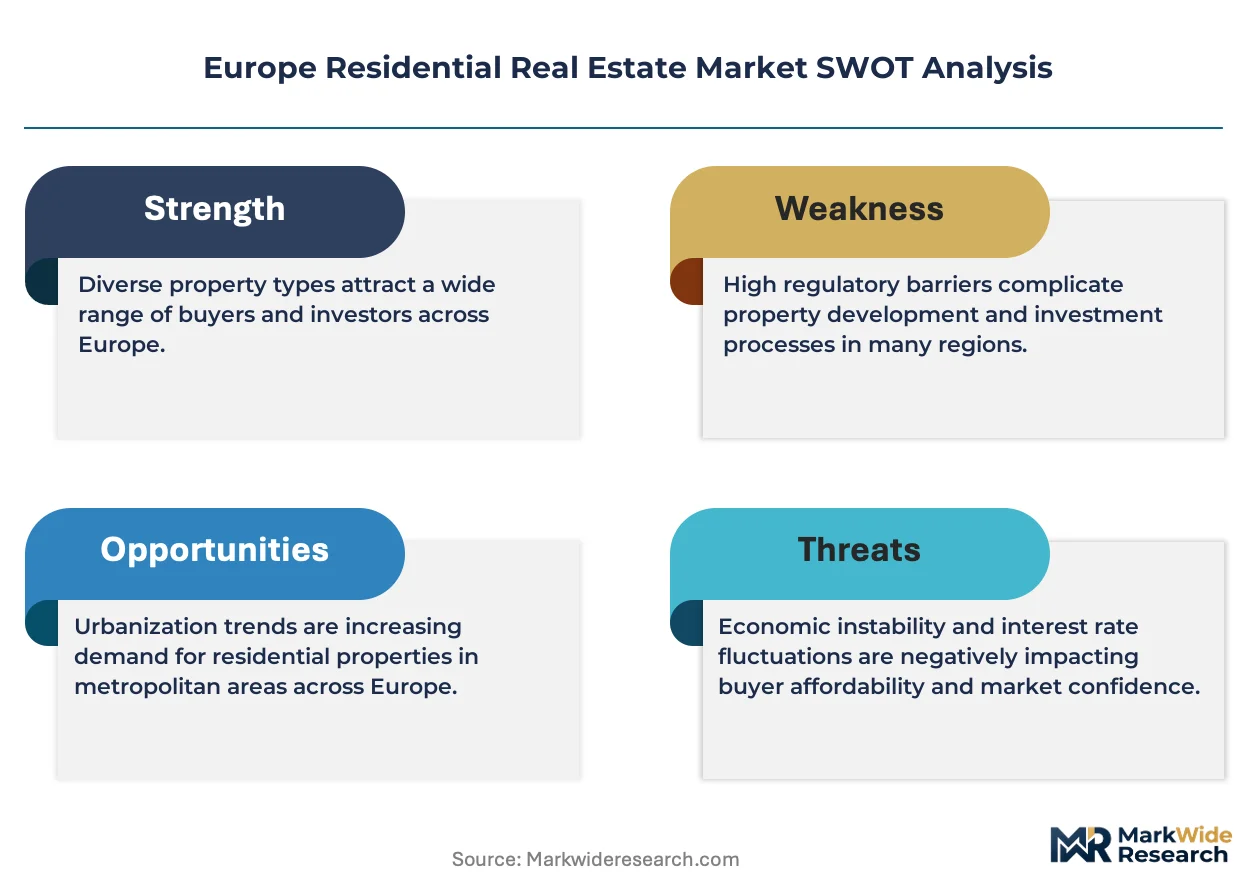
EMA, ECHA, and national building codes under the EU Green Deal collectively shape material specifications, energy retrofit timelines, and financing eligibility for residential assets across member states. ECHA's expanding restricted substance list directly impacts insulation and flooring procurement decisions, while the EU Green Deal's phased carbon performance standards threaten obsolescence risk for pre-1990 building stock. Stakeholders must monitor regulatory calibration between national transpositions and Brussels-level enforcement to anticipate which vintage of housing stock faces accelerated depreciation or mandatory capital injection.
Market Dynamics
EU Green Deal retrofit mandates are compressing investment timelines across Europe's aging housing stock, forcing institutional landlords to front-load capital expenditure or face asset obsolescence.
Growth Catalysts
- EU Green Deal building renovation requirements:Mandatory energy performance upgrades trigger sustained capital deployment into insulation, HVAC replacement, and envelope improvements across member states.
- Institutional capital rotation:Pension funds and sovereign wealth vehicles channel allocations into stabilized multifamily rental stock as inflation-linked income hedges.
- German urban corridor demand:Berlin, Munich, and Hamburg absorb disproportionate household formation as remote-work flexibility concentrates talent in lower-cost tier-one cities.
Market Restraints
- Construction input cost volatility:Reinforced steel and engineered timber prices swing with energy-intensive production curtailments, compressing developer margins on greenfield projects.
- ECHA restricted substance list expansion:REACH compliance costs for insulation foams and interior finishes add 8-15% to material procurement budgets for renovation pipelines.
- Substitution threat from build-to-rent alternatives:Purpose-built student housing and co-living operators capture young professional demand that previously filtered into traditional multifamily.
Strategic Opportunities
- Poland and Czech Republic secondary cities:Wrocław, Kraków, and Brno show rental yield spreads 150-200 basis points above Western European capitals with comparable demographic tailwinds.
- EU CSRD-aligned green financing:Sustainability-linked loans offer 25-50 basis point coupon reductions for assets meeting certified energy performance thresholds.
- Modular prefabrication convergence:Cross-laminated timber panels paired with factory-installed MEP systems compress construction schedules from 24 to 14 months on mid-rise residential.
Industry Challenges
- Deep retrofit skill scarcity:Qualified building envelope specialists and energy auditors command 40% wage premiums across Scandinavia and the Netherlands, constraining project velocity.
- Legacy asset integration complexity:Pre-1990 building stock requires phased capital injection to avoid tenant displacement, stretching hold-period returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Residential Real Estate Market |
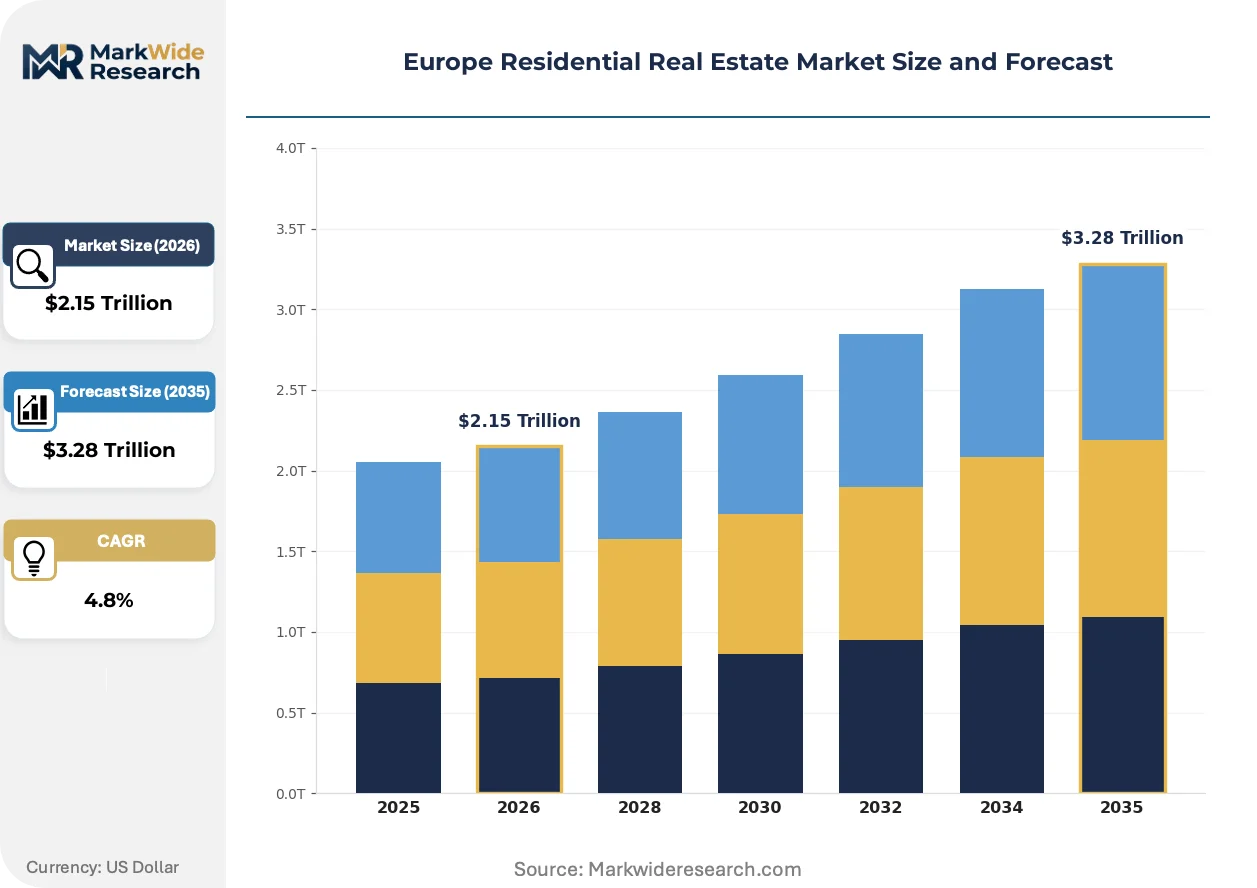
| Market Size in 2026 | $2.15 Trillion |
| Market Size in 2035 | $3.28 Trillion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Single-Family Homes, Condominiums, Townhouses, Multi-Family Units End User: First-Time Buyers, Investors, Seniors, Renters Price Range: Low, Medium, High, Luxury Transaction Type: Sales, Leasing, Auctions, Short-Term Rentals |
| Companies Covered | Vonovia SE, LEG Immobilien AG, Heimstaden Bostad AB, TAG Immobilien AG, Grand City Properties S.A., Places for People Group Limited, CPI Property Group, Aroundtown Property Holdings, Covivio, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Residential Real Estate Market Shifts & Advancements
Digital building twins and predictive maintenance platforms are compressing operating expenditure curves for large-scale residential operators across Northern Europe.
Heat pump technology paired with district heating interconnection is rewriting thermal system economics for mid-rise multifamily assets. Swedish and Finnish housing associations deploy air-source and ground-source configurations at 300-unit scale. The technology is rewriting capex allocation away from gas boiler replacement toward integrated electrification and thermal storage.
EU Green Deal phased carbon performance standards tighten operational emissions thresholds through 2030 and 2040 milestones. Assets failing to meet Class C or higher energy labels face financing exclusion from ECB-collateralized lending facilities. German and Dutch residential REITs front-load envelope upgrades to secure green bond eligibility.
Rental platform intermediation concentrates tenant acquisition power in consolidated digital channels. Prospective lesseants in Madrid, Milan, and Vienna now initiate searches through algorithmic matching services that rank listings by commute time and energy cost transparency. Traditional brokerage retains value only at the luxury price band where discretion and viewing logistics justify commission premiums.
Europe Residential Real Estate Market Segmentation
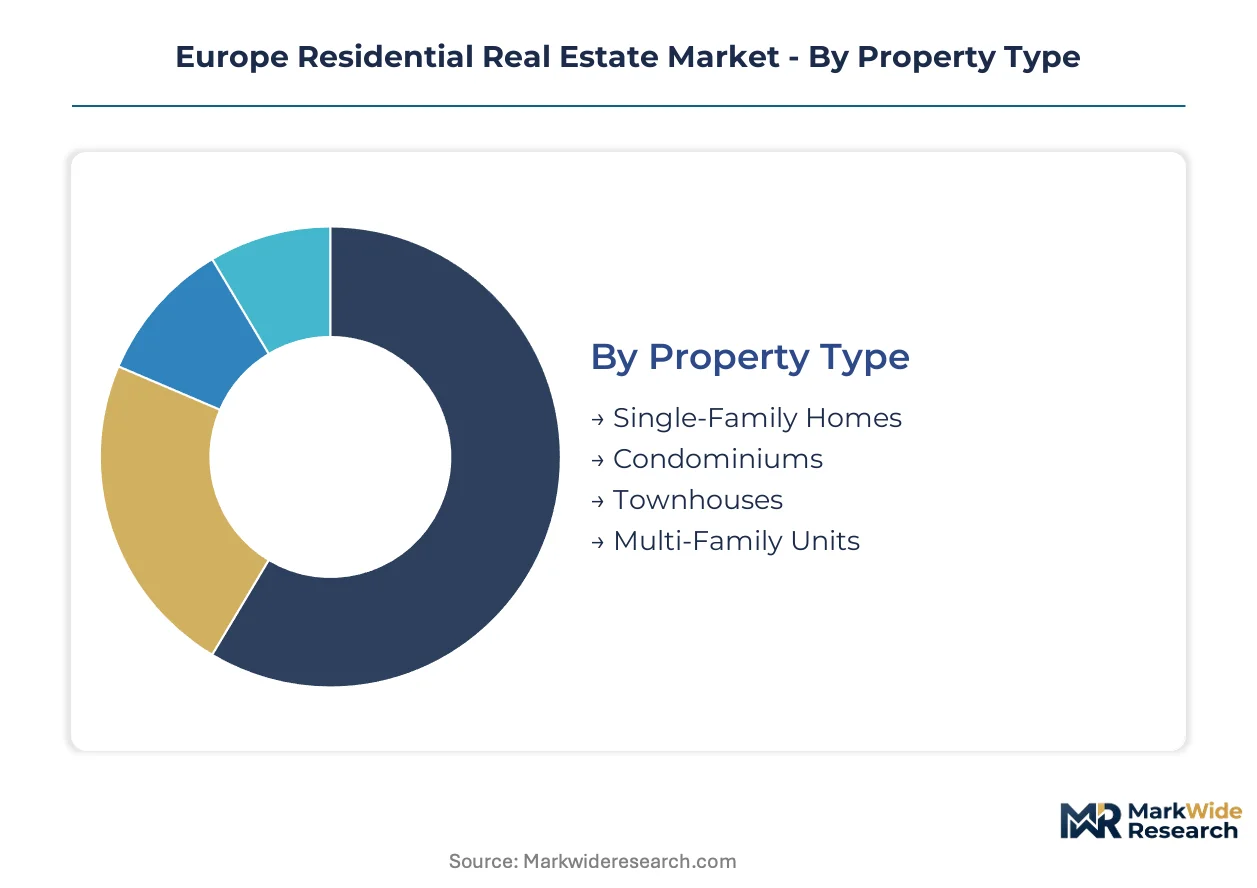
Segmentation in Europe residential real estate reveals how capital allocation, demographic cohorts, and regulatory exposure fragment across distinct asset classes. Investors deploy different underwriting criteria for each category, with energy retrofit liabilities and yield compression varying materially by property type and price tier.
Property Type:
Investor risk appetite and capital intensity diverge sharply across structural categories, with institutional buyers favoring scaleable rental stock while retail capital chases owner-occupancy preferences.
- Single-Family Homes:Detached structures on individual land parcels, typically masonry construction with pitched roofs and private outdoor space. Southern European markets—Spain, Italy, Portugal—absorb deepest liquidity here as intergenerational wealth transfer sustains family ownership cycles despite urban densification policies.
- Multi-Family Units:Purpose-built rental blocks with centralized services and professional management platforms. German and Scandinavian institutional landlords concentrate acquisition pipelines here, capturing operational efficiencies through standardized maintenance protocols and bulk procurement of heat pump installations.
- Condominiums:Strata-titled units in mid-rise buildings with shared envelope and common area governance. Berlin, Madrid, and Milan generate highest absolute transaction volumes as first-time buyers trade space for transit accessibility.
- Townhouses:Attached or semi-detached row housing with fractional land ownership and individual utility metering. Dutch and Belgian urban peripheries favor this typology for family households seeking density without high-rise living.
Single-family homes lead volumes today; multi-family units are gaining share fastest as pension fund allocations rotate into stabilized rental yield.
End User:
Financing eligibility and holding period expectations separate these cohorts, with regulatory incentives and interest rate sensitivity driving divergent demand patterns.
- First-Time Buyers:Households entering ownership through mortgage leverage, typically targeting medium-tier condominiums or peripheral townhouses. German KfW subsidies and Dutch NHG guarantees shape purchasing power, though ECB rate tightening has compressed affordability ratios across eurozone markets.
- Investors:Institutional and private capital seeking income-producing assets with inflation-linked rental escalations. Vonovia, LEG Immobilien, and Heimstaden Bostad dominate multifamily acquisition as EU Green Deal retrofit timelines compress yield underwriting.
- Renters:Households priced out of ownership or prioritizing labor mobility over equity accumulation. Platform intermediation through ImmoScout24, Idealista, and Leboncoin concentrates search behavior, with algorithmic ranking now prioritizing energy cost transparency.
- Seniors:Downsizing owner-occupants or age-in-place households seeking single-level accessibility. Scandinavian housing associations retrofit common areas and install elevator infrastructure to retain this cohort, avoiding vacancy loss in aging building stock.
Investors lead capital deployment today; renters are expanding fastest as build-to-rent pipelines mature and ownership affordability erodes.
Price Range:
Mortgage market depth and cross-border capital flows concentrate differently across tiers, with luxury segments showing highest margin volatility.
- Luxury:Prime assets in London, Paris, and Monaco commanding discretionary buyer pools and currency-hedge demand from non-EU wealth. Transactions here generate disproportionate fee income for brokerage networks but face acute sensitivity to wealth tax policy shifts and sterling/euro exchange rate movements.
- Medium:The volume engine of European residential, spanning Berlin's Altbau apartments, Madrid's Eixample flats, and Milan's periphery new-build. This tier absorbs highest absolute transaction flow and drives construction input demand for engineered timber, insulation systems, and fenestration.
- High:Premium owner-occupied stock in tier-one city centers with energy label B or above. Dutch and German buyers dominate here, leveraging low loan-to-value ratios to absorb ECB rate increases without forced selling.
- Low:Subsidized social housing and distressed vintage stock requiring deep retrofit. Municipal housing associations and impact funds deploy here, capturing EU CSRD-aligned green financing spreads while managing tenant displacement risk during envelope upgrades.
Medium tier leads transaction volumes today; luxury is expanding fastest as non-EU capital seeks euro-denominated safe-haven assets.
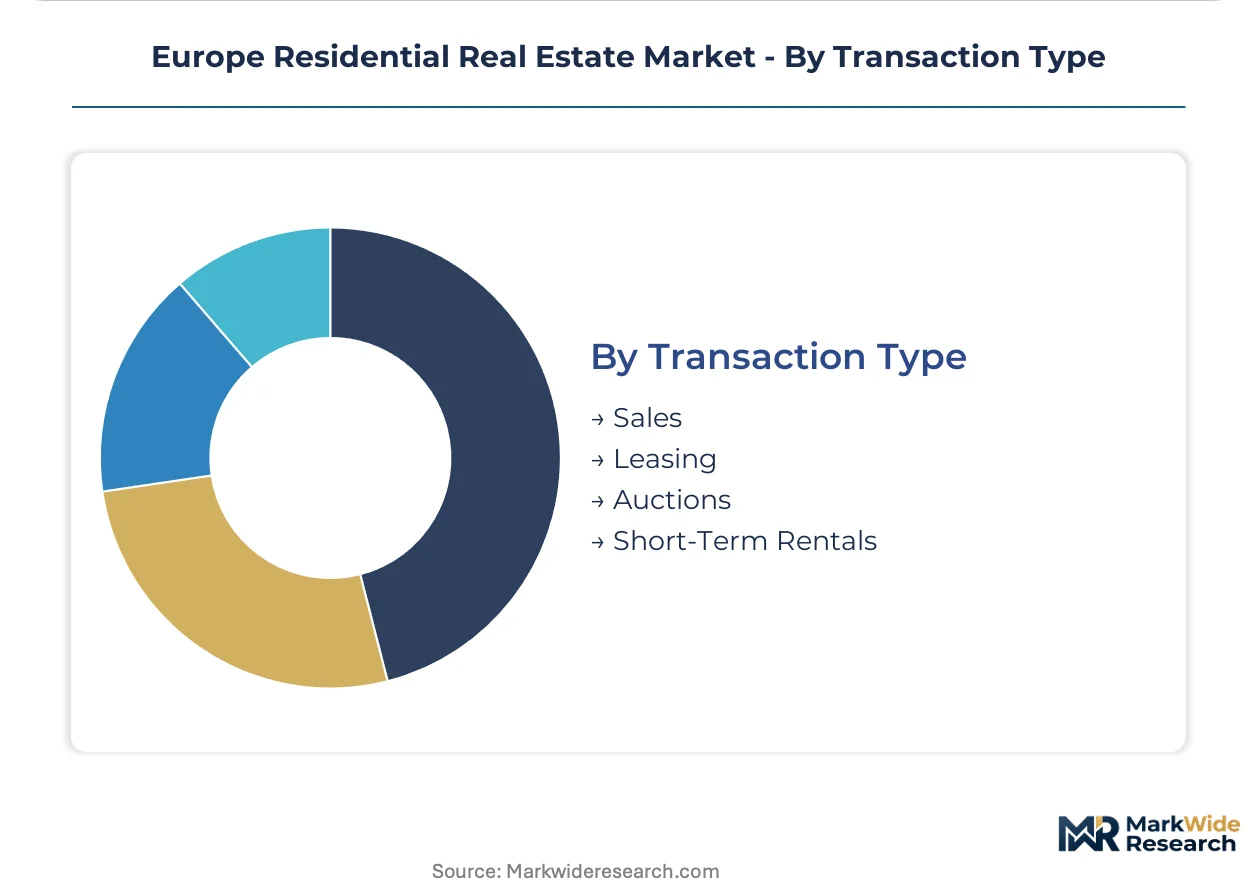
Transaction Type:
Legal structure and counterparty risk allocation vary across mechanisms, with digital intermediation disrupting traditional brokerage capture.
- Sales:Fee-simple or strata-title transfer with notarial execution, dominant in Southern European owner-occupancy markets. Spanish and Italian transactions require extensive land registry verification, extending closing timelines relative to German notarization efficiency.
- Leasing:Contractual occupancy rights with regulated rent controls in Germany, France, and Netherlands. Indexation clauses and energy pass-through mechanisms now dominate negotiation as operational cost transparency becomes tenant priority.
- Short-Term Rentals:Platform-mediated stays through Airbnb and Booking.com, concentrated in Barcelona, Lisbon, and Prague historic centers. Municipal licensing restrictions and tourist tax enforcement are compressing supply growth as housing affordability pressures mount.
- Auctions:Distressed or probate sales with accelerated closing requirements. Irish and UK markets maintain specialist auction houses, while continental Europe relies on judicial enforcement procedures with longer timelines.
Sales lead transaction flow today; leasing is climbing fastest as institutional build-to-rent stock scales across Northern Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern European residential real estate traces its institutional roots to post-war reconstruction programs that scaled multifamily construction across Germany and the Netherlands. These early public-private frameworks established the legal and financial infrastructure that now supports continental pension fund allocation into stabilized rental stock.
Germany
Berlin, Munich, and Hamburg absorb disproportionate household formation as remote-work flexibility concentrates talent in lower-cost tier-one cities. The KfW subsidy program shapes first-time buyer purchasing power, though ECB rate tightening has compressed affordability ratios. Vonovia SE and LEG Immobilien AG anchor acquisition pipelines in university cities with durable rental demand.
United Kingdom
London's prime market commands discretionary buyer pools and currency-hedge demand from non-EU wealth. The UK Green Deal and MEES regulations tighten minimum energy efficiency standards for rental properties. Build-to-rent pipelines mature across Manchester and Birmingham as institutional capital seeks inflation-linked income hedges.
France
Paris and Île-de-France generate concentrated luxury transaction flow with acute sensitivity to wealth tax policy shifts. The Elan Law and RE2020 environmental regulations mandate progressive carbon performance thresholds for new construction. Lyon and Marseille see accelerating platform intermediation through algorithmic rental matching services.
Netherlands
Randstad urban corridors favor townhouse typologies for family households seeking density without high-rise living. The NHG guarantee scheme and Woningwet social housing framework shape financing eligibility across owner-occupied and rental segments. Amsterdam and Rotterdam housing associations retrofit common areas to retain senior cohorts and avoid vacancy loss.
Sweden
Stockholm and Scandinavian capitals deploy air-source and ground-source heat pump configurations at 300-unit scale. The National Board of Housing, Building and Planning enforces stringent U-value thresholds that accelerate envelope upgrade timelines. Heimstaden Bostad AB sustains portfolio growth through standardized unit refurbishment protocols that reduce per-door compliance costs.
Europe Residential Real Estate Market Competitive Landscape
The competitive structure tilts toward vertically integrated platform operators with captive maintenance capabilities and centralized procurement. Consolidation pressure intensifies as EU Green Deal retrofit mandates compress investment timelines and force asset aggregation to achieve scale economies in energy auditing and envelope contracting. Two strategic archetypes dominate: diversified pan-European REITs with standardized retrofit playbooks, and national specialists with concentrated exposure to specific demographic corridors. Competitive moves center on portfolio aggregation through distressed asset acquisition and green bond issuance to front-load capital expenditure.
Within the vertically integrated tier, Vonovia SE and LEG Immobilien AG exemplify the German platform model that combines property management with in-house maintenance execution. Heimstaden Bostad AB occupies a position among Scandinavian operators that have systematized unit-turn protocols to compress compliance cost curves. These three entities represent the prevailing industry configuration where scale in operational execution determines retrofit liability management capacity.
| Leading Market Players |
|---|
| Vonovia SE |
| LEG Immobilien AG |
| Heimstaden Bostad AB |
| TAG Immobilien AG |
| Grand City Properties S.A. |
| Places for People Group Limited |
| CPI Property Group |
| Aroundtown Property Holdings |
| Covivio |
| Others |
Supply & Pricing Matrix
Deep retrofit skill scarcity across Scandinavia and the Netherlands creates labor-cost differentials that widen pricing-tier spreads between premium energy-efficient stock and standard vintage assets. German envelope specialists command wage premiums that feed into renovation contractor pricing, compressing margins on mid-tier multifamily units while luxury new-builds absorb specialized labor through fixed-price development contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates transaction flows, with energy label certification and proximity to transit nodes serving as primary price differentiation drivers. Cost compression in the economy tier intensifies as ECHA compliance costs for insulation and sealants add material procurement burdens. First-time buyers in peripheral markets show acute price sensitivity, while institutional investors acquiring stabilized rental stock prioritize yield stability over per-unit acquisition cost.
Supply Chain Analysis
Reverse-logistics flows for building envelope components—recovered insulation panels, refurbished fenestration units, and remanufactured HVAC modules—are concentrating in Poland and Czech Republic secondary processing hubs. Raw material procurement draws from German engineered timber suppliers, Chinese aluminum extrusion mills, and Scandinavian cross-laminated timber producers. Single-source vulnerability in heat pump compressor manufacturing creates supply chain risk. Distribution runs through vertically integrated landlord procurement platforms and specialized building envelope contractors serving institutional retrofit pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe residential real estate functions as a geographic-arbitrage play where Polish and Czech secondary cities offer yield spreads 150-200 basis points above Western European capitals despite comparable demographic trajectories. The regulatory gap between EU Green Deal enforcement timelines across member states creates differential obsolescence risk that sophisticated capital can exploit.
For Market Incumbents: Lock in retrofit execution capacity through captive contracting relationships with envelope specialists before wage inflation accelerates across Northern Europe. Aggregate distressed pre-1990 stock in German university cities to achieve scale economies in energy auditing and bulk heat pump procurement. The substitution threat from build-to-rent alternatives demands defensive positioning through platform-controlled tenant acquisition channels.
For New Entrants and Emerging Players: Begin with modular prefabrication partnerships targeting mid-rise residential in Dutch and Belgian urban peripheries where townhouse typologies dominate family household demand. Wrocław and Brno present the most penetrable geographies with institutional capital underweight relative to rental yield potential. A sustainability-linked financing go-to-market angle secures 25-50 basis point coupon advantages against incumbent cost of capital.
For Investors and Strategic Acquirers: Pan-European diversified REITs are the most active acquirer in this space, compressing timelines for portfolio aggregation plays. Long-term viability over a 5-10 year window rests on EU CSRD-aligned green financing access and retrofit liability management at scale. Acquisition targets should display concentrated exposure to German urban corridors or Scandinavian capitals with standardized maintenance protocols. Monitor ECB collateral eligibility criteria for energy label thresholds as the critical inflection indicator for asset repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Aggregation Through Distressed Asset Acquisition | Vonovia SE and LEG Immobilien AG capture scale economies in envelope contracting across German university cities. |
| Green Bond Issuance for Retrofit Capital Front-Loading | German and Dutch residential REITs secure ECB-collateralized lending eligibility through Class C energy label attainment. |
| Standardized Unit Refurbishment Protocol Development | Heimstaden Bostad AB reduces per-door compliance costs through systematized heat pump installation at 300-unit scale. |
| Sustainability-Linked Loan Structuring | EU CSRD-aligned financing offers coupon reductions for assets meeting certified energy performance thresholds. |
| Digital Building Twin Platform Deployment | Predictive maintenance platforms compress operating expenditure curves for large-scale residential operators across Northern Europe. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with property portfolio managers, energy auditors, building envelope contractors, and EPC developers were cross-validated against secondary sources including ECHA substance restriction databases, EU Green Deal national transposition documents, ECB collateral eligibility frameworks, and national building code registries. This triangulation approach ensures demand-side household formation data aligns with supply-side construction input cost indices.
Input-output matrices map residential transaction volumes across property type, end-user cohort, price tier, and transaction mechanism segments. The projection framework models CAGRs through econometric relationships between mortgage affordability ratios, institutional capital allocation trends, and regulatory compliance cost curves. Forecast inputs incorporate EU Green Deal phased carbon performance milestones, REACH restricted substance list expansion timelines, and heat pump technology adoption rates across Northern European housing associations.
Several conditions sit outside the modeled scope, including abrupt ECB policy reversals, unilateral national rent control interventions, and construction input trade disruption. Forecasts reflect assumptions regarding regulatory calibration between Brussels-level enforcement and national transposition. Practitioners should monitor ECHA substance restriction announcements and ECB energy label collateral threshold adjustments for early signals of asset repricing velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
UK Real Estate Market
Residential Real Estate Market
Saudi Arabia Residential Real Estate Market
Residential Real Estate Market
United States Manufactured Homes Market
Residential Real Estate Market
ASEAN Manufactured Homes Market
Residential Real Estate Market
Malaysia Residential Real Estate Market
Residential Real Estate Market
South Korea Residential Real Estate Market
Residential Real Estate Market
France Residential Real Estate Market
Residential Real Estate Market
Indonesia Real Estate Market
Residential Real Estate Market
Asia Pacific Manufactured Homes Market
Residential Real Estate Market
Malaysia Real Estate Market
Residential Real Estate Market
Myanmar Residential Real Estate Market
Residential Real Estate Market
Mexico Residential Real Estate Market
Residential Real Estate Market
UK Residential Real Estate Market
Residential Real Estate Market
Canada E-House Market
Residential Real Estate Market
Germany Residential Real Estate Market
Residential Real Estate Market
US E-House Market