
 UAE Condominiums and Apartments Market | 2026-2036
UAE Condominiums and Apartments Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Condominiums and Apartments Market Analytics
Dubai-based master developers are expanding luxury residential supply across the emirate's coastal zones. Emaar Properties anchors its position through integrated community design spanning retail, hospitality, and residential verticals. DAMAC Properties differentiates via branded residence partnerships with luxury hospitality operators. Sobha Realty sustains premium positioning through in-house manufacturing of concrete and steel products.
UAE condominiums and apartments constitute multi-unit residential structures featuring reinforced concrete frames, centralized HVAC distribution, and smart building management systems, purpose-built for ownership or leasehold tenure in high-density urban environments. The luxury condominiums segment captures disproportionate margin pools from ultra-high-net-worth international buyers seeking branded services and marina access. Studio apartments and 1-bedroom units compete on rental yield metrics, attracting institutional investors targeting the mid-range price tier where liquidity concentrates.
MOHAP oversees health and safety compliance in residential construction, while the Dubai Municipality Building Department enforces structural integrity and fire safety codes that shape material specifications and design parameters. The Emirates Green Building Council's Pearl rating system mandates energy efficiency thresholds that elevate mechanical and electrical system costs. Stakeholders must monitor evolving escrow account regulations and off-plan sales frameworks that govern capital flows and completion risk allocation.
Market Dynamics
Emirates Green Building Council mandates are compressing development timelines while elevating mechanical and electrical specifications, forcing developers to redesign project delivery workflows around Pearl rating compliance.
Growth Catalysts
- Expatriate Professional Influx:Finance and technology sector workers from Europe and South Asia are absorbing studio and one-bedroom inventory in Dubai Marina and Business Bay corridors.
- MOHAP Health and Safety Codes:Stricter residential construction standards are differentiating compliant master developers from speculative operators, concentrating buyer trust in established players.
- Waterfront Premium Clustering:Saadiyat Island and Dubai Creek Harbour are capturing disproportionate foreign direct investment through marina-adjacent zoning privileges.
Market Restraints
- Reinforced Steel and Concrete Cost Volatility:Global commodity swings are squeezing gross margins on mid-range apartment developments before presales close.
- Escrow Account Rigidity:Dubai's off-plan sales frameworks lock developer capital until construction milestones complete, straining working capital for new project launches.
- Labor Pool Concentration:Dependence on South Asian construction workforce creates vulnerability to bilateral visa policy fluctuations and remittance cost spikes.
Strategic Opportunities
- Branded Residence Convergence:Hospitality-operated service contracts are penetrating Abu Dhabi's Al Reem Island, capturing ultra-high-net-worth buyers seeking turnkey asset management.
- Smart Building Management Integration:IoT-enabled HVAC and access control systems are opening premium pricing tiers in Dubai's sustainable city districts.
- Ras Al Khaimah Secondary Market:Lower land costs and emerging casino-adjacent zoning are attracting institutional investors priced out of Dubai's prime coastal zones.
Industry Challenges
- Green Certification Timeline Compression:Pearl rating documentation requirements are extending pre-construction phases by eight to fourteen months, delaying revenue recognition.
- Specialized MEP Engineering Scarcity:Centralized district cooling and high-efficiency electrical distribution design expertise concentrates in a handful of Dubai-based consultancies, inflating professional fees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Condominiums and Apartments Market |
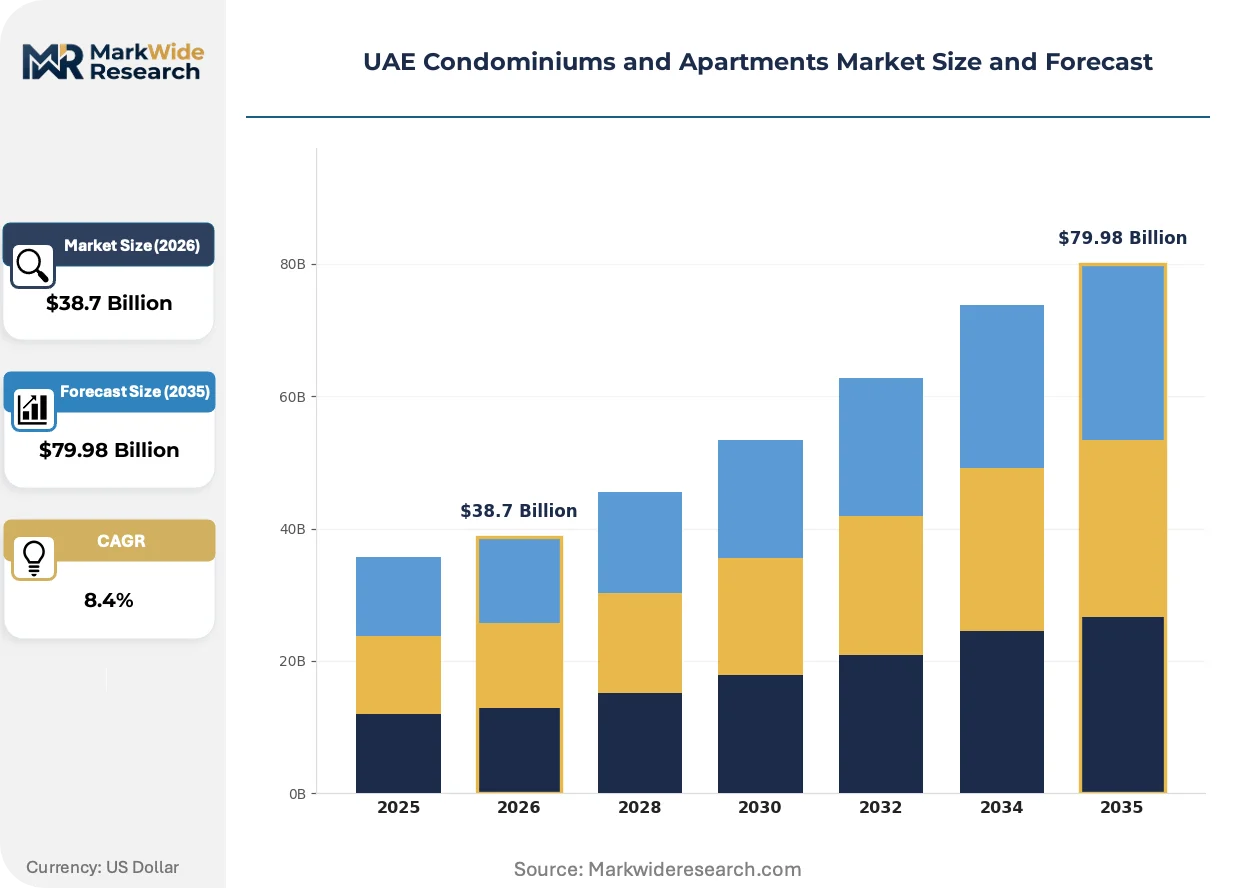
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Condominiums, Studio Apartments, 1-Bedroom Apartments, 2-Bedroom Apartments End User: First-Time Buyers, Investors, Renters, Retirees Price Tier: Affordable, Mid-Range, Premium, Ultra-Premium Service Type: Maintenance, Property Management, Leasing, Sales |
| Companies Covered | Sobha Realty, Mira Developments, Emaar Properties, Ellington Properties, Dubai Properties, Nakheel, Meraas, Binghatti, DAMAC Properties, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Condominiums and Apartments Market Evolving Landscape
Building automation and prefabrication are compressing traditional construction schedules while regulatory mandates around energy performance are rewriting material specification standards across the emirates.
Building-integrated photovoltaics and high-performance glazing are integrating facade design with on-site energy generation. Emaar and Aldar developments are specifying these systems for Pearl-rated towers, compressing reliance on district cooling baseload during peak summer demand. The technology is integrating mechanical and architectural disciplines, forcing contractors to coordinate earlier in design phases.
Dubai Municipality's updated fire safety and structural integrity codes are mandating enhanced concrete cover specifications and redundant egress systems. These requirements are elevating material costs for mid-rise developments while accelerating obsolescence of pre-2020 building stock. Luxury waterfront projects are absorbing compliance premiums most readily through adjusted unit pricing.
Institutional buyers are consolidating direct procurement relationships with master developers, bypassing traditional brokerage channels for bulk acquisitions. Family offices and sovereign wealth vehicles are negotiating block purchases in Abu Dhabi's Cultural District, replacing individual investor aggregation. This concentration is most visible in off-plan sales for super-prime inventory above fifteen million dirhams.
UAE Condominiums and Apartments Market Segmentation
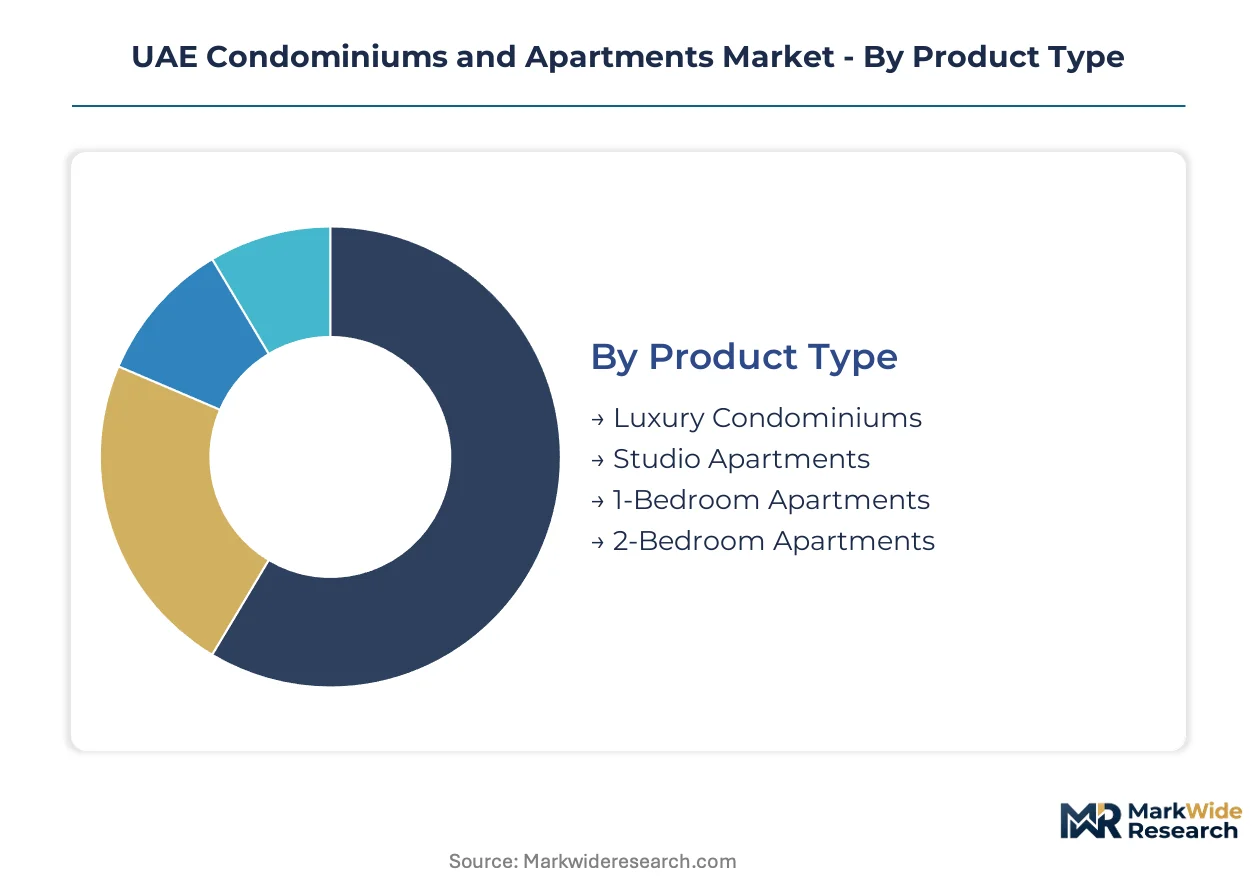
Segmentation in the UAE condominiums and apartments market reveals how regulatory certification burdens, buyer demographics, and service infrastructure shape product development and capital allocation across Dubai and Abu Dhabi's master-planned districts.
Product Type:
Pearl rating mandates from the Emirates Green Building Council impose tiered compliance costs across product categories, with larger unit configurations triggering more extensive MEP documentation and energy modeling requirements.
- Luxury Condominiums:These assets combine reinforced concrete superstructures with centralized district cooling and smart building management systems. Demand clusters in Dubai's waterfront districts and Saadiyat Island, where ultra-high-net-worth buyers prioritize marina access and branded hospitality services.
- Studio Apartments:Compact single-room configurations with integrated kitchenettes and space-efficient HVAC distribution. Finance and technology sector expatriates from Europe and South Asia are absorbing inventory in Dubai Marina and Business Bay, driven by rental yield metrics and proximity to employment clusters.
- 1-Bedroom Apartments:Separate sleeping quarters with living zones, attracting institutional investors targeting mid-range liquidity tiers.
- 2-Bedroom Apartments:Family-oriented configurations with dual bathroom specifications, concentrated in suburban master communities.
Studio apartments sit at the top of the volume ranking, with luxury condominiums climbing the fastest.
End User:
Buyer type determines financing structures, with institutional capital deploying differently than individual purchasers across Dubai's escrow-regulated off-plan frameworks.
- First-Time Buyers:Entry-level purchasers navigating mortgage qualification and deposit requirements, concentrated in affordable and mid-range inventory.
- Investors:Yield-focused capital deploying across rental-generating assets, with institutional buyers consolidating block purchases in Abu Dhabi's Cultural District.
- Renters:Temporary tenure seekers prioritizing flexibility, absorbing studio and one-bedroom supply in transit-oriented corridors.
- Retirees:Long-stay visa holders seeking low-maintenance coastal units, a segment gaining regulatory support through Dubai's retirement visa program.
Investors command the deepest capital pools, while first-time buyers are expanding most quickly as mortgage accessibility improves.
Price Tier:
Construction cost volatility in reinforced steel and concrete compresses margins most severely at the affordable tier, where presale pricing flexibility is constrained.
- Affordable:Entry-price inventory with standardized finishes and minimal amenity provision, located in secondary emirate locations.
- Mid-Range:The liquidity concentration point where institutional investment concentrates, featuring Pearl-rated efficiency specifications.
- Premium:Elevated material specifications with branded fitness and concierge services, positioned in coastal zones.
- Ultra-Premium:Super-prime inventory above fifteen million dirhams, absorbing compliance premiums through adjusted unit pricing and capturing family office capital.
Mid-range inventory sits at the top of the volume ranking, with ultra-premium assets climbing the fastest.
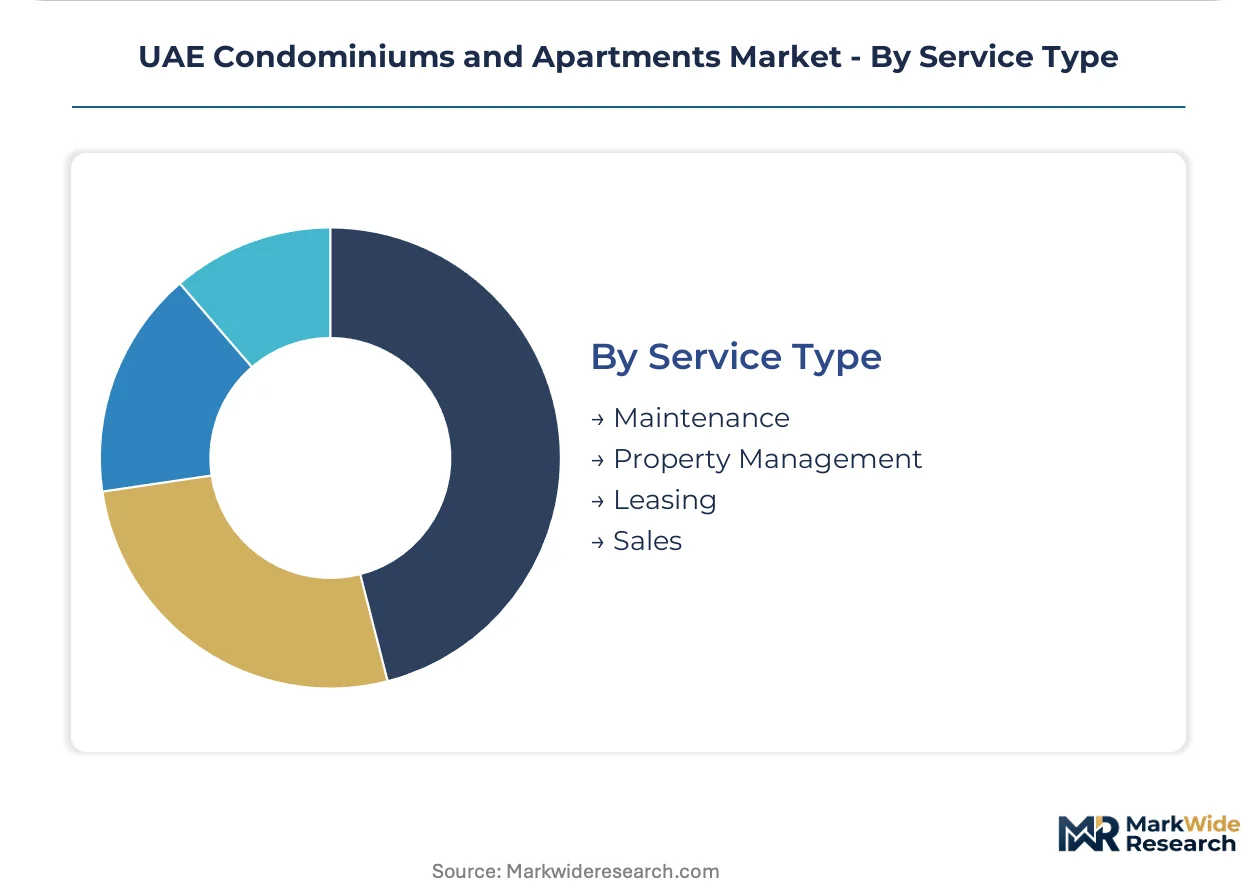
Service Type:
Service infrastructure requirements vary by asset class, with luxury inventory demanding hospitality-grade operational capabilities.
- Maintenance:Reactive and preventive building upkeep, increasingly technology-enabled through IoT sensor networks.
- Property Management:Comprehensive operational oversight including vendor coordination and resident services, concentrated in branded residence developments.
- Leasing:Tenant acquisition and retention functions, critical for investor-focused inventory in Business Bay and Dubai Marina.
- Sales:Transaction facilitation and marketing, with institutional buyers bypassing traditional brokerage channels for direct master developer relationships.
Leasing services sit at the top of the volume ranking, with property management climbing the fastest as branded residence penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai commands premium pricing velocity that Abu Dhabi cannot yet replicate, while secondary emirates attract yield-focused capital seeking lower entry thresholds. This hierarchy shapes development patterns across the federation's seven emirates.
Dubai
Finance and technology sector expatriates from Europe and South Asia are absorbing studio and one-bedroom inventory in Dubai Marina and Business Bay corridors. Dubai Municipality Building Department enforces updated fire safety and structural integrity codes that mandate enhanced concrete cover specifications. Waterfront districts including Dubai Creek Harbour are capturing disproportionate foreign direct investment through marina-adjacent zoning privileges.
Abu Dhabi
Ultra-high-net-worth buyers seeking branded hospitality services are concentrating demand on Saadiyat Island and Al Reem Island corridors. MOHAP oversees health and safety compliance in residential construction, differentiating compliant master developers from speculative operators. The Cultural District is witnessing institutional buyers negotiating block purchases, replacing individual investor aggregation for super-prime inventory.
Sharjah
Mid-range affordability seekers and first-time buyers are driving absorption in this emirate's emerging master communities. The Emirates Green Building Council's Pearl rating system applies federation-wide, elevating mechanical and electrical system costs here as elsewhere. Secondary corridor developments are attracting families priced out of Dubai's coastal zones while maintaining commute viability.
Ras Al Khaimah
Institutional investors priced out of Dubai's prime coastal zones are deploying capital toward casino-adjacent zoning and lower land costs. Escrow account regulations and off-plan sales frameworks govern capital flows here with equivalent rigor to Dubai. Emerging hospitality-integrated developments are capturing attention from yield-focused regional family offices.
Northern Emirates
Ajman, Fujairah, and Umm Al Quwain are attracting entry-level purchasers through standardized finishes and minimal amenity provision. Labor pool concentration from South Asian construction workforce creates equivalent vulnerability to bilateral visa policy fluctuations across these jurisdictions. Affordable inventory clusters here serve domestic demand and commuter populations working in Dubai and Sharjah.
UAE Condominiums and Apartments Market Competitive Landscape
Dubai-based developers anchor the premium tier; Abu Dhabi specialists hold institutional-grade capabilities. The market structure concentrates around vertically integrated master developers with captive manufacturing and hospitality-operated service contracts. Three archetypes dominate: integrated community designers, branded residence operators, and in-house material producers. Competitive intensity manifests through strategic partnerships with luxury hospitality brands and portfolio diversification into retail and hospitality verticals.
Within the integrated community tier, Emaar Properties exemplifies master-planned district development spanning residential, retail, and hospitality functions. DAMAC Properties occupies a position representing branded residence convergence through hospitality-operator partnerships. Sobha Realty anchors the in-house manufacturing archetype through captive concrete and steel production capabilities. These three developers collectively illustrate the strategic positioning spectrum available to competitors seeking differentiation in a Pearl-rated regulatory environment.
| Leading Market Players |
|---|
| Sobha Realty |
| Mira Developments |
| Emaar Properties |
| Ellington Properties |
| Dubai Properties |
| Nakheel |
| Meraas |
| Binghatti |
| DAMAC Properties |
| Others |
Value Network & Pricing Analysis
Institutional buyers consolidating block purchases in Abu Dhabi's Cultural District are anchoring a contract-based pricing model that rewards volume scale and direct master developer relationships. Pearl rating compliance costs feed through to unit pricing most visibly at the mid-range tier, where presale flexibility faces compression from standardized MEP specifications.
Pricing Analysis
Capacity additions in Ras Al Khaimah are reshaping price floors for secondary emirate inventory, introducing competitive pressure on Dubai's affordable tier. Three-tier pricing structure across ultra-premium, mid-range, and affordable levels stratifies by certification grade and amenity depth. Cost compression in mid-range developments is intensifying because reinforced steel and concrete volatility squeezes margins before presales close. First-time buyers exhibit highest price sensitivity, while ultra-high-net-worth purchasers absorb compliance premiums through adjusted unit pricing with minimal elasticity.
Supply Chain Analysis
Freight costs for prefabricated concrete components from China, India, and Turkey are elevating landed costs for mid-rise developments dependent on imported structural elements. Reinforced steel rebar, high-performance glazing, and district cooling equipment constitute critical input dependencies. Single-source vulnerability concentrates in MEP engineering consultancies based in Dubai, where Pearl documentation expertise resides in a handful of firms. Distribution runs through vertically integrated master developers with captive manufacturing capabilities, bypassing fragmented subcontractor networks for core structural components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Emirates Green Building Council's Pearl rating mandates compound development economics by extending pre-construction phases and elevating mechanical specifications, creating structural demand for compliant master developers.
For Market Incumbents: Hedge against commodity volatility through backward integration into concrete and steel production, mirroring Sobha Realty's captive manufacturing model. Secure long-term offtake agreements with South Asian labor recruiters to mitigate bilateral visa policy fluctuations. Prioritize certification investment in Pearl Gold and Platinum ratings to differentiate from speculative operators facing compliance timeline compression.
For New Entrants and Emerging Players: Branded hospitality operators represent the most accessible channel partnership for penetrating Abu Dhabi's Al Reem Island corridor, where turnkey asset management demand concentrates. Target Ras Al Khaimah's casino-adjacent zoning as the most penetrable geography, where lower land costs attract institutional capital priced out of Dubai. Pursue smart building management integration as the primary go-to-market angle, capturing premium pricing tiers through IoT-enabled HVAC and access control differentiation.
For Investors and Strategic Acquirers: Sovereign wealth vehicles and regional family offices are the most active acquirer in this space, consolidating direct procurement relationships with master developers for super-prime inventory. Long-term viability centers on developers with integrated community design capabilities spanning retail, hospitality, and residential verticals. Watch escrow account regulation amendments as the critical signal for capital flow inflection and completion risk repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Branded Residence Partnership | Hospitality-operated service contracts capture ultra-high-net-worth buyers seeking turnkey asset management on Saadiyat Island. |
| Pearl Rating Certification Investment | Gold and Platinum ratings differentiate compliant developers from speculative operators facing extended pre-construction phases. |
| Smart Building Management Integration | IoT-enabled HVAC and access control systems open premium pricing tiers in Dubai's sustainable city districts. |
| Backward Integration into Materials | Captive concrete and steel production insulates margins from global commodity volatility in reinforced structural inputs. |
| Ras Al Khaimah Geographic Expansion | Casino-adjacent zoning and lower land costs attract institutional investors priced out of Dubai's prime coastal zones. |
Research Methodology
Direct dialogue with master developer project directors, Emirates Green Building Council certification officers, MEP engineering consultants, and institutional acquisition officers at sovereign wealth vehicles grounded the qualitative foundation. Secondary validation drew from Dubai Municipality Building Department code filings, MOHAP health and safety compliance records, escrow account regulatory frameworks, and master developer annual disclosures. Bottom-up project pipeline enumeration triangulated against top-down emirate-level construction spend aggregates.
Bottom-up unit absorption modeling by product type and price tier cross-referenced against top-down GDP and expatriate population projections across the analysis window. Segmentation dimensions included product type, end user category, price tier, service type, and emirate-level regulatory cluster. CAGRs derived from regression-based trending of historical absorption rates against Pearl rating penetration curves and waterfront zoning privilege expansion.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to bilateral visa policy shifts, reinforced steel commodity cycles, and Pearl rating documentation requirement amendments. Forecasts reflect documented assumptions around expatriate professional influx persistence and escrow regulation stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condominium and Apartments
Qatar Condominium and Apartment Market
Condominium and Apartments
Germany Condominiums and Apartments Market
Condominium and Apartments
Japan Condominiums and Apartments Market
Condominium and Apartments
Asia-Pacific Condominiums and Apartments Market
Condominium and Apartments
Canada Condominiums and Apartments Market
Condominium and Apartments
Europe Condominiums and Apartments Market
Condominium and Apartments
Italy Condominiums and Apartments Market
Condominium and Apartments
Latin America Condominiums and Apartments Market
Condominium and Apartments
Spain Condominiums and Apartments Market
Condominium and Apartments
Condom Market
Condominium and Apartments
Global Condominiums and Apartments Market
Condominium and Apartments
India Condominium and Apartments Market
Condominium and Apartments
Saudi Arabia Condominiums and Apartments Market
Condominium and Apartments
Egypt Condominiums and Apartments Market
Condominium and Apartments
ASEAN Condominiums and Apartments Market