
 France Condominiums and Apartments Market | 2026-2036
France Condominiums and Apartments Market Size, Share, and Industry Trends Forecast 2026-2036
France Condominiums and Apartments Market Foresight
Property management software subscriptions is consolidating around platforms that bundle tenant billing, maintenance dispatch, and energy monitoring into recurring revenue streams. Bouygues Immobilier leverages its captive digital infrastructure to lock in co-ownership syndicates across Greater Paris. Nexity anchors its competitive stance through vertically integrated design-build-operate contracts that span from land acquisition to post-handover facility management.
France condominiums and apartments comprise multi-unit residential structures governed by co-ownership law, with individual freehold titles for private units and undivided shares in common areas; RE2020 compliance now mandates embodied carbon below 640 kg CO2e per square meter for new buildings above four stories. The ownership model dimension shows co-ownership structures commanding premium pricing in Lyon and Bordeaux due to scarcity of compliant new supply, while freehold garden apartments in Provence-Alpes-Côte d'Azur attract retiree buyers seeking single-level layouts with reduced maintenance exposure. High-rise construction faces margin compression from steel and concrete cost volatility, whereas mid-rise timber-frame projects in Normandy and Brittany benefit from faster permitting under France's simplified environmental assessment pathways.
France's RE2020 building regulation, enforced by the Ministry of Ecological Transition, tightens operational and embodied carbon limits sequentially through 2031, pushing developers toward cross-laminated timber and low-carbon concrete formulations. The country's national construction regulator, alongside ANAH (National Housing Agency) renovation subsidies, steers capital toward energy retrofitting of existing condominiums rather than greenfield development. Stakeholders must track how Paris Region's local urbanism plans revise height and density allowances around Grand Paris Express stations, as these zoning shifts will determine which property type segments absorb the next wave of institutional capital.
Market Dynamics
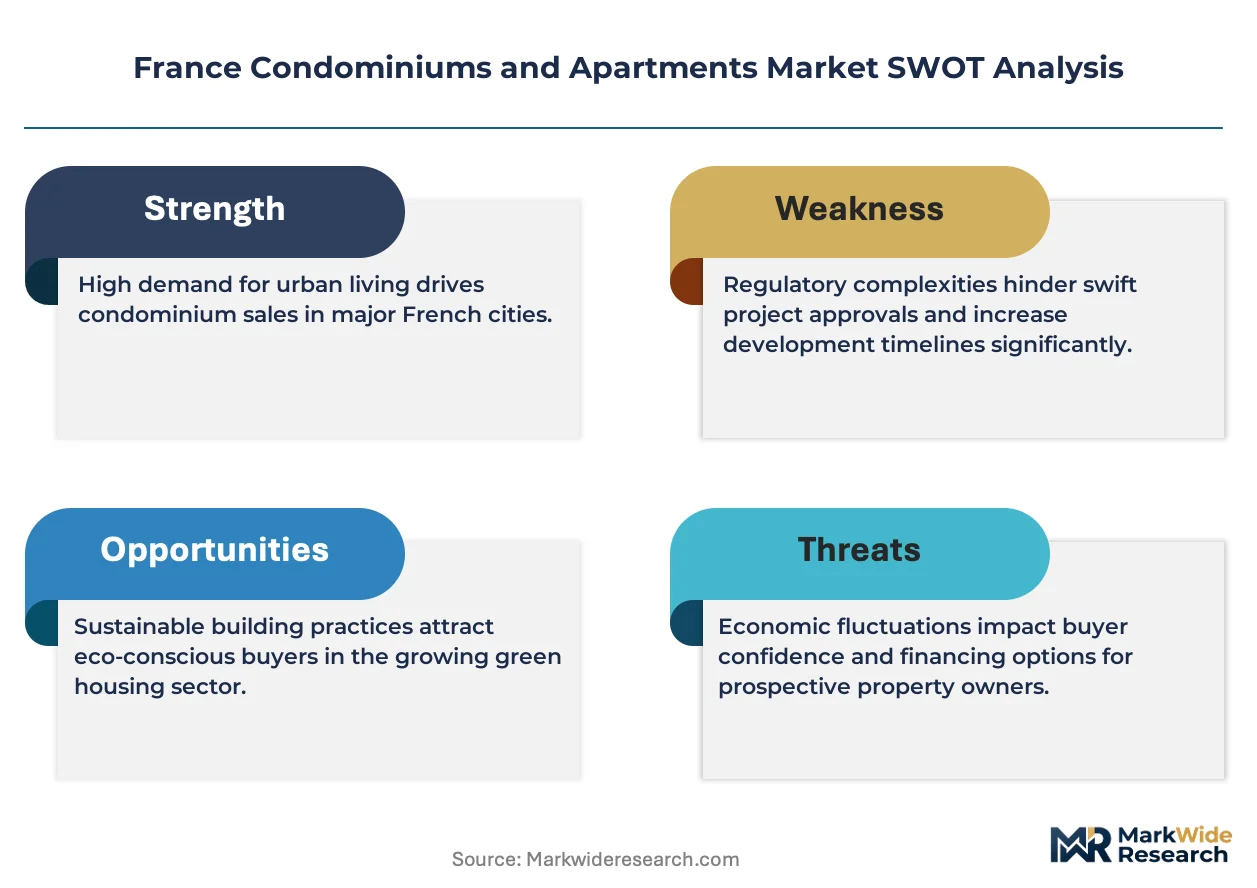
France's RE2020 environmental regulation is compressing development timelines and redrawing competitive positioning around embodied carbon compliance, forcing developers to retool material procurement and construction methods before the 2031 threshold tightening.
Growth Catalysts
- RE2020 Carbon Thresholds:The Ministry of Ecological Transition's sequential tightening of embodied carbon limits to 640 kg CO2e per square meter is accelerating adoption of cross-laminated timber and low-carbon concrete formulations in new residential construction.
- Grand Paris Express Station Proximity:Local urbanism plans revising height and density allowances around new transit nodes are unlocking institutional capital flows into high-rise condominium development in Seine-Saint-Denis and Val-de-Marne.
- ANAH Renovation Subsidies:The National Housing Agency's capital steering toward energy retrofitting of existing condominium stock is sustaining contractor activity even as greenfield permits face environmental review delays.
Market Restraints
- Steel and Concrete Cost Volatility:Input price swings for structural materials are compressing margins on high-rise concrete projects in Île-de-France, pushing developers toward smaller-scale timber-frame alternatives.
- Co-Ownership Syndicate Fragmentation:The dispersed decision-making structure of existing condominium associations creates friction in collective renovation decisions, slowing energy retrofit uptake in aging Parisian stock.
- Permitting Timeline Extension:France's environmental assessment pathways, even simplified routes for mid-rise timber construction, still impose 18-24 month approval cycles that tie up developer working capital.
Strategic Opportunities
- Normandy and Brittany Timber Corridors:These regions benefit from faster permitting under simplified environmental assessment pathways and local forestry supply chains that reduce embodied carbon in structural elements.
- Property Management Platform Bundling:Integrated software combining tenant billing, maintenance dispatch, and energy monitoring creates recurring revenue capture from co-ownership syndicates seeking operational efficiency.
- Certified Energy-Efficient Investor Stock:Lyon and Marseille see concentrated institutional demand for RE2020-compliant existing units, creating arbitrage potential for early retrofit adopters.
Industry Challenges
- Cross-Laminated Timber Engineering Talent Scarcity:The shift from steel-concrete to mass timber construction outpaces vocational training output, creating project execution risk in Normandy and Brittany developments.
- Co-Ownership Law Compliance Complexity:Navigating the legal framework governing collective decision-making in existing condominiums requires specialized legal expertise that lengthens transaction timelines for renovation financing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Condominiums and Apartments Market |
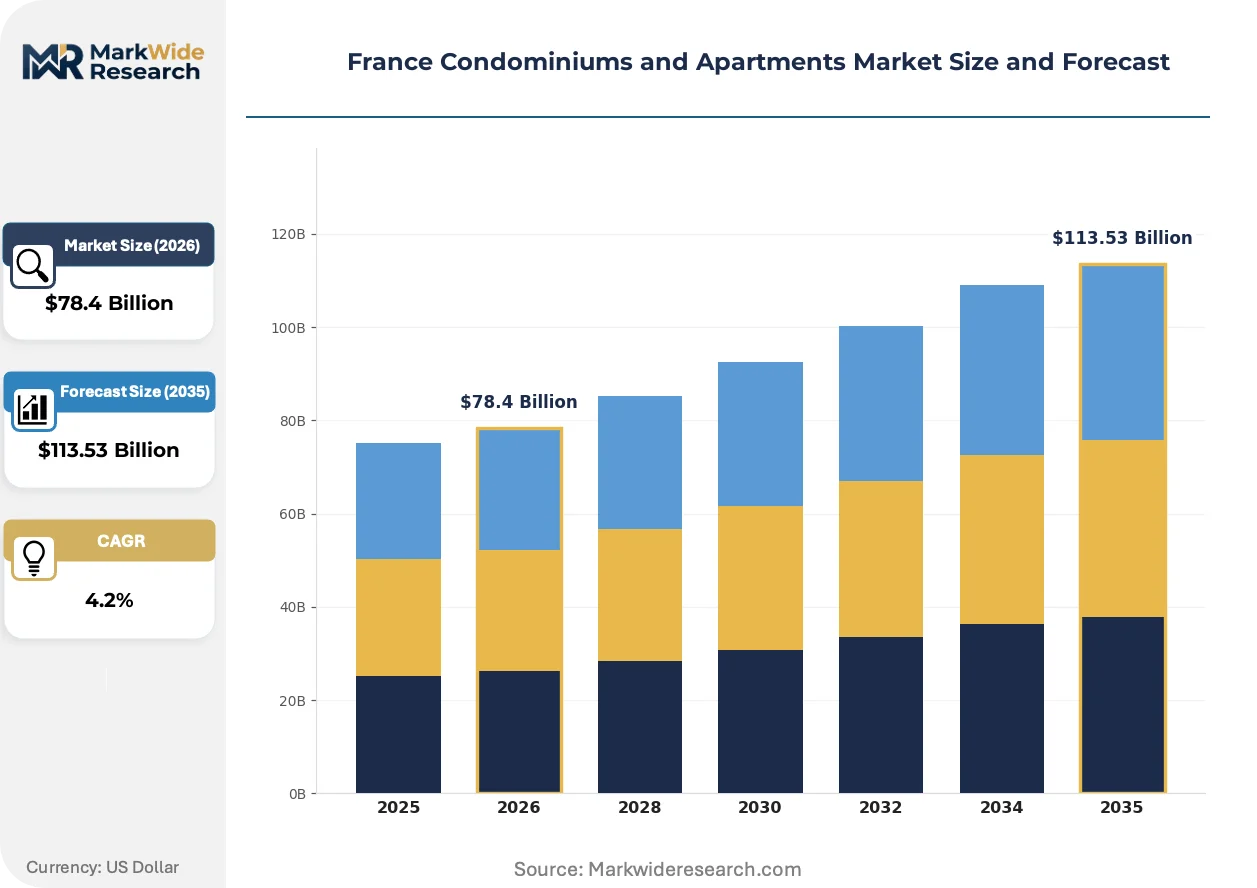
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $113.53 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: High-Rise, Mid-Rise, Low-Rise, Garden Apartments, Duplexes Ownership Model: Freehold, Leasehold, Co-Ownership, Timeshare Target Customer: First-Time Buyers, Investors, Retirees, Young Professionals, Expats Distribution Channel: Real Estate Agents, Online Portals, Direct Developers, Auctions |
| Companies Covered | Bouygues Batiment Ile De France, Vinci Construction France, Entreprise Generale Leon Grosse, Demathieu Bard Construction, GCC, Nexity, Bouygues Immobilier, Vinci Immobilier, Eiffage Immobilier, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Condominiums and Apartments Market Shifts & Advancements
Digital infrastructure and material science advances are reconfiguring how France's condominium and apartment market delivers, finances, and operates residential assets. Three developments warrant particular attention.
Building energy management systems is automating the collection and analysis of real-time consumption data across common areas and individual units. Property managers in Greater Paris are deploying these platforms to meet RE2020 operational carbon tracking requirements. The technology is automating compliance reporting and enabling dynamic utility billing that aligns tenant charges with actual usage patterns.
France's RE2020 regulation, enforced by the Ministry of Ecological Transition, tightens operational and embodied carbon limits sequentially through 2031. Developers must now source Environmental Product Declaration-certified materials and document lifecycle emissions from extraction through end-of-life. High-rise projects above four stories face the steepest compliance burden, accelerating experimentation with hybrid steel-timber structural systems.
Young professional households in Île-de-France are compressing their property search and purchase timelines, favoring turnkey new construction over renovation projects with uncertain completion dates. Digital-native buyers expect virtual staging, drone site surveys, and blockchain-secured transaction documentation. This behavioral shift favors developers with captive design-build-operate capabilities over traditional fragmented project delivery models.
France Condominiums and Apartments Market Segmentation
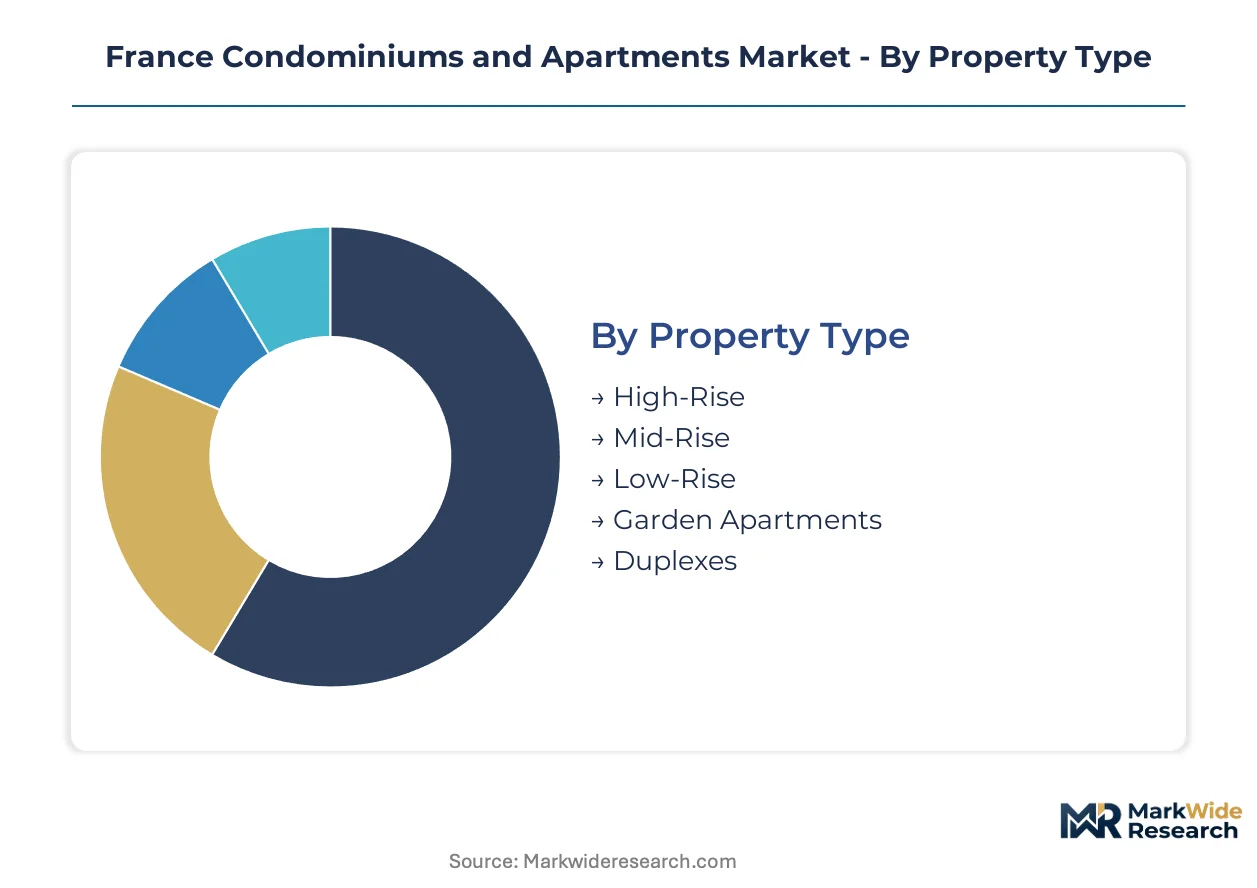
France's condominium and apartment market segments along four distinct axes that determine RE2020 compliance pathways, financing structures, and buyer acquisition channels. Each segmentation dimension carries specific regulatory and commercial implications for developers, syndicates, and investors operating across Île-de-France and regional metropolitan cores.
Property Type:
RE2020 carbon thresholds apply differentially across vertical construction categories, with high-rise structures facing the steepest embodied carbon limits under Ministry of Ecological Transition enforcement.
- High-Rise:Structures exceeding four stories must achieve embodied carbon below 640 kg CO2e per square meter, forcing hybrid steel-timber engineering and low-carbon concrete formulations. Institutional capital concentrates in Seine-Saint-Denis and Val-de-Marne high-rises proximate to Grand Paris Express stations, though steel cost volatility compresses developer margins.
- Mid-Rise:Four-story timber-frame construction benefits from simplified environmental assessment pathways in Normandy and Brittany, with cross-laminated timber supply chains reducing compliance costs. Regional developers favor this segment for faster permitting cycles and lower structural material exposure.
- Low-Rise:Traditional masonry construction dominates Provence-Alpes-Côte d'Azur retiree markets seeking single-level accessibility with minimal maintenance obligations.
- Garden Apartments:Ground-floor units with private outdoor space command premiums in Lyon and Bordeaux where compliant new supply remains scarce.
- Duplexes:Two-level configurations attract young professional households in Île-de-France seeking spatial separation within dense urban fabric.
Leading the category by volume: Mid-Rise. Growing fastest: High-Rise.
Ownership Model:
Legal structure determines renovation financing access, collective decision-making friction, and resale liquidity across France's co-ownership law framework.
- Freehold:Individual title ownership eliminates syndicate coordination costs, accelerating renovation decisions in aging Parisian stock. Retiree buyers in Provence-Alpes-Côte d'Azur prioritize freehold garden apartments for reduced maintenance exposure and direct control over property modifications.
- Co-Ownership:Undivided shares in common areas create premium pricing in Lyon and Bordeaux due to scarcity of RE2020-compliant new supply, though dispersed decision-making slows energy retrofit uptake.
- Leasehold:Ground rent obligations reduce upfront acquisition costs for first-time buyers in Greater Paris, extending household leverage capacity.
- Timeshare:Fractional ownership structures capture seasonal demand in coastal Provence and Alpine zones, with limited institutional participation.
Volume leader: Co-Ownership. Steepest expansion trajectory: Freehold.
Target Customer:
Buyer demographics align with distinct financing instruments, spatial preferences, and digital engagement patterns across the acquisition journey.
- Young Professionals:Digital-native households in Île-de-France compress search timelines, favoring turnkey new construction with virtual staging and blockchain-secured documentation over renovation uncertainty.
- Investors:Institutional and private capital concentrates in Lyon and Marseille certified energy-efficient stock, creating arbitrage potential for early RE2020 retrofit adopters.
- First-Time Buyers:ANAH subsidy eligibility steers this segment toward energy renovation of existing stock rather than greenfield acquisition.
- Retirees:Single-level layouts in Provence-Alpes-Côte d'Azur freehold garden apartments minimize maintenance exposure and mobility constraints.
- Expats:Corporate relocation demand clusters in Paris Region and Lyon, with preference for furnished turnkey units and property management platform integration.
Volume leader: Young Professionals. Climbing the fastest: Investors.
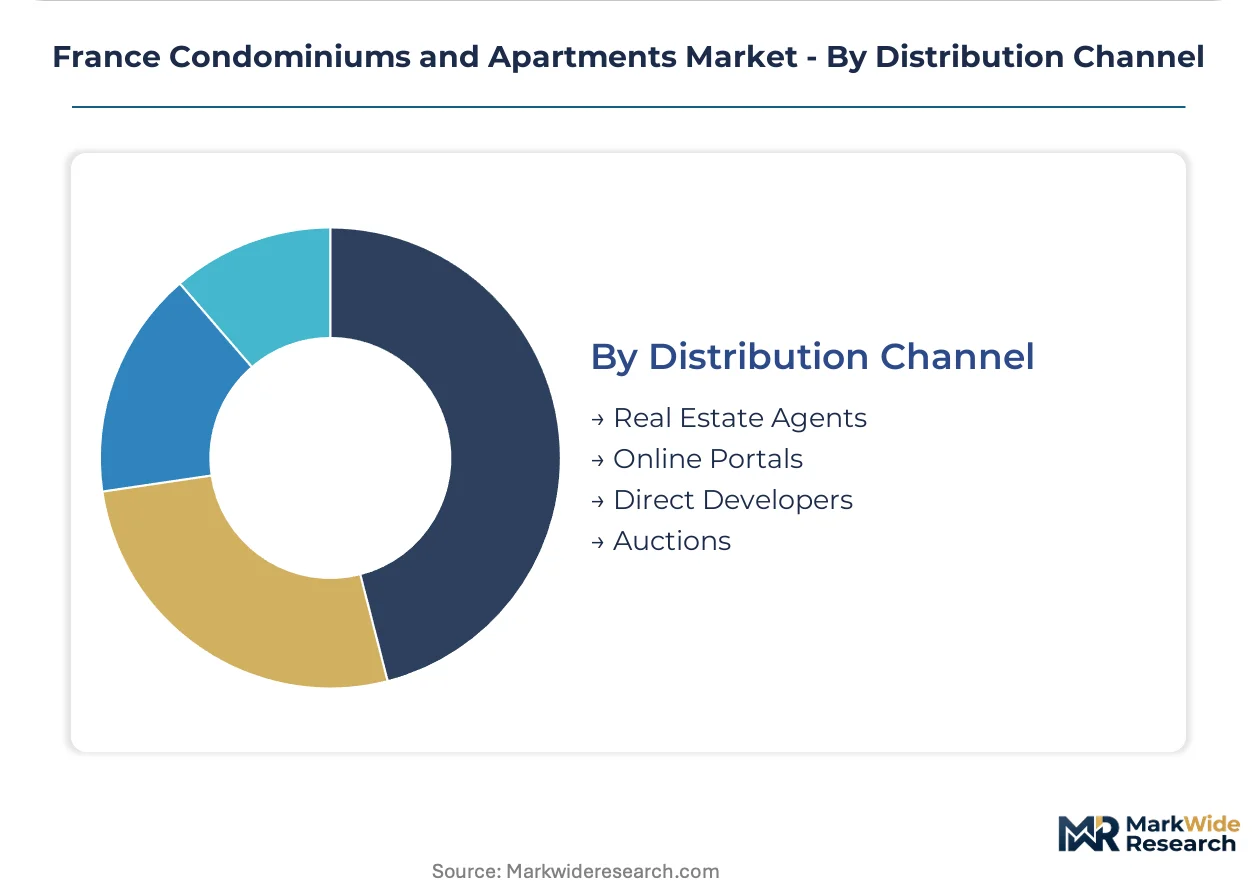
Distribution Channel:
Channel selection determines customer acquisition cost, syndicate relationship depth, and recurring revenue capture for property management services.
- Direct Developers:Bouygues Immobilier and Nexity leverage captive digital infrastructure to lock in co-ownership syndicates across Greater Paris, bundling tenant billing, maintenance dispatch, and energy monitoring into recurring revenue streams.
- Online Portals:Virtual staging and drone site survey capabilities attract young professional households seeking compressed decision timelines.
- Real Estate Agents:Traditional intermediaries retain dominance in retiree and first-time buyer segments requiring financing navigation assistance.
- Auctions:Distressed and renovation-heavy properties transact through judicial and voluntary sale mechanisms, appealing to investor buyers with specialized legal expertise.
Volume leader: Real Estate Agents. Gaining share fastest: Direct Developers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France dominates France's condominium and apartment market, with Grand Paris Express station proximity unlocking institutional capital flows into high-rise development across Seine-Saint-Denis and Val-de-Marne.
Île-de-France
Young professional households compress search timelines, favoring turnkey new construction with virtual staging capabilities. The Ministry of Ecological Transition enforces RE2020 embodied carbon thresholds of 640 kg CO2e per square meter for structures above four stories. Bouygues Immobilier and Nexity anchor development activity in Greater Paris through vertically integrated design-build-operate contracts.
Auvergne-Rhône-Alpes
Certified energy-efficient stock in Lyon attracts concentrated institutional investor demand, creating arbitrage potential for early retrofit adopters. ANAH renovation subsidies steer capital toward energy retrofitting of existing condominiums rather than greenfield projects. The metropolitan core sees premium pricing for co-ownership structures due to scarcity of RE2020-compliant new supply.
Provence-Alpes-Côte d'Azur
Retiree buyers prioritize freehold garden apartments with single-level layouts and reduced maintenance exposure. Local urbanism plans around transit nodes are revising height and density allowances to accommodate demographic shifts. Marseille's certified energy-efficient stock mirrors Lyon in drawing investor capital seeking compliant assets.
Normandy
Mid-rise timber-frame construction benefits from simplified environmental assessment pathways and faster permitting cycles. Cross-laminated timber supply chains reduce embodied carbon in structural elements, aligning with RE2020 compliance trajectories. Regional developers favor this segment for lower structural material cost exposure compared to steel-concrete alternatives.
Brittany
Local forestry supply chains support mass timber construction, though cross-laminated timber engineering talent scarcity creates project execution risk. The region's simplified environmental assessment pathways accelerate approval timelines relative to high-rise concrete projects elsewhere. Timber corridor development concentrates contractor activity away from margin-compressed vertical construction.
France Condominiums and Apartments Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across France's condominium and apartment market, with integrated developers controlling captive digital infrastructure while specialized contractors compete on timber engineering expertise. The market structure consolidates around three strategic archetypes: vertically integrated national developers with in-house property management platforms, regional timber-frame specialists exploiting simplified permitting pathways, and institutional-grade retrofit contractors capturing ANAH-subsidized renovation demand. Dominant competitive moves include backward integration into cross-laminated timber supply chains and bundling of tenant billing, maintenance dispatch, and energy monitoring into recurring revenue streams.
Within the integrated developer tier, Bouygues Immobilier and Nexity occupy positions defined by captive digital infrastructure and design-build-operate contract capabilities. Nexity exemplifies the vertically integrated archetype spanning land acquisition through post-handover facility management. Among construction-focused entities, Bouygues Batiment Ile De France and Vinci Construction France represent capital-heavy engineering and contracting specialists. Eiffage Immobilier sits within the property development arm of diversified infrastructure groups. These named entities anchor competitive dynamics without exhaustive market coverage.
| Leading Market Players |
|---|
| Bouygues Batiment Ile De France |
| Vinci Construction France |
| Entreprise Generale Leon Grosse |
| Demathieu Bard Construction |
| GCC |
| Nexity |
| Bouygues Immobilier |
| Vinci Immobilier |
| Eiffage Immobilier |
| Others |
Supply & Pricing Matrix
Cross-laminated timber engineering talent concentration in Normandy and Brittany feeds labor-cost differentials that widen pricing-tier spreads between mass timber mid-rise projects and steel-concrete high-rise alternatives across France's residential construction sector.
Pricing Analysis
Energy performance certification anchors value-based pricing in France's condominium market, with RE2020-compliant units commanding premiums over non-compliant stock in Lyon and Marseille. Pricing stratifies across premium certified-efficient tiers, standard code-compliant mid-market offerings, and economy-grade aging inventory requiring renovation. Cost compression in high-rise concrete construction intensifies because steel and concrete input volatility erodes developer margins. First-time buyers accessing ANAH subsidies exhibit highest price sensitivity, while institutional investors acquiring certified-efficient stock show lowest sensitivity to per-unit acquisition costs.
Supply Chain Analysis
Deconstruction and material recovery flows from aging Parisian condominiums feed secondary timber and reclaimed structural elements into Normandy and Brittany renovation supply chains. Raw material sourcing draws from French domestic forestry for cross-laminated timber, German and Austrian engineered wood product imports, and domestic low-carbon concrete formulations. Single-source vulnerability concentrates in cross-laminated timber engineering expertise, where vocational training output lags project demand. Distribution runs through vertically integrated developers with captive digital infrastructure, regional timber-frame specialists, and traditional contractor networks serving co-ownership syndicate renovation demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's condominium and apartment market constitutes a consolidation play as RE2020 compliance thresholds force capital-constrained developers toward exit or acquisition by integrated national platforms.
For Market Incumbents: Hedge against steel and concrete cost volatility by accelerating backward integration into cross-laminated timber supply chains and securing long-term forestry offtake agreements in Normandy. Lock in co-ownership syndicate relationships through bundled property management platforms combining tenant billing, maintenance dispatch, and energy monitoring to create switching costs that deter competitor encroachment. For New Entrants and Emerging Players: Property management software vendors represent the most penetrable channel partner type for gaining co-ownership syndicate access without competing directly against Bouygues Immobilier and Nexity's land-banking advantages. Target mid-rise timber-frame development in Brittany and Normandy where simplified environmental assessment pathways compress permitting timelines relative to high-rise concrete alternatives. Pursue design-build-operate contract capabilities spanning land acquisition through post-handover facility management to match incumbent integrated delivery models. For Investors and Strategic Acquirers: The window for entry favors regional timber-frame specialists with established cross-laminated timber engineering teams and local forestry supply relationships. Long-term viability hinges on positioning ahead of 2031 RE2020 threshold tightening, when embodied carbon limits below 640 kg CO2e per square meter will disqualify conventional steel-concrete construction methods. Monitor ANAH subsidy allocation shifts and Grand Paris Express station zoning revisions as inflection indicators for capital flow redirection between greenfield development and existing stock retrofitting.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cross-Laminated Timber Supply | Secures embodied carbon compliance advantage ahead of 2031 RE2020 threshold tightening enforced by Ministry of Ecological Transition. |
| Property Management Platform Bundling | Creates recurring revenue capture from co-ownership syndicates seeking operational efficiency across Greater Paris. |
| Design-Build-Operate Contract Capabilities | Spans land acquisition through post-handover facility management to match Nexity's vertically integrated competitive stance. |
| ANAH-Subsidized Renovation Specialization | Captures capital flows steered by National Housing Agency toward energy retrofitting of aging Parisian condominium stock. |
| Grand Paris Express Station Proximity Development | Unlocks institutional capital flows as local urbanism plans revise height and density allowances in Seine-Saint-Denis and Val-de-Marne. |
Research Methodology
Independent corroboration across primary interviews with property development executives, co-ownership syndicate managers, timber engineering specialists, and ANAH program administrators, combined with secondary validation of Ministry of Ecological Transition regulatory filings, ANAH subsidy disbursement records, and Grand Paris Express infrastructure development disclosures, underwrites the qualitative findings. Bottom-up project pipeline tracking across Île-de-France, Auvergne-Rhône-Alpes, and Provence-Alpes-Côte d'Azur metropolitan areas triangulates against top-down construction permit database analysis.
Rate-of-change decomposition across the projection horizon segments volume and value outputs by property type, ownership model, target customer archetype, and distribution channel. CAGRs derive from regression analysis of historical permit issuance, absorption rates by buyer segment, and regulatory compliance cost trajectories. Cross-laminated timber supply capacity expansion timelines and RE2020 threshold implementation schedules constitute industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including macroeconomic interest rate shifts affecting household mortgage capacity, unforeseen regulatory amendments to RE2020 carbon thresholds, and geopolitical disruptions to engineered wood product imports from German and Austrian suppliers. Forecasts reflect assumptions regarding continued ANAH subsidy availability and Grand Paris Express construction schedule adherence. Practitioners should monitor steel and concrete input price volatility, cross-laminated timber engineering graduate pipeline expansion, and co-ownership syndicate voting threshold reforms for early signals warranting forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Canada Residential Real Estate Market
Residential Real Estate Market
Germany Residential Real Estate Market
Residential Real Estate Market
Saudi Arabia Residential Real Estate Market
Residential Real Estate Market
France Manufactured Homes Market
Residential Real Estate Market
Egypt Manufactured Homes Market
Residential Real Estate Market
India Manufactured Homes Market
Residential Real Estate Market
UK Residential Real Estate Market
Residential Real Estate Market
India Residential Construction Market
Residential Real Estate Market
Germany Manufactured Homes Market
Residential Real Estate Market
India Residential Real Estate Market
Residential Real Estate Market
Singapore Real Estate Market
Residential Real Estate Market
Qatar Manufactured Homes Market
Residential Real Estate Market
South Africa Residential Real Estate Market
Residential Real Estate Market
Real Estate Market
Residential Real Estate Market
Global Manufactured Housing Market
Residential Real Estate Market
Malaysia Residential Real Estate Market