
 Qatar Manufactured Homes Market | 2026-2036
Qatar Manufactured Homes Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Manufactured Homes Market Analytics
Qatar's National Vision 2030 green building mandates are repositioning manufactured housing procurement toward energy-efficient modular solutions across major infrastructure corridors. SHELTER Group leverages its vertical integration into steel fabrication to control material costs for large-scale worker camp deployments. Qatar Speed House anchors its competitive position through specialized R&D in climate-adaptive insulation systems engineered for Gulf summer extremes. Desert Line Group differentiates via its dominance in rapid-deployment hybrid construction models serving Lusail and Ras Laffan industrial zones.
Manufactured homes are prefabricated dwelling units produced in controlled factory environments, typically incorporating steel or composite framing with standardized dimensions of 14 to 16 feet in width for road-transportable sections, designed for rapid on-site assembly to serve residential, commercial, or institutional occupancy needs. Modular units lead volume deployment across Qatar's infrastructure pipeline due to their scalability for labor camp expansions tied to World Cup legacy projects and North Field gas expansion works. Single-section products occupy the premium tier in remote site applications where transport logistics restrict multi-section delivery, while steel-framed construction dominates the building material mix given Qatar's humidity corrosion challenges and the country's fire safety regulatory thresholds.
Qatar's Ministry of Municipality and Environment enforces construction permits through the Building Permits Department, while the Qatar General Organization for Standardization (QS) mandates product conformity for imported modular components under Gulf Standardization Organization harmonized codes. The Ministry of Labour's worker welfare regulations shape demand specifications through mandated square footage, ventilation, and amenity standards for employer-provided accommodation. Stakeholders must monitor how QS adoption of updated GSO modular building standards will alter import sourcing patterns and local fabrication requirements.
Market Dynamics
Qatar's National Vision 2030 green building mandates are compressing procurement cycles toward energy-certified modular units, forcing fabricators to requalify entire product lines for enhanced thermal performance standards ahead of North Field expansion timelines.
Growth Catalysts
- North Field gas expansion:State-backed infrastructure works are generating sustained demand for scalable worker accommodation across Ras Laffan and Mesaieed industrial corridors.
- QS-GSO harmonized standards:Qatar General Organization for Standardization adoption of updated modular building codes is streamlining import pathways for prefabricated steel components.
- Hybrid construction methods:Rapid-deployment systems combining factory-built modules with site-assembled cores are cutting project timelines for Lusail satellite district developments.
Market Restraints
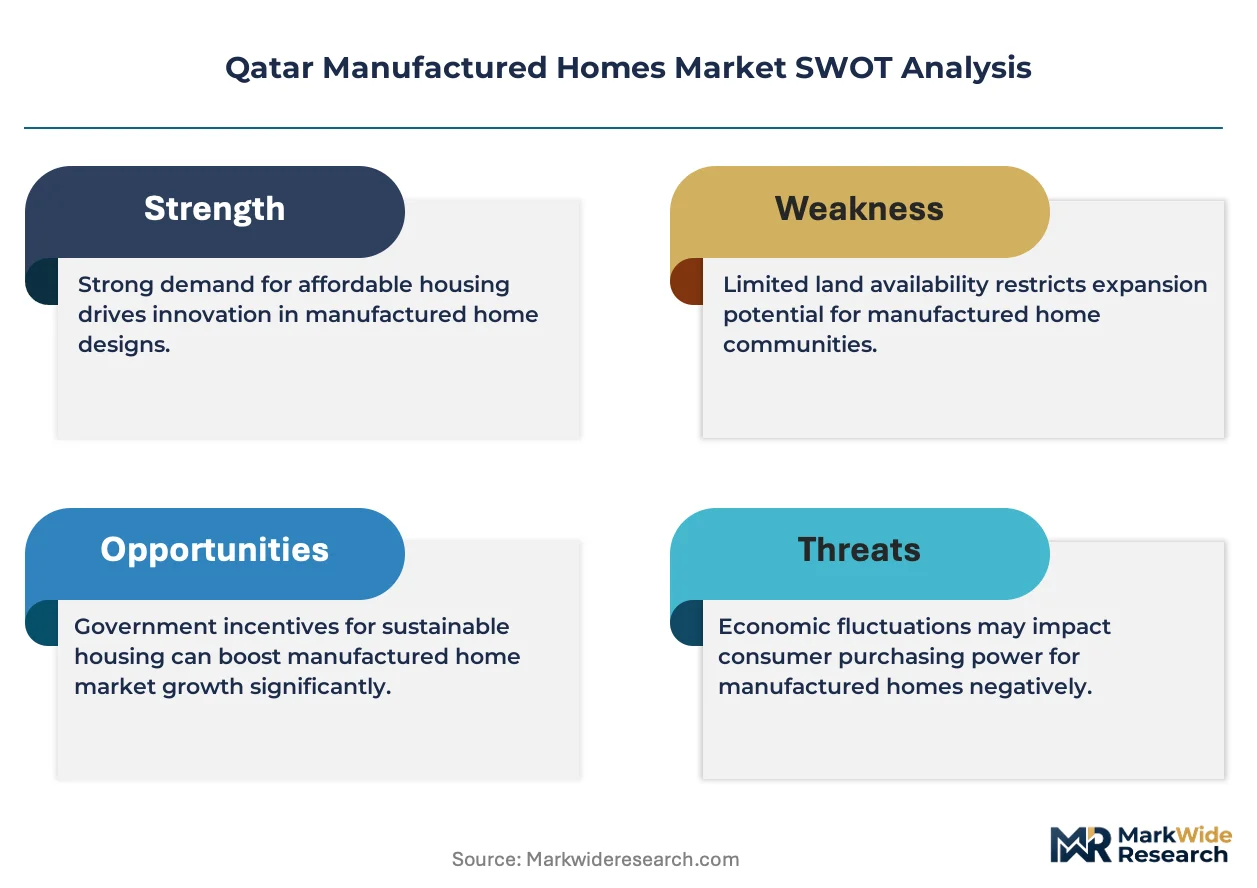
- Steel price volatility:Raw material cost swings in structural steel and galvanized framing inputs compress fabrication margins on fixed-price camp contracts.
- Single-source supply risk:Specialized climate-adaptive insulation systems rely on concentrated Gulf-based chemical suppliers vulnerable to regional logistics disruptions.
- Transport dimensional limits:Road-transportable module widths capped at sixteen feet restrict floorplan flexibility for premium single-section deployments in remote site applications.
Strategic Opportunities
- Al Wakrah logistics hub:Underdeveloped port-adjacent zones offer greenfield fabrication capacity to serve southern industrial corridor demand.
- Worker welfare upgrades:Ministry of Labour mandated amenity standards are creating premium tier demand for enhanced ventilation and square footage specifications.
- Solar-integrated envelopes:Building-integrated photovoltaics converging with modular wall systems open new bidding categories for net-zero camp demonstrations.
Industry Challenges
- Welding certification bottlenecks:Qatar Civil Defence Authority fire-rated joint inspection queues extend project handover timelines for steel-framed assemblies.
- Legacy camp retrofit integration:Existing worker accommodation stock requires costly thermal envelope upgrades to meet current QS insulation performance thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Manufactured Homes Market |
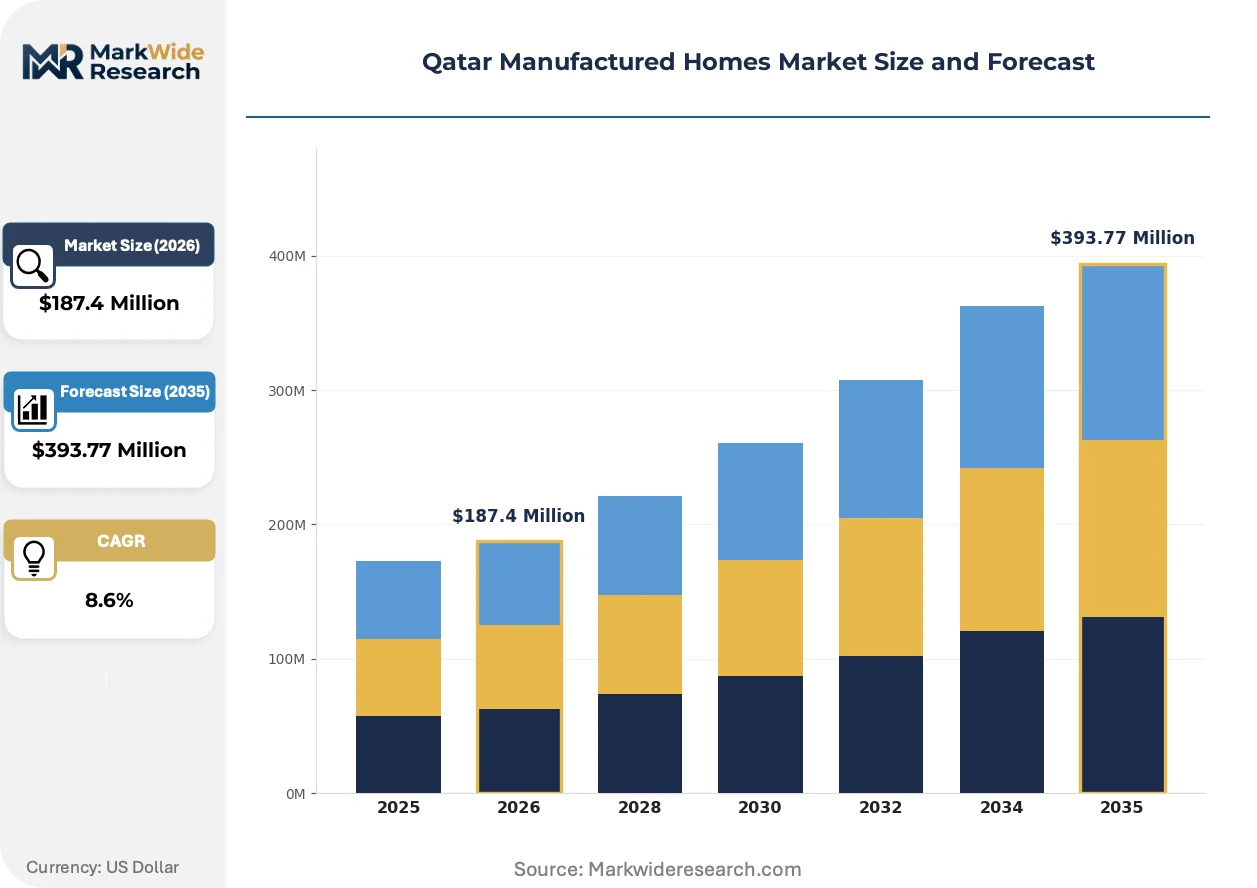
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Section, Multi-Section, Tiny Homes, Modular Units End User: Residential, Commercial, Temporary Housing, Government Projects Building Material: Wood, Steel, Concrete, Composite Deployment Model: On-Site, Off-Site, Hybrid, Custom Builds |
| Companies Covered | SHELTER Group, Qatar Speed House, Domopan, Desert Line Group, TSSC Group, Dalal Steel Industries, Clayton Homes, Morton Buildings Inc, Prefabex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Manufactured Homes Market Evolving Landscape
Climate-adaptive building envelopes and digital fabrication workflows are compressing traditional construction timelines while Qatar's regulatory framework tightens performance standards for temporary worker housing.
Advanced composite wall panels with integrated phase-change materials are modularizing thermal mass distribution across Qatar's manufactured housing sector. Infrastructure contractors deploying these systems for North Field labor camps are achieving enhanced indoor temperature stability during Gulf summer peaks. The technology is modularizing procurement specifications as QS mandates increasingly reference factory-certified envelope performance rather than site-built alternatives.
Ministry of Municipality and Environment enforcement of updated green building codes is mandating enhanced insulation R-values and air-tightness testing for all new worker accommodation permits. Fabricators must now submit third-party thermal bridge calculations alongside structural drawings, adding documentation burden but creating quality differentiation. Camp operators in Doha's industrial zone corridors are responding by pre-qualifying suppliers with certified envelope simulation capabilities.
Build-operate-transfer contracting is displacing traditional purchase-and-own models for large-scale worker accommodation. Qatar's infrastructure developers now prefer vendors who retain asset ownership and deliver housing as a service across multi-year project lifecycles. This shift concentrates most visibly in Lusail construction districts where single-source responsibility for maintenance and compliance reduces employer administrative overhead.
Qatar Manufactured Homes Market Segmentation
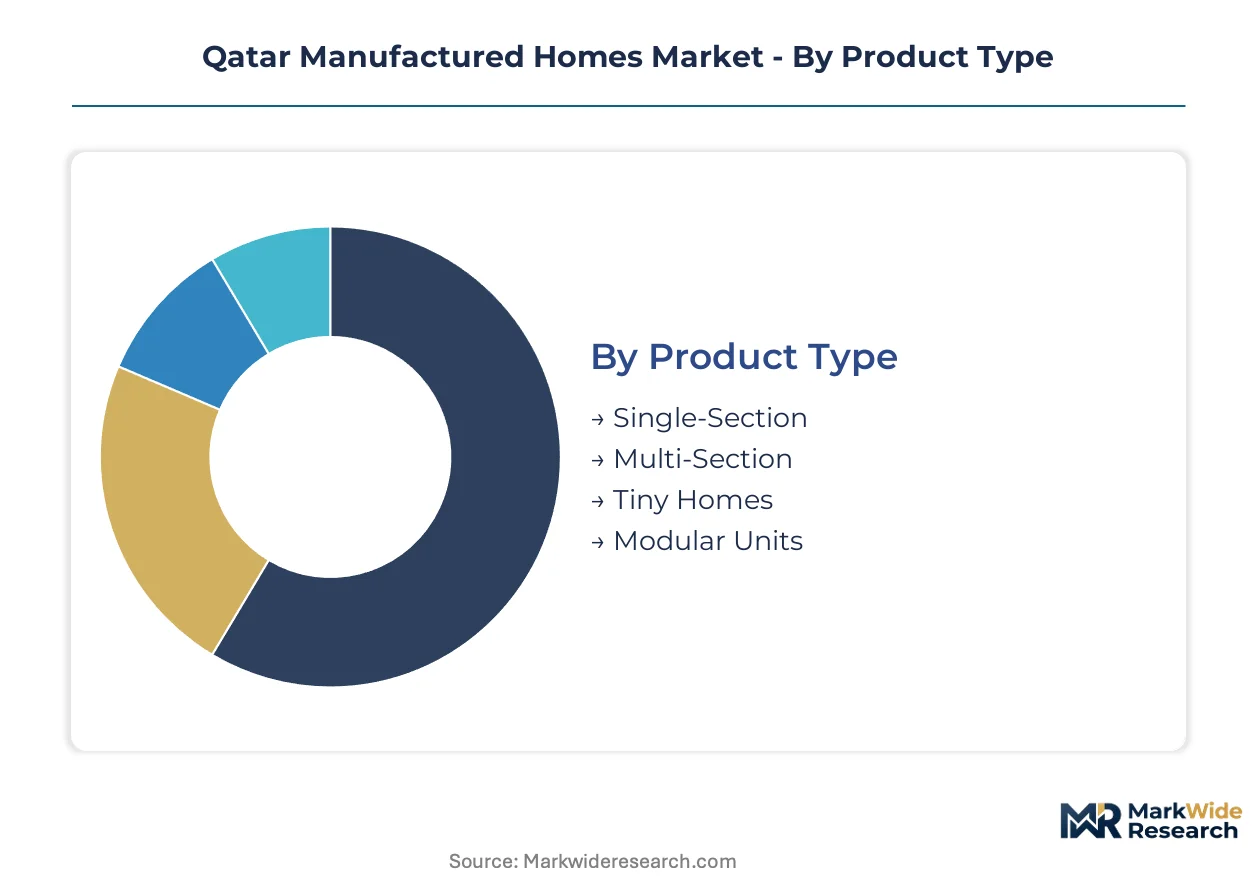
Qatar's manufactured housing procurement splits across four distinct axes, each reflecting how National Vision 2030 mandates and North Field infrastructure timelines reshape specification requirements. Understanding these segment boundaries clarifies where thermal performance standards, steel framing preferences, and rapid-deployment logistics concentrate commercial opportunity.
Product Type:
Structural modularity and transport geometry define competitive positioning across Qatar's product spectrum.
- Single-Section:Factory-built units with widths capped at sixteen feet for road transportability serve remote site applications where multi-section delivery proves logistically prohibitive. Premium pricing concentrates in Ras Laffan industrial zone worker camps requiring rapid standalone deployment.
- Multi-Section:Two or more transportable modules joined on-site enable larger floorplans for Lusail satellite district labor accommodations. Scalability advantages align with Ministry of Labour square footage mandates for employer-provided housing.
- Tiny Homes:Compact sub-400 square foot units target specialized remote security posts and isolated maintenance facilities across Mesaieed corridors.
- Modular Units:Standardized volumetric construction dominates volume deployment for World Cup legacy project expansions and North Field gas works.
Mature deployment sits with Modular Units. Newer deployment is concentrated in Single-Section premium configurations for constrained-access sites.
End User:
Procurement authority and compliance burden vary sharply across buyer categories, reshaping vendor qualification requirements.
- Residential:Individual purchasers seeking permanent or semi-permanent dwellings represent limited volume given Qatar's expatriate housing norms and property ownership restrictions.
- Commercial:Corporate employers sourcing worker accommodation under Ministry of Labour welfare regulations drive standardized specification demand across Doha industrial corridors.
- Temporary Housing:Infrastructure contractors requiring 2-5 year asset lifecycles for project-tied labor camps generate recurring replacement demand aligned with North Field expansion phasing.
- Government Projects:State-backed entities procuring through Qatar General Organization for Standardization certified channels enforce stringent thermal envelope and fire safety documentation.
Volume concentration favors Commercial buyers. Margin expansion is accelerating fastest in Government Projects given certification barriers.
Building Material:
Climate durability and regulatory compliance dictate material selection against Gulf humidity and Qatar Civil Defence Authority fire ratings.
- Wood:Limited application in interior finishes and non-structural elements due to moisture degradation risks and fire code restrictions in high-occupancy camp settings.
- Steel:Galvanized structural framing dominates the material mix, addressing corrosion challenges from coastal humidity while meeting mandatory fire-rated joint inspection protocols.
- Concrete:Precast floor slabs and foundation systems anchor hybrid construction models combining factory-built modules with site-cast structural cores.
- Composite:Advanced wall panels integrating phase-change materials and insulated metal facades command specification in QS-certified green building demonstrations.
Steel maintains incumbent position across volume contracts. Composite is gaining share fastest in sustainability-mandated procurement tiers.
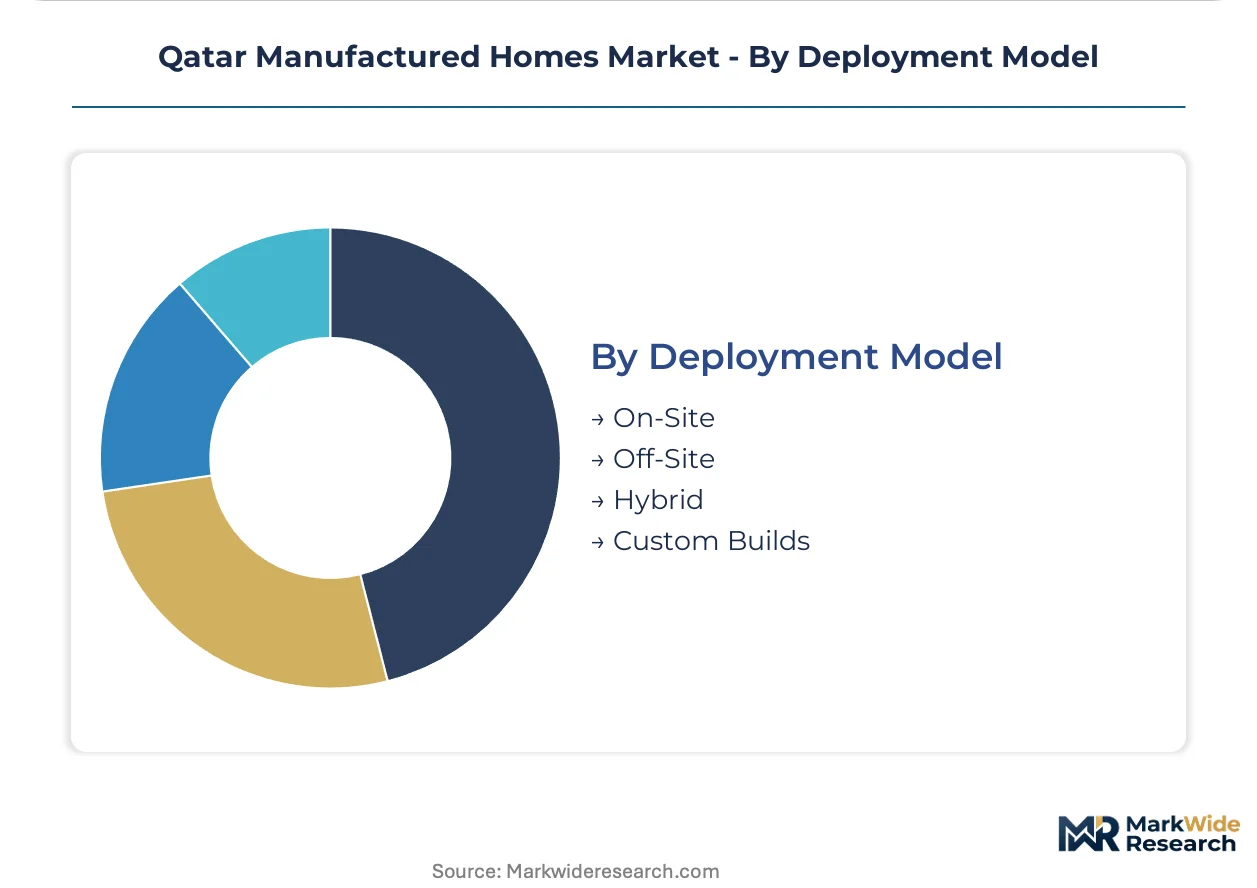
Deployment Model:
Project timeline compression and asset ownership structures reshape how manufactured housing reaches Qatar's construction zones.
- On-Site:Traditional stick-built construction persists in legacy camp retrofits where existing foundations constrain modular replacement economics.
- Off-Site:Factory-controlled production of complete volumetric units minimizes weather delays and quality variance for standardized worker camp expansions.
- Hybrid:Rapid-deployment systems merging factory-built modules with site-assembled structural cores dominate Lusail and Al Wakrah logistics hub developments.
- Custom Builds:Project-specific engineering for non-standard camp configurations serves specialized North Field operational requirements.
Off-Site fabrication anchors current procurement patterns. Hybrid deployment is expanding most quickly as build-operate-transfer contracting displaces purchase-and-own models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Doha's industrial zone corridors concentrate Qatar's manufactured housing procurement, with Ras Laffan and Mesaieed anchoring demand tied to North Field gas expansion timelines. Lusail's construction satellite districts and Al Wakrah's emerging logistics hub reshape deployment geography as build-operate-transfer contracting displaces traditional purchase models.
Doha Industrial Corridor
Worker accommodation camps along the Doha-Ras Laffan highway generate sustained demand for standardized modular units under Ministry of Labour welfare regulations. Qatar Civil Defence Authority fire-rated joint inspection protocols compress vendor qualification timelines for steel-framed assemblies. The Mesaieed industrial zone hosts concentrated camp retrofits where legacy stock requires thermal envelope upgrades to meet current QS insulation thresholds.
Lusail Satellite Districts
World Cup legacy project expansions drive scalable labor housing procurement through hybrid construction models merging factory-built modules with site-assembled cores. Build-operate-transfer contracting concentrates here as infrastructure developers prefer vendors retaining asset ownership across multi-year lifecycles. The Ministry of Municipality and Environment enforces enhanced green building codes mandating third-party thermal bridge calculations for all new permits.
Al Wakrah Logistics Hub
Underdeveloped port-adjacent zones offer greenfield fabrication capacity to serve southern industrial corridor demand from North Field expansion works. Qatar General Organization for Standardization adoption of updated GSO modular building codes streamlines import pathways for prefabricated steel components. Local fabricators are positioning for rapid-deployment contracts as Mesaieed contractor demand shifts southward.
Ras Laffan Industrial Zone
State-backed gas infrastructure works generate premium-tier demand for single-section units where remote site access restricts multi-section delivery logistics. Specialized climate-adaptive insulation systems command specification as QS mandates increasingly reference factory-certified envelope performance. Camp operators here pre-qualify suppliers with certified envelope simulation capabilities ahead of summer peak deployment cycles.
Al Khor Northern Corridor
Isolated maintenance facilities and security posts across northern extraction sites drive compact sub-400 square foot tiny home deployments. Transport dimensional limits cap module widths at sixteen feet, restricting floorplan flexibility for premium standalone configurations. Ministry of Labour mandated amenity standards are creating upgrade demand for enhanced ventilation specifications in legacy camp stock.
Qatar Manufactured Homes Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-tier segmentation, with QS-certified envelope performance creating defendable pricing separation. The vendor base clusters around three strategic archetypes: steel fabricators with backward integration into raw material supply, climate-adaptive insulation specialists, and rapid-deployment hybrid construction integrators. Consolidation pressure intensifies as fixed-price camp contracts compress fabrication margins during steel price volatility. Dominant competitive moves center on welding certification pre-qualification to bypass Qatar Civil Defence Authority inspection queues and captive supply of galvanized framing inputs.
Among Qatar-based fabricators, SHELTER Group and Qatar Speed House exemplify the certification-tier premium archetype, while Desert Line Group anchors rapid-deployment positioning. SHELTER Group represents steel fabrication backward integration, controlling material costs for large-scale camp deployments. Qatar Speed House occupies the climate-adaptive specialization tier. Desert Line Group sits within the hybrid construction integrator category serving Lusail and Ras Laffan industrial zones. These three named entities illustrate how competitive positioning stratifies across thermal performance certification, material supply control, and deployment speed capabilities.
| Leading Market Players |
|---|
| SHELTER Group |
| Qatar Speed House |
| Domopan |
| Desert Line Group |
| TSSC Group |
| Dalal Steel Industries |
| Clayton Homes |
| Morton Buildings Inc |
| Prefabex |
| Others |
Value Network & Pricing Analysis
QS-certified envelope performance separates premium-tier fabricators from commodity steel assemblers across Qatar's manufactured housing procurement, with certification ladders dictating both bid pricing and upstream sourcing configurations. Thermal bridge calculation capabilities and Qatar Civil Defence Authority welding pre-qualification status determine which vendors capture fixed-price camp contracts versus spot-market module sales.
Pricing Analysis
Value-based pricing anchored to worker welfare compliance outcomes dominates Qatar's manufactured housing procurement, with camp operators paying premiums for guaranteed Qatar General Organization for Standardization certification acceptance. Price differentiation hinges on thermal performance grade and Qatar Civil Defence Authority fire-rated joint inspection pre-approval status, with certified envelope simulation capabilities commanding substantial bid premiums. Pricing pressure stems from structural steel cost volatility compressing margins on multi-year fixed-price North Field expansion contracts. Commercial buyers under Ministry of Labour welfare mandates exhibit highest price sensitivity, while government project procurement through certified channels shows lowest sensitivity given compliance risk aversion.
Supply Chain Analysis
Direct-to-contractor channels handle hyperscale infrastructure buyer demand across Qatar's manufactured housing sector, bypassing distributor markups for North Field and Lusail deployment volumes. Geographic supply concentration centers on China for galvanized structural steel framing, the UAE for climate-adaptive insulation chemical feedstocks, and India for precast concrete foundation components. Raw material dependencies rest on structural steel coils, phase-change material formulations, and fire-rated joint sealant systems. Single-source vulnerability in Gulf-based specialized insulation suppliers creates supply chain risk given regional logistics disruption exposure. Distribution runs through fabricator-direct relationships with major infrastructure contractors and build-operate-transfer consortiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's manufactured housing sector is transitioning from site-built legacy stock toward factory-certified modular systems, with phase-change material envelope technology displacing conventional insulation across North Field expansion timelines.
For Market Incumbents: Deepen backward integration into galvanized steel coil supply to insulate margin compression from raw material volatility on fixed-price camp contracts. Prioritize Qatar Civil Defence Authority welding certification pre-qualification to bypass inspection queue bottlenecks that extend project handover timelines. Invest in certified envelope simulation capabilities to defend premium positioning as QS mandates increasingly reference factory-certified thermal performance. For New Entrants and Emerging Players: Al Wakrah logistics hub operators represent an underserved buyer archetype seeking rapid-deployment fabrication capacity for southern industrial corridor demand. Target build-operate-transfer contracting opportunities in Lusail satellite districts where asset ownership retention models reduce employer administrative overhead. Pursue solar-integrated envelope demonstrations as a go-to-market angle for net-zero camp bidding categories. For Investors and Strategic Acquirers: Re-rating potential sits with climate-adaptive insulation specialists given Ministry of Municipality and Environment green building code tightening across the analysis window. Long-term viability favors fabricators with captive steel supply and QS-certified envelope capabilities serving recurring North Field infrastructure replacement cycles. Monitor Qatar General Organization for Standardization adoption timelines for updated GSO modular building standards as inflection indicators for import sourcing pattern shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Welding Certification Pre-Qualification | Qatar Civil Defence Authority fire-rated joint inspection bypass compresses project handover timelines for steel-framed assemblies. |
| Backward Integration into Steel Supply | Captive galvanized coil sourcing insulates fabrication margins from volatility on fixed-price North Field camp contracts. |
| Build-Operate-Transfer Contracting Expansion | Asset ownership retention models align with Lusail infrastructure developer preferences for housing-as-a-service delivery. |
| Solar-Integrated Envelope Development | Building-integrated photovoltaics convergence opens net-zero camp demonstration bidding categories under National Vision 2030 mandates. |
| Al Wakrah Fabrication Capacity Buildout | Port-adjacent greenfield positioning captures southern industrial corridor demand from Mesaieed contractor migration. |
Research Methodology
Multi-period observation of QS certification adoption rates, thermal envelope specification trends, and North Field expansion phasing anchored the trend analysis, supplemented by interviews with camp operators, infrastructure procurement directors, and Qatar General Organization for Standardization technical committee members. Secondary validation drew from Ministry of Municipality and Environment permit issuance databases, Ministry of Labour worker welfare compliance filings, and Gulf Standardization Organization harmonized code updates. Bottom-up project pipeline tracking and top-down construction sector forecasting enabled triangulation across demand estimation approaches.
Input-output matrices modeled deployment volumes against North Field gas expansion timelines, segmentation dimensions spanning product type, end user category, building material, and deployment model, plus regional corridor concentration within Qatar. CAGRs were derived from regression analysis of historical procurement patterns projected across the analysis window. Industry-specific forecast inputs incorporated Qatar Civil Defence Authority inspection queue durations and QS-GSO harmonized standard implementation schedules.
Revisions become necessary when steel price volatility exceeds historical bands, when Qatar General Organization for Standardization accelerates GSO standard adoption timelines, or when Ministry of Labour welfare mandate enforcement intensity shifts materially. Practitioners should monitor QS technical committee deliberations, North Field expansion contractor award announcements, and Al Wakrah port infrastructure development milestones for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
United Arab Emirates Residential Real Estate Market
Residential Real Estate Market
Real Estate Market
Residential Real Estate Market
South Korea Residential Real Estate Market
Residential Real Estate Market
UK Residential Real Estate Market
Residential Real Estate Market
Asia Pacific Manufactured Homes Market
Residential Real Estate Market
Global Manufactured Housing Market
Residential Real Estate Market
North America Tiny Homes Market
Residential Real Estate Market
Malaysia Residential Real Estate Market
Residential Real Estate Market
Online Home Rental Market
Residential Real Estate Market
Canada E-House Market
Residential Real Estate Market
Residential Real Estate Market
Residential Real Estate Market
Spain Residential Real Estate Market
Residential Real Estate Market
South Africa Residential Real Estate Market
Residential Real Estate Market
Latin America Residential Real Estate Market
Residential Real Estate Market
India Residential Construction Market
Residential Real Estate Market
Japan Manufactured Homes Market