
 Germany Protein Market | 2026-2036
Germany Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Protein Market Foresight
Subscription-based personalized nutrition programs is recalibrating how protein products reach German consumers. Cargill, Incorporated leverages its agricultural supply chain to secure consistent raw material flows for plant-based isolates. Beneo specializes in functional prebiotic-protein combinations that command premium positioning in digestive health segments. Kerry Group PLC sustains formulation partnerships with mid-sized German food manufacturers seeking clean-label protein enrichment.
Germany protein encompasses amino acid chains derived from dairy, plant, and microbial sources, typically processed through enzymatic hydrolysis or membrane filtration to achieve specific protein content thresholds between 80% and 95% dry weight, serving primarily as nutritional fortification in human food and animal feed systems. Whey protein dominates volume flows through established dairy processing infrastructure in Bavaria and Lower Saxony, while pea protein registers the fastest structural expansion as German food brands reformulate to reduce allergen exposure and meet EU sustainability disclosure requirements. Functional foods applications anchor margin pools due to longer development cycles and higher technical barriers compared to commodity sports powders.
BfR (German Federal Institute for Risk Assessment) and the EU EFSA novel food authorization pathway govern ingredient safety assessments, with REACH compliance adding layers of chemical transparency for imported protein concentrates. The EU Green Deal's carbon footprint labeling mandates are pushing German processors to document scope-three emissions across soy supply chains from South America and pea protein from Baltic origins. Stakeholders must monitor how the EU Deforestation Regulation reshapes sourcing economics for imported oilseed and dairy proteins before compliance deadlines tighten traceability requirements.
Market Dynamics
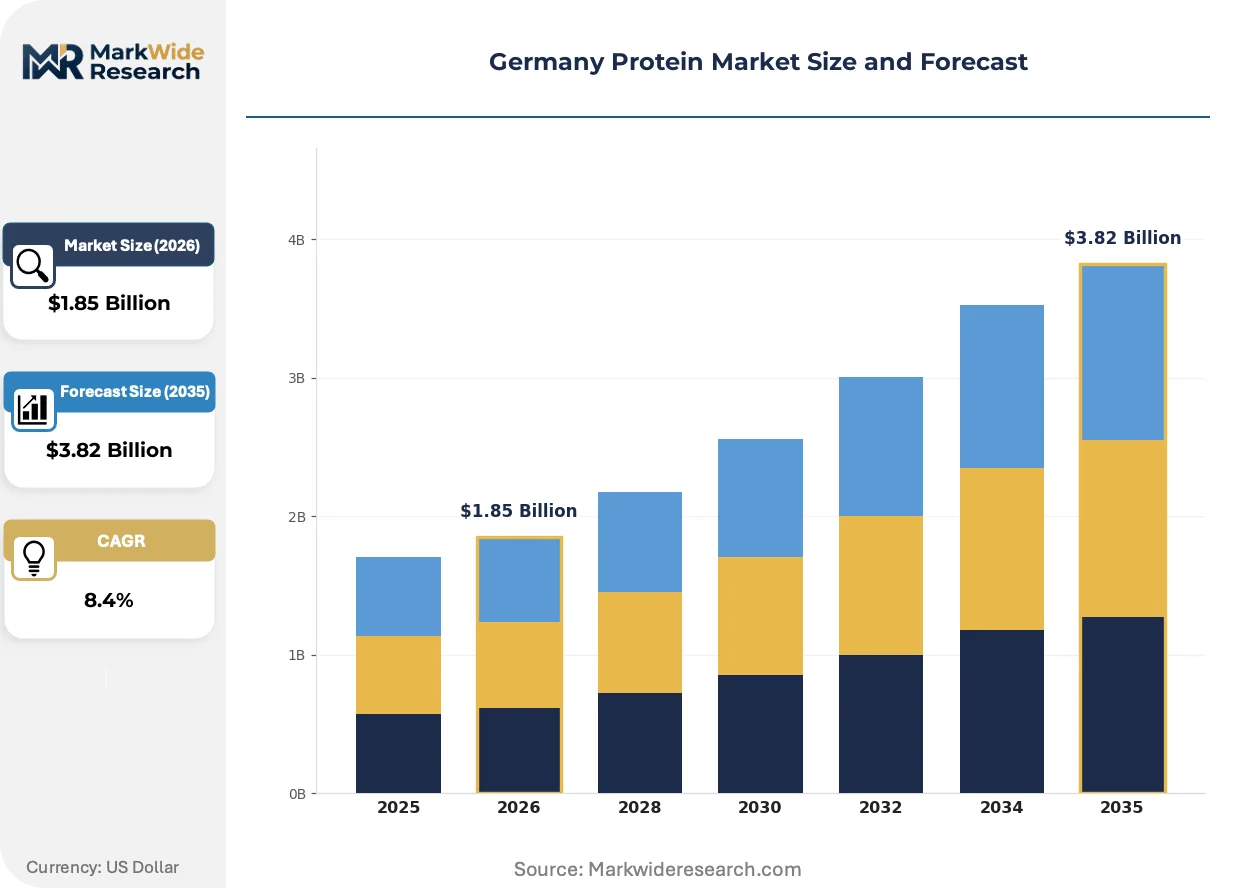
The EU Green Deal's Farm to Fork strategy is compressing sourcing timelines for German protein processors while simultaneously opening premium positioning for verified low-carbon ingredients. This regulatory pressure is restructuring supplier relationships and capital allocation across dairy, plant, and microbial protein streams.
Growth Catalysts
- EU Deforestation Regulation:Traceability mandates for imported soy and palm derivatives are accelerating demand for Baltic-region pea protein with documented chain-of-custody credentials.
- Sports nutrition formulators:Fitness enthusiasts in North Rhine-Westphalia and Bavaria are driving volume pull for whey protein isolates above 90% concentration.
- Enzymatic hydrolysis advances:Novel protease blends are unlocking functional protein fractions that previously degraded during processing, expanding application scope in senior nutrition.
Market Restraints
- Scope-three emission documentation:German processors face capital-intensive carbon accounting requirements for South American soy supply chains under EU Green Deal labeling rules.
- Dairy infrastructure lock-in:Bavarian whey concentration capacity creates path dependency that slows plant-protein pivot timelines for mid-scale manufacturers.
- Allergen cross-contamination protocols:Strict BfR guidance on milk-protein labeling adds formulation complexity and extends product development cycles for hybrid dairy-plant offerings.
Strategic Opportunities
- Lower Saxony biogas integration:Anaerobic digestion facilities adjacent to dairy processing plants offer captive energy supply for protein drying operations with verified carbon reductions.
- Prebiotic-protein combinations:Functional formulations targeting digestive health segments command margin premiums above commodity sports powders in pharmacy and specialist retail channels.
- Subscription-based personalized nutrition:Direct-to-consumer platforms in Berlin and Munich are capturing recurring revenue streams through algorithm-driven protein blending services.
Industry Challenges
- Novel food authorization timelines:EFSA pathway durations for microbial protein sources extend market entry schedules and consume R&D budgets without revenue offset.
- Clean-label formulation expertise:Shortage of food technologists capable of maintaining solubility and mouthfeel in reduced-additive protein systems constrains new product pipeline velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Protein Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein Protein, Soy Protein, Pea Protein, Rice Protein, Hemp Protein Application: Sports Nutrition, Weight Management, Functional Foods, Infant Nutrition, Animal Feed, Dietary Supplements End User: Athletes, Fitness Enthusiasts, Elderly Consumers, Infants, Pet Owners, Health-conscious Adults Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Pharmacies, Fitness Centers, Direct Sales |
| Companies Covered | Meggle Group, Archer Daniels Midland Company, Arla Foods amba, Kerry Group PLC, Cargill, Incorporated, DMK Group, Agrial Group, Beneo, FrieslandCampina Ingredients, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Protein Market Shifts & Advancements
Membrane filtration technology is consolidating production economics for high-purity protein fractions while regulatory disclosure requirements are reshaping competitive differentiation around verified supply chain data rather than functional claims alone.
Precision fermentation for whey protein identicals is consolidating capital flows toward microbial production platforms that bypass dairy agriculture entirely. Specialty ingredient divisions at German chemical conglomerates are piloting 10,000-liter bioreactor runs with protein titers approaching commercial thresholds. This technology is consolidating the traditional separation between dairy processing and industrial biotechnology, enabling new entrants to circumvent established Bavarian whey infrastructure.
REACH compliance for imported protein concentrates now requires full chemical characterization of processing aids and residual solvents, extending documentation burdens for South American soy isolates. German customs authorities are rejecting shipments lacking comprehensive safety data sheets aligned with ECHA guidance. Sports nutrition brands reformulating for EU market access are absorbing these compliance costs into premium pricing strategies targeting sustainability-conscious consumers.
Direct procurement from Baltic pea protein processors is displacing trader-mediated sourcing for mid-sized German food manufacturers seeking origin transparency. Brand technical teams are conducting on-site audits of Estonian and Latvian fractionation facilities to validate carbon footprint claims. This pattern concentrates most visibly among clean-label bakery and meat-alternative producers in Baden-Württemberg facing retailer sustainability scorecard requirements.
Germany Protein Market Segmentation
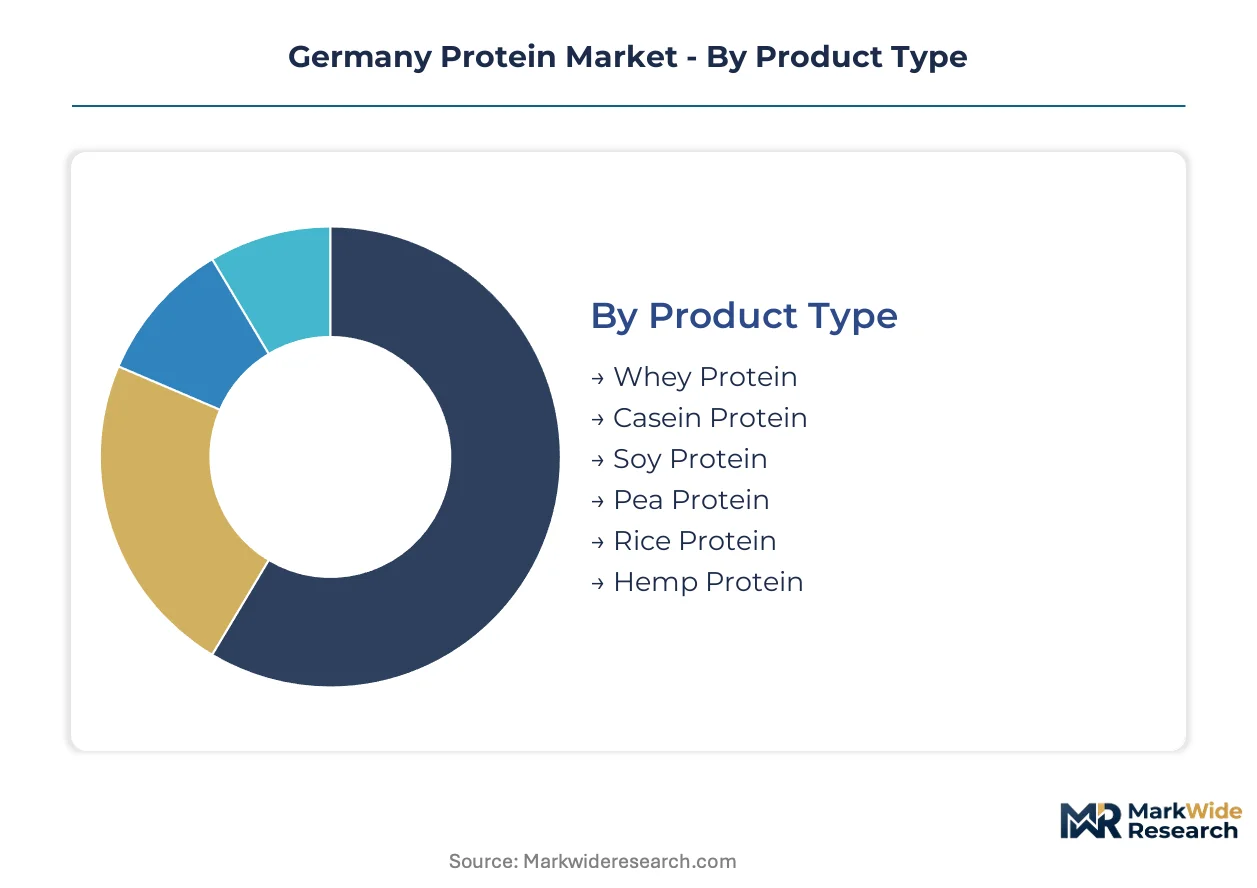
Protein segmentation in Germany reflects divergent technical requirements across dairy heritage infrastructure and emerging plant-based processing. Manufacturers configure production lines around protein concentration thresholds, solubility profiles, and allergen management protocols that vary sharply by end-use application.
Product Type:
Standardization dominates commodity grades while customization concentrates in premium isolates targeting specific functional specifications.
- Whey Protein:Concentrates and isolates derived from cheese manufacturing byproducts in Bavarian and Lower Saxony dairy clusters. Sports nutrition formulators in North Rhine-Westphalia specify protein content above 90% for premium positioning, though dairy infrastructure lock-in slows plant-protein pivot timelines for mid-scale processors.
- Pea Protein:Fractionated isolates from Baltic-region yellow peas with documented chain-of-custody credentials meeting EU Deforestation Regulation requirements. Clean-label bakery and meat-alternative producers in Baden-Württemberg drive demand as retailer sustainability scorecards tighten sourcing transparency.
- Casein Protein:Micellar structures from skim milk processing deliver slow-release amino acid profiles for overnight recovery formulations.
- Soy Protein:Isolates and concentrates face scope-three emission documentation burdens under EU Green Deal labeling rules for South American supply chains.
- Rice Protein:Hypoallergenic positioning serves formulation teams eliminating major allergens from senior nutrition products.
- Hemp Protein:Fiber-rich whole-seed meals appeal to organic-certified brands in Berlin's direct-to-consumer subscription channels.
Leading the category by volume: Whey Protein. Growing fastest: Pea Protein.
Application:
Margin structures stratify sharply between commodity sports powders and functional foods requiring extended development cycles.
- Sports Nutrition:Protein bars, ready-to-drink beverages, and powdered supplements targeting post-workout recovery windows. Fitness enthusiasts in Bavaria and North Rhine-Westphalia pull volume for whey isolates above 90% concentration, with enzymatic hydrolysis advances unlocking functional fractions for senior nutrition extensions.
- Functional Foods:Protein-enriched bakery, dairy alternatives, and meat analogues with clean-label positioning. Pharmacy and specialist retail channels command margin premiums for prebiotic-protein combinations targeting digestive health segments.
- Weight Management:Meal replacement formulations emphasizing satiety signaling through specific amino acid ratios.
- Infant Nutrition:Hydrolyzed proteins meeting strict BfR guidance on allergen labeling and compositional requirements.
- Animal Feed:Compound feed proteins for poultry and swine operations facing sustainability disclosure pressures.
- Dietary Supplements:Capsule and tablet formats targeting health-conscious adults with targeted micronutrient co-formulations.
Widest margin pool: Functional Foods. Steepest volume expansion: Sports Nutrition.
End User:
Usage frequency and dosage precision separate professional athletic applications from casual wellness consumption.
- Athletes:Competitive and professional sports participants requiring batch-tested products with anti-doping certification. Algorithm-driven protein blending services through Berlin and Munich direct-to-consumer platforms capture recurring revenue with personalized amino acid profiling.
- Fitness Enthusiasts:Regular gym attendees prioritizing convenience and taste over clinical precision in protein supplementation choices.
- Elderly Consumers:Sarcopenia prevention drives demand for leucine-enriched formulations with improved solubility in ambient beverages.
- Infants:Specialized hydrolysates for allergy management and premature nutrition protocols.
- Pet Owners:Premium companion animal nutrition incorporating human-grade protein sourcing claims.
- Health-conscious Adults:General wellness positioning emphasizing digestive tolerance and clean-label ingredient decks.
Highest per-capita consumption: Athletes. Fastest demographic expansion: Elderly Consumers.
Distribution Channel:
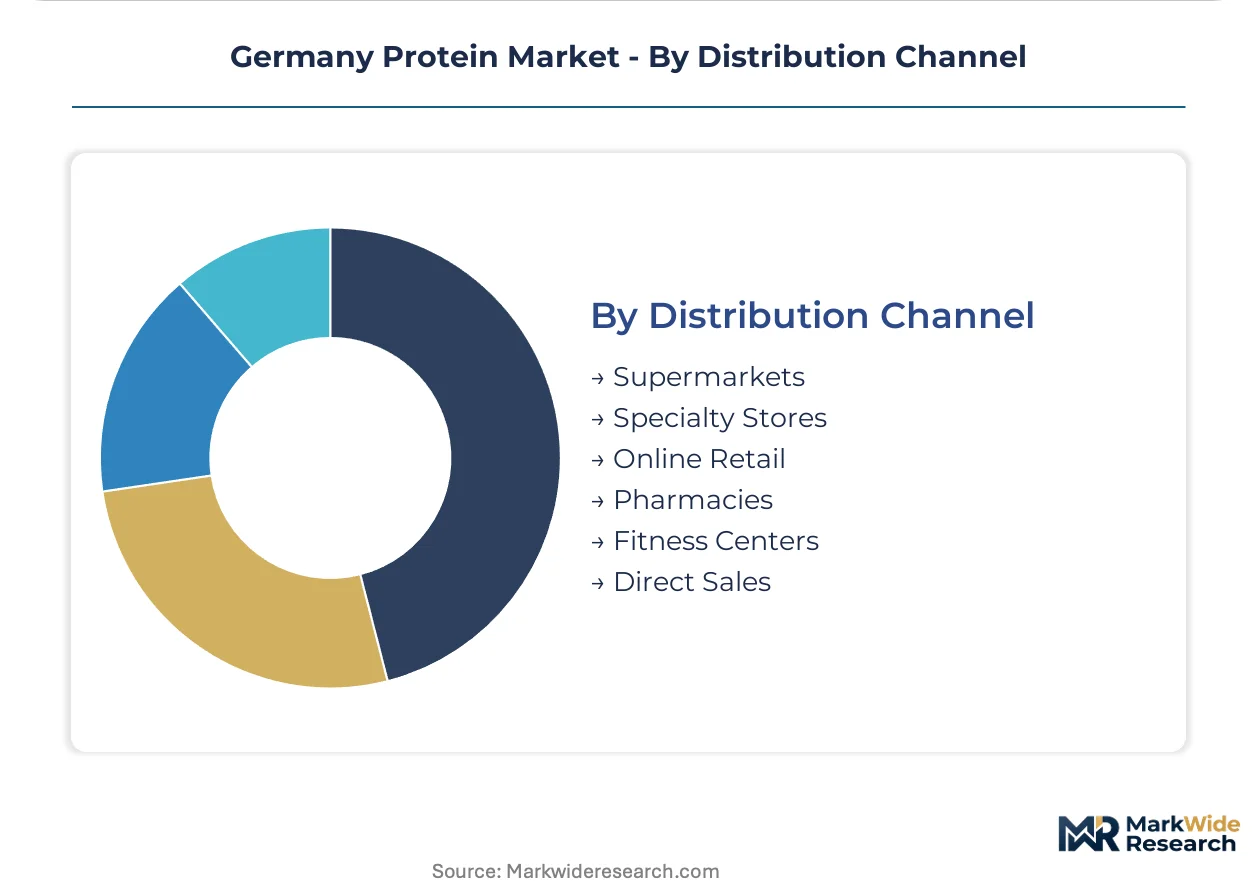
Channel selection determines margin retention versus reach tradeoffs, with digital platforms eroding traditional pharmacy dominance in premium segments.
- Specialty Stores:Dedicated sports nutrition retailers with trained staff and sampling programs. Technical consultation capabilities support premium whey isolate sales above 90% concentration, while on-site audits of Baltic pea protein facilities validate carbon footprint claims for sustainability-conscious consumers.
- Online Retail:Direct-to-consumer platforms with subscription mechanics and algorithm-driven personalization. Berlin and Munich-based operators capture recurring revenue streams through protein blending services with flexible delivery cadences.
- Supermarkets:Mass-market penetration for commodity concentrates with private-label positioning.
- Pharmacies:Clinical credibility for senior nutrition and digestive health formulations with prebiotic combinations.
- Fitness Centers:Impulse purchase placement targeting immediate post-workout consumption occasions.
- Direct Sales:Multi-level marketing networks with personalized coaching attachments.
Deepest market penetration: Specialty Stores. Fastest channel expansion: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German protein production concentrates in Bavarian and Lower Saxony dairy clusters while consumption spreads across industrialized western states. This geographic mismatch creates logistics intensity for plant-based alternatives seeking to bypass established whey infrastructure.
North Rhine-Westphalia
Fitness culture in Cologne and Düsseldorf metro areas drives volume consumption of whey protein isolates. The state's chemical industry heritage supplies enzymatic processing expertise to sports nutrition formulators. Ruhr Valley logistics hubs coordinate distribution of Baltic-sourced pea protein to domestic manufacturers.
Bavaria
Dairy processing infrastructure around Munich anchors whey protein concentrate production for export markets. The BfR maintains headquarters here, accelerating regulatory consultation access for local processors. Precision fermentation startups in the Munich biotech corridor pilot microbial protein alternatives to traditional dairy streams.
Baden-Württemberg
Clean-label bakery and meat-alternative producers in Stuttgart cluster face retailer sustainability scorecard pressures. Direct procurement teams conduct on-site audits of Estonian pea protein facilities to validate carbon claims. The state's automotive supplier culture transfers quality systems expertise to food ingredient verification protocols.
Lower Saxony
Anaerobic digestion facilities adjacent to dairy plants offer captive biogas supply for protein drying operations. Oldenburg and Osnabrück processing zones integrate agricultural waste streams into circular production models. The region's feed industry heritage supports technical knowledge for animal protein applications transitioning to human nutrition.
Berlin-Brandenburg
Direct-to-consumer subscription platforms in Berlin capture recurring revenue through algorithm-driven protein personalization. The capital's venture capital concentration funds novel food startups navigating EFSA authorization pathways. Brandenburg's organic farming belt supplies hemp protein raw materials for premium positioning in urban wellness channels.
Germany Protein Market Competitive Landscape
Capital-heavy dairy processors compete with asset-light ingredient designers across the German protein landscape. Bavarian whey concentration capacity creates structural advantages for established operators while constraining pivot timelines for plant-based expansion. Three archetypes dominate: integrated dairy conglomerates with captive raw material access, specialized functional ingredient houses with formulation partnerships, and agricultural traders securing supply chain transparency for sustainability-conscious brands. Competitive moves concentrate on backward integration into Baltic pea protein sourcing and enzymatic hydrolysis capability acquisition.
Among agricultural supply chain operators, Cargill, Incorporated and Archer Daniels Midland Company anchor the commodity sourcing tier with documented chain-of-custody systems for imported oilseeds. Beneo exemplifies the functional specialization archetype through its prebiotic-protein combination portfolio targeting digestive health segments. These three represent distinct competitive positions: trader-mediated volume, vertically integrated dairy heritage, and ingredient innovation focus.
| Leading Market Players |
|---|
| Meggle Group |
| Archer Daniels Midland Company |
| Arla Foods amba |
| Kerry Group PLC |
| Cargill, Incorporated |
| DMK Group |
| Agrial Group |
| Beneo |
| FrieslandCampina Ingredients |
| Others |
Supply & Pricing Matrix
Sports nutrition formulators in North Rhine-Westphalia and Bavaria concentrate purchasing power for whey protein isolates above 90% concentration, anchoring contract-based long-term offtake agreements that lock in volume commitments against spot-market volatility. This buyer concentration enables processors to enforce tiered pricing separating pharmaceutical-grade isolates from standard sports nutrition grades, with EU Green Deal carbon documentation costs absorbed into premium positioning for sustainability-verified supply chains.
Pricing Analysis
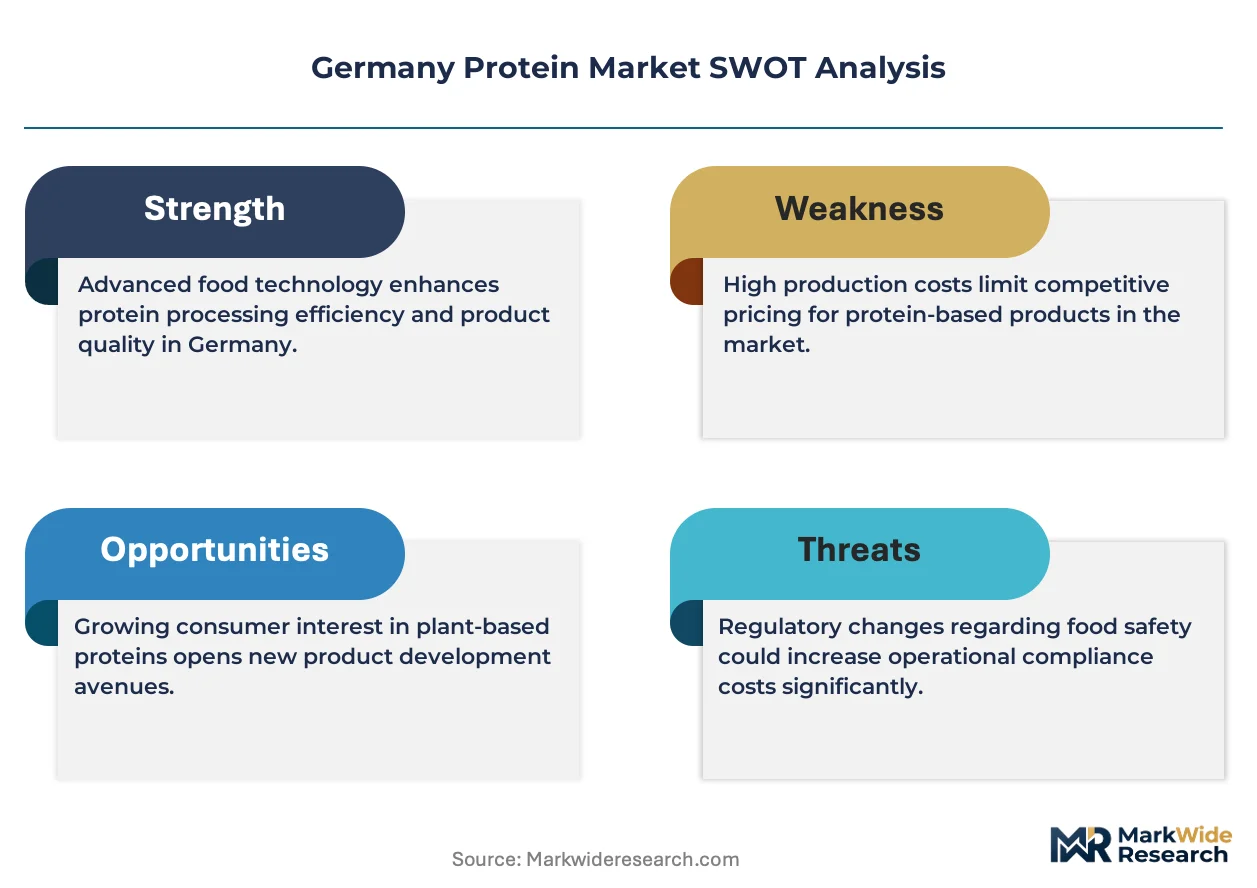
Cost-down pressure on standard whey concentrates accelerates because Bavarian dairy infrastructure lock-in constrains mid-scale manufacturers from pivoting to lower-carbon plant alternatives. Three-tier pricing structure across premium isolates, standard concentrates, and economy-grade feed proteins reflects differentiation by certification level — EFSA novel food authorization and BfR allergen compliance command substantial premia. Price erosion runs through commodity soy isolates as scope-three emission documentation burdens compound South American sourcing costs. Fitness enthusiasts demonstrate lowest price sensitivity for batch-tested, anti-doping certified products, while mass-market supermarket buyers drive hardest bargain on private-label concentrates.
Supply Chain Analysis
EU Deforestation Regulation traceability mandates are reshaping sourcing patterns toward Baltic-region pea protein processors with documented chain-of-custody credentials. German supply chains draw from Estonian and Latvian fractionation facilities, Bavarian dairy clusters, and South American soy crushing operations. Raw material dependencies center on yellow pea crops, cheese whey streams, and oilseed meals. Single-source vulnerability concentrates in South American soy isolates facing customs rejection for incomplete REACH documentation. Distribution runs through Ruhr Valley logistics hubs coordinating rail and road networks to Baden-Württemberg clean-label manufacturers and Berlin direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German protein market consolidation is accelerating as EU Deforestation Regulation compliance costs and carbon accounting requirements force sub-scale traders and non-integrated processors toward exit or acquisition.
For Market Incumbents: Hedge against dairy infrastructure obsolescence by acquiring enzymatic hydrolysis capabilities and Baltic pea protein sourcing relationships before precision fermentation startups achieve commercial scale. Bavarian whey concentration capacity remains defensible only if paired with verified low-carbon energy supply through Lower Saxony biogas integration. Reinforcing formulation partnerships with mid-sized manufacturers provides channel control against direct-to-consumer subscription platforms eroding traditional distribution. For New Entrants and Emerging Players: Direct-to-consumer algorithm-driven personalization platforms offer the most penetrable entry vector, with Berlin and Munich metro areas showing recurring revenue traction for flexible subscription cadences. Target senior nutrition applications where enzymatic hydrolysis advances unlock functional protein fractions with limited incumbent specialization. White-space exists in prebiotic-protein combinations for pharmacy channels, where Beneo's dominance leaves margin room for challengers with novel synbiotic formulations. For Investors and Strategic Acquirers: The window for entry favors asset-light ingredient designers with formulation expertise over capital-heavy dairy processors locked into path-dependent infrastructure. Acquisition targets should demonstrate established EFSA novel food authorization navigation capabilities and documented Baltic supply chain audits. Watch for inflection when precision fermentation protein titers breach commercial thresholds, collapsing the traditional separation between dairy processing and industrial biotechnology.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Baltic Pea Protein Sourcing | Direct procurement from Estonian fractionation facilities satisfies EU Deforestation Regulation chain-of-custody requirements for Baden-Württemberg manufacturers. |
| Enzymatic Hydrolysis Capability Acquisition | Novel protease blends unlock functional protein fractions for senior nutrition extensions beyond commodity sports powder positioning. |
| Biogas Integration for Protein Drying Operations | Lower Saxony anaerobic digestion facilities adjacent to dairy plants offer verified carbon reductions for EU Green Deal labeling compliance. |
| Direct-to-Consumer Platform Launch | Berlin and Munich subscription mechanics capture recurring revenue through algorithm-driven protein blending services with flexible delivery. |
| Prebiotic-Protein Combination Development | Functional formulations targeting digestive health segments command margin premiums above commodity sports powders in pharmacy channels. |
Research Methodology
Document review covered BfR guidance documents, EFSA novel food authorization records, EU Green Deal Farm to Fork strategy implementation reports, and REACH compliance databases, complemented by interviews with sports nutrition formulators, dairy processing plant managers, Baltic-region pea protein procurement leads, and pharmacy channel category buyers. Secondary validation drew from customs trade data, dairy industry association statistics, and sustainability certification body disclosures. Bottom-up volume modeling triangulated against top-down market sizing from protein concentration capacity assessments across Bavarian and Lower Saxony processing clusters.
Cross-referencing historical pricing patterns from whey and plant protein commodity exchanges against panel input from procurement directors established the analytical framework across the analysis window. Segmentation dimensions modeled include protein type, application category, end-user demographic, and distribution channel, with additional granularity on EU regulatory compliance tier. CAGRs were derived from trend extrapolation of volume flows through established dairy infrastructure versus structural expansion rates for Baltic-sourced plant alternatives. Forecast inputs incorporated enzymatic processing technology maturation curves and precision fermentation pilot scale-up timelines.
The model holds under stable EU Deforestation Regulation implementation timelines and continued EFSA authorization pathway durations; deviation in novel food approval acceleration or carbon border adjustment mechanism expansion would shift competitive positioning toward microbial protein platforms. Forecasts reflect documented assumptions on Baltic crop yields, Bavarian whey stream availability, and biogas facility commissioning rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Yeast Flakes Market
Ingredients
Baking Ingredients Market
Ingredients
Bouillon Cubes Market
Ingredients
North America Vegetable Oils Market
Ingredients
Cacao Bean Market
Ingredients
Edible Peanut Oil and Soybean Oil Market
Ingredients
Europe Malt Extract Market
Ingredients
Europe Alcohol Ingredients Market
Ingredients
Precision Fermentation Ingredient Supplier Market
Ingredients
Global Antimicrobial (Enzymatic) Protein Hydrolysates Market
Ingredients
Mediterranean Marine Ingredients for Pet Health Market
Ingredients
Organic Edible Oil Market
Ingredients
North America Soy Protein Concentrate Market
Ingredients
Bangladesh Mustard Oil Market
Ingredients
Fruit Pectin Market
Ingredients
Pulses Ingredients Market