
 Yeast Flakes Market | 2026-2036
Yeast Flakes Market Size, Share, and Industry Trends Forecast 2026-2036
Yeast Flakes Market Analysis
Nutritional yeast is repositioning conventional savory flavoring economics across plant-based food manufacturing. Lesaffre leverages its vertically integrated fermentation infrastructure to supply industrial-scale bakeries and ingredient blenders across Europe. Angel Yeast anchors Asia-Pacific production capacity with specialized strains for nutritional fortification. Bob's Red Mill Natural Foods differentiates through certified gluten-free and non-GMO positioning in North American retail channels.
Yeast flakes consist of deactivated Saccharomyces cerevisiae cells dried into thin, flaky particles containing complete protein profiles, B-vitamin complexes, and naturally occurring glutamates that deliver savory flavor without sodium. Manufacturers cultivate yeast on molasses or sugar beet substrates before pasteurization, drum-drying, and flaking to preserve nutritional density for food and supplement applications. Nutritional yeast flakes command premium positioning within the product type landscape due to fortification-grade specifications and vegan-label alignment, while dry flakes dominate the form category through extended shelf stability and bulk handling efficiency. Dietary supplements represent the fastest-expanding application segment as protein-conscious consumers seek whole-food micronutrient sources.
FDA oversight of nutritional content claims and EFSA health claim substantiation requirements are elevating analytical documentation burdens for yeast flake exporters entering regulated markets. The USDA organic certification and EU organic regulation shape premium tier access and pricing power for certified producers. Stakeholders must monitor evolving fortification thresholds and clean-label audit standards as procurement criteria tighten across institutional foodservice and direct-to-consumer channels.
Market Dynamics
Plant-based food manufacturers are forcing ingredient specification upgrades across yeast flake supply chains as dairy-replacement demand intensifies and fortification-grade certifications become mandatory for retail placement.
Growth Catalysts
- EFSA health claim substantiation:European regulators tightened analytical documentation requirements for B-vitamin fortification claims, pushing manufacturers toward certified production lines that command premium pricing in export markets.
- Sugar beet substrate cultivation:Molasses alternatives from Central European agricultural processing are expanding raw material sourcing flexibility and reducing import dependency for fermentation feedstock.
- Vegan cheese formulation:Nutritional yeast flakes are displacing sodium-heavy savory enhancers in dairy-free sauce and spread applications across North American and European plant-based food manufacturing.
Market Restraints
- Molasses price volatility:Cane sugar harvest fluctuations in Brazil and India directly compress fermentation input cost predictability for yeast cultivators operating on thin margin contracts.
- Drum-drying energy intensity:Natural gas and electricity input costs for thermal dehydration stages create persistent cost pressure against spray-dried alternatives in bulk ingredient procurement.
- Saccharomyces cerevisiae strain IP concentration:Proprietary nutritional fortification strains remain concentrated among legacy fermentation houses, limiting new entrant access to high-B-vitamin titers.
Strategic Opportunities
- USDA organic certification pipeline:Clean-label retail channels in the United States are expanding shelf space allocation for certified organic yeast flakes, creating margin expansion potential for compliant producers.
- Sports nutrition powder blending:Complete protein profiles and umami masking properties are opening formulation contracts with whey-alternative protein powder manufacturers seeking whole-food micronutrient sources.
- Direct-to-consumer subscription channels:Specialty health-food e-commerce platforms are bypassing conventional retail distribution markups for bulk flake formats targeting home vegan cooking enthusiasts.
Industry Challenges
- FDA nutritional content claim documentation:Substantiation requirements for B12 and folate fortification claims are extending product launch timelines and elevating analytical testing expenditure for export-bound shipments.
- Gluten-free certification audit complexity:Cross-contamination protocols in shared fermentation facilities require segregated production runs and dedicated equipment cleaning validation that compresses batch scheduling efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yeast Flakes Market |
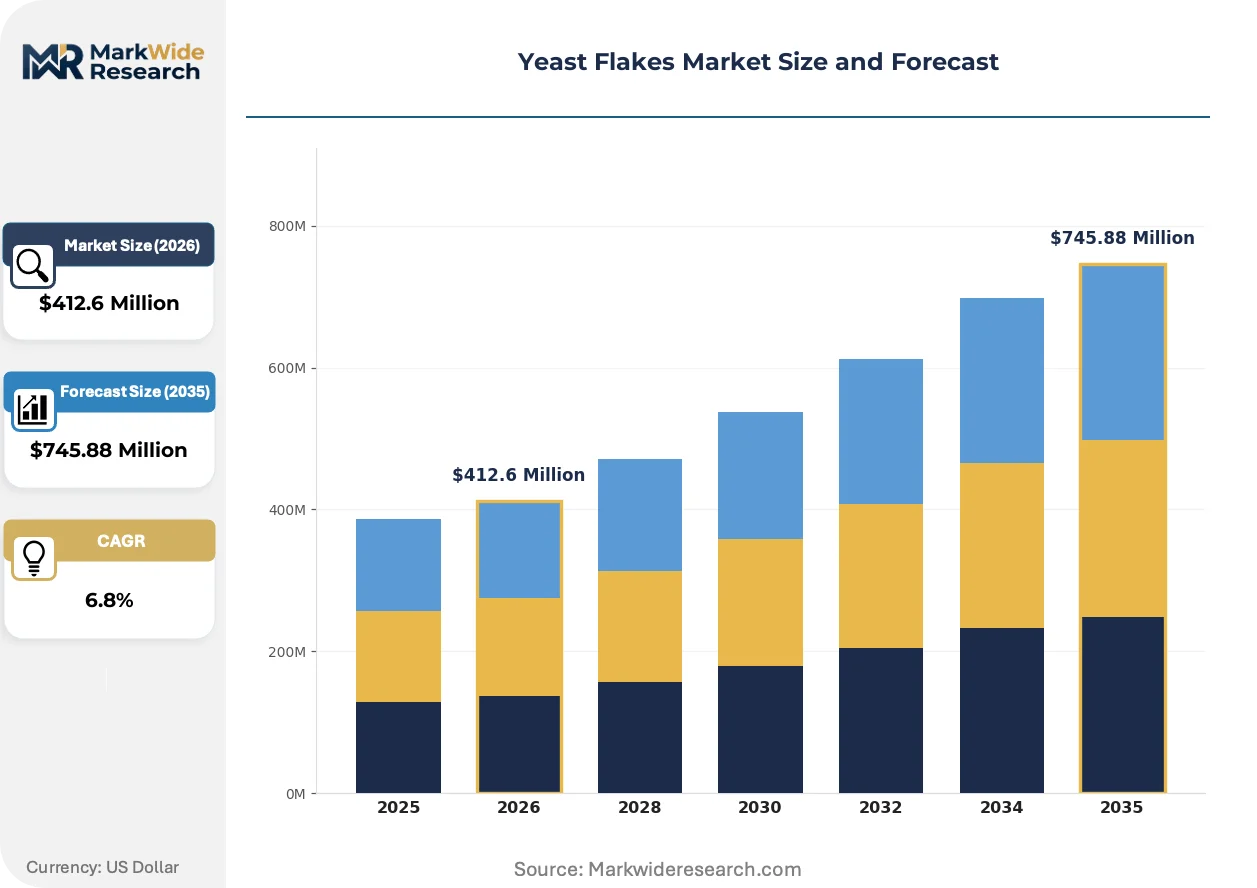
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baker's Yeast, Brewer's Yeast, Nutritional Yeast, Instant Yeast Application: Baking, Brewing, Dietary Supplements, Animal Feed Form: Dry Flakes, Granules, Powder, Liquid Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Wholesale |
| Companies Covered | Lesaffre, Now Foods, Anthony's Goods, Bob's Red Mill Natural Foods, Bragg Live Food Products, Hoosier Hill Farm, Urban Platter, Sari Foods, Angel Yeast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yeast Flakes Market Emerging Trajectories
Yeast flake processing is converging with precision fermentation analytics and clean-label certification protocols as manufacturers compete for premium positioning in ingredient supply chains.
Precision fermentation monitoring systems are unifying real-time biomass density tracking with downstream drying optimization. Industrial-scale bakeries and ingredient blenders in Germany and the Netherlands are adopting these sensor arrays to reduce batch-to-batch nutritional variance. This technology convergence is compressing specification rejection rates and enabling just-in-time fortification adjustments before drum-drying commences.
EFSA health claim substantiation requirements are elevating third-party analytical documentation burdens for B-vitamin fortification claims. Exporters entering European markets must now maintain chain-of-custody records from substrate sourcing through final flaking. Nutritional yeast flake categories face the steepest compliance ramps as fortification-grade specifications attract heightened regulatory scrutiny.
Clean-label procurement preferences are rotating demand toward certified organic and non-GMO verified formats in North American retail channels. Institutional foodservice buyers are displacing conventional commodity flakes with identity-preserved supply contracts that specify substrate origin and strain provenance. This specification tightening is most visible in United States natural food retail and direct-to-consumer subscription segments where certification logos drive shelf placement decisions.
Yeast Flakes Market Segmentation
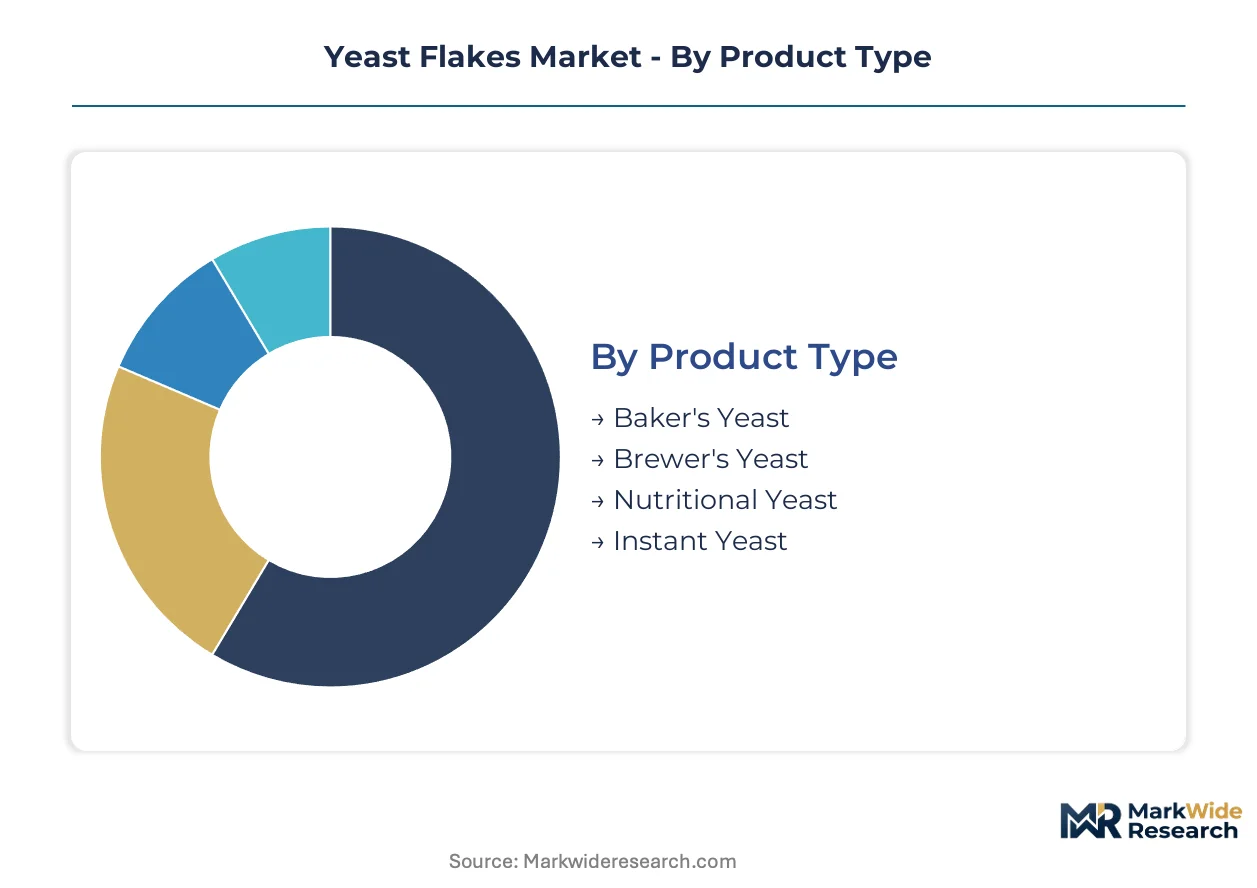
Yeast flake segmentation reflects divergent technical specifications across fermentation substrates, downstream processing intensity, and end-use fortification requirements. Manufacturers configure production lines around strain selection and drying protocols that align with distinct customer procurement criteria.
Product Type:
Standardization dominates commodity grades while customization concentrates in fortification-grade strains with proprietary B-vitamin titers.
- Nutritional Yeast:Deactivated Saccharomyces cerevisiae cultivated on molasses or sugar beet substrates delivers complete protein profiles and B-complex fortification. Demand concentrates in German health-food retail and North American vegan cheese manufacturing where EFSA and FDA substantiation requirements elevate analytical documentation burdens for export-bound shipments.
- Brewer's Yeast:Byproduct of beer fermentation retains bitter hop residues that limit food-grade applications but command dedicated supplement positioning. Germany's traditional brewing heritage anchors supply concentration, with expanding extraction into animal feed formulations across Central European agricultural processing.
- Baker's Yeast:Live active cultures for leavening applications require refrigerated supply chains distinct from deactivated flake processing. Industrial-scale bakeries in France and Italy drive procurement volume for fresh and compressed formats.
- Instant Yeast:Rapid-rehydration granules displace conventional active dry formats in high-throughput commercial baking operations. Shelf-stable packaging extends distribution reach into institutional foodservice channels with limited cold storage infrastructure.
Most installed capacity flows through Brewer's Yeast. Expansion is steepest in Nutritional Yeast.
Application:
Cost tier stratification separates commodity feed inputs from premium human-grade fortification specifications with full chain-of-custody documentation.
- Dietary Supplements:Protein-conscious consumers seeking whole-food micronutrient sources propel formulation contracts with whey-alternative powder manufacturers. Sports nutrition blending in the United States and United Kingdom drives specification upgrades for umami masking and complete amino acid profiles.
- Baking:Leavening function depends on live cell viability incompatible with deactivated flake formats, creating distinct procurement channels. French and Italian artisan bakeries sustain demand for fresh yeast despite flake format convenience advantages.
- Brewing:Primary fermentation stage consumes live yeast cultures with flake derivatives limited to specialty brewing adjuncts. German and Czech Republic brewing clusters generate byproduct feedstock for downstream nutritional extraction.
- Animal Feed:Protein supplementation for livestock and aquaculture operates on thin margin contracts with minimal fortification requirements. Molasses price volatility from Brazilian and Indian cane sugar harvests directly compresses input cost predictability for this price-sensitive segment.
Volume concentration sits in Animal Feed. Value expansion is climbing the fastest in Dietary Supplements.
Form:
Customer type segmentation distinguishes bulk ingredient procurement efficiency from retail-ready convenience formats.
- Dry Flakes:Drum-dried thin particles preserve nutritional density through extended shelf stability and bulk handling efficiency. Industrial ingredient blenders and institutional foodservice buyers in Germany and the Netherlands specify this format for vegan cheese and sauce applications.
- Powder:Finely milled particles integrate into protein powder matrices and beverage premixes where dissolution uniformity matters. Sports nutrition manufacturers in the United States specify powder for whey-alternative formulations with whole-food positioning.
- Granules:Intermediate particle size bridges rehydration speed with flowability for automated dispensing equipment. Commercial bakeries favor this format for scaling consistency across batch operations.
- Liquid:Live cultures for immediate-use applications require refrigerated logistics that exclude this format from flake market boundaries. Limited relevance to deactivated product categories.
Procurement volume concentrates in Dry Flakes. Premium positioning is gaining share fastest in Powder.
Distribution Channel:
Geography shapes channel selection with urban health-food retail density determining direct-to-consumer penetration potential.
- Health Food Stores:Certified organic and non-GMO verified formats command shelf space allocation based on clean-label audit standards. German and United States natural food retail clusters drive placement decisions for fortification-grade nutritional yeast.
- Online Retail:Subscription channels bypass conventional distribution markups for bulk flake formats targeting home vegan cooking enthusiasts. Direct-to-consumer platforms in the United States and United Kingdom expand reach into underpenetrated postal code regions.
- Supermarkets:Mass-market placement requires price competitiveness that commodity grades satisfy through scale economies. Conventional retail consolidation in France and Spain limits specialty format penetration.
- Wholesale:Bulk procurement by industrial bakeries and ingredient blenders operates on contract pricing with specification lock-ins. German and Dutch procurement offices coordinate just-in-time delivery schedules for fermentation-derived inputs.
Transaction volume flows predominantly through Wholesale. Channel expansion is accelerating most quickly in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's brewing heritage and health-food retail density anchor the European yeast flakes market, with fermentation clusters in Bavaria and North Rhine-Westphalia driving both supply concentration and demand sophistication.
United States
Plant-based cheese manufacturers in California and New York Metro drive nutritional yeast procurement for vegan sauce formulations. FDA substantiation requirements for B12 fortification claims extend product launch timelines for exporters. Los Angeles and Brooklyn health-food retail clusters command premium shelf placement for certified organic formats.
Germany
Traditional brewing infrastructure in Bavaria generates brewer's yeast byproduct streams for downstream nutritional extraction. EFSA health claim documentation mandates elevate analytical burdens for fortification-grade exports. Hamburg and Berlin health-food retail channels concentrate demand for clean-label nutritional yeast flakes.
China
Industrial-scale fermentation capacity in Shandong and Jiangsu provinces supplies bulk nutritional yeast for domestic supplement manufacturing. SAMR food fortification standards shape product specifications for human-grade applications. Zhengzhou-based ingredient blenders process drum-dried flakes for protein powder integration.
United Kingdom
Sports nutrition formulators in London and Manchester specify yeast flake powder for whey-alternative protein matrices. FSA labeling enforcement for vegan claims tightens procurement documentation requirements. Direct-to-consumer subscription channels headquartered in Greater London bypass conventional retail distribution.
India
Bakery and biscuit manufacturers in Maharashtra and Gujarat procure instant yeast granules for commercial leavening applications. FSSAI fortification guidelines for micronutrient enrichment influence nutritional yeast import specifications. Mumbai health-food retail expansion creates emerging demand for premium flake formats.
Yeast Flakes Market Vendor Landscape
Capacity expansion dominates the current landscape as fermentation houses scale drum-drying infrastructure to capture plant-based ingredient demand. The vendor base stratifies across three tiers: legacy brewing conglomerates with captive yeast streams, specialized nutritional yeast cultivators with proprietary fortification strains, and private-label blenders serving retail channels. Strategic archetypes include upstream substrate controllers, downstream brand builders, and contract manufacturing specialists. M&A activity concentrates on organic certification assets and precision fermentation analytics capabilities.
Among legacy fermentation specialists, Lesaffre exemplifies the integrated brewing-to-nutrition supply model. Angel Yeast anchors Asia-Pacific production capacity with Chinese fermentation infrastructure. Bob's Red Mill Natural Foods occupies the clean-label retail tier with certified gluten-free positioning in North American natural food channels.
| Leading Market Players |
|---|
| Lesaffre |
| Now Foods |
| Anthony's Goods |
| Bob's Red Mill Natural Foods |
| Bragg Live Food Products |
| Hoosier Hill Farm |
| Urban Platter |
| Sari Foods |
| Angel Yeast |
| Others |
Supply Flow & Price Mechanics
EFSA fortification-grade certification requirements are compressing supplier qualification timelines and forcing buyers toward contract-based procurement with premium-tier pricing for documented chain-of-custody. This specification tightening elevates analytical documentation costs that pass through to end-product pricing.
Pricing Analysis
Molasses and sugar beet substrate cost pass-through dominates contract negotiations between fermentation houses and industrial ingredient blenders. Three-tier pricing structure across fortification-grade, food-grade, and feed-grade levels separates nutritional yeast with B-vitamin titers from commodity brewer's yeast derivatives. Pricing pressure stems from drum-drying energy intensity as natural gas input costs compress margin structures against spray-dried alternatives. Animal feed buyers exhibit highest price sensitivity due to thin margin contracts, while dietary supplement manufacturers absorb premium positioning for certified organic formats.
Supply Chain Analysis
Dual-sourcing mandates from German and Dutch industrial bakeries require qualification of multiple fermentation suppliers to mitigate batch-to-batch nutritional variance risks. Supply concentrates in Germany, China, and France where brewing heritage and industrial-scale fermentation infrastructure anchor production gravity. Raw material dependencies center on Brazilian and Indian cane sugar harvests for molasses substrates, Central European sugar beet processing, and proprietary Saccharomyces cerevisiae strain inventories. Single-source vulnerability persists for high-B-vitamin fortification strains held by legacy fermentation houses. Distribution runs through wholesale contract channels with specification lock-ins, though direct-to-consumer subscription platforms are bypassing conventional markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The yeast flakes market compounds steadily as plant-based food manufacturing mandates displace dairy-derived umami ingredients with nutritional fortification alternatives.
For Market Incumbents: Deploy precision fermentation monitoring systems to reduce batch-to-batch specification variance and defend against emerging contract manufacturers with sensor-based quality assurance. Incumbent fermentation houses should deepen backward integration into sugar beet substrate cultivation across Central European agricultural processing regions. Certification investment in USDA organic and EU organic regulation compliance creates shelf space lock-in against private-label blenders entering clean-label retail channels. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms represent the most penetrable channel expansion vector for bulk flake formats targeting home vegan cooking enthusiasts. White-space concentration sits in sports nutrition powder blending contracts with whey-alternative manufacturers seeking whole-food micronutrient sources. New entrants should pursue sports nutrition formulators in the United States and United Kingdom with umami masking and complete amino acid profile specifications as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with organic certification asset owners positioned for clean-label retail channel expansion. The yeast flakes market offers viable long-term compounder characteristics through sustained plant-based food manufacturing demand and regulatory fortification mandates. Acquisition targets should emphasize precision fermentation analytics capabilities and established EFSA documentation protocols. The signal to watch is FDA substantiation requirement tightening for B12 fortification claims that would elevate analytical documentation barriers and consolidate supplier bases toward compliant incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Analytics Investment | Real-time biomass monitoring reduces specification rejection rates for EFSA-compliant exports. |
| Organic Certification Pipeline Expansion | USDA organic certification unlocks premium shelf placement in Los Angeles and Brooklyn retail clusters. |
| Backward Integration into Substrate Cultivation | Sugar beet sourcing from Central European processing reduces Brazilian molasses import dependency. |
| Sports Nutrition Formulation Partnerships | Whey-alternative protein powder contracts leverage complete amino acid profiles for United States manufacturers. |
| Direct-to-Consumer Channel Development | Subscription platforms bypass wholesale markups for bulk flake formats in United Kingdom postal regions. |
Methodological Framework
Multiple input streams — fermentation facility technical directors, health-food retail category buyers, sports nutrition formulation scientists, and regulatory affairs specialists — were reconciled with secondary validation from EFSA guidance documents, FDA substantiation databases, and customs trade records. Bottom-up production capacity assessments across German, Chinese, and French fermentation clusters were triangulated against top-down demand modeling from plant-based food manufacturing procurement data.
Historical shipment volumes were cross-referenced against panel input from ingredient blender procurement offices to anchor growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled include product type tier, application end-use, form specification, and distribution channel intensity. CAGRs were derived from production capacity expansion schedules and end-use demand elasticity coefficients, with molasses price volatility and drum-drying energy cost trajectories incorporated as scenario inputs.
Revisions become necessary when EFSA fortification thresholds tighten, FDA B12 claim documentation requirements extend, or Brazilian cane sugar harvest disruptions materialize beyond historical variance bands. Deviation in any of these triggers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Hydrolyzed Corn Protein Market
Ingredients
Spain Sodium Reduction Ingredient Market
Ingredients
Functional Flours Market
Ingredients
Apple Extract Market
Ingredients
Pepsin Market
Ingredients
Gymnema Extract Market
Ingredients
Dry Molasses Products Market
Ingredients
Sugar Beet Pectin Market
Ingredients
Terminalia Extract Market
Ingredients
Corn Gluten Meal Market
Ingredients
Pea Protein Ingredients Industry Status and Prospects Professional Market
Ingredients
Polydextrose Ingredients Market
Ingredients
South America Fruit and Vegetable Ingredients Market
Ingredients
Global Cocoa Ingredients Market
Ingredients
Algae-Based Ingredients Market
Ingredients
Europe Whey Protein Ingredients Market