
 Plant-Based Fish Market | 2026-2036
Plant-Based Fish Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Fish Market Outlook
ISO 22000 certification is rotating as the baseline food safety qualification that determines which manufacturers can supply retail and foodservice channels in major markets. Nestlé S.A. leverages its frozen food infrastructure to distribute plant-based fish through European supermarket networks. Good Catch anchors its position through proprietary legume-protein binding systems that replicate flaky textures. Revo Foods GmbH dominates precision extrusion technology for whole-cut analogs in Central Europe.
Plant-based fish denotes formulated food products engineered from non-animal proteins, starches, and lipid systems to replicate the organoleptic properties of conventional seafood, typically containing 12-20% protein content and structured through high-moisture extrusion or shear-cell processing. The ingredient base segment shows algal protein commanding premium positioning due to marine lipid fidelity, while pea protein sustains the fastest volume growth driven by allergen-friendly labeling. Among end users, supermarkets occupy the largest margin pool through private-label expansion, whereas meal kits capture the highest growth trajectory as subscription models reduce consumer trial barriers.
The FDA oversees GRAS determinations for novel proteins in the United States, while the EMA and EFSA frameworks govern nutritional and safety assessments across Europe, collectively elevating compliance costs but filtering out undercapitalized entrants. In China, the national food safety regulator applies GB standards that restrict certain algae-derived colorants, shaping formulation choices for export-oriented suppliers. Stakeholders must monitor evolving allergen labeling mandates and carbon-footprint disclosure rules that will determine which product architectures secure shelf space in the next regulatory cycle.
Market Dynamics
High-moisture extrusion technology is compressing production timelines and enabling whole-cut analogs that satisfy foodservice specifications previously unreachable for plant-based seafood manufacturers.
Growth Catalysts
- EU Novel Food Regulation streamlining:The centralized approval pathway accelerates market entry for algae-derived protein formulations across Germany, France, and the Netherlands.
- Foodservice menu expansion:Restaurant chains in the United States and United Kingdom are adding dedicated plant-based seafood sections to capture flexitarian diners.
- Precision fermentation maturation:This lipid synthesis method delivers marine omega-3 fidelity without wild catch dependency, attracting premium positioning in retail.
Market Restraints
- Pea protein price volatility:Contracting supply from Canadian and Ukrainian growers creates input cost instability for mid-tier manufacturers.
- Extrusion equipment oligopoly:German and Italian machinery suppliers control 70% of high-moisture extrusion installations, limiting capacity expansion speed.
- Texture replication ceiling:Current shear-cell processing cannot achieve the fibrous mouthfeel of raw sashimi-grade fish, constraining premium segment penetration.
Strategic Opportunities
- Japanese institutional foodservice:Corporate cafeterias and school lunch programs seek certified sustainable seafood alternatives with lower mercury risk profiles.
- Subscription meal kit integration:Direct-to-consumer platforms reduce consumer trial barriers through portion-controlled introductory formats.
- Carbon footprint labeling mandates:Pending EU requirements will reward suppliers with verified low-emission supply chains, creating first-mover advantage.
Industry Challenges
- ISO 22000 certification backlog:Third-party audit capacity constraints delay supplier qualification for retail distribution.
- Flavor masking formulation complexity:Removing legume off-notes while preserving clean-label status demands specialized food science talent scarce in Central Europe.
- Cross-contamination protocol standardization:Allergen management gaps between plant-based and conventional seafood processing lines complicate co-manufacturing arrangements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Fish Market |
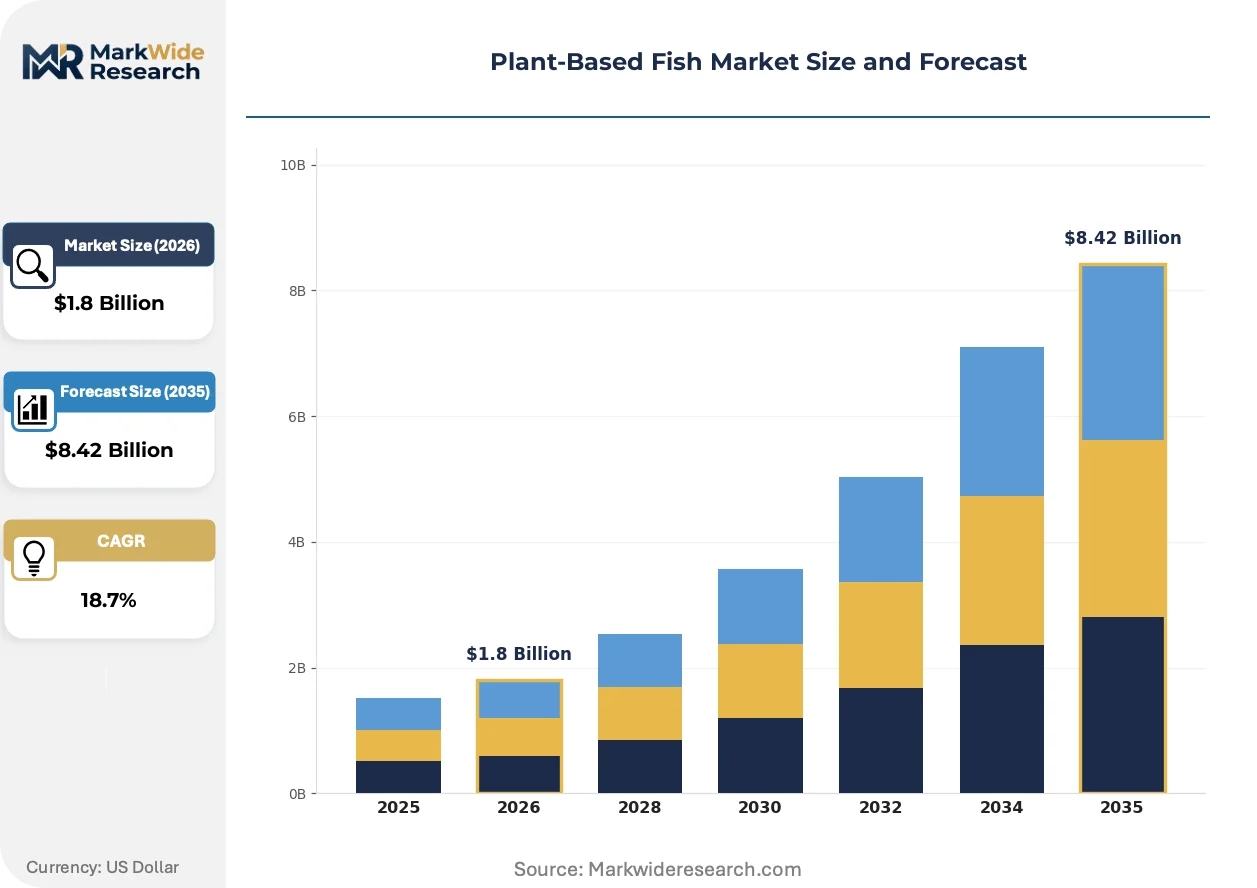
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fillets, Nuggets, Tacos, Spreads Ingredient Base: Algal Protein, Soy Protein, Pea Protein, Wheat Gluten End User: Restaurants, Supermarkets, Meal Kits, Cafés Flavor Profile: Smoked, Spicy, Garlic, Teriyaki |
| Companies Covered | Nestlé S.A., Good Catch, Impossible Foods, Gardein, OmniFoods, Revo Foods GmbH, Atlantic Natural Foods, The Plant Based Seafood Co., New Wave Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Fish Market Strategic Shifts
Shear-cell processing architectures are displacing conventional extrusion as the dominant production paradigm, compressing capital requirements while expanding textural possibility spaces for whole-muscle analogs.
High-moisture extrusion systems are miniaturizing from industrial-scale installations to modular units deployable in regional production hubs. Mid-sized food manufacturers in Spain and Poland are adopting these compact lines to serve local supermarket private-label programs. This distributed production model is compressing logistics costs and enabling fresher product delivery cycles.
REACH chemical safety registrations are tightening scrutiny on algae-derived colorants and lipid carriers used in European formulations. Manufacturers must submit expanded toxicological dossiers for novel extraction solvents. The regulatory burden falls heaviest on startups lacking dedicated regulatory affairs functions, advantaging established players with compliance infrastructure.
Direct sourcing contracts between retailers and ingredient suppliers are displacing traditional distributor intermediaries in the United States and United Kingdom. Supermarket chains now negotiate pea protein and algal oil purchases directly, compressing margin pools for legacy foodservice distributors. This channel restructuring concentrates procurement power among the four largest retail groups.
Plant-Based Fish Market Segmentation
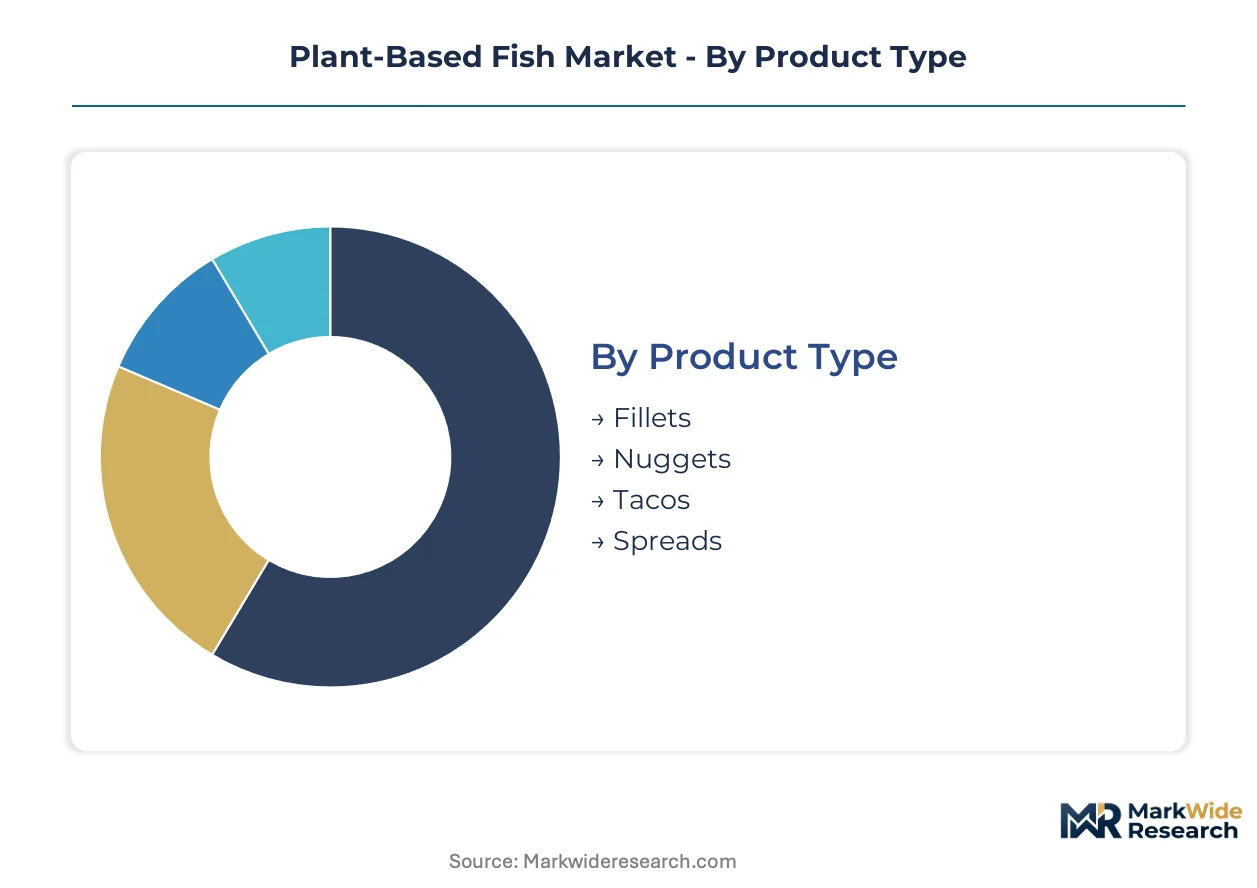
Plant-based fish manufacturers configure product architectures around distinct channel requirements, with foodservice demanding bulk formats and retail favoring portion-controlled SKUs. Ingredient sourcing strategies and certification tiers further stratify competitive positioning across these segments.
Product Type:
Restaurant chains and retail channels pull different formats through their supply chains, with foodservice prioritizing kitchen-ready cuts and supermarkets favoring consumer-convenience packaging.
- Fillets:Whole-muscle analogs produced through high-moisture extrusion replicate flaky texture profiles for center-plate applications. German and British restaurant groups specify these for fish-and-chip menu replacements.
- Nuggets:Bite-sized formats with breaded exteriors target children's menus and quick-service applications. Meal kit providers in the United States bundle these as introductory trial SKUs for flexitarian households.
- Tacos:Pre-seasoned shredded formats reduce kitchen labor for fast-casual operators.
- Spreads:Emulsified products resembling pâté or rillettes serve appetizer and retail deli cases.
By volume, fillets lead. By growth pace, nuggets are ahead.
Ingredient Base:
Cost structures and allergen labeling requirements divide procurement strategies, with premium positioning commanding marine-derived inputs and mass-market SKUs optimizing for price stability.
- Algal Protein:Marine-sourced proteins deliver authentic lipid profiles and omega-3 content without wild-catch dependency. Precision fermentation suppliers in the Netherlands and California command premium pricing through DHA fidelity.
- Pea Protein:Allergen-friendly extraction from Canadian and Ukrainian growers sustains the steepest expansion trajectory. Clean-label positioning avoids soy and wheat disclosure triggers.
- Soy Protein:Established supply infrastructure from Midwestern processors offers cost advantages for conventional retail tiers.
- Wheat Gluten:Seitan-derived textures provide chew characteristics for Asian-market whole-cut applications.
Pea protein captures volume leadership in new product launches. Algal protein commands margin premiums.
End User:
Procurement authority concentrates differently across channels, with supermarket private-label programs exerting direct ingredient sourcing power previously held by distributors.
- Supermarkets:Private-label expansion by Tesco, Carrefour, and Whole Foods Market concentrates shelf-space negotiation power. Direct pea protein and algal oil contracts bypass legacy foodservice distributors.
- Meal Kits:Subscription models from HelloFresh and Blue Apron reduce consumer trial barriers through portion-controlled introductory formats. Recurring revenue structures justify higher customer acquisition costs.
- Restaurants:Chain operators in the United States and United Kingdom add dedicated plant-based seafood sections.
- Cafés:Limited-service formats favor grab-and-go applications with minimal preparation requirements.
Supermarkets dominate current revenue. Meal kits show the steepest expansion trajectory.
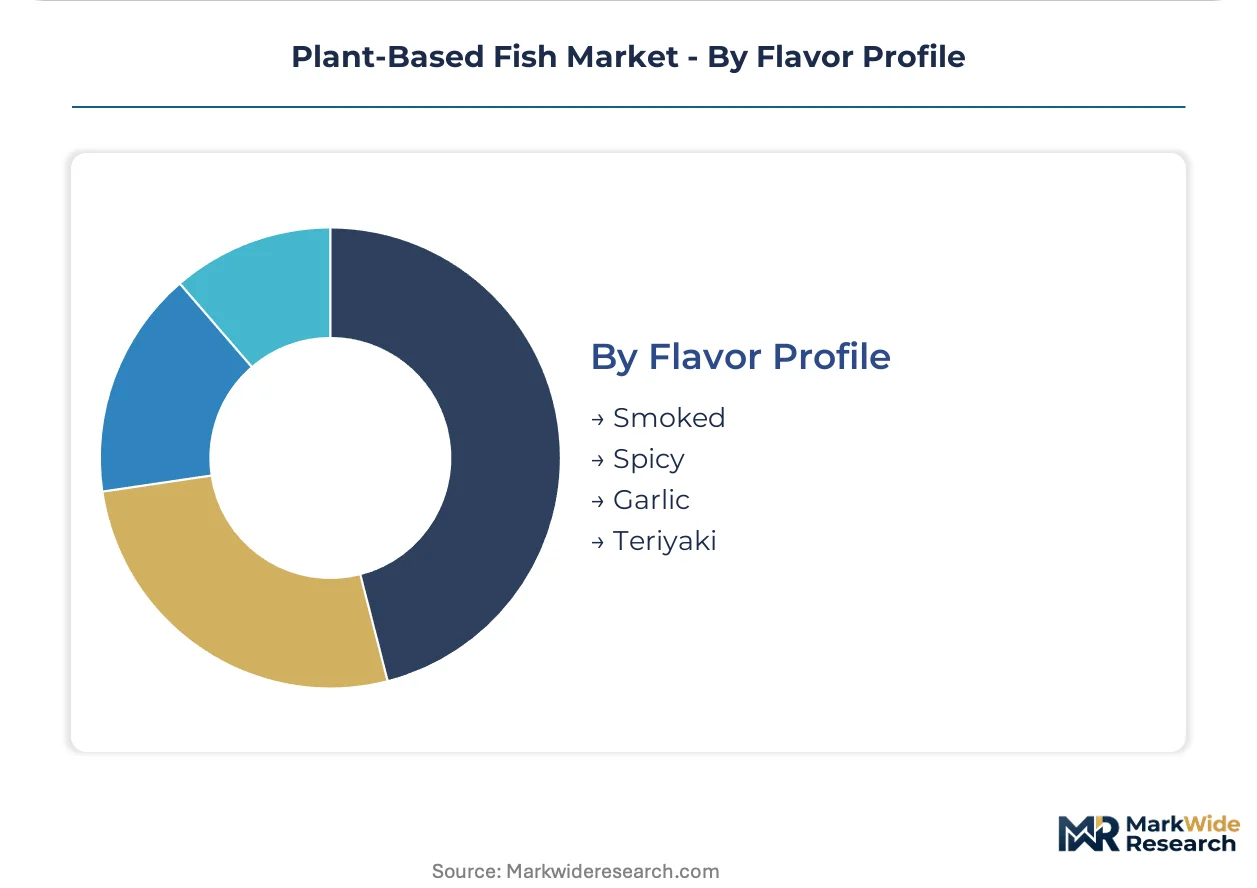
Flavor Profile:
Regional palate preferences and preparation method compatibility shape formulation R&D priorities, with smoked profiles bridging breakfast and appetizer occasions.
- Smoked:Cold-smoked processing techniques using algal-derived carriers replicate salmon and mackerel flavor signatures. British and Scandinavian retail buyers specify these for bagel and cracker pairings.
- Spicy:Capsicum and pepper formulations target Latin American and Southeast Asian foodservice applications.
- Garlic:Universal Mediterranean profile suits pasta and pizza topping integrations.
- Teriyaki:Soy-ginger glazes align with Japanese and Korean convenience store offerings.
Smoked profiles lead in retail velocity. Spicy variants climb fastest in foodservice adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supermarket private-label buyers and foodservice procurement managers concentrate demand across four distinct national markets where regulatory pathways and retail infrastructure maturity diverge sharply.
United States
Flexitarian diners in coastal metros drive foodservice menu expansion for plant-based seafood alternatives. FDA GRAS determinations for novel proteins create a structured but costly entry pathway for new suppliers. California-based precision fermentation clusters supply algal-derived omega-3 lipids to national retail chains.
Germany
Discounters Aldi and Lidl propel private-label volume through price-aggressive shelf placement of extruded fillet analogs. EU Novel Food Regulation centralized approvals accelerate algae-protein formulations across the single market. Berlin-Brandenburg hosts Revo Foods GmbH's precision extrusion facility serving Central European supermarket networks.
United Kingdom
Meal kit subscription models reduce trial barriers for flexitarian households in Greater London and the Southeast. Post-Brexit retained EU law maintains novel food safety standards while enabling faster domestic determinations. Scottish salmon-processing regions repurpose cold-smoking infrastructure for plant-based smoked analog exports.
Netherlands
Algae cultivation technology suppliers cluster around Wageningen University research corridors. EMA and EFSA frameworks govern nutritional assessments for marine lipid alternatives entering European distribution. Rotterdam port logistics enable bulk algal oil import for regional formulation facilities.
Japan
Corporate cafeteria operators and school lunch programs seek certified sustainable alternatives with reduced mercury exposure profiles. METI clean-label initiatives promote domestic fermentation capacity for marine lipid synthesis. Tokyo-Osaka foodservice corridors test whole-cut analogs in institutional catering contracts.
Plant-Based Fish Market Competitive Environment
Player mix skews toward diversified food conglomerates and specialized protein technology ventures. Tiered concentration prevails: three multinational frozen food operators control retail distribution infrastructure, while mid-scale extrusion specialists capture foodservice contract manufacturing. Strategic archetypes include legacy CPG players repurposing existing cold-chain assets, precision extrusion technology owners, and algae-derived ingredient platform builders. Dominant competitive moves center on direct retail sourcing contracts that bypass legacy distributors, and high-moisture extrusion capacity expansion through German and Italian machinery procurement.
Among European technology-focused ventures, Revo Foods GmbH exemplifies the precision extrusion archetype through its whole-cut analog specialization. Nestlé S.A. anchors the diversified conglomerate tier with frozen infrastructure leverage across supermarket networks. Good Catch occupies a position within the proprietary binding-system specialist category. These three entities represent distinct competitive vectors: technology ownership, distribution scale, and texture-replication intellectual property.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Good Catch |
| Impossible Foods |
| Gardein |
| OmniFoods |
| Revo Foods GmbH |
| Atlantic Natural Foods |
| The Plant Based Seafood Co. |
| New Wave Foods |
| Others |
Value Chain & Pricing Dynamics
Pea protein displacement of soy concentrates in European formulations simultaneously redraws procurement geography toward Canadian and Baltic growers and compresses margin structures for mid-tier manufacturers locked into legacy ingredient contracts.
Pricing Analysis
Cost-plus contracts indexed to Rotterdam algal oil spot markets dominate premium-tier negotiations, while standard SKUs anchor to Midwestern pea protein futures. Price differentiation hinges on ISO 22000 certification tier and direct retail sourcing scale. Pricing pressure stems from Ukrainian crop volatility and extrusion equipment backlogs. Discounters exhibit acute price sensitivity; precision fermentation suppliers show inelastic demand.
Supply Chain Analysis
Rotterdam port congestion on Atlantic algal oil routes elevates inbound logistics costs for Central European formulators. Supply concentrates in Germany, the Netherlands, and Canada for protein inputs, with precision fermentation clusters in California and the Netherlands for marine lipids. Raw material dependencies include Canadian pea protein, Dutch algal oil, and German extrusion machinery. Single-source vulnerability sits with Italian and German equipment suppliers controlling high-moisture extrusion installations. Distribution runs through direct retailer contracts displacing legacy foodservice distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized food science talent scarcity in shear-cell processing and flavor masking constrains formulation velocity, creating acquisition premiums for teams with clean-label expertise.
For Market Incumbents: Shield market position through backward integration into Canadian pea protein origination and captive high-moisture extrusion capacity in Germany. Nestlé-scale frozen infrastructure leverage and ISO 22000 certification depth create defensive moats against emerging precision fermentation entrants. Prioritize direct sourcing contracts with Aldi and Lidl to lock discounter shelf space.
For New Entrants and Emerging Players: Anchor in Japanese institutional foodservice white space, where corporate cafeteria procurement seeks mercury-free alternatives and regulatory pathways favor novel food submissions. Meal kit subscription channels reduce consumer trial barriers through portion-controlled formats. Lead with smoked flavor profiles leveraging repurposed Scottish cold-smoking infrastructure.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision extrusion specialists holding proprietary shear-cell architectures. Five-to-ten year viability hinges on carbon footprint verification capabilities and algae-derived lipid platform durability. Watch EU carbon labeling mandate timing as inflection signal for first-mover advantage crystallization.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Extrusion Capacity Expansion | Revo Foods GmbH's Berlin facility demonstrates whole-cut analog scalability for Central European supermarket networks. |
| Direct Retail Sourcing Contracts | Tesco and Carrefour procurement teams now negotiate pea protein purchases directly, compressing legacy distributor margins. |
| Precision Fermentation Scale-Up | Dutch and California clusters supply algal-derived omega-3 lipids with marine fidelity without wild-catch dependency. |
| ISO 22000 Certification Investment | Third-party audit qualification determines retail and foodservice channel access in Germany and the United Kingdom. |
| Meal Kit Platform Integration | HelloFresh and Blue Apron subscription models reduce consumer trial barriers through recurring revenue structures. |
Study Parameters
A spread of perspectives from plant-based protein R&D directors, supermarket category buyers, foodservice procurement managers, and precision fermentation technology leads converged on the working assumptions. Primary fieldwork combined with secondary validation from EFSA novel food submission databases, FDA GRAS notification filings, EU customs trade records, and cold-chain logistics provider disclosures. Bottom-up volume modeling and top-down market sizing triangulated across ingredient supplier interviews and retail scanner data.
Segmentation dimensions modeled include product architecture, ingredient base, end-user channel, and flavor profile across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating flexitarian household penetration rates and foodservice menu adoption velocity. Forecast inputs incorporated EU Novel Food Regulation approval timelines and high-moisture extrusion capacity expansion schedules.
Material uncertainties — regulatory determination delays, pea protein crop yield volatility, and carbon labeling mandate timing — sit outside the modeled envelope. Forecasts reflect documented assumptions about substitution elasticity and channel migration patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Organic Rice Protein Market
Plant Based Food
Plant-Based Milk Alternatives Market
Plant Based Food
Plant-Based Nuggets Market
Plant Based Food
Plant Based Eggs Market
Plant Based Food
United States Pea Protein Market
Plant Based Food
US Plant-Based Meat Market
Plant Based Food
Global Plant Protein Market
Plant Based Food
Indoor Leafy Green Precision Nutrition Program Market
Plant Based Food
Middle East and Africa Meat Substitute Market
Plant Based Food
Soy Protein Market
Plant Based Food
Japan Plant Protein Market
Plant Based Food
Plant-Based Protein Food Market
Plant Based Food
South America Pea Protein Market
Plant Based Food
Global Tofu Market
Plant Based Food
Vegan Protein Foods Market
Plant Based Food
Vegan Bacon Market