
 Middle East and Africa Plant-Based Egg Market | 2026-2036
Middle East and Africa Plant-Based Egg Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Plant-Based Egg Market Foresight
Ingredient supply contracting is reconfiguring margin distribution across the Middle East and Africa plant-based egg value chain. Eat Just leverages its proprietary mung bean protein isolation technology to secure premium positioning in Gulf retail channels. Kerry anchors regional formulation partnerships, supplying emulsifier systems to local food manufacturers seeking egg-free binding solutions. Corbion competes through its microbial fermentation-derived ingredient portfolio, targeting clean-label demands in South African baking applications.
Plant-based egg denotes formulated food systems designed to replicate the functional properties—coagulation, foaming, and emulsification—of avian eggs using proteins extracted from legumes, algae, or fungal biomass, typically achieving gelation temperatures between 65°C and 85°C depending on protein source and hydrocolloid adjuncts. These systems serve industrial bakers, food service operators, and retail consumers requiring allergen-reduced or cholesterol-free alternatives to conventional eggs. Liquid egg substitute dominates current volume flows through food service procurement channels, while powdered egg alternative captures expanding shelf-stable demand from health food stores and online retail platforms across the region. Frozen egg replacement remains nascent, constrained by cold chain gaps in secondary cities but presenting latent margin pools where logistics infrastructure improves.
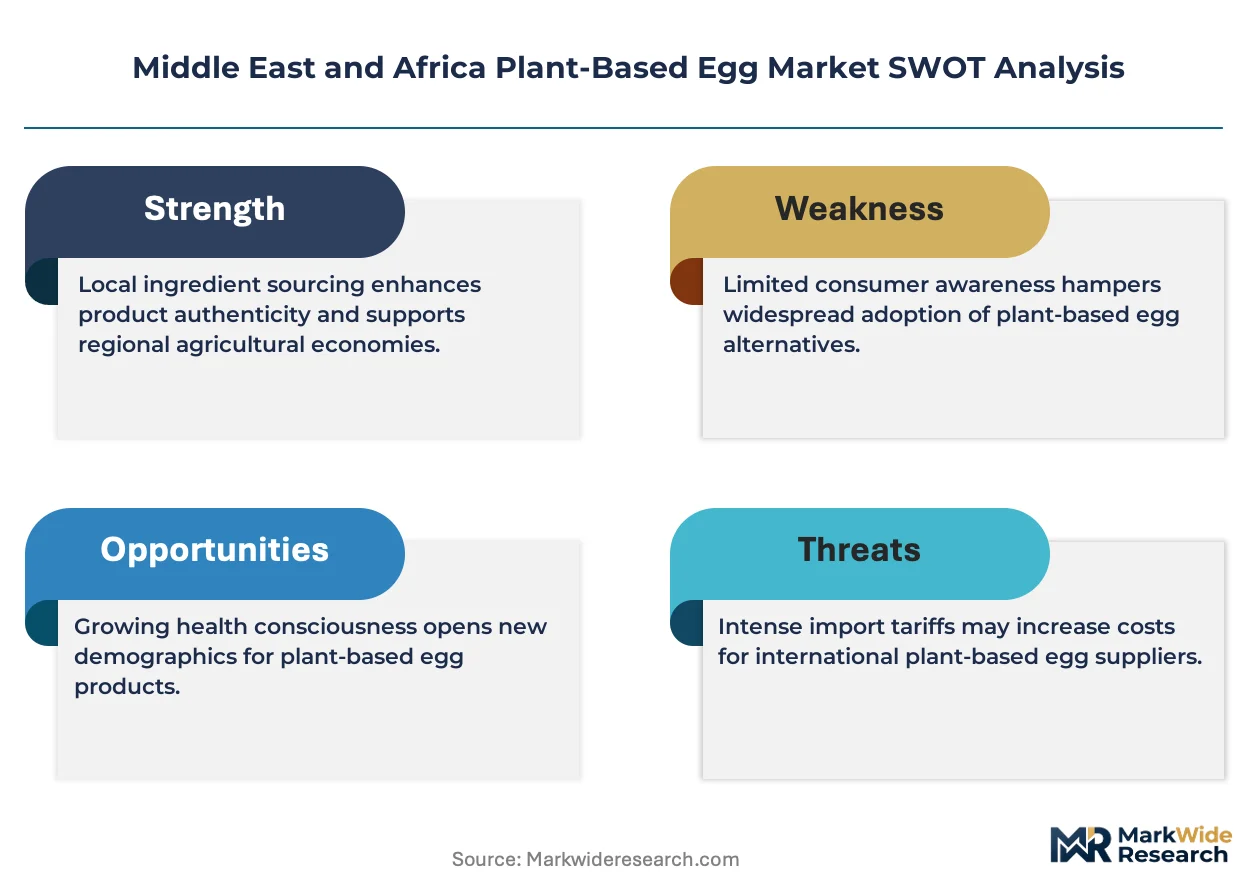
SFDA standards in Saudi Arabia and MOHAP regulations in the United Arab Emirates govern novel food ingredient approvals, directly conditioning market entry timelines for imported plant-based egg formulations. South Africa's Department of Health enforces labeling requirements that distinguish between egg analogs and allergen-free claims, shaping consumer communication strategies. Stakeholders must monitor evolving halal certification protocols for novel protein sources and assess which Gulf markets will harmonize import standards fastest.
Market Dynamics
Ingredient supply contracting is reconfiguring margin distribution across the Middle East and Africa plant-based egg value chain, as mung bean protein isolation capacity concentrates among a handful of specialized processors.
Growth Catalysts
- SFDA novel food frameworks:Saudi Arabia's streamlined approval pathways for legume-derived proteins accelerate commercialization timelines for imported formulations targeting Gulf retail shelves.
- Food service vegan menu expansion:United Arab Emirates hospitality operators integrate liquid egg substitutes into bakery applications, creating pull-through demand from commercial kitchens in Dubai and Abu Dhabi.
- Mung bean protein extraction:Rising consumer familiarity with this processing technology in South Africa steers procurement toward powdered alternatives with clean-label positioning.
Market Restraints
- Input cost volatility:Mung bean supply fluctuates with monsoon patterns in Indian subcontinent sourcing regions, compressing processor margins during drought cycles.
- Cold chain gaps:Frozen egg replacement distribution faces infrastructure deficits in secondary Saudi and South African cities, limiting addressable market expansion.
- Regulatory friction:Divergent halal certification protocols for novel protein sources across Gulf Cooperation Council states create compliance duplication costs for entrants.
Strategic Opportunities
- Underpenetrated Nigerian markets:Lagos and Abuja present latent demand pools where rising cholesterol awareness meets limited domestic egg analog availability.
- Emulsifier-binder convergence:Integration of microbial fermentation-derived hydrocolloids with legume proteins enables single-ingredient replacement systems for industrial bakers.
- MOHAP clean-label incentives:United Arab Emirates regulatory guidance favoring reduced-allergen formulations creates preferential shelf placement for certified egg alternatives.
Industry Challenges
- Protein functionality expertise gap:Regional food technologists lack depth in gelation temperature optimization for multi-source protein blends, slowing formulation iteration.
- Halal certification timeline compression:Novel protein sources require case-by-case religious authority review, extending product launch cycles by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Plant-Based Egg Market |
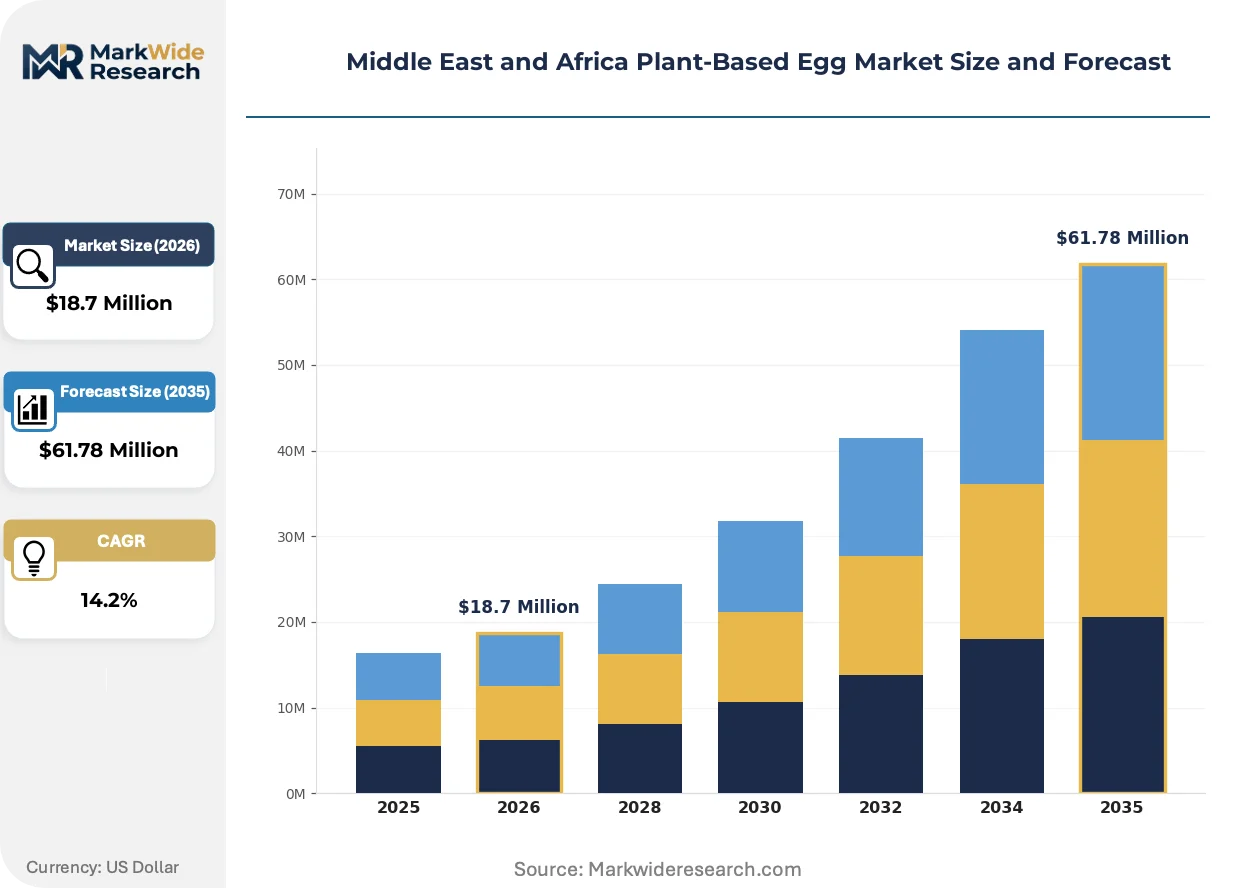
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $61.78 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Egg Substitute, Powdered Egg Alternative, Frozen Egg Replacement, Ready-to-Eat Egg Product End User: Households, Food Service, Retail Chains, Food Manufacturers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Convenience Stores Application: Baking, Cooking, Vegan Meals, Protein Supplements |
| Companies Covered | Eat Just, DuPont, Alternative Foods, Ingredion, MGP, Kerry, Tate & Lyle, Corbion, Cargill, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Plant-Based Egg Market Shifts & Advancements
Formulation science and distribution infrastructure are advancing in parallel across Middle East and Africa markets, creating new competitive axes beyond simple ingredient substitution.
Microbial fermentation-derived emulsifier systems are hybridizing with traditional legume protein bases to achieve superior foaming stability in high-temperature baking applications. South African industrial bakers adopt these hybrid systems fastest, replacing separate egg and chemical emulsifier purchases with unified ingredient streams. This convergence is compressing supplier count per bakery while raising technical barriers for pure commodity protein vendors.
MOHAP in the United Arab Emirates and SFDA in Saudi Arabia are harmonizing novel food ingredient notification requirements through bilateral regulatory cooperation frameworks. This alignment reduces duplicate safety documentation for formulations entering both markets simultaneously. Powdered egg alternatives gain first-mover advantage as these streamlined pathways prioritize shelf-stable products with extended stability data.
Health food retailers in Gulf Cooperation Council corridors are consolidating procurement through centralized distribution hubs rather than direct manufacturer relationships. Dubai-based logistics operators now aggregate plant-based egg SKUs from multiple international suppliers for redistribution across smaller Emirates markets. Kenya and Egypt are replicating this hub-and-spoke model, with Nairobi emerging as an East African consolidation point for specialty ingredient imports.
Middle East and Africa Plant-Based Egg Market Segmentation
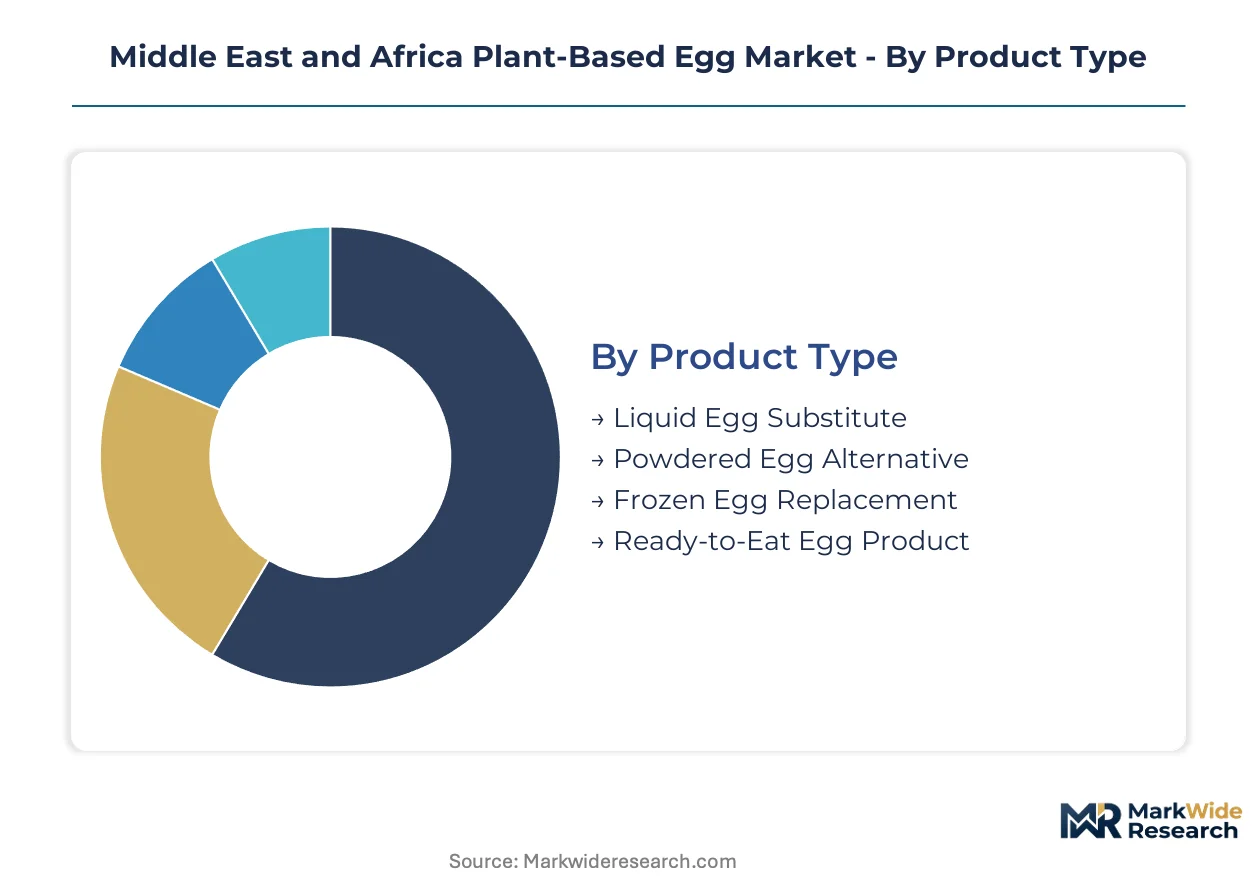
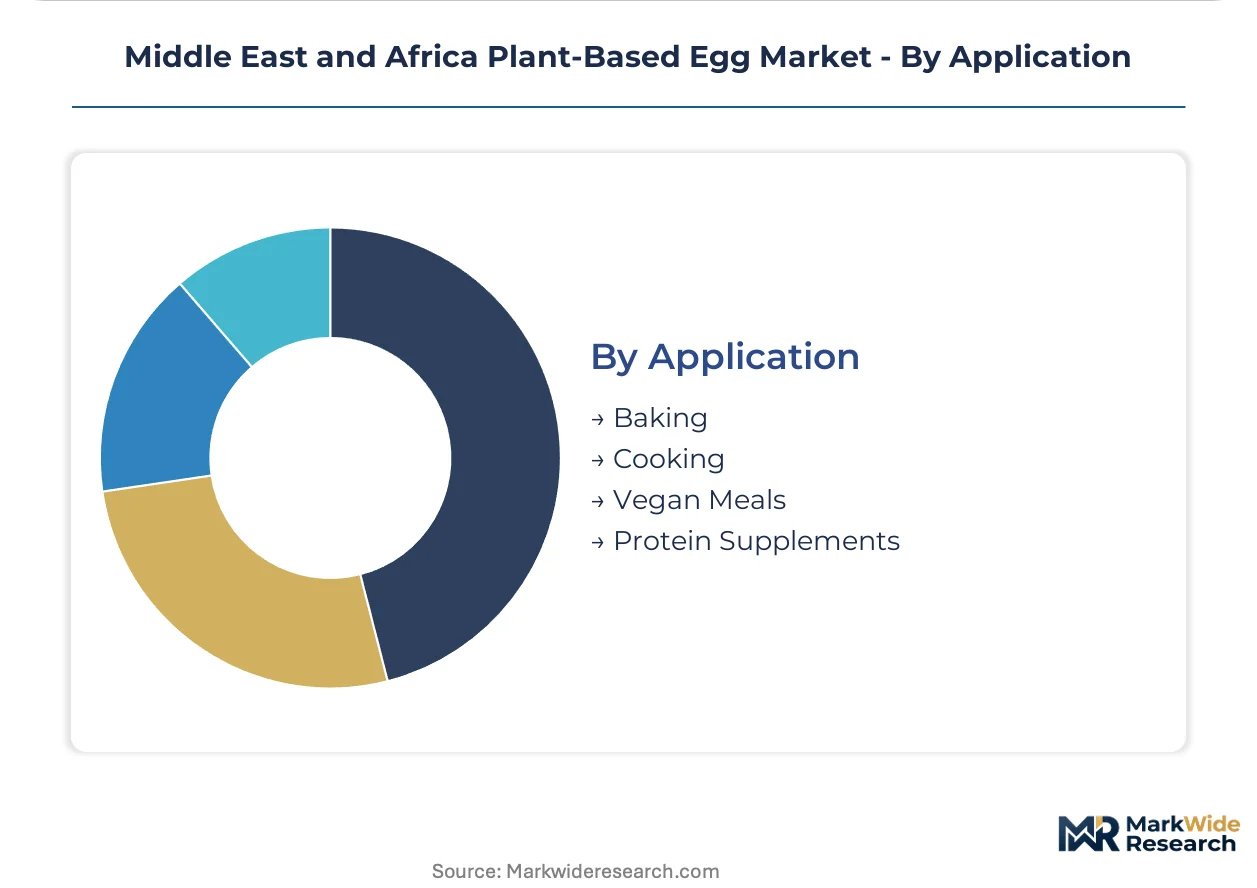
Product format selection determines cold chain requirements and margin capture across Middle East and Africa markets. Distribution channel configuration shapes which customer segments manufacturers can economically serve. Application-specific functional demands drive protein source selection and formulation complexity.
Product Type:
Cost tier differentiation separates premium refrigerated formats from shelf-stable economy alternatives across regional procurement channels.
- Liquid Egg Substitute:Refrigerated emulsions of mung bean or chickpea protein achieve gelation temperatures of 65°C to 75°C. Dubai and Abu Dhabi food service operators dominate procurement volumes, driven by vegan menu expansion in hospitality sectors. Liquid formats command premium positioning but require continuous cold chain integrity.
- Powdered Egg Alternative:Spray-dried protein concentrates with hydrocolloid stabilizers enable extended ambient storage. South African health food retailers and Kenyan import distributors concentrate demand, steered by clean-label positioning and reduced logistics complexity. Powdered formats bypass refrigerated distribution gaps in secondary cities.
- Frozen Egg Replacement:Blast-frozen protein matrices maintain functional properties through thaw cycles. Cold chain infrastructure deficits in Riyadh and Johannesburg peripheries constrain addressable market expansion.
- Ready-to-Eat Egg Product:Pre-cooked scramble or patty formats target convenience-oriented retail segments. Limited domestic manufacturing capacity across Gulf Cooperation Council states restricts availability.
Liquid egg substitute holds installed capacity. Powdered egg alternative is rotating up the share rankings.
End User:
Customer type segmentation maps volume scale against technical specification requirements and procurement sophistication.
- Food Service:Commercial kitchens in Dubai, Riyadh, and Cape Town specify functional performance metrics—foaming stability, coagulation speed, emulsification capacity—driving supplier technical service intensity. Bulk procurement contracts concentrate purchasing power among hotel chains and bakery cooperatives.
- Food Manufacturers:Industrial bakers in South Africa and the United Arab Emirates integrate plant-based egg systems into standardized production lines, requiring batch consistency certifications and halal compliance documentation.
- Households:Urban consumers in Gulf Cooperation Council capitals purchase retail formats for home baking and breakfast preparation, with purchasing decisions influenced by allergen labeling and cholesterol reduction claims.
- Retail Chains:Supermarket private label programs in Saudi Arabia and the United Arab Emirates negotiate exclusive supply arrangements, compressing margins for branded alternatives.
Food service holds installed capacity. Food manufacturers is climbing the fastest.
Distribution Channel:
Supply concentration varies by channel type, with direct manufacturer relationships yielding highest margins and aggregator models compressing supplier economics.
- Supermarkets:Carrefour, Lulu, and Spinneys operations across Dubai, Abu Dhabi, and Riyadh maintain dedicated plant-based refrigerated sections, creating shelf placement competition among liquid format suppliers.
- Online Retail:Amazon.ae, Noon, and Jumia platforms aggregate powdered and shelf-stable formats, with subscription models capturing repeat purchase loyalty in Saudi and South African urban markets.
- Health Food Stores:Independent retailers in Cape Town, Nairobi, and Lagos specialize in allergen-free and organic-certified alternatives, commanding price premiums through curation authority.
- Convenience Stores:Limited refrigerated footprint restricts liquid format availability; powdered sachets targeting single-use baking applications represent primary penetration vector.
Supermarkets holds installed capacity. Online retail is gaining share fastest.
Application:
Functional performance requirements by use case determine protein blend complexity and hydrocolloid adjunct selection.
- Baking:Industrial and artisanal bakeries require foaming stability for sponge cakes and emulsification for laminated doughs, driving demand for mung bean-alginate hybrid systems with superior thermal tolerance.
- Cooking:Scramble and omelet applications prioritize coagulation texture and mouthfeel, with South African food service operators testing fungal biomass alternatives for neutral flavor profiles.
- Vegan Meals:Restaurant and ready-meal manufacturers specify complete amino acid profiles and absence of animal-derived processing aids, triggering halal certification complexity for novel protein sources.
- Protein Supplements:Sports nutrition formulations in United Arab Emirates and Saudi Arabia emphasize protein content per serving and digestibility scores, competing with established whey and pea protein categories.
Baking holds installed capacity. Vegan meals is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the Middle East and Africa. Gulf Cooperation Council states favor liquid refrigerated formats for food service applications, while South African and East African markets gravitate toward powdered shelf-stable alternatives that bypass cold chain limitations.
United Arab Emirates
Dubai and Abu Dhabi hospitality operators drive liquid egg substitute procurement for vegan bakery menus and hotel breakfast programs. MOHAP clean-label incentives accelerate novel protein ingredient approvals. Dubai-based logistics hubs aggregate plant-based egg SKUs for redistribution across smaller Emirates markets.
Saudi Arabia
Riyadh and Jeddah food service chains specify halal-certified egg alternatives for institutional catering contracts. SFDA streamlined novel food frameworks compress commercialization timelines for imported legume-derived formulations. Eastern Province industrial bakers test microbial fermentation-derived emulsifier systems for high-temperature applications.
South Africa
Cape Town health food retailers concentrate demand for powdered egg alternatives with organic and allergen-free positioning. The Department of Health enforces labeling standards that distinguish egg analogs from allergen-free claims, shaping manufacturer communication strategies. Johannesburg industrial baking cooperatives integrate mung bean protein systems into standardized production lines.
Nigeria
Lagos and Abuja urban consumers exhibit rising cholesterol awareness without corresponding domestic egg analog availability. The country's national food regulator maintains evolving standards for novel protein ingredient safety assessments. Nigerian import distributors source powdered formats through Nairobi-based East African consolidation hubs.
Egypt
Cairo and Alexandria bakery manufacturers seek cost-competitive binding solutions for traditional pastry applications. Egyptian food safety authorities align import requirements with broader regional harmonization efforts. Nile Delta industrial zones attract regional formulation partnerships targeting North African distribution networks.
Middle East and Africa Plant-Based Egg Market Competitive Landscape
Capability concentration sits with specialized ingredient technology developers; scale advantage sits with diversified global suppliers with existing regional distribution infrastructure. The market structures around three tiers: proprietary protein isolation specialists, formulation service providers, and commodity ingredient distributors. Dominant competitive moves include strategic partnerships between technology developers and regional food manufacturers, plus capacity expansion in spray-dried protein concentrate production.
Among protein technology specialists, Eat Just anchors the proprietary isolation tier through its mung bean-derived platform positioning. Kerry and Corbion occupy formulation partnership roles, supplying emulsifier systems and microbial fermentation-derived ingredients to regional industrial bakers. DuPont and Ingredion represent diversified ingredient distributors with existing supply relationships across Gulf and African markets.
| Leading Market Players |
|---|
| Eat Just |
| DuPont |
| Alternative Foods |
| Ingredion |
| MGP |
| Kerry |
| Tate & Lyle |
| Corbion |
| Cargill |
| Others |
Supply & Pricing Matrix
Indian mung bean processing clusters in Gujarat and Maharashtra anchor protein isolate supply, concentrating upstream pricing power among a handful of specialized extractors serving Gulf and African markets. Contract structures downstream reflect this asymmetry, with long-term offtake agreements dominating procurement between regional food manufacturers and ingredient suppliers.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships, though spot purchasing persists for smaller food service operators testing novel formulations. Three-tier pricing structure across premium, standard, and economy levels separates proprietary mung bean isolates from commodity legume blends and generic hydrocolloid systems. Cost compression in economy tiers intensifies because Indian monsoon volatility feeds raw material uncertainty. Retail chains in Gulf Cooperation Council states exhibit highest price sensitivity due to private label negotiation leverage, while industrial bakers prioritize functional performance over unit cost.
Supply Chain Analysis
Extended payment terms from Dubai-based logistics aggregators are restructuring working capital requirements for smaller ingredient suppliers entering Gulf markets. Manufacturing concentration centers on India, South Africa, and the United Arab Emirates, with spray-dried protein concentrates flowing from Indian processors and blended formulations emerging from South African industrial zones. Supply chains rest on mung bean harvests, chickpea protein supplies, and microbial fermentation feedstocks. Single-source vulnerability in Indian mung bean procurement creates exposure to climate-driven crop failures. Distribution runs through Dubai consolidation hubs for Gulf markets and Nairobi aggregation points for East African penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward food service chains and retail private label programs across Gulf Cooperation Council states, fragmenting supplier margins as procurement concentrates among fewer large-scale operators.
For Market Incumbents: Pre-empt margin erosion by securing exclusive formulation partnerships with South African industrial baking cooperatives and investing in halal certification infrastructure for novel protein sources. The threat of microbial fermentation-derived alternatives from Corbion and Kerry compresses traditional legume protein value capture. Backward integration into Indian mung bean processing capacity insulates against raw material volatility. For New Entrants and Emerging Players: Nigerian urban markets present the most penetrable white-space opportunity, where cholesterol awareness runs ahead of domestic egg analog availability. Target powdered shelf-stable formats for Lagos and Abuja distribution through Nairobi-based East African consolidation hubs. A technical service-led go-to-market approach addressing protein functionality expertise gaps in regional food technology communities accelerates adoption curves. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors proprietary protein isolation platforms with established regulatory approval pathways over commodity formulation providers. Long-term viability hinges on defensible intellectual property in extraction efficiency and clean-label positioning. Acquisition targets should demonstrate demonstrated SFDA or MOHAP clearance traction. The signal to watch is harmonization velocity across Gulf Cooperation Council novel food frameworks, which would compress multi-market entry costs for approved platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Infrastructure Investment | SFDA and MOHAP alignment on novel protein religious review protocols accelerates multi-market product launches. |
| Spray-Dried Protein Capacity Expansion | South African manufacturing footprint captures shelf-stable demand from health food retailers bypassing cold chain gaps. |
| Formulation Partnership with Industrial Bakers | Kerry and Corbion emulsifier integration creates sticky supplier relationships in high-volume baking applications. |
| Dubai Logistics Hub Consolidation | Aggregator model reduces distribution complexity for smaller Emirates markets and East African redistribution. |
| Mung Bean Processing Backward Integration | Captive supply from Indian Gujarat clusters insulates margin compression from monsoon-driven raw material volatility. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SFDA novel food filings, South African Department of Health labeling standards, and Gulf Cooperation Council customs data. Interviews with food technology directors at regional ingredient suppliers, procurement leads at Dubai hospitality operators, and regulatory affairs specialists at halal certification bodies informed demand and compliance dynamics. Trade flow analysis from Indian chemical export registries and South African industrial production surveys provided supply-side validation. Bottom-up segment sizing triangulated against top-down macro consumption trends.
Forecast inputs span product format evolution, protein source substitution elasticity, and regulatory harmonization velocity across the projection horizon. Segmentation dimensions modeled include liquid versus powdered versus frozen formats, food service versus manufacturing versus household end-use, and baking versus cooking versus vegan meal applications. CAGRs derived from fitted growth curves against historical adoption patterns in analogous alternative protein categories. Mung bean supply volatility and cold chain infrastructure development pace served as scenario-weighting variables.
Macroeconomic conditions sit as an overlay; deviation in Gulf Cooperation Council hospitality spending, Indian agricultural output, or regional currency stability would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory approval timelines and protein functionality improvement rates. Technological breakthroughs in microbial fermentation, shifts in halal certification protocols, or sustained drought cycles in Indian sourcing regions would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
North America Textured Vegetable Protein Market
Plant Based Food
Plant-Based Butter Market
Plant Based Food
Dandelion Root Extract Market
Plant Based Food
Vegan Marshmallows Market
Plant Based Food
Vegan Drink Mixes Market
Plant Based Food
Asia-Pacific Plant-Based Seafood Market
Plant Based Food
Vegan Cookies Market
Plant Based Food
India Plant Based Meat Alternatives Market
Plant Based Food
Plant-Based Bars Market
Plant Based Food
Vegan Dessert Market
Plant Based Food
Indonesia Plant-Based Food and Beverages Market
Plant Based Food
Soy Food Products Market
Plant Based Food
United States Rice Protein Market
Plant Based Food
Europe Plant-Based Seafood Market
Plant Based Food
Plant-Based Wellness Foods Market
Plant Based Food
Kava Root Extract Market