
 Vegan Asian Food Market | 2026-2036
Vegan Asian Food Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Asian Food Market Analytics
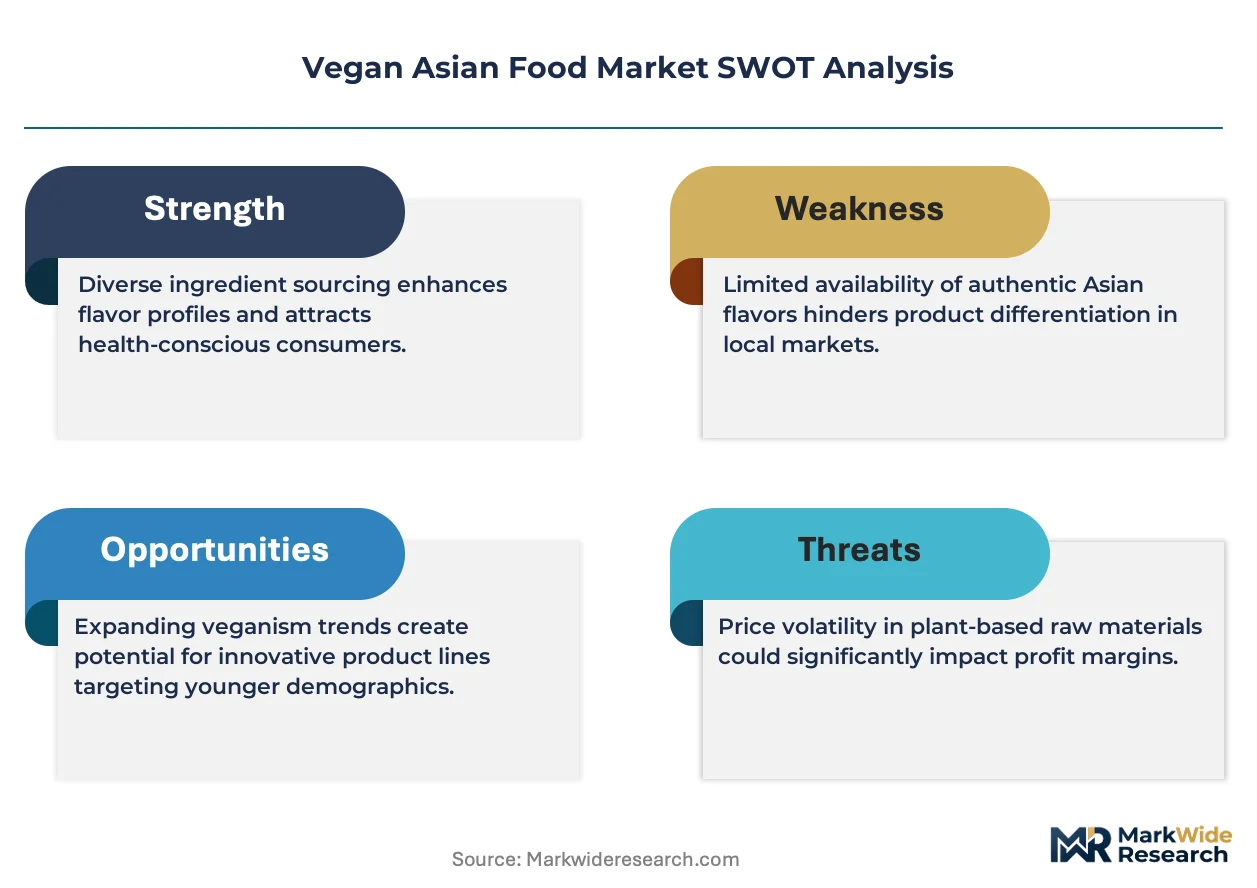
Asset-light licensing and co-manufacturing arrangements is fragmenting competitive boundaries in the vegan Asian food sector. Green Monday Group leverages its omnichannel brand architecture to sustain market presence across retail and foodservice. Hodo Foods anchors its position through in-house tofu craftsmanship and premium ingredient sourcing. OmniFoods competes via proprietary texturization technology that replicates traditional meat mouthfeel in dumpling and dim sum applications.
Vegan Asian food encompasses plant-based preparations derived from East and Southeast Asian culinary traditions, utilizing proteins such as soy-derived tofu with 8-15% solids content, fermented tempeh with Rhizopus oligosporus cultures, and wheat gluten seitan processed through repeated washing and simmering to achieve fibrous texture. The category serves commercial foodservice operators and retail consumers seeking authentic flavor profiles without animal-derived ingredients. Tofu and tempeh command established volume positions in supermarkets and specialty stores, while vegetable-based sauces capture expanding margin pools through premium positioning in online retail channels. Stir-fry and noodle cuisine types dominate household preparation occasions, whereas sushi applications lead within restaurant and cafe segments due to precision presentation requirements.
The FDA governs allergen labeling and GRAS determinations for soy and wheat protein ingredients in the United States, while EFSA establishes novel food safety assessments for fermented plant proteins entering European commerce. REACH compliance shapes packaging material selection and supply chain documentation for exporters serving EU member states. Stakeholders must monitor evolving national protein content thresholds and fermentation process certifications as regulatory divergence between jurisdictions intensifies compliance complexity.
Market Dynamics
Meal delivery services are fragmenting traditional retail channels as South Korean vegan startups and K-food globalisation compress adoption timelines across multiple geographies.
Growth Catalysts
- EU Green Deal sustainability mandates:The framework's ingredient sourcing requirements are forcing reformulation investments across European supply chains, opening premium positioning for compliant Asian vegan exporters.
- Texturization technology maturation:Proprietary extrusion and fermentation processes now replicate traditional meat mouthfeel in dumpling applications, expanding addressable occasions beyond committed vegans.
- South Korea:K-food globalisation and domestic startup density are accelerating category development faster than in neighboring markets, creating template markets for product-market fit testing.
Market Restraints
- Soy protein input volatility:Commodity price swings for non-GMO soybeans compress margin predictability for tofu and tempeh manufacturers dependent on premium ingredient sourcing.
- Regulatory friction from REACH compliance:Packaging material documentation requirements create supply chain documentation burdens for Asian exporters serving EU member states.
- Wheat gluten substitution ceiling:Celiac-sensitive consumer segments cap seitan addressability, limiting category expansion in health-positioned retail channels.
Strategic Opportunities
- Online retail channel premiumization:Vegetable-based sauces capture expanding margin pools through direct-to-consumer positioning that bypasses conventional supermarket slotting constraints.
- Foodservice precision applications:Sushi and dim sum segments reward authentic flavor replication with higher per-unit economics than mass retail formats.
- Fermented protein novel food pathways:EFSA assessment frameworks for Rhizopus oligosporus-derived ingredients create first-mover advantages for compliant European market entry.
Industry Challenges
- Fermentation process certification timelines:Novel food safety assessments for tempeh and other cultured proteins extend time-to-market for European commercialization.
- Co-manufacturing quality consistency:Asset-light licensing arrangements fragment quality control accountability across distributed production networks.
- Allergen labeling complexity:Divergent FDA and EFSA threshold standards for soy and wheat protein declarations multiply compliance engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Asian Food Market |
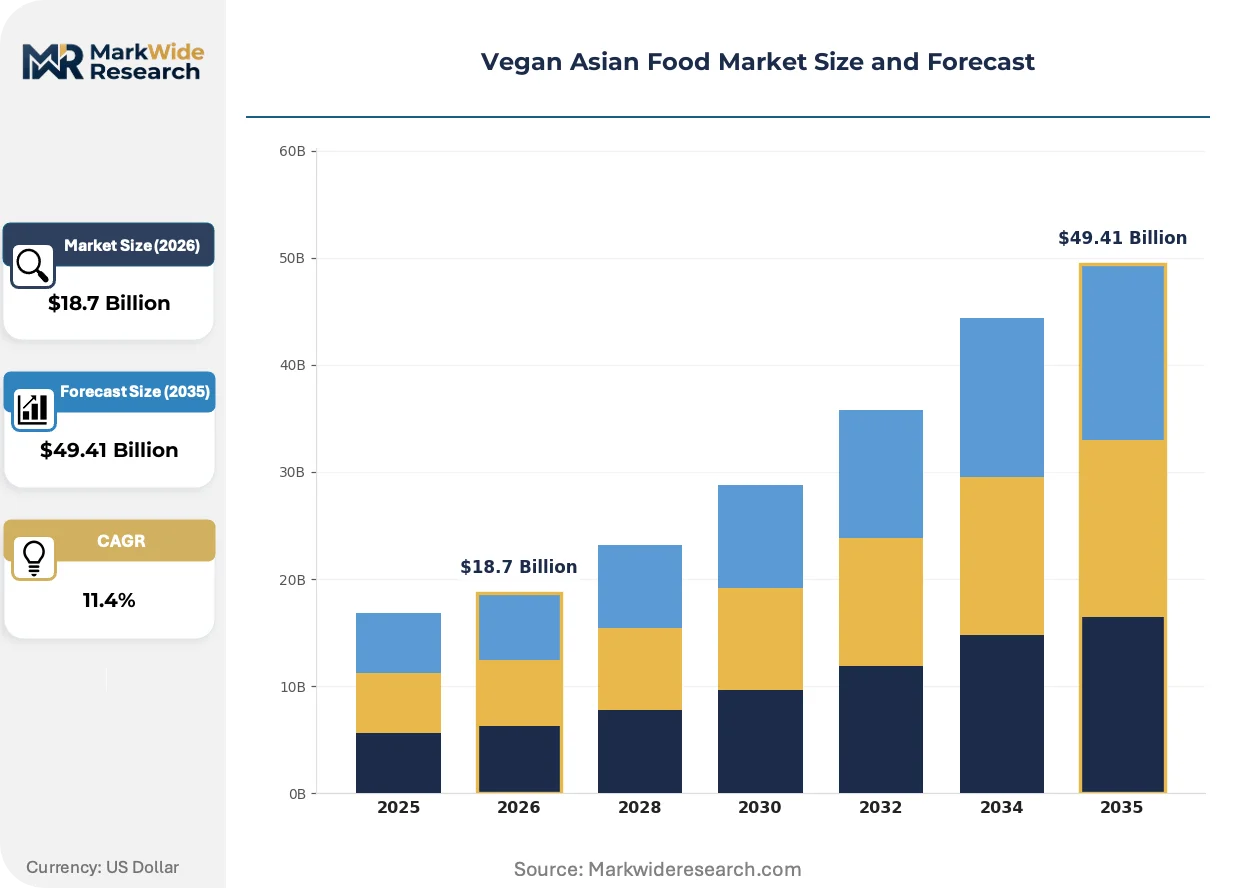
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tofu, Tempeh, Seitan, Vegetable-based Sauces End User: Households, Restaurants, Meal Delivery Services, Cafes Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Farmers Markets Cuisine Type: Sushi, Stir-fry, Noodles, Curries |
| Companies Covered | Green Monday Group, Immi, Unlimeat, Sanzo, Jack & Friends, Hodo Foods, Mekhala, BOBABAM, OmniFoods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Asian Food Market Evolving Landscape
Protein texturization methods and regulatory divergence are compressing product development cycles while delivery infrastructure reconfigures channel economics.
High-moisture extrusion technology is migrating from European plant-meat specialists to Asian dumpling and dim sum manufacturers seeking fibrous texture replication without animal inputs. Foodservice operators in South Korea and Japan are adopting these systems at pilot scale. The shift is enabling premium positioning in restaurant channels previously inaccessible to plant-based alternatives.
REACH and EU Green Deal packaging mandates are reshaping material selection for Asian exporters serving European commerce. Biodegradable film requirements and supply chain documentation obligations now filter supplier eligibility. Tempeh and fermented protein categories face the steepest compliance engineering investments given their novel food classification thresholds.
Subscription meal kits are displacing conventional retail discovery for stir-fry and noodle preparation occasions. South Korean delivery platforms and Japanese precision-cooking services are consolidating buyer relationships through recurring revenue models. The pattern concentrates demand forecasting power with platform operators rather than brand manufacturers.
Vegan Asian Food Market Segmentation
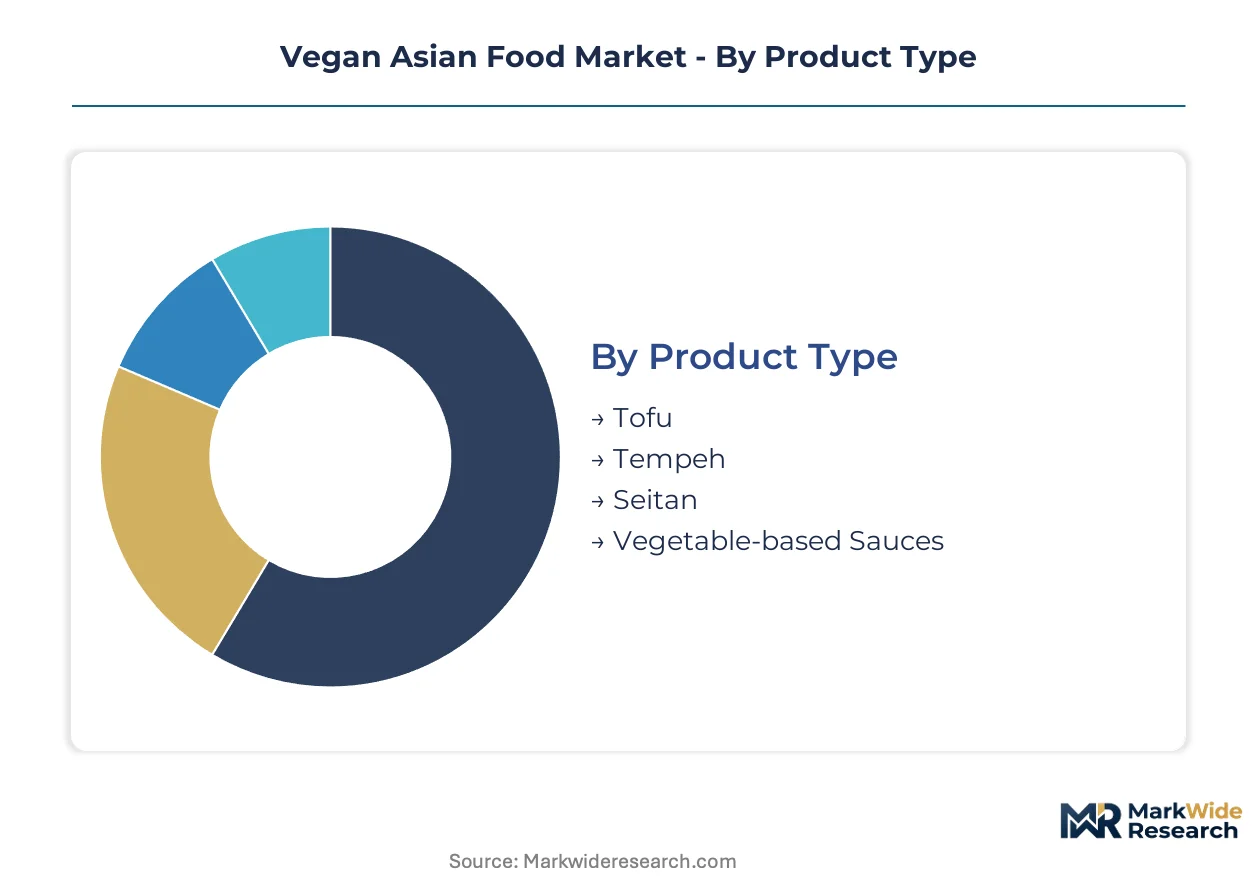
Segmentation in vegan Asian food reveals how protein format, preparation occasion, and purchase context reshape margin capture. Manufacturers must align R&D investment with the specific technical and regulatory demands of each slice.
Product Type:
After-sales service intensity varies sharply across protein formats, with fermented products requiring fermentation monitoring support and fresh tofu demanding cold-chain troubleshooting.
- Tofu:Soy-derived curd with 8-15% solids content coagulated through calcium sulfate or nigari precipitation. Household demand concentrates in South Korea and Japan where K-food globalisation drives premium fresh-block positioning; restaurants require firmness-graded SKUs for precision cutting applications.
- Tempeh:Whole-soybean fermentation using Rhizopus oligosporus cultures bound into compact cakes. European commercial foodservice operators drive adoption as EFSA novel food pathways gradually clarify; fermentation process certification timelines currently constrain EU market entry velocity.
- Seitan:Wheat gluten isolate processed through repeated washing and simmering to achieve fibrous texture.
- Vegetable-based Sauces:Fermented soybean, chili, and umami concentrates for home cooking and foodservice finishing.
Tofu holds the largest share; momentum sits with tempeh as regulatory clarity emerges.
End User:
Cost tier stratification separates mass-market household penetration from premium foodservice contracts with divergent specification rigor.
- Households:Retail consumers preparing stir-fry and noodle occasions at home. Supermarket and online retail channels capture this demand with convenience-oriented packaging formats; subscription meal kits are displacing conventional retail discovery in South Korea and Japan.
- Restaurants:Full-service operators requiring consistent portion control and authentic flavor replication. Sushi and dim sum applications reward precision with higher per-unit economics; high-moisture extrusion technology adoption is migrating to Asian dumpling manufacturers at pilot scale.
- Meal Delivery Services:Platform operators consolidating demand forecasting power through recurring revenue models. South Korean delivery platforms compress adoption timelines across multiple geographies.
- Cafes:Limited-service operators seeking grab-and-go vegan protein options for lunch occasions.
Restaurants hold the largest share; meal delivery services are expanding most quickly.
Distribution Channel:
Volume concentration in traditional retail is fragmenting as direct-to-consumer platforms capture margin pools previously absorbed by slotting fees.
- Online Retail:Direct-to-consumer and third-party marketplace sales bypassing conventional supermarket slotting constraints. Vegetable-based sauces capture expanding margin pools through premium positioning; REACH compliance documentation burdens filter supplier eligibility for EU-bound exporters.
- Supermarkets:Mass retail chains with established tofu and tempeh volume positions. Soy protein input volatility compresses margin predictability for manufacturers dependent on premium non-GMO soybean sourcing.
- Specialty Stores:Asian grocery and health-food retailers serving diaspora communities and committed vegan consumers.
- Farmers Markets:Local producer-direct sales with minimal packaging compliance overhead.
Supermarkets hold the largest share; online retail is gaining share fastest.
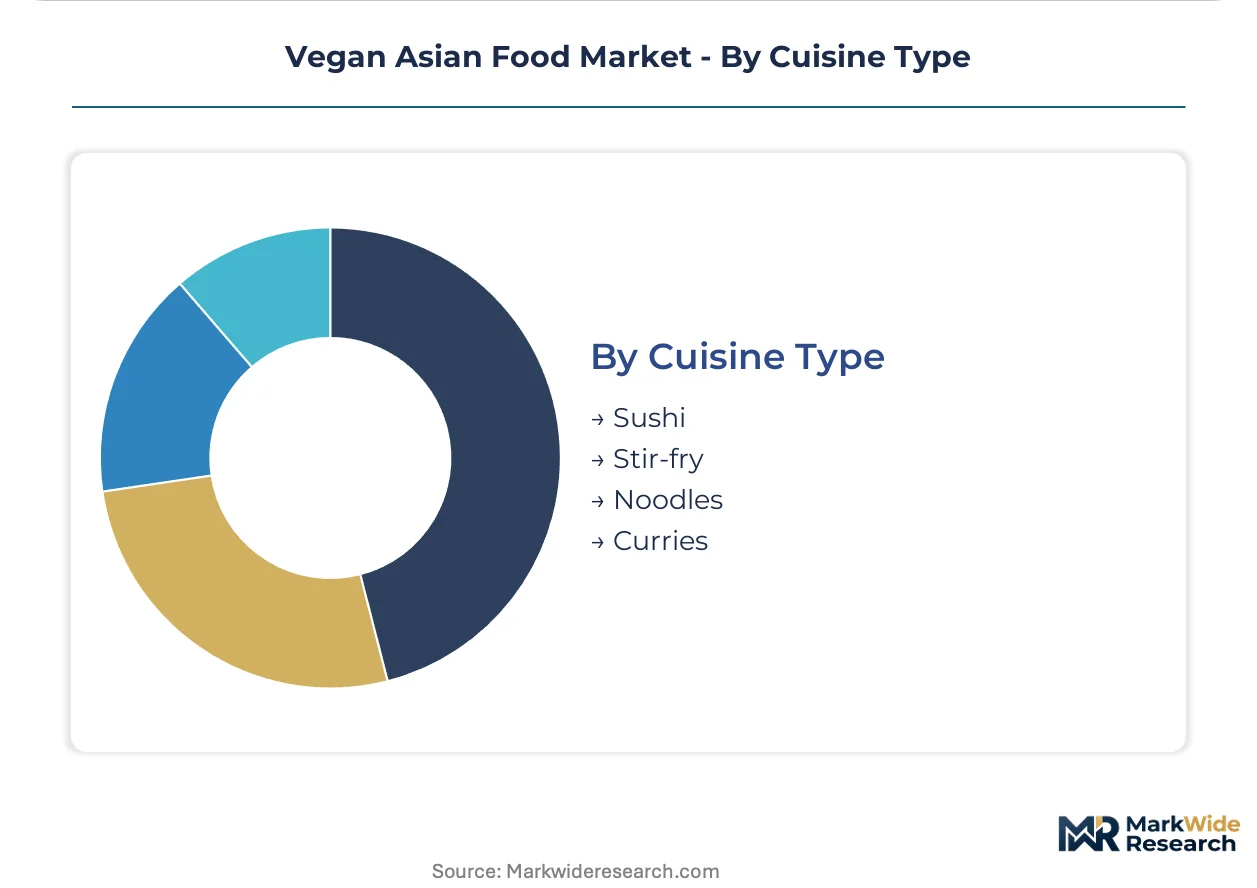
Cuisine Type:
Application maturity separates established household preparation formats from precision-dependent restaurant presentations with divergent equipment requirements.
- Sushi:Vinegared rice preparations with plant-based seafood and vegetable fillings. Restaurant and cafe segments lead due to precision presentation requirements; authentic flavor replication rewards compliant manufacturers with premium positioning.
- Stir-fry:High-heat wok preparations with cubed tofu or seitan strips. Household preparation occasions dominate; meal kit subscription models are consolidating buyer relationships through recurring revenue.
- Noodles:Wheat or rice noodle preparations with protein toppings and broth.
- Curries:Coconut or spice-based simmered preparations with tofu or tempeh integration.
Stir-fry holds the largest share; sushi shows the steepest expansion trajectory in foodservice channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal sustainability mandates and K-food globalisation are redrawing demand maps across the vegan Asian food sector. South Korea's domestic startup density and export-oriented meal delivery platforms are compressing adoption timelines. Regulatory divergence between FDA allergen thresholds and EFSA novel food assessments is fragmenting compliance pathways for exporters.
South Korea
Seoul-based vegan startups and K-food globalisation are accelerating category development faster than neighboring markets. MFDS fermentation process certifications and protein content thresholds shape domestic product approval timelines. The Seoul Capital Area concentrates meal delivery platform operators consolidating demand forecasting power through recurring revenue models.
United States
FDA GRAS determinations for soy and wheat proteins govern ingredient approval pathways for domestic manufacturers. Allergen labeling requirements for soy-derived tofu and seitan products multiply compliance engineering costs for exporters. California and New York Metro anchor retail discovery for vegetable-based sauces through specialty store networks and direct-to-consumer platforms.
Germany
REACH compliance documentation and EU Green Deal packaging mandates filter supplier eligibility for Asian exporters serving European commerce. EFSA novel food safety assessments for Rhizopus oligosporus-derived tempeh extend time-to-market for fermented protein categories. The Berlin-Brandenburg corridor hosts foodservice operators piloting high-moisture extrusion technology for dumpling applications.
Japan
METI sustainability frameworks and precision-cooking subscription services are consolidating buyer relationships in stir-fry and noodle preparation occasions. JIS standards for fermented plant proteins intersect with EFSA assessment frameworks for European-bound exports. The Kanto region around Tokyo anchors restaurant demand for sushi applications requiring authentic flavor replication.
United Kingdom
Post-Brexit regulatory divergence from EU novel food pathways is creating parallel compliance tracks for tempeh and fermented protein imports. FSA allergen thresholds for soy and wheat proteins differ from FDA and EFSA standards, multiplying label engineering costs. London and the Southeast concentrate meal kit subscription platforms displacing conventional retail discovery channels.
Vegan Asian Food Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented competitive boundaries. Asset-light licensing and co-manufacturing arrangements are fragmenting quality control accountability across distributed production networks. Three archetypes dominate: omnichannel brand architects, in-house craftsmanship specialists, and proprietary technology licensors. Capacity expansion and strategic partnerships represent the dominant competitive moves as players seek to secure premium ingredient sourcing relationships.
Within the omnichannel tier, Green Monday Group and OmniFoods exemplify brand architectures spanning retail and foodservice channels. Hodo Foods anchors the craftsmanship specialist position through California-based operations. These three companies occupy distinct strategic positions: one leverages multi-channel presence, another controls proprietary texturization capabilities, and the third emphasizes in-house production expertise.
| Leading Market Players |
|---|
| Green Monday Group |
| Immi |
| Unlimeat |
| Sanzo |
| Jack & Friends |
| Hodo Foods |
| Mekhala |
| BOBABAM |
| OmniFoods |
| Others |
Value Network & Pricing Analysis
Seoul Capital Area cold-chain infrastructure and K-food export platform density concentrate margin capture among Korean tofu and tempeh manufacturers serving European premium channels. Non-GMO soybean procurement costs and REACH packaging compliance investments feed directly into delivered price positioning for EU-bound shipments.
Pricing Analysis
Certification level (EFSA novel food clearance vs. standard export grade) creates the primary spread between European foodservice contracts and conventional retail SKUs. Three-tier pricing structure across premium, standard, and economy levels segments by protein format—tempeh commands fermentation process premiums, while tofu competes on volume scale. Price erosion runs through standard-grade supermarket SKUs as South Korean meal delivery platforms compress discovery economics. Restaurants and foodservice operators show least price sensitivity due to authentic flavor replication requirements.
Supply Chain Analysis
Tariff exposure between United States and China dominates input cost volatility for non-GMO soybean sourcing. Manufacturing concentrates in South Korea, Japan, and Indonesia for fermented protein formats; China and Vietnam anchor tofu and seitan processing. Raw material dependencies center on non-GMO soybeans, Rhizopus oligosporus cultures, and wheat gluten isolate. Single-source vulnerability in fermentation starter cultures threatens tempeh batch consistency. Distribution runs through Seoul-based meal delivery platforms consolidating last-mile economics with recurring revenue models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern demand forecasting power as South Korean delivery operators and Japanese precision-cooking services disintermediate conventional retail discovery. Interoperability between meal kit subscription infrastructure and co-manufacturing networks reconfigures competitive boundaries.
For Market Incumbents: Harden cold-chain custody capabilities and EFSA novel food certification pipelines against South Korean startup encroachment in European premium channels. Backward integration into non-GMO soybean sourcing secures margin predictability amid commodity volatility. Defensive capacity additions in Seoul Capital Area and Berlin-Brandenburg corridor anchor foodservice contract renewals. For New Entrants and Emerging Players: Establish a beachhead in tempeh fermentation process certification services for EU market entry acceleration. White-space targets include novel food compliance consulting and high-moisture extrusion equipment leasing for Asian dumpling manufacturers. Direct-to-consumer vegetable-based sauce positioning bypasses supermarket slotting constraints with premium margin capture. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified Asian food conglomerates with underperforming plant-based divisions and stranded fermentation assets. Long-term viability hinges on regulatory clearance velocity rather than brand equity accumulation. Watch EFSA assessment framework standardization timelines as inflection signal for European market entry valuations.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Certification Investment | Unlocks European foodservice premium positioning for Rhizopus oligosporus-derived tempeh formats. |
| High-Moisture Extrusion Technology Adoption | Enables fibrous texture replication in dumpling applications for restaurant channel penetration. |
| Meal Delivery Platform Partnership | Consolidates recurring revenue relationships through Seoul-based operator integration. |
| Non-GMO Soybean Supply Agreement | Secures input cost predictability against commodity volatility for tofu manufacturers. |
| Co-Manufacturing Quality Audit Program | Addresses fragmentation in asset-light licensing arrangements across distributed networks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with vegan foodservice procurement managers, plant-based R&D directors, fermentation process engineers, and meal delivery platform category buyers. Secondary validation drew from MFDS certification databases, EFSA novel food registers, customs trade flows for soy protein concentrates, and Seoul Capital Area cold-chain logistics disclosures. Bottom-up SKU volume builds and top-down category spend estimates were triangulated for convergence.
Calibration against historical adoption curves in adjacent plant-based protein categories anchored projection parameters across the analysis window. Segmentation dimensions modeled include protein format, preparation occasion, purchase context, and regulatory clearance tier. CAGRs were derived from slope-stability testing across multiple scenario bands. Fermentation process certification timelines and meal delivery platform subscriber conversion rates served as industry-specific forecast inputs.
Stress conditions across soybean commodity volatility, EFSA assessment duration variance, and platform operator consolidation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory divergence acceleration or substitution technology breakthroughs. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Europe Plant-Based Seafood Market
Plant Based Food
Plant Based Ice Cream Market
Plant Based Food
Plant-Based Natural Flavor Market
Plant Based Food
Global Plant Protein Market
Plant Based Food
Chicory Roots Market
Plant Based Food
United Kingdom Tofu Market
Plant Based Food
Europe Rice Protein Market
Plant Based Food
Plant-Based Meatballs Market
Plant Based Food
Singapore Plant-Based Food and Beverages Market
Plant Based Food
Lentil Protein Market
Plant Based Food
Plant Derived Proteins Market
Plant Based Food
Vegan Flour Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
North America Textured Vegetable Protein Market
Plant Based Food
Plant-Based Food and Beverages Market
Plant Based Food
China Rice Protein Market