
 India Pea Protein Market | 2026-2036
India Pea Protein Market Size, Share, and Industry Trends Forecast 2026-2036
India Pea Protein Market Foresight
Multi-source procurement from domestic and international yellow-pea suppliers is expanding across Indian food-ingredient manufacturers. Proeon Foods Pvt Ltd leverages its indigenous extraction technology to compete on cost and freshness against imports. Roquette India Pvt Ltd anchors its position through backward integration into European pea-protein supply chains. Cargill Inc sustains market relevance by controlling distribution networks that reach mid-tier food processors in western India.
Pea protein denotes the isolated or concentrated protein fraction extracted from Pisum sativum seeds through dry or wet milling followed by alkaline solubilization and isoelectric precipitation, typically yielding 80-90% protein content in isolate form for use as a functional emulsifier and gelling agent in formulated foods. The isolate segment dominates value capture due to superior amino-acid completeness and solubility profiles demanded by premium nutritional-supplement brands. Textured pea protein occupies the fastest-expanding application niche as plant-based meat analogues gain shelf space in Indian retail. Sports nutrition within the end-user dimension leads volume offtake, though vegan-consumer targeting generates higher per-unit margins through specialized branding.
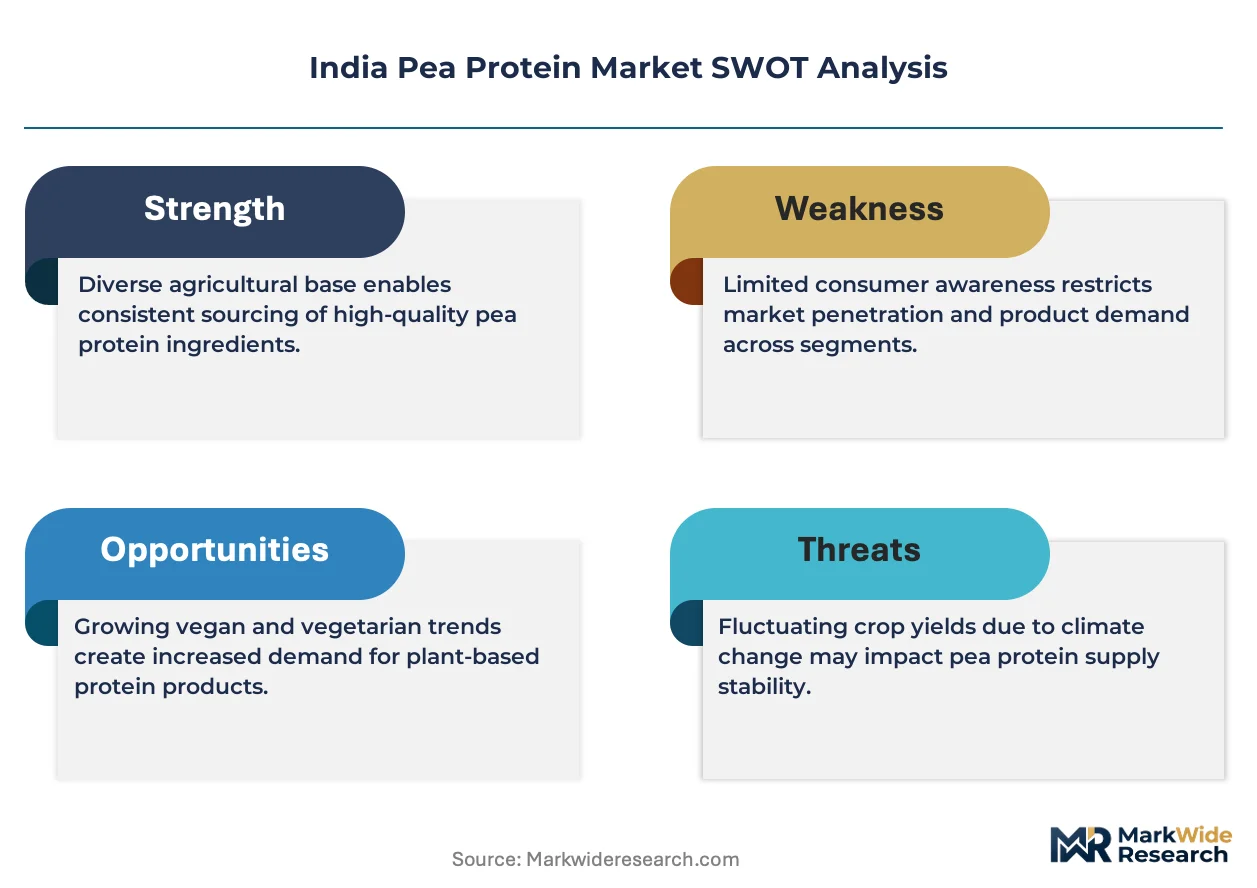
FSSAI mandates protein-content declarations and purity thresholds that directly influence formulation choices by domestic manufacturers. BIS standards for food-grade plant proteins intersect with DGFT import tariff structures to shape the landed cost of raw yellow-pea concentrate. CDSCO oversight of protein-based nutritional supplements adds a compliance layer for products crossing into pharmaceutical-channel distribution. Stakeholders must monitor how state-level food-processing subsidies in Gujarat and Maharashtra alter the economics of domestic extraction capacity versus import dependence.
Market Dynamics
Domestic extraction capacity expansion in Maharashtra and Gujarat is compressing import dependence for yellow-pea concentrate, while FSSAI protein-labeling mandates force reformulation transparency across sports-nutrition and plant-based-meat portfolios.
Growth Catalysts
- Processing-cluster subsidies:Gujarat and Maharashtra state food-processing incentives reduce capital-recovery timelines for indigenous extraction facilities, drawing contract manufacturers toward western India.
- FSSAI protein-content mandates:Standardized declaration requirements elevate isolate-grade products in premium nutritional-supplement channels, rewarding suppliers with certified purity thresholds.
- Textured-protein formulation advances:Wet-extraction improvements in gelling and fibrous-structure replication accelerate plant-based-meat-analogue adoption by quick-service restaurant chains.
Market Restraints
- Yellow-pea import concentration:DGFT tariff structures on raw concentrate from Canada and Ukraine expose processors to currency and trade-policy volatility.
- Technical solubility limitations:Native pea-protein foaming and emulsion-stability deficits restrict application in beverage systems without enzymatic modification.
- CDSCO supplement-channel friction:Protein-based nutritional products crossing into pharmaceutical distribution face extended approval timelines and clinical-evidence requirements.
Strategic Opportunities
- Tier-two city retail penetration:Organized modern-trade expansion in Pune, Ahmedabad, and Surat creates shelf-space access for branded plant-protein products beyond Mumbai and Delhi.
- BIS-ISO harmonization:Alignment of domestic food-grade plant-protein standards with international certification opens export pathways to Middle Eastern and Southeast Asian markets.
- Pulse-protein blending convergence:Pea-rice and pea-mung protein combinations address amino-acid-completeness gaps, enabling clean-label positioning in pediatric and geriatric nutrition.
Industry Challenges
- Specialized extraction-technician scarcity:Wet-milling and isoelectric-precipitation expertise concentrates with European equipment vendors, inflating commissioning and maintenance costs for domestic facilities.
- Multi-regulator compliance layering:Simultaneous FSSAI food-safety, BIS quality-mark, and CDSCO therapeutic-claim navigation extends product-launch timelines and legal-review expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Pea Protein Market |
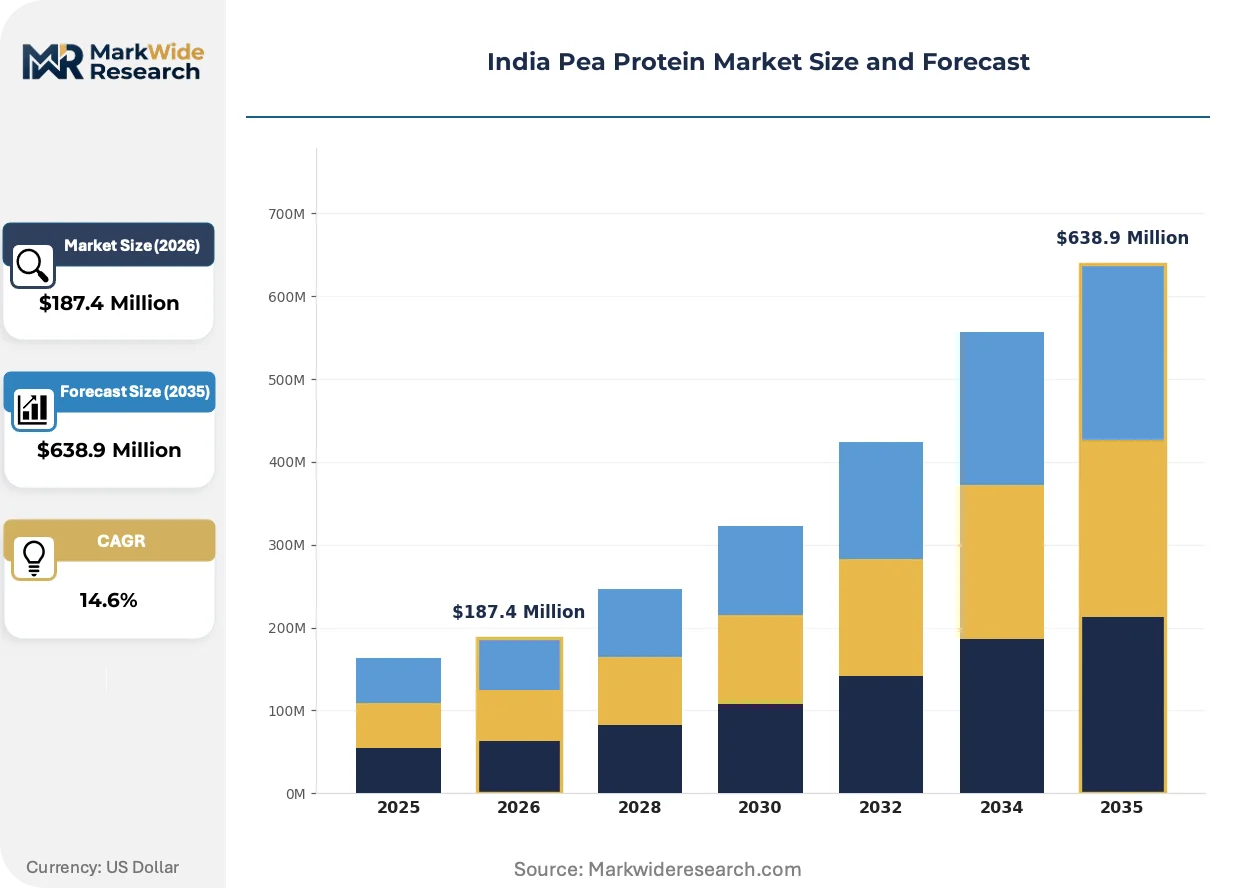
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Textured, Flour Application: Food & Beverages, Nutritional Supplements, Animal Feed, Bakery Products End User: Sports Nutrition, Vegan Consumers, Health-Conscious Individuals, Food Manufacturers Form: Powder, Granules, Liquid, Solid |
| Companies Covered | Ingredion India Pvt Ltd, Proeon Foods Pvt Ltd, Archer Daniels Midland Company, Prot, RELSUS, Cargill Inc, Titan Biotech Ltd, Shandong Jianyuan Group, Roquette India Pvt Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Pea Protein Market Shifts & Advancements
Enzymatic modification and fermentation-assisted extraction are reshaping functional-performance benchmarks, while regulatory clarity and channel evolution compress go-to-market cycles for differentiated protein ingredients.
Enzymatic hydrolysis of pea-protein isolates is electrifying solubility and digestibility profiles for high-protein beverage applications. Sports-nutrition formulators in Mumbai and Bangalore are adopting hydrolyzed grades at accelerating pace, displacing unmodified concentrates in ready-to-drink portfolios. This enzymatic shift is compressing the performance gap between plant and dairy proteins in premium recovery-product positioning.
FSSAI's evolving protein-labeling norms mandate quantitative amino-acid profiling and allergen cross-contamination thresholds for plant-protein products. Domestic manufacturers must revalidate analytical methods and supplier documentation to maintain compliance, with isolate-grade suppliers facing the heaviest documentation burden. Maharashtra-based processors are responding by investing in in-house HPLC amino-acid analysis capabilities to accelerate batch-release decisions.
Direct-procurement relationships between food-ingredient manufacturers and Maharashtra and Gujarat processing clusters are shortening supply chains for mid-tier brands. Traditional import-distributor intermediaries serving western Indian food processors are losing volume to contracted domestic supply agreements. This channel restructuring is most visible in the plant-based-meat-analogue segment, where freshness and lot-traceability requirements favor localized sourcing.
India Pea Protein Market Segmentation
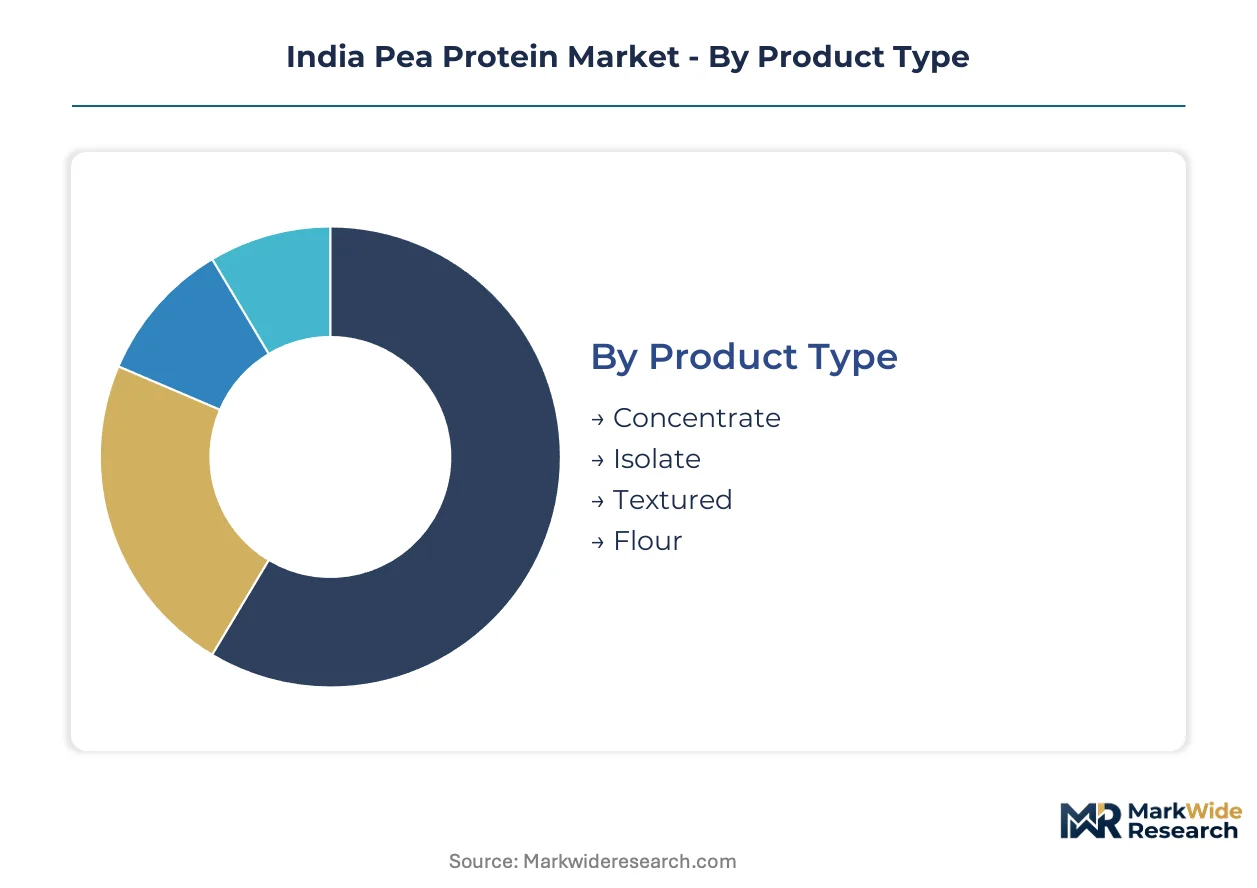
Segmentation reveals how pea protein migrates across distinct value tiers in India. Product-grade differentiation, application-specific formulation requirements, and end-user purchasing behavior create divergent margin profiles that suppliers must navigate simultaneously.
Product Type:
Upgrade cycles from concentrate to isolate grades accelerate as FSSAI purity mandates tighten and premium nutritional brands demand certified amino-acid completeness.
- Isolate:Refined through isoelectric precipitation to achieve 80-90% protein content with superior solubility and emulsification properties. Maharashtra-based sports-nutrition formulators in Mumbai and Pune drive volume offtake, with FSSAI protein-content declarations elevating certified isolate in premium supplement channels.
- Textured:Extruded pea protein engineered to replicate fibrous meat structures through thermomechanical processing. Quick-service restaurant chains in Gujarat expand procurement as plant-based-meat-analogue shelf space widens in Ahmedabad and Surat retail.
- Concentrate:Intermediate protein fraction retaining more starch and fiber, serving cost-sensitive bakery and processed-food applications across western India.
- Flour:Minimally processed whole-pea powder with protein content below 50%, finding use in traditional Indian snack fortification and regional bakery formulations.
Volume placements concentrate in Isolate; the faster expansion belongs to Textured.
Application:
Cost-tier stratification separates commodity feed applications from pharmaceutical-grade supplement channels with tenfold price differentials.
- Nutritional Supplements:High-specification isolate and hydrolyzed grades for protein powders, bars, and ready-to-drink recovery formulations. CDSCO oversight of therapeutic claims adds compliance friction for products crossing into pharmaceutical distribution, compressing go-to-market timelines for Mumbai and Bangalore brands.
- Food & Beverages:Functional emulsifier applications spanning dairy alternatives, high-protein beverages, and meat extenders. Enzymatic modification addresses native solubility limitations that otherwise restrict beverage-system adoption.
- Bakery Products:Concentrate and flour grades for protein fortification of bread, biscuits, and traditional Indian baked goods, with Gujarat processing clusters supplying mid-tier contract manufacturers.
- Animal Feed:Lowest-cost concentrate and processing byproducts for poultry and aquaculture nutrition, competing with soy and cottonseed meal on price-per-protein-unit metrics.
Revenue concentrates in Nutritional Supplements; margin expansion is steepest in Food & Beverages as enzymatic modification unlocks premium beverage positioning.
End User:
Customer-type divergence creates parallel demand tracks: institutional bulk procurement versus branded retail premiumization.
- Sports Nutrition:Athletes and fitness enthusiasts demanding 20-30g protein servings with complete amino-acid profiles and rapid digestibility. This segment generates the highest absolute volumes through Mumbai, Delhi, and Bangalore gym-channel distribution.
- Vegan Consumers:Ethical and environmental motivation drives willingness-to-pay premiums for certified plant-origin products with supply-chain traceability documentation.
- Health-Conscious Individuals:Middle-income households seeking protein fortification for general wellness, price-sensitive and responsive to modern-trade promotional activity in tier-two cities.
- Food Manufacturers:Industrial buyers integrating pea protein as cost-reduction or clean-label replacement for soy and wheat gluten in processed-food formulations.
Absolute volume leadership sits with Sports Nutrition; per-unit margin expansion is fastest among Vegan Consumers.
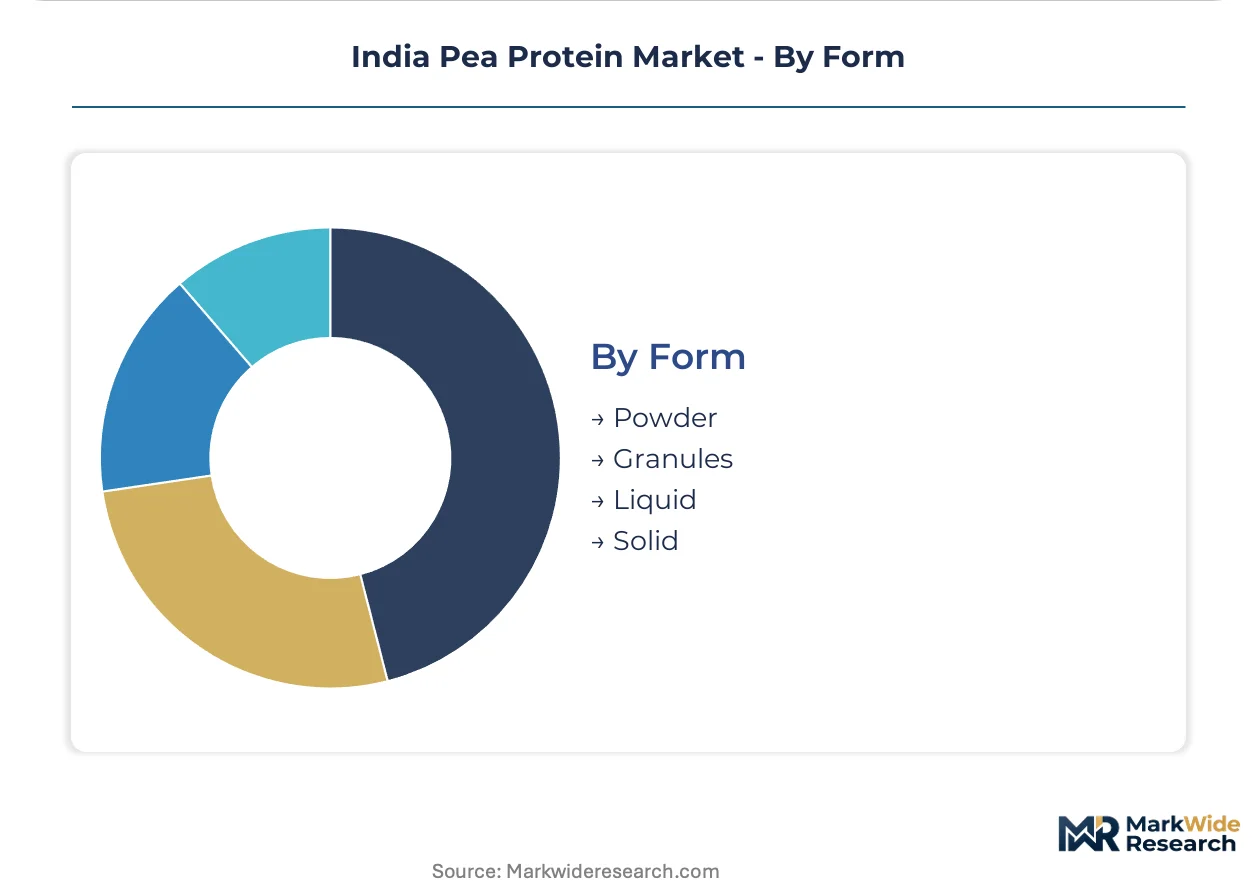
Form:
Supply-concentration effects favor powder processing in Maharashtra and Gujarat clusters, while liquid and solid forms require specialized downstream capabilities.
- Powder:Dominant format enabling precise dosing, extended shelf stability, and efficient logistics for nutritional supplements and ingredient manufacturing. Dry-milling and spray-drying capacity concentrates in Surat and Ahmedabad processing zones.
- Liquid:Pre-hydrated protein suspensions for ready-to-drink beverages and industrial food processing, constrained by cold-chain requirements and shorter shelf life that limit geographic reach from production points.
- Granules:Intermediate texture for specific meat-analogue extrusion processes and controlled-release supplement applications.
- Solid:Compressed or extruded forms including protein bars and textured chunks, requiring additional forming equipment and binding-agent formulation expertise.
Processing infrastructure concentrates in Powder; format innovation is expanding fastest in Liquid as beverage brands seek differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for pea protein concentrates in Maharashtra and Gujarat food-processing clusters outpaces supply from domestic extraction facilities, forcing mid-tier brands to maintain parallel import channels from Canadian and Ukrainian yellow-pea suppliers.
Maharashtra
Mumbai and Pune sports-nutrition formulators drive isolate-grade volume offtake as gym-channel distribution expands. FSSAI protein-content declaration mandates elevate certified products in premium supplement channels. Ambernath and Taloja industrial zones host wet-milling extraction facilities commissioned by domestic ingredient manufacturers seeking import substitution.
Gujarat
Ahmedabad and Surat quick-service restaurant chains accelerate textured-pea-protein procurement for plant-based-meat-analogue menu items. State food-processing subsidies under the Gujarat Industrial Policy reduce capital-recovery timelines for indigenous extraction investments. Sanand and Vadodara processing clusters attract contract manufacturers from pan-Indian food brands seeking western India supply-chain proximity.
Karnataka
Bangalore sports-nutrition brands adopt enzymatically modified hydrolyzed grades for ready-to-drink recovery portfolios. CDSCO oversight of therapeutic protein claims creates compliance friction for products crossing into pharmaceutical-channel distribution. Peenya Industrial Area hosts formulation facilities serving southern Indian modern-trade retail expansion.
Delhi-NCR
Health-conscious households in Gurugram and Noida generate price-sensitive demand for protein-fortified traditional snacks and bakery applications. BIS quality-mark requirements intersect with DGFT import tariff structures to shape landed costs for raw concentrate. Okhla and Faridabad ingredient distributors serve northern Indian processed-food manufacturers.
Tamil Nadu
Chennai-based vegan-consumer brands command per-unit margin premiums through certified plant-origin positioning with supply-chain traceability documentation. State-level food-processing incentives under Tamil Nadu Industrial Policy attract extrusion equipment investments for textured-protein manufacturing. Sriperumbudur and Oragadam industrial corridors host emerging contract manufacturing capacity for export-oriented plant-protein ingredients.
India Pea Protein Market Competitive Landscape
Capacity expansion dominates the current landscape as domestic extraction facilities multiply across western India processing clusters. The vendor base stratifies into three tiers: multinational ingredient suppliers with backward integration into global supply chains, indigenous technology specialists competing on extraction cost and freshness, and import-dependent distributors serving cost-sensitive mid-tier processors. Strategic archetypes include European-anchored majors leveraging supply-chain control, domestic technology innovators, and trading houses managing tariff-exposed concentrate flows. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with state subsidy capture and FSSAI certification acceleration as secondary vectors.
Among multinational ingredient suppliers, Roquette India Pvt Ltd and Cargill Inc exemplify the European-anchored archetype through supply-chain integration advantages. Proeon Foods Pvt Ltd occupies a position within the indigenous technology tier, representing domestic extraction innovation. These three entities anchor the competitive structure without exhausting its diversity, as regional trading specialists and emerging domestic processors populate adjacent market positions.
| Leading Market Players |
|---|
| Ingredion India Pvt Ltd |
| Proeon Foods Pvt Ltd |
| Archer Daniels Midland Company |
| Prot |
| RELSUS |
| Cargill Inc |
| Titan Biotech Ltd |
| Shandong Jianyuan Group |
| Roquette India Pvt Ltd |
| Others |
Supply & Pricing Matrix
Yellow-pea futures on Canadian commodity exchanges cascade through DGFT tariff structures into three distinct pricing tiers for Indian processors, with landed concentrate costs compressing margins for import-dependent mid-tier brands while state-subsidized domestic extraction in Gujarat and Maharashtra enables sharper pricing discipline.
Pricing Analysis
Volume leadership concentrates in concentrate grades for cost-sensitive bakery and feed applications, while margin capture concentrates in isolate and hydrolyzed grades for sports-nutrition channels. Three-tier pricing structure across premium certified-isolate, standard food-grade concentrate, and economy feed-grade flour segments reflects FSSAI certification burden and amino-acid completeness testing. Pricing pressure stems from currency volatility on Canadian and Ukrainian raw-material imports, with Mumbai-based sports-nutrition brands showing least price sensitivity and northern Indian snack manufacturers exhibiting highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Canadian and Ukrainian yellow-pea concentrate suppliers, where DGFT tariff exposure and currency fluctuation create procurement uncertainty for Indian processors. Domestic extraction draws from Maharashtra and Gujarat state food-processing subsidies, while wet-milling equipment and isoelectric-precipitation expertise rest on European vendor relationships. Tariff exposure on raw concentrate imports constitutes the dominant structural risk. Distribution runs through Ambernath and Taloja industrial zones for western India, with Peenya Industrial Area serving southern markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FSSAI protein-content declaration mandates and CDSCO therapeutic-claim oversight erect a cost-of-compliance moat that rewards incumbent players with certified in-house analytical capabilities while filtering undercapitalized entrants from premium channels.
For Market Incumbents: Deepen backward integration into Maharashtra and Gujarat processing clusters to capture state subsidy flows and compress import dependence on Canadian yellow-pea concentrate. Accelerate HPLC amino-acid analysis certification to exploit FSSAI documentation burdens that disadvantage smaller competitors. Threat substitution from enzymatically modified rice and mung protein blends requires rapid clean-label positioning in pediatric and geriatric nutrition portfolios. For New Entrants and Emerging Players: Capture tier-two city retail penetration in Pune, Ahmedabad, and Surat where modern-trade shelf space remains undercontested by established Mumbai and Delhi brands. Target textured-pea-protein supply agreements with Gujarat quick-service restaurant chains seeking localized sourcing for plant-based-meat-analogue menu expansion. Go-to-market angle emphasizes lot-traceability documentation and freshness premiums against import-dependent distributors. For Investors and Strategic Acquirers: Distressed-cycle entries favor wet-milling extraction specialists with commissioned Maharashtra or Gujarat facilities and pending FSSAI certification pathways. Long-term viability hinges on BIS-ISO harmonization enabling Middle Eastern and Southeast Asian export expansion. Signal to watch: state-level food-processing subsidy renewal intensity in Gujarat Industrial Policy negotiations as inflection indicator for domestic capacity economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Domestic Extraction | Maharashtra and Gujarat state subsidies compress capital-recovery timelines for indigenous wet-milling capacity. |
| FSSAI Certification Acceleration | In-house HPLC amino-acid analysis capabilities expedite batch-release decisions for isolate-grade suppliers. |
| Enzymatic Modification Investment | Hydrolyzed grade production unlocks ready-to-drink beverage applications previously restricted by solubility deficits. |
| Tier-Two City Distribution Expansion | Pune, Ahmedabad, and Surat modern-trade penetration captures price-sensitive health-conscious household demand. |
| Pulse-Protein Blending Convergence | Pea-rice and pea-mung combinations address amino-acid-completeness gaps for pediatric and geriatric clean-label positioning. |
Research Methodology
FSSAI regulatory filings, DGFT customs records, and BIS quality-mark databases formed the secondary backbone, cross-referenced with primary interviews involving extraction-technology vendors, sports-nutrition formulators, and Gujarat-based contract manufacturers. Bottom-up triangulation across product-grade volume flows and top-down validation against state-level food-processing subsidy disbursements anchored the analytical framework.
Historical trendline analysis of isolate and concentrate grade pricing trajectories informed projection modeling across the forecast period, with segmentation dimensions spanning product type, application tier, end-user archetype, and regional processing cluster. CAGRs were derived from fitted growth curves applied to validated baseline estimates, incorporating enzymatic modification adoption rates and textured-protein extrusion capacity expansion as industry-specific inputs.
The model holds under stable DGFT tariff structures and continued FSSAI enforcement intensity; deviation in Canadian yellow-pea export policy or Maharashtra subsidy renewal would shift capacity economics and pricing tier boundaries. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Organic Rice Protein Market
Plant Based Food
Plant-Based Fish Market
Plant Based Food
Europe Plant-Based Seafood Market
Plant Based Food
Australia Plant Protein Market
Plant Based Food
Indonesia Plant-Based Food and Beverages Market
Plant Based Food
Global Plant Protein Market
Plant Based Food
Europe Pea Protein Market
Plant Based Food
Plant-Based Burger Market
Plant Based Food
Plant Based Supplement Market
Plant Based Food
Vegan Meat Alternatives Market
Plant Based Food
Vegan Drink Mixes Market
Plant Based Food
India Plant Based Meat Alternatives Market
Plant Based Food
Global Plant Based Milk Market
Plant Based Food
Plant Based Tuna Market
Plant Based Food
Vegan Marshmallows Market
Plant Based Food
Soy- Based Food Market