
 Vegan Drink Mixes Market | 2026-2036
Vegan Drink Mixes Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Drink Mixes Market Analytics
Fitness professionals is rotating toward bulk and subscription purchasing, displacing casual health enthusiasts as the dominant buyer archetype in institutional channels. Orgain leverages its organic supply chain to sustain pharmacy and club-store placement across North America. Vega anchors the premium sports-nutrition segment through extensive athlete ambassador programs and third-party certifications. Garden of Life differentiates via non-GMO and regenerative agriculture messaging that commands shelf-space premiums in natural retail.
Vegan drink mixes comprise shelf-stable powdered or granulated formulations derived entirely from plant sources, typically processed through spray-drying or freeze-drying to preserve bioactive compounds and achieve solubility in water or plant-based milk alternatives. These products serve commercial and consumer markets seeking convenient protein supplementation, hydration support, or micronutrient fortification without animal-derived inputs. Protein powders dominate current revenue pools due to established gym-channel penetration and higher per-unit pricing, while electrolyte powders represent the fastest-expanding category as endurance athletes shift from conventional sports drinks to mineral formulations free of artificial coloring and animal-derived processing aids. Ready-to-drink formats remain nascent but attract venture investment because of their convenience premium and direct-to-consumer shipping economics.
The FDA exercises jurisdiction over plant-protein health claims and facility registration, while the USDA Organic seal governs ingredient sourcing standards that many buyers treat as non-negotiable. The EU's EFSA evaluates novel protein sources such as algae and fermented legume isolates for safety prior to market authorization, creating a multi-year lag for innovative entrants. Stakeholders must monitor evolving positions from China's SAMR on imported plant-protein labeling, as any mandatory origin-disclosure rule would reshape sourcing strategies for brands reliant on Asian pea-protein supply bases.
Market Dynamics
Fitness professionals now dominate institutional procurement, rotating purchasing patterns toward bulk and subscription models that displace casual health enthusiasts as the primary volume driver.
Growth Catalysts
- EU Novel Food Regulation:Tightened purity standards elevate consumer trust in certified plant-protein products, accelerating pharmacy-channel placement across Germany and adjacent markets.
- Spray-drying technology:Advanced dehydration methods preserve bioactive compounds in pea and rice isolates, enabling cleaner-label formulations that command shelf-space premiums.
- Endurance athletics:Marathon and triathlon training programs institutionalize electrolyte powder protocols, creating recurring demand cycles absent from casual fitness segments.
Market Restraints
- Pea-protein supply concentration:Asian processing facilities control upstream isolate supply, exposing brands to origin-disclosure risks under evolving SAMR import rules.
- Algae protein approval lag:EFSA's multi-year novel food evaluation timeline blocks innovative entrants from European commercialization.
- Freeze-drying capex intensity:Capital equipment requirements for low-temperature processing limit mid-scale manufacturer participation.
Strategic Opportunities
- Pharmacy channel expansion:German clean-label positioning demonstrates replicable placement models for sports-nutrition products in regulated retail environments.
- Direct-to-consumer subscription:Venture-backed ready-to-drink formats exploit shipping economics to bypass traditional gym-channel gatekeepers.
- Regenerative agriculture certification:USDA Organic and emerging soil-health standards create differentiation vectors beyond basic non-GMO claims.
Industry Challenges
- Third-party certification backlog:NSF Certified for Sport and Informed Sport queue times delay product launches by six to twelve months.
- Plant-protein formulator talent scarcity:Food science programs lack specialized training in solubility optimization for multi-source vegan blends.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Drink Mixes Market |
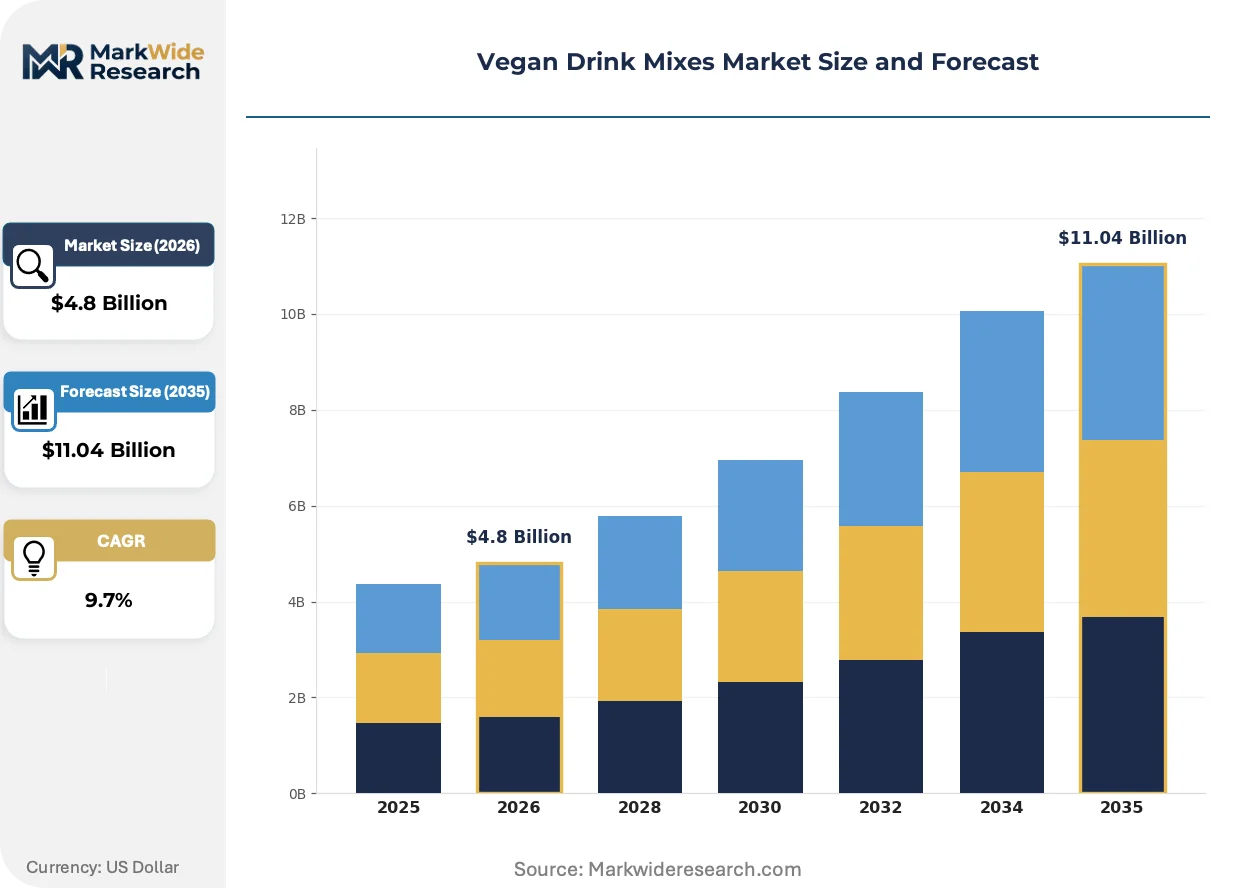
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Powders, Smoothie Mixes, Flavor Enhancers, Electrolyte Powders End User: Health Enthusiasts, Athletes, Vegan Consumers, Fitness Professionals Form: Powder, Liquid, Granules, Ready-to-Drink Flavor: Chocolate, Vanilla, Berry, Tropical |
| Companies Covered | Sunwarrior, Sunwink, Vega, Plant Fusion, Aloha, Orgain, Amazing Grass, Nuzest, Garden of Life, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Drink Mixes Market Evolving Landscape
Formulation science and regulatory positioning are compressing development cycles while channel structures fragment toward direct and specialized retail.
Precision fermentation of fungal and bacterial protein isolates is miniaturizing production footprints, enabling distributed manufacturing near demand centers. Boutique sports-nutrition brands adopt these systems to reduce freight costs and freshness windows. The technology is miniaturizing economies of scale that previously favored centralized Asian processing hubs.
EFSA's evolving stance on fermented legume isolates is tightening safety documentation requirements for novel protein submissions. European brands now front-load toxicology studies to preempt authorization delays. Germany's pharmacy-dominant retail structure feels this most acutely, as clean-label positioning depends on regulatory certainty.
Bulk purchasing contracts now displace individual supplement transactions in collegiate and professional athletic programs. Club stores and direct-procurement platforms capture volume previously flowing through specialty retailers. This concentration is most visible across North American Division I programs and private training facilities.
Vegan Drink Mixes Market Segmentation
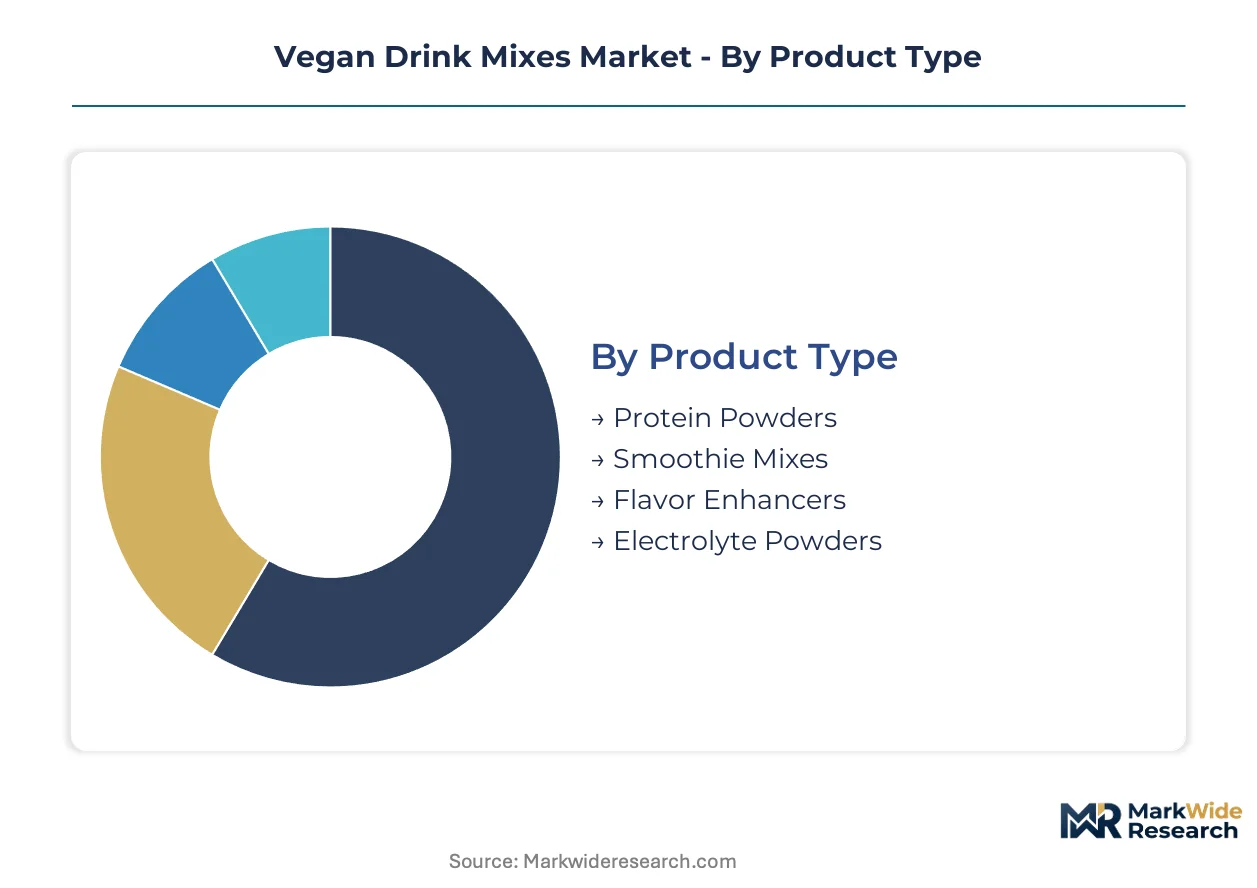
Segmentation in vegan drink mixes reveals where substitution pressure concentrates and which buyer archetypes command pricing power. Understanding these divides exposes vulnerability to conventional sports nutrition and dairy-based alternatives.
Product Type:
Protein powders face the most intense substitution threat from whey and casein formulations, while electrolyte powders operate in a less contested functional space.
- Protein Powders:Spray-dried isolates from pea, rice, and hemp deliver 15-25g protein per serving with complete amino acid profiles. Demand clusters in North American gym channels where NSF Certified for Sport status determines institutional procurement. EFSA's evolving plant-protein health claim standards constrain European positioning.
- Electrolyte Powders:Mineral formulations replace sodium, potassium, and magnesium without artificial coloring or animal-derived processing aids. Marathon and triathlon training programs in Germany institutionalize these protocols, creating recurring bulk purchasing cycles absent from casual fitness segments.
- Smoothie Mixes:Blended formulations combining protein, fiber, and micronutrients for meal-replacement applications target time-constrained professionals.
- Flavor Enhancers:Clean-label sweeteners and natural extracts modify base formulations without caloric load.
Protein powders anchor the volume base while electrolyte powders gain share at the steepest rate.
End User:
Cost tier stratification separates institutional buyers with subscription purchasing power from discretionary consumers.
- Fitness Professionals:Trainers, coaches, and physical therapists rotate procurement toward bulk and subscription models that displace individual transactions. Collegiate athletic programs and private training facilities in the United States concentrate demand through direct-procurement platforms.
- Athletes:Endurance competitors and strength athletes require third-party certified formulations for competition compliance. Germany's pharmacy-channel placement prioritizes these buyers through clean-label positioning.
- Health Enthusiasts:Casual wellness seekers drive trial purchases through specialty retail and e-commerce.
- Vegan Consumers:Ethical and environmental motivation sustains loyalty premiums independent of performance claims.
Fitness professionals concentrate procurement volume while athletes sustain the highest per-unit pricing tier.
Form:
Supply concentration in Asian spray-drying facilities shapes which formats achieve cost-competitive scale.
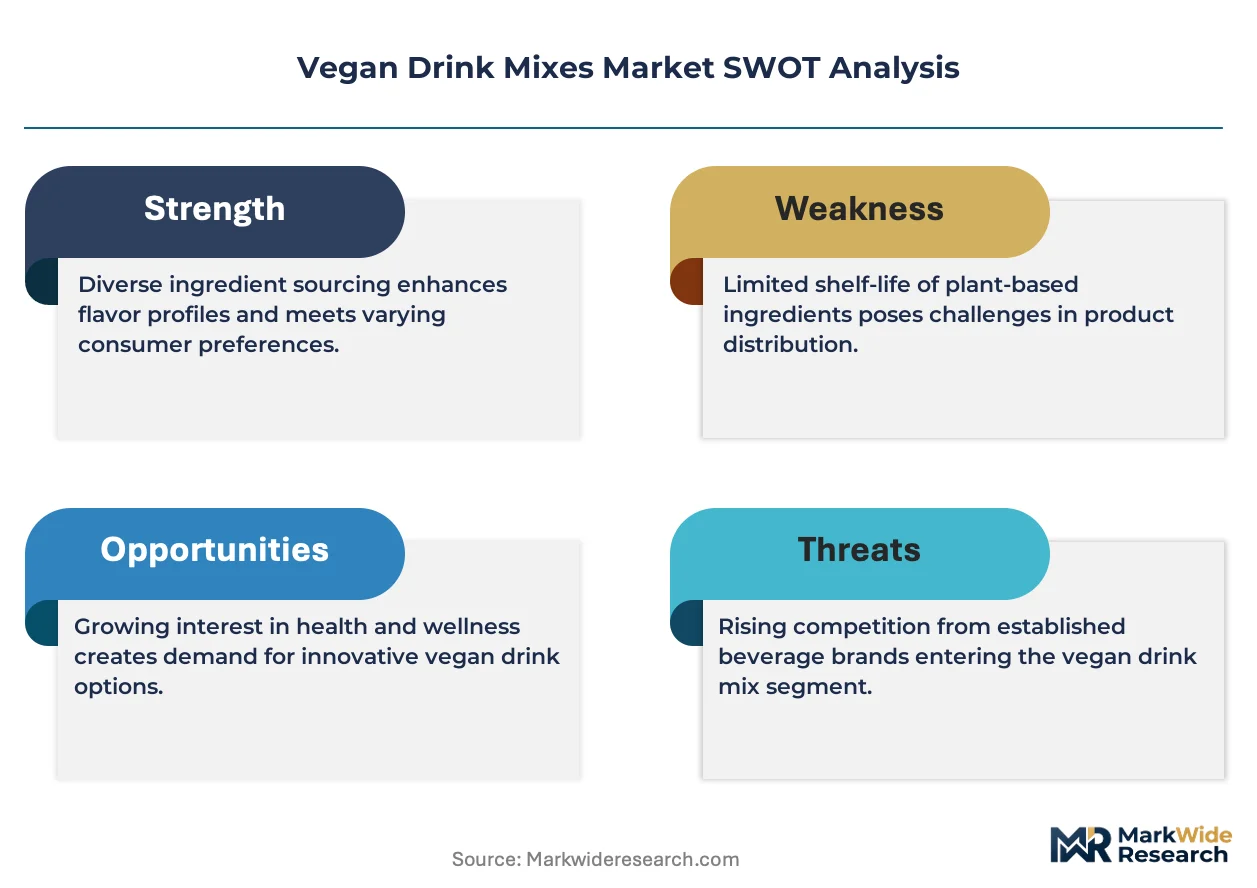
- Powder:Shelf-stable formulations processed through spray-drying or freeze-drying preserve bioactive compounds and achieve solubility in water or plant-based milk alternatives. This format dominates current revenue pools due to established gym-channel penetration and favorable shipping economics.
- Ready-to-Drink:Pre-mixed beverages attract venture investment for direct-to-consumer subscription models that bypass traditional retail gatekeepers. Freeze-drying capex intensity limits mid-scale manufacturer participation in comparable powder alternatives.
- Liquid:Concentrates requiring dilution reduce shipping weight but complicate storage stability.
- Granules:Agglomerated particles improve dispersibility in cold liquids for on-the-go applications.
Powder formats retain the installed demand base while ready-to-drink climbs the fastest on convenience premiums.
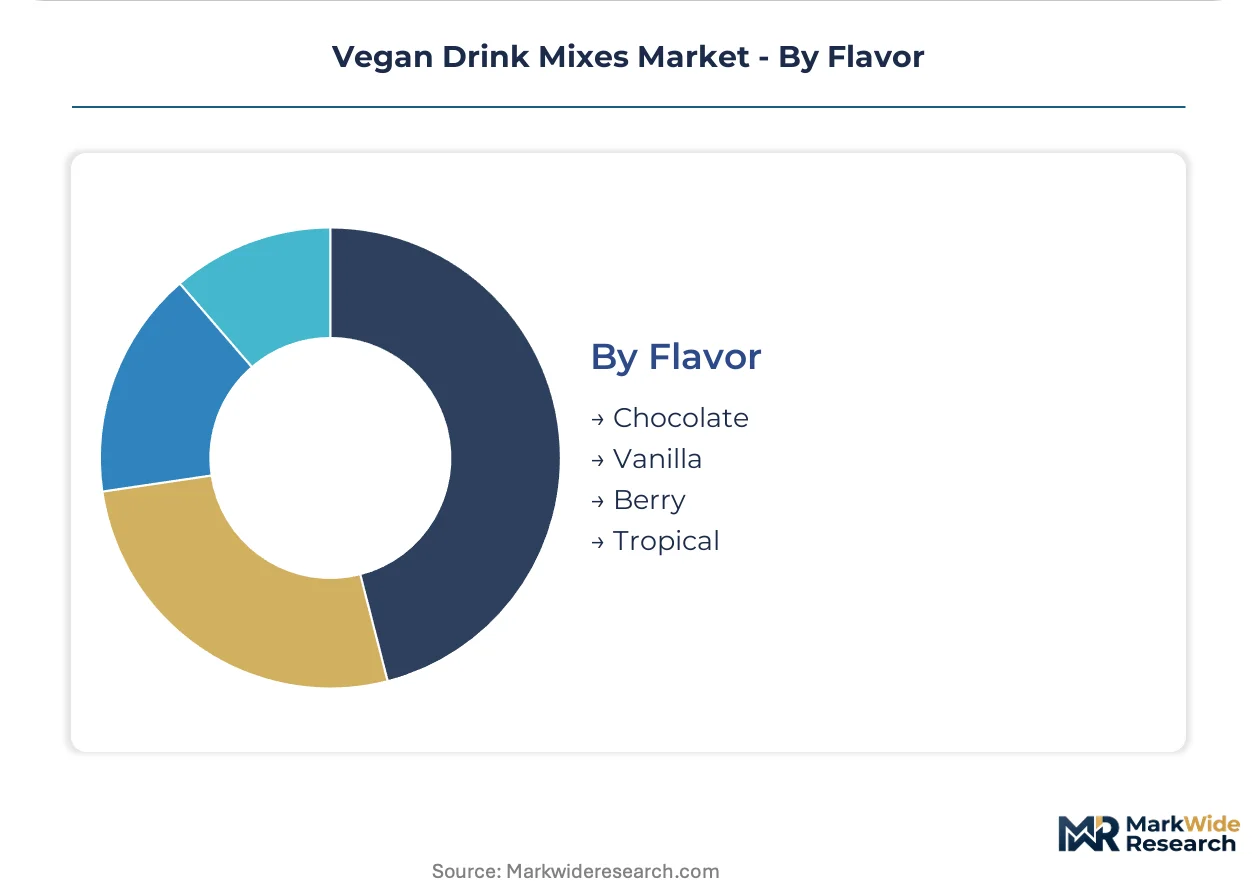
Flavor:
Application context determines whether familiar profiles or exotic positioning drives repeat purchase.
- Chocolate:Cocoa-based formulations leverage established palatability expectations from conventional protein supplements. North American club stores and pharmacy channels allocate premium shelf space to organic-certified variants.
- Vanilla:Neutral profiles serve as base layers for custom blending in smoothie applications. German clean-label positioning favors natural vanilla extract over synthetic vanillin.
- Berry:Acai, blueberry, and mixed berry profiles target antioxidant messaging in sports recovery positioning.
- Tropical:Mango, pineapple, and coconut variants differentiate in saturated protein powder aisles through vacation-associated sensory cues.
Chocolate and vanilla sustain the core repeat-purchase base while tropical profiles expand most quickly through novelty-seeking trial.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's dominance in European plant-protein distribution, while the Los Angeles-Long Beach port complex anchors North American import flows for pea-protein isolates.
United States
Fitness professionals and collegiate athletic programs drive institutional procurement through bulk subscription platforms. The FDA's plant-protein health claim guidelines and facility registration requirements shape formulation standards. Greater Los Angeles concentrates venture-backed ready-to-drink startups exploiting direct-to-consumer shipping economics.
Germany
Clean-label vegan sports nutrition commands premium shelf positioning across pharmacy and specialty retail channels. The EU's Novel Food Regulation and EFSA safety evaluations constrain novel protein authorization timelines. Berlin and Munich anchor the pharmacy-dominant retail structure where third-party certified products secure placement.
China
Asian processing facilities control upstream pea-protein isolate supply for global brands. SAMR's evolving import labeling rules threaten origin-disclosure requirements that would reshape sourcing strategies. Yangtze River Delta manufacturing clusters dominate spray-drying capacity for export markets.
United Kingdom
Endurance athletics and marathon training programs institutionalize electrolyte powder protocols. EFSA novel food standards apply through retained EU regulation alignment post-Brexit. London's specialty retail and e-commerce channels concentrate demand for premium organic-certified variants.
Canada
Health enthusiasts and ethical vegan consumers sustain loyalty premiums independent of performance claims. Health Canada and PMRA govern natural health product licensing for plant-protein supplements. Toronto and Vancouver anchor natural retail chains where regenerative agriculture messaging commands shelf-space premiums.
Vegan Drink Mixes Market Competitive Landscape
Concentration sits with organic-certified specialists and sports-nutrition pure-plays that have secured pharmacy and club-store placement. The vendor base spans multinational consumer health divisions, independent organic brands, and venture-backed direct-to-consumer entrants. Three archetypes dominate: legacy organic protein houses with supply chain depth, athlete-ambassador-driven sports specialists, and regenerative agriculture messengers. Competitive moves center on third-party certification acquisition and subscription platform development.
Within the organic-certified tier, Orgain and Garden of Life exemplify supply chain control strategies that sustain premium retail positioning. Vega anchors the athlete-ambassador archetype through extensive third-party certification programs. These three companies occupy positions that illustrate how clean-label differentiation and institutional channel penetration determine competitive standing.
| Leading Market Players |
|---|
| Sunwarrior |
| Sunwink |
| Vega |
| Plant Fusion |
| Aloha |
| Orgain |
| Amazing Grass |
| Nuzest |
| Garden of Life |
| Others |
Value Network & Pricing Analysis
Pea-protein isolate substitution for soy and rice concentrates is simultaneously shifting procurement geography toward Yangtze River Delta processing hubs and compressing per-kilogram pricing economics for mid-tier formulations. This input migration concentrates volume purchasing power among institutional buyers while fragmenting margin structures across certification tiers.
Pricing Analysis
Volume-discount tiering structures dominate institutional procurement, with collegiate athletic programs and private training facilities capturing 30-40% per-unit reductions against individual retail pricing. Premium-mid-economy pricing differentiation hinges on NSF Certified for Sport status and organic supply chain documentation, with pharmacy-channel placement in Germany sustaining the highest per-unit premiums. Cost compression in standard-tier protein powders is intensifying as Asian spray-drying capacity expands and shipping economics improve. Fitness professionals exhibit the lowest price sensitivity due to subscription purchasing power, while casual health enthusiasts drive competitive tension in economy tiers.
Supply Chain Analysis
Strait of Malacca transit underwrites the lion's share of pea-protein isolate flows from Chinese processing facilities to European and North American formulation plants. Upstream supply draws from Yangtze River Delta spray-drying clusters, Canadian prairie pea cultivation, and emerging Ukrainian processing investments. Single-source vulnerability concentrates in Asian isolate supply, with SAMR's evolving origin-disclosure rules threatening import disruption. Distribution runs through Rotterdam and Hamburg for European pharmacy channels, Los Angeles-Long Beach for North American club stores, and direct-procurement platforms for institutional athletic programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription replenishment services now expand faster than base powder sales, transforming vegan drink mixes into a recurring-revenue attach opportunity where formulation loyalty compounds lifetime value.
For Market Incumbents: Compound pharmacy-channel positioning through accelerated NSF Certified for Sport and Informed Sport queue investments, compressing six-to-twelve-month certification delays that cede shelf space to compliant rivals. Deepen backward integration into regenerative agriculture certification programs to defend margin position against commodity pea-protein price erosion. Vertical control over organic supply chains remains the critical defensive lever against venture-backed direct-to-consumer entrants exploiting shipping economics. For New Entrants and Emerging Players: Differentiate on precision-fermented protein isolates in European markets where EFSA novel food authorization creates incumbent blind spots. Target endurance athletics electrolyte protocols in German pharmacy channels, the most penetrable white space given institutionalized bulk purchasing cycles. Launch through direct-to-consumer subscription platforms to bypass gym-channel gatekeeper concentration and capture fitness professional procurement migration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed ready-to-drink formats possessing subscriber bases but lacking manufacturing scale. Long-term viability across the analysis window favors brands with captive organic supply chains and third-party certification depth over pure-play formulation houses. Watch EFSA's stance on fermented legume isolates as the signal for European market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Platform Development | Recurring revenue capture from fitness professional procurement rotation institutionalizes demand cycles. |
| Third-Party Certification Investment | NSF Certified for Sport and Informed Sport status determines pharmacy and collegiate channel access. |
| Precision Fermentation Scale-Up | Distributed manufacturing near demand centers reduces freight costs and freshness windows for boutique brands. |
| Regenerative Agriculture Certification | USDA Organic and soil-health standards create differentiation beyond basic non-GMO claims in natural retail. |
| Direct-to-Consumer Channel Expansion | Venture-backed formats exploit shipping economics to bypass traditional gym-channel gatekeepers. |
Research Methodology
A spread of perspectives from sports nutrition formulators, pharmacy category managers, collegiate athletic procurement directors, and third-party certification auditors converged on the working assumptions underlying demand and pricing trajectories. Primary fieldwork combined structured interviews with supply chain stakeholders and secondary validation through FDA facility registration databases, EFSA novel food submission records, EU organic certification registries, and customs trade flow documentation. Bottom-up volume modeling from product-type and end-user segments triangulated against top-down market sizing from channel revenue flows.
Segmentation dimensions modeled include product type, end-user archetype, formulation format, and flavor profile across the projection horizon. CAGRs were derived from historical growth rate analysis adjusted for regulatory inflection points and technology adoption curves. Forecast inputs incorporated spray-drying capacity expansion timelines, EFSA authorization lag distributions, and subscription platform penetration rates by buyer segment.
Material uncertainties — SAMR import rule evolution, EFSA novel food evaluation acceleration or delay, and precision fermentation cost curves — sit outside the modeled envelope. Forecasts reflect documented assumptions on certification queue times and shipping cost stability. Practitioners should keep alternative scenarios live as regulatory positioning and alternative protein technology maturation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Textured Pea Protein Market
Plant Based Food
North America Plant-Based Egg Market
Plant Based Food
Vegan Steak Market
Plant Based Food
United States Rice Protein Market
Plant Based Food
Plant-Based Meatballs Market
Plant Based Food
India Plant Protein Market
Plant Based Food
Germany Plant Protein Market
Plant Based Food
Plant-Based Ham Market
Plant Based Food
Plant Based Pasta Market
Plant Based Food
United States Textured Vegetable Protein Market
Plant Based Food
Europe Plant-Based Food Market
Plant Based Food
Middle East and Africa Meat Substitute Market
Plant Based Food
Global Plant Protein Market
Plant Based Food
Vegan Protein Foods Market
Plant Based Food
France Plant Protein Market
Plant Based Food
Vegan Chocolate Market