
 United States Pea Protein Market | 2026-2036
United States Pea Protein Market Size, Share, and Industry Trends Forecast 2026-2036
United States Pea Protein Market Analytics
Subscription-based ingredient sourcing platforms is recalibrating how pea protein gets priced and allocated across buyer tiers. PURIS leverages its domestic vertical farming network to secure non-GMO yellow pea supply chains. Roquette Frères anchors its position through European extraction expertise adapted for U.S. food-grade specifications. Kerry Group PLC differentiates via flavor-mask technologies that broaden application scope in beverage formulations.
Pea protein denotes the isolated or concentrated protein fraction extracted from yellow field peas through dry or wet milling followed by alkaline solubilization and isoelectric precipitation, yielding products with protein content ranging from 80% to 90% on a dry basis for isolates. This ingredient serves as a functional emulsifier, gelling agent, and complete protein source in formulated foods targeting allergen avoidance and sustainability claims. Isolate commands premium positioning in nutritional supplements where protein purity dictates margin pools, while textured formats gain traction in meat analog applications requiring chew structure and water retention. Concentrate occupies volume leadership in bakery and snack applications where cost thresholds constrain isolate adoption.
FDA allergen labeling requirements and USDA organic certification standards shape pea protein market access, with the former driving substitution away from soy and dairy declarations and the latter commanding price premiums in natural channel distribution. EPA biofuel policies indirectly influence pea acreage competition, tightening feedstock availability for protein processors during planting season decisions. Stakeholders must monitor FDA protein quality scoring methodology revisions and state-level clean-label legislation momentum as determinants of formulation investment cycles.
Market Dynamics
Sports nutrition brands are systematically displacing whey with plant-based formulations, compressing formulation cycles and rewiring procurement relationships across the protein supply base.
Growth Catalysts
- FDA Allergen Labeling Rules:Substitution away from soy and dairy declarations accelerates pea protein adoption in clean-label formulations targeting allergen-sensitive consumers.
- Yellow Pea Vertical Farming Networks:Domestic cultivation clusters in Minnesota and North Dakota secure non-GMO feedstock pipelines with traceability credentials.
- Meat Analog Manufacturing:Textured pea protein formats capture share in extruded plant-based cutlet and ground applications requiring chew structure.
Market Restraints
- Yellow Pea Acreage Competition:EPA biofuel policies divert planting decisions toward ethanol feedstocks, tightening protein processor supply during spring contracting windows.
- Flavor-Masking Cost Burden:Beany off-notes require additional processing steps or masking technologies that compress margins in beverage applications.
- Protein Quality Scoring Uncertainty:Pending FDA methodology revisions for PDCAAS replacement create formulation investment hesitation among CPG brands.
Strategic Opportunities
- Pacific Northwest Manufacturing Clusters:Clean-label food production concentration around Portland and Seattle anchors long-term supply contracts with premium pricing tiers.
- Infant Nutrition Formulations:Hypoallergenic positioning opens entry into pediatric medical foods where dairy protein exclusion drives clinical preference.
- USDA Organic Certification Premiums:Natural channel distribution commands price multiples that justify segregated handling and processing infrastructure.
Industry Challenges
- Isoelectric Precipitation Expertise Gap:Wet extraction process optimization requires protein chemists with pea-specific solubility curve knowledge that outstrips current talent pools.
- Organic Certification Timeline Compression:Three-year transition requirements for conventional acreage conversion delay organic volume scaling to match demand signals.
- Legacy Dairy Equipment Retrofit Costs:Spray drying and separation infrastructure designed for whey requires capital-intensive modification to handle pea protein viscosity profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Pea Protein Market |
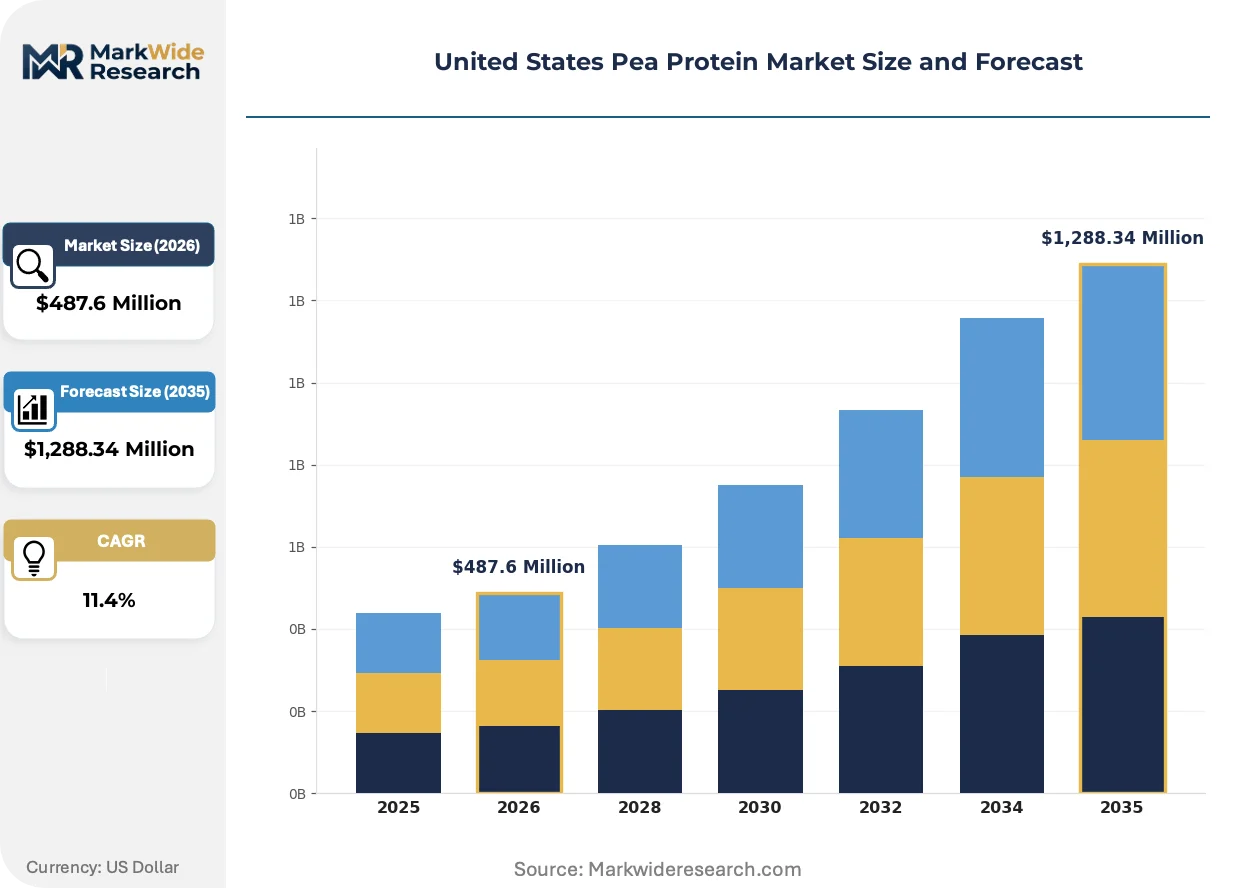
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Textured, Hydrolysate Application: Food & Beverage, Nutritional Supplements, Animal Feed, Bakery Products End User: Vegetarians, Vegans, Athletes, Health-Conscious Consumers Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, Roquette Frères, Ingredion Incorporated, The Scoular Company, PURIS, Axiom Foods, Inc., Burcon NutraScience Corporation, Kerry Group PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Pea Protein Market Evolving Landscape
Processing technology convergence and procurement platform digitization are compressing margin capture timelines while expanding application scope beyond legacy sports nutrition positioning.
Fermentation-assisted protein extraction is electrifying yield economics in pilot-scale facilities. Biotech-enabled processing startups deploy engineered enzymes that reduce alkaline solubilization energy inputs by half. This technology is compressing capital recovery periods for isolate production lines and enabling Midwest processors to compete with European extraction specialists on unit economics.
FDA protein quality scoring methodology revisions are forcing reformulation roadmaps across the supplement sector. The agency's shift toward DIAAS from PDCAAS elevates digestibility-corrected amino acid scores as the compliance benchmark. Brands targeting clinical and performance segments are accelerating third-party testing investments to preempt labeling disputes.
Subscription-based ingredient sourcing platforms are fragmenting buyer power across tiered customer segments. Small-batch craft food manufacturers now access spot pricing and flexible minimum order quantities previously reserved for multinational CPG procurement teams. This channel innovation concentrates most visibly in California's Bay Area and Brooklyn's food startup ecosystem.
United States Pea Protein Market Segmentation
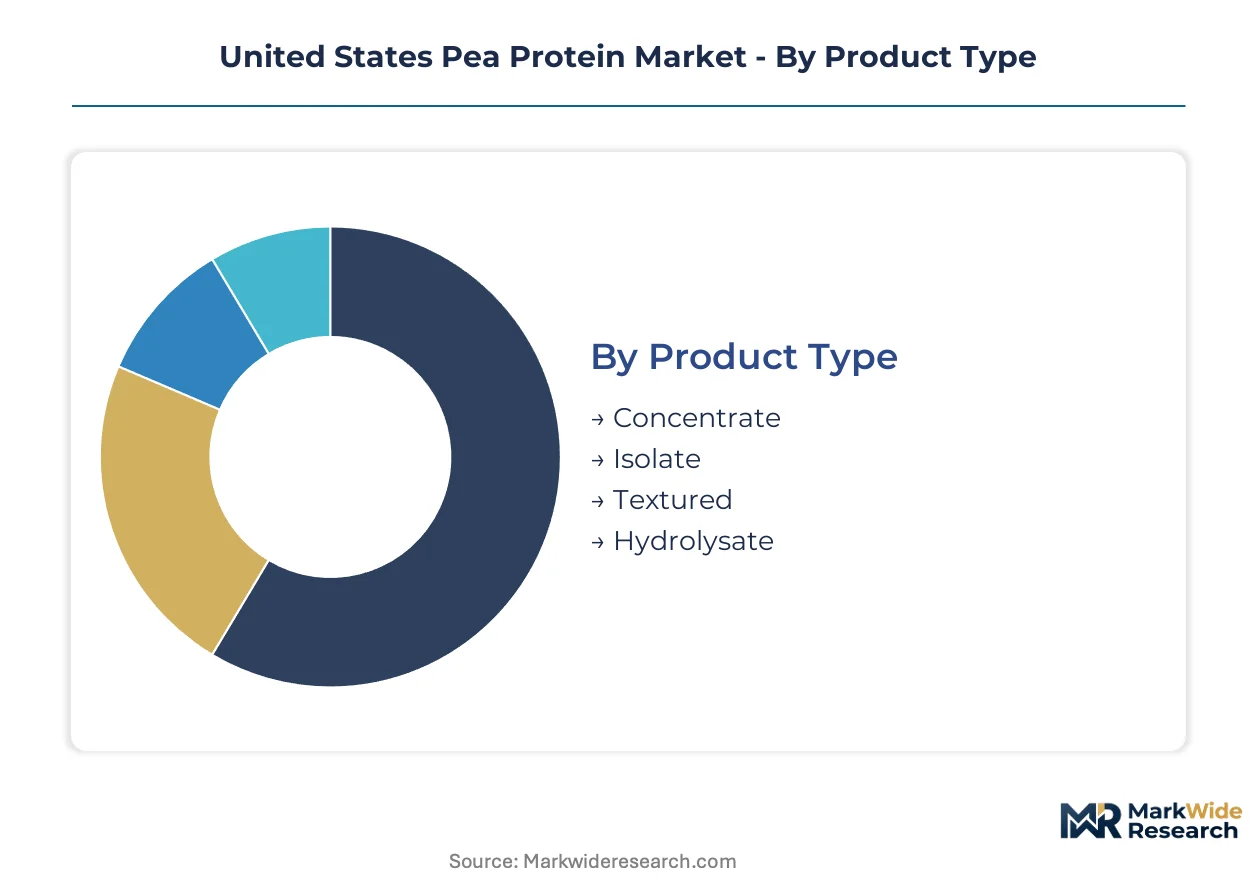
Pea protein segmentation in the United States reflects divergent capital requirements across extraction technologies and end-use specifications. Investment intensity varies from fermentation-assisted wet extraction facilities to simple dry-milling operations serving commodity feed markets.
Product Type:
Capital intensity peaks with isolate production requiring isoelectric precipitation infrastructure and spray-drying systems engineered for protein viscosity profiles.
- Isolate:Protein content reaches 80% to 90% on a dry basis through alkaline solubilization followed by isoelectric precipitation. Premium sports nutrition brands in California and the Pacific Northwest anchor demand where protein purity dictates margin capture and formulation premiums.
- Concentrate:Lower protein content (typically 50% to 80%) achieved through simpler dry or wet milling without full fractionation. Cost thresholds in bakery and snack applications across the Midwest constrain isolate adoption, making concentrate the default for mass-market CPG formulations.
- Textured:Extruded formats requiring specialized thermal-mechanical processing to create fibrous structures mimicking meat chew. Meat analog manufacturing clusters in Minnesota and North Dakota drive procurement contracts.
- Hydrolysate:Enzymatically pre-digested protein fractions targeting rapid amino acid absorption in clinical and performance nutrition. Infant nutrition formulations and hypoallergenic medical foods in pediatric segments concentrate demand.
Isolate absorbs the bulk of installed capacity; textured formats are expanding most quickly.
Application:
Application segmentation tracks margin stratification from commodity feed inputs to pharmaceutical-grade medical nutrition.
- Nutritional Supplements:Protein powders, ready-to-drink beverages, and bar formulations where FDA protein quality scoring methodology revisions are forcing third-party testing investments. Athletes and clinical nutrition segments in metropolitan health corridors drive premium positioning.
- Food & Beverage:Plant-based dairy alternatives, meat analogs, and functional beverages where flavor-masking technologies determine formulation feasibility. Clean-label manufacturing clusters in Portland and Seattle anchor supply contracts with traceability requirements.
- Bakery Products:Protein fortification in bread, muffins, and snack items where cost thresholds favor concentrate grades. Health-conscious consumer segments in suburban retail corridors sustain volume.
- Animal Feed:Commodity-grade protein meal competing with soybean meal on price per unit protein. EPA biofuel policies indirectly tighten yellow pea acreage availability for this lowest-margin tier.
Food & Beverage captures the widest formulation breadth; nutritional supplements command the steepest price premiums.
End User:
End user segmentation maps distinct purchasing behaviors across dietary identity and performance orientation.
- Athletes:Performance-focused consumers prioritizing protein quality scores and leucine content in recovery formulations. Sports nutrition brands systematically displace whey with plant-based alternatives in this segment.
- Health-Conscious Consumers:Flexitarian households seeking protein diversification without full dietary commitment. Supermarket and online retail channels capture this largest-volume segment.
- Vegans:Ethical dietary adherents requiring complete amino acid profiles from single-source plant proteins. Allergen avoidance claims accelerate pea protein preference over soy in this cohort.
- Vegetarians:Lacto-ovo dietary practitioners using pea protein to supplement dairy and egg intake. Health store distribution and direct sales channels concentrate here.
Health-conscious consumers generate the broadest volume base; athletes deliver the highest per-unit margins.
Distribution Channel:
Channel segmentation reflects the fragmentation of buyer power through digital procurement platforms.
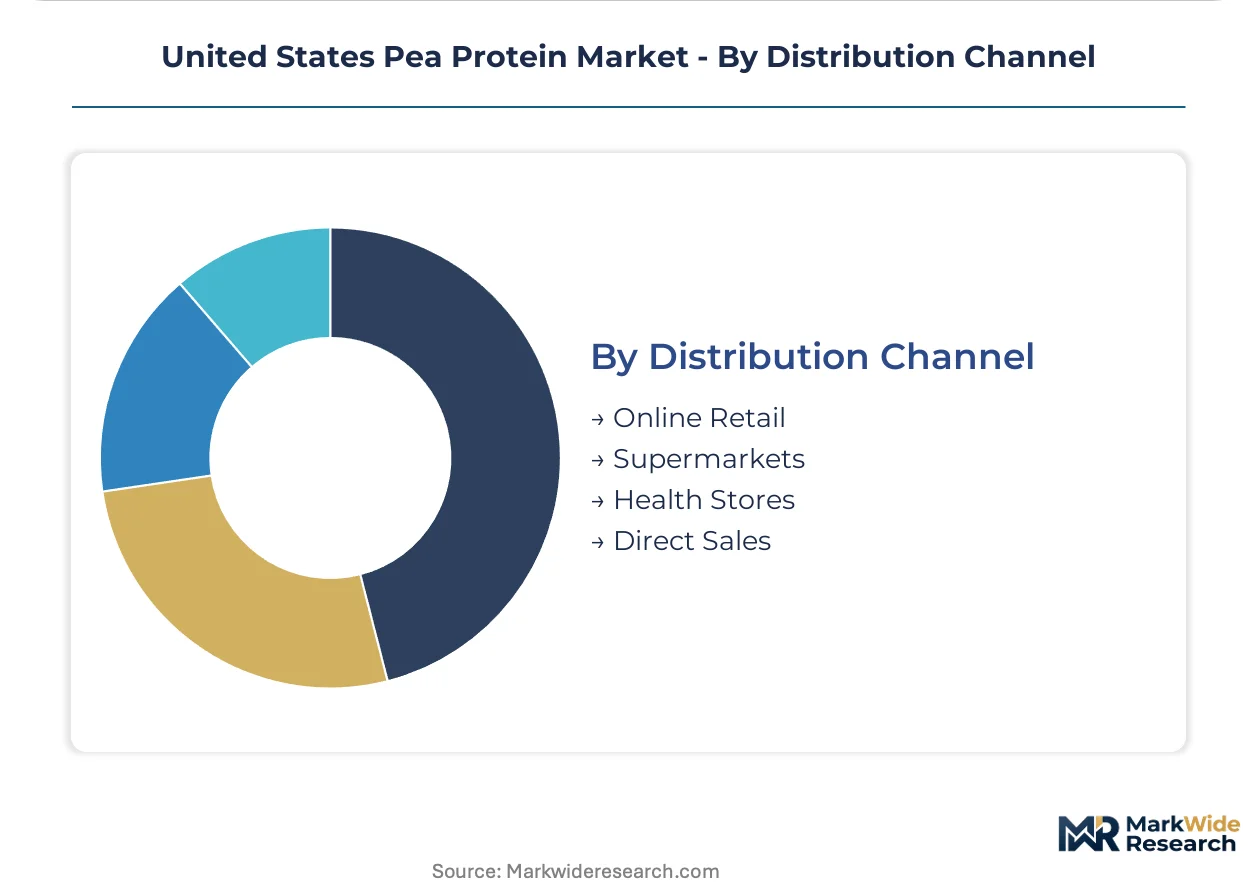
- Supermarkets:Mass retail placement requiring slotting fees and national distribution infrastructure. Clean-label product lines in conventional grocery anchor this channel's growth.
- Online Retail:Subscription-based ingredient sourcing platforms and direct-to-consumer brands enabling small-batch manufacturers to access spot pricing. Brooklyn and Bay Area food startups concentrate here.
- Health Stores:Natural channel distribution commanding USDA organic certification premiums and segregated handling infrastructure. Pacific Northwest retail cooperatives sustain regional concentration.
- Direct Sales:B2B supply contracts with food manufacturers and institutional foodservice operators. Long-term agreements with pea protein processors lock in volume commitments.
Supermarkets dominate absolute volume throughput; online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yellow pea cultivation concentrates in the northern Plains while processing infrastructure and formulation demand cluster in coastal manufacturing corridors. This geographic split shapes freight economics and contract structures across the value chain.
California
Plant-based food startups in Los Angeles and San Francisco anchor formulation innovation for meat analogs and dairy alternatives. FDA allergen labeling enforcement accelerates pea protein substitution in clean-label product development. The Bay Area hosts subscription-based ingredient sourcing platforms that fragment procurement power across small-batch manufacturers.
Pacific Northwest
Clean-label manufacturing clusters in Portland and Seattle lock in long-term supply contracts with traceability requirements. Oregon and Washington state-level clean-label legislation momentum shapes investment cycles for regional processors. PURIS operates vertical farming networks here that secure non-GMO yellow pea supply chains with domestic provenance credentials.
Minnesota and North Dakota
Yellow pea acreage in the Red River Valley supplies feedstock to wet extraction facilities and textured protein extrusion plants. EPA biofuel policies create spring planting competition with corn ethanol feedstocks that tightens processor contracting windows. Meat analog manufacturing facilities in Minneapolis-St. Paul drive procurement for extruded formats requiring chew structure.
Midwest Industrial Corridor
Illinois and Ohio host spray-drying infrastructure retrofitted from legacy whey operations to handle pea protein viscosity profiles. USDA organic certification premiums command segregated handling infrastructure that extends processing timelines. Chicago anchors distribution logistics for bakery and snack applications where concentrate grades dominate cost-sensitive formulations.
Northeast Corridor
Specialty health food distribution through Boston and New York Metro channels captures vegan and allergen-avoidance consumer segments. Sports nutrition brands in metropolitan health corridors displace whey with plant-based recovery formulations. Direct-to-consumer subscription models concentrate in Brooklyn's food startup ecosystem with flexible minimum order quantities.
United States Pea Protein Market Competitive Landscape
Top-tier vendors anchor premium isolate and hydrolysate production, while mid-scale processors compete on concentrate volume and textured format capacity. The vendor base stratifies across extraction technology sophistication, with wet milling and isoelectric precipitation capabilities separating price tiers. Three archetypes dominate: agricultural conglomerates with captive pea supply, specialized protein extraction technology licensors, and flavor-system integrators with masking competencies. Capacity expansion in the northern Plains and strategic partnerships with coastal formulation labs represent the dominant competitive moves.
Among agricultural conglomerates with integrated supply chains, Archer Daniels Midland Company and Cargill, Incorporated exemplify scale-driven positions that span cultivation through ingredient distribution. Roquette Frères anchors the European extraction expertise archetype adapted for U.S. food-grade specifications, while Kerry Group PLC occupies the flavor-system integrator tier with technologies that broaden beverage application scope. PURIS represents the domestic vertical farming model that secures non-GMO feedstock pipelines with traceability credentials. These three archetypes—agricultural integrators, extraction specialists, and formulation enablers—structure competitive rivalry across the value chain.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Roquette Frères |
| Ingredion Incorporated |
| The Scoular Company |
| PURIS |
| Axiom Foods, Inc. |
| Burcon NutraScience Corporation |
| Kerry Group PLC |
| Others |
Value Network & Pricing Analysis
Yellow pea feedstock costs cascade through three distinct pricing tiers as Minnesota and North Dakota cultivation cycles tighten processor contracting windows each spring. FDA protein quality scoring uncertainty and EPA biofuel policy competition for acreage amplify volatility at the isolate premium tier while concentrate grades absorb volume pressure in Midwest bakery applications.
Pricing Analysis
Margin tightening in beverage-grade isolate reflects flavor-masking technology investments that compress returns despite premium positioning. Three-tier pricing structure across organic-certified, conventional food-grade, and feed-grade specifications separates buyer segments by certification investment and application purity requirements. Cost-down pressure on concentrate accelerates because health-conscious consumers in suburban retail channels drive volume without quality-score premiums. Athletes in metropolitan health corridors show least price sensitivity; mass-market CPG formulators in the Midwest exhibit highest elasticity.
Supply Chain Analysis
Domestic-content requirements in USDA organic certification programs reshape sourcing toward PURIS vertical farming networks and Red River Valley cultivation clusters. Geographic supply concentration centers on Minnesota, North Dakota, and Pacific Northwest processing infrastructure with European extraction expertise imports from Roquette Frères. Raw material dependencies include non-GMO yellow pea seed stock, fermentation-assisted enzyme inputs, and spray-drying energy feeds. Single-source vulnerability concentrates in isoelectric precipitation expertise pools that outstrip current protein chemist availability. Distribution runs through direct B2B contracts with coastal formulation labs and subscription-based platforms fragmenting small-batch procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic certification timeline compression creates a structural capacity bottleneck that props pricing premiums through the forecast horizon.
For Market Incumbents: Acquire fermentation-assisted extraction technology assets to compress capital recovery periods and defend against biotech-enabled processing startups. Secure long-term offtake agreements with Minnesota and North Dakota cultivation clusters before EPA biofuel policies tighten spring contracting windows. Invest in segregated handling infrastructure to capture USDA organic certification premiums in natural channel distribution. For New Entrants and Emerging Players: The gap between premium isolate and economy concentrate pricing opens white-space entry in textured protein formats for meat analog applications. Target Pacific Northwest manufacturing clusters in Portland and Seattle where clean-label legislation momentum anchors supply contract premiums. Deploy subscription-based platform access as the go-to-market angle to fragment procurement power among Bay Area and Brooklyn food startups. For Investors and Strategic Acquirers: FDA DIAAS methodology finalization is the leading indicator that clinical and performance nutrition segments will accelerate third-party testing investments and consolidate around quality-score leaders. The five-to-ten year viability window favors extraction technology licensors with wet milling capabilities over commodity concentrate processors. Target acquisition archetypes include fermentation-assisted processing startups and flavor-mask technology specialists. Watch state-level clean-label legislation momentum as the inflection signal for regional premium pricing durability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yellow Pea Cultivation | PURIS-style vertical farming networks secure non-GMO supply chains with domestic provenance credentials. |
| Fermentation-Assisted Extraction Scale-Up | Biotech-enabled processing reduces alkaline solubilization energy inputs and compresses isolate production economics. |
| Flavor-Mask Technology Licensing | Kerry Group PLC-type competencies broaden beverage application scope beyond beany off-note limitations. |
| USDA Organic Certification Infrastructure | Segregated handling capabilities capture natural channel price multiples that justify three-year acreage conversion timelines. |
| Pacific Northwest Supply Contract Anchoring | Long-term agreements with Portland and Seattle clean-label manufacturing clusters lock in premium pricing tiers. |
Research Methodology
Independent corroboration across FDA regulatory filings, EPA biofuel policy documents, and USDA organic certification databases underwrites the qualitative findings in this analysis. Primary interviews with pea protein processors, sports nutrition brand formulators, and clean-label manufacturing procurement leads combined with secondary validation from trade customs data, SEC 10-K filings of agricultural conglomerates, and state-level clean-label legislative records. Bottom-up volume modeling from cultivation acreage through extraction capacity triangulates against top-down demand segmentation across athlete, health-conscious, vegan, and vegetarian end-user cohorts.
Comparable historical reference periods spanning pre- and post-FDA allergen labeling rule implementation anchor the forecast window calibration. Segmentation dimensions modeled include product type tier, application purity requirements, end-user dietary identity, and distribution channel structure across the projection horizon. CAGRs derive from installed capacity expansion trajectories in northern Plains processing facilities and substitution elasticity estimates from whey displacement patterns in sports nutrition formulations.
Inputs from protein processor production disclosures and cultivation cooperative planting reports were available through the study window; gaps in real-time isoelectric precipitation yield data and confidential flavor-mask technology licensing terms introduce uncertainty bands around isolate margin projections. Forecasts reflect documented assumptions regarding FDA DIAAS timeline and EPA renewable fuel standard adjustments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Chickpea-Based Products Market
Plant Based Food
Plant Based Pork Market
Plant Based Food
Italy Plant Protein Market
Plant Based Food
Vegan Flavor Market
Plant Based Food
Global Vegan Fast Foods Market
Plant Based Food
United States Plant Protein Market
Plant Based Food
Vegan Margarine Market
Plant Based Food
Pea Protein Isolate Market
Plant Based Food
Rhubarb Root Extract Market
Plant Based Food
India Meat Substitutes Market
Plant Based Food
Europe Pea Protein Market
Plant Based Food
Europe Rice Protein Market
Plant Based Food
Plant-Based Sausages Market
Plant Based Food
West Africa Plant Based Product Market
Plant Based Food
Organic Pea Protein Market
Plant Based Food
Plant-Based Shrimp Market