
 Germany Patient Monitoring Market | 2026-2036
Germany Patient Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Patient Monitoring Market Foresight
The EU Medical Device Regulation is pivoting the cost-of-entry calculus for patient monitoring systems in Germany, forcing manufacturers to recertify legacy platforms under stricter clinical evidence rules. Drägerwerk AG & Co. KGaA leverages its domestic manufacturing base to sustain rapid regulatory turnaround times. Siemens Healthineers anchors its position through deep integration of imaging and monitoring data streams. Biotronik SE & Co. KG specializes in cardiac rhythm management devices that navigate the MDR pathway with targeted clinical dossiers.
Germany patient monitoring encompasses devices, software, and connectivity infrastructure that acquire, transmit, and analyze physiological parameters such as electrocardiography waveforms, pulse oximetry values, respiratory rate, and invasive blood pressure. These systems employ sensor arrays with sampling frequencies ranging from 125 Hz for standard vital signs to 1000 Hz for high-fidelity hemodynamic monitoring, serving to detect clinical deterioration, guide therapeutic interventions, and enable decentralized care delivery outside traditional hospital wards. Wearable devices and remote monitors lead volume adoption as German sickness funds expand reimbursement for ambulatory telemetry, while IoT Solutions and data analytics capture margin pools through recurring software licensing and predictive algorithm subscriptions. Cloud computing infrastructure remains nascent in acute settings due to cybersecurity hesitancy but grows fastest in post-acute and home care channels where data sovereignty requirements are less restrictive.
The Federal Institute for Drugs and Medical Devices enforces MDR compliance timelines that shape product launch sequencing, while the German Institute for Standardization maintains DIN EN ISO 81001 and IEC 60601 series standards governing electromagnetic compatibility and alarm safety for bedside monitors. The German Social Code Book V drives demand through diagnosis-related group reimbursement structures that reward reduced length of stay enabled by continuous monitoring. Stakeholders must weigh capital expenditure for integrated monitoring platforms against modular, software-upgradable architectures that preserve optionality as regulatory and reimbursement rules evolve.
Market Dynamics
The EU Medical Device Regulation is compressing product launch timelines and forcing capital reallocation toward clinical evidence generation, fundamentally restructuring how patient monitoring systems enter German hospitals.
Growth Catalysts
- Ambulatory reimbursement expansion:German sickness funds now reimburse remote cardiac telemetry for post-operative patients, accelerating demand for wearable ECG patches and cellular-connected pulse oximeters in home care settings.
- MDR Article 117 pathway:The regulation's software classification rules create predictable compliance roadmaps for AI-enabled arrhythmia detection algorithms, reducing regulatory uncertainty for developers of embedded diagnostic modules.
- University hospital consolidation:Bavaria's Klinikum rechts der Isar and North Rhine-Westphalia's University Hospital Cologne are standardizing on single-vital-sign platforms across their networks, creating procurement pull for integrated monitoring suites.
Market Restraints
- Clinical evidence cost inflation:MDR Annex XIV requirements for post-market surveillance and PMCF studies have doubled the cost of maintaining legacy device registrations, squeezing mid-tier manufacturers with limited trial infrastructure.
- Semiconductor supply concentration:Analog front-end chips for high-fidelity ECG acquisition depend on Taiwan-based foundry capacity, exposing German device makers to lead-time volatility for 24-bit ADC components.
- Cloud infrastructure hesitancy:DIN EN ISO 27001 certification gaps among acute-care IT departments block deployment of cloud-native monitoring analytics, limiting software-as-a-service revenue models in hospital settings.
Strategic Opportunities
- Baden-Württemberg medtech cluster:The Stuttgart-Tübingen corridor offers proximity to Fraunhofer IPA and University Hospital Tübingen for co-development of AI-interpretable hemodynamic monitoring, with state-level innovation vouchers reducing R&D risk.
- Integration of radar-based contactless sensing:Frequency-modulated continuous-wave radar for respiratory rate monitoring converges with mmWave sleep staging algorithms, opening non-wearable monitoring for neonatal and burn-ward applications.
- Diagnosis-related group optimization:German Social Code Book V reimbursement codes for early-warning-score-triggered interventions reward continuous monitoring investments, creating financial headroom for platform upgrades in secondary hospitals.
Industry Challenges
- Embedded cybersecurity engineering scarcity:IEC 81001-5-1 secure lifecycle requirements demand specialized firmware architects familiar with medical device threat modeling, a skill set concentrated among Munich and Berlin specialists with limited labor pool depth.
- Legacy bedside monitor refresh cycles:IEC 60601-1-8 fourth edition alarm safety mandates require hardware retrofits for devices deployed 2015-2019, stretching hospital biomedical engineering capacity during parallel EMR upgrade projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Patient Monitoring Market |
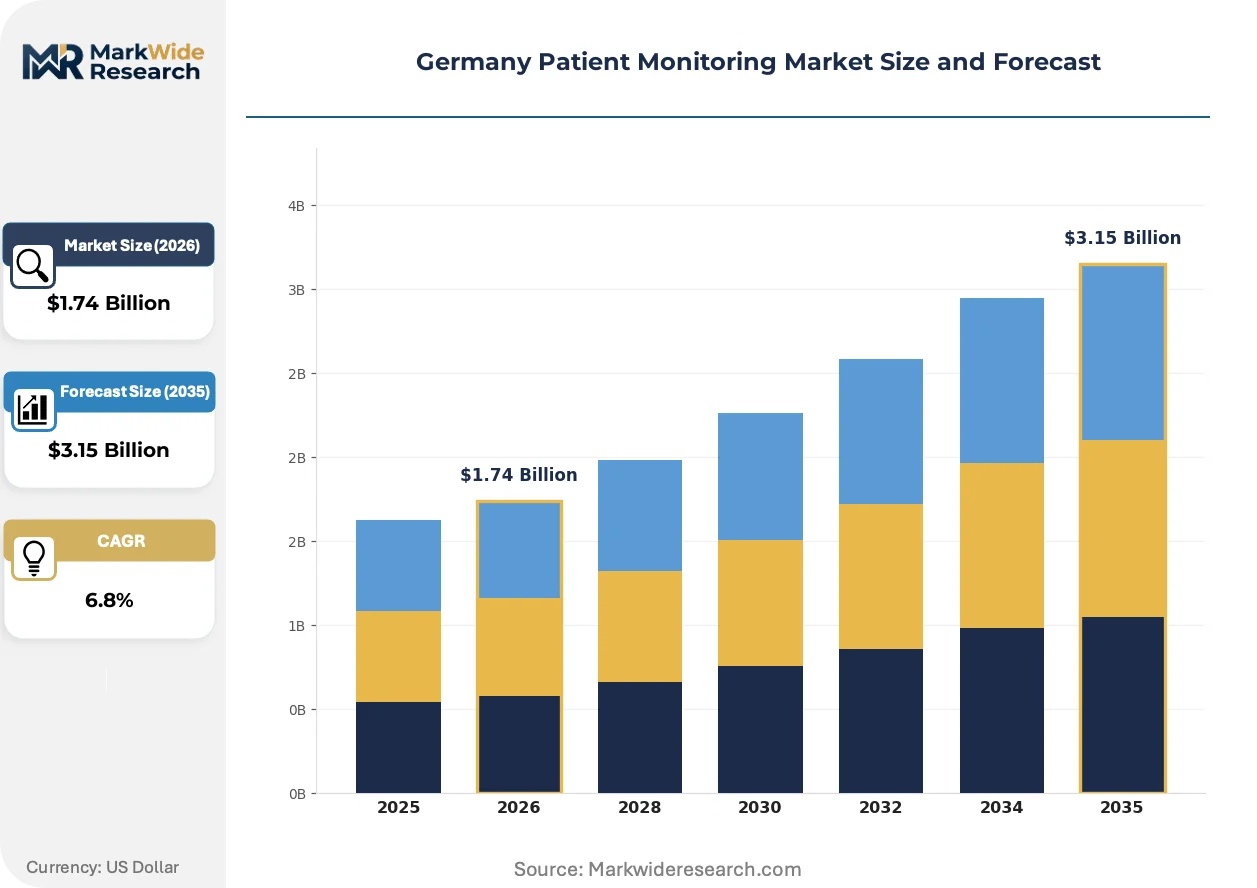
| Market Size in 2026 | $1.74 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Smart Beds, Remote Monitors, Portable Devices Technology: IoT Solutions, Wireless Tracking, Data Analytics, Cloud Computing End User: Hospitals, Home Care, Rehabilitation Centers, Long-term Care Facilities Application: Chronic Disease Management, Anesthesia Monitoring, Vital Signs Monitoring, Patient Management Systems |
| Companies Covered | Drägerwerk AG & Co. KGaA, Biotronik SE & Co. KG, Siemens Healthineers, Medtronic, Koninklijke Philips, GE Healthcare, Masimo Corporation, Abbott Laboratories, Fresenius SE & Co. KGaA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Patient Monitoring Market Shifts & Advancements
Sensor fusion architectures and edge-computing telemetry are collapsing the distinction between acute and ambulatory monitoring modalities, enabling continuous physiological surveillance across care settings without patient re-instrumentation.
Multi-parameter wearable patches incorporating photoplethysmography, bioimpedance spectroscopy, and accelerometry are unifying cardiac, respiratory, and activity monitoring into single-body-worn devices. Charité – Universitätsmedizin Berlin and Heidelberg University Hospital are piloting these platforms for post-discharge heart failure surveillance, compressing the traditional multi-device telemetry stack into disposable 7-day wearables that eliminate electrode-skin interface variability.
The EU AI Act's risk-classification framework for medical device software is forcing algorithm developers to restructure quality management systems around post-market performance monitoring. Class IIa monitoring devices with embedded machine learning now require continuous accuracy tracking against reference standards, driving German manufacturers to implement MLOps pipelines that automate model drift detection and trigger retraining protocols before regulatory thresholds breach.
Hospital procurement committees in Bavaria and North Rhine-Westphalia are unbundling hardware acquisition from software licensing, separating capital expenditure for bedside monitors from recurring subscriptions for predictive analytics. This disintermediation of the traditional integrated-vendor model creates evaluation friction as biomedical engineering teams must now assess interoperability across independently sourced hardware and cloud platforms, with University Hospital Frankfurt documenting 14-month procurement cycles for multi-vendor monitoring architectures.
Germany Patient Monitoring Market Segmentation
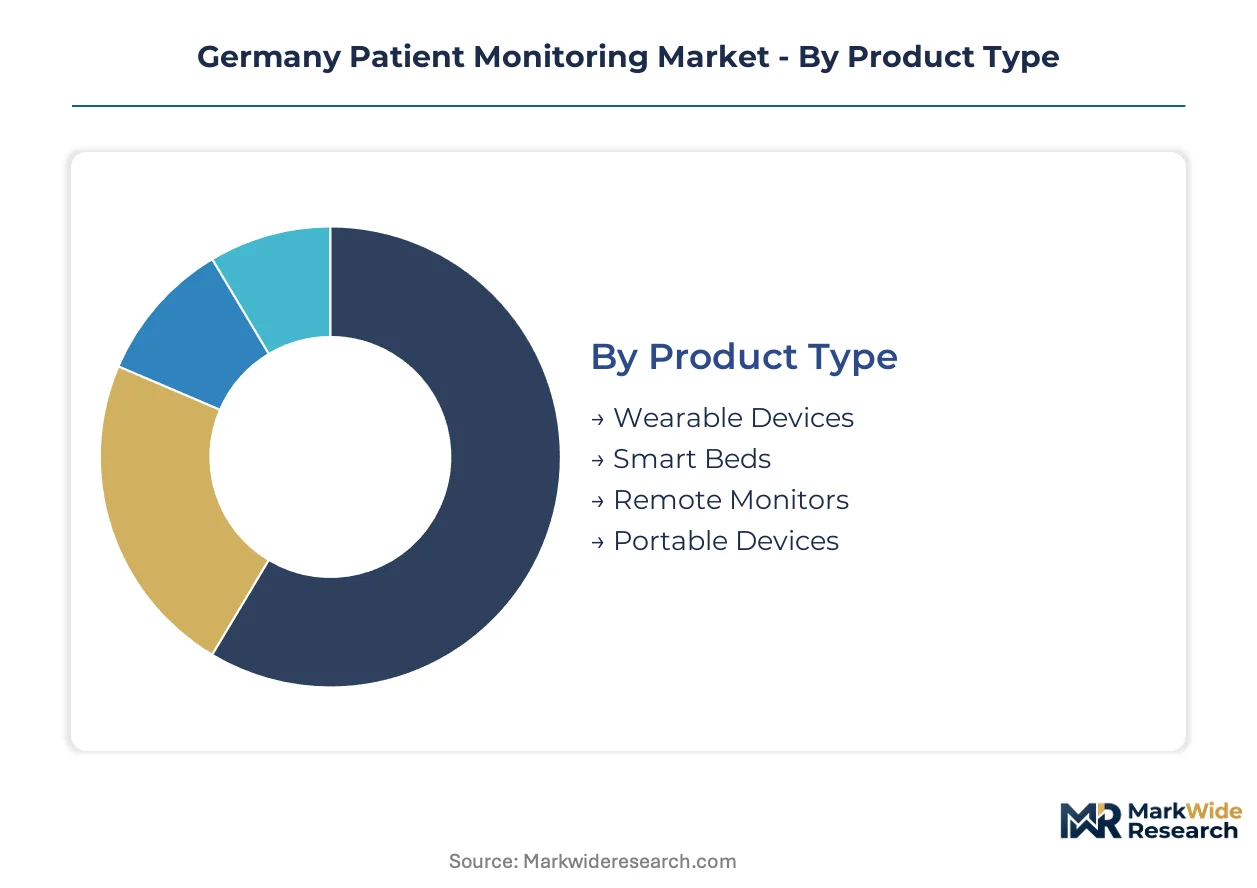
Patient monitoring systems in Germany fragment across hardware form factors, connectivity architectures, care settings, and clinical use cases. Each dimension carries distinct regulatory burdens and procurement pathways that shape vendor competitive positioning.
Product Type:
Wearable Devices and Remote Monitors carry Class IIa MDR certification requirements with clinical evidence dossiers, while Smart Beds and Portable Devices navigate separate conformity routes under IEC 60601-1 third edition and DIN EN ISO 81001.
- Wearable Devices:Multi-sensor patches integrating photoplethysmography, bioimpedance, and accelerometry sample physiological signals at 125-500 Hz. Bavarian university hospitals concentrate procurement for post-discharge cardiac telemetry, driven by sickness fund reimbursement expansion for ambulatory monitoring.
- Remote Monitors:Cellular-connected hub devices aggregate data from distributed sensors and transmit to clinical decision support platforms. North Rhine-Westphalia's hospital networks standardize on these systems for rural patient surveillance, constrained by DIN EN ISO 27001 certification gaps in acute IT departments.
- Smart Beds:Pressure-sensing mattresses with embedded load cells enable continuous position and respiratory rate tracking without patient contact. Baden-Württemberg's long-term care operators evaluate radar-augmented variants for fall prevention.
- Portable Devices:Battery-powered multi-parameter monitors support intra-hospital transport and emergency deployment. Secondary hospitals in Saxony prioritize modular architectures permitting software upgrades without hardware replacement.
Wearable Devices sit at the top of the volume ranking, with Remote Monitors climbing the fastest.
Technology:
Technology segments stratify by margin structure, with hardware-enabled connectivity commanding upfront capital and software layers capturing recurring revenue through subscription licensing.
- IoT Solutions:Sensor networks and edge gateways enable real-time telemetry across distributed care settings. Fraunhofer IPA co-development programs in Stuttgart-Tübingen accelerate deployment of AI-interpretable hemodynamic monitoring with state innovation voucher support.
- Data Analytics:Predictive algorithms for early warning score calculation and arrhythmia detection require MDR Article 117 compliance for embedded diagnostic modules. German manufacturers implement MLOps pipelines for automated model drift detection under EU AI Act risk-classification mandates.
- Wireless Tracking:Bluetooth Low Energy and proprietary radio protocols connect body-worn sensors to consolidation hubs. Electromagnetic compatibility testing under DIN EN ISO 81001 extends certification timelines for multi-protocol devices.
- Cloud Computing:SaaS platforms for remote monitoring analytics face deployment barriers in acute settings due to data sovereignty requirements and cybersecurity hesitancy, expanding fastest in post-acute and home care channels.
IoT Solutions capture the dominant revenue share, while Data Analytics expands most quickly through predictive algorithm subscriptions.
End User:
End user segments diverge by procurement authority, with hospital purchasing committees managing capital budgets separately from home care reimbursement pathways administered by sickness funds.
- Hospitals:University hospitals in Bavaria, North Rhine-Westphalia, and Baden-Württemberg drive standardization toward single-vital-sign platforms across network facilities. Procurement cycles extend 14 months for multi-vendor architectures requiring interoperability assessment.
- Home Care:Ambulatory telemetry reimbursement under German Social Code Book V accelerates demand for wearable ECG patches and cellular-connected pulse oximeters. Patient-managed devices require simplified interfaces and remote technical support infrastructure.
- Rehabilitation Centers:Post-acute facilities prioritize continuous monitoring for early mobilization protocols and complication detection. Integration with hospital EMR systems determines vendor selection.
- Long-term Care Facilities:Nursing homes evaluate contactless radar-based sensing for residents with skin integrity concerns or cognitive impairment preventing wearable device compliance.
Hospitals maintain the largest installed base, with Home Care gaining share fastest as reimbursement frameworks mature.
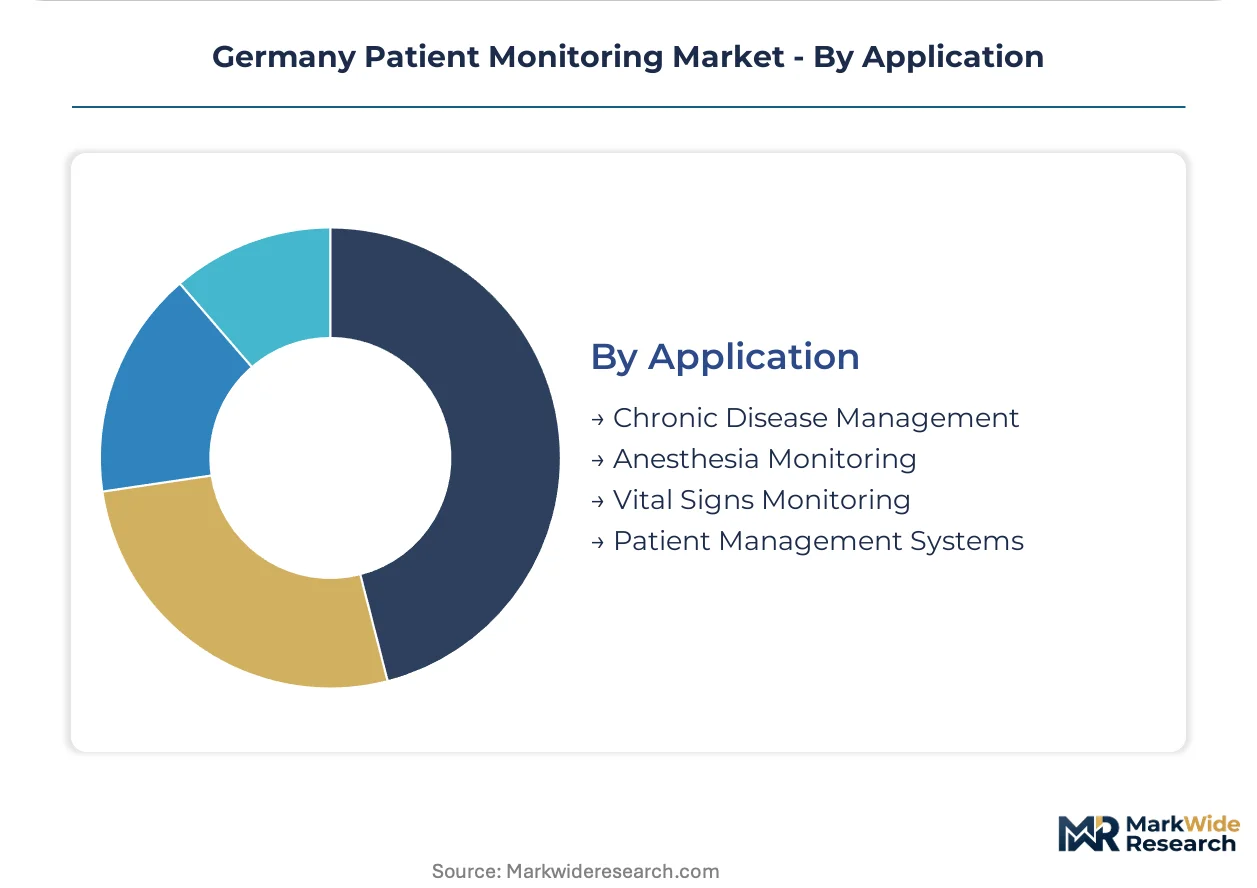
Application:
Application segments align with diagnosis-related group reimbursement incentives, where reduced length of stay and complication prevention create financial headroom for monitoring investments.
- Vital Signs Monitoring:Continuous tracking of heart rate, blood pressure, respiratory rate, and oxygen saturation underpins early warning systems for clinical deterioration. IEC 60601-1-8 fourth edition alarm safety mandates drive hardware refresh cycles for devices deployed 2015-2019.
- Chronic Disease Management:Post-discharge surveillance for heart failure and COPD patients leverages multi-parameter wearable patches compressing traditional telemetry stacks. Charité – Universitätsmedizin Berlin and Heidelberg University Hospital pilot 7-day disposable platforms.
- Anesthesia Monitoring:Operating room and procedural sedation applications demand high-fidelity hemodynamic monitoring with 1000 Hz sampling for advanced waveform analysis. Analog front-end chip supply concentration in Taiwan creates lead-time volatility.
- Patient Management Systems:Integrated platforms combining monitoring data with EMR documentation and workflow orchestration require cybersecurity engineering scarce among Munich and Berlin firmware specialists.
Vital Signs Monitoring represents the foundational application layer, with Chronic Disease Management showing the steepest expansion trajectory as ambulatory reimbursement broadens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German biomedical engineering talent concentrates in Munich, Berlin, and the Stuttgart-Tübingen corridor, anchoring domestic R&D capacity for patient monitoring innovation. This workforce distribution shapes regional procurement patterns and regulatory response capabilities across federal states.
Bavaria
Klinikum rechts der Isar and Ludwig-Maximilians-Universität München drive demand for integrated monitoring suites across standardized hospital networks. The Bavarian State Ministry of Health enforces procurement guidelines favoring interoperable platforms. Munich's medical technology cluster hosts Fraunhofer research institutes co-developing AI-enabled hemodynamic algorithms with state innovation voucher support.
North Rhine-Westphalia
University Hospital Cologne and RWTH Aachen University Hospital anchor cardiac telemetry procurement for post-operative surveillance programs. The state's hospital association negotiates framework agreements under German Social Code Book V reimbursement structures. The Cologne-Bonn corridor concentrates cellular-connected remote monitoring deployment for rural patient outreach.
Baden-Württemberg
University Hospital Tübingen and Heidelberg University Hospital pilot disposable multi-parameter wearable patches for heart failure surveillance. The Ministry of Science, Research and Arts funds medtech innovation through the Stuttgart-Tübingen corridor cluster. Fraunhofer IPA collaborates with device manufacturers on radar-based contactless sensing for neonatal applications.
Lower Saxony
Hannover Medical School advances anesthesia monitoring applications requiring high-fidelity waveform analysis. The Lower Saxony Ministry of Social Affairs coordinates hospital IT infrastructure upgrades affecting monitoring system integration. The Hannover-Braunschweig region develops embedded cybersecurity engineering capacity for IEC 81001-5-1 compliance.
Berlin-Brandenburg
Charité – Universitätsmedizin Berlin leads post-discharge chronic disease management trials using compressed telemetry stacks. The Berlin Senate Department for Health oversees implementation of EU AI Act risk-classification frameworks for algorithm-enabled devices. The capital region attracts firmware architects specializing in medical device threat modeling for MDR compliance.
Germany Patient Monitoring Market Competitive Landscape
The competitive structure tilts toward diversified health technology conglomerates with parallel imaging and monitoring portfolios. Domestic manufacturers leverage proximity to regulatory authorities for accelerated MDR turnaround times, while multinational device makers compete through integrated software-hardware bundles. Two archetypes dominate: vertically integrated hospital solution providers and cardiac rhythm management specialists with targeted clinical dossiers. Competitive moves concentrate on regulatory co-development partnerships and unbundled procurement strategies separating hardware capital expenditure from analytics subscriptions.
Among Germany-based diversified manufacturers, Drägerwerk AG & Co. KGaA and Siemens Healthineers occupy positions exemplifying the integrated-solution archetype, with the former representing domestic manufacturing agility and the latter anchoring imaging-monitoring convergence. Biotronik SE & Co. KG exemplifies the specialized cardiac pathway, occupying a position within the rhythm management tier where targeted clinical evidence generation supports MDR navigation. These three entities collectively represent the structural spectrum from broad hospital infrastructure to focused therapeutic monitoring applications.
| Leading Market Players |
|---|
| Drägerwerk AG & Co. KGaA |
| Biotronik SE & Co. KG |
| Siemens Healthineers |
| Medtronic |
| Koninklijke Philips |
| GE Healthcare |
| Masimo Corporation |
| Abbott Laboratories |
| Fresenius SE & Co. KGaA |
| Others |
Supply & Pricing Matrix
Analog front-end chip procurement from Taiwan-based foundries feeds through three distinct pricing tiers for German patient monitoring systems, with 24-bit ADC component lead-time volatility compressing margins on high-fidelity hemodynamic platforms while subscription-based analytics software captures recurring revenue above hardware depreciation curves.
Pricing Analysis
The bundled-vs-unbundled service split now dominates German hospital procurement, with Bavarian and North Rhine-Westphalian purchasing committees separating capital expenditure for bedside monitors from recurring subscriptions for predictive analytics. Price differentiation hinges on MDR certification tier and embedded AI diagnostic capability, with Class IIa devices commanding premium positioning over legacy IEC 60601-1 third edition hardware. Pricing pressure stems from sickness fund reimbursement compression for standard vital signs monitoring, squeezing mid-tier manufacturers lacking software recurring revenue. Secondary hospitals in Saxony exhibit highest price sensitivity due to constrained capital budgets, while university hospital networks prioritize interoperability premiums over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for critical semiconductor components now mandate multi-supplier qualification for analog front-end chips, with German device makers qualifying both Taiwan and South Korean foundry capacity to mitigate single-source vulnerability. Raw material dependencies center on 24-bit ADC components, Bluetooth Low Energy radio modules, and medical-grade sensor substrates. Supply chain risk concentrates in Taiwan-based foundry concentration for high-fidelity ECG acquisition chips, exposing manufacturers to geopolitical logistics chokepoints. Distribution runs through regional medical device distributors serving hospital procurement committees, with direct-to-hospital contracting expanding for integrated monitoring suite deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German patient monitoring offers margin expansion through software-as-a-service tiering, where predictive algorithm subscriptions offset hardware commoditization while MDR compliance costs filter out undercapitalized competitors.
For Market Incumbents: Anchor market position through backward integration into firmware development capacity, capturing scarce IEC 81001-5-1 cybersecurity engineering talent concentrated in Munich and Berlin. Defend against modular architecture disruptors by embedding AI-enabled arrhythmia detection as standard rather than premium-tier features, while accelerating MDR Article 117 pathway navigation to outpace mid-tier manufacturers with limited clinical evidence infrastructure. For New Entrants and Emerging Players: Long-term care facilities represent the most penetrable channel partner target, with radar-based contactless sensing for fall prevention and neonatal applications offering white-space entry outside contested acute-care procurement. Home care reimbursement expansion under German Social Code Book V creates ambulatory telemetry openings for simplified-interface wearable patches, with cellular-connected pulse oximeter partnerships providing fastest route to sickness fund inclusion. For Investors and Strategic Acquirers: Consolidation pressure builds where MDR Annex XIV post-market surveillance costs exceed mid-tier manufacturer cash flow sustainability. Five-to-ten year viability favors specialized cardiac rhythm management platforms with targeted clinical dossiers over undifferentiated hardware vendors. Watch for Fraunhofer IPA co-development program exits as inflection signal for AI-interpretable hemodynamic monitoring acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Recertification Fast-Track | Accelerated BfArM turnaround times compress competitor response windows for legacy platform replacements. |
| AI Algorithm MLOps Pipeline | Automated model drift detection satisfies EU AI Act Class IIa continuous accuracy tracking mandates. |
| Radar Contactless Sensing Integration | Fraunhofer IPA co-development opens non-wearable monitoring for burn wards and neonatal units. |
| Hospital Network Standardization Partnership | Single-vital-sign platform consolidation across Klinikum rechts der Isar and University Hospital Cologne creates procurement lock-in. |
| Sickness Fund Reimbursement Strategy | German Social Code Book V ambulatory telemetry codes reward post-discharge wearable ECG patch deployment. |
Research Methodology
Multiple input streams — hospital procurement database analysis, GPO contract documentation, and BfArM regulatory filing review — were reconciled against primary interviews with biomedical engineering directors, hospital purchasing committee members, and GPO contracts managers. Secondary validation drew from DIN EN ISO standard revision records, sickness fund reimbursement code updates, and Fraunhofer IPA research program disclosures. Bottom-up device shipment modeling and top-down healthcare IT expenditure analysis were triangulated to cross-verify market sizing.
Data-stream reconciliation across hardware form factor, connectivity architecture, care setting, and clinical application dimensions generated segment-level projections over the analysis window. CAGRs were derived from installed base evolution, replacement cycle compression, and reimbursement elasticity modeling. Forecast inputs incorporated MDR implementation timeline phasing, semiconductor supply lead-time volatility, and sickness fund ambulatory telemetry coverage expansion trajectories.
Revisions become necessary when BfArM enforcement intensity, Taiwan foundry capacity allocation, or sickness fund reimbursement code modifications materialize outside modeled parameters. Deviation in EU AI Act risk-classification implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Central Patient Monitoring System Market
Patient Monitoring
Sleep Monitoring Devices Market
Patient Monitoring
Asia-Pacific Respiratory Monitoring Market
Patient Monitoring
United States Patient Monitoring Market
Patient Monitoring
Holter Monitoring Systems Market
Patient Monitoring
US Remote Patient Monitoring and Care Market
Patient Monitoring
Asia Pacific Wireless Healthcare Market
Patient Monitoring
Heart Beat Monitor and Sensor Market
Patient Monitoring
Bedside Monitors Market
Patient Monitoring
South America Patient Monitoring Market
Patient Monitoring
Global Ambulatory Blood Pressure Monitoring (ABPM) Devices Market
Patient Monitoring
Middle East and Africa Fetal and Neonatal Monitoring Market
Patient Monitoring
Holter Monitor Market
Patient Monitoring
MR Vital Sign Monitors Market
Patient Monitoring
Health Sensors Market
Patient Monitoring
Wrist Blood Pressure Monitors Market