
 Global Vital Sign Monitoring Market | 2026-2036
Global Vital Sign Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vital Sign Monitoring Market Foresight
The EU Medical Device Regulation is shifting procurement criteria toward continuous connectivity and cybersecurity validation across connected vital sign platforms. Medtronic leverages its integrated hospital-to-home portfolio to sustain service contracts with large health systems. Koninklijke Philips anchors its position through intensive R&D spending on photoplethysmography algorithms. GE Healthcare dominates imaging-adjacent monitoring installations in acute care settings across North America and Western Europe.
Vital sign monitoring encompasses the continuous or periodic measurement of physiological parameters including heart rate, blood pressure, respiratory rate, blood oxygen saturation, and body temperature, typically achieved through non-invasive sensor arrays sampling at 250-500 Hz with wireless transmission to clinical information systems. Wearable monitors and remote patient monitors are capturing the fastest expansion as reimbursement codes in the United States and Germany explicitly cover ambulatory cardiac and respiratory surveillance. Bedside monitors retain the largest installed base in hospitals but face margin compression from commoditized hardware and software-as-a-service conversion pressures.
The FDA enforces premarket clearance pathways for Class II monitoring devices under 21 CFR 870, while the EMA coordinates Notified Body oversight through the MDR framework, and Japan's PMDA maintains distinct approval requirements for software-enabled diagnostics that slow cross-border platform launches. Stakeholders must track evolving interoperability mandates from these regulators to determine whether to pursue modular certification or unified global platform architectures.
Market Dynamics
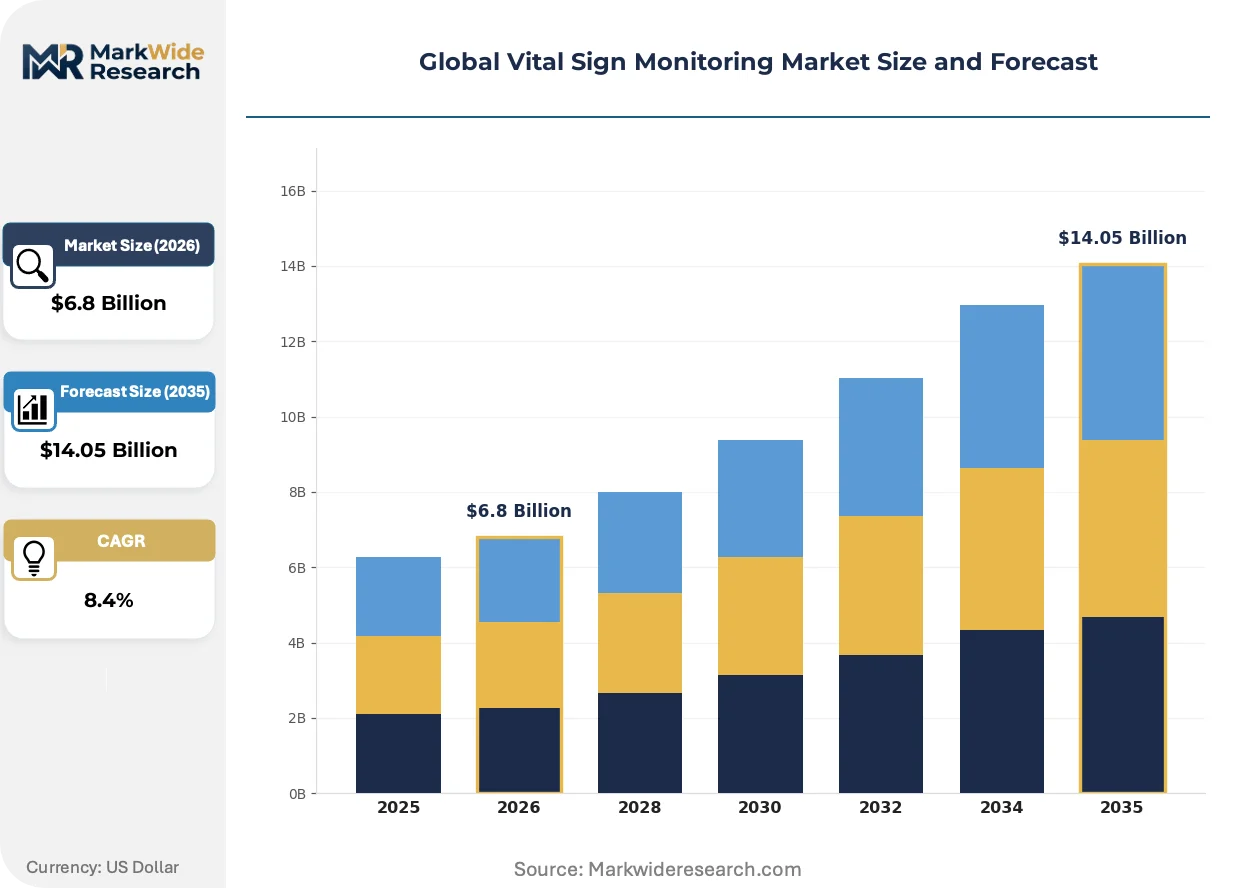
The EU Medical Device Regulation is compressing certification timelines for connected vital sign platforms while reimbursement expansion in the United States and Germany pulls hardware procurement toward subscription-based remote patient monitoring models.
Growth Catalysts
- MDR Compliance Mandates:The EU Medical Device Regulation forces hospital systems to replace legacy bedside monitors with cybersecurity-validated connected platforms, creating replacement demand across Western European acute care networks.
- Photoplethysmography Advancement:Algorithmic improvements in optical heart rate sensing enable single-sensor wearables to replace multi-lead ECG patches for ambulatory cardiac surveillance in home healthcare settings.
- Japan's PMDA Software Pathway:Japan's Pharmaceuticals and Medical Devices Agency streamlined approval for AI-enabled diagnostic algorithms, accelerating cross-border launches of predictive vital sign analytics.
Market Restraints
- Semiconductor Supply Concentration:Analog front-end chips for biosignal acquisition concentrate in Taiwanese foundry capacity, exposing monitor manufacturers to geographic supply disruption risk.
- Reimbursement Fragmentation:Germany's Diagnosis-Related Group system and the United States' fragmented payer landscape create pricing inconsistency that stalls standardized platform deployment.
- Sensor Calibration Drift:Optical sensors in wearable form factors exhibit signal degradation from skin tone variation and motion artifact, limiting clinical equivalence to wired alternatives.
Strategic Opportunities
- India's PLI Scheme:India's Production Linked Incentive scheme for medical electronics offers cost-advantaged manufacturing capacity for export-oriented monitor assembly.
- Continuous Glucose-Vital Convergence:Integration of metabolic and cardiorespiratory streams into unified dashboards creates new value pools for diabetes management platforms.
- Retail Pharmacy Distribution:CVS Health and Walgreens in the United States are building remote monitoring infrastructure, opening direct-to-consumer channels bypassing hospital procurement.
Industry Challenges
- Interoperability Certification Backlog:FDA 510(k) reviewers face queue delays for devices claiming Health Level Seven integration, extending time-to-revenue for connected platforms.
- Biomedical Engineering Talent Scarcity:Signal processing expertise for artifact rejection algorithms concentrates in Boston and Tel Aviv clusters, creating recruitment bottlenecks for distributed R&D teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vital Sign Monitoring Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Monitors, Bedside Monitors, Remote Patient Monitors, Ambulatory Devices, Portable Monitors Technology: Optical Sensors, Bioelectrical Impedance, Acoustic Sensors, Thermal Sensors, Photoplethysmography Application: Critical Care, Home Healthcare, Telehealth, Fitness Tracking, Sports Performance End User: Hospitals, Ambulatory Care Centers, Diagnostic Laboratories, Elderly Care Facilities |
| Companies Covered | Medtronic, Koninklijke Philips, GE Healthcare, Masimo, Omron Healthcare, Nihon Kohden, Mindray, Baxter International, A&D Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vital Sign Monitoring Market Shifts & Advancements
Edge computing architectures and federated learning frameworks are redistributing where vital sign data is processed, shifting value capture from hardware manufacturers toward algorithm licensors and cloud infrastructure providers.
Sensor fusion technology is modularizing how multi-parameter monitoring devices are architected. Discrete photoplethysmography, bioimpedance, and accelerometer modules now integrate through standardized digital interfaces rather than custom analog circuitry. Hospital biomedical engineering teams in Germany and the United States are adopting these building blocks to configure ward-specific monitoring stacks. The shift is modularizing vendor lock-in patterns and compressing margins for integrated device manufacturers.
REACH restrictions on persistent organic pollutants in electronic medical devices are forcing redesigns of cable insulation and sensor housings across European supply chains. The European Chemicals Agency's substance candidate list now captures phthalates common in legacy patient cable assemblies. Monitor OEMs serving EU health systems are accelerating qualification of thermoplastic elastomer alternatives, with acute care bedside units facing the steepest compliance cost escalation.
Health system purchasing consortia in the United States are unbundling device acquisition from data analytics subscriptions, reversing decade-long bundled contracting conventions. Premier and Vizient group purchasing organizations now separately evaluate hardware performance and algorithm licensing terms. This bifurcation is most pronounced in integrated delivery networks with captive accountable care organization risk, where internal data science teams demand API-accessible raw waveform data rather than black-box diagnostic outputs.
Global Vital Sign Monitoring Market Segmentation
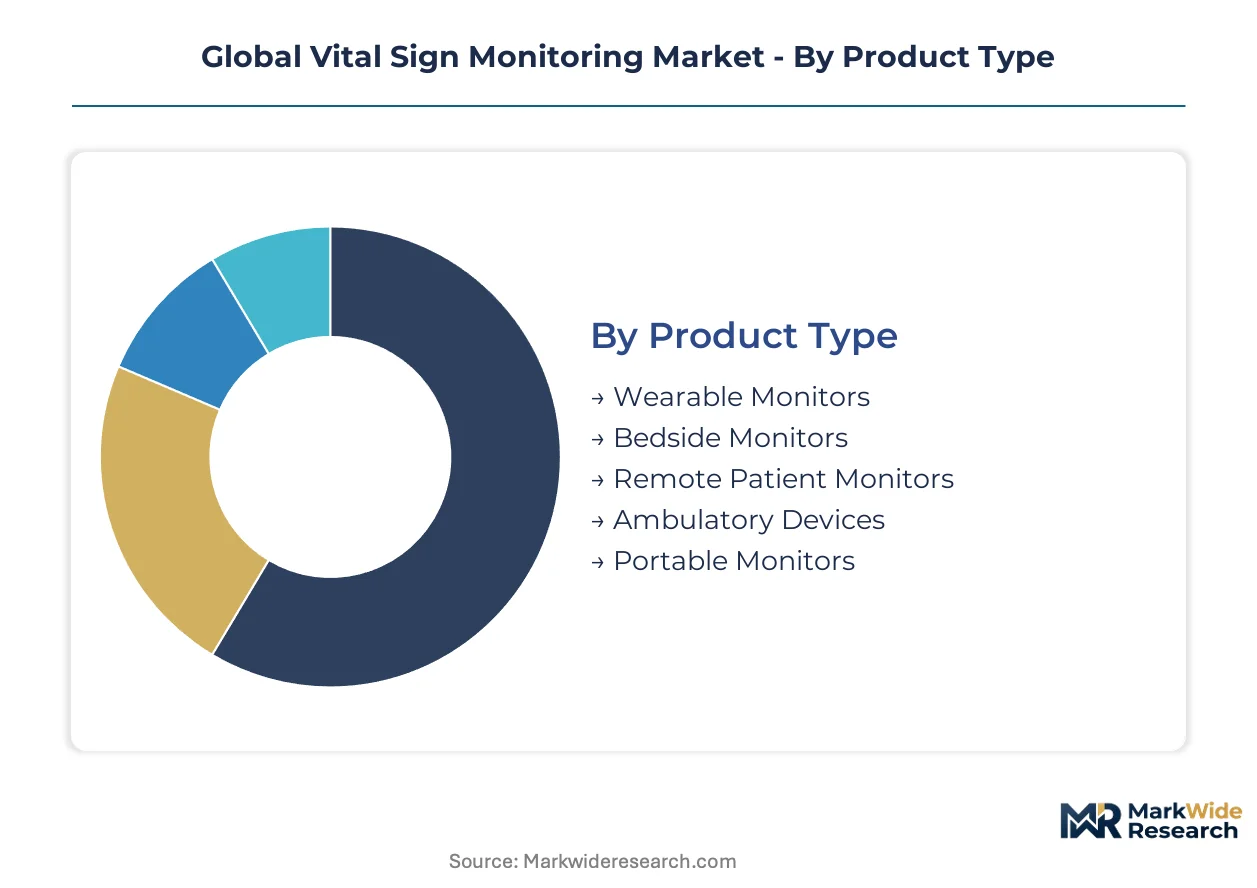
Vital sign monitoring segments diverge sharply in regulatory burden and reimbursement eligibility. FDA 510(k) pathways favor established bedside platforms while MDR compliance costs reshape wearable and remote categories.
Product Type:
Certification requirements split across Class II 510(k) clearances for hospital-grade hardware versus self-certified wellness devices exempt from premarket review.
- Wearable Monitors:Photoplethysmography-enabled wrist and finger sensors sample at 100-512 Hz for ambulatory cardiac surveillance. Demand concentrates in United States home healthcare settings where CMS reimbursement codes now cover remote physiological monitoring for chronic heart failure.
- Bedside Monitors:Multi-parameter platforms integrate ECG, SpO2, NIBP, and respiration through modular parameter boards. German hospital procurement favors these units for intensive care wards under Diagnosis-Related Group reimbursement frameworks that reward length-of-stay reduction.
- Remote Patient Monitors:Cellular-connected hub devices aggregate data from peripheral sensors for cloud transmission.
- Ambulatory Devices:Holter monitors and event recorders capture extended ECG datasets for arrhythmia detection.
- Portable Monitors:Battery-powered multi-parameter units serve emergency medical services and field hospital deployments.
Leading the category by volume: Bedside Monitors. Growing fastest: Wearable Monitors.
Technology:
Sensor modalities differentiate by signal fidelity requirements and power budgets, with optical methods displacing electrical contact in consumer-facing applications.
- Photoplethysmography:LED-photodiode arrays detect blood volume changes at green or infrared wavelengths, enabling heart rate and SpO2 estimation without skin preparation. Algorithm licensors in Boston and Tel Aviv clusters now command premium licensing fees for motion-tolerant implementations.
- Optical Sensors:Broad category encompassing PPG, camera-based rPPG, and spectroscopic methods for hydration and glucose proxy measurement.
- Bioelectrical Impedance:Four-electrode configurations measure tissue resistance for body composition and thoracic fluid status estimation.
- Acoustic Sensors:Contact microphones and accelerometers capture heart sounds, lung sounds, and snoring patterns for sleep apnea screening.
- Thermal Sensors:Infrared thermopiles enable non-contact core temperature estimation from facial vasculature.
Photoplethysmography commands the largest installed base. Optical Sensors are expanding most quickly into fitness and wellness channels.
Application:
Clinical versus consumer endpoints determine accuracy tolerances, with FDA-cleared devices requiring ±2% SpO2 precision versus ±5% for wellness exemptions.
- Critical Care:Continuous invasive arterial pressure and advanced hemodynamic monitoring in surgical and trauma settings. United States academic medical centers drive replacement demand as cybersecurity-validated platforms displace legacy devices.
- Home Healthcare:Post-acute surveillance for COPD, heart failure, and hypertension management. German statutory health insurers now reimburse telemonitoring for defined chronic disease cohorts.
- Telehealth:Synchronous video visits augmented by real-time biometric streaming.
- Fitness Tracking:Consumer wristbands and smartwatches with wellness-grade heart rate and sleep staging.
- Sports Performance:Team and individual athlete monitoring for load management and recovery optimization.
Critical Care generates the highest revenue per unit. Home Healthcare shows the steepest expansion trajectory as reimbursement frameworks mature.
End User:
Procurement authority and technical integration requirements vary across facility types, with hospitals demanding full EHR interoperability versus standalone operation in elderly care.
- Hospitals:Integrated delivery networks in the United States and university hospitals in Germany consolidate purchasing through Premier and Vizient group purchasing organizations. Biomedical engineering teams specify Health Level Seven integration and cybersecurity validation.
- Ambulatory Care Centers:Same-day surgery and infusion centers require compact, rapid-deployment monitoring for procedural sedation.
- Diagnostic Laboratories:Sleep centers and cardiac stress testing facilities need specialized polysomnography and exercise tolerance platforms.
- Elderly Care Facilities:Skilled nursing and assisted living operators in Japan deploy passive monitoring to reduce fall risk and detect nocturnal events.
Hospitals dominate capital expenditure. Elderly Care Facilities are gaining share fastest as aging demographics reshape care delivery sites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Boston anchors algorithmic development for photoplethysmography signal processing, while Minneapolis-St. Paul sustains hospital-to-home platform integration. Tel Aviv and Eindhoven concentrate motion-tolerant optical sensing R&D. Regulatory divergence across FDA, EMA, and PMDA frameworks shapes where manufacturers prioritize certification investments.
United States
CMS reimbursement codes now explicitly cover remote physiological monitoring for chronic heart failure, accelerating home healthcare procurement. The FDA enforces 510(k) premarket clearance under 21 CFR 870 for Class II devices, with reviewers facing queue delays for Health Level Seven integration claims. Premier and Vizient group purchasing organizations in Chicago and Irving unbundle hardware acquisition from analytics subscriptions, reshaping vendor contracting.
Germany
Statutory health insurers reimburse telemonitoring for defined COPD and heart failure cohorts, pulling procurement toward subscription-based models. The EU Medical Device Regulation compresses certification timelines for cybersecurity-validated connected platforms. Berlin and Munich hospital systems replace legacy bedside monitors under Diagnosis-Related Group frameworks that reward length-of-stay reduction.
Japan
Aging demographics drive passive monitoring deployment in skilled nursing facilities to reduce fall risk and detect nocturnal events. The Pharmaceuticals and Medical Devices Agency streamlined approval pathways for AI-enabled diagnostic algorithms. Osaka and Nagoya medical device clusters accelerate cross-border launches of predictive vital sign analytics platforms.
India
The Production Linked Incentive scheme for medical electronics offers cost-advantaged manufacturing capacity for export-oriented monitor assembly. CDSCO regulatory harmonization with IMDRF standards accelerates import substitution for critical care devices. Bengaluru and Hyderabad EMS clusters scale photoplethysmography module production for global wearable OEMs.
United Kingdom
NHS England integrated care systems consolidate purchasing for remote patient monitoring to manage post-acute surgical recovery. MHRA post-Brexit regulatory autonomy maintains CE marking recognition while building distinct UKCA pathways. Cambridge and Oxford biomedical engineering hubs specialize in federated learning frameworks for edge-computing vital sign architectures.
Global Vital Sign Monitoring Market Competitive Landscape
The competitive structure tilts toward diversified health technology conglomerates with integrated hospital-to-home portfolios. Tier-one positions concentrate among firms with captive distribution through group purchasing organizations and health system service contracts. Three archetypes dominate: imaging-adjacent acute care specialists, algorithm-centric wearable platform licensors, and diversified critical care device manufacturers. Competitive moves center on sensor fusion module standardization and unbundled hardware-software contracting to capture recurring revenue streams.
Within the diversified medical technology tier, Medtronic and Koninklijke Philips occupy positions shaped by intensive R&D spending and integrated portfolio breadth. Medtronic exemplifies the hospital-to-home service contract model, while Philips anchors photoplethysmography algorithm development. GE Healthcare represents the imaging-adjacent acute care archetype through multi-parameter bedside platform dominance. These three firms collectively illustrate how regulatory compliance scale and captive health system relationships determine competitive positioning.
| Leading Market Players |
|---|
| Medtronic |
| Koninklijke Philips |
| GE Healthcare |
| Masimo |
| Omron Healthcare |
| Nihon Kohden |
| Mindray |
| Baxter International |
| A&D Company |
| Others |
Supply & Pricing Matrix
United States group purchasing organizations and German hospital procurement consortia concentrate buying power for bedside monitors, anchoring contract-based subscription pricing for connected vital sign platforms. This buyer concentration compresses hardware margins while elevating recurring revenue from software analytics and cybersecurity validation services.
Pricing Analysis
Outcome-linked reimbursement anchors value-based pricing for remote patient monitoring platforms in United States home healthcare settings. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared Class II devices from self-certified wellness monitors and unregulated consumer wearables. Cost compression in economy-tier wellness devices is intensifying because of commoditized photoplethysmography module supply from Indian EMS clusters. Price sensitivity peaks among elderly care facility operators in Japan seeking passive monitoring solutions, while United States academic medical centers show lowest sensitivity due to cybersecurity compliance mandates.
Supply Chain Analysis
Analog front-end chip supply for biosignal acquisition rests on Taiwanese foundry capacity, with secondary sourcing from South Korean and United States semiconductor fabricators. Discrete photoplethysmography modules, bioimpedance sensors, and accelerometer components feed from Chinese and Indian electronics manufacturing clusters. Single-source vulnerability in Taiwanese analog chip supply exposes monitor OEMs to geographic disruption risk. Distribution runs through hospital group purchasing organizations in the United States, statutory health insurer frameworks in Germany, and retail pharmacy networks expanding into direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photoplethysmography-enabled wearables are displacing multi-lead ECG patches in ambulatory cardiac surveillance, compressing margins for legacy bedside monitor manufacturers while opening algorithm licensing value pools for optical sensing specialists.
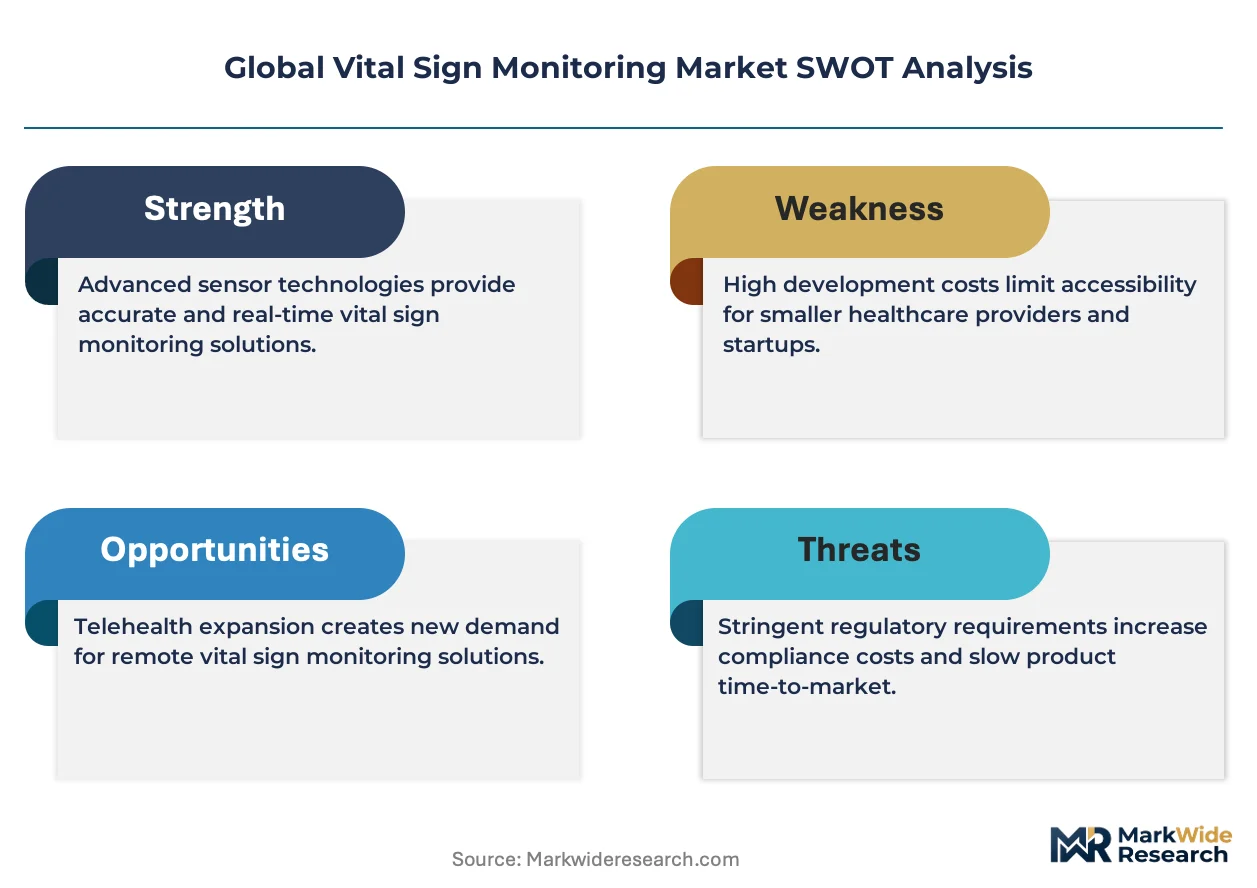
For Market Incumbents: Deepen service contract integration with United States integrated delivery networks to lock in cybersecurity-validated platform refresh cycles. Prioritize in-house production of motion-tolerant PPG algorithms to defend against Tel Aviv and Boston licensor encroachment. Accelerate CE marking pathway completion under EU MDR compressed timelines to capture Western European replacement demand. For New Entrants and Emerging Players: Direct-to-consumer retail pharmacy channels in the United States offer the most penetrable route for wellness-grade wearable monitors bypassing hospital procurement gatekeepers. Target India's PLI scheme for cost-advantaged manufacturing of photoplethysmography modules serving global OEM demand. Pursue reimbursement strategy development for German statutory health insurer telemonitoring coverage of COPD and heart failure cohorts. For Investors and Strategic Acquirers: The window for entry favors algorithm-centric platform licensors with Health Level Seven integration capabilities and FDA 510(k) clearance track records. Long-term viability hinges on federated learning framework development for edge-computing vital sign architectures. Watch Japan's PMDA AI-enabled diagnostic algorithm approval velocity as inflection indicator for predictive analytics platform valuation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compressed timelines force cybersecurity validation investment for Western European acute care access. |
| Hospital System Partnership | Premier and Vizient GPO contracts anchor recurring revenue through unbundled hardware-software subscription models. |
| Software Companion Development | FDA 510(k) clearance for algorithm modules captures value from photoplethysmography signal processing advances. |
| Reimbursement Strategy | German Diagnosis-Related Group and United States CMS code coverage determines home healthcare procurement eligibility. |
| Sensor Fusion Integration | Modular PPG, bioimpedance, and accelerometer interfaces reduce vendor lock-in and compress integrated device margins. |
Research Methodology
FDA 510(k) clearance databases, EU MDR Notified Body submission records, and CMS Medicare reimbursement code filings formed the secondary backbone for regulatory pathway mapping. Primary interviews with hospital biomedical engineers, GPO contracts managers, and PPG algorithm R&D directors in Boston and Tel Aviv clusters combined with secondary validation. Bottom-up triangulation across product-level shipment estimates and top-down reconciliation against health system capital expenditure disclosures anchored market sizing.
Historical trendline analysis of bedside monitor replacement cycles, wearable adoption curves, and remote patient monitoring reimbursement expansion informed projection modeling across the analysis window. Segmentation dimensions spanned product type, sensor technology modality, clinical versus consumer application, and end-user facility category. CAGRs derived from regression-adjusted growth rate convergence with named inputs including semiconductor supply constraints and regulatory certification backlog timelines.
The model holds under stable reimbursement code coverage and foundry capacity allocation; deviation in FDA 510(k) queue delays or Taiwan semiconductor export restrictions would shift hardware availability and pricing trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Urine Monitoring Systems Market
Patient Monitoring
Japan Patient Care Monitoring Equipment Market
Patient Monitoring
Middle East and Africa Remote Patient Monitoring Market
Patient Monitoring
United States Patient Monitoring Market
Patient Monitoring
IoT in Healthcare Market
Patient Monitoring
Australia Patient Monitoring Market
Patient Monitoring
South America Body Temperature Monitoring Market
Patient Monitoring
Remote Patient Monitoring Devices Market
Patient Monitoring
MRI Pulse Oximeters Market
Patient Monitoring
Global Body Temperature Monitoring Market
Patient Monitoring
Real-Time Location System (RTLS) in Healthcare Market
Patient Monitoring
Asia-Pacific Remote Patient Monitoring Systems Market
Patient Monitoring
Patient Monitoring Accessories Market
Patient Monitoring
South America Cardiac Monitoring Market
Patient Monitoring
Global Ambulatory Blood Pressure Monitoring (ABPM) Devices Market
Patient Monitoring
Mobile Continuous Patient Monitors Market