
 Wearable Health Sensors Market | 2026-2036
Wearable Health Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Health Sensors Market Outlook
Multi-source procurement of MEMS and optical sensor modules is restructuring supply relationships across wearable health device manufacturers. Apple Inc. leverages captive semiconductor design to control core photoplethysmography chip architectures. DexCom, Inc. anchors its position through vertically integrated continuous glucose monitoring substrate production. STMicroelectronics N.V. competes as a merchant supplier of accelerometers and gyroscopes to multiple wearable OEMs simultaneously.
Wearable health sensors comprise electromechanical and optical transducers integrated into body-worn form factors, typically operating at sampling frequencies between 100-512 Hz for cardiac applications and utilizing photodiode arrays with green LED illumination at 525 nm wavelengths for blood-oxygen estimation. Their primary commercial purpose is capturing physiological biomarkers for real-time health status transmission to clinical decision-makers or personal analytics platforms. Smartwatches now command the dominant product-type revenue pool as multipurpose devices subsume single-function fitness trackers. Chronic disease management represents the fastest-expanding application segment as payors reimburse remote patient monitoring deployments. Bluetooth retains technology leadership in connectivity protocols, though bioimpedance methods are gaining traction for body-composition analytics in premium device tiers.
FDA Software as a Medical Device frameworks and EU MDR Class IIa certification requirements shape product development timelines and market access conditions for wearable health sensor manufacturers. HIPAA compliance obligations in the United States and GDPR health-data provisions in Europe constrain cloud-architecture choices and cross-border data routing strategies. Stakeholders must monitor evolving reimbursement coding decisions by national health technology assessment bodies to anticipate which sensor modalities achieve sustainable commercial traction.
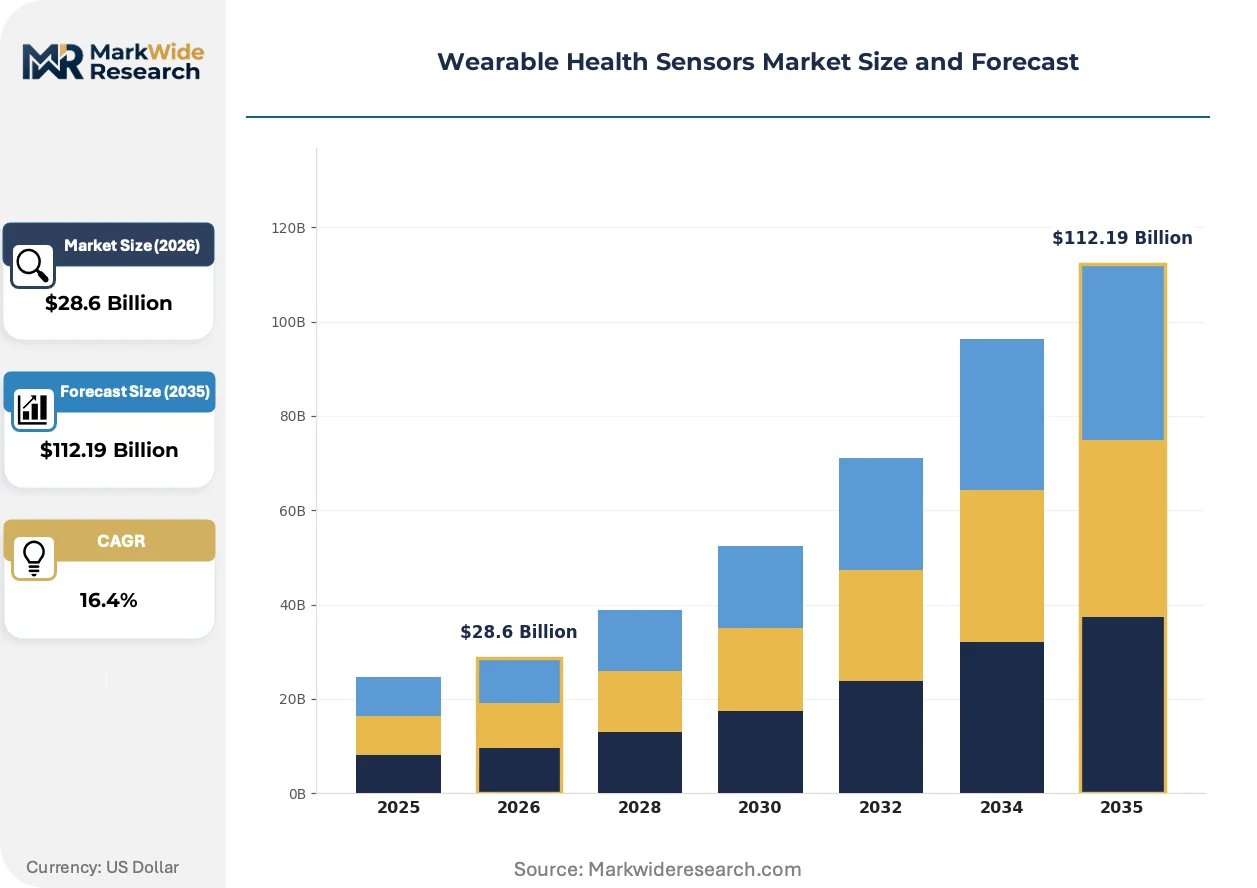
Market Dynamics
Software as a Medical Device pathways at FDA are compressing commercialization timelines for photoplethysmography and bioimpedance-based wearables, while MEMS supply concentration in East Asian foundries creates procurement bottlenecks for cardiac-monitoring form factors.
Growth Catalysts
- Remote Patient Monitoring Reimbursement:Germany's digital health reimbursement framework (DiGA) now covers prescribed wearable sensors for hypertension and diabetes management, expanding insured patient access.
- FDA SaMD Clearance Acceleration:De novo and 510(k) pathways for algorithm-driven cardiac arrhythmia detection are reducing time-to-market for smartwatch-integrated ECG applications.
- Chronic Disease Management Programs:North American health systems are expanding sensor procurement for heart failure and COPD remote monitoring, driving institutional volume commitments.
Market Restraints
- MEMS Foundry Concentration:Taiwan and South Korean semiconductor foundries control 70%+ of accelerometer and gyroscope wafer supply, creating geographic single-point-of-failure risk.
- EU MDR Class IIa Certification Friction:Extended notified body backlogs and clinical evidence requirements for blood-oxygen measurement claims are delaying EU market entry.
- Optical Sensor Cost Structure:Green LED photodiode arrays at 525 nm wavelengths remain cost-prohibitive for economy-tier fitness bands, constraining feature democratization.
Strategic Opportunities
- Underpenetrated Clinical Settings:Post-acute care facilities and skilled nursing institutions in the United States lack standardized remote monitoring protocols, representing greenfield deployment potential.
- Bioimpedance Convergence:Integration of multi-frequency bioimpedance spectroscopy with optical heart-rate sensing enables body-composition analytics previously requiring dedicated scales.
- India PLI Scheme for Electronics:Production-linked incentives for wearable device assembly are attracting contract manufacturers to establish local sensor module integration capacity.
Industry Challenges
- Biomedical Algorithm Validation Talent:Scarce expertise in IEC 62304 software lifecycle processes and clinical validation study design extends development cycles for SaMD submissions.
- Cross-Border Data Architecture Complexity:HIPAA-GDPR divergence forces dual cloud infrastructure investments, fragmenting analytics platforms and raising operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Health Sensors Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $112.19 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Health Monitors, ECG Monitors Technology: Bluetooth, NFC, Optical Sensors, Bioimpedance Application: Fitness Tracking, Chronic Disease Management, Telemedicine, Sleep Monitoring End User: Consumers, Healthcare Providers, Fitness Enthusiasts, Researchers |
| Companies Covered | Apple Inc., Fitbit Inc., Samsung Electronics Co., Ltd., STMicroelectronics N.V., Analog Devices Inc., Texas Instruments Inc., Garmin Ltd., DexCom, Inc., Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Health Sensors Market Strategic Shifts
Edge computing architectures and on-device machine learning inference are redistributing analytical workloads away from cloud dependencies, while regulatory clarity on Software as a Medical Device is unlocking new clinical claims for consumer-form-factor hardware.
Photoplethysmography chipsets with embedded arrhythmia classification algorithms are decentralizing cardiac monitoring from dedicated Holter systems to wrist-worn devices. Hospital-at-home programs and employer wellness platforms are adopting these capabilities at accelerating pace. This shift is compressing revenue capture for traditional ambulatory ECG equipment manufacturers while expanding addressable volume for multipurpose smartwatch OEMs.
EU MDR Class IIa certification requirements for blood-oxygen saturation claims are forcing wearable manufacturers to conduct clinical validation studies against arterial blood gas reference methods. The industrial consequence is elevated R&D expenditure and extended development timelines for SpO2 feature launches. Premium smartwatch tiers targeting European markets are responding by front-loading clinical evidence generation to secure notified body approvals ahead of competitors.
Institutional procurement of wearable sensor fleets is displacing individual consumer purchases in chronic disease management applications. United States health systems and risk-bearing provider groups are negotiating enterprise licensing for remote patient monitoring platforms that include subsidized device distribution. This channel rotation is most visible in Medicare Advantage plans covering heart failure and diabetes populations, where capitated reimbursement models align sensor deployment with admission reduction incentives.
Wearable Health Sensors Market Segmentation
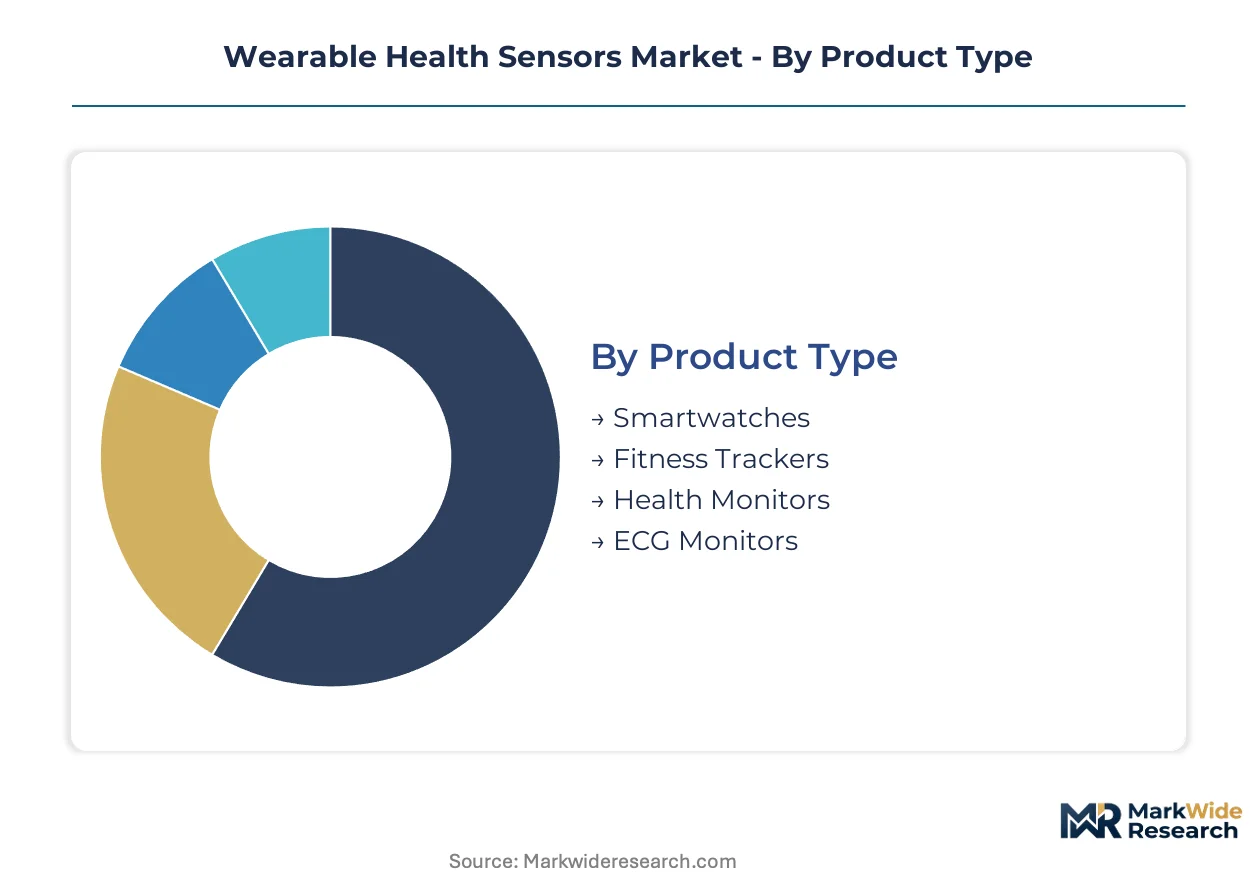
Wearable health sensor procurement splits across divergent buyer priorities: consumers optimize for multipurpose utility, while health systems demand clinical-grade validation. Technology selection and application focus determine reimbursement eligibility and commercial trajectory.
Product Type:
Form factor choice reflects the tension between convenience and clinical depth that buyers navigate.
- Smartwatches:Multipurpose wrist-worn devices integrating photoplethysmography, accelerometry, and ECG electrodes into unified chassis designs. Medicare Advantage plans in the United States are subsidizing device distribution for heart failure populations, converting consumer electronics into clinical infrastructure.
- Fitness Trackers:Dedicated activity monitors emphasizing step counting and calorie estimation with stripped-down sensor arrays. Cost-sensitive procurement in India's PLI scheme assembly corridors concentrates demand for basic optical heart-rate modules.
- Health Monitors:Single-function devices targeting specific biomarkers such as continuous glucose or blood pressure. FDA SaMD clearance pathways are accelerating commercialization timelines for algorithm-driven arrhythmia detection variants.
- ECG Monitors:Cardiac-focused wearables with medical-grade electrode configurations and Holter-equivalent sampling precision. German DiGA reimbursement coverage is expanding insured patient access for hypertension management deployments.
Smartwatches lead on scale; chronic disease management applications are driving health monitor momentum fastest.
Technology:
Connectivity and sensing modality selection constrains which clinical claims manufacturers can substantiate.
- Bluetooth:Dominant short-range wireless protocol enabling real-time data streaming to paired smartphones and clinical dashboards. North American health system procurement specifications mandate Bluetooth Low Energy for remote patient monitoring platform integration.
- NFC:Near-field communication for tap-to-pair authentication and localized data transfer without persistent connectivity. European hospital-at-home programs in France and Germany are piloting NFC for patient identity verification in sensor fleet management.
- Optical Sensors:Photodiode arrays with green LED illumination at 525 nm wavelengths for blood-oxygen and heart-rate estimation. EU MDR Class IIa certification requirements are forcing clinical validation studies against arterial blood gas reference methods.
- Bioimpedance:Multi-frequency spectroscopy for body-composition analytics previously requiring dedicated scale hardware. Premium smartwatch tiers are converging bioimpedance with optical sensing to differentiate feature sets.
Bluetooth leads on installed base; bioimpedance is climbing the fastest as body-composition analytics migrate from fitness to clinical use cases.
Application:
Use case focus determines reimbursement coding and regulatory pathway complexity.
- Fitness Tracking:Consumer wellness applications emphasizing activity quantification and performance benchmarking. Economy-tier device procurement in contract manufacturing clusters concentrates on basic accelerometer integration.
- Chronic Disease Management:Clinical monitoring for diabetes, hypertension, and heart failure with provider oversight. Germany's DiGA framework now covers prescribed wearable sensors, expanding insured patient access fastest.
- Telemedicine:Real-time physiological data transmission enabling remote clinical encounters and asynchronous specialist review. United States health systems are negotiating enterprise licensing for remote patient monitoring platforms with subsidized device distribution.
- Sleep Monitoring:Nocturnal biomarker capture for apnea screening and circadian rhythm assessment. Optical heart-rate variability algorithms are displacing dedicated polysomnography equipment in preliminary screening protocols.
Fitness tracking leads on unit volume; chronic disease management shows the steepest expansion trajectory as capitated reimbursement models align sensor deployment with admission reduction incentives.
End User:
Customer type dictates pricing tolerance, validation requirements, and procurement channel structure.
- Consumers:Individual purchasers prioritizing design aesthetics and multipurpose functionality over clinical precision. Apple's captive semiconductor design for photoplethysmography chip architectures targets this segment's premium tier.
- Healthcare Providers:Institutional procurement of sensor fleets for remote patient monitoring and hospital-at-home programs. Risk-bearing provider groups in the United States are driving volume commitments through capitated reimbursement structures.
- Fitness Enthusiasts:Performance-oriented users demanding granular biomechanical and physiological analytics. DexCom's vertically integrated continuous glucose monitoring substrate production serves this segment's precision requirements.
- Researchers:Academic and clinical trial investigators requiring raw sensor data access and protocol customization. HIPAA-GDPR divergence forces dual cloud infrastructure investments for cross-border study deployments.
Consumers lead on absolute volume; healthcare providers are gaining share fastest as institutional procurement displaces individual purchases in chronic disease applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's semiconductor foundry corridor concentrates MEMS wafer supply for accelerometer and gyroscope production serving wearable OEMs worldwide. FDA clearance pathways in the United States and Germany's DiGA reimbursement framework are accelerating commercial deployment timelines. Health system procurement across multiple geographies is shifting volume from consumer retail toward institutional channels.
United States
Medicare Advantage plans are subsidizing smartwatch distribution for heart failure and diabetes populations through capitated reimbursement structures. FDA Software as a Medical Device pathways are compressing commercialization timelines for photoplethysmography-based arrhythmia detection. The Greater Boston corridor hosts clinical validation study design expertise for IEC 62304 software lifecycle processes.
Germany
The DiGA digital health reimbursement framework now covers prescribed wearable sensors for hypertension and diabetes management, expanding insured patient access. EU MDR Class IIa certification requirements for blood-oxygen claims are forcing clinical validation studies against arterial blood gas reference methods. Berlin's health technology assessment bodies are determining which sensor modalities achieve sustainable commercial traction through reimbursement coding decisions.
China
Domestic OEMs are securing local MEMS supply through foundry relationships with Taiwan and South Korean wafer producers. NMPA medical device registration pathways are streamlining for Software as a Medical Device classifications. The Yangtze River Delta manufacturing clusters are attracting assembly capacity for economy-tier fitness bands targeting export markets.
India
The PLI scheme for electronics manufacturing is attracting contract manufacturers to establish local sensor module integration capacity. CDSCO medical device regulations are evolving to accommodate algorithm-driven health claims for wearable form factors. Karnataka's Bangalore-Tumkur electronics corridor is concentrating fitness tracker assembly for domestic and African export markets.
South Korea
Semiconductor foundries are controlling critical accelerometer and gyroscope wafer supply for global wearable OEMs. MFDS medical device approval pathways are aligning with international standards for connected health sensor submissions. Seoul's Pangyo Techno Valley is hosting R&D facilities for bioimpedance spectroscopy integration into premium smartwatch tiers.
Wearable Health Sensors Market Competitive Environment
Global majors compete with regional champions across captive semiconductor design and merchant component supply. The market structures around three tiers: integrated device manufacturers controlling core chip architectures, vertically specialized sensor producers, and merchant semiconductor suppliers serving multiple OEMs simultaneously. Strategic moves concentrate on backward integration into MEMS fabrication and algorithm-driven Software as a Medical Device clearance acquisition.
Within the integrated device tier, Apple Inc. exemplifies captive control over photoplethysmography chip architectures. DexCom, Inc. and STMicroelectronics N.V. occupy distinct positions—one representing vertically specialized substrate production for continuous glucose monitoring, the other anchoring merchant supply of accelerometers and gyroscopes to multiple wearable OEMs. These three entities collectively illustrate the competitive spectrum from closed-stack integration to open merchant supply.
| Leading Market Players |
|---|
| Apple Inc. |
| Fitbit Inc. |
| Samsung Electronics Co., Ltd. |
| STMicroelectronics N.V. |
| Analog Devices Inc. |
| Texas Instruments Inc. |
| Garmin Ltd. |
| DexCom, Inc. |
| Abbott Laboratories |
| Others |
Value Chain & Pricing Dynamics
Photoplethysmography chip miniaturization and MEMS foundry consolidation are simultaneously compressing sensor module costs and concentrating procurement leverage among East Asian wafer producers. This dual transformation rewards wearable OEMs with captive semiconductor design while squeezing margins for merchant component buyers dependent on spot-market MEMS supply.
Pricing Analysis
Input-cost pass-through from green LED photodiode arrays and accelerometer wafer supply is reshaping tiered pricing across premium, standard, and economy device levels. FDA SaMD certification tier and volume scale represent the primary price differentiation drivers, with clinical-grade validation commanding substantial premiums over consumer wellness variants. Pricing pressure stems from optical sensor cost structures that remain prohibitive for basic fitness bands, eroding feature democratization timelines. Healthcare providers demonstrate lowest price sensitivity due to capitated reimbursement models, while individual consumers in emerging assembly markets exhibit highest elasticity.
Supply Chain Analysis
Freight cost volatility from East Asian semiconductor corridors is amplifying landed cost uncertainty for European and North American wearable OEMs sourcing MEMS components. Taiwan, South Korea, and China anchor global supply for accelerometer and gyroscope wafer production, with photodiode arrays and ECG electrode substrates representing critical input dependencies. Single-source vulnerability at Taiwanese foundries creates geographic concentration risk for cardiac-monitoring form factors. Distribution runs through enterprise licensing channels for health system procurement and direct-to-consumer retail for individual purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wearable health sensors market functions as a stable compounder, with chronic disease management reimbursement expansion providing durable demand visibility across economic cycles.
For Market Incumbents: Deepen backward integration into MEMS fabrication to secure accelerometer supply against Taiwan foundry concentration risk. Prioritize FDA SaMD clearance acquisition for algorithm-driven cardiac arrhythmia detection to defend against emerging consumer-electronics entrants with clinical ambitions. Channel control through hospital system partnerships represents the critical lever for institutional procurement displacement of individual purchases. For New Entrants and Emerging Players: Contract manufacturers serving India's PLI scheme electronics corridor offer the most penetrable entry pathway for economy-tier fitness tracker assembly. Post-acute care facilities and skilled nursing institutions in the United States present greenfield deployment potential lacking standardized remote monitoring protocols. A reimbursement-first go-to-market angle targeting Germany's DiGA framework coverage for prescribed hypertension sensors enables faster commercial traction than consumer retail competition. For Investors and Strategic Acquirers: Valuations sit cheapest among vertically specialized sensor producers with captive substrate production and clinical validation capabilities. The five-to-ten year viability window favors acquisition targets with established EU MDR Class IIa certification pathways and health system procurement relationships. Watch for inflection signals in national health technology assessment body reimbursement coding decisions that determine which sensor modalities achieve sustainable commercial traction.| Strategic Initiative | Industry Significance |
|---|---|
| Software as a Medical Device Clearance | FDA SaMD pathways compress commercialization timelines for photoplethysmography-based arrhythmia detection. |
| MEMS Foundry Partnership | Taiwan and South Korean wafer supply agreements secure accelerometer procurement against geographic concentration risk. |
| Hospital System Enterprise Licensing | Capitated reimbursement models in Medicare Advantage plans align sensor deployment with admission reduction incentives. |
| EU MDR Class IIa Certification | Clinical validation against arterial blood gas methods unlocks blood-oxygen claims in European markets. |
| Production-Linked Incentive Assembly | India's PLI scheme attracts contract manufacturers establishing local sensor module integration capacity. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each regional cluster combining executive interviews with wearable device manufacturers, procurement leads at health systems, regulatory affairs specialists, and MEMS foundry operations managers. Secondary validation draws from FDA 510(k) and De novo clearance databases, EU MDR notified body submission records, CMS Medicare reimbursement coding decisions, and customs trade data for sensor module flows. Bottom-up sensor unit demand modeling triangulates against top-down health system procurement budget analysis.
Rate-of-change decomposition across the analysis window separates volume expansion from pricing trajectory and mix-shift effects. Segmentation dimensions include product type, sensing technology, application focus, and end-user archetype, with regional regulatory framework and reimbursement eligibility status modeled as cross-cutting variables. CAGR derivation incorporates historical health system procurement cycle analysis and algorithm-driven feature adoption curves for clinical-grade wearables.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA SaMD pathway evolution, EU MDR notified body capacity constraints, and MEMS foundry geographic diversification progress. Forecasts reflect assumptions about reimbursement coding expansion and clinical validation study success rates that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Abetalipoproteinemia Monitoring Systems Market
Patient Monitoring
Europe Patient Monitoring Devices Market
Patient Monitoring
Remote Patient Monitoring System Market
Patient Monitoring
China ICU Patient Monitor Market
Patient Monitoring
Global Epilepsy Monitoring Devices Market
Patient Monitoring
South Korea Patient Monitoring Market
Patient Monitoring
Latin America Self -Monitoring Blood Glucose Market
Patient Monitoring
Middle East and Africa Remote Patient Monitoring Market
Patient Monitoring
Europe Cardiac Holter Monitor Market
Patient Monitoring
Europe Fetal and Neonatal Monitoring Market
Patient Monitoring
Fetal and Neonatal Heart Monitor Market
Patient Monitoring
Cerebral Oximetry Monitoring Market
Patient Monitoring
North America Patient Temperature Management Market
Patient Monitoring
Heart Monitoring Devices Market
Patient Monitoring
Europe Hemodynamic Monitoring Market
Patient Monitoring
Global Body Temperature Monitoring Market