
 Patient Monitoring Pods Market | 2026-2036
Patient Monitoring Pods Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Monitoring Pods Market Analytics
ISO 13485 certification cycles for wireless medical devices is collapsing from twenty-four months to under fourteen months at leading notified bodies. Koninklijke Philips N.V. leverages its bedside monitor installed base across European hospital networks to accelerate pod deployment. GE Healthcare anchors its position through in-house sensor manufacturing that reduces component lead times. Mindray Medical International competes aggressively on portable monitor configurations for emerging health systems in Southeast Asia.
Patient monitoring pods are self-contained wireless enclosures integrating multi-parameter biosensors, edge computing modules, and encrypted telemetry transceivers for continuous physiological surveillance outside traditional ICU settings. These units typically process electrocardiography, pulse oximetry, and respiratory rate data at sampling frequencies exceeding 250 Hz before cloud transmission. Hospitals command the dominant share of procurement volume, though home care installations are expanding fastest as reimbursement frameworks shift toward remote patient management. Bluetooth-enabled pods lead technology deployments for short-range clinical environments, while cellular connectivity captures the steepest growth trajectory for rural and ambulatory applications.
FDA premarket notification requirements under 510(k) pathways govern wireless medical device approvals in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for pod classifications above Class IIa. Japan's PMDA enforces distinct electromagnetic compatibility testing that extends certification timelines for manufacturers lacking prior METI filings. Stakeholders must weigh regulatory jurisdiction sequencing against reimbursement velocity when prioritizing geographic rollout schedules.
Market Dynamics
Health system consolidation in the United States is compressing procurement cycles and favoring vendors with centralized monitoring platforms that integrate across hospital networks. This structural force is reshaping vendor selection criteria toward enterprise-scale deployment capabilities and interoperability certification.
Growth Catalysts
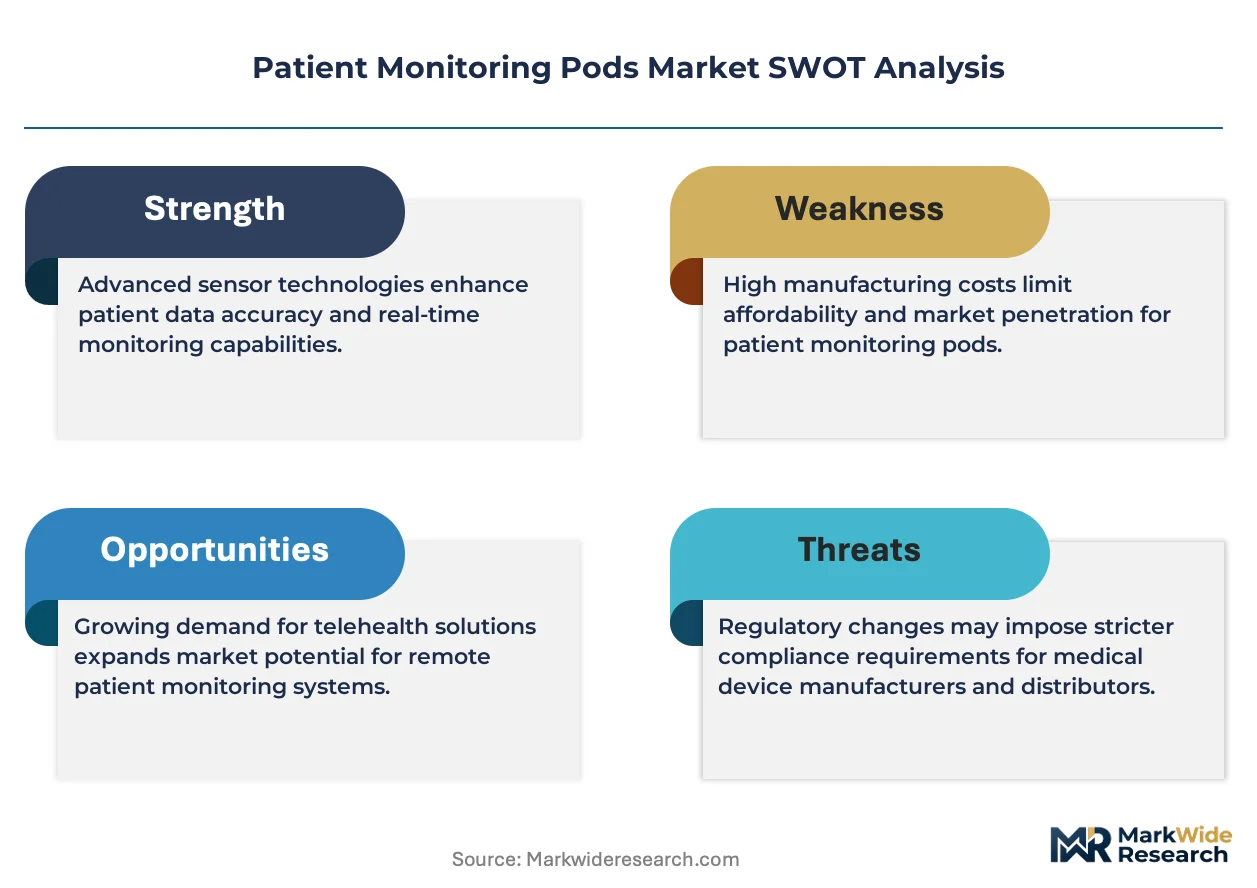
- FDA 510(k) pathway compression:Wireless medical device clearance timelines have shortened substantially, accelerating product-to-market velocity for pod manufacturers targeting US hospital systems.
- Bluetooth Low Energy maturation:Short-range clinical environments now deploy pods with sub-10mW power consumption, enabling continuous multi-parameter monitoring without bedside tethering.
- German hospital infrastructure expansion:Remote patient monitoring networks across Bavaria and North Rhine-Westphalia are driving pod procurement for step-down units and emergency department overflow.
Market Restraints
- EU MDR clinical evidence requirements:Class IIa and above pod classifications demand expanded post-market surveillance studies, extending certification investment horizons.
- Semiconductor foundry concentration:Edge computing module fabrication depends on Taiwan-based advanced node capacity, exposing supply timelines to geopolitical friction.
- Disposable biosensor cost structure:Single-use electrode arrays represent 40-60% of per-procedure economics, limiting adoption in price-sensitive health systems.
Strategic Opportunities
- Cellular connectivity for rural ambulatory:LTE-M and NB-IoT modules enable pod deployment beyond hospital WiFi perimeters, capturing home-based chronic disease management.
- Japan PMDA electromagnetic compatibility:Manufacturers with prior METI filings can access premium hospital procurement channels through accelerated regulatory recognition.
- Edge AI inference convergence:On-device arrhythmia detection algorithms reduce cloud transmission bandwidth requirements and enable real-time clinical alerting without network dependency.
Industry Challenges
- ISO 13485 quality management system implementation:Medical device software lifecycle processes require specialized personnel that mid-scale manufacturers struggle to recruit.
- Legacy electronic health record integration:HL7 FHIR compatibility gaps force custom interface development, extending deployment timelines and inflating professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Monitoring Pods Market |
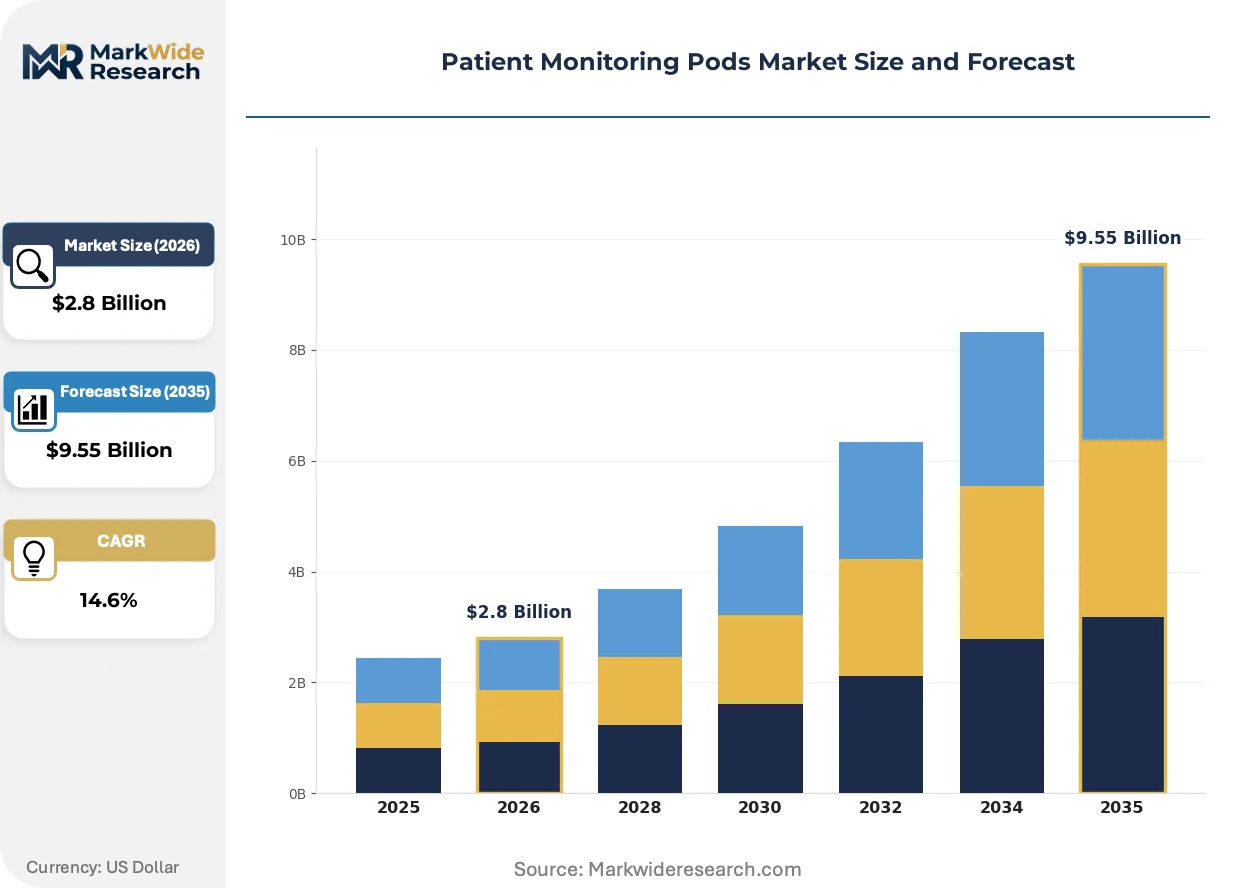
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Bedside Monitors, Portable Monitors, Mobile Applications Technology: Bluetooth, Wi-Fi, Cellular, NFC End User: Hospitals, Home Care, Rehabilitation Centers, Long-term Care Facilities Application: Chronic Disease Management, Emergency Care, Post-operative Monitoring, Health Tracking |
| Companies Covered | Drägerwerk AG & Co. KGaA, Koninklijke Philips N.V., GE Healthcare, Mindray Medical International, Hill-Rom Holdings, Medtronic, Abbott Laboratories, Nihon Kohden, Omron Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Monitoring Pods Market Evolving Landscape
Continuous physiological surveillance is migrating from centralized nursing stations to distributed edge nodes, fundamentally altering where clinical decision-making occurs. This spatial redistribution of monitoring intelligence is compressing response latency and expanding the addressable patient population beyond traditional ICU boundaries.
Multi-parameter biosensor miniaturization is supplanting modular rack-based monitoring architectures in step-down and general ward deployments. Hospital systems in the United States are adopting these integrated enclosures at accelerating pace, with health networks in Texas and Florida completing thousand-bed rollouts within eighteen-month windows. The structural consequence is a collapse in per-bed monitoring infrastructure footprint and a shift toward subscription-based equipment provisioning.
The EU Medical Device Regulation's software-as-a-medical-device classification guidance is forcing pod manufacturers to restructure quality management systems around cybersecurity validation and post-market performance monitoring. Industrial consequence includes mandatory unannounced audits of notified bodies and expanded clinical evidence requirements for algorithm updates. Wireless pod vendors targeting European hospital procurement are responding by establishing in-country regulatory affairs functions in Germany and the Netherlands.
Health system procurement committees are consolidating vendor relationships around enterprise monitoring platforms that span acute, ambulatory, and home settings. Group purchasing organizations are displacing individual hospital negotiations, concentrating contract volume with three to four full-stack suppliers. This concentration is most visible in the southeastern United States, where hospital network mergers have reduced qualified vendor lists by half across cardiac monitoring categories.
Patient Monitoring Pods Market Segmentation
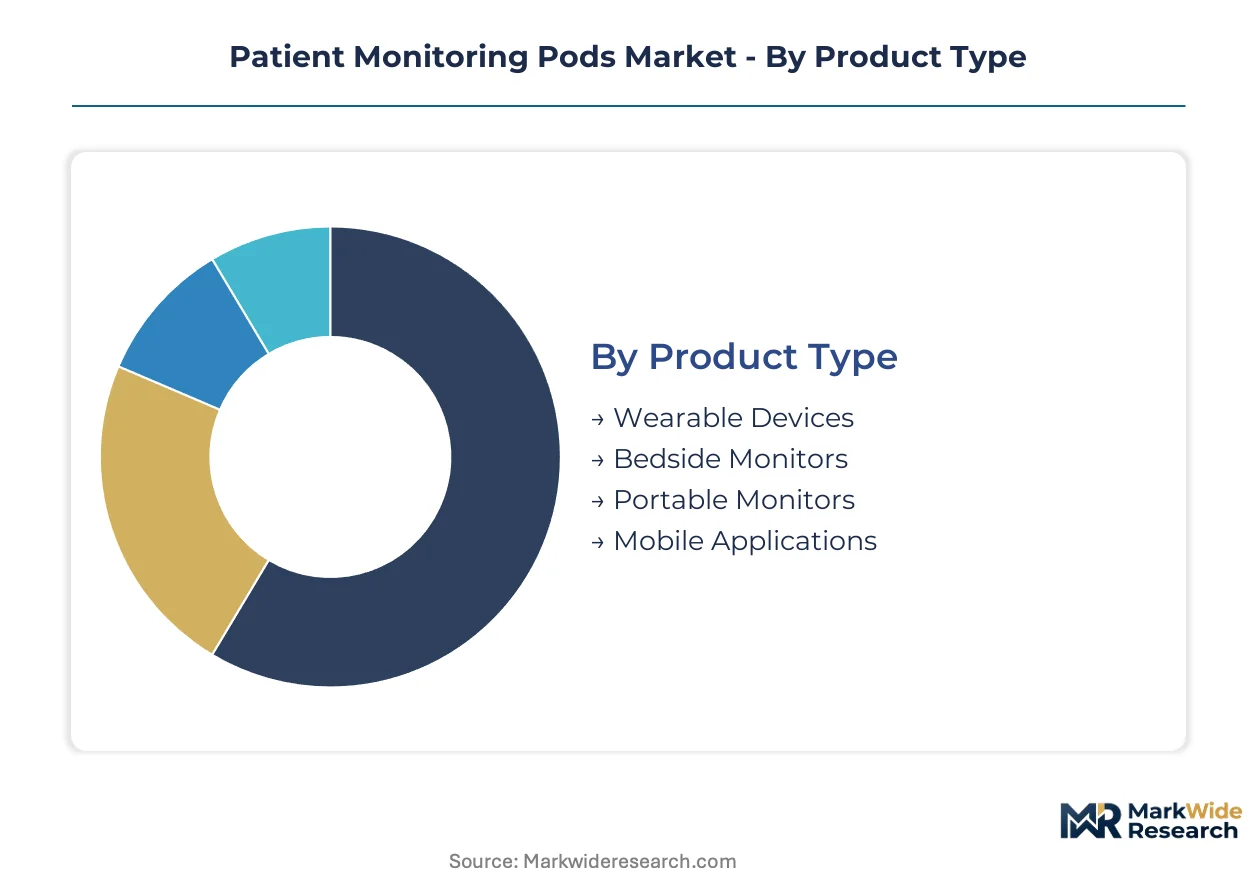
Patient monitoring pods fragment across four critical dimensions that determine regulatory pathway complexity, reimbursement velocity, and deployment architecture. Each segmentation axis carries distinct margin profiles and certification requirements that shape vendor portfolio prioritization.
Product Type:
FDA 510(k) clearance timelines vary dramatically across enclosure formats, with wearable devices facing distinct biocompatibility testing that bedside monitors bypass through predicate device pathways.
- Wearable Devices:These pods integrate flexible electrode arrays and skin-adhesive biosensors for ambulatory electrocardiography and pulse oximetry sampling. Demand concentrates in United States home care settings where CMS remote patient monitoring reimbursement codes drive physician practice adoption. FDA biocompatibility ISO 10993 testing extends development cycles for novel skin-contact materials.
- Bedside Monitors:Stationary enclosures with multi-parameter sensor suites and edge computing modules for step-down units and emergency department overflow. German hospital networks in Bavaria and North Rhine-Westphalia are expanding procurement for these configurations as ICU capacity constraints persist.
- Portable Monitors:Battery-powered units with wheeled enclosures for intrahospital transport and temporary deployment. Southeast Asian health systems favor these for resource-constrained environments requiring equipment mobility.
- Mobile Applications:Software interfaces aggregating pod telemetry for clinical review and patient-facing dashboards. EU MDR software-as-a-medical-device classification imposes cybersecurity validation requirements that lengthen quality management system implementation.
Bedside monitors handle the majority of throughput; wearable devices are the fastest mover on share.
Technology:
Connectivity selection determines power budget, transmission range, and regulatory electromagnetic compatibility testing scope.
- Bluetooth:Short-range protocols with sub-10mW power consumption dominate hospital ward deployments where WiFi infrastructure is saturated. Bluetooth Low Energy maturation enables continuous multi-parameter streams without bedside tethering.
- Wi-Fi:Higher bandwidth connectivity for pods requiring real-time video integration or large-file diagnostic transmission. United States health systems with consolidated network infrastructure favor this for centralized nursing station integration.
- Cellular:LTE-M and NB-IoT modules enable deployment beyond hospital perimeters for rural ambulatory and home-based chronic disease management. This segment climbs the fastest as reimbursement frameworks shift toward remote patient management.
- NFC:Near-field protocols for patient identity verification and pod configuration handoff at point of care. Limited to authentication workflows rather than continuous physiological streaming.
Bluetooth captures the dominant installation base; cellular connectivity is expanding most quickly into new care settings.
End User:
Procurement authority and reimbursement mechanisms diverge sharply across care setting types.
- Hospitals:Command concentrated purchasing volume through group purchasing organizations and enterprise monitoring platform consolidation. United States health system mergers in Texas and Florida have compressed vendor qualification lists by half.
- Home Care:Fastest-expanding installation category as CMS and private payers extend remote patient management reimbursement. Bluetooth-enabled pods with simplified patient interfaces dominate this channel.
- Rehabilitation Centers:Intermediate care settings requiring portable configurations for mobility therapy integration. Demand tracks post-acute care network expansion in Germany and the Netherlands.
- Long-term Care Facilities:Skilled nursing environments with limited clinical staffing where automated alert systems reduce response latency. Regulatory oversight varies by state-level long-term care quality standards in the United States.
Hospitals command the dominant procurement volume; home care is gaining share fastest on reimbursement tailwinds.
Application:
Clinical use case determines sensor parameter requirements, sampling frequency, and alert threshold configurations.
- Chronic Disease Management:Continuous glucose, blood pressure, and arrhythmia surveillance for heart failure and diabetes populations. United States accountable care organizations drive pod deployment to reduce emergency department utilization.
- Emergency Care:Rapid-deployment configurations for emergency department triage and disaster response. German hospital infrastructure expansion targets this application for step-down overflow capacity.
- Post-operative Monitoring:Cardiac and respiratory surveillance following discharge from surgical intervention. Reimbursement bundling in United States commercial payers accelerates adoption for high-risk procedures.
- Health Tracking:Consumer-facing wellness monitoring with lower clinical validation requirements. EU MDR classification uncertainty constrains manufacturer positioning in this ambiguous regulatory space.
Chronic disease management handles the majority of deployed pod hours; post-operative monitoring is expanding most quickly on surgical volume recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement code expansions for remote patient monitoring are redirecting procurement budgets toward wireless pod infrastructure across major health systems. FDA 510(k) pathway efficiencies are compressing product-to-market timelines for manufacturers targeting United States hospital networks. German hospital infrastructure investments are accelerating deployment in step-down units and emergency department overflow capacity.
United States
Health system consolidation in Texas and Florida has compressed vendor qualification lists by half across cardiac monitoring categories. CMS remote patient management reimbursement codes are driving physician practice adoption of Bluetooth-enabled pods for home care settings. Hospital networks in the Southeast are completing thousand-bed rollouts within eighteen-month procurement windows.
Germany
Remote patient monitoring networks across Bavaria and North Rhine-Westphalia are expanding pod procurement for ICU capacity constraints and step-down unit overflow. EU Medical Device Regulation imposes stricter clinical evidence standards for Class IIa and above pod classifications, extending certification investment horizons. Berlin-Brandenburg health clusters are establishing in-country regulatory affairs functions to navigate unannounced notified body audits.
Japan
PMDA electromagnetic compatibility testing requirements extend certification timelines for manufacturers lacking prior METI filings. Premium hospital procurement channels favor vendors with accelerated regulatory recognition through established compliance pathways. Kanto region medical device clusters concentrate edge computing module integration expertise for on-device arrhythmia detection algorithms.
China
NMPA wireless medical device approvals govern pod classifications with distinct cybersecurity validation requirements for cloud-connected telemetry systems. Provincial health commissions in Yangtze River Delta and Pearl River Delta regions are piloting centralized monitoring platforms across merged hospital networks. Domestic sensor manufacturing capabilities are reducing component lead times for multi-parameter biosensor miniaturization.
India
CDSCO medical device rules are harmonizing with IMDRF guidelines for wireless physiological monitoring equipment, though state-level implementation varies across Maharashtra and Karnataka health clusters. Price-sensitive procurement in public hospital systems favors portable monitor configurations with simplified patient interfaces. Bangalore medical technology corridors are developing edge AI inference capabilities for real-time clinical alerting without network dependency.
Patient Monitoring Pods Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with established bedside monitor installed bases and specialized wireless device manufacturers with regulatory acceleration expertise. Market structure concentrates contract volume with three to four full-stack suppliers capable of spanning acute, ambulatory, and home settings through enterprise monitoring platforms. Dominant archetypes include sensor-integrated systems builders, regulatory pathway specialists, and subscription-based equipment provisioners. Competitive moves center on strategic partnerships for HL7 FHIR interoperability certification and backward integration into edge computing module fabrication to reduce Taiwan foundry exposure.
Within the diversified systems tier, Koninklijke Philips N.V. and GE Healthcare exemplify archetypes leveraging installed base scale and in-house manufacturing control respectively. Among Asia-Pacific specialists, Mindray Medical International occupies a position representing portable configuration expertise for emerging health systems. These three anchors sit within a vendor landscape where group purchasing organizations are displacing individual hospital negotiations and enterprise platform consolidation is reshaping qualification criteria toward interoperability certification depth.
| Leading Market Players |
|---|
| Drägerwerk AG & Co. KGaA |
| Koninklijke Philips N.V. |
| GE Healthcare |
| Mindray Medical International |
| Hill-Rom Holdings |
| Medtronic |
| Abbott Laboratories |
| Nihon Kohden |
| Omron Healthcare |
| Others |
Value Network & Pricing Analysis
Flexible electrode arrays displacing rigid printed circuit boards in wearable pod configurations are redrawing manufacturing geography toward South Korean and Taiwanese substrate specialists while compressing per-unit material costs by eliminating gold-plated connector assemblies. This substitution simultaneously shifts procurement leverage from legacy EMS providers to semiconductor packaging houses and erodes the traditional 40-60% disposable biosensor cost premium that constrained price-competitive positioning in emerging health systems.
Pricing Analysis
Cost-plus contracts with semiconductor foundries indexed to TSMC wafer pricing govern edge computing module procurement for pod manufacturers. Three-tier pricing structure across FDA-cleared premium, CE-marked standard, and economy configurations without dual-certification separates hospital procurement tiers. Pricing pressure stems from CMS reimbursement compression for remote patient monitoring codes in United States home care settings. Price sensitivity concentrates among public hospital systems in India and Southeast Asia, while German and Japanese university hospitals prioritize interoperability certification over unit cost.
Supply Chain Analysis
Strategic stockpiling of Bluetooth Low Energy chipsets and MEMS accelerometers has displaced just-in-time inventory practices following Taiwan foundry capacity constraints in 2021-2022. Taiwan, South Korea, and China anchor edge computing module fabrication, while Germany and the Netherlands concentrate regulatory compliance component testing. Single-source vulnerability in advanced node semiconductor capacity exposes delivery timelines to geopolitical friction. Distribution runs through group purchasing organizations in United States health systems and direct hospital procurement in European step-down unit expansions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The patient monitoring pods market sits at a platform-economics inflection where HL7 FHIR interoperability certification is displacing standalone device procurement as the primary vendor selection criterion across consolidated United States health networks.
For Market Incumbents: Shield installed base erosion by accelerating backward integration into edge computing module design to reduce Taiwan foundry exposure. Deepen regulatory affairs capabilities in Berlin-Brandenburg and Tokyo-Kanto clusters to compress EU MDR and Japan PMDA clearance timelines before emerging entrants achieve predicate device pathways. Prioritize enterprise monitoring platform subscriptions that span acute-to-home settings over transactional bedside monitor sales.
For New Entrants and Emerging Players: Differentiate on cellular-enabled rural ambulatory configurations where LTE-M and NB-IoT modules bypass saturated hospital WiFi infrastructure and incumbent platform lock-in. Target India CDSCO harmonization windows and Southeast Asian portable monitor demand as the most penetrable white-space geographies. Pursue software-as-a-medical-device positioning in EU MDR Class IIa pathways to circumvent capital-intensive hardware certification cycles.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors regulatory pathway specialists with accelerated FDA 510(k) and EU MDR notified body relationships. Long-term viability hinges on acquisition targets possessing in-country quality management system infrastructure in Germany or the Netherlands and demonstrated HL7 FHIR integration with Epic or Cerner deployments. Watch for inflection when CMS expands remote patient management reimbursement codes beyond chronic disease management into post-acute surgical monitoring.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Compresses product-to-market velocity for wireless pod manufacturers targeting United States hospital procurement consolidation. |
| EU MDR Notified Body Expansion | Establishes in-country regulatory affairs functions in Germany and the Netherlands to navigate unannounced audit requirements. |
| Hospital System Partnership | Secures thousand-bed enterprise monitoring platform rollouts through group purchasing organization contract concentration. |
| Software Companion Development | Extends pod telemetry aggregation into patient-facing mobile interfaces for CMS remote patient management reimbursement capture. |
| Reimbursement Strategy | Aligns cellular connectivity pod deployment with shifting CMS and private payer frameworks toward home-based chronic disease management. |
Research Methodology
Operator-level perspectives from hospital biomedical engineers, group purchasing organization contracts managers, regulatory affairs leads at notified bodies, and CMS reimbursement policy specialists anchored the qualitative base for this analysis. Primary interview findings triangulated against FDA 510(k) clearance databases, EU MDR notified body audit schedules, hospital procurement records from Texas and Florida health networks, and CMS Medicare claims data for remote patient monitoring codes. Bottom-up pod shipment estimates by product type and technology segment reconciled with top-down health system capital expenditure surveys across the analysis window.
Sensitivity analysis tested forecast outputs against semiconductor foundry capacity scenarios, EU MDR implementation timeline variations, and CMS reimbursement code expansion assumptions. Segmentation modeling spanned product type, connectivity technology, end-user setting, and clinical application dimensions. CAGRs derived from regression analysis of historical procurement velocity correlated with health system consolidation metrics and regulatory pathway efficiency indices. Edge AI inference adoption curves and disposable biosensor cost compression trajectories informed technology transition assumptions.
Material uncertainties — Taiwan semiconductor foundry geopolitical disruption, EU MDR Class IIa clinical evidence requirement expansion, and CMS reimbursement code contraction — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued FDA 510(k) pathway efficiency and Bluetooth Low Energy protocol maturation. Revision becomes warranted when health system consolidation velocity in the United States falls below historical thresholds or when semiconductor supply concentration shifts materially alter component lead time assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Global Patient Positioning System Market
Patient Monitoring
Body Fat Measurement Market
Patient Monitoring
Wearable Health Sensors Market
Patient Monitoring
Middle East and Africa Remote Patient Monitoring Market
Patient Monitoring
UAE Patient Monitoring Equipment Market
Patient Monitoring
Contact-Free Sleep Monitoring Systems Market
Patient Monitoring
Middle East and Africa Patient Monitoring Market
Patient Monitoring
Monitoring Wristband Market
Patient Monitoring
Multiparameter Patient Monitoring System Market
Patient Monitoring
Wireless Fetal Monitoring Systems Market
Patient Monitoring
North America Body Temperature Monitoring Market
Patient Monitoring
Global Smart Pulse Oximeters Market
Patient Monitoring
Lung Monitoring Devices Market
Patient Monitoring
Remote Patient Monitoring System Market
Patient Monitoring
Global Patient Monitoring Market
Patient Monitoring
North America Patient Monitoring Market