
 Opioids Market | 2026-2036
Opioids Market Size, Share, and Industry Trends Forecast 2026-2036
Opioids Market Intelligence
The integration of abuse-deterrent formulation technologies into opioid manufacturing is tilting the product landscape towards safer, controlled-release medications. This shift favors companies with strong R&D capabilities in drug delivery systems. Purdue Pharma L.P. sustains its position through its historical expertise in extended-release formulations. Teva Pharmaceuticals Inc. competes with a diverse portfolio of both generic and branded pain treatments, while Pfizer Inc. leverages its global manufacturing scale.
Opioids are psychoactive compounds that bind to opioid receptors, primarily for analgesia. These substances, either naturally derived from opium or synthetically produced, work by reducing the perception of pain signals sent to the brain. Chronic pain management represents a mature and large-volume therapy area, while the cancer pain category shows consistent necessity-driven demand. Product usage varies, with Fentanyl and its analogues often used for severe acute pain, whereas Oxycodone is common in postoperative settings.
Regulatory oversight from the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) heavily influences market access. These agencies mandate stringent clinical trials and post-market surveillance, including Risk Evaluation and Mitigation Strategies (REMS), to manage risks of addiction and misuse. Navigating the complex requirements for proving both efficacy and safety remains the central challenge for drug developers seeking market approval.
Market Dynamics
The central force shaping the opioids market is the intense regulatory pressure to mitigate addiction risk. This pressure, stemming from a public health crisis, is compelling manufacturers to invest heavily in abuse-deterrent formulations and controlled-release drug delivery systems.
Growth Catalysts
- Chronic Disease Prevalence:A rising incidence of cancer and other chronic pain conditions, particularly within aging populations in developed nations like Japan and Germany, sustains a baseline demand for effective analgesics.
- Formulation Technology:Advances in abuse-deterrent technologies, which create physical or chemical barriers to prevent manipulation for misuse, offer a pathway for new product approvals that meet stricter safety mandates.
- Palliative Care Expansion:Global initiatives led by organizations like the WHO to improve access to palliative care and pain relief in low- and middle-income countries create new, regulated channels for opioid distribution.
Market Restraints
- Stringent Regulatory Hurdles:The U.S. Food and Drug Administration (FDA) and European Medicines Agency (EMA) impose exceptionally high barriers to entry, requiring extensive clinical data on both efficacy and abuse potential, which delays and increases the cost of market access.
- Non-Opioid Competition:A strong clinical and societal push towards non-opioid pain management, including NSAIDs, nerve blocks, and physical therapy, directly threatens opioid prescription volumes for many common pain conditions.
- Litigation and Stigma:Pervasive litigation risk and severe public stigma, especially in the United States, create significant commercial and reputational challenges for manufacturers, influencing prescribing patterns and investment decisions.
Strategic Opportunities
- Targeted Pain Therapies:Development of opioids with novel mechanisms of action, such as biased agonism, presents an opportunity to create analgesics with reduced side effects like respiratory depression or addictive potential.
- Opioid Use Disorder (OUD) Treatments:The growing need for medication-assisted treatment (MAT) for OUD creates a significant market for drugs like buprenorphine and methadone, representing a parallel growth area.
- Digital Health Integration:Combining opioid prescriptions with digital monitoring tools, such as smart pill dispensers and patient-facing apps, offers a way to improve adherence, track outcomes, and satisfy regulatory post-market surveillance requirements.
Industry Challenges
- Complex Compliance Frameworks:Navigating the intricate and varied Risk Evaluation and Mitigation Strategies (REMS) in the U.S. and similar risk management plans in other jurisdictions requires substantial administrative and financial resources.
- Counterfeit Drug Proliferation:The infiltration of illicitly manufactured fentanyl and its analogues into the supply chain in various countries poses a severe public health threat and complicates enforcement efforts for legitimate products.
- Negative Public Perception:Overcoming the deep-seated negative public and physician perception of opioids, even for appropriate medical use, remains a core challenge to ensuring patient access for severe pain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Opioids Market |
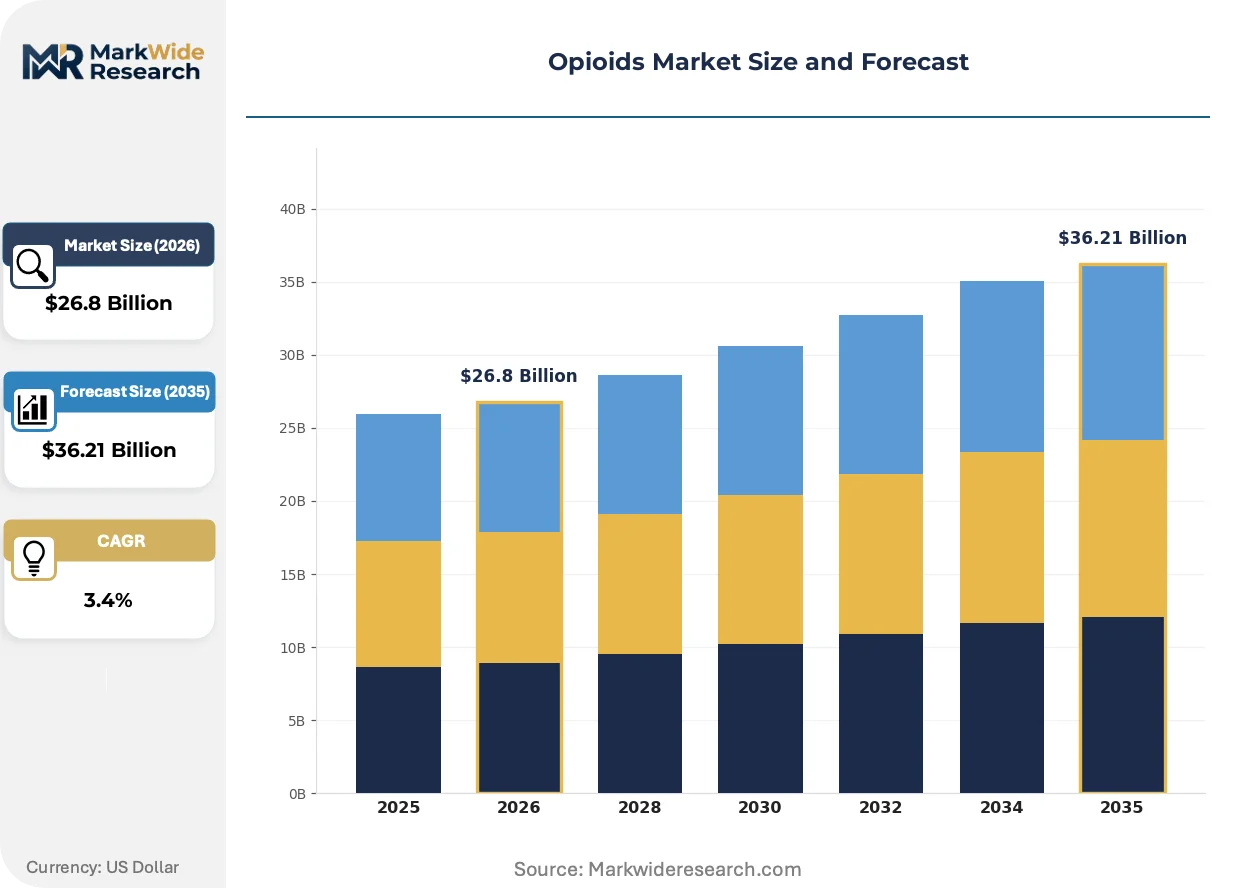
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $36.21 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Morphine, Oxycodone, Fentanyl, Codeine Therapy Area: Chronic Pain, Cancer Pain, Postoperative Pain, Neuropathic Pain Delivery Mode: Oral, Injectable, Transdermal, Intranasal End User: Hospitals, Clinics, Home Care, Pain Management Centers |
| Companies Covered | Mallinckrodt Pharmaceuticals, Teva Pharmaceuticals Inc., Purdue Pharma L.P., Hikma Pharmaceuticals PLC, Pfizer Inc., Johnson & Johnson Services, Inc., AbbVie Inc., Sun Pharmaceutical Industries Ltd, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Opioids Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot towards safety and control. This fundamental reorientation is reshaping product development pipelines, regulatory strategies, and prescribing behaviors in response to the global opioid crisis, prioritizing risk mitigation alongside analgesic efficacy.
Abuse-deterrent formulation (ADF) technology incorporates physical and chemical barriers into opioid medications to prevent misuse. Pain management specialists and hospitals are steadily adopting these newer products for high-risk patients. This shift toward intrinsically safer designs is rendering obsolete traditional, easily manipulated immediate-release tablets that were a primary source of diverted prescription drugs.
Regulatory frameworks are becoming increasingly restrictive globally. The European Medicines Agency (EMA) has issued guidance recommending stricter controls and shorter durations for opioid prescriptions in chronic non-cancer pain, mirroring actions by the FDA. This policy is forcing a re-evaluation of long-term pain management protocols across European Union member states. The segment most affected is chronic back and musculoskeletal pain management, where prescribers are now incentivized to exhaust non-opioid options first.
Prescribing patterns are undergoing a significant transformation from broad, primary-care-led initiation to a specialist-driven, multimodal approach. This change means general practitioners are increasingly referring complex pain patients to specialized clinics rather than managing long-term opioid therapy themselves. This behavioral shift is most visible in the United States and Canada, where updated clinical guidelines and intense public health scrutiny have directly impacted physician decision-making for chronic pain.
Opioids Market Segmentation
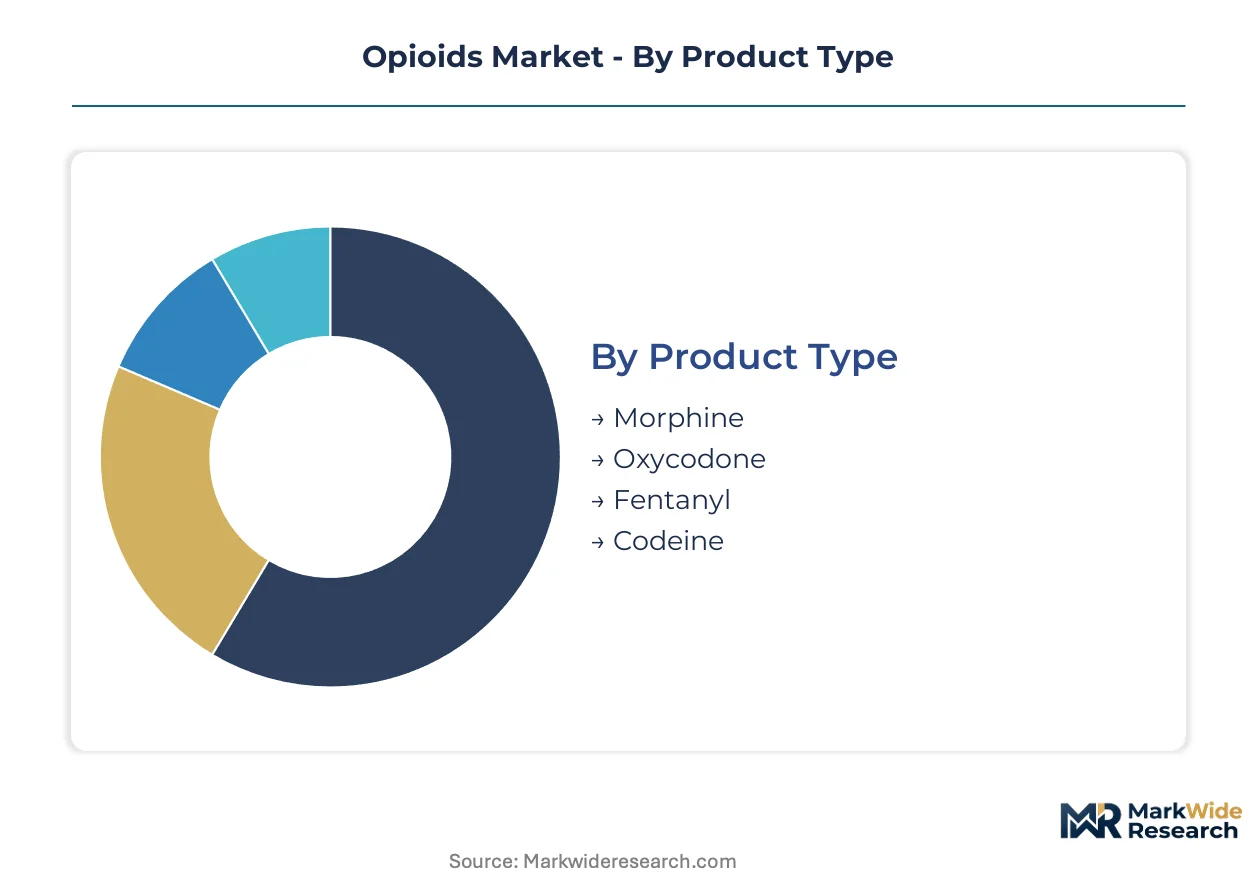
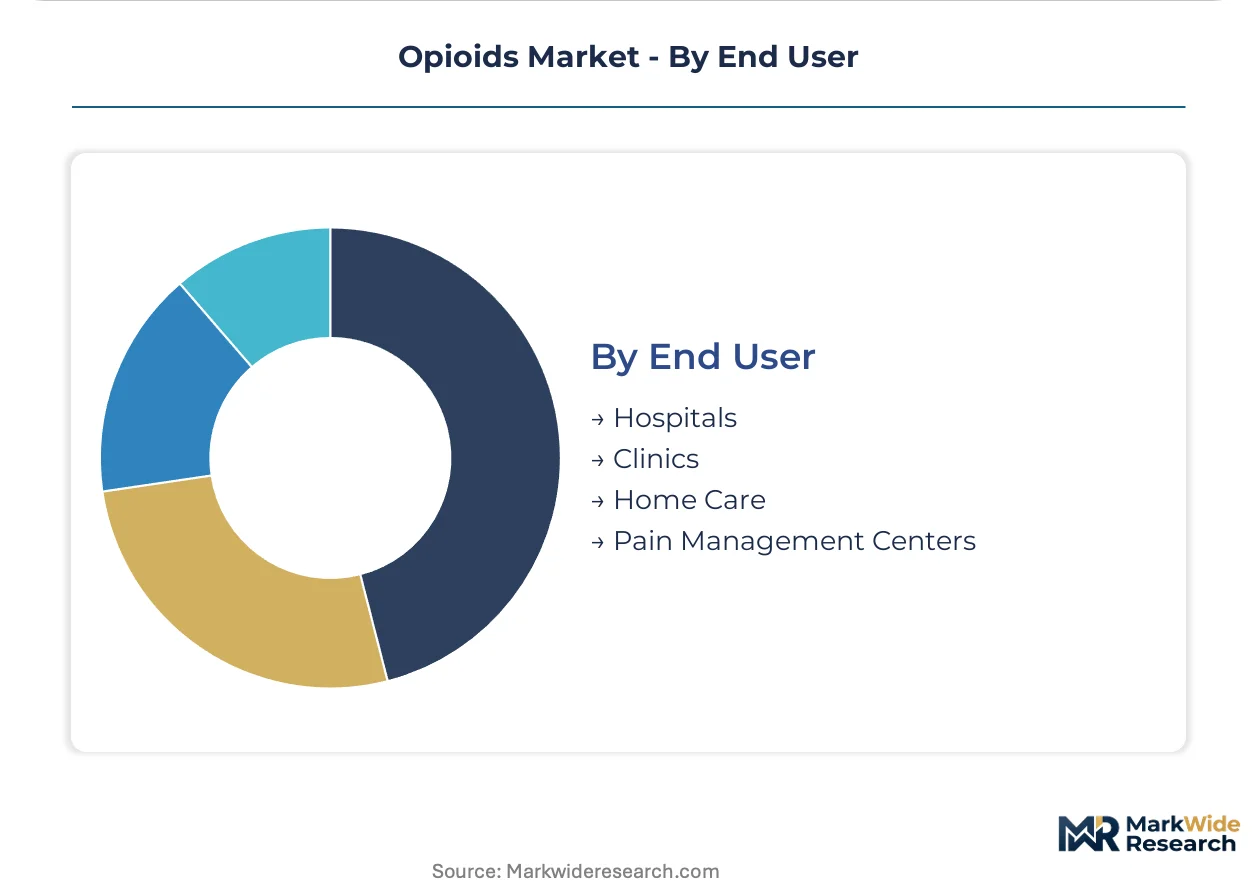
Understanding the Opioids Market through segmentation reveals how diverse product types, therapy areas, delivery modes, and end-user requirements shape demand and innovation. This granular view helps stakeholders navigate the complex regulatory environment and address specific patient needs across the pain management landscape.
Product Type:
The opioids market product types span a wide use-case spectrum, from severe acute pain management to long-term chronic conditions.
- Fentanyl:This potent synthetic opioid is often administered for severe acute pain, particularly in hospital settings or for breakthrough cancer pain. Demand concentration is influenced by its rapid onset and high efficacy, despite its association with illicitly manufactured analogues.
- Oxycodone:A semi-synthetic opioid, Oxycodone is widely used for moderate to severe pain, frequently in postoperative recovery or for chronic conditions. Its demand concentrates in prescribed settings, with a focus on extended-release and abuse-deterrent formulations to enhance safety.
- Morphine:As a naturally derived opiate, Morphine serves as a benchmark analgesic for a broad range of moderate to severe pain conditions.
- Codeine:This weaker opioid is typically prescribed for mild to moderate pain relief and as an antitussive agent in cough suppressants.
The dominant share belongs to Oxycodone, while Fentanyl is closing the gap fastest.
Therapy Area:
Therapy areas delineate the specific medical applications and patient populations requiring opioid intervention.
- Cancer Pain:This segment addresses the intense and often debilitating pain experienced by oncology patients, including pain from tumors, treatments, or palliative care needs. Demand for cancer pain management opioids shows consistent necessity-driven growth, especially with expanding global palliative care initiatives.
- Chronic Pain:Encompassing persistent pain lasting longer than three to six months, this segment includes conditions like chronic back pain and osteoarthritis. Demand in chronic pain management remains substantial, particularly within aging populations in developed nations.
- Postoperative Pain:Acute pain experienced by patients immediately following surgical procedures requires short-term opioid management for comfort and recovery.
- Neuropathic Pain:This complex pain type, resulting from nerve damage or dysfunction, often requires specific opioid formulations or adjunctive therapies for effective relief.
The demand profile shows Chronic Pain as a foundational segment, with Cancer Pain demonstrating significant expansion.
Delivery Mode:
Delivery modes reflect diverse patient needs and clinical settings, influencing absorption rates and onset of action.
- Oral:This mode involves tablets, capsules, or liquid formulations, representing the most common and convenient method for opioid administration. Demand for oral opioids is widespread, with a strong focus on controlled-release and abuse-deterrent formulations to enhance safety.
- Injectable:Administered intravenously or intramuscularly, injectable opioids provide rapid pain relief, primarily used in hospital settings for severe acute pain or emergency situations. Demand concentrates in acute care environments where immediate action is critical.
- Transdermal:Opioid patches deliver medication through the skin for sustained release, offering continuous pain management for chronic conditions.
- Intranasal:This delivery method allows for rapid absorption through the nasal mucosa, often used for breakthrough pain or in emergency medical situations.
While Oral remains the most accessible, Injectable offers specialized advantages for specific clinical scenarios.
End User:
End-user segments categorize the primary healthcare facilities and care settings where opioid medications are dispensed and administered.
- Hospitals:These institutions are primary end-users for opioids, particularly for postoperative pain management, emergency care, and severe acute conditions. Demand in hospitals remains high due to the need for immediate and controlled analgesia in critical situations.
- Pain Management Centers:Specialized clinics focusing on chronic and complex pain conditions provide comprehensive opioid therapy under expert supervision. Demand in these centers is increasing as complex pain patients are referred for multimodal, specialist-driven care.
- Clinics:General practitioner and specialist outpatient clinics represent a significant end-user segment for initial opioid prescriptions and ongoing management of less severe pain.
- Home Care:This segment involves patient self-administration of prescribed opioids in their home environment, often for chronic pain or palliative care support.
The shift towards specialized care favors Pain Management Centers, while Hospitals maintain a broad foundational role.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opioid distribution from established pharmaceutical manufacturing hubs in Europe and North America supplies a significant portion of global demand. This supply chain supports diverse regional needs, from acute pain management in hospitals to long-term palliative care initiatives across various countries.
United States
High chronic pain prevalence and advanced healthcare infrastructure drive substantial demand for opioids in the United States. The U.S. Food and Drug Administration (FDA) mandates stringent Risk Evaluation and Mitigation Strategies (REMS) to control addiction risks. Major pharmaceutical research and development clusters, particularly in the Northeast corridor, focus on abuse-deterrent formulation technologies.
Germany
An aging population and a high incidence of chronic diseases sustain a consistent demand for effective analgesics in Germany. The European Medicines Agency (EMA) influences national prescribing guidelines, emphasizing controlled access and appropriate use. Specialized pain clinics throughout cities like Berlin and Munich integrate multimodal pain management approaches, including opioid therapy.
Japan
Japan's rapidly aging demographic profile contributes to a rising demand for pain management, especially in cancer and chronic non-cancer pain. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees strict regulations for opioid approval and distribution. Pharmaceutical companies in the Tokyo and Osaka regions are investing in novel drug delivery systems for pain relief.
Canada
Public health initiatives to address the opioid crisis significantly shape the market dynamics in Canada, influencing prescribing patterns. Health Canada implements strict controls on opioid medications, promoting safer prescribing practices and alternative therapies. Academic medical centers in cities such as Toronto and Montreal lead research into pain management guidelines and addiction prevention.
United Kingdom
The National Health Service (NHS) system manages opioid access for a broad patient population, particularly for chronic and palliative care needs. The Medicines and Healthcare products Regulatory Agency (MHRA) enforces guidelines for opioid prescribing, aiming to balance pain relief with addiction mitigation. Major medical research institutions in London and Oxford contribute to studies on pain mechanisms and treatment efficacy.
Opioids Market Key Industry Players
Channel-controlling players compete with product-specialist players across the opioids market. The market structure exhibits consolidation among a few large pharmaceutical companies, while numerous smaller entities focus on niche product development. Diversified pharmaceutical giants leverage their broad portfolios, while specialized pain management companies focus on advanced formulations. Strategic partnerships for R&D and portfolio diversification represent dominant competitive moves.
Within the diversified pharmaceutical segment, Teva Pharmaceuticals Inc. and Pfizer Inc. exemplify global reach and broad product offerings, including both branded and generic pain treatments. Purdue Pharma L.P., historically recognized for its extended-release formulations, occupies a position anchored by its expertise in specific drug delivery systems. These companies navigate complex regulatory environments to maintain market presence.
| Leading Market Players |
|---|
| Mallinckrodt Pharmaceuticals |
| Teva Pharmaceuticals Inc. |
| Purdue Pharma L.P. |
| Hikma Pharmaceuticals PLC |
| Pfizer Inc. |
| Johnson & Johnson Services, Inc. |
| AbbVie Inc. |
| Sun Pharmaceutical Industries Ltd |
| Sanofi |
| Others |
Cost & Logistics Intelligence
The transatlantic pharmaceutical freight corridor's cost dynamics directly influence the pricing of specialized opioid formulations, reflecting supply concentration from key manufacturing hubs. This corridor's efficiency impacts downstream price differentiation for advanced analgesics.
Pricing Analysis
A significant pricing gap exists between current-generation abuse-deterrent opioid formulations and prior-generation standard opioids. Pricing primarily follows a value-based model for novel, specialized products, while older generics operate on a per-unit transactional basis. Price differentiation stems from FDA or EMA certification levels for abuse-deterrent features and brand premium, with pricing softness reflecting intense non-opioid competition. Hospitals demonstrate lower price sensitivity for critical, advanced pain management solutions, whereas individual patients remain highly sensitive to out-of-pocket costs.
Supply Chain Analysis
The upstream feedstock for opioids, whether naturally derived opium poppy or synthetic chemical precursors, originates primarily from India, China, and specialized European manufacturers. The supply chain draws from these concentrated sources for key active pharmaceutical ingredients and specialized drug delivery components. Regulatory restrictions on controlled substances represent a significant structural risk, alongside the constant threat of illicit manufacturing infiltration. Distribution runs through a highly controlled network of licensed wholesalers to hospitals, pain management centers, and pharmacies, ensuring stringent oversight.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The opioids market is positioned for a cyclical recovery, driven by the increasing integration of abuse-deterrent formulations into clinical practice. This shift reflects a market rebalancing from prior over-prescription towards safer, regulated usage.
For Market Incumbents: Insulate core market share by accelerating investment in next-generation abuse-deterrent formulations and novel mechanisms of action like biased agonism. Strategic partnerships for advanced drug delivery systems can mitigate the threat of non-opioid competition and generic erosion. Leveraging deep regulatory expertise to navigate complex FDA and EMA requirements is crucial for sustained market presence.
For New Entrants and Emerging Players: Pursue niche opportunities in orphan indications for severe, intractable pain or the expanding opioid use disorder (OUD) treatment market. The palliative care segment in low- and middle-income countries represents a penetrable area for regulated access. A targeted go-to-market strategy could involve combining novel analgesics with integrated digital health monitoring tools to enhance patient safety and adherence.
For Investors and Strategic Acquirers: Specialized drug delivery technology firms and digital health platforms represent attractive acquisition targets over the long term. Demand for severe pain management and opioid use disorder treatments ensures market viability for the next decade. A critical signal to watch is the acceleration of regulatory approvals for novel non-addictive analgesics, indicating a major market shift.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement for ADFs | Accelerates market access for safer opioid formulations, meeting stringent FDA and EMA safety mandates. |
| Regulatory Approval Pathway Optimization | Streamlines the complex process for new opioid products, reducing time-to-market for pharmaceutical companies. |
| Manufacturing Scale-Up for Synthetics | Ensures consistent supply of critical opioid APIs, addressing global demand for essential pain medications. |
| Pipeline Diversification into OUD Treatments | Expands revenue streams by addressing the parallel public health need for opioid use disorder therapies. |
| Strategic Partnerships for Digital Health | Integrates patient monitoring tools, improving adherence and post-market surveillance for prescribers. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary research. Primary insights were gathered from drug development executives, regulatory affairs leads, hospital procurement managers, and pain management specialists. Secondary validation utilized FDA filings, EMA submissions, ClinicalTrials.gov, and specialized pharmaceutical industry reports. This approach enabled comprehensive bottom-up and top-down triangulation of market data.
Forecast inputs considered historical market performance, current regulatory landscapes, and future technological developments across the analysis window. The analytical framework modeled segmentation dimensions including product type, therapy area, delivery mode, and end-user. Compound annual growth rates were derived from historical trends and future projections. Key industry-specific inputs included the evolving prevalence of chronic pain conditions and adoption rates of abuse-deterrent opioid formulations.
Sensitivities concentrate around unforeseen regulatory shifts, the emergence of novel non-opioid treatments, and significant public health policy changes. Forecasts reflect assumptions based on current market dynamics and known pipeline developments. Cross-checking against external pharmaceutical market benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Bulbospinal Muscular Atrophy Drugs Market
Pharmaceuticals
Germany Pharmaceutical 3PL Market
Pharmaceuticals
Bispecific Antibody Therapeutics Contract Manufacturing Market
Pharmaceuticals
Global Interstitial Cystitis Drugs Market
Pharmaceuticals
Testosterone Nasal Gels Market
Pharmaceuticals
Albinism Drugs Market
Pharmaceuticals
Subcutaneous Immunoglobulin Market
Pharmaceuticals
Global Vaccine Market
Pharmaceuticals
Pharmaceuticals Lipids Market
Pharmaceuticals
Human Combination Vaccines Market
Pharmaceuticals
Digital Pharmaceutical Supply Chain Management Market
Pharmaceuticals
Tetanus Market
Pharmaceuticals
Netherlands Pharmaceutical Market
Pharmaceuticals
Hydroxyzine Market
Pharmaceuticals
Compounding Chemotherapy Market
Pharmaceuticals
Synthetic Drugs Market