
 Pancrelipase Market | 2026-2036
Pancrelipase Market Size, Share, and Industry Trends Forecast 2026-2036
Pancrelipase Market Intelligence
The specialty pharmacy distribution channel is reconfiguring access and reimbursement protocols for high-cost pancreatic enzyme replacement therapies. AbbVie Inc. leverages its strong position in gastroenterology to maintain formulary access for its brands. Viatris Inc. competes with a focus on generic versions and broad market penetration. Nestlé S.A. anchors its strategy in the nutritional science segment, complementing therapeutic interventions for patients with pancreatic insufficiency.
Pancrelipase is a therapeutic agent containing a mixture of digestive enzymes, including lipase, protease, and amylase, derived from porcine pancreas glands. These formulations are designed to help digest fats, proteins, and carbohydrates in patients with exocrine pancreatic insufficiency. Enteric-coated capsules represent the dominant product type, engineered to ensure enzyme delivery past the stomach to the small intestine. Within applications, treatment for cystic fibrosis and chronic pancreatitis-related insufficiency constitutes the core demand driver.
Product approval and marketing are governed by stringent regulatory oversight from bodies like the U.S. FDA and the European Medicines Agency (EMA). These agencies mandate rigorous clinical trials to prove efficacy and safety, particularly for new formulations and biosimilar pathways. The NMPA in China also enforces strict standards for imported drug registrations. Future competitive advantage will hinge on navigating the complex bioequivalence requirements for generic entry and demonstrating superior patient outcomes.
Market Dynamics
The central structural force shaping the pancrelipase market is the rigorous regulatory framework for bioequivalence. This standard, enforced by agencies like the FDA and EMA, dictates the pathways for both new product innovation and generic market entry, concentrating power with established manufacturers.
Growth Catalysts
- Increasing Disease Prevalence:Higher diagnosis rates for exocrine pancreatic insufficiency, particularly linked to cystic fibrosis and chronic pancreatitis in developed nations like the United States and Germany, directly expand the core patient population requiring therapy.
- Formulation Advancements:Innovations in enteric-coating technologies that improve enzyme stability and targeted delivery to the small intestine enhance therapeutic efficacy and patient compliance, encouraging adoption of newer, more effective products.
- Regulatory Clarity:Specific guidance from the U.S. FDA on bioequivalence for pancrelipase products, while stringent, provides a defined development and approval pathway for manufacturers capable of meeting the high technical standards.
Market Restraints
- Raw Material Dependency:The market's complete reliance on porcine pancreas glands as the source for enzymes creates significant supply chain vulnerability, subject to animal health epidemics and regional sourcing disruptions.
- High Development Costs:Stringent clinical trial requirements mandated by the FDA and EMA for proving safety and efficacy result in long, expensive development cycles, acting as a substantial barrier for new entrants.
- Bioequivalence Complexity:Demonstrating bioequivalence for generic pancrelipase formulations is technically difficult and costly, which limits the pace of generic competition and keeps prices for branded products high.
Strategic Opportunities
- Non-Porcine Enzyme Development:Investing in research for recombinant or plant-based enzyme sources presents a major opportunity to overcome raw material constraints and address the needs of patients with dietary or religious restrictions.
- Emerging Market Penetration:Expanding diagnostic education and market access in underpenetrated regions, such as Latin America and Southeast Asia, offers significant growth potential as healthcare infrastructure improves.
- Digital Health Integration:The use of telehealth platforms and mobile applications to support patient adherence, dose adjustment, and monitoring for chronic conditions like cystic fibrosis represents a new frontier for improving outcomes.
Industry Challenges
- Manufacturing Consistency:Ensuring consistent enzymatic activity and potency from batch to batch remains a significant operational challenge due to the inherent variability of the biological raw material sourced from porcine glands.
- Reimbursement Negotiations:Securing favorable formulary placement and navigating complex reimbursement protocols with pharmacy benefit managers (PBMs) for high-cost therapies is a persistent hurdle for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pancrelipase Market |
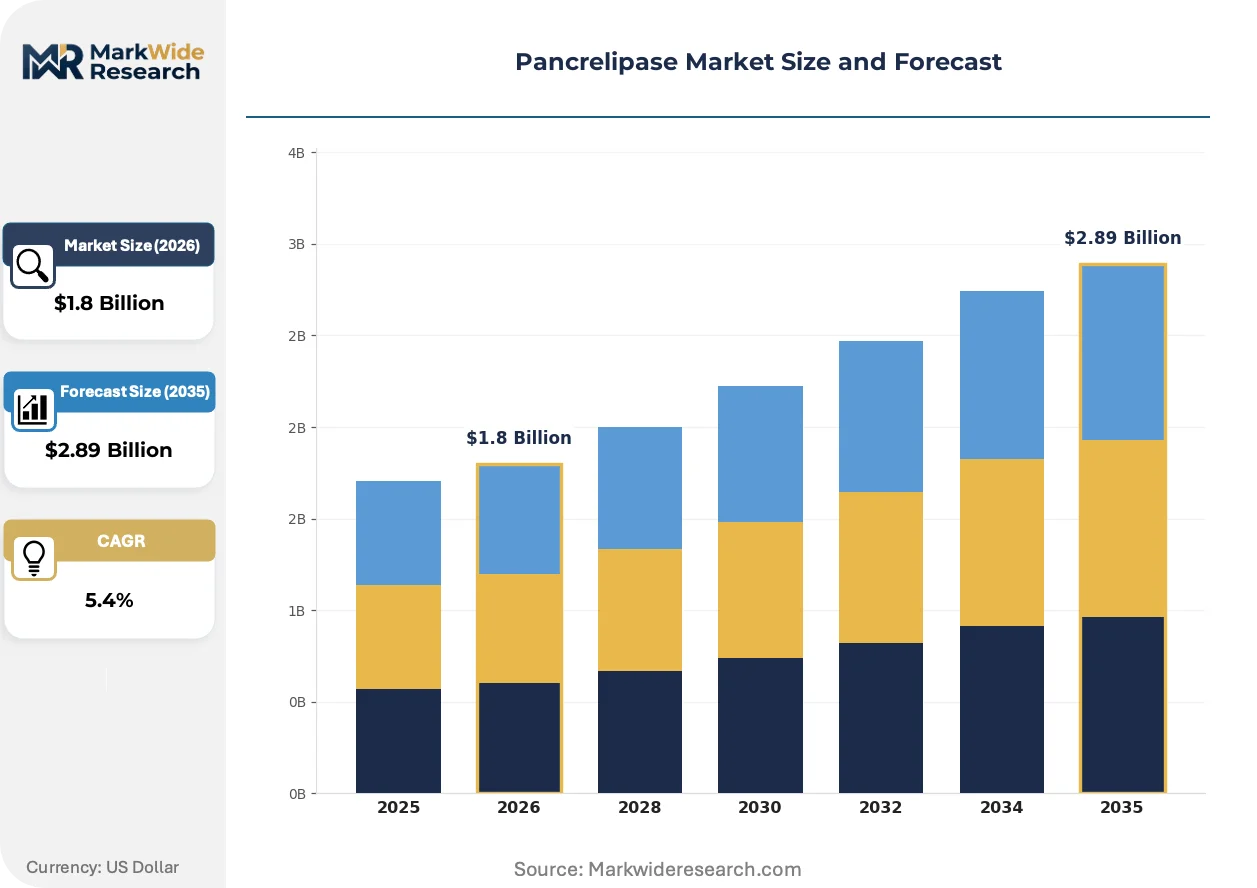
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.89 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micronized, Enteric-Coated Capsules, Powder Formulation, Delayed-Release Tablets Application: Digestive Disorders, Cystic Fibrosis, Pancreatic Insufficiency, Malabsorption Syndromes End User: Hospitals, Clinics, Long-Term Care Facilities, Home Care Settings Delivery Mode: Oral Administration, Liquid Form, Enteral Nutrition, Sublingual Tablets |
| Companies Covered | AbbVie Inc., Digestive Care, Inc., Viatris Inc., Nestlé S.A., Vivus Llc., Abbott Laboratories, Organon Canada Inc., Scientific Protein Laboratories, Allergan Pharmaceuticals International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pancrelipase Market Strategic Shifts & Innovations
The market is shifting toward more precise, patient-centric therapeutic strategies. This evolution is driven by advances in formulation science and a regulatory emphasis on proven clinical outcomes, moving the treatment paradigm beyond standardized dosing to more individualized care.
Advanced Drug Delivery
Microencapsulation and other advanced enteric-coating technologies are at the forefront of product innovation. These systems are designed to protect the fragile enzymes from stomach acid and ensure a predictable release profile in the duodenum. Gastroenterology and cystic fibrosis treatment centers are steadily adopting these improved formulations to enhance patient response and minimize gastrointestinal side effects. This level of precision in timing and location of enzyme release is virtualizing the natural digestive process for patients with pancreatic insufficiency.
Regulatory Stringency
Guidance from the U.S. FDA regarding bioequivalence for pancrelipase products has solidified a high barrier to entry for generic competitors. The regulations demand extensive in-vitro testing to characterize dissolution profiles and in-vivo clinical studies to confirm therapeutic equivalence. This framework disproportionately affects manufacturers of enteric-coated capsule products, who must meticulously replicate the performance of the reference listed drug to gain approval.
Channel Consolidation
A distinct behavioral shift is underway as pancrelipase distribution moves from broad retail pharmacy networks to specialized pharmacy channels. This consolidation is driven by payers aiming to manage the high expense and clinical complexity associated with pancreatic enzyme replacement therapy. The trend is most advanced in the United States, where specialty pharmacies integrate dispensing with crucial patient support services, including adherence monitoring and benefits coordination.
Pancrelipase Market Segmentation
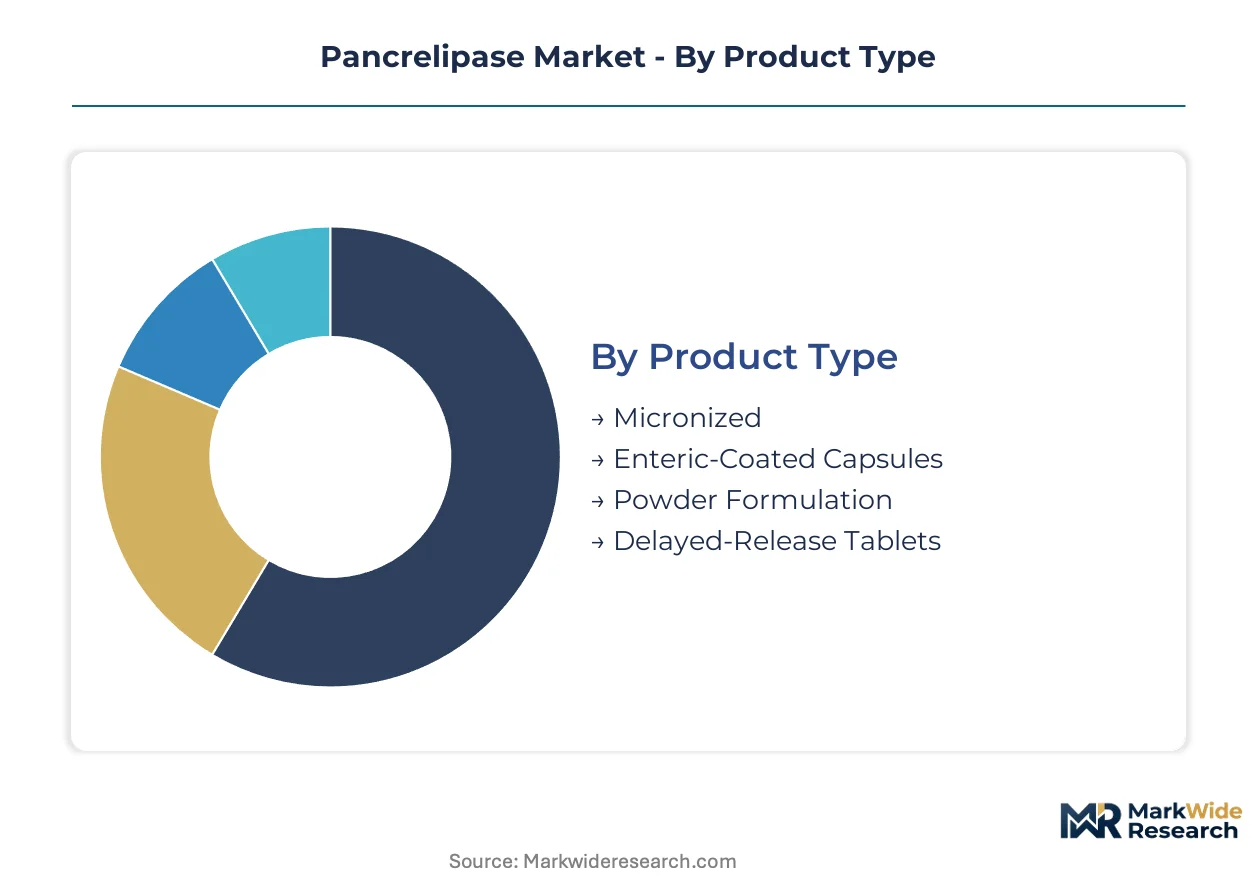
The pancrelipase market's distinct segments reflect diverse patient needs and therapeutic approaches. Understanding these categories illuminates key areas of demand, product innovation, and market access strategies. This segmentation analysis provides a granular view of the therapeutic landscape.
Product Type:
The product type spectrum for pancrelipase is defined by the specific formulation technologies employed to optimize enzyme delivery and efficacy for various clinical scenarios.
- Enteric-Coated Capsules:These formulations feature enzymes encapsulated within a protective layer designed to resist stomach acid. Demand concentrates in chronic pancreatic insufficiency patients, where precise release in the small intestine significantly improves nutrient absorption.
- Delayed-Release Tablets:These tablets are engineered to release their enzymatic content at a controlled rate, often after a specific transit time in the gastrointestinal tract. Their adoption is increasing among patients requiring sustained enzyme activity over longer periods, particularly in complex digestive disorders.
- Micronized:Micronized pancrelipase offers a fine powder formulation, often used for patients who have difficulty swallowing capsules or require mixing with food.
- Powder Formulation:This type provides a versatile option for pediatric patients or those needing adjustable dosing, allowing for direct mixing with soft foods.
The dominant share belongs to Enteric-Coated Capsules, while Delayed-Release Tablets are closing the gap fastest.
Application:
The application segments for pancrelipase reflect distinct patient populations, each presenting unique diagnostic and therapeutic requirements for enzyme replacement therapy.
- Cystic Fibrosis:Pancrelipase is essential for individuals with cystic fibrosis, who frequently experience severe exocrine pancreatic insufficiency. Treatment in this group is critical for managing malabsorption and improving nutritional status, especially in developed healthcare systems like the United States.
- Pancreatic Insufficiency:This broad category encompasses various etiologies of insufficient pancreatic enzyme production, including chronic pancreatitis and post-surgical conditions. Management focuses on restoring digestive function and reducing symptoms like steatorrhea, driven by rising prevalence in aging populations.
- Digestive Disorders:Pancrelipase addresses a range of digestive impairments where enzyme deficiency contributes to symptoms, offering symptomatic relief and improved nutrient uptake.
- Malabsorption Syndromes:These syndromes involve impaired nutrient absorption, and pancrelipase can provide critical enzymatic support to enhance digestion and nutrient assimilation.
Cystic Fibrosis represents a consistent demand base, with Pancreatic Insufficiency applications showing significant expansion.
End User:
The end-user landscape for pancrelipase is characterized by varying patient volumes and care complexities, influencing product distribution and support services.
- Hospitals:Hospitals serve as primary centers for initial diagnosis and acute management of conditions requiring pancrelipase therapy. High patient turnover and critical care needs drive substantial procurement volumes, particularly in urban centers.
- Home Care Settings:The shift towards outpatient and long-term management of chronic conditions has increased the use of pancrelipase in home care. These settings emphasize patient convenience and adherence, supported by integrated digital health platforms.
- Clinics:Clinics, including gastroenterology and specialty clinics, manage a significant patient load for ongoing pancrelipase therapy, focusing on routine follow-ups and dose adjustments.
- Long-Term Care Facilities:These facilities cater to elderly or chronically ill patients needing continuous pancrelipase administration, where consistent supply and ease of use are paramount.
Hospitals remain crucial for initial patient onboarding, while Home Care Settings are gaining share due to evolving care models.
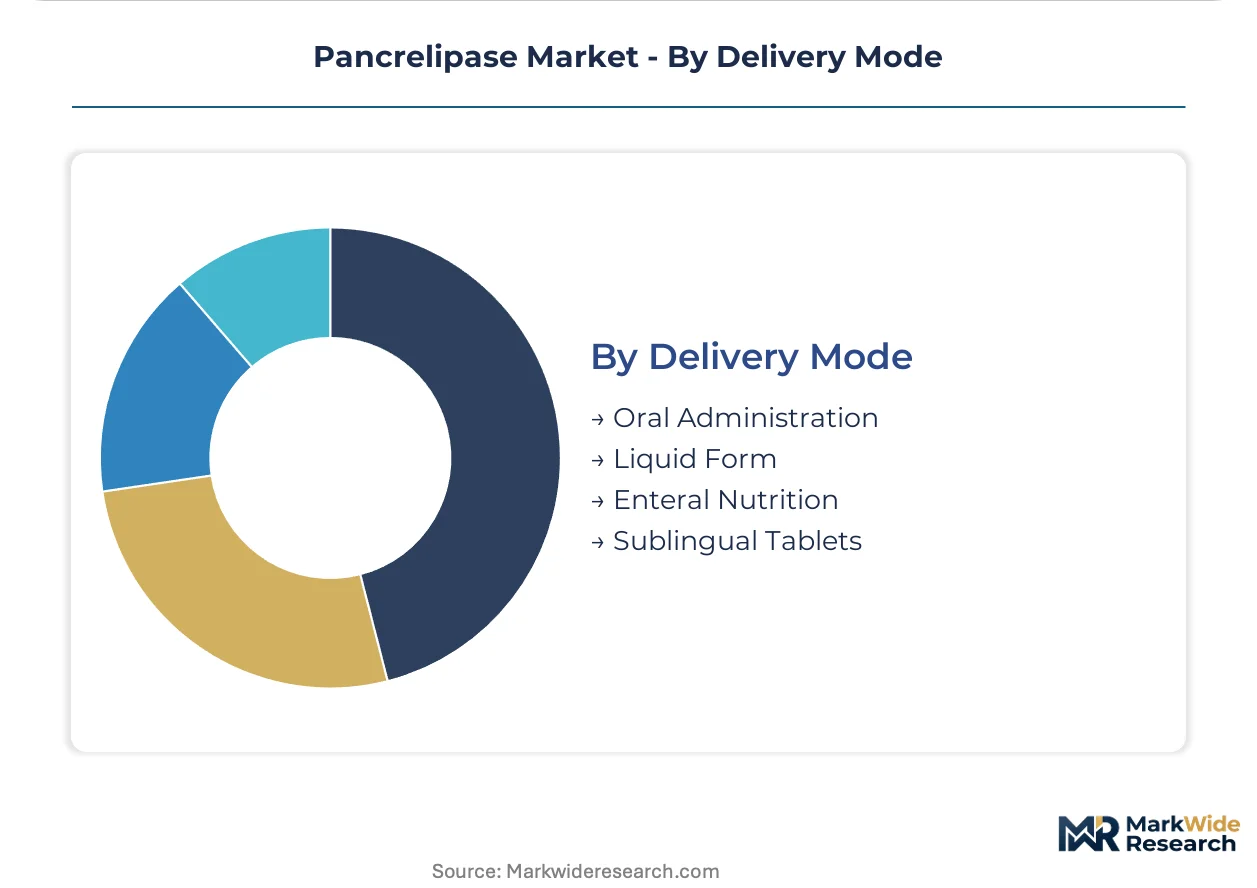
Delivery Mode:
The maturity of pancrelipase delivery modes ranges from established oral forms to specialized methods addressing particular patient challenges and clinical needs.
- Oral Administration:This traditional method involves swallowing capsules or tablets and remains the most common delivery route for pancrelipase. Its widespread acceptance is due to patient convenience and established efficacy in most patient populations.
- Enteral Nutrition:Pancrelipase can be administered through enteral feeding tubes for patients unable to take oral medications or requiring tube feeding. This mode ensures consistent enzyme delivery, particularly in critically ill or pediatric patients.
- Liquid Form:Liquid pancrelipase formulations offer an alternative for patients with dysphagia or those needing precise, small-volume dosing, especially in pediatric care.
- Sublingual Tablets:While less common for pancrelipase, sublingual administration offers rapid absorption for certain medications, though its application for digestive enzymes is limited.
Oral Administration dominates the market, with Enteral Nutrition providing critical support for specific patient cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Policy frameworks, such as specific guidance from the U.S. FDA, establish clear development pathways for pancrelipase products. These regulatory standards, mirrored by agencies like the European Medicines Agency (EMA), foster innovation while ensuring product safety and efficacy. This structured environment encourages investment in advanced formulations and delivery systems across key markets.
United States
Higher diagnosis rates for exocrine pancreatic insufficiency, particularly linked to cystic fibrosis, drive significant demand in the United States. The U.S. FDA's stringent bioequivalence guidelines ensure high-quality product development and market entry. Major pharmaceutical hubs in the Northeast, including areas around Boston and New Jersey, see concentrated research and manufacturing activities for these specialized therapies.
Germany
Germany's advanced healthcare system and high prevalence of chronic pancreatitis contribute to substantial pancrelipase consumption. The European Medicines Agency (EMA) oversees rigorous approval processes for all enzyme replacement therapies. Specialized gastroenterology clinics and research institutes in cities like Munich and Berlin are at the forefront of patient management and clinical trials.
Japan
Japan's aging population experiences an increasing incidence of pancreatic disorders, fueling a steady demand for digestive enzyme supplements. The Pharmaceuticals and Medical Devices Agency (PMDA) enforces strict efficacy and safety standards for all pharmaceutical products. Research clusters in Tokyo and Osaka focus on developing innovative formulations and improving patient adherence strategies for chronic conditions.
China
China's expanding healthcare infrastructure and rising diagnosis of digestive disorders, including pancreatic insufficiency, are creating new market opportunities. The National Medical Products Administration (NMPA) regulates the registration and marketing of imported and domestic drug products. Pharmaceutical manufacturing zones in Shanghai and Guangdong are actively expanding production capabilities to meet growing domestic and regional demand.
Pancrelipase Market Key Industry Players
On the supply side, the industry is characterized by a mix of established pharmaceutical giants and specialized digestive health companies. These players typically leverage their existing research capabilities and distribution networks for market presence. Strategic archetypes include large multinational pharmaceutical corporations, generic drug manufacturers, and nutritional science companies. Dominant competitive moves involve securing formulary access and navigating complex regulatory pathways for product approval.
Within the established pharmaceutical and nutritional science tiers, AbbVie Inc. exemplifies a major player with a strong focus on gastroenterology, leveraging its market position for formulary access. Viatris Inc. represents a significant force in the generic pharmaceutical segment, aiming for broad market penetration with its cost-effective offerings. Nestlé S.A., a Swiss-based multinational, sits within the nutritional science segment, complementing therapeutic interventions with its specialized dietary products for patients with pancreatic insufficiency. These companies anchor different strategic approaches to the pancrelipase market.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Digestive Care, Inc. |
| Viatris Inc. |
| Nestlé S.A. |
| Vivus Llc. |
| Abbott Laboratories |
| Organon Canada Inc. |
| Scientific Protein Laboratories |
| Allergan Pharmaceuticals International Limited |
| Others |
Cost & Logistics Intelligence
Single-source dependency on porcine pancreas glands significantly determines pricing tier spreads and shapes the pancrelipase supply chain. Stringent bioequivalence regulations also impose substantial costs, influencing market access and product pricing.
Pricing Analysis
FDA-grade certification level creates the primary pricing spread for pancrelipase products. The market operates on a value-based pricing model, heavily influenced by advanced formulation technologies and brand reputation. Pricing pressure stems from complex reimbursement negotiations with pharmacy benefit managers, yet high development costs maintain premium tiers. Patients seeking cost-effective options exhibit higher price sensitivity for generic versions, while hospitals and specialty clinics prioritize efficacy for branded products.
Supply Chain Analysis
Raw material dependency on porcine pancreas glands represents a significant supply chain vulnerability. Major sourcing regions for these glands include the United States, Germany, and China, influencing global availability. Animal health epidemics or regional sourcing disruptions pose a structural risk to consistent enzyme supply. Distribution primarily runs through specialized pharmacy channels and hospital procurement networks, ensuring controlled access for high-cost therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pancrelipase market exhibits a defensive-moat story, primarily driven by significant regulatory entrenchment. Stringent bioequivalence guidelines from the U.S. FDA and EMA create high barriers to entry, protecting established players.
For Market Incumbents: Insulate core market share by continuously investing in advanced formulation R&D, particularly microencapsulation technologies. Secure long-term, diversified raw material supply contracts to mitigate variability and animal health risks. This strategy counters potential erosion from emerging generic entrants and ensures consistent product quality. Deepen channel control through strategic partnerships with specialty pharmacies for enhanced reimbursement navigation.
For New Entrants and Emerging Players: Establish a beachhead in the non-porcine enzyme development segment, addressing dietary and religious restrictions. Target underpenetrated emerging markets like Latin America and Southeast Asia with diagnostic education initiatives. A go-to-market angle focusing on advanced delivery systems for pediatric patients or digital health integration for adherence can differentiate offerings. This approach bypasses direct competition in highly regulated, established segments.
For Investors and Strategic Acquirers: The market sits at a mature growth phase that favors established pharmaceutical and nutritional science companies. Long-term viability remains strong due to the essential nature of pancrelipase therapy and high regulatory barriers. Acquisition targets should include firms with proven bioequivalence capabilities, advanced formulation IP, or robust specialty pharmacy distribution networks. The signal to watch is any significant breakthrough in non-porcine enzyme commercialization.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | For new formulations, clinical trials validate superior efficacy and safety to secure regulatory approval. |
| Manufacturing Scale-Up | Expanding production capabilities in China meets growing domestic and regional demand for pancrelipase. |
| Licensing Agreement | Partnerships for novel enteric-coating technologies enhance enzyme stability and targeted delivery. |
| Distribution Channel Expansion | Integrating with specialty pharmacy networks streamlines access and reimbursement for high-cost therapies. |
| Pipeline Diversification | Investing in non-porcine enzyme development addresses raw material constraints and patient needs. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted for this analysis, combining primary interviews with extensive secondary validation. Stakeholders included gastroenterologists, regulatory affairs leads, specialty pharmacy managers, and R&D executives. Secondary data encompassed U.S. FDA guidance, EMA submissions, clinical trial registries, and company financial filings. A rigorous bottom-up and top-down triangulation approach ensured data consistency.
Volume and value outputs were calibrated against historical market trends and projected growth drivers over the projection horizon. Segmentation dimensions modeled included product type, application, end user, delivery mode, and regional regulatory clusters. Compound Annual Growth Rates were derived from market dynamics. Disease prevalence rates and regulatory approval timelines served as critical forecast inputs.
Sensitivities concentrate around raw material supply disruptions and unforeseen regulatory shifts impacting bioequivalence standards. Forecasts reflect assumptions regarding disease prevalence and healthcare infrastructure development. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Mtor Inhibitors Market
Pharmaceuticals
Diuretic Drugs Market
Pharmaceuticals
Josamycin Market
Pharmaceuticals
Cancer Therapeutics and Biotherapeutics Market
Pharmaceuticals
Thrombosis Drugs Market
Pharmaceuticals
Recombinant Plasma Protein Therapeutics Market
Pharmaceuticals
Global Pediatric Vaccines Market
Pharmaceuticals
Global Pharmaceutical Warehousing Market
Pharmaceuticals
Anti-Viral Therapeutics Market
Pharmaceuticals
Global Primary Biliary Cirrhosis Drug Market
Pharmaceuticals
Dipeptide Peptidase 4 Inhibitors Market
Pharmaceuticals
Flavors Into Over-The-Counter (OTC) Pharmaceuticals Market
Pharmaceuticals
Propofol Market
Pharmaceuticals
Intravitreal (IVT) Injectables Market
Pharmaceuticals
Estrogen Replacement Therapy (ERT) Market
Pharmaceuticals
Global Pharmaceutical Contract Manufacturing Market