
 Egypt Diabetes Drugs Market | 2026-2036
Egypt Diabetes Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Diabetes Drugs Market Foresight
Market Context
Biologic-grade insulin analogs is rotating toward the center of Egypt's diabetes treatment protocols, displacing older human insulin formulations in metropolitan hospital systems. Novo Nordisk leverages its recombinant DNA manufacturing platform to anchor supply security for rapid-acting analogs across Egyptian Ministry of Health tenders. Sanofi competes through differentiated basal insulin portfolios distributed via Pharco's established local logistics network.
Technical Definition and Segment Structure
Egypt diabetes drugs comprise pharmaceutical formulations engineered to modulate blood glucose homeostasis through exogenous insulin replacement, pancreatic beta-cell stimulation, hepatic glucose suppression, or incretin pathway enhancement, with bioequivalence thresholds typically requiring HbA1c reduction of 0.5–1.5 percentage points versus placebo. Injectable administration routes dominate hospital procurement due to precise dosing control and rapid onset requirements in acute hyperglycemic management. Retail pharmacy channels sustain volume leadership in chronic outpatient maintenance, while online distribution channels represent the fastest-growing segment as Egypt's digital health infrastructure matures under central bank e-payment directives.
Regulatory Framework and Outlook
CDSCO-aligned bioequivalence standards through Egypt's Drug Authority govern generic sulfonylurea and metformin approvals, while the Ministry of Health and Population insulin tender system shapes pricing accessibility and volume allocation across public hospitals. The Egyptian Drug Authority's accelerated registration pathway for biosimilars is forcing originator firms to recalibrate local partnership strategies. Stakeholders must monitor how universal health insurance expansion reshapes reimbursement tiers for DPP-4 inhibitors versus traditional oral hypoglycemics.
Market Dynamics
Universal health insurance reforms under Egypt's Ministry of Health and Population are restructuring procurement volumes and reimbursement tiers for diabetes therapeutics, shifting volume toward hospital-based insulin analogs and compressing margins on older oral formulations.
Growth Catalysts
- Universal Health Insurance Act expansion:Egypt's phased rollout of universal coverage is enrolling millions of previously uninsured patients into chronic disease protocols, creating guaranteed demand pools for diabetes medications through public hospital tenders.
- Injectable insulin analogs:Rapid-acting and basal analog formulations are capturing prescription share in Cairo and Alexandria's specialized endocrinology centers due to superior HbA1c control and reduced hypoglycemic events versus human insulin.
- Digital health infrastructure:Central Bank of Egypt e-payment directives are enabling telemedicine platforms and online pharmacy channels to reach rural governorates previously underserved by brick-and-mortar distribution.
Market Restraints
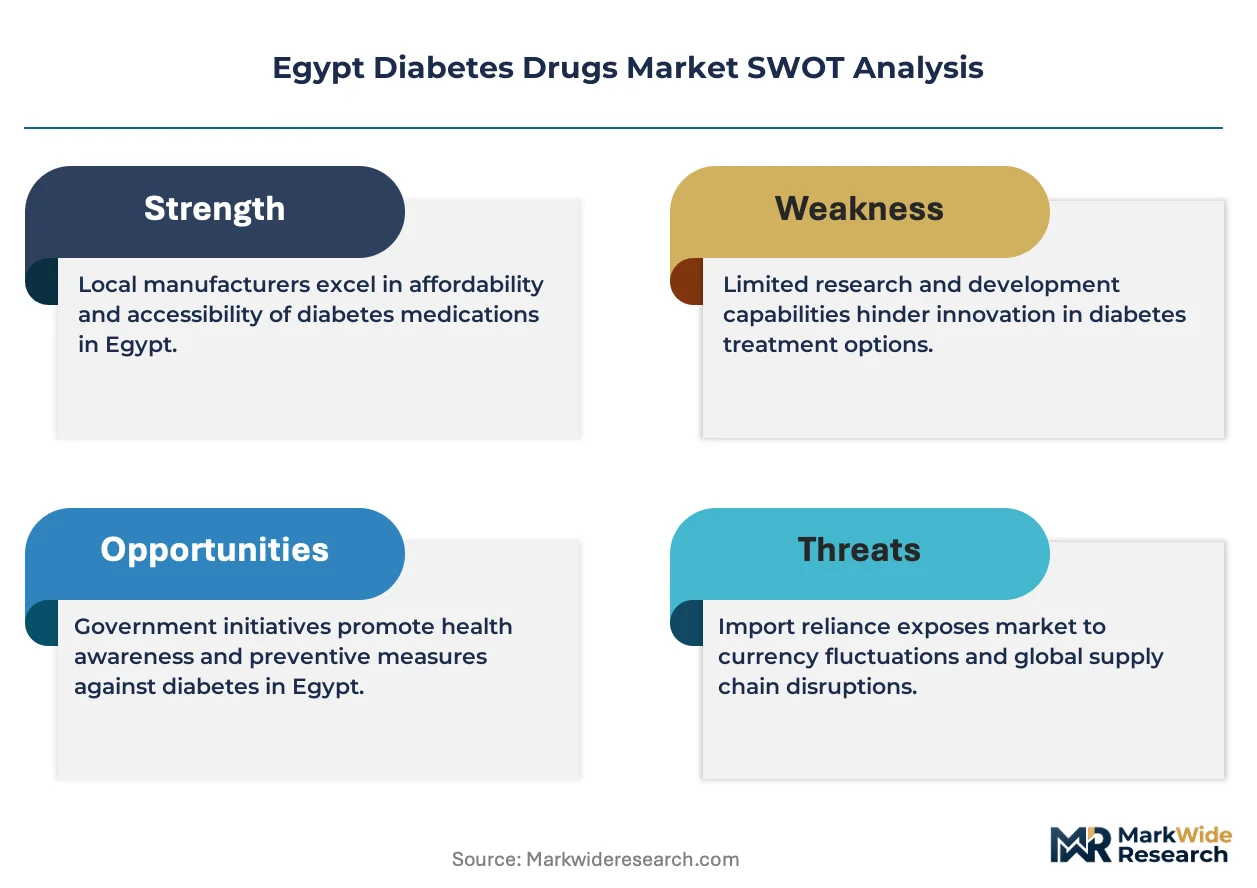
- Import dependency for biologics:Egypt lacks domestic recombinant insulin manufacturing, exposing supply security to currency volatility and foreign exchange rationing by the central bank.
- CDSCO-aligned bioequivalence requirements:Egyptian Drug Authority standards for generic sulfonylurea and metformin approvals create multi-year registration timelines that delay market entry for cost-competitive alternatives.
- Reimbursement tier compression:Ministry of Health tender pricing for human insulin formulations caps margins, discouraging investment in cold chain infrastructure for temperature-sensitive biologics.
Strategic Opportunities
- Upper Egypt governorates:Asyut, Sohag, and Qena present underpenetrated demand for diabetes management as urban migration concentrates specialist care in Cairo-Alexandria corridor.
- Biosimilar registration pathway:Egyptian Drug Authority accelerated approvals for insulin biosimilars create first-mover advantages for manufacturers able to demonstrate analytical similarity to originator products.
- Retail pharmacy network densification:Independent pharmacy chains in Delta region cities are expanding chronic disease counseling services, creating alternative channels beyond hospital dispensing.
Industry Challenges
- Cold chain integrity gaps:Temperature excursions during last-mile distribution to rural clinics degrade insulin potency, requiring capex-intensive refrigerated logistics investments that strain distributor working capital.
- Endocrinologist concentration:Specialist physician density in Cairo-Alexandria exceeds ten times that of frontier governorates, creating diagnostic and prescription bottlenecks outside metropolitan areas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Diabetes Drugs Market |
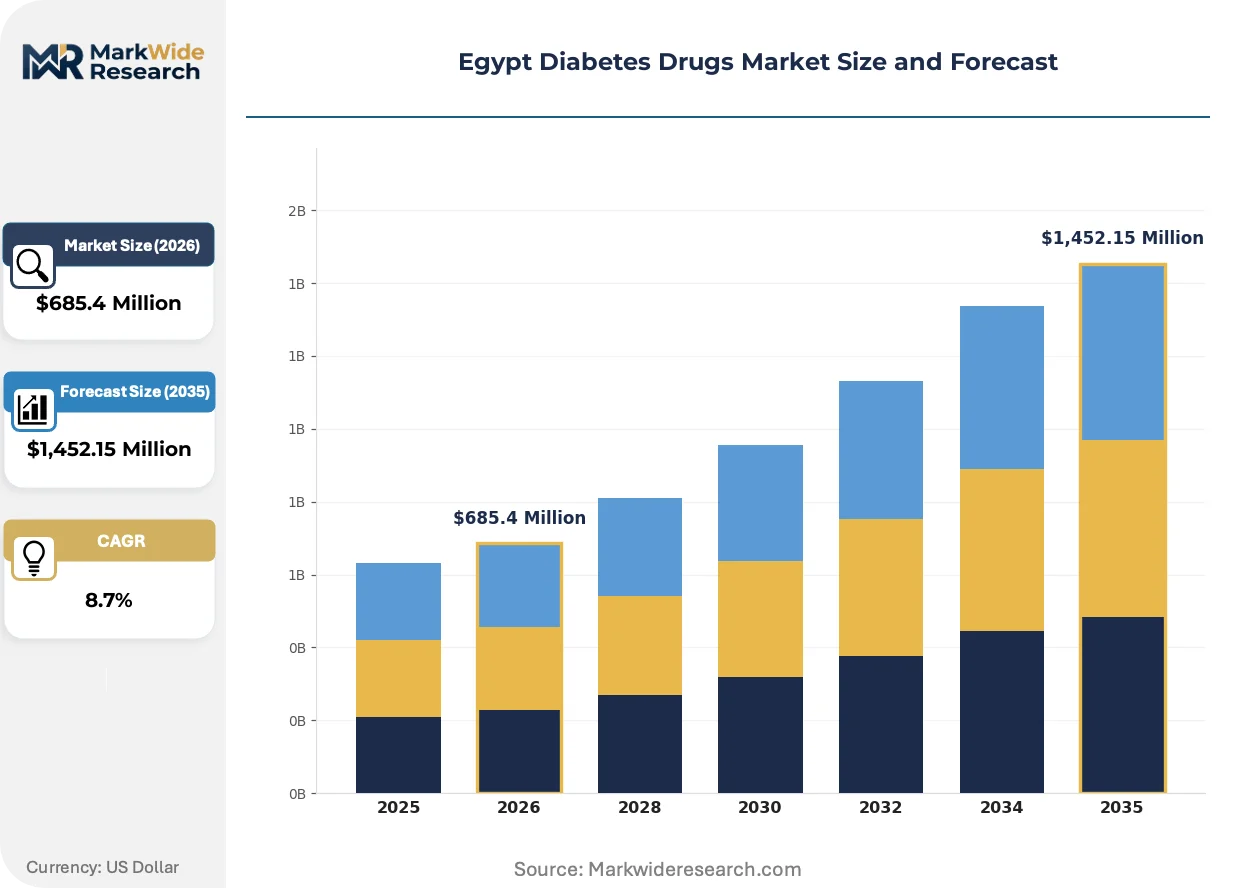
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, Sulfonylureas, DPP-4 Inhibitors, Metformin End User: Hospitals, Clinics, Pharmacies, Home Care Distribution Channel: Online, Retail, Direct Sales, Wholesale Administration Route: Injectable, Oral, Inhaled, Transdermal |
| Companies Covered | Eva Pharma, Merck & Co., Novo Nordisk, Pharco, Hikma, Sanofi, AstraZeneca, Julphar, Eli Lilly, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Diabetes Drugs Market Shifts & Advancements
Technological substitution in insulin delivery, regulatory acceleration for biosimilars, and channel fragmentation are converging to reshape competitive positioning and access patterns across Egypt's diabetes therapeutic landscape.
Continuous glucose monitoring systems paired with smart insulin pens are supplanting traditional self-monitoring blood glucose routines in private hospital networks. Affluent patient segments in Cairo's Mohandessin and Heliopolis districts are adopting these integrated systems despite out-of-pocket costs. The technology is compressing demand for conventional glucometer strips while creating new service revenue streams for device calibration and data interpretation.
Egyptian Drug Authority alignment with CDSCO bioequivalence standards is streamlining generic approvals for oral hypoglycemics while tightening analytical requirements for insulin biosimilars. Domestic manufacturers are responding by investing in in vitro bioassay capabilities to demonstrate pharmacokinetic equivalence. Small molecule generics are benefiting from faster registration timelines, whereas biologic entrants face extended characterization studies.
Hospital-centric procurement is fragmenting as retail pharmacy chains and digital health platforms capture chronic maintenance prescriptions following initial diagnosis. Patients stabilized on insulin regimens in public hospitals are transferring refill loyalty to neighborhood pharmacies offering home delivery. This shift is most pronounced in Giza and Alexandria, where pharmacy density and mobile penetration support subscription-based medication delivery models.
Egypt Diabetes Drugs Market Segmentation
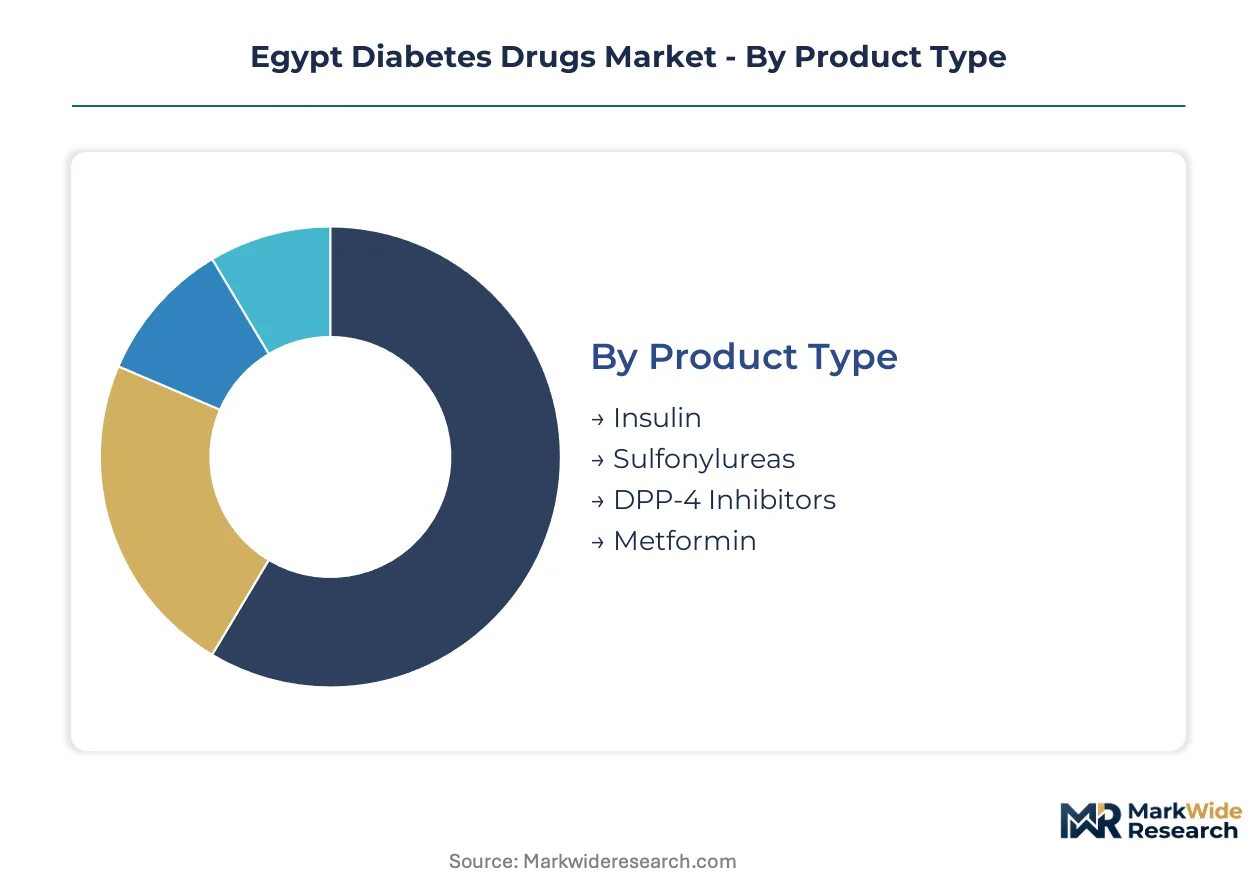
Segmentation in Egypt's diabetes drugs market reveals how procurement reform, channel fragmentation, and biologic substitution are redistributing value across product categories and delivery modalities. Understanding these fault lines exposes where pricing power concentrates and where volume growth is accelerating.
Product Type:
Margin pools concentrate in biologic-grade insulin analogs as Egyptian Ministry of Health tenders shift procurement toward hospital-based injectable therapies with superior glycemic control profiles.
- Insulin:Recombinant human insulin and rapid-acting/basal analog formulations dominate hospital procurement under universal health insurance protocols. Cairo and Alexandria's specialized endocrinology centers concentrate demand for analogs due to reduced hypoglycemic event rates versus older human insulin formulations.
- DPP-4 Inhibitors:Oral incretin pathway modulators capture outpatient prescription share among affluent patient segments seeking weight-neutral glucose control. Private hospital networks in Giza and Mohandessin districts drive volume for sitagliptin and vildagliptin formulations as Egyptian Drug Authority registration pathways mature.
- Sulfonylureas:Legacy pancreatic beta-cell stimulants retain volume in public sector tenders due to cost-competitive positioning against newer therapeutic classes.
- Metformin:First-line hepatic glucose suppressant maintains ubiquity across retail pharmacy channels for Type 2 diabetes initial therapy.
Insulin holds installed capacity. DPP-4 Inhibitors is rotating up the share rankings.
End User:
Volume concentration follows Egypt's specialist physician geography, with diagnostic and prescription authority clustering where endocrinology infrastructure is densest.
- Hospitals:Public and private hospital systems anchor insulin analog procurement through Ministry of Health tender mechanisms. Universal health insurance enrollment is funneling chronic disease patients into hospital-based protocols, consolidating dispensing authority within institutional pharmacy units.
- Pharmacies:Independent and chain retail pharmacies capture maintenance prescription refills following initial hospital diagnosis. Delta region cities including Tanta and Mansoura are seeing pharmacy network densification with chronic disease counseling services.
- Clinics:Outpatient diabetes centers in urban corridors provide diagnostic and titration services, though dispensing remains secondary to hospital and pharmacy channels.
- Home Care:Nurse-assisted insulin administration and glucose monitoring services are emerging in affluent Cairo districts, supported by digital health platform coordination.
Hospitals command procurement volume. Pharmacies are climbing the fastest as channel fragmentation accelerates.
Distribution Channel:
Channel economics diverge sharply between cold chain-dependent biologics and ambient-stable oral formulations, with working capital requirements shaping distributor participation.
- Retail:Brick-and-mortar pharmacy networks sustain volume leadership for oral hypoglycemic maintenance therapies. Alexandria and Giza pharmacy chains are piloting subscription-based home delivery for stabilized insulin patients.
- Online:Telemedicine-integrated pharmacy platforms represent the steepest expansion trajectory as Central Bank of Egypt e-payment directives enable digital prescription fulfillment. Rural governorates previously underserved by physical distribution are accessing diabetes medications through mobile-enabled channels.
- Wholesale:Cold chain-capable distributors supply hospital tenders and retail networks with temperature-sensitive insulin formulations.
- Direct Sales:Manufacturer-to-institution contracting occurs for high-volume insulin analog tenders to Ministry of Health systems.
Retail maintains refill dominance. Online is gaining share fastest among channel modalities.
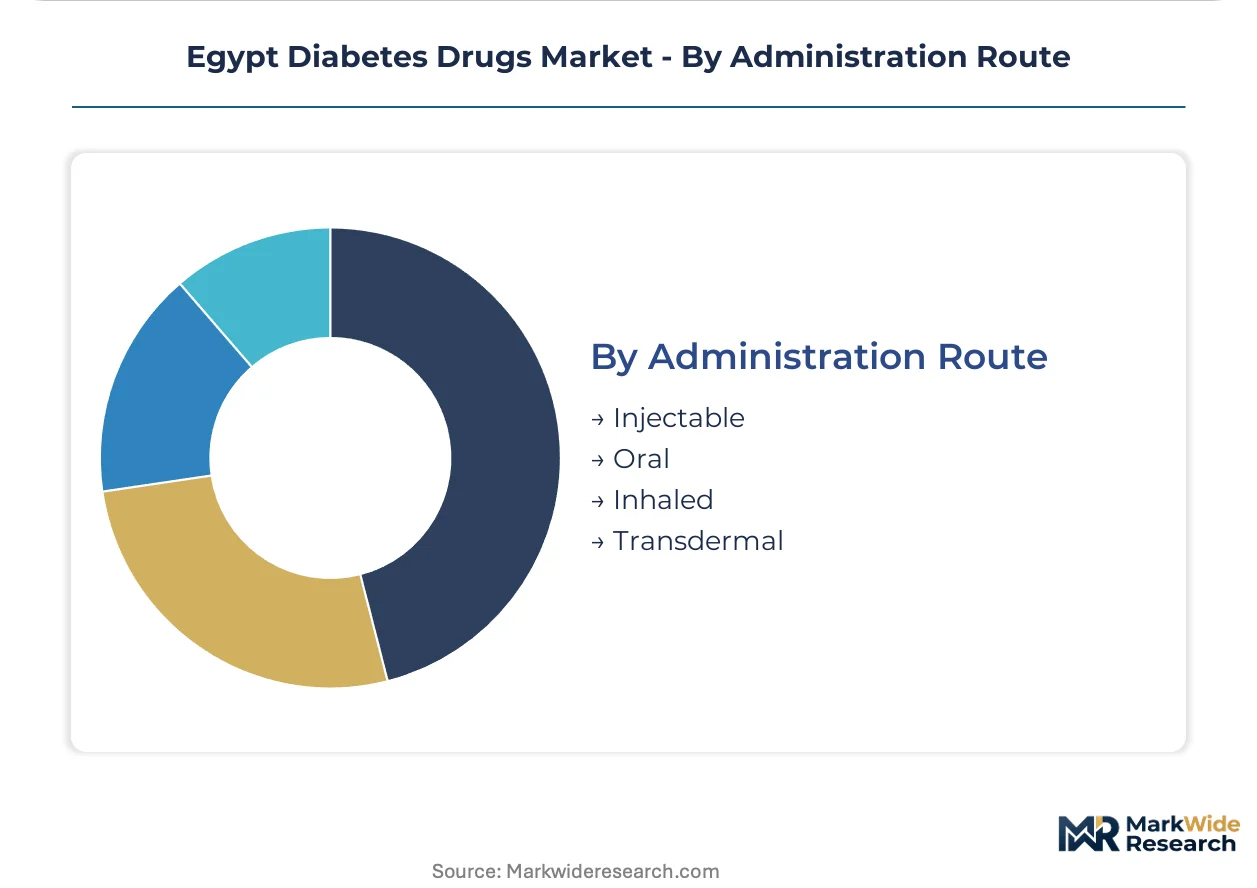
Administration Route:
Route selection correlates with disease progression stage and patient access to specialist care, with injectable therapies concentrated where diagnostic infrastructure is most developed.
- Injectable:Subcutaneous insulin delivery dominates Type 1 diabetes management and advanced Type 2 cases requiring exogenous replacement. Precision dosing requirements and rapid onset needs in acute hyperglycemic management sustain hospital preference for injectable administration.
- Oral:Tablet and capsule formulations for metformin, sulfonylureas, and DPP-4 inhibitors anchor early-stage Type 2 diabetes protocols. Patient preference for non-invasive administration sustains retail pharmacy volume for oral therapies.
- Inhaled:Pulmonary insulin delivery remains niche due to limited Egyptian Drug Authority registrations and reimbursement uncertainty.
- Transdermal:Patch-based delivery systems for glucose monitoring adjuncts are experimental in private hospital pilot programs.
Injectable anchors biologic value. Oral retains volume scale across patient populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt's diabetes drugs market depends heavily on imported biologic formulations, with foreign exchange availability governing supply security for insulin analogs. The country's pharmaceutical trade balance tilts toward finished dosage imports from European and Indian manufacturing hubs. Domestic formulation capabilities concentrate in Cairo and Alexandria, where local partners repackage and distribute for multinational patent holders.
Cairo Governorate
Cairo's specialized endocrinology centers generate concentrated demand for rapid-acting insulin analogs as Egypt's Ministry of Health and Population directs universal health insurance patients toward hospital-based chronic disease protocols. Egyptian Drug Authority registration offices in Nasr City process accelerated biosimilar applications, compressing approval timelines for manufacturers demonstrating analytical similarity. New Cairo and Heliopolis districts host private hospital networks piloting continuous glucose monitoring integration.
Alexandria
Alexandria's port infrastructure handles temperature-sensitive biologic imports through cold chain-capable logistics networks serving Delta region distribution. Pharco's local headquarters anchors insulin formulation and packaging operations for multinational partners seeking Egyptian market access. Smouha and San Stefano medical districts concentrate private diabetes clinics prescribing DPP-4 inhibitors to affluent outpatients.
Giza
Giza's retail pharmacy chains capture maintenance prescription refills as patients stabilized in Cairo hospitals transfer loyalty to neighborhood dispensing points. Central Bank of Egypt e-payment directives enable Mohandessin-based telemedicine platforms to reach chronic disease patients across the governorate. Sheikh Zayed City's emerging medical complexes attract endocrinology specialists from downtown Cairo.
Upper Egypt Governorates
Asyut, Sohag, and Qena present underpenetrated demand pools where diagnostic infrastructure scarcity delays Type 2 diabetes identification and insulin initiation. Egyptian Ministry of Health and Population mobile screening units traverse rural circuits to enroll patients into universal health insurance chronic disease protocols. Local pharmacy networks in these governorates rely on Alexandria-based wholesalers for intermittent insulin supply.
Delta Region
Tanta and Mansoura anchor expanding pharmacy chains offering chronic disease counseling services beyond traditional dispensing functions. Egyptian Drug Authority bioequivalence requirements for generic metformin and sulfonylureas sustain multi-year registration timelines that delay cost-competitive alternatives. Regional distributors invest in refrigerated vehicle fleets to maintain cold chain integrity for temperature-sensitive biologics reaching frontier clinics.
Egypt Diabetes Drugs Market Competitive Landscape
Listed leaders compete with private specialists across tender participation and retail channel access in Egypt's diabetes drugs sector. Novo Nordisk and Sanofi anchor the multinational tier through recombinant insulin manufacturing platforms and established Egyptian Drug Authority registrations. Local private specialists including Eva Pharma and Pharco concentrate on generic oral hypoglycemic formulation and distribution logistics. Competitive moves center on biosimilar registration acceleration and cold chain partnership densification.
Within the multinational tier, Novo Nordisk and Sanofi occupy positions anchored by recombinant DNA manufacturing platforms supplying Egyptian Ministry of Health insulin tenders. Eli Lilly and AstraZeneca sit within the diversified portfolio archetype spanning injectable and oral hypoglycemic categories. Among locally integrated operators, Eva Pharma and Pharco exemplify private specialists leveraging distribution infrastructure and regulatory navigation capabilities. Merck & Co., Hikma, and Julphar represent hybrid archetypes combining multinational reach with regional formulation presence. The competitive dynamic pits originator biologic defenders against biosimilar entrants capitalizing on Egyptian Drug Authority accelerated pathways.
| Leading Market Players |
|---|
| Eva Pharma |
| Merck & Co. |
| Novo Nordisk |
| Pharco |
| Hikma |
| Sanofi |
| AstraZeneca |
| Julphar |
| Eli Lilly |
| Others |
Supply & Pricing Matrix
Ninety-day insulin inventory buffers at Alexandria cold storage facilities concentrate pricing power with Ministry of Health tender participants while exposing distributors to Egyptian pound volatility against euro-denominated import invoices. This inventory-to-pricing nexus shapes margin allocation across recombinant biologics and generic oral formulations.
Pricing Analysis
Public hospital procurement managers anchor insulin analog pricing through centralized Egyptian Ministry of Health tenders, with three-tier pricing structure across originator biologics, licensed biosimilars, and human insulin formulations. Price differentiation rests on cold chain certification grade and volume scale commitments in annual offtake agreements. Cost compression in human insulin tiers is intensifying because universal health insurance reimbursement caps prioritize accessibility over distributor margins. Retail pharmacy segments exhibit highest price sensitivity due to patient out-of-pocket exposure, while private hospital networks absorb premium analog pricing through bundled service packages.
Supply Chain Analysis
Strait of Hormuz transit underwrites temperature-sensitive biologic shipments reaching Egyptian ports, with Denmark, France, and Germany anchoring recombinant insulin manufacturing for Egyptian market access. Active pharmaceutical ingredients for metformin and sulfonylureas draw from Indian and Chinese chemical synthesis hubs. Single-source vulnerability concentrates in recombinant DNA cell culture capacity controlled by European originators. Distribution runs through Alexandria-based cold chain wholesalers serving Delta region pharmacy networks and Upper Egypt rural clinics via refrigerated vehicle fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's diabetes drugs market functions as a regulatory-moat arena where Egyptian Drug Authority registration timelines and Ministry of Health tender participation rights create entrenched competitive positions. Switching costs for hospital formulary managers reinforce incumbent dominance.
For Market Incumbents: Fortify cold chain infrastructure partnerships with Delta region distributors to preempt biosimilar entrants from achieving last-mile temperature integrity. Deepen backward integration into Egyptian Drug Authority bioequivalence testing capabilities to accelerate generic metformin registration timelines. The accelerating biosimilar approval pathway threatens originator insulin margin pools. For New Entrants and Emerging Players: Anchor in Upper Egypt governorates where diagnostic infrastructure scarcity delays insulin initiation and local pharmacy networks rely on intermittent Alexandria wholesaler supply. Target Asyut and Sohag mobile screening circuits as patient enrollment channels. Deploy telemedicine-integrated pharmacy platforms to circumvent Cairo-Alexandria specialist concentration. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational pharmaceutical parents seeking to divest legacy human insulin portfolios amid analog substitution pressure. Assess distribution-rights holdings with Ministry of Health tender participation history as durable cash flow generators. Monitor Egyptian pound stabilization against euro as inflection indicator for import-dependent biologic supply security.| Strategic Initiative | Industry Significance |
|---|---|
| Biosimilar Registration Acceleration | Egyptian Drug Authority fast-track approvals compress originator exclusivity windows for insulin analogs. |
| Cold Chain Partnership Densification | Refrigerated logistics investments in Delta region cities secure last-mile biologic integrity. |
| Telemedicine Platform Integration | Central Bank of Egypt e-payment directives enable digital prescription fulfillment in rural governorates. |
| Retail Pharmacy Network Expansion | Independent chains in Tanta and Mansoura add chronic disease counseling beyond dispensing. |
| Universal Health Insurance Tender Participation | Ministry of Health procurement reforms consolidate volume through institutional pharmacy units. |
Research Methodology
The analysis maps insulin analog, oral hypoglycemic, and biosimilar sub-sectors, each validated through hospital procurement managers, pharmacy chain operators, regulatory affairs specialists, and cold chain logistics directors. Primary interviews with Egyptian Ministry of Health formulary committees and pharmaceutical distributor executives combined with secondary validation against Egyptian Drug Authority registration databases, Ministry of Health tender disclosures, and Central Bank of Egypt import statistics. Bottom-up patient population modeling and top-down pharmaceutical trade flow analysis provided triangulation checks.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, administration route, distribution channel, and regional regulatory cluster within Egypt. CAGRs derived from patient enrollment trajectories under universal health insurance expansion, insulin analog substitution rates, and bioequivalence approval velocity assumptions. Forecast inputs incorporated Egyptian pound exchange rate sensitivity and cold chain infrastructure investment cycles.
Decision-makers should treat outputs as directional under stable universal health insurance enrollment assumptions; material deviation in foreign exchange rationing would warrant model refresh. Forecasts reflect assumptions on biosimilar registration timelines and Ministry of Health tender pricing protocols. Practitioners should keep alternative scenarios live as Egyptian Drug Authority regulatory alignment with CDSCO standards evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Depression Drugs Market
Pharmaceuticals
Intravitreal (IVT) Injectables Market
Pharmaceuticals
Global Fluorouracil (5FU) Market
Pharmaceuticals
H1N1 Vaccination Market
Pharmaceuticals
Next-Generation Immunology Drugs Market
Pharmaceuticals
Propofol Market
Pharmaceuticals
Pharma PLM Market
Pharmaceuticals
Global Controlled Release Drug Delivery Market
Pharmaceuticals
Drug-Loaded Oral Thin Films Market
Pharmaceuticals
Mouth Ulcers Treatment Market
Pharmaceuticals
Urinary Retention Drugs Market
Pharmaceuticals
Germany Pharmaceutical Warehousing Market
Pharmaceuticals
Global Anesthesia Drugs Market
Pharmaceuticals
Sulfonylureas Market
Pharmaceuticals
Leukotriene Modifiers Market
Pharmaceuticals
Latin America Dipeptide Peptidase 4 (DPP-4) Inhibitors Market