
 Carbetocin Acetate Market | 2026-2036
Carbetocin Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
Carbetocin Acetate Market Insights
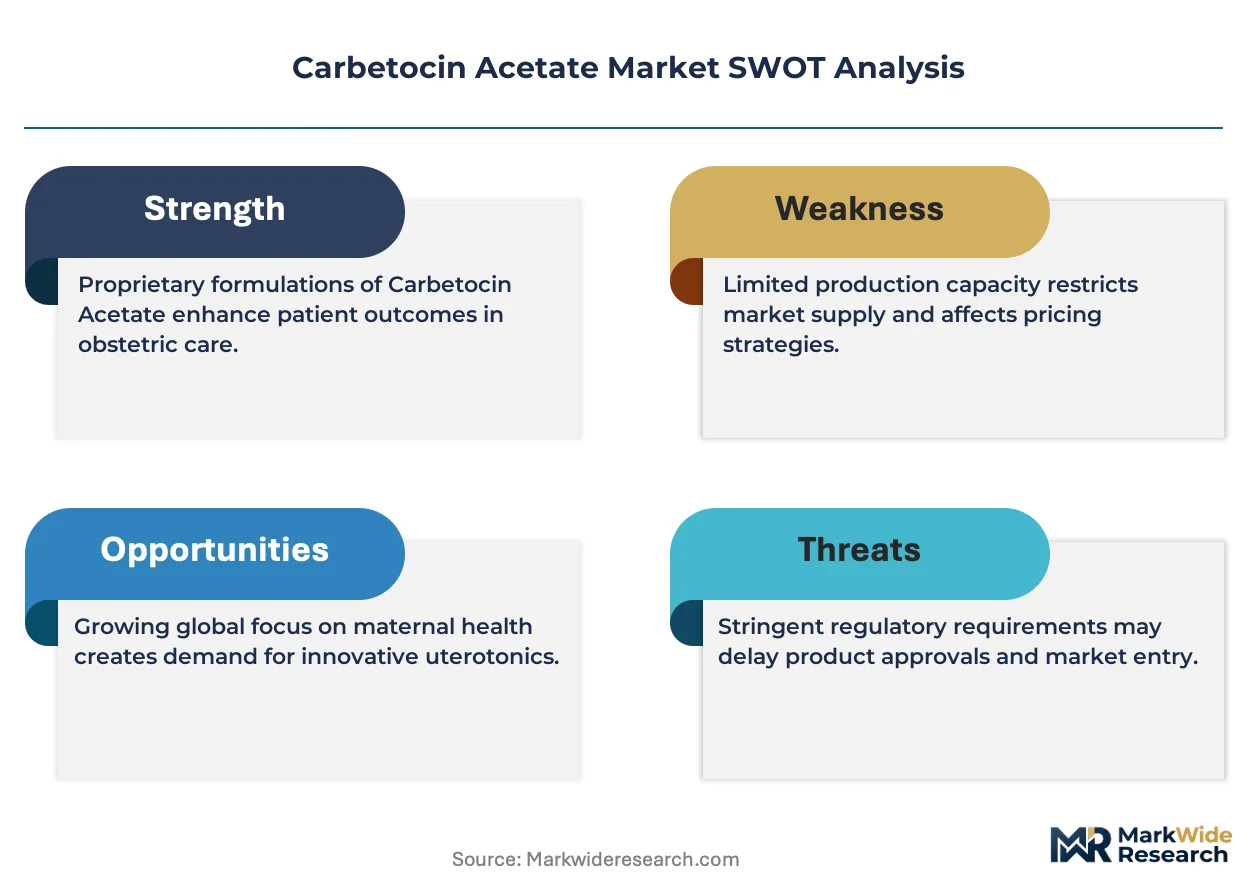
CE marking under the EU Medical Device Regulation is unwinding competitive access for European contract manufacturers. CordenPharma leverages its peptide synthesis infrastructure to anchor supply relationships with multinational pharmaceutical firms. Piramal Pharma Solutions competes through integrated active pharmaceutical ingredient and finished dosage form capabilities across multiple geographies. BCN Peptides specializes in niche peptide production, occupying a defensible position in carbetocin-specific manufacturing expertise.
Carbetocin acetate is a synthetic long-acting oxytocin analogue with an eight-amino-acid cyclic peptide structure, manufactured through solid-phase peptide synthesis followed by acetylation and purification steps. It functions primarily as a uterotonic agent for preventing postpartum hemorrhage by inducing sustained uterine contraction after cesarean section. The injection segment dominates current volume due to established hospital protocols and rapid onset requirements in obstetric emergencies. Prefilled syringe formats are gaining structural importance as maternity centers seek to reduce preparation errors and streamline administration workflows. Homecare settings remain nascent but represent a developing margin pool where subcutaneous delivery modes could expand addressable use cases.
FDA oversight of peptide drug substance manufacturing, EMA's Good Manufacturing Practice inspections for sterile injectables, and China's NMPA drug registration requirements collectively shape market access and quality benchmarks for carbetocin acetate suppliers. These regulatory frameworks elevate compliance costs for smaller manufacturers while reinforcing the position of firms with established inspection histories and dedicated peptide facilities. Stakeholders must monitor evolving pharmacovigilance obligations and biosimilar peptide guidance documents that could redefine competitive thresholds without warning.
Market Dynamics
Hospital procurement protocols for postpartum hemorrhage prevention are tightening around long-acting uterotonics, compressing purchasing cycles and elevating peptide API quality benchmarks as the decisive competitive filter.
Growth Catalysts
- FDA postpartum hemorrhage prevention guidelines:Updated clinical protocols mandate prophylactic uterotonic administration after cesarean delivery, institutionalizing carbetocin acetate within hospital formularies.
- Solid-phase peptide synthesis automation:Advances in continuous manufacturing reduce batch-to-batch variability and accelerate time-to-market for generic peptide suppliers.
- China's NMPA drug registration pathway:Streamlined biosimilar peptide approval processes enable domestic manufacturers to capture share in institutional birth markets.
Market Restraints
- Specialized peptide starting material concentration:Protected amino acid derivatives and resins concentrate among three European chemical suppliers, exposing margins to input volatility.
- EMA Good Manufacturing Practice inspection backlog:Sterile injectable facility certification delays extend commercialization timelines for emerging manufacturers by 18-24 months.
- Oxytocin cost anchor:Generic oxytocin infusion maintains formulary presence at one-fifth the unit cost, constraining carbetocin uptake in price-sensitive public health systems.
Strategic Opportunities
- Prefilled syringe workflow integration:Maternity centers in Germany and the United States are adopting ready-to-administer formats to reduce preparation errors and nursing labor.
- Subcutaneous delivery development:Alternative administration routes could extend addressable use cases toward outpatient postpartum monitoring protocols.
- India's institutional birth expansion:National health mission targets for facility-based deliveries create procurement volume in a market currently dependent on oxytocin.
Industry Challenges
- Peptide analytical method transfer:Complex impurity profiling and bioassay validation require specialized talent pools that concentrate among contract research organizations in Switzerland and the Netherlands.
- Cold chain integrity maintenance:Temperature excursion risks during multi-modal distribution to secondary and tertiary hospitals elevate quality assurance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbetocin Acetate Market |
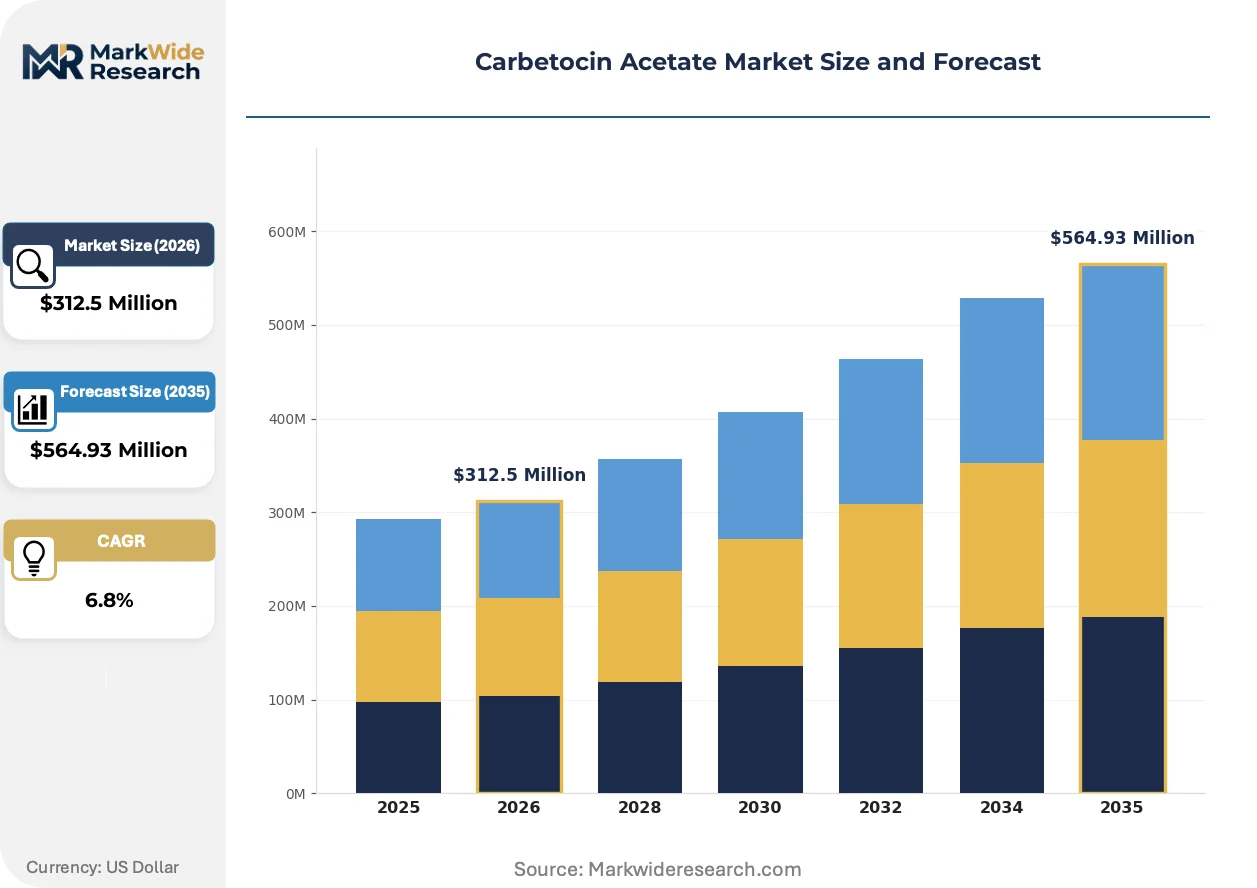
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection, Powder, Solution, Prefilled Syringe End User: Hospitals, Clinics, Maternity Centers, Homecare Settings Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral Packaging Type: Vials, Ampoules, Blister Packs, Others |
| Companies Covered | Rochem International Inc., BCN Peptides, Suzhou Tianma Pharma Group, Ningbo Syntame Biotech, Omgene Life Sciences, Anhui Anke Biotechnology, Piramal Pharma Solutions, CordenPharma, Shenzhen JYMed Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbetocin Acetate Market Trends and Innovations
Peptide manufacturing technology and regulatory data requirements are reshaping competitive access, with automation and digital traceability emerging as the primary vectors of differentiation among sterile injectable suppliers.
Continuous flow peptide synthesis is fragmenting traditional batch manufacturing economics. Mid-scale contract manufacturers in Germany and the United States are piloting integrated synthesis-purification platforms that reduce solvent consumption and improve yield consistency. This technology is fragmenting the historical advantage of large-volume batch specialists by enabling flexible, smaller-scale production with comparable unit economics.
EMA's Medical Device Regulation CE marking requirements for combination products are extending compliance burdens to prefilled syringe assemblies. Device-peptide integration now demands dual technical files and coordinated quality management systems. European maternity networks are responding by consolidating supplier panels to manufacturers with proven MDR technical documentation capabilities.
Hospital pharmacy committees are compressing therapeutic interchange timelines for postpartum hemorrhage protocols. Formulary decisions that previously spanned 18-month review cycles now conclude within 90 days based on pharmacoeconomic modeling and obstetric outcome data. This behavioral shift is most pronounced in United States academic medical centers where value-based obstetric bundles incentivize rapid protocol standardization.
Carbetocin Acetate Market Segmentation
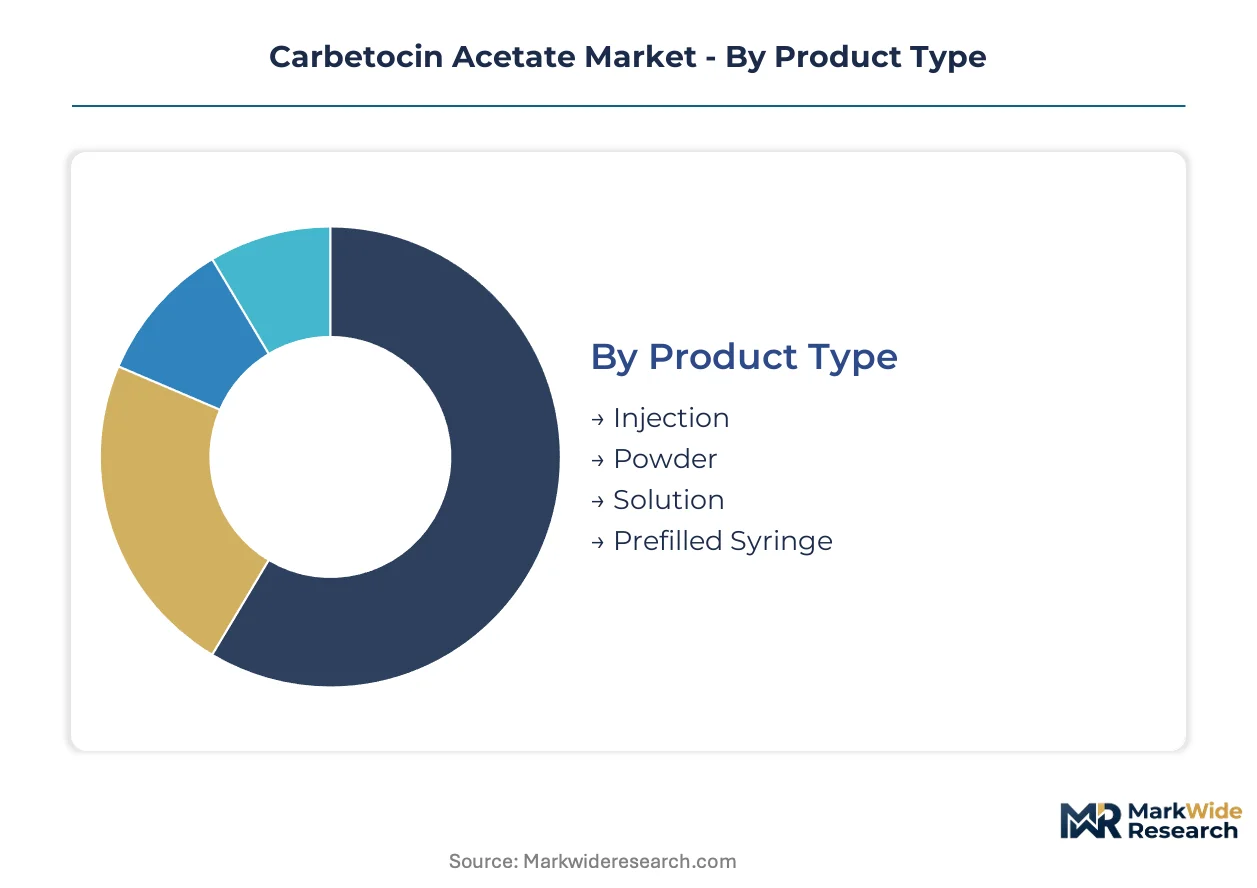
Carbetocin acetate's therapeutic positioning spans acute hospital protocols and emerging outpatient pathways, with each segment carrying distinct regulatory, logistical, and clinical requirements that reshape supplier economics.
Product Type:
FDA sterile injectable guidelines, EMA Good Manufacturing Practice standards for peptides, and China's NMPA drug registration protocols each impose divergent stability and documentation burdens across formulation categories.
- Injection:Liquid formulation in single-dose containers dominates procurement volume through established compatibility with cesarean section protocols. Hospital formularies in the United States and Germany anchor demand here, though cold chain requirements constrain distribution to secondary facilities.
- Prefilled Syringe:Ready-to-administer assemblies reduce preparation errors in maternity center workflows. CE marking under EU Medical Device Regulation extends compliance timelines, but German obstetric networks are consolidating purchasing around MDR-capable suppliers.
- Powder:Lyophilized format extends shelf stability for inventory-heavy procurement models in price-sensitive systems.
- Solution:Pre-mixed liquid presentations suit high-throughput surgical centers with dedicated pharmacy infrastructure.
Established volume favors injection; emerging adoption favors prefilled syringe.
End User:
Institutional procurement sophistication varies sharply, with tertiary hospitals demanding peptide API traceability that outpatient settings currently bypass.
- Hospitals:Academic medical centers in the United States drive protocol standardization through value-based obstetric bundles. Their purchasing committees compress therapeutic interchange timelines to 90-day review cycles.
- Maternity Centers:Specialized obstetric facilities in Germany prioritize workflow efficiency, accelerating prefilled format uptake despite premium positioning.
- Clinics:Outpatient surgical settings lack cold chain infrastructure for peptide stability requirements.
- Homecare Settings:Subcutaneous delivery development could extend addressable use cases toward post-discharge monitoring protocols.
Procurement concentration sits with hospitals; margin expansion potential concentrates in maternity centers.
Delivery Mode:
Pharmacokinetic profiles and onset requirements segment clinical utility across obstetric emergency versus prophylactic applications.
- Intravenous:Rapid uterotonic onset aligns with cesarean section protocols. FDA postpartum hemorrhage prevention guidelines institutionalize IV administration within hospital formularies.
- Subcutaneous:Sustained absorption profiles suit outpatient monitoring scenarios. Development programs target India's institutional birth expansion where facility-based delivery targets create procurement volume.
- Intramuscular:Intermediate onset characteristics occupy niche positioning where IV access is delayed.
- Oral:Bioavailability limitations exclude this route from current carbetocin formulations.
Clinical protocol rigidity sustains intravenous dominance; alternative route development targets subcutaneous expansion.
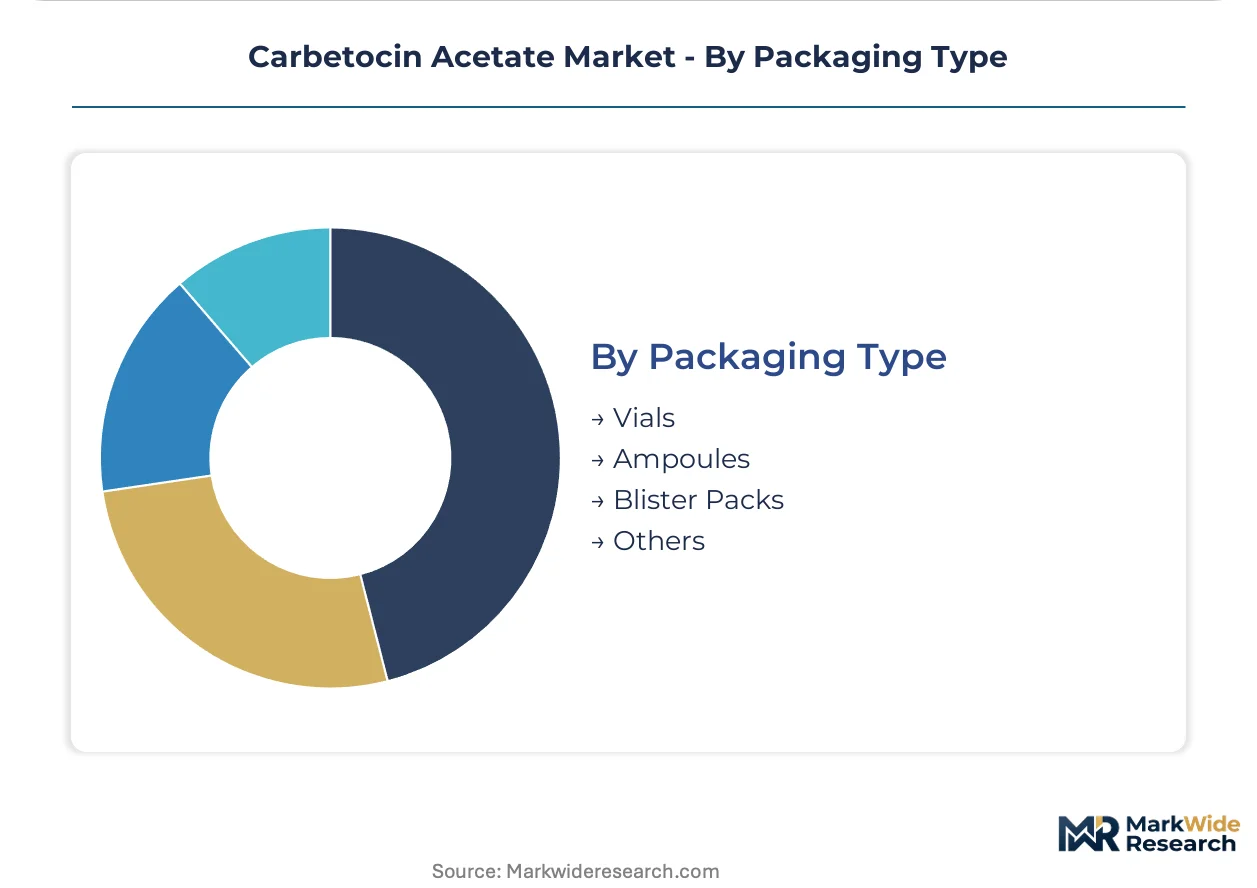
Packaging Type:
Container-closure integrity requirements and administration workflow preferences fragment supplier specialization.
- Vials:Multi-dose glass containers suit pharmacy-compounding workflows in high-volume United States hospitals.
- Ampoules:Single-unit presentations reduce contamination risk in European maternity networks.
- Blister Packs:Unit-dose configurations support automated dispensing systems in German academic centers.
- Others:Cartridge and dual-chamber formats occupy developmental positioning for combination product integration.
Glass primary packaging retains volume leadership; plastic-barrier and combination formats gain share in workflow-optimized settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA postpartum hemorrhage prevention guidelines institutionalize carbetocin acetate within United States hospital formularies, while China's NMPA streamlines biosimilar peptide approvals and Germany's EMA MDR compliance reshapes European procurement.
United States
Academic medical centers compress therapeutic interchange timelines to 90-day review cycles through value-based obstetric bundles. FDA sterile injectable guidelines mandate peptide API traceability for hospital formulary inclusion. The Greater Boston cluster anchors contract research organization concentration for analytical method development.
Germany
Maternity networks prioritize prefilled syringe workflows to reduce nursing labor and preparation errors. EMA Medical Device Regulation CE marking extends compliance timelines for combination products. The Rhine-Main region concentrates peptide synthesis infrastructure serving multinational pharmaceutical supply relationships.
China
National health mission targets for facility-based deliveries expand institutional birth procurement volume. NMPA drug registration pathways enable domestic manufacturers to capture share in peptide API production. The Yangtze River Delta anchors solid-phase peptide synthesis automation investments.
India
Janani Suraksha Yojana and allied maternal health programs drive procurement volume toward long-acting uterotonics. CDSCO regulatory frameworks elevate compliance costs while reinforcing established inspection histories. Maharashtra's pharmaceutical manufacturing belt concentrates sterile injectable facility investments.
Switzerland
Specialized contract research organizations concentrate peptide analytical method transfer capabilities. Swissmedic pharmacovigilance obligations shape biosimilar peptide guidance development. The Basel-Lucerne corridor anchors impurity profiling and bioassay validation talent pools.
Carbetocin Acetate Market Competitive Landscape
Listed leaders compete with private specialists across manufacturing scale and regulatory certification depth, producing a tiered structure where consolidated peptide API suppliers anchor supply relationships while mid-scale automation adopters fragment batch economics. Three archetypes dominate: integrated active pharmaceutical ingredient and finished dosage form operators, dedicated peptide synthesis specialists, and emerging continuous manufacturing pilot programs. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with M&A activity concentrating among European contract manufacturers seeking MDR technical documentation capabilities.
Among peptide synthesis specialists, BCN Peptides exemplifies defensible positioning in carbetocin-specific manufacturing expertise. Piramal Pharma Solutions and CordenPharma occupy positions within the integrated API-finished dosage form tier, representing archetypes that compete through multi-geography capabilities and established inspection histories respectively. These anchors illustrate how regulatory certification depth and manufacturing scale separate competitive tiers.
| Leading Market Players |
|---|
| Rochem International Inc. |
| BCN Peptides |
| Suzhou Tianma Pharma Group |
| Ningbo Syntame Biotech |
| Omgene Life Sciences |
| Anhui Anke Biotechnology |
| Piramal Pharma Solutions |
| CordenPharma |
| Shenzhen JYMed Technology |
| Others |
Pricing and Supply Chain Analysis
FDA sterile injectable guidelines and EMA Good Manufacturing Practice standards gate both supplier qualification and price differentiation in carbetocin acetate procurement. Certification depth separates premium peptide API suppliers from commodity oxytocin alternatives, compressing margins for manufacturers lacking established inspection histories while rewarding firms with dedicated sterile facilities.
Pricing Analysis
Certification level (FDA-grade versus CE-marked versus standard GMP) creates the primary spread across supplier tiers. Three-tier pricing structure across premium, standard, and economy levels reflects peptide API traceability depth and sterile facility audit status. Pricing pressure stems from generic oxytocin infusion maintaining formulary presence at substantially lower unit cost in price-sensitive public health systems. Academic medical centers in the United States demonstrate lowest price sensitivity due to value-based obstetric bundle incentives, while India's national health mission procurement shows highest sensitivity to unit economics.
Supply Chain Analysis
China and India anchor solid-phase peptide synthesis capacity for generic API production, while Switzerland and Germany concentrate specialized analytical method development. Protected amino acid derivatives and resins draw from three European chemical suppliers, exposing margins to input concentration. Single-source vulnerability in specialized starting materials elevates cost volatility risk for mid-scale manufacturers. Distribution runs through cold chain logistics networks serving hospital pharmacy and maternity center procurement channels, with temperature excursion risks elevating quality assurance costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generic oxytocin infusion represents a persistent substitution threat that carbetocin acetate incumbents must navigate through clinical outcome differentiation and protocol institutionalization.
For Market Incumbents: Fortify hospital formulary anchoring through prefilled syringe workflow integration that reduces nursing labor and preparation errors. Deepen backward integration into protected amino acid derivative supply to mitigate input volatility from European chemical suppliers. EMA Medical Device Regulation CE marking requirements for combination products threaten competitive access for manufacturers lacking technical documentation capabilities. For New Entrants and Emerging Players: China's NMPA streamlined biosimilar peptide approval pathway offers fastest regulatory access for domestic manufacturers targeting institutional birth expansion. India's national health mission facility-based delivery targets create white-space procurement volume currently dependent on oxytocin. Subcutaneous delivery development programs targeting outpatient postpartum monitoring protocols offer differentiated go-to-market positioning against established IV-centric suppliers. For Investors and Strategic Acquirers: EMA Medical Device Regulation implementation reshapes the acquisition landscape toward manufacturers with proven MDR technical documentation capabilities and sterile injectable facility inspection histories. Acquisition target archetypes include mid-scale European contract manufacturers seeking MDR compliance depth and dedicated peptide synthesis specialists with carbetocin-specific manufacturing expertise. Signal to watch: pharmacovigilance obligation expansions and biosimilar peptide guidance documents that could redefine competitive thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Prefilled Syringe Workflow Integration | Reduces preparation errors in German and United States maternity center protocols. |
| Continuous Manufacturing Scale-Up | Enables flexible production with comparable unit economics to batch specialists. |
| MDR Technical Documentation Investment | Secures CE marking access for combination products in European obstetric networks. |
| Subcutaneous Delivery Development | Extends addressable use cases toward India's outpatient postpartum monitoring expansion. |
| Backward Integration into Starting Materials | Mitigates margin exposure to protected amino acid derivative supply concentration. |
Research Methodology
The analysis maps peptide API manufacturing, sterile injectable formulation, and combination product assembly, each validated through hospital procurement managers, regulatory affairs leads, formulary directors, and contract manufacturing executives. Primary interviews with these stakeholders combined with secondary validation from FDA filings, EMA inspection records, ClinicalTrials.gov protocols, and hospital procurement databases. Bottom-up volume modeling and top-down market sizing triangulate against trade flow data and pharmaceutical customs records.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product type, end user, delivery mode, and packaging format alongside regional regulatory cluster differentiation. CAGRs derive from fitted growth curves applied to hospital birth volume projections and peptide API capacity expansion announcements. Forecast inputs incorporate institutional birth rate targets and sterile injectable facility certification timelines.
Decision-makers should treat outputs as directional under base assumptions of sustained FDA postpartum hemorrhage prevention guideline enforcement and stable peptide starting material supply; material deviation would warrant model refresh. Specific risk factors include EMA inspection backlog extensions, biosimilar peptide guidance revisions, and cold chain infrastructure gaps in secondary hospital networks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Glycerol Fructose and Sodium Chloride Injection Market
Pharmaceuticals
US External Analgesics Market
Pharmaceuticals
Iron Deficiency Injectables Market
Pharmaceuticals
Global Pediatric Electrolyte Solutions Market
Pharmaceuticals
Soft Capsules Drugs CMO Market
Pharmaceuticals
Japan Pharmaceutical 3PL Market
Pharmaceuticals
Metaxalone Market
Pharmaceuticals
AI Drug Development Market
Pharmaceuticals
Sitagliptin Market
Pharmaceuticals
Global Human Rotavirus Vaccine Market
Pharmaceuticals
Penicillin Market
Pharmaceuticals
Drug-Loaded Oral Thin Films Market
Pharmaceuticals
Cryoprecipitated Antihemophilic Factor Market
Pharmaceuticals
Latin America Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Demerol (Meperidine) Market
Pharmaceuticals
Intravenous Pegloticase Market