
 Global Rx to OTC Switches Market | 2026-2036
Global Rx to OTC Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rx to OTC Switches Market Foresight
Botanical extracts and bioadhesive delivery formats are broadening the addressable consumer base for formerly prescription gastrointestinal and respiratory therapies. Pfizer leverages its established consumer health infrastructure to sustain shelf presence across European and North American retail networks. Bayer AG anchors its competitive position through deep specialization in analgesic switches with proven safety profiles spanning multiple regulatory jurisdictions. GlaxoSmithKline plc differentiates via in-house production of nicotine replacement and acid reflux therapies that have cleared OTC pathways in key markets.
Rx to OTC switches represent the regulatory reclassification of pharmaceutical products from prescription-only to non-prescription status, typically following demonstration of adequate safety margins, clear labeling comprehension, and favorable risk-benefit ratios in consumer-use settings. These transitions require reformulation into lower strengths, unit-dose packaging, or modified release profiles to prevent misuse while preserving therapeutic efficacy. Analgesics occupy the largest existing revenue pool within product type segments, reflecting decades of accumulated switch precedent for ibuprofen and naproxen formulations. Digestive aids represent the fastest-expanding category as proton pump inhibitors and H2 antagonists complete successive waves of regulatory approval. The switch driver dimension shows consumer demand and documented safety profile together determining which candidates advance through review queues at FDA and EMA.
FDA's OTC monograph reform and EMA's Article 58 referral procedure together define the dual-track regulatory environment governing switch feasibility across the Atlantic. REACH compliance for packaging materials and ISO 13485 quality management standards further condition manufacturing investments for products seeking non-prescription status. Stakeholders must monitor how pharmacovigilance data from real-world OTC use reshapes regulator willingness to approve additional therapeutic classes for self-selection.
Market Dynamics
FDA's OTC monograph reform is compressing approval timelines for formerly prescription-only ingredients, while pharmacy chains in Germany and the United States simultaneously expand self-care aisles to capture shifting consumer access preferences.
Growth Catalysts
- Regulatory Streamlining:FDA's OTC monograph reform eliminates redundant efficacy reviews for ingredients with established safety profiles, accelerating switch pathways for proton pump inhibitors and H2 antagonists.
- Retailer Infrastructure Investment:Pharmacy chains across Germany and the United States are dedicating expanded floor space to self-care medication sections, creating physical distribution capacity for newly switched products.
- Consumer Self-Diagnosis Tools:Digital symptom-checker applications and pharmacist-led consultation protocols enable confident consumer self-selection for chronic condition management.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:China and India dominate API manufacturing for switched analgesics and digestive aids, creating supply vulnerability for European and North American formulators.
- Packaging Material Compliance Costs:REACH compliance requirements for blister films and child-resistant closures add 15-20% to unit packaging costs compared to prescription-only equivalents.
- Substitution by Generic Prescription:Low-cost generic prescription alternatives in markets with subsidized healthcare systems reduce consumer incentive to switch to higher-priced OTC options.
Strategic Opportunities
- Underpenetrated Latin American Markets:Brazil's ANVISA and Mexico's COFEPRIS maintain conservative switch policies, creating first-mover advantage for companies that establish local pharmacovigilance infrastructure.
- Pharmacist-Enabled Digital Channels:Telehealth-integrated pharmacy platforms in the United States enable remote consultation requirements for Schedule H switches without physical clinic visits.
- Biologic Delivery Convergence:Combination of microneedle patch technology with established small-molecule APIs opens switch pathways for previously injectable therapies in diabetes and osteoporosis.
Industry Challenges
- Post-Market Surveillance Scaling:Companies must build real-world evidence collection systems capable of detecting rare adverse events across millions of unsupervised consumer users.
- Label Comprehension Validation:FDA and EMA require documented evidence that target literacy populations correctly interpret dosing instructions without professional intervention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rx to OTC Switches Market |
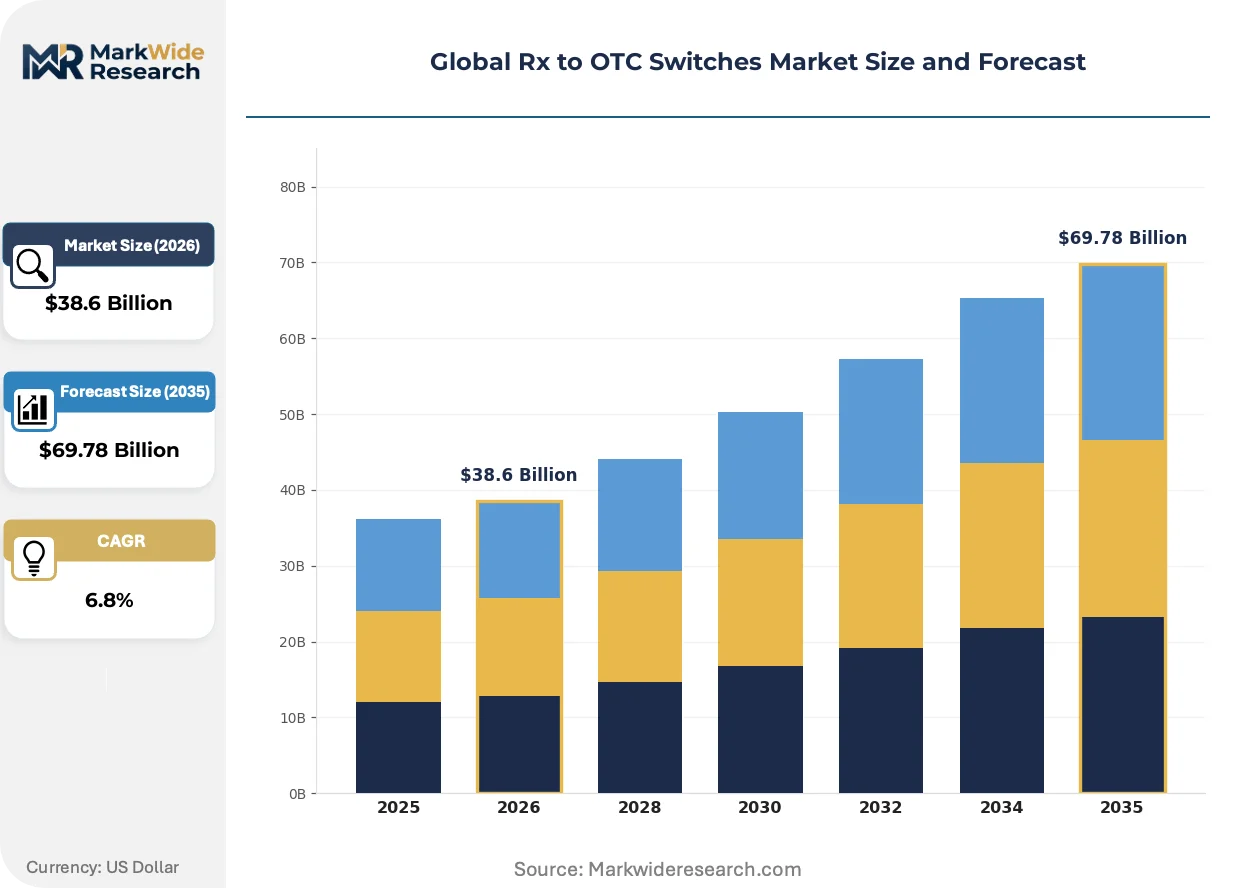
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Antihistamines, Digestive Aids, Cough & Cold Remedies, Dermatologicals Switch Driver: Safety Profile, Cost-effectiveness, Consumer Demand, Regulatory Approval, Market Exclusivity End User: Pharmacies, Retail Chains, Online Health Platforms, Specialty Stores, Healthcare Practitioners Distribution Channel: Brick-and-Mortar Stores, E-commerce, Drug Stores, Supermarkets, Direct-To-Consumer |
| Companies Covered | AstraZeneca, Bayer AG, GlaxoSmithKline plc, Pfizer, Boehringer Ingelheim, Sanofi, Merck KGaA, Novartis, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rx to OTC Switches Market Shifts & Advancements
Delivery technology advances and regulatory digitization are compressing development cycles for switch candidates while reshaping how consumers access self-care therapies.
Microarray patch technology is modularizing the administration of formerly injectable therapies into consumer-friendly transdermal formats. Endocrinology-focused switch candidates in the United States and Japan are adopting microneedle platforms to bypass gastrointestinal degradation. This modularization enables chronic disease therapies to meet OTC criteria by eliminating needle-handling risks and dosing precision requirements.
EMA's Article 58 referral procedure harmonizes switch assessments across EU member states, reducing redundant national reviews. The centralized pathway compresses regulatory timelines for proton pump inhibitors and nicotine replacement therapies seeking simultaneous market access. German and French regulators are piloting mutual recognition protocols that further streamline multi-jurisdiction launches.
Pharmacist consultation models are displacing traditional physician gatekeeping for chronic condition switches. Retail pharmacy chains in the United States now embed diagnostic kiosks and video consultation suites within self-care aisles. This channel evolution concentrates switch conversion in markets where pharmacy scope-of-practice laws permit independent prescribing authority.
Global Rx to OTC Switches Market Segmentation
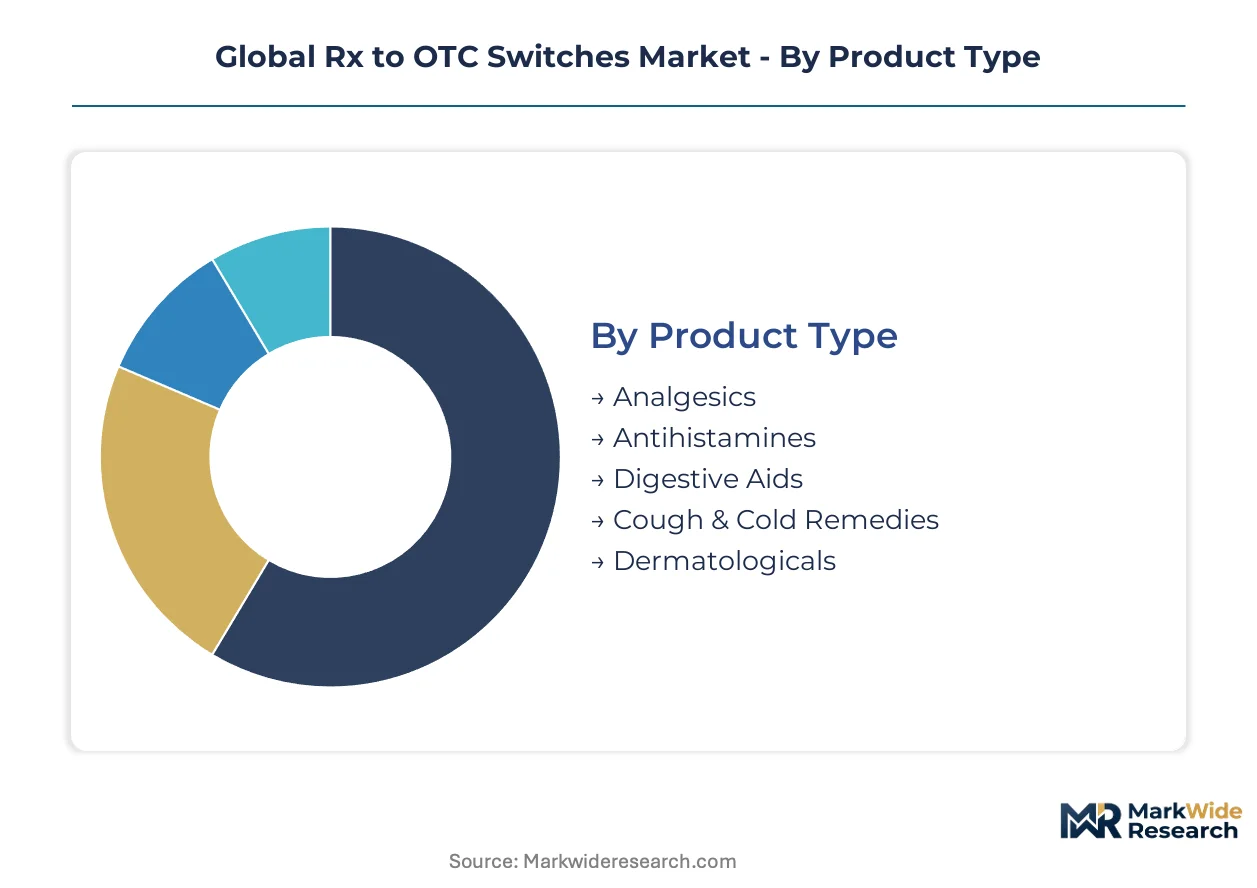
Segmentation in the Rx to OTC switches market reveals how regulatory burden, channel economics, and consumer access patterns concentrate value across distinct product and distribution configurations. Understanding these partitions enables stakeholders to align formulation investments with the specific compliance and commercial pathways that govern switch success.
Product Type:
FDA OTC monograph alignment and EMA Article 58 referral status determine which therapeutic classes bear lighter versus heavier evidentiary burdens for non-prescription approval.
- Analgesics:Ibuprofen and naproxen formulations with decades of post-market surveillance data require minimal supplemental safety studies for switch maintenance. Demand concentrates in United States and German retail channels where pharmacist consultation protocols support consumer self-selection for chronic pain management.
- Digestive Aids:Proton pump inhibitors and H2 antagonists now navigate streamlined FDA monograph pathways following cumulative safety demonstrations. German pharmacy chains and United States drug stores are expanding shelf space for these therapies as self-care preferences shift toward gastrointestinal condition management.
- Antihistamines:Second-generation formulations with established cardiac safety profiles qualify for expedited EMA centralized assessments.
- Cough & Cold Remedies:Decongestant and expectorant switches face heightened scrutiny for misuse potential in adolescent populations.
- Dermatologicals:Topical corticosteroid and antifungal candidates require localized tolerability studies under ISO 13485 quality frameworks.
Analgesics sits at the top of the volume ranking, with Digestive Aids climbing the fastest.
Switch Driver:
Cost tier segmentation distinguishes between switches driven by public health economics versus those propelled by commercial exclusivity strategies.
- Safety Profile:Candidates with documented favorable risk-benefit ratios across millions of patient-years qualify for FDA monograph reform exemptions from redundant efficacy trials. United States and Japanese regulators prioritize these candidates for accelerated review timelines.
- Consumer Demand:Self-diagnosis tool proliferation and pharmacy consultation infrastructure enable confident consumer selection for chronic condition therapies. Retail chains in Germany and the United States are expanding self-care aisles specifically to capture this demand-driven switch category.
- Cost-effectiveness:Healthcare system budget pressures in subsidized markets drive switches that reduce physician visit burdens.
- Regulatory Approval:EMA Article 58 harmonization creates multi-jurisdiction launch economies for candidates with centralized pathway eligibility.
- Market Exclusivity:First-mover switch status provides temporary competitive insulation before generic OTC entry erodes margins.
Safety Profile commands the largest addressable candidate pool, while Consumer Demand is expanding most quickly as digital health tools proliferate.
End User:
Customer type segmentation maps how professional oversight requirements vary across dispensing settings, directly shaping packaging and labeling investments.
- Pharmacies:German and French pharmacy chains embed diagnostic kiosks and video consultation suites that satisfy Schedule H-equivalent switch requirements without mandatory physician visits. These channels concentrate demand for chronic condition therapies requiring pharmacist-enabled patient counseling.
- Retail Chains:United States drug store and supermarket pharmacy counters leverage scope-of-practice laws permitting independent prescribing authority for specific switch categories. Shelf space allocation for self-care sections is expanding across CVS, Walgreens, and Rite Aid networks.
- Online Health Platforms:Telehealth-integrated pharmacy platforms enable remote consultation documentation for switch eligibility verification.
- Specialty Stores:Natural health retailers capture botanical extract switches with positioning outside conventional pharmacy channels.
- Healthcare Practitioners:Physician office dispensing maintains residual volume for complex switches requiring initial professional guidance.
Pharmacies retains the dominant volume position, with Online Health Platforms gaining share fastest as telehealth regulations mature.
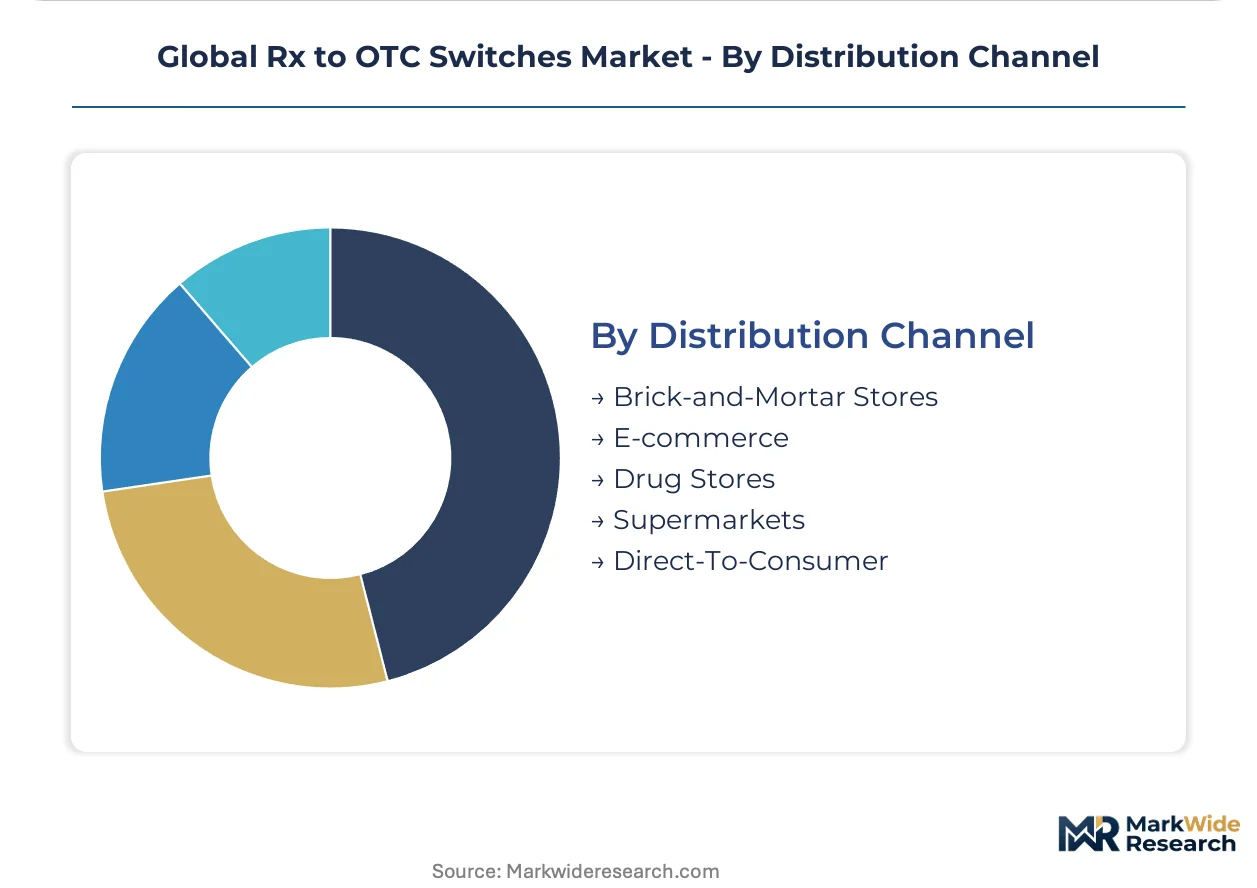
Distribution Channel:
Supply concentration patterns differentiate channels by their API sourcing vulnerability and last-mile fulfillment economics.
- Brick-and-Mortar Stores:Physical retail networks in the United States and Germany carry inventory risk for switched products with seasonal demand fluctuation. These channels require REACH-compliant packaging investments that add unit cost premiums versus prescription-only equivalents.
- E-commerce:Direct-to-consumer platforms bypass pharmacy consultation requirements in jurisdictions with permissive self-selection regulations. Amazon Pharmacy and specialized health platforms are capturing switch volume for maintenance therapies with established safety profiles.
- Drug Stores:Dedicated pharmacy chains concentrate pharmacist expertise for consultation-mandatory switch categories.
- Supermarkets:Mass retail grocery pharmacies compete on convenience positioning for low-complexity analgesic and antihistamine switches.
- Direct-To-Consumer:Manufacturer-owned channels capture margin premiums for subscription-based chronic therapy replenishment.
Brick-and-Mortar Stores holds the volume lead, with E-commerce showing the steepest expansion trajectory as regulatory frameworks adapt to remote dispensing models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr metropolitan region anchors pharmaceutical distribution infrastructure for switched medications across Western Europe. Pharmacy chains in Düsseldorf and Cologne operate consultation-enabled self-care sections that satisfy EMA Article 58 requirements. German regulators pilot mutual recognition protocols with French counterparts to compress multi-jurisdiction launch timelines.
United States
FDA's OTC monograph reform drives switch volume through streamlined efficacy exemptions for proton pump inhibitors and H2 antagonists. Pharmacy scope-of-practice laws in California and New York permit independent prescribing authority for specific switch categories. CVS and Walgreens embed diagnostic kiosks in Chicago and Houston stores to capture consultation-mandatory switch demand.
Germany
Pharmacy chains expand self-care floor space in Munich and Frankfurt to accommodate digestive aid switches with established safety profiles. EMA Article 58 referral procedures enable centralized assessments that reduce redundant national reviews. Bavarian and North Rhine-Westphalian regulators coordinate pharmacovigilance data sharing for real-world OTC surveillance.
Japan
PMDA maintains conservative switch policies for analgesic and respiratory therapies despite consumer self-diagnosis tool proliferation. METI guidelines on telehealth-integrated pharmacy platforms enable remote consultation documentation for chronic condition switches. Tokyo and Osaka pharmacy networks pilot microneedle patch distribution for formerly injectable diabetes therapies.
United Kingdom
MHRA post-Brexit regulatory autonomy permits accelerated switch pathways for ibuprofen and naproxen formulations with decades of surveillance data. London and Manchester retail pharmacy chains leverage diagnostic suite investments to satisfy Schedule H-equivalent consultation requirements. NHS budget pressures drive cost-effectiveness evaluations for physician visit reduction through self-care switches.
Brazil
ANVISA maintains conservative switch policies that create first-mover advantage for companies establishing local pharmacovigilance infrastructure. São Paulo and Rio de Janeiro pharmacy networks expand self-care sections despite regulatory hesitation on proton pump inhibitor reclassification. Consumer demand for gastrointestinal condition management outpaces regulatory approval velocity.
Global Rx to OTC Switches Market Competitive Landscape
Portfolio diversification dominates the current landscape as established pharmaceutical manufacturers reallocate prescription assets toward consumer health divisions. The market structure concentrates around multinational conglomerates with existing OTC infrastructure and specialized regional players with regulatory navigation expertise. Three archetypes prevail: legacy pharmaceutical giants with consumer health spin-offs, mid-cap specialists in analgesic or digestive therapeutic classes, and emerging telehealth-integrated pharmacy platforms. M&A activity and strategic licensing agreements represent the dominant competitive vectors as companies acquire switch-ready assets and local distribution capabilities.
Within the legacy pharmaceutical tier, Bayer AG and GlaxoSmithKline plc exemplify archetypes of deep therapeutic specialization and in-house production integration respectively. Pfizer occupies a position bridging prescription originator strength with consumer health channel leverage across North American and European retail networks. These three companies represent distinct strategic postures: Bayer AG through analgesic switch concentration, GlaxoSmithKline plc through nicotine replacement and acid reflux therapy verticalization, and Pfizer through infrastructure-scale shelf presence maintenance.
| Leading Market Players |
|---|
| AstraZeneca |
| Bayer AG |
| GlaxoSmithKline plc |
| Pfizer |
| Boehringer Ingelheim |
| Sanofi |
| Merck KGaA |
| Novartis |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between FDA monograph-aligned formulations and legacy prescription-only equivalents splits both pricing power and sourcing complexity across the Rx to OTC transition. This bifurcation concentrates margin capture in manufacturers with pre-validated quality management systems while forcing price-responsive competitors toward API spot markets.
Pricing Analysis
Input-cost pass-through from API and REACH-compliant packaging materials shapes pricing stratification across premium, standard, and economy tiers. Brand premiums attach to established safety profiles with decades of pharmacovigilance data, while price erosion runs through commodity analgesic switches facing generic prescription substitution. Healthcare system reimbursement policies in Germany and the United States create divergent buyer sensitivity, with uninsured consumers most responsive to unit-cost differentials.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and China's NMPA localization requirements are reshaping API sourcing patterns for Western formulators. Active pharmaceutical ingredient production draws from India, China, and selected European facilities, with ibuprofen and naproxen precursors particularly concentrated. Single-source vulnerability in microneedle substrate supply creates exposure for transdermal switch candidates. Distribution runs through pharmacy chain central buying offices in the United States and Germany, with e-commerce platforms capturing direct-to-consumer replenishment volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
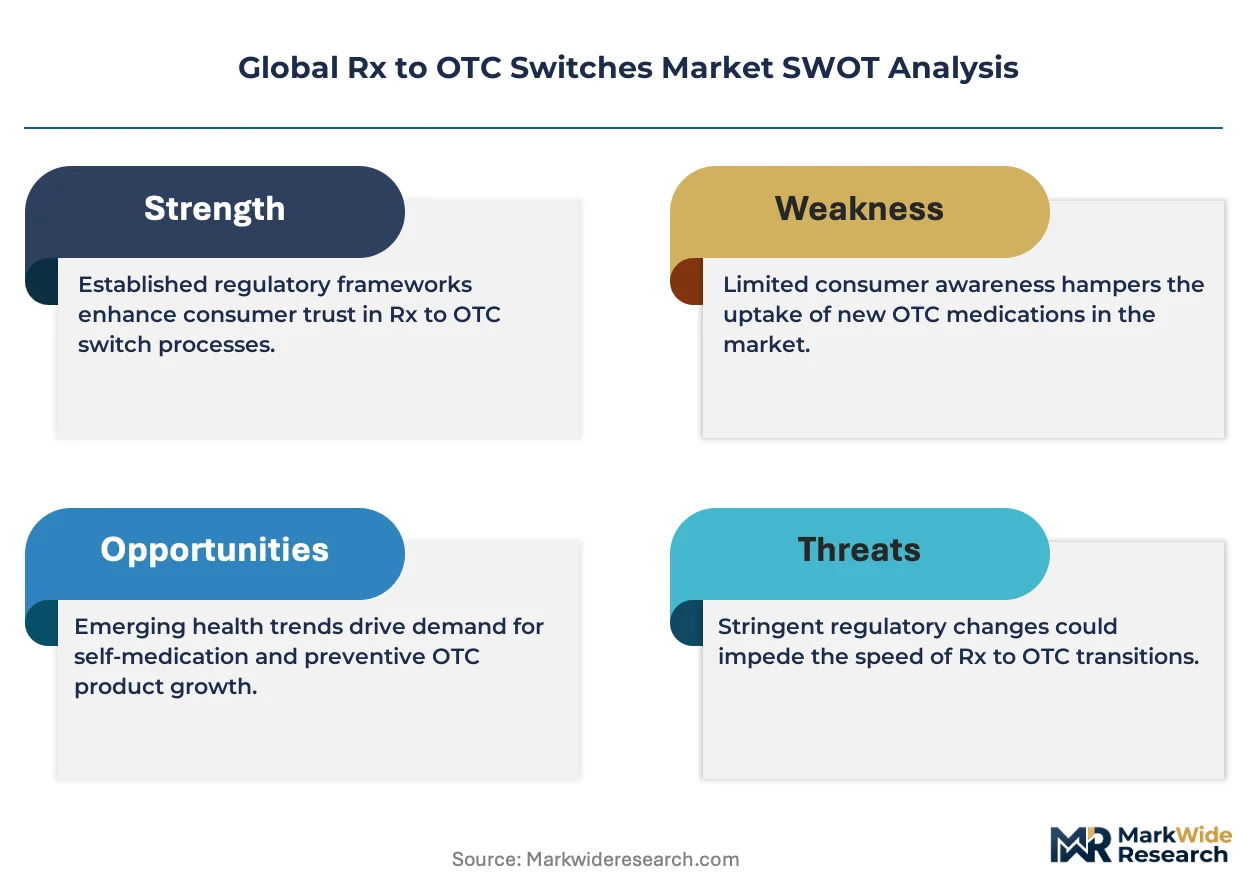
The Rx to OTC switches market functions as a stable compounder anchored by irreversible regulatory streamlining that perpetually expands the eligible candidate pool. This structural tailwind supports predictable value accretion for positioned players.
For Market Incumbents: Deepen backward integration into API supply through captive manufacturing or long-term offtake agreements with Indian and Chinese producers to defend against concentration risk. Fortify pharmacist consultation infrastructure in CVS, Walgreens, and German pharmacy networks to maintain channel control against telehealth-integrated platforms eroding physical foot traffic. For New Entrants and Emerging Players: Telehealth-integrated pharmacy platforms in the United States offer the lowest barrier to consultation-mandatory switch categories without brick-and-mortar capital deployment. Target Brazil's gastrointestinal condition management segment where ANVISA hesitation has created demand-supply asymmetry, and pursue microneedle patch partnerships with Japanese PMDA-registered manufacturers for diabetes therapy switches. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing regulatory navigation expertise in conservative jurisdictions like Brazil and Japan. The five-to-ten year viability window favors acquisition targets with established pharmacovigilance infrastructure rather than pure pipeline assets. Watch EMA-FDA mutual recognition protocol expansion as the signal for accelerated multi-jurisdiction launch economies.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA Article 58 centralized assessments compress redundant national reviews across Germany and France. |
| Backward Integration | Captive API manufacturing insulates formulators from India-China supply concentration risk. |
| Pharmacist Consultation Infrastructure | Diagnostic kiosk deployment in CVS and Walgreens satisfies Schedule H-equivalent switch requirements. |
| Telehealth Platform Integration | Remote consultation documentation enables switch eligibility verification without physical clinic visits. |
| Microneedle Delivery Development | Transdermal modularization opens OTC pathways for formerly injectable diabetes therapies. |
Research Methodology
Multiple input streams — regulatory affairs directors at multinational pharmaceutical manufacturers, pharmacy chain formulary managers, and API procurement specialists — were reconciled against FDA OTC monograph filings, EMA Article 58 referral documentation, and national pharmacovigilance databases. Bottom-up volume estimates from country-level switch approvals were cross-validated with top-down spending projections from healthcare system budget disclosures.
Historical switch velocity across analgesic, digestive aid, and respiratory therapeutic classes was cross-referenced against expert panel assessments of pipeline candidate readiness. The analytical framework modeled product type, switch driver, end-user channel, and regional regulatory cluster dimensions across the projection horizon. CAGRs were derived from segmented growth rate reconciliation with macroeconomic healthcare expenditure trends and documented safety profile maturation timelines.
The model assumes a particular technology adoption path for microneedle patch platforms; alternative pathways for transdermal biologic delivery would alter the outlook for injectable-to-OTC conversion rates. Forecasts reflect assumptions regarding EMA-FDA harmonization progress and REACH compliance cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
South Korea Diabetes Drugs Market
Pharmaceuticals
Dipeptidyl Peptidase-4 (DPP-4) Inhibitors Market
Pharmaceuticals
MRSA Antibiotic Preparations Market
Pharmaceuticals
Controlled Substance Market
Pharmaceuticals
Global Compounding Pharmacy Market
Pharmaceuticals
Global Atherosclerosis Drugs Market
Pharmaceuticals
Global Ebola Virus Vaccine Market
Pharmaceuticals
Intranasal Corticosteroids Market
Pharmaceuticals
Global Topical Analgesic Market
Pharmaceuticals
High Potency API Contract Manufacturing Market
Pharmaceuticals
Albinism Drugs Market
Pharmaceuticals
US External Analgesics Market
Pharmaceuticals
Middle-East and Africa Meglitinide Market
Pharmaceuticals
SGLT2 Inhibitors Market
Pharmaceuticals
Global Anti-Suicide Drugs Market
Pharmaceuticals
Parenteral Drugs Market