
 Angiopoietin Inhibitors Therapeutic Market | 2026-2036
Angiopoietin Inhibitors Therapeutic Market Size, Share, and Industry Trends Forecast 2026-2036
Angiopoietin Inhibitors Therapeutic Market Outlook
Project finance structures for late-stage biologics development is rewriting competitive dynamics in angiopoietin inhibitor development. Amgen leverages its established oncology infrastructure to advance anti-angiogenic programs through commercial-scale manufacturing. Regeneron Pharmaceuticals anchors its position through proprietary VelocImmune platform technology that accelerates antibody discovery timelines. Boehringer Ingelheim specializes in fibrotic disease applications, differentiating its pipeline from oncology-heavy competitors.
Angiopoietin inhibitors are biologic or small-molecule agents that block signaling through Tie2 receptors, disrupting pathological vascular permeability and aberrant angiogenesis in diseased tissues. These therapeutics function by neutralizing angiopoietin-1 and angiopoietin-2 ligands, with monoclonal antibodies commanding the largest current revenue share due to validated manufacturing processes and infusion-center reimbursement infrastructure. Cancer treatment applications lead absolute spending, though diabetic retinopathy represents the fastest-expanding indication as intravitreal delivery formats gain regulatory traction. Hospitals dominate end-user volume, while homecare settings emerge as a structural growth vector for subcutaneous formulations.
FDA breakthrough therapy designation and EMA PRIME eligibility criteria shape clinical investment priorities and timeline expectations for developers in this space. The EU AI Act and FDA's evolving guidance on real-world evidence integration are altering how post-market surveillance data supports label expansion. Stakeholders must monitor how CMS national coverage determination processes and NICE technology appraisals reconcile premium pricing for combination angiopoietin-VEGF therapies against budget impact thresholds.
Market Dynamics
Accelerated FDA breakthrough therapy designations and EMA PRIME eligibility are compressing development timelines for angiopoietin inhibitors, forcing developers to front-load manufacturing scale-up and commercial infrastructure before Phase III readouts. This temporal compression is restructuring capital deployment across the competitive landscape.
Growth Catalysts
- Intravitreal delivery formats:Sustained-release depot formulations for diabetic retinopathy are expanding addressable patient pools beyond oncology centers into ophthalmology clinics. This delivery innovation is capturing treatment-naive populations previously managed by laser photocoagulation.
- CMS national coverage determination processes:Favorable reimbursement rulings for combination angiopoietin-VEGF therapies in the United States are accelerating hospital formulary adoption. Academic medical centers are prioritizing these agents in value-based care contracts.
- Real-world evidence integration:FDA guidance on post-market surveillance data is enabling label expansion pathways that bypass traditional randomized controlled trials. Developers are leveraging electronic health record networks to supplement clinical trial datasets.
Market Restraints
- Biologics manufacturing concentration:Contract development and manufacturing organizations in Switzerland and Singapore control critical fill-finish capacity for monoclonal antibodies. Supply bottlenecks at these nodes create program delays for mid-cap developers lacking captive production.
- Subcutaneous formulation stability:Protein aggregation during shelf storage limits homecare distribution for angiopoietin inhibitors. Cold chain requirements constrain penetration into rural and emerging markets.
- EU AI Act compliance burdens:Machine learning algorithms used for patient stratification in clinical trials face heightened documentation requirements. Algorithmic transparency mandates are extending trial startup timelines.
Strategic Opportunities
- Fibrotic disease applications:Idiopathic pulmonary fibrosis and non-alcoholic steatohepatitis represent indication expansions with limited competing anti-angiogenic penetration. Boehringer Ingelheim's specialized positioning demonstrates pathway viability.
- Homecare subcutaneous administration:Self-injection devices for maintenance dosing could shift site-of-care economics away from infusion centers. Germany's ambulatory care reimbursement framework provides a testbed for this channel migration.
- China NMPA conditional approval pathways:Accelerated review for therapies addressing unmet medical needs in diabetic retinopathy is attracting multinational trial investment. Domestic patient recruitment density supports faster enrollment than Western sites.
Industry Challenges
- Combination therapy IP complexity:Patent thickets surrounding angiopoietin-VEGF co-formulations are generating licensing disputes. Freedom-to-operate analyses now consume 18-24 months before program initiation.
- Tie2 biomarker assay standardization:Discordant readouts between centralized and point-of-care testing platforms are complicating patient selection. Clinical laboratories require harmonization protocols that delay trial execution.
- Legacy EHR integration:Real-world evidence collection demands interoperability with hospital information systems built on incompatible architectures. Data extraction pipelines require bespoke engineering at each site.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Angiopoietin Inhibitors Therapeutic Market |
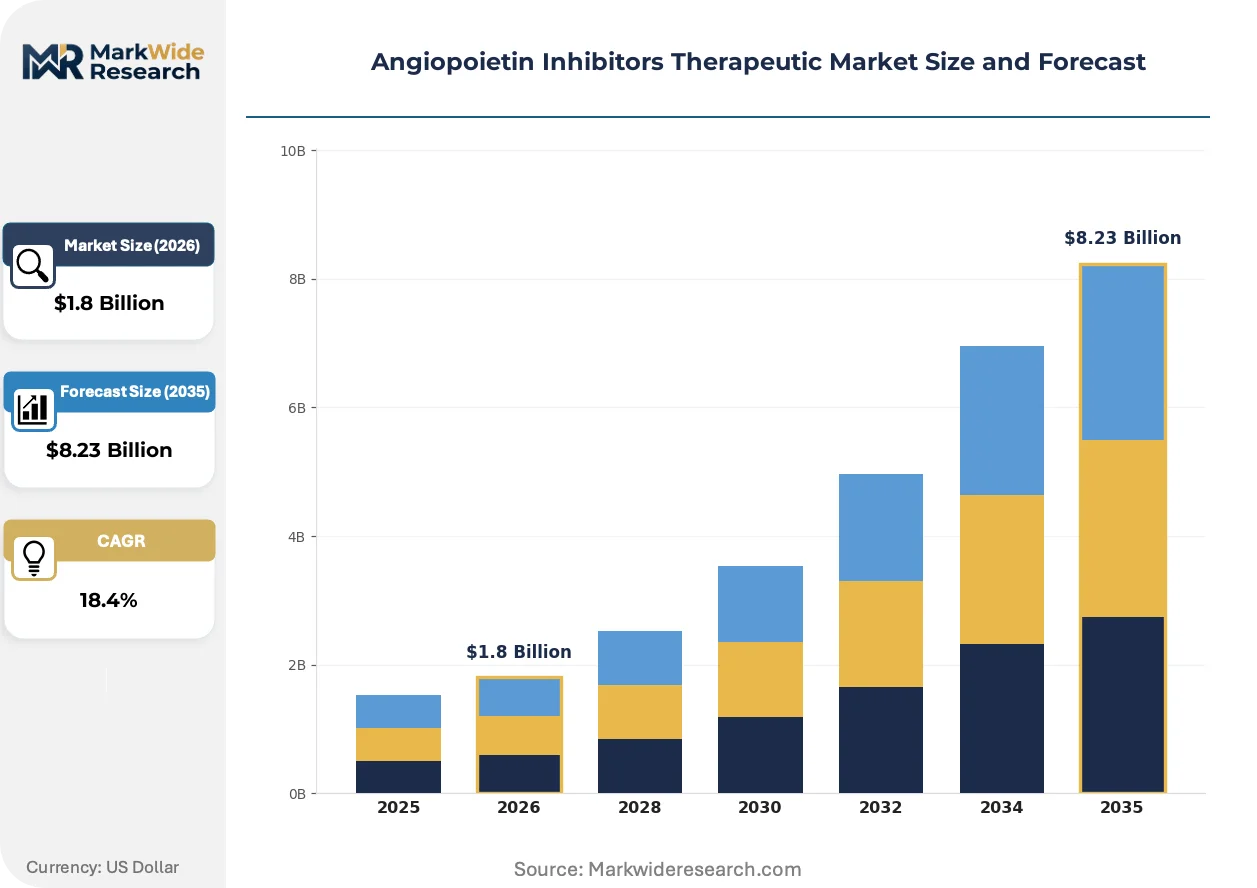
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Small Molecule Inhibitors, Peptide-Based Therapies, Combination Therapies Application: Cancer Treatment, Diabetic Retinopathy, Cardiovascular Disorders, Inflammatory Diseases End User: Hospitals, Clinics, Research Laboratories, Homecare Settings Delivery Mode: Intravenous Infusion, Subcutaneous Injection, Oral Administration, Topical Application |
| Companies Covered | Amgen, Bayer, Regeneron Pharmaceuticals, Pfizer, AstraZeneca, Boehringer Ingelheim, Novartis, Roche, Innovent Biologics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Angiopoietin Inhibitors Therapeutic Market Strategic Shifts
Bioconjugation chemistry and bispecific antibody engineering are collapsing traditional boundaries between oncology and ophthalmology development programs. These platform advances are enabling indication-spanning therapeutic architectures that reshape portfolio economics.
Bispecific antibodies targeting both angiopoietin-2 and VEGF-A simultaneously are collapsing the historical sequencing of anti-angiogenic therapies. Oncology departments at academic medical centers in the United States and Germany are adopting these agents as first-line standards in renal cell carcinoma and hepatocellular carcinoma. This adoption pattern is compressing revenue timelines for sequential monotherapy franchises.
EMA's evolving guidance on real-world evidence integration is altering post-market surveillance obligations for anti-angiogenic therapies. Developers must now prospectively design registries capable of supporting label expansion submissions. Oncology indications face the steepest compliance ramps as survival endpoints demand extended follow-up protocols.
Hospital procurement committees are consolidating vendor relationships for biologic oncology agents around integrated supply and data contracts. Infusion centers in the United States are negotiating outcomes-based arrangements that tie reimbursement to progression-free survival metrics. This contracting evolution is most visible in Medicare Advantage networks where risk-bearing entities control formulary placement.
Angiopoietin Inhibitors Therapeutic Market Segmentation
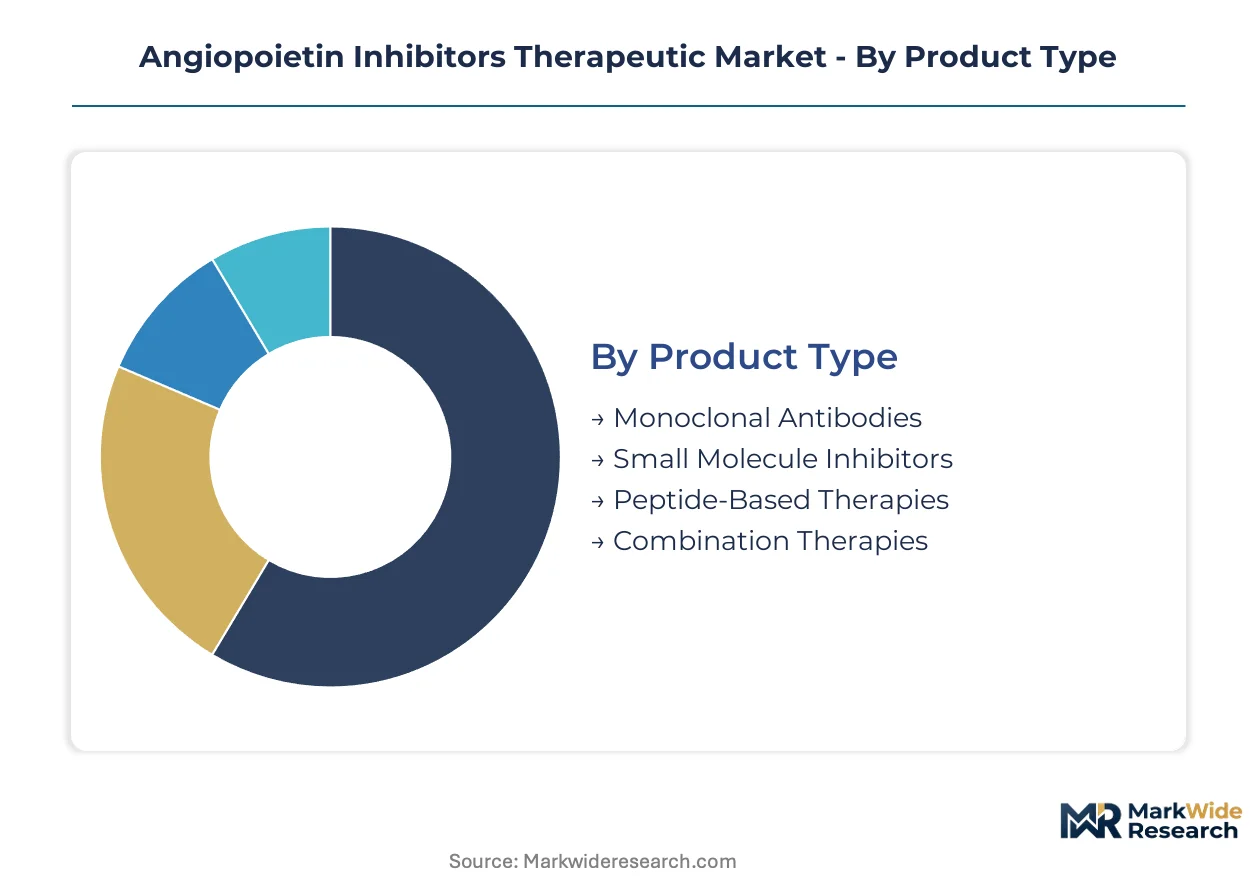
Angiopoietin inhibitor developers must align platform investments with distinct technical and commercial requirements across product architectures, clinical settings, and administration formats. Segmentation clarity determines whether pipeline candidates target hospital-based infusion economics or ambulatory self-administration models.
Product Type:
Mature biologic platforms dominate current revenue, while emerging modalities reshape competitive entry barriers and manufacturing scale requirements.
- Monoclonal Antibodies:These recombinant protein therapeutics bind angiopoietin-1 and angiopoietin-2 with high specificity, leveraging established CHO cell production infrastructure. Demand concentrates in United States academic medical centers where infusion-center reimbursement codes support premium pricing for oncology indications. Cold chain requirements and validated fill-finish capacity at Swiss CDMOs constrain supply expansion for mid-cap developers.
- Small Molecule Inhibitors:Oral bioavailable compounds targeting Tie2 receptor kinase domains enable outpatient prescribing without infusion logistics. Germany's ambulatory care reimbursement framework favors these agents for maintenance therapy in fibrotic diseases, though hepatotoxicity monitoring requirements limit label breadth compared to biologics.
- Peptide-Based Therapies:Engineered peptide fragments disrupting angiopoietin-Tie2 interfaces offer tissue-specific targeting with reduced systemic exposure.
- Combination Therapies:Co-formulated angiopoietin-VEGF inhibitors compress treatment sequencing in oncology protocols.
Monoclonal antibodies handle the majority of throughput; small molecule inhibitors are expanding most quickly on share.
Application:
Oncology applications anchor near-term revenue, while ophthalmology and fibrotic indications redefine addressable patient populations and site-of-care economics.
- Cancer Treatment:Anti-angiogenic protocols in renal cell carcinoma and hepatocellular carcinoma utilize angiopoietin inhibitors to normalize tumor vasculature and enhance chemotherapy penetration. United States hospital procurement committees prioritize these agents in Medicare Advantage risk contracts where progression-free survival metrics determine formulary placement.
- Diabetic Retinopathy:Intravitreal depot formulations targeting pathological retinal neovascularization capture treatment-naive populations from laser photocoagulation. China's NMPA conditional approval pathways accelerate trial enrollment for these therapies, leveraging domestic patient density in tier-one cities.
- Cardiovascular Disorders:Heart failure with preserved ejection fraction represents an exploratory indication with unmet need.
- Inflammatory Diseases:Rheumatoid arthritis and inflammatory bowel disease applications remain preclinical for most developers.
Cancer treatment commands the largest absolute spending; diabetic retinopathy shows the steepest expansion trajectory.
End User:
Institutional settings capture acute administration, while homecare migration depends on formulation stability and reimbursement parity.
- Hospitals:Inpatient oncology units and infusion centers manage acute angiopoietin inhibitor administration with nursing supervision and adverse event monitoring. United States academic medical centers anchor volume through value-based care contracts integrating drug cost with episode reimbursement.
- Homecare Settings:Subcutaneous self-injection devices for maintenance dosing shift site-of-care economics away from facility fees. Germany's disease management program reimbursement supports this channel, though protein aggregation during shelf storage limits rural distribution.
- Clinics:Ophthalmology ambulatory surgery centers handle intravitreal injections for retinal indications.
- Research Laboratories:Academic and contract research organizations utilize reference compounds for biomarker validation and mechanism studies.
Hospitals process the dominant patient volume; homecare settings are climbing the fastest on share.
Delivery Mode:
Route selection determines regulatory pathway complexity, cold chain infrastructure, and competitive differentiation through patient convenience.
- Intravenous Infusion:Hospital-based administration of monoclonal antibodies ensures therapeutic exposure with immediate adverse event management. United States CMS national coverage determinations for combination angiopoietin-VEGF therapies reinforce hospital formulary prioritization of this delivery format.
- Subcutaneous Injection:Prefilled syringes and auto-injector devices enable outpatient maintenance without infusion center dependency. EMA guidance on real-world evidence collection supports label expansion for subcutaneous formulations using registry data rather than controlled trials.
- Oral Administration:Small molecule inhibitors targeting Tie2 kinase domains bypass parenteral logistics entirely.
- Topical Application:Ophthalmic drops and dermal formulations remain developmental for angiopoietin pathway modulation.
Intravenous infusion manages the majority of dose throughput; subcutaneous injection is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough therapy designations and CMS national coverage determinations in the United States anchor reimbursement certainty for combination angiopoietin-VEGF therapies. China's NMPA conditional approval pathways compress trial timelines for diabetic retinopathy indications. Germany's disease management program reimbursement supports ambulatory care migration for subcutaneous formulations.
United States
Academic medical centers in Boston and New York Metro anchor Phase III trial enrollment for renal cell carcinoma protocols. Medicare Advantage risk contracts tie formulary placement to progression-free survival metrics, reshaping hospital procurement committee priorities. The FDA's real-world evidence integration guidance enables label expansion using electronic health record networks rather than controlled trials.
China
Tier-one cities concentrate treatment-naive diabetic retinopathy populations previously managed by laser photocoagulation. NMPA conditional approval for therapies addressing unmet medical needs accelerates multinational trial investment beyond Western enrollment rates. Shanghai and Beijing host the densest patient recruitment networks for intravitreal depot formulation studies.
Germany
Baden-Württemberg and Bavaria anchor outpatient maintenance therapy demand through disease management program reimbursement frameworks. The EMA PRIME eligibility criteria shape developer timeline expectations for anti-angiogenic therapies seeking accelerated assessment. Munich and Heidelberg academic centers prioritize value-based care contracts integrating drug cost with episode reimbursement.
Switzerland
Contract development and manufacturing organizations in Basel and Zurich control critical fill-finish capacity for monoclonal antibodies. Swissmedic regulatory alignment with EMA procedures streamlines parallel submission pathways for angiopoietin inhibitors. The country's biologics manufacturing concentration creates supply bottlenecks that delay programs for developers lacking captive production.
United Kingdom
NICE technology appraisals reconcile premium pricing for combination therapies against budget impact thresholds in England. London and Cambridge academic medical centers expand adoption of anti-angiogenic agents through integrated supply and data contracts. The MHRA's post-Brexit regulatory autonomy enables tailored approval pathways distinct from EMA centralized procedures.
Angiopoietin Inhibitors Therapeutic Market Competitive Environment
On the supply side, the industry is consolidating around platform-anchored biopharmaceuticals with validated manufacturing infrastructure and established oncology commercial networks. Large-cap developers with captive fill-finish capacity command procurement committee relationships that mid-cap entrants cannot replicate. Two strategic archetypes dominate: integrated biologics manufacturers leveraging VelocImmune-style antibody discovery platforms, and fibrotic disease specialists differentiating through non-oncology indication focus. Competitive moves center on manufacturing scale-up ahead of Phase III readouts and outcomes-based contracting with Medicare Advantage networks.
Within the integrated biologics tier, Amgen and Regeneron Pharmaceuticals occupy positions defined by commercial-scale manufacturing infrastructure and proprietary discovery platforms. Boehringer Ingelheim exemplifies the fibrotic disease specialist archetype, anchoring its competitive position through indication differentiation away from oncology-heavy peer portfolios. These three entities represent the structural fault lines reshaping capital deployment across late-stage development programs.
| Leading Market Players |
|---|
| Amgen |
| Bayer |
| Regeneron Pharmaceuticals |
| Pfizer |
| AstraZeneca |
| Boehringer Ingelheim |
| Novartis |
| Roche |
| Innovent Biologics |
| Others |
Value Chain & Pricing Dynamics
Basel and Zurich CDMO clusters control critical fill-finish capacity for monoclonal antibody production, concentrating upstream supply power and enabling premium pricing for validated manufacturing slots. This geographic concentration creates asymmetric leverage where developers lacking captive production face extended lead times and cost premiums that compress downstream margin structures.
Pricing Analysis
Certification level creates the primary spread between FDA-breakthrough designated therapies and standard-of-care agents. Three-tier pricing structure across premium, standard, and economy levels reflects EMA PRIME eligibility, CMS national coverage determination status, and manufacturing scale. Cost compression in mid-cap developer tiers is intensifying because Swiss fill-finish bottlenecks force expedited slot premiums. Academic medical centers in the United States exhibit lowest price sensitivity due to value-based care contract structures, while emerging market hospitals face acute budget constraints.
Supply Chain Analysis
Extended payment terms from supply-chain finance facilities anchor working capital structures for CDMO-dependent developers. Manufacturing concentrates in Switzerland, Singapore, and the United States, with fill-finish capacity drawing from specialized CHO cell production infrastructure. Critical inputs include recombinant protein expression systems, single-use bioreactor assemblies, and validated aseptic filling lines. Single-source vulnerability at Swiss nodes creates program delay risks for developers without multi-site qualification. Distribution runs through hospital procurement committees and specialty pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indication fragmentation across oncology, ophthalmology, and fibrotic disease creates multiple entry niches for specialized positioning. The shift toward site-of-care migration and homecare administration splits demand into distinct technical and reimbursement segments.
For Market Incumbents: Insulate manufacturing scale advantages through captive fill-finish capacity expansion in Basel-region facilities before Phase III readouts compress timeline options. Secure outcomes-based contracts with Medicare Advantage networks to lock formulary placement against biosimilar entrants. Prioritize real-world evidence registry design that supports label expansion without controlled trial investment. For New Entrants and Emerging Players: Build out fibrotic disease applications in idiopathic pulmonary fibrosis and non-alcoholic steatohepatitis where anti-angiogenic penetration remains limited and Boehringer Ingelheim's specialized positioning demonstrates pathway viability. Target China's NMPA conditional approval pathways for diabetic retinopathy indications leveraging domestic patient recruitment density. Pursue licensing arrangements for Tie2 biomarker assay standardization to differentiate patient selection capabilities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-anchored biopharmaceuticals with validated manufacturing infrastructure over asset-specific plays. Long-term viability across the analysis window rests on CDMO relationship depth and regulatory pathway momentum rather than single-asset approval events. Acquisition target archetype: mid-cap developers with EMA PRIME eligibility and Swiss manufacturing partnerships. Monitor CMS national coverage determination timelines as inflection indicators for reimbursement certainty.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerated FDA breakthrough designations compress development timelines and front-load capital deployment requirements. |
| Manufacturing Scale-Up | Swiss CDMO slot securing ahead of Phase III readouts prevents supply bottlenecks for monoclonal antibody programs. |
| Regulatory Approval Pathway | EMA PRIME eligibility and NMPA conditional approval frameworks reshape competitive entry sequencing across geographies. |
| Licensing Agreement | Combination therapy IP arrangements resolve patent thickets surrounding angiopoietin-VEGF co-formulation freedom-to-operate. |
| Pipeline Diversification | Fibrotic disease indication expansion reduces oncology concentration risk and opens ambulatory reimbursement pathways. |
Study Parameters
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation. FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases anchored quantitative segmentation. Bottom-up patient population modeling and top-down therapeutic class expenditure analysis provided triangulation checks.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions included treatment line, dosage form, administration route, and regional regulatory cluster. CAGRs were derived from enrollment velocity in Phase III protocols and historical approval-to-peak curves for anti-angiogenic agents. Forecast inputs incorporated CMS national coverage determination timelines and NMPA conditional approval conversion rates.
The forecast holds incumbent behavior within observed patterns; aggressive manufacturing capacity expansion by platform-anchored biopharmaceuticals would shift competitive dynamics. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Large Molecule Contract Development and Manufacturing Organization Market
Pharmaceuticals
Global HPMC Capsules Market
Pharmaceuticals
Germany Pneumococcal Vaccines Market
Pharmaceuticals
Contraceptive Drugs Market
Pharmaceuticals
Global Angina Pectoris Drugs Market
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market
Pharmaceuticals
Parenteral Drugs Market
Pharmaceuticals
Palonosetron Hydrochloride Market
Pharmaceuticals
MRSA Antibiotic Preparations Market
Pharmaceuticals
Global Osteoporosis Drugs Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
PDE Inhibitors Market
Pharmaceuticals
Fertility Drug and Surgery Market
Pharmaceuticals
Medicinal Fungi Market
Pharmaceuticals
Europe Diabetes Drugs Market
Pharmaceuticals
Compound Diclofenac Sodium and Chlorphenamine Maleate Tablets Market