
 Global Lidocaine Market | 2026-2036
Global Lidocaine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lidocaine Market Foresight
Aftermarket service revenue around lidocaine delivery systems is fragmenting as generic manufacturers compete on formulation technology rather than molecule exclusivity. Pfizer Inc. leverages its injectable infrastructure to sustain hospital channel dominance in North America. Teva Pharmaceutical Industries Ltd. anchors its position through vertical integration into active pharmaceutical ingredient supply. Fresenius Kabi AG differentiates via specialized parenteral production lines that serve critical-care settings.
Lidocaine is a synthetic amide-type local anesthetic with a molecular weight of 234.34 g/mol, functioning through reversible sodium channel blockade in neuronal membranes to inhibit nerve impulse transmission. Manufacturers produce it via multi-step organic synthesis starting from 2,6-xylidine, with final formulations requiring sterile processing for injectable grades and precise pH buffering between 6.5 and 7.5 for stability. Injection forms command the largest volume share due to their indispensability in surgical and dental settings, while patch and transdermal segments attract premium positioning for chronic pain management applications. Liposomal and extended-release technologies concentrate margin pools by extending duration of action and reducing dosing frequency.
The FDA enforces stringent current good manufacturing practice requirements for lidocaine APIs and finished dosage forms, while the EMA's REACH framework governs chemical safety assessments for European production facilities. Japan's PMDA maintains distinct pharmacopoeial standards for local anesthetic purity that exceed baseline international requirements, creating compliance-driven segmentation between export markets. Stakeholders must monitor evolving regulatory convergence between the FDA and EMA on nitrosamine impurity thresholds, as these standards will determine which manufacturers retain multi-region supply qualifications.
Market Dynamics
Extended-release and liposomal formulation technologies are fragmenting competitive advantage away from raw API scale toward delivery-system sophistication, forcing manufacturers to rebuild margin structures around patent-protected formulation platforms rather than commodity chemistry.
Growth Catalysts
- Ambulatory surgical expansion:Outpatient procedure volumes in the United States and Germany are accelerating lidocaine procurement for minimally invasive interventions. Same-day discharge protocols favor local anesthetic protocols over general anesthesia.
- REACH chemical safety alignment:The EMA's framework for nitrosamine impurity monitoring is creating compliance-driven demand for certified high-purity API batches. Manufacturers with validated analytical capabilities capture hospital formulary slots.
- Liposomal encapsulation:This delivery technology extends duration of action from hours to days, opening postoperative pain management applications previously served by opioid alternatives.
Market Restraints
- 2,6-xylidine feedstock volatility:Petrochemical-derived starting material costs fluctuate with crude oil benchmarks, compressing margin predictability for non-integrated producers.
- API supply concentration:A limited set of Chinese and Indian manufacturers dominate bulk lidocaine base production, creating single-source vulnerability for formulated dose producers.
- Substitution by bupivacaine and ropivacaine:Longer-acting amide anesthetics displace lidocaine in certain orthopedic and obstetric applications where extended blockade is clinically preferred.
Strategic Opportunities
- Brazilian regulatory upgrading:ANVISA's tightening purity standards for imported APIs create first-mover advantage for manufacturers willing to pre-certify against advanced pharmacopoeial specifications.
- Transdermal patch channel expansion:Direct-to-pharmacy distribution models for lidocaine 4% and 5% patches bypass traditional wholesale markups in fragmented retail pharmacy markets.
- Combination with capsaicin or menthol:Convergence of local anesthetic and counterirritant mechanisms enables OTC positioning for chronic neuropathic pain segments previously restricted to prescription channels.
Industry Challenges
- Sterile manufacturing qualification timelines:FDA pre-approval inspection backlogs for aseptic processing facilities delay product launches by 12-18 months for new market entrants.
- Formulation chemist scarcity:Specialized expertise in liposome stabilization and extended-release polymer matrix design concentrates among a small cohort of contract development organizations.
- Legacy ERP integration with serialization:Track-and-trace mandates for pharmaceutical distribution require expensive upgrades to manufacturing execution systems at mid-scale facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lidocaine Market |
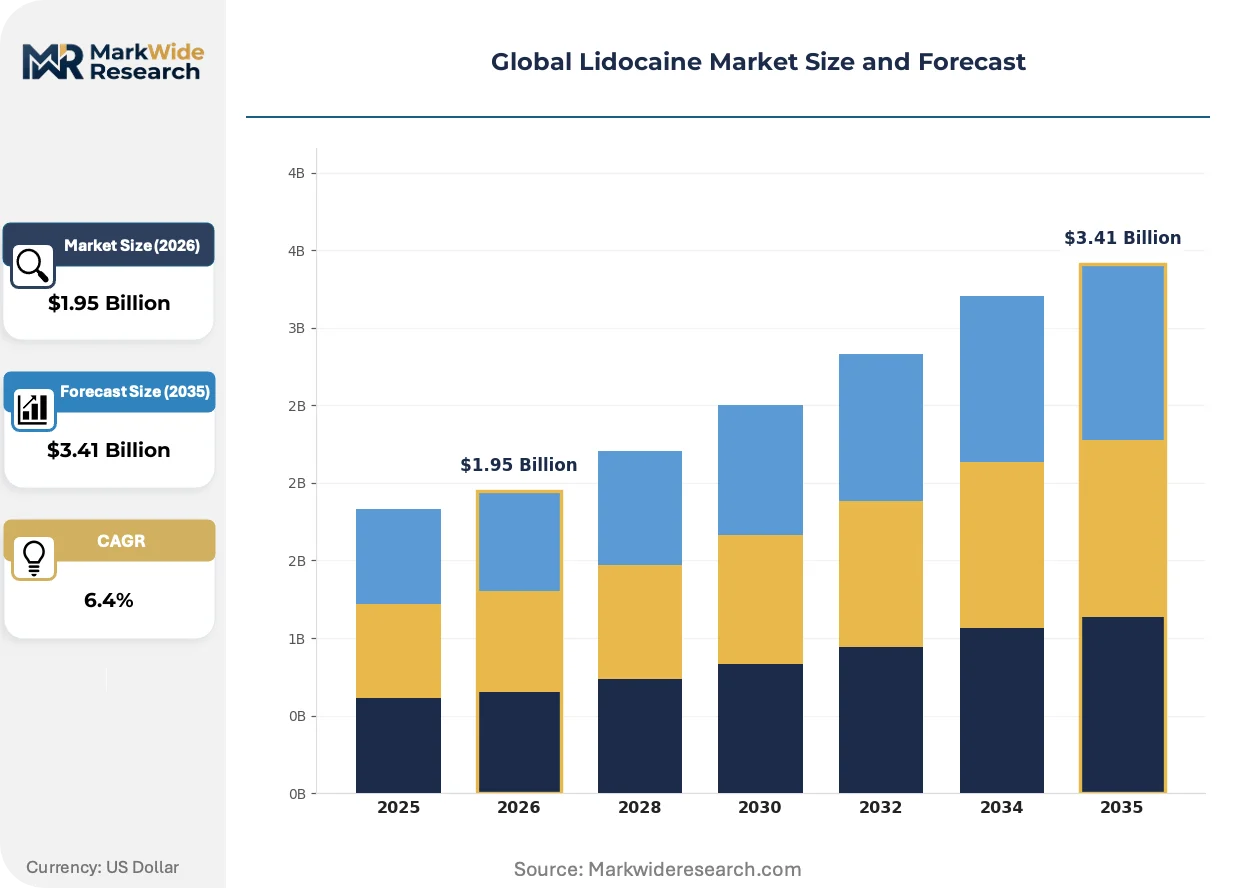
| Market Size in 2026 | $1.95 Billion |
| Market Size in 2035 | $3.41 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Form, Topical Cream, Patch, Gel, Spray Application: Dental Procedures, Minor Surgeries, Dermatology Treatments, Pain Management, Electrocardiography End User: Dental Clinics, Ambulatory Surgical Centers, Dermatology Clinics, Pain Therapy Centers Formulation Technology: Immediate Release, Extended Release, Liposomal, Microneedle, Transdermal |
| Companies Covered | Pfizer Inc., Teva Pharmaceutical Industries Ltd., AstraZeneca plc, Fresenius Kabi AG, Hikma Pharmaceuticals PLC, Endo International plc, Amneal Pharmaceuticals LLC, Viatris Inc., Hisamitsu Pharmaceutical Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lidocaine Market Shifts & Advancements
Digital formulation platforms and real-time release testing protocols are compressing development cycles while regulatory convergence on impurity standards is reshaping supplier qualification criteria across manufacturing networks.
Microfluidic liposome manufacturing is virtualizing traditional batch processing by enabling continuous-flow production of uniform particle-size distributions. German and Swiss contract manufacturers are adopting these platforms to serve biotech clients requiring rapid scale-up of novel delivery formulations. This technology is virtualizing the economics of small-batch specialty production, allowing profitable manufacture of orphan indications previously uneconomical under conventional tank-reactor methods.
The FDA-EMA pilot program on mutual recognition of nitrosamine risk assessments is harmonizing testing protocols for lidocaine APIs destined for transatlantic distribution. European manufacturers with existing ICH Q3D elemental impurity data packages gain accelerated US market entry. Injectable-grade producers in Ireland and Italy are consolidating analytical capabilities to serve dual-jurisdiction filings without redundant stability studies.
Hospital procurement consortia in the United States are unbundling device-anesthetic combinations, forcing separate negotiation of delivery systems and drug volume. Integrated delivery vendors face margin compression as group purchasing organizations award lidocaine vial contracts to lowest-unit-cost generic suppliers while sourcing pumps and needles through distinct tenders. This bifurcation is most visible in academic medical centers consolidating anesthesia supply contracts under centralized pharmacy governance models.
Global Lidocaine Market Segmentation
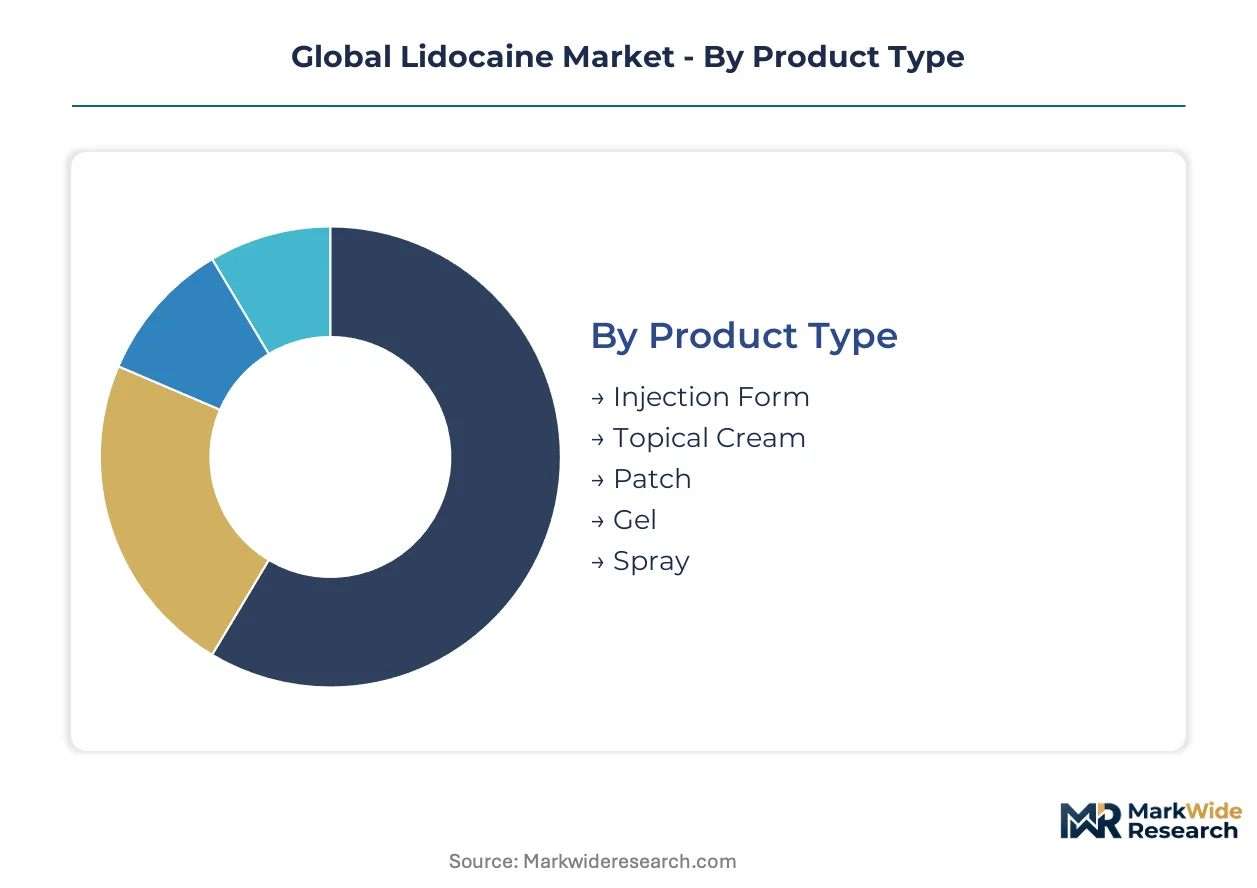
Segmentation in the lidocaine market reflects divergent technical requirements across clinical settings. Formulation sophistication determines pricing power, while end-user channel dynamics shape procurement patterns and margin structures.
Product Type:
Mature injectable formats dominate hospital procurement, while emerging delivery systems target outpatient and retail pharmacy expansion.
- Injection Form:Sterile aqueous solutions buffered to pH 6.5-7.5 for intravenous, subcutaneous, and nerve block administration. Dental clinics and ambulatory surgical centers in the United States and Germany drive procurement volume for same-day discharge protocols.
- Patch:Reservoir or matrix-type transdermal systems delivering sustained lidocaine release over 12-24 hours. Pain therapy centers in Japan favor these for post-herpetic neuralgia management where systemic opioid exposure is clinically undesirable.
- Topical Cream:Semi-solid emulsions for mucosal and intact skin application, common in dermatology outpatient settings.
- Gel:Viscous aqueous preparations optimized for urethral, oral, and endoscopic procedures requiring localized anesthesia.
- Spray:Metered-dose aerosol formulations for mucosal surface anesthesia prior to intubation or minor laceration repair.
Injection forms handle the majority of throughput; patches are gaining share fastest as chronic pain management shifts toward non-opioid alternatives.
Application:
Volume concentration follows procedural migration from inpatient to outpatient settings, with premium pricing attaching to specialized therapeutic indications.
- Dental Procedures:Inferior alveolar and buccal nerve blocks using 2% solutions with epinephrine vasoconstrictor. Dental clinics in Germany and Brazil are expanding lidocaine procurement as private practice consolidation accelerates.
- Pain Management:Neuropathic and postoperative pain protocols employing patches, infused pumps, and extended-release injectables. Pain therapy centers in Japan and the United States favor liposomal formulations for multi-day analgesia.
- Minor Surgeries:Local infiltration for excisional biopsies, wound closure, and superficial lesion removal in ambulatory settings.
- Dermatology Treatments:Pre-procedural anesthesia for laser therapy, Mohs surgery, and cosmetic injectable procedures.
- Electrocardiography:Intravenous administration for ventricular arrhythmia termination in emergency and critical-care settings.
Dental applications anchor volume demand; pain management shows the steepest expansion trajectory as regulatory pressure curtails opioid prescribing.
End User:
Channel fragmentation intensifies as procurement governance models diverge between consolidated health systems and independent specialty practices.
- Ambulatory Surgical Centers:High-throughput facilities performing same-day orthopedic, ophthalmic, and gastrointestinal procedures. These centers in the United States negotiate lidocaine vial contracts through group purchasing organizations while sourcing delivery devices separately.
- Dental Clinics:Private practices and dental service organizations requiring cartridge-format local anesthetics. German dental clinics are upgrading to automated dispensing systems that track lot-level consumption for regulatory compliance.
- Dermatology Clinics:Aesthetic and medical dermatology practices using topical and injectable lidocaine for laser, filler, and excisional procedures.
- Pain Therapy Centers:Specialized facilities managing complex regional pain syndrome, post-surgical neuropathy, and cancer-related pain through multimodal protocols.
Ambulatory surgical centers process the highest absolute volumes; pain therapy centers are expanding most quickly as chronic disease prevalence rises.
Formulation Technology:
Technology differentiation determines competitive moats, with immediate-release formats commoditizing and advanced delivery systems commanding formulation patents.
- Liposomal:Phospholipid bilayer encapsulation extending duration of action to 48-72 hours. Manufacturers in Switzerland and Germany deploy microfluidic continuous-flow production to serve biotech clients requiring rapid scale-up.
- Extended Release:Polymer matrix or depot formulations reducing dosing frequency for postoperative pain management. These technologies are displacing conventional bolus injections in orthopedic ambulatory procedures.
- Immediate Release:Conventional aqueous solutions with rapid onset and short duration, standard for procedural anesthesia.
- Microneedle:Dissolvable or coated microprojections enabling intradermal delivery without hypodermic injection, targeting needle-phobic patient segments.
- Transdermal:Passive diffusion systems optimized for chronic neuropathic pain indications requiring steady-state plasma levels.
Immediate release formulations still dominate unit volume; liposomal platforms are climbing the fastest on revenue contribution as hospital formularies prioritize reduced opioid exposure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bulk lidocaine API manufacturing clusters in China and India supply formulated dose producers worldwide, while advanced delivery-system production concentrates in Switzerland, Germany, and the United States. Regulatory divergence on nitrosamine impurity thresholds is fragmenting supply qualifications across jurisdictions.
United States
Dental clinics and ambulatory surgical centers in Texas and Florida are expanding lidocaine procurement for same-day discharge protocols. The FDA enforces current good manufacturing practice requirements that delay aseptic facility approvals by 12-18 months. Boston-area academic medical centers are consolidating anesthesia supply contracts under centralized pharmacy governance.
Germany
Private dental practice consolidation is accelerating cartridge-format anesthetic demand in Bavaria and North Rhine-Westphalia. The EMA's REACH framework governs chemical safety assessments for API production facilities. Swiss and German contract manufacturers near Basel are adopting microfluidic continuous-flow platforms for liposome production.
Japan
Pain therapy centers in Tokyo and Osaka favor lidocaine patches for post-herpetic neuralgia where systemic opioid exposure is clinically undesirable. The PMDA maintains pharmacopoeial purity standards exceeding baseline international requirements. Kanto-region manufacturers are pre-certifying against advanced specifications to retain hospital formulary slots.
Brazil
Private dental clinics in São Paulo and Rio de Janeiro are upgrading procurement as practice consolidation accelerates. ANVISA's tightening purity standards for imported APIs create first-mover advantage for pre-certified suppliers. Southeast Brazilian distributors are building direct-to-pharmacy channels for transdermal patch products.
Switzerland
Specialized parenteral production lines near Basel serve critical-care settings across European markets. Swissmedic maintains alignment with EMA nitrosamine risk assessment protocols while preserving distinct national pharmacovigilance requirements. Microfluidic liposome manufacturing platforms in the Basel-Zurich corridor enable profitable small-batch orphan indication production.
Global Lidocaine Market Competitive Landscape
Integrated pharmaceutical conglomerates and specialized generic manufacturers split the market along formulation sophistication lines. Hospital channel dominance requires validated sterile processing capabilities that concentrate among established injectable infrastructure holders. Three archetypes predominate: backward-integrated API-to-dose producers, formulation-technology specialists, and critical-care parenteral suppliers. Competitive moves center on liposomal platform patent protection and pre-certification against tightening pharmacopoeial standards in secondary markets.
Within the integrated infrastructure tier, Pfizer Inc. and Teva Pharmaceutical Industries Ltd. occupy positions anchored by injectable manufacturing scale and captive API supply respectively. Fresenius Kabi AG exemplifies the critical-care specialization archetype through parenteral production line dedication. These three entities represent the dominant competitive anchors against which mid-scale manufacturers and contract development organizations position formulation-technology differentiation.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| AstraZeneca plc |
| Fresenius Kabi AG |
| Hikma Pharmaceuticals PLC |
| Endo International plc |
| Amneal Pharmaceuticals LLC |
| Viatris Inc. |
| Hisamitsu Pharmaceutical Co., Inc. |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese API manufacturing clusters is compressing spot pricing for lidocaine base while simultaneously forcing integrated producers toward formulation-technology differentiation to defend margin pools. This utilization dynamic creates divergent supplier strategies: commodity-scale manufacturers absorb volume-driven price erosion, while liposomal and extended-release specialists capture premium positioning through delivery-system sophistication.
Pricing Analysis
Aftermarket service revenue around lidocaine delivery systems—including pump maintenance contracts, needle safety training, and formulary compliance consulting—drives lifetime value for hospital channel vendors. Three-tier pricing structure across premium, standard, and economy levels segments by formulation technology sophistication: liposomal platforms command formulation-patent premiums, sterile injectables compete on GMP-certification tier, and immediate-release vials face commodity spot-market pressure. Pricing pressure stems from group purchasing organization consolidation in United States academic medical centers, where unbundled device-anesthetic procurement favors lowest-unit-cost generic suppliers. Ambulatory surgical centers exhibit highest price sensitivity due to thin procedural margins, while pain therapy centers demonstrate lowest sensitivity where reduced opioid exposure justifies premium positioning.
Supply Chain Analysis
Upstream 2,6-xylidine feedstock draws from petrochemical complexes concentrated in China, India, and Germany, with pricing volatility tethered to crude oil benchmarks and regional refining capacity. Raw material dependencies span 2,6-xylidine starting material, phospholipid excipients for liposomal production, and specialized pH-buffering agents for sterile formulation stability. Single-source vulnerability concentrates in bulk lidocaine base production, where a limited manufacturer set in Shandong and Gujarat provinces supplies formulated dose producers worldwide. Distribution runs through hospital procurement consortia and group purchasing organizations in developed markets, with direct-to-pharmacy channels emerging for transdermal patch products in fragmented retail pharmacy markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in liposome stabilization and extended-release polymer matrix design concentrates among a narrow cohort of contract development organizations, creating capability scarcity that determines competitive positioning. This skill gap separates formulation-technology leaders from commodity-scale followers across the analysis window.
For Market Incumbents: Harden sterile manufacturing qualifications against FDA pre-approval inspection backlogs that delay product launches by 12-18 months for new entrants. Expand captive API production or backward integration into 2,6-xylidine supply to buffer feedstock volatility from Chinese and Indian source markets. Prioritize liposomal platform patent protection as bupivacaine and ropivacaine substitution threats intensify in orthopedic and obstetric applications.
For New Entrants and Emerging Players: Brazilian private dental clinics in São Paulo and Rio de Janeiro present underpenetrated procurement upgrade opportunities as ANVISA tightens purity standards for imported APIs. Target pain therapy center channels in Japan where PMDA pharmacopoeial standards exceed baseline international requirements and pre-certified suppliers capture formulary slots. Pursue microfluidic continuous-flow liposome manufacturing partnerships with Swiss and German contract manufacturers near Basel to bypass capital-intensive sterile facility buildouts.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liposomal and extended-release formulation segments as microfluidic platform deployment and specialized parenteral line dedication require sustained R&D commitment. Acquisition targets should demonstrate validated analytical capabilities for nitrosamine impurity monitoring under converging FDA-EMA protocols, with existing ICH Q3D elemental impurity data packages enabling accelerated dual-jurisdiction filings. Monitor FDA-EMA pilot program mutual recognition progress as signal for which manufacturers retain multi-region supply qualifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Liposomal Platform Patent Expansion | Extends duration of action from hours to days, opening postoperative pain management applications previously served by opioids. |
| Microfluidic Manufacturing Scale-Up | Enables continuous-flow production of uniform particle-size distributions for profitable small-batch orphan indication manufacture. |
| ANVISA Pre-Certification Investment | Captures first-mover advantage as Brazilian regulatory tightening creates compliance-driven segmentation for imported APIs. |
| Direct-to-Pharmacy Patch Distribution | Bypasses traditional wholesale markups in fragmented retail pharmacy markets for lidocaine 4% and 5% transdermal products. |
| Nitrosamine Analytical Capability Consolidation | Positions manufacturers for FDA-EMA mutual recognition of risk assessments without redundant stability studies. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across regulatory and commercial databases. Primary interviews encompassed pharmaceutical manufacturing executives, sterile processing facility managers, hospital formulary directors, group purchasing organization contract specialists, and pain therapy center clinical directors. Secondary sources included FDA drug approval databases, EMA REACH framework submissions, ClinicalTrials.gov protocol registries, and customs trade data for lidocaine API import flows. Bottom-up volume modeling by formulation technology and application segment triangulated against top-down market size estimates from trade association filings.
Forecast inputs considered procedural volume migration from inpatient to ambulatory settings, regulatory convergence timelines on nitrosamine impurity thresholds, and substitution dynamics from longer-acting amide anesthetics. Segmentation dimensions modeled spanned formulation technology, application setting, end-user channel, and regional regulatory cluster. CAGRs derived from slope-log regression across the projection horizon, with cross-validation against historical growth patterns in local anesthetic markets. Industry-specific inputs included dental clinic consolidation rates, ambulatory surgical center same-day discharge protocol adoption, and pain therapy center multimodal analgesia protocol shifts.
Practitioners should monitor regulatory divergence on nitrosamine standards, feedstock price volatility in 2,6-xylidine markets, and liposomal formulation patent expiration schedules for early signals requiring forecast revision. Cross-checking against FDA Orange Book formulation approvals and EMA public assessment reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Middle East and Africa Adenomyosis Drugs Market
Pharmaceuticals
SGLT2 Inhibitors Market
Pharmaceuticals
Urinary Retention Drugs Market
Pharmaceuticals
Middle East and Africa Psychedelic Drugs Market
Pharmaceuticals
Global Nasal Drug Delivery Technology Market
Pharmaceuticals
Water for Injection Market
Pharmaceuticals
Vutrisiran Market
Pharmaceuticals
Hydrocortisone Market
Pharmaceuticals
Authorized Generics Market
Pharmaceuticals
Global Azithromycin Market
Pharmaceuticals
Etoricoxib Market
Pharmaceuticals
Fibromyalgia Antidepressant Market
Pharmaceuticals
Ramipril Market
Pharmaceuticals
Iron Deficiency Injectables Market
Pharmaceuticals
Latin America Pharmaceutical Contract Manufacturing Organization Market
Pharmaceuticals
Bacteriostatic Water for Injection Market