
 Germany Lip Care Products Market | 2026-2036
Germany Lip Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Lip Care Products Market Intelligence
Direct-to-consumer subscription financing and asset-light e-commerce leasing is rewriting competitive entry barriers for mid-sized brands in the Germany lip care sector. Beiersdorf AG leverages its Hamburg-based R&D campus to sustain formulation leadership across medicated and cosmetic balms. L'Oréal S.A. competes through pharmacy channel control and dermatological co-branding with German skincare clinics. Unilever PLC differentiates via mass-market shelf positioning in Rewe and Edeka supermarket networks.
Lip care products encompass topical formulations—typically combining emollients such as petrolatum, natural waxes, or plant-derived butters with active agents including UV filters, vitamins, or humectants—manufactured through hot-pour processes into stick, pot, or tube formats designed to prevent desiccation, protect against environmental exposure, and restore epidermal barrier function. SPF-Infused products lead volume contribution as German consumers prioritize photoprotection under stricter dermatological guidance, while Natural ingredient claims capture fastest-growing shelf space driven by BDIH and NATRUE certification recognition. Pharmacy distribution channels command premium margin pools due to pharmacist recommendation authority and reimbursement-adjacent positioning for therapeutic lip treatments.
German manufacturers navigate BfR safety assessments for cosmetic ingredients alongside EU REACH substance restrictions and the EU Green Deal's packaging sustainability mandates, which collectively elevate compliance costs but simultaneously filter out non-compliant imports. The German Federal Institute for Drugs and Medical Devices enforces borderline classification scrutiny when lip care products claim therapeutic efficacy, creating regulatory segmentation between cosmetic and quasi-pharmaceutical positioning. Stakeholders must monitor evolving BDIH organic certification thresholds and draft EU microplastic restrictions in rinse-off and leave-on cosmetic formulations.
Market Dynamics
German lip care manufacturers confront a structural squeeze between EU Green Deal packaging mandates and pharmacy channel margin pressure, forcing reformulation investments that smaller competitors cannot absorb.
Growth Catalysts
- EU REACH substance restrictions:Chemical safety thresholds filter out non-compliant imports, creating protected market space for domestic formulators investing in plant-based wax substitutes.
- Pharmacy channel authority:German pharmacist recommendation power drives premium positioning for therapeutic lip treatments adjacent to reimbursement pathways.
- Urban center concentration:Berlin, Munich, and Hamburg generate disproportionate volume through specialty retail and pharmacy density.
Market Restraints
- Beeswax supply volatility:Climate stress on European apiculture raises input costs for natural-positioned formulations.
- Regulatory friction from BfR assessments:Extended safety evaluation timelines delay product launches by 8-14 months.
- Substitution threat from multi-use balms:All-in-one skincare products capture routine-simplifying consumers.
Strategic Opportunities
- Rhineland-Palatinate and Saxony underpenetration:Eastern German states show pharmacy channel whitespace outside Berlin-Hamburg-Munich axis.
- Direct-to-consumer subscription models:Asset-light e-commerce leasing lowers entry barriers for mid-sized brands.
- BDIH organic certification tailwind:Rising consumer recognition of NATRUE standards creates premium shelf differentiation.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in SPF-stability and natural emulsifier compatibility commands premium wages.
- Microplastic compliance timeline uncertainty:Draft EU restrictions on leave-on cosmetics create planning paralysis for polyethylene-based exfoliant formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Lip Care Products Market |
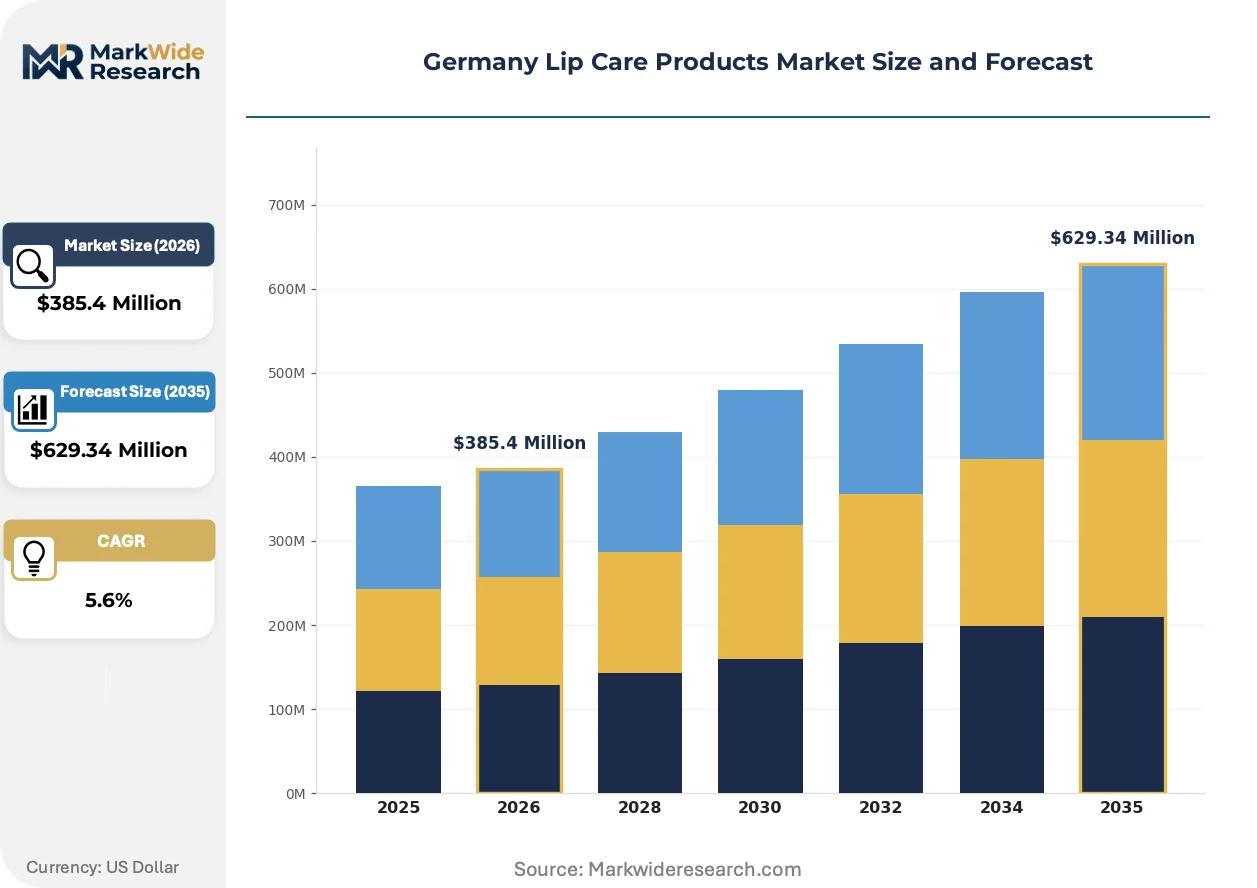
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $629.34 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lip Balm, Lip Scrub, Lip Gloss, Lipstick Ingredient: Natural, Organic, Synthetic, SPF-Infused Distribution Channel: Online, Supermarkets, Pharmacy, Department Stores End User: Women, Men, Children, Unisex |
| Companies Covered | Beiersdorf AG, L'Oréal S.A., Unilever PLC, The Procter and Gamble Company, Bayer AG, Kao Corporation, Colgate-Palmolive Company, The Estée Lauder Companies Inc., Revlon Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Lip Care Products Market Strategic Shifts & Innovations
Formulation science and channel control are rewriting competitive rules in German lip care, with sustainability credentials and dermatological credibility becoming inseparable from market access.
SPF-infused lip care is migrating from niche summer positioning to year-round baseline expectation among German consumers. Pharmacy shoppers now reject unprotected balms during winter months. This migration from seasonal to routine application compresses margin for single-function competitors.
REACH substance restrictions and the EU Green Deal packaging mandates are forcing hot-pour manufacturing retrofits. German facilities face six-figure capital outlays for biodegradable mold systems. Mid-tier brands without Hamburg or Munich R&D proximity struggle to pace compliance.
Subscription-based replenishment is displacing supermarket impulse purchases among urban millennials. Direct-to-consumer platforms capture recurring revenue from Berlin and Munich professionals. Bavaria and Baden-Württemberg show highest adoption of auto-ship lip care programs.
Germany Lip Care Products Market Segmentation
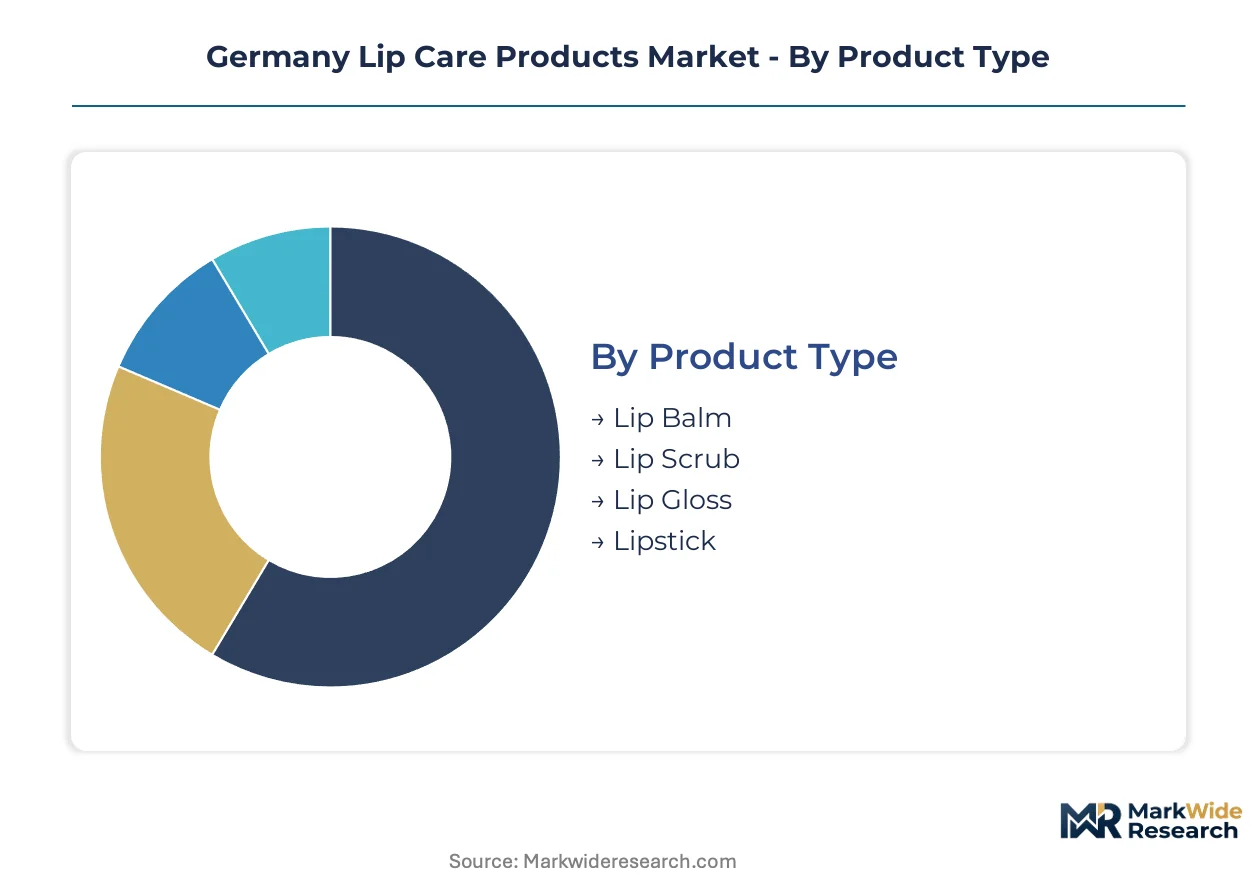
German lip care segmentation reveals divergent margin architectures across functional and aesthetic product lines. Cycle times vary dramatically—pharmacy-channel therapeutic balms turn inventory quarterly while color cosmetics rotate seasonally. Manufacturers optimize formulation platforms across these velocity mismatches to capture both recurring replenishment and impulse upgrade spending.
Product Type:
Lip Balm commands the shortest replenishment cycles at 6-8 weeks for core users, while Lipstick stretches to 4-6 months per purchase. Cycle velocity directly shapes working capital requirements and shelf-space negotiation leverage.
- Lip Balm:Stick, pot, and tube formats combining petrolatum or plant-derived waxes with humectants. Berlin, Munich, and Hamburg pharmacy channels drive volume through year-round SPF-infused positioning. German consumers now reject unprotected variants even in winter months, compressing margin for single-function competitors.
- Lip Scrub:Exfoliating formulations using sugar crystals, jojoba beads, or biodegradable alternatives to polyethylene. REACH substance restrictions and draft EU microplastic mandates force rapid reformulation away from synthetic exfoliants. BDIH certification recognition accelerates adoption of natural-abrasive variants.
- Lip Gloss:High-shine emulsions with varying viscosity grades. Teen and young-adult demographics in urban centers favor frequent shade rotation.
- Lipstick:Pigmented wax-based color cosmetics with longest purchase intervals. Department store and specialty retail channels dominate.
Lip Balm dominates installed base. Lip Scrub is where expansion concentrates.
Ingredient:
Cost tier stratification runs deepest here—synthetic formulations occupy mass-market price points while organic certification commands 40-60% premiums. Raw material sourcing geography determines compliance burden under EU REACH.
- Natural:Plant-derived waxes, butters, and oils without synthetic additives. Beeswax supply volatility from climate-stressed European apiculture raises input costs unpredictably. German manufacturers source alternative candelilla and carnauba waxes to reduce dependency.
- Organic:BDIH and NATRUE-certified formulations meeting strict cultivation and processing standards. Baden-Württemberg and Bavaria consumers show highest willingness-to-pay for certified organic positioning. Pharmacist recommendation authority amplifies credibility in these states.
- Synthetic:Petrolatum and mineral-oil-based formulations at lowest cost tier. Rewe and Edeka supermarket networks capture volume here.
- SPF-Infused:UV-filter formulations migrating from seasonal to year-round baseline expectation. BfR safety assessments for photostable active ingredients extend development timelines.
Synthetic formulations dominate installed base. Organic certification is where expansion concentrates.
Distribution Channel:
Margin structure inverts between volume and value—supermarkets move units at 15-20% manufacturer margins while pharmacy channels extract 35-45% through recommendation authority.
- Online:Direct-to-consumer platforms and third-party marketplaces. Subscription-based replenishment is displacing impulse purchases among Berlin and Munich millennials. Auto-ship programs show highest adoption in Bavaria and Baden-Württemberg.
- Supermarkets:Rewe, Edeka, and Aldi networks for mass-market positioning. Shelf-space competition intensifies during winter heating-season demand peaks.
- Pharmacy:Apotheke channels with pharmacist recommendation authority. Therapeutic lip treatments adjacent to reimbursement pathways command premium positioning. Eastern German states outside Berlin-Hamburg-Munich axis show whitespace opportunity.
- Department Stores:Douglas, Kaufhof, and specialty cosmetics retail for color cosmetics and gift sets. Seasonal promotional calendars drive volume concentration.
Supermarkets dominate installed base. Online subscription models are where expansion concentrates.
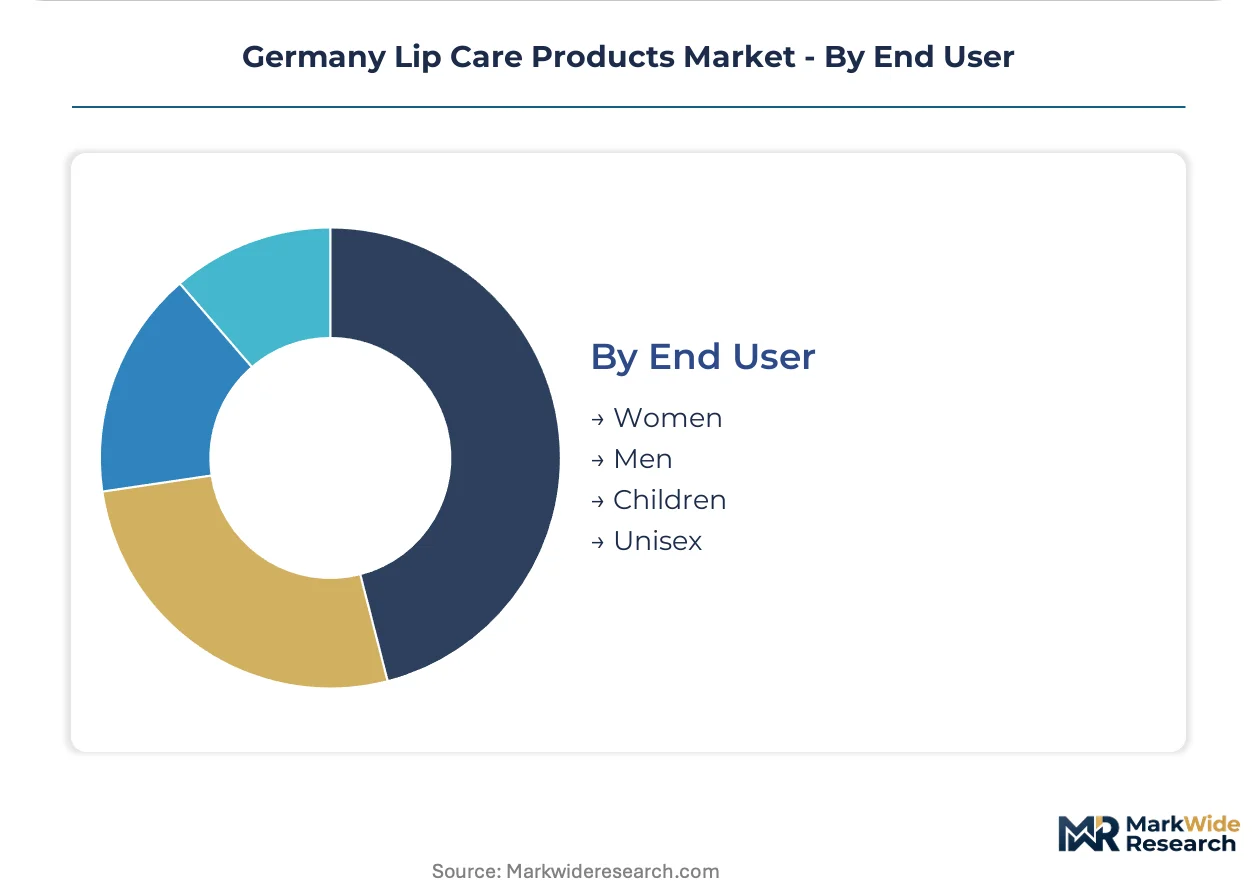
End User:
Application occasion and purchase decision authority split segmentation—self-directed adult purchasing versus caregiver-mediated selection for minors.
- Women:Core demographic with highest category penetration and SKU experimentation. Multi-step routines combining treatment and color products.
- Men:Simplified single-product usage with growing SPF awareness. Pharmacy channels capture this segment through no-nonsense therapeutic positioning.
- Children:Caregiver-purchased formulations with strict safety and ingestion-risk considerations. BfR assessments for pediatric-appropriate ingredients create formulation constraints.
- Unisex:Neutral positioning targeting household consolidation and shared usage. Minimal fragrance and plain packaging reduce gendered marketing costs.
Women dominate installed base. Men and Unisex positioning are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal packaging mandates and REACH compliance requirements are redistributing manufacturing capacity toward states with established chemical R&D infrastructure. Regional disparities in pharmacist recommendation authority and organic certification recognition create uneven premium capture across German territory.
North Rhine-Westphalia
Industrial chemical heritage supports rapid reformulation capacity for plant-based wax substitutes. ECHA REACH substance restrictions filter import competition through Cologne-Düsseldorf logistics corridors. Leverkusen and Düsseldorf host contract manufacturing facilities serving pharmacy-channel brands with therapeutic positioning.
Bavaria
Auto-ship subscription adoption concentrates in Munich and Nuremberg metropolitan zones. BDIH organic certification recognition drives premium willingness-to-pay among Baden-Württemberg-adjacent consumers. Ingolstadt and Augsburg specialty retail clusters sustain above-average margins for NATRUE-standard formulations.
Baden-Württemberg
Stuttgart and Karlsruhe pharmacy density enables therapeutic lip treatment positioning adjacent to reimbursement pathways. EU Green Deal sustainability mandates accelerate biodegradable packaging transitions in Freiburg manufacturing zones. Regional apiculture stress elevates candelilla and carnauba wax sourcing from alternative supply chains.
Berlin-Brandenburg
Direct-to-consumer platform penetration peaks in Berlin's urban millennial demographic. BfR safety assessment timelines delay product launches for brands lacking Hamburg R&D proximity. Potsdam specialty retail corridors experiment with unisex positioning and minimal fragrance formulations.
Hamburg
Pharmacy channel control and dermatological co-branding concentrate in Germany's northern commercial hub. Beiersdorf AG leverages local R&D campus infrastructure for SPF-stability formulation leadership. Port logistics facilitate beeswax alternative imports from non-European supply sources.
Germany Lip Care Products Market Key Industry Players
Channel-controlling players compete with product-specialist players across pharmacy, supermarket, and direct-to-consumer vectors. The vendor base organizes around three strategic archetypes: Hamburg-based R&D-integrated formulators, Paris/London-centered luxury dermatology brands, and Rotterdam/Amsterdam-positioned mass-market distributors. Dominant competitive moves include pharmacy channel exclusivity agreements and biodegradable packaging retrofits forced by EU regulatory timelines.
Among Hamburg-based R&D-integrated formulators, Beiersdorf AG exemplifies the therapeutic-cosmetic hybrid archetype through its proximity to BfR regulatory pathways. L'Oréal S.A. and Unilever PLC occupy divergent positions within the channel-control spectrum—L'Oréal representing pharmacy-authority premium positioning while Unilever anchors mass-market supermarket penetration. These three entities collectively illustrate how geographic clustering around regulatory and logistics infrastructure shapes competitive access.
| Leading Market Players |
|---|
| Beiersdorf AG |
| L'Oréal S.A. |
| Unilever PLC |
| The Procter and Gamble Company |
| Bayer AG |
| Kao Corporation |
| Colgate-Palmolive Company |
| The Estée Lauder Companies Inc. |
| Revlon Inc. |
| Others |
Cost & Logistics Intelligence
Cologne-Düsseldorf logistics corridors channel beeswax alternative imports from Latin American and Asian supply sources, concentrating inbound cost dynamics for plant-derived waxes while enabling downstream price differentiation between BDIH-certified organic formulations and synthetic petrolatum-based tiers.
Pricing Analysis
Certification level (BDIH/NATRUE-grade) creates the primary spread between mass-market and premium tiers. Three-tier pricing structure across organic, natural, and synthetic levels reflects raw material sourcing geography and REACH compliance investment. Cost compression in the synthetic tier is intensifying because supermarket chains Rewe and Edeka consolidate shelf-space negotiations. Pharmacy-channel buyers show least price sensitivity due to reimbursement-adjacent therapeutic positioning.
Supply Chain Analysis
Contract manufacturing concentration rests with Leverkusen and Düsseldorf facilities serving pharmacy-channel therapeutic brands. Raw material sourcing draws from Brazilian carnauba plantations, Mexican candelilla harvesters, and European rapeseed oil processors. Single-source vulnerability elevates around climate-stressed European apiculture and beeswax substitution timelines. Distribution runs through Apotheke networks for premium capture and supermarket DCs for volume throughput.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemists capable of SPF-stability engineering and natural emulsifier compatibility represent the critical capability gap constraining competitive entry and expansion pacing in German lip care.
For Market Incumbents: Entrench pharmacy channel control through exclusive Apotheke distribution agreements and dermatological co-branding investments. Accelerate biodegradable packaging retrofits ahead of EU Green Deal enforcement timelines to filter out compliance-lagged imports. Backward integration into candelilla and carnauba wax sourcing reduces beeswax volatility exposure. For New Entrants and Emerging Players: Rhineland-Palatinate and Saxony pharmacy whitespace outside the Berlin-Hamburg-Munich axis offers lowest competitive density for therapeutic positioning. Direct-to-consumer subscription models with asset-light e-commerce leasing bypass supermarket slotting fee barriers. BDIH certification investment unlocks premium pricing in Baden-Württemberg and Bavaria. For Investors and Strategic Acquirers: Mid-tier brands with Hamburg or Munich R&D proximity and existing SPF-formulation platforms present acquisition targets with compliance-ready infrastructure. Long-term viability hinges on REACH substance restriction adaptation capacity and biodegradable packaging transition execution. Monitor BfR safety assessment timeline extensions as inflection signals for launch-delay risk accumulation.| Strategic Initiative | Industry Significance |
|---|---|
| BDIH Organic Certification Investment | BDIH thresholds unlock 40-60% price premiums in Bavaria and Baden-Württemberg pharmacy channels. |
| Biodegradable Packaging Retrofit | EU Green Deal mandates force six-figure capital outlays that filter non-compliant import competition. |
| Direct-to-Consumer Subscription Launch | Berlin and Munich millennial auto-ship adoption displaces supermarket impulse purchase volume. |
| Pharmacy Channel Expansion | Apotheke recommendation authority captures 35-45% margins versus 15-20% in supermarket networks. |
| Plant-Based Wax Reformulation | Candelilla and carnauba sourcing reduces climate-stressed European apiculture dependency. |
Research Approach
Cross-validation between primary interviews with brand managers, category buyers at Rewe and Edeka, Apotheke pharmacists, and supply planners anchors the qualitative findings. Secondary validation draws from BfR safety assessment databases, EU REACH substance restriction filings, BDIH certification registries, and Nielsen retail audit data. Bottom-up SKU-level demand modeling and top-down category spend analysis complete the triangulation.
Calibration against historical pharmacy-channel sell-through data and supermarket promotional calendars shapes the analytical framework across the projection horizon. Segmentation dimensions include product type, ingredient certification tier, distribution channel, and end-user demographic. CAGRs derive from trend-line extrapolation adjusted for regulatory inflection points. SPF-infused formulation adoption curves and subscription model penetration rates serve as industry-specific forecast inputs.
Practitioners should monitor BfR assessment timeline extensions, EU microplastic restriction finalization, and beeswax supply volatility indices for early signals of forecast revision triggers. Quarterly review of Apotheke inventory turns and direct-to-consumer churn rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Home Use Anti-Aging Beauty Device Market
Beauty & Personal Care
China Antibacterial Soap Market
Beauty & Personal Care
Middle East and Africa Beauty and Personal Care Products Market
Beauty & Personal Care
Eyelash Serum Market
Beauty & Personal Care
Europe Hair and Skincare Market
Beauty & Personal Care
North America Hair Conditioner Market
Beauty & Personal Care
Hair Removal Epilator Market
Beauty & Personal Care
Facial Epilator Market
Beauty & Personal Care
Shaving Foam Market
Beauty & Personal Care
Facial Rollers Market
Beauty & Personal Care
Global Shampoo Bars Market
Beauty & Personal Care
Gua Sha Tools Market
Beauty & Personal Care
Nail Polish Remover Market
Beauty & Personal Care
Portable Atomizer Market
Beauty & Personal Care
Body Care Products Market
Beauty & Personal Care
Deodorant Wipes Market