
 European Discount Retail Market | 2026-2036
European Discount Retail Market Size, Share, and Industry Trends Forecast 2026-2036
European Discount Retail Market Analysis
Central and Eastern Europe is rewriting competitive geography for hard discounters. Aldi leverages its German supply-base efficiency to undercut local incumbents in Poland. Lidl sustains private-label dominance across Iberia and the Balkans through bakery-led traffic generation. Action anchors margin performance with extreme SKU rotation in non-food general merchandise.
European discount retail denotes a high-volume, low-margin distribution format operating on permanent low pricing rather than promotional cycles, with typical assortments of 1,000–2,500 SKUs and gross margins below 20 percent. The model prioritizes operational productivity over experiential retail, serving consumers who trade brand equity for price certainty. Grocery commands the largest revenue pool but yields thinner margins than household items, where private-label penetration remains lower and sourcing arbitrage persists. Online distribution channels represent the fastest-growing access point yet remain marginal to total discount volume, while hypermarkets face structural decline as convenience-oriented formats capture time-pressed families.
The EU Green Deal and national packaging directives from Germany's Federal Environment Agency reshape product specifications and supplier compliance costs for discount chains. REACH chemicals regulation and the EU AI Act's emerging retail surveillance rules further constrain private-label formulation and in-store analytics deployment. Stakeholders must track how regulatory compliance costs transmit through already-constrained margin structures.
Market Dynamics
The EU Green Deal's packaging mandates are compressing format economics for hard discounters, forcing simultaneous SKU rationalization and supplier compliance investments that reshape margin allocation across the value chain.
Growth Catalysts
- Urban Millennial Density:Basket-size expansion in Warsaw, Bucharest, and Prague drives traffic to compact formats. Eastern European capitals concentrate purchasing power for private-label penetration.
- REACH Chemicals Regulation:Compliance costs favor large-scale private-label formulators with dedicated regulatory affairs teams. Smaller competitors face exclusion from shelf space.
- AI-Driven Demand Forecasting:Machine learning models compress inventory carrying costs for ambient grocery categories. Deployment spans distribution centers in Poland and Romania.
Market Restraints
- Energy Input Volatility:Refrigeration and transport costs fluctuate with continental power markets. Discount chains lack pricing power to pass through spikes.
- German Supply-Base Concentration:Hard discounters depend on Bavarian and Baden-Württemberg manufacturers for core private-label volume. Geographic risk concentrates margin pressure.
- EU AI Act Surveillance Rules:In-store analytics deployment faces consent and data-minimization constraints. Customer tracking for personalized offers encounters compliance friction.
Strategic Opportunities
- Romania Regional Expansion:Secondary cities like Cluj-Napoca and Timișoara remain underpenetrated by organized discount formats. Local purchasing power supports format replication.
- Bakery-Led Traffic Generation:In-store bread production commands margin premiums and differentiates against online grocery. Portuguese and Spanish consumer patterns validate model transfer.
- CSRD Reporting Alignment:Early compliance with corporate sustainability disclosure rules attracts ESG-mandated institutional capital. Supply-chain transparency becomes competitive signaling.
Industry Challenges
- Refrigeration Technician Scarcity:Cold-chain maintenance talent pools contract across Eastern Europe. Service response times extend, risking stockouts in frozen categories.
- Legacy POS Integration:Real-time inventory systems must interface with decade-old checkout infrastructure. Rollout timelines stretch across multi-format estates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | European Discount Retail Market |
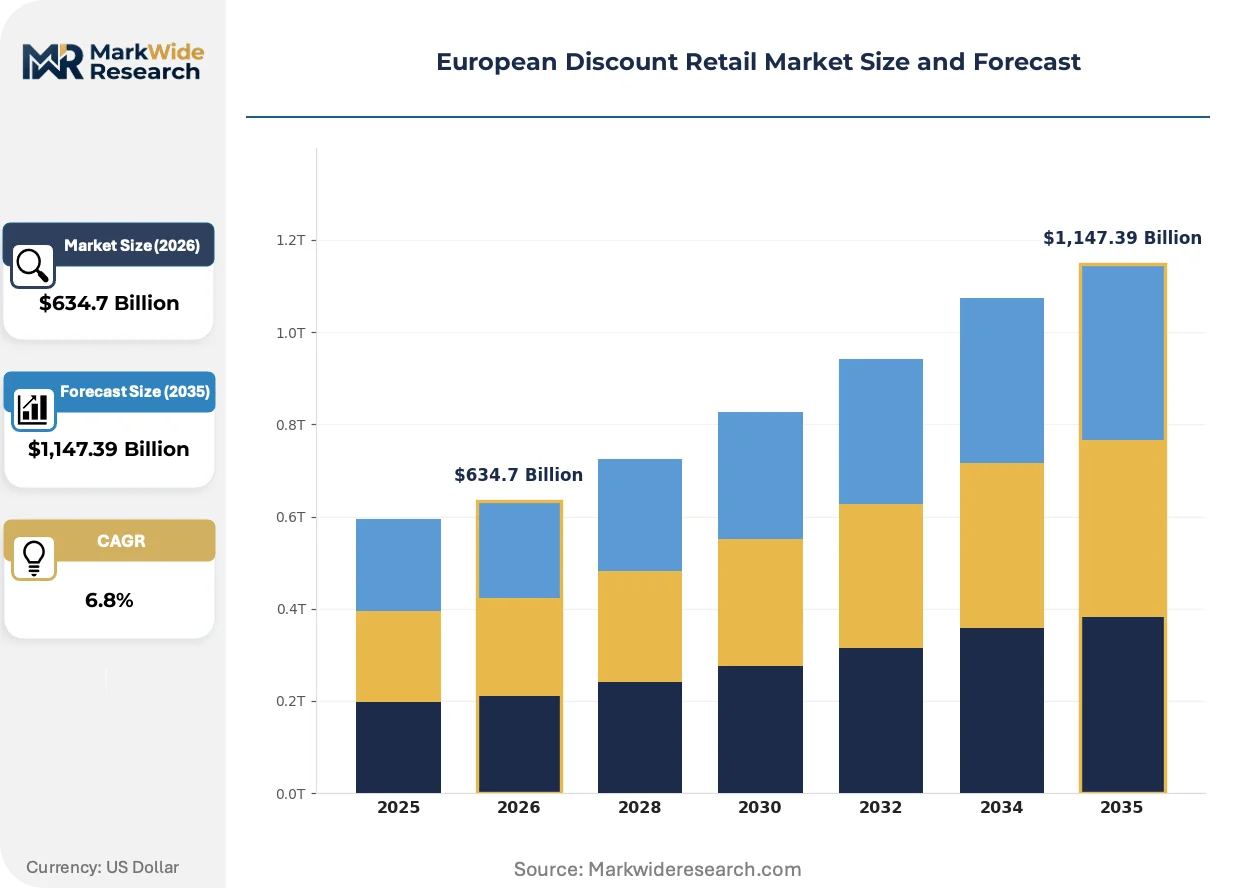
| Market Size in 2026 | $634.7 Billion |
| Market Size in 2035 | $1,147.39 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grocery, Household Items, Apparel, Electronics Distribution Channel: Online, Hypermarkets, Wholesalers, Convenience Stores Customer Type: Cost-Conscious Shoppers, Families, Students, Seniors Price Tier: Low-Cost, Mid-Range, Budget, Promotional |
| Companies Covered | Lidl, Biedronka, Tedi, Penny, Netto Marken Discount, Action, Mercadona, X5 Retail Group, Aldi, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
European Discount Retail Market Emerging Trajectories
Automation is compressing labor intensity in back-of-store operations while regulatory packaging mandates force front-of-store format reinvention. Consumer time scarcity accelerates convenience-oriented channel experimentation.
Autonomous shelf-scanning robotics is collapsing the cost structure of inventory management in high-SKU discount environments. German and Polish operators deploy mobile units for nightly stock-count verification. Labor reallocation toward customer-facing roles follows, though technical reliability varies across store footprints.
The EU Green Deal's single-use plastics directive forces laminated packaging redesign for private-label dry groceries. Suppliers absorb reformulation costs while retailers negotiate extended payment terms. Iberian markets face accelerated compliance timelines relative to Central European counterparts.
Urban consumers consolidate weekly shopping into single destination trips, compressing the addressable market for standalone convenience formats. Hard discounters capture this rotation through expanded fresh and ready-meal sections. Bucharest and Budapest register the fastest format-switching incidence in household panel data.
European Discount Retail Market Segmentation

Segmentation in European discount retail reveals how format economics vary by product velocity, channel cost structure, and customer price sensitivity. Cycle-time differences between ambient grocery and seasonal general merchandise dictate inventory deployment and margin recovery timelines across the value chain.
Product Type:
Grocery SKUs turn over fastest while electronics and apparel operate on extended replenishment cycles with higher obsolescence risk.
- Grocery:Ambient and chilled food categories dominate transaction frequency with weekly purchase patterns. Eastern European capitals drive basket expansion as urban millennials consolidate shopping trips into hard discount destinations.
- Household Items:Cleaning products and paper goods yield higher margins than food with lower storage complexity. REACH chemicals regulation compliance costs favor large-scale private-label formulators with dedicated regulatory affairs capacity.
- Apparel:Extreme SKU rotation models compress fashion risk through rapid inventory clearance.
- Electronics:Small appliances and accessories face online price transparency pressure.
Grocery anchors the volume base while household items gains share at the steepest rate.
Distribution Channel:
Channel economics diverge sharply between fixed-cost store networks and variable-cost digital fulfillment.
- Online:Digital channels represent the fastest-growing access point yet remain marginal to total discount volume. Machine learning deployment in Polish and Romanian distribution centers compresses inventory carrying costs for ambient categories.
- Hypermarkets:Large-format stores face structural decline as convenience-oriented formats capture time-pressed families. Bucharest and Budapest register the fastest format-switching incidence in household panel data.
- Wholesalers:B2B bulk supply serves independent retailers and foodservice operators.
- Convenience Stores:Small-footprint proximity formats compete for immediate consumption occasions.
Hypermarkets retain the installed base while online climbs the fastest in incremental traffic capture.
Customer Type:
Demographic segments exhibit distinct trip frequency and private-label acceptance patterns.
- Cost-Conscious Shoppers:Price-certainty seekers trade brand equity for permanent low pricing without promotional hunting. This segment concentrates in Eastern European markets where organized discount penetration remains below Western European levels.
- Families:Multi-person households drive large-basket shopping with strong fresh and bakery attachment.
- Students:Younger consumers prioritize entry-price points with limited loyalty to specific formats.
- Seniors:Older shoppers favor familiar store layouts and consistent product availability.
Families generate the highest per-trip revenue while cost-conscious shoppers expand most quickly in emerging markets.
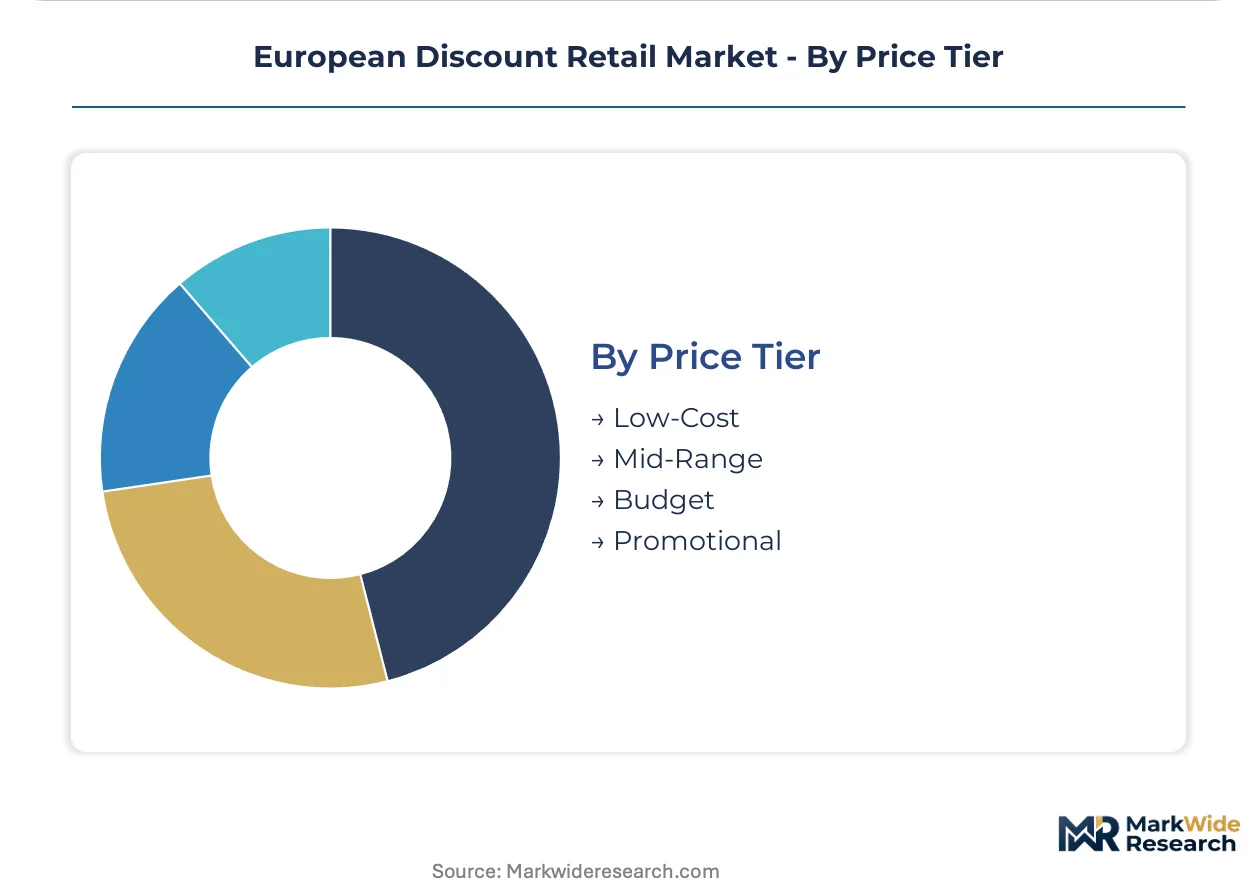
Price Tier:
Tier positioning determines supplier negotiation leverage and margin structure.
- Low-Cost:Permanent everyday low pricing without promotional cycles defines hard discount positioning. German supply-base efficiency undercuts local incumbents in Polish market entry.
- Mid-Range:Slightly elevated quality tiers capture consumers trading up within constrained budgets.
- Budget:Extreme value positioning minimizes service elements and fixture investment.
- Promotional:Temporary price reductions contradict core discount format principles and see limited deployment.
Low-cost tiers dominate transaction volume while mid-range positioning gains traction in Iberian and Balkan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between Western Europe's mature private-label markets and Eastern Europe's emerging hard-discount adoption. Polish and Romanian shoppers prioritize permanent low pricing over promotional hunting, while Iberian consumers demonstrate stronger bakery-led format loyalty.
Germany
Bavarian and Baden-Württemberg manufacturers anchor the supply base for core private-label volume. The Federal Environment Agency's packaging directives force laminated packaging redesign for dry groceries. Berlin and Hamburg concentrate format experimentation with autonomous shelf-scanning robotics deployment.
Poland
Warsaw drives basket-size expansion among urban millennials consolidating weekly shopping trips. REACH chemicals regulation compliance costs favor large-scale private-label formulators with dedicated regulatory affairs teams. Łódź and Kraków register concentrated new store openings from German supply-base entrants.
Romania
Bucharest exhibits the fastest format-switching incidence in household panel data as convenience-oriented formats capture time-pressed families. EU Green Deal packaging mandates compress format economics and force SKU rationalization. Cluj-Napoca and Timișoara remain underpenetrated by organized discount formats.
Spain
Iberian markets face accelerated compliance timelines for single-use plastics directives relative to Central European counterparts. Bakery-led traffic generation commands margin premiums and differentiates against online grocery. Barcelona and Madrid validate model transfer from Portuguese consumer patterns.
Portugal
Fresh and ready-meal sections expand to capture urban consumers consolidating weekly shopping into single destination trips. ESG-mandated institutional capital flows toward early CSRD reporting alignment. Lisbon and Porto concentrate purchasing power for private-label penetration in compact formats.
European Discount Retail Market Vendor Landscape
Capability concentration sits with German supply-base operators; scale advantage sits with Eastern European format replicators. The vendor base organizes around three tiers: hard discounters with captive private-label supply, regional specialists with extreme SKU rotation models, and emerging entrants leveraging AI-driven demand forecasting. Consolidation pressures intensify as REACH compliance costs exclude smaller competitors from shelf space. Dominant competitive moves span geographic expansion into Romanian secondary cities and backward integration into bakery production.
Within the hard-discount tier, Aldi and Lidl exemplify divergent competitive approaches to Eastern European market entry. Aldi leverages German supply-base efficiency to undercut local incumbents in Poland. Lidl sustains private-label dominance across Iberia and the Balkans through traffic-generating bakery operations. Action occupies a distinct position with extreme SKU rotation in non-food general merchandise, anchoring margin performance through rapid inventory clearance models.
| Leading Market Players |
|---|
| Lidl |
| Biedronka |
| Tedi |
| Penny |
| Netto Marken Discount |
| Action |
| Mercadona |
| X5 Retail Group |
| Aldi |
| Others |
Supply Flow & Price Mechanics
German supply-base concentration determines both pricing tier spreads and supply chain shape across European hard discount retail. Bavarian and Baden-Württemberg manufacturers anchor core private-label volume, compressing margin recovery timelines while forcing Eastern European entrants to absorb transport premiums or localize sourcing.
Pricing Analysis
Polish and Romanian markets exhibit wider spreads between entry-price and quality-tier SKUs than Iberian counterparts. Three-tier pricing structure across premium, standard, and economy levels reflects brand-equity trade-offs and private-label penetration depth. Price differentiation hinges on bakery-led traffic generation and fresh-section investment. Cost-conscious shoppers in Eastern Europe drive pricing pressure downward as they consolidate weekly trips into single destinations.
Supply Chain Analysis
REACH chemicals regulation acts as an export-control regime limiting flows from smaller private-label formulators lacking dedicated regulatory affairs teams. Bavarian manufacturers, Polish distribution centers, and Romanian secondary cities anchor geographic supply concentration. Raw material dependencies span laminated packaging substrates, refrigeration gases, and ambient grocery commodities. Single-source vulnerability concentrates in German supply-base relationships. Distribution runs through Poland and Romania toward underpenetrated Eastern European secondary cities.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Urban millennial consolidation of weekly shopping into single destinations fragments addressable demand across format types. This demand-side shift creates niches for bakery-led differentiation and compact-format replication in secondary cities.
For Market Incumbents: Pre-empt margin compression by backward integration into captive bakery production and cold-chain infrastructure. German supply-base efficiency must extend into Polish and Romanian distribution center automation to defend against local cost arbitrage. REACH compliance investments should exclude smaller competitors from shelf space.
For New Entrants and Emerging Players: Build out presence in Cluj-Napoca and Timișoara where organized discount penetration remains thin. Romanian secondary cities offer the most penetrable geography. Go-to-market positioning should emphasize fresh-section investment and bakery-led traffic generation validated in Portuguese patterns.
For Investors and Strategic Acquirers: EU Green Deal packaging mandates reshape the acquisition landscape by elevating compliance costs for mid-scale private-label formulators. Long-term viability favors targets with established regulatory affairs capacity and laminated packaging redesign capabilities. Watch for accelerated Iberian compliance timelines as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Bakery Production Integration | In-store bread commands margin premiums and differentiates against online grocery in Bucharest and Budapest. |
| Distribution Center Automation | Machine learning deployment in Polish and Romanian hubs compresses inventory carrying costs for ambient categories. |
| REACH Compliance Investment | Regulatory affairs capacity excludes smaller formulators from shelf space across Eastern European markets. |
| Secondary City Expansion | Cluj-Napoca and Timișoara remain underpenetrated by organized discount formats with sufficient purchasing power. |
| CSRD Reporting Alignment | Early sustainability disclosure compliance attracts ESG-mandated institutional capital to Iberian operators. |
Methodological Framework
Initial hypotheses were tested against primary input from discount chain category managers, private-label procurement directors, and refrigeration logistics specialists and refined through secondary validation. Store operations heads and EU regulatory compliance officers provided operational detail. Secondary sources encompassed customs records for cross-border private-label flows, ECHA REACH registration databases, and CSRD disclosure filings. Bottom-up store-level modeling and top-down market sizing were triangulated.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions spanned product velocity tiers, distribution channel cost structures, customer price sensitivity clusters, and regional regulatory compliance clusters. CAGRs were derived from trend extrapolation against demographic and format-penetration benchmarks. Forecast inputs incorporated urban millennial density metrics and EU Green Deal implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by German supply-base entrants into Romanian secondary cities would shift outcomes. Material shifts in REACH enforcement intensity or EU AI Act surveillance rule interpretation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
Electronics Retailing Market
Retailing
Furniture Rental Service Market
Retailing
Philippines Retail Industry Market
Retailing
Floor Displays Market
Retailing
Retail Vending Machine Market
Retailing
In Store Signage Market
Retailing
Home Shopping Market
Retailing
Gift Baskets Market
Retailing
Global Food and Non-Food Retail Market
Retailing
Department Stores Market
Retailing
Out-Door Signage Market
Retailing
Consumer Shopping Cart Market
Retailing
Out Store Signage Market
Retailing
Clothing Retail Market
Retailing
Consumer Products and Retail Market
Retailing
Singapore Gifting Market