
 France Vegan Cosmetics Market | 2026-2036
France Vegan Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
France Vegan Cosmetics Market Insights
The gap between premium vegan lines and mass-market alternatives is realigning shelf positioning across French retail. L'Oreal SA leverages its formulation infrastructure to scale certified vegan SKUs across multiple price tiers. Lamazuna anchors the solid-format niche with waterless products that reduce preservative complexity. Refeel Naturals differentiates through hyper-local sourcing of botanical actives from Provence cooperatives.
France vegan cosmetics encompass beauty and personal care products formulated without animal-derived ingredients, animal testing, or byproducts, typically relying on plant oils, mineral pigments, and biotechnological substitutes to achieve functional equivalence with conventional formulations. These products serve consumers seeking ethical alignment between purchase decisions and animal welfare values, often carrying third-party certifications from bodies such as Leaping Bunny or Vegan Society. Skincare dominates current revenue pools due to higher per-unit pricing and repeat purchase frequency, while fragrance represents the fastest-expanding category as alcohol-free and botanical extraction methods mature. Online retail channels capture growing volume share, though pharmacies sustain margin premiums through dermatological credibility and trained consultation.
ANSM enforces cosmetic safety assessments under the EU Cosmetics Regulation, while ECHA administers REACH restrictions on allergenic and persistent chemicals that directly affect vegan formulation choices. The EU Green Deal accelerates biodegradable packaging mandates and carbon footprint disclosure, reshaping supplier qualification criteria for brands seeking French market access. Stakeholders must monitor evolving certification harmonization between national organic labels and international vegan standards to avoid consumer confusion and compliance duplication.
Market Dynamics
EU Green Deal packaging mandates and REACH chemical restrictions are forcing simultaneous reformulation and supply chain reconfiguration across French vegan cosmetics, compressing timelines for brands dependent on conventional petroleum-derived inputs and single-use plastics.
Growth Catalysts
- EU Green Deal biodegradability mandates:Packaging suppliers must pivot to plant-based films and molded fiber, creating procurement pull for biopolymer innovators serving Paris-based formulation houses.
- Pharmacy channel dermatological credibility:Trained consultation drives repeat purchase frequency for sensitive-skin vegan lines, anchoring margin premiums unavailable through mass retail.
- Biotechnological active substitutes:Lab-grown ceramides and fermented squalane achieve functional parity with animal-derived equivalents, removing performance gaps that previously constrained category expansion.
Market Restraints
- Organic rosehip and jojoba price volatility:Climate stress on Moroccan and Argentine growing regions compresses gross margins for brands with fixed retail price commitments.
- Single-source dependency for glass packaging:Three Italian furnaces supply majority of premium cosmetic flacons, creating vulnerability to energy cost spikes or logistics disruption.
- Preservative efficacy gaps in waterless formats:Solid shampoo and conditioner bars face microbial stability challenges that extend stability testing timelines beyond conventional liquid equivalents.
Strategic Opportunities
- Provence cooperative vertical integration:Direct sourcing contracts with lavender and immortelle distilleries in Alpes-de-Haute-Provence enable traceability narratives and input cost control unavailable to competitors reliant on spot markets.
- Refill station network expansion:Independent zero-waste retailers in Lyon and Marseille pilot returnable-container systems that bypass conventional packaging cost structures entirely.
- CSRD-aligned carbon footprint disclosure:Early compliance with corporate sustainability reporting requirements positions brands for institutional procurement channels and B2B white-label contracts.
Industry Challenges
- Cosmetovigilance reporting capacity:ANSM adverse event notification requirements demand pharmacovigilance expertise scarce among indie brands, forcing outsourcing to specialized consultancies at fixed cost burdens.
- Multi-certification audit fatigue:Simultaneous pursuit of Vegan Society, Leaping Bunny, and COSMOS-Organic labels creates documentation redundancy and inspector scheduling conflicts.
- Legacy ERP integration with batch-level traceability:Existing inventory systems lack granularity for ingredient origin tracking required by EU deforestation-free supply chain regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Vegan Cosmetics Market |
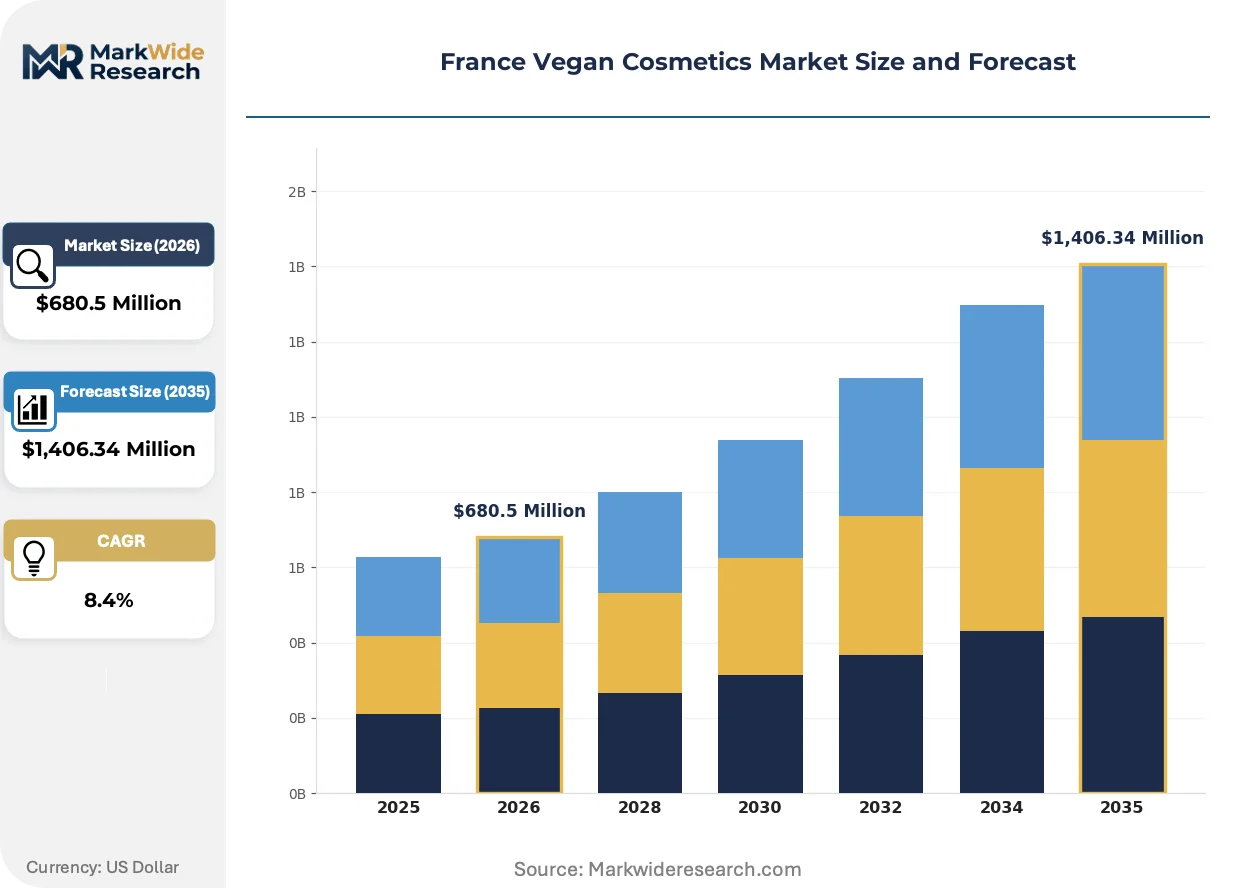
| Market Size in 2026 | $680.5 Million |
| Market Size in 2035 | $1,406.34 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Haircare, Fragrance Formulation: Creams, Serums, Oils, Gels Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies Customer Type: Millennials, Gen Z, Eco-conscious Consumers, Professionals |
| Companies Covered | La Canopée, Arbonne International, L'Oreal SA, Fairglow, BYOME LABS, Jean-Charles Brosseau, Lamazuna, Refeel Naturals, LEONIA Paris, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Vegan Cosmetics Market Trends and Innovations
Biotechnology-derived actives and solid-format waterless delivery systems are displacing conventional petroleum-based formulations, while regulatory disclosure requirements reshape competitive positioning around transparency infrastructure rather than marketing claims alone.
Fermentation-produced squalane is converging with enzymatic extraction methods to deliver consistent molecular profiles independent of olive harvest variability. Mid-tier skincare brands in Île-de-France are adopting these inputs at accelerating pace, compressing the traditional two-year reformulation cycle into eight-month windows as stability data accumulates faster than heritage botanical sourcing permits.
REACH restrictions on microplastic-containing leave-on products force immediate reformulation of glitter, filler, and texture-modifying ingredients. The industrial consequence is a supplier qualification scramble toward cellulose-derived alternatives, with color cosmetics manufacturers facing the tightest compliance deadlines and responding through direct investment in biodegradable film-former production partnerships.
Ingredient origin transparency has shifted from marketing differentiator to pre-purchase screening criterion among pharmacy channel buyers in Paris and Bordeaux. Specialty retailers now replace generalist distributors for initial brand discovery, displacing the traditional Sephora-centric launch pathway for emerging vegan lines and concentrating early revenue in consultative environments where staff training investments justify higher wholesale margins.
France Vegan Cosmetics Market Segmentation
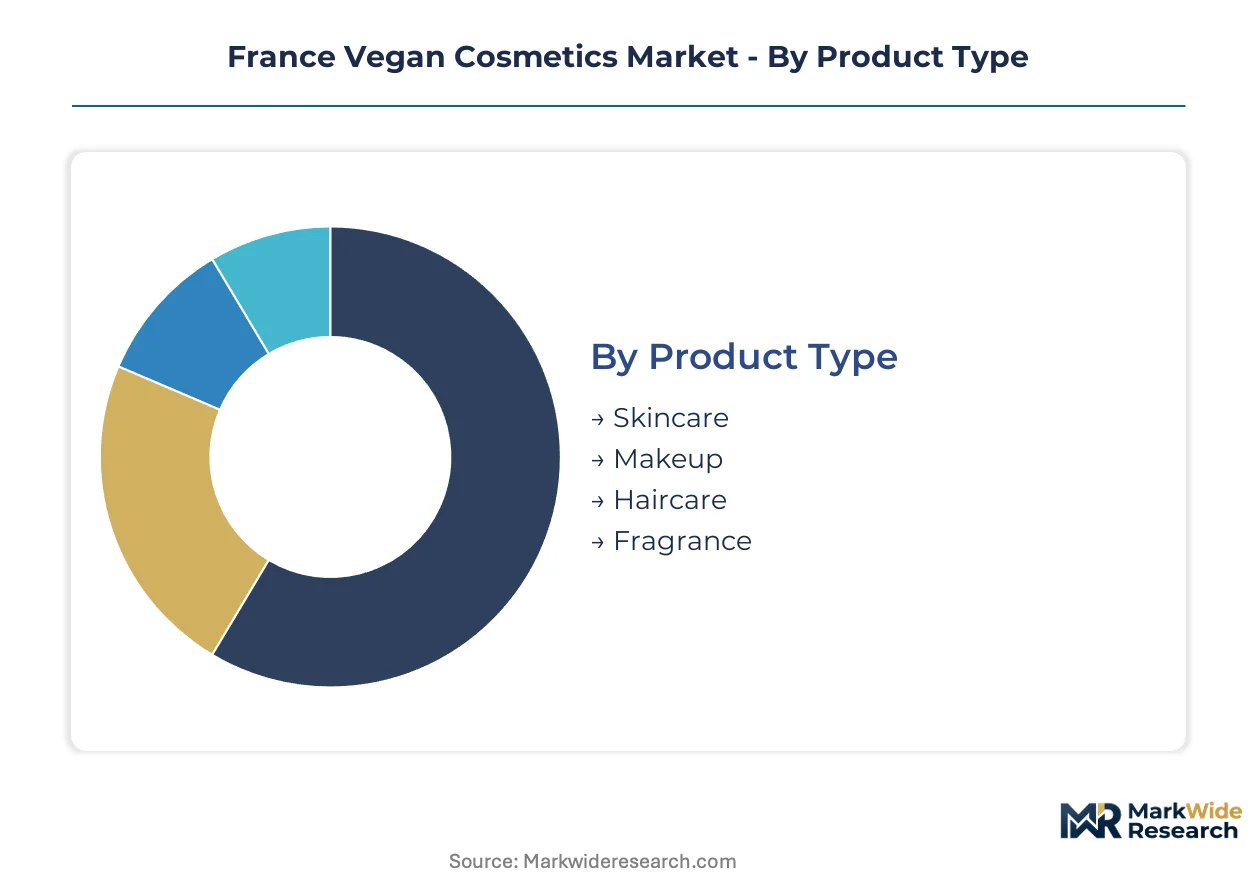
France vegan cosmetics segmentation reveals how formulation complexity and channel specialization create distinct margin profiles. Each dimension exposes where supply bottlenecks concentrate and which customer cohorts drive premium pricing.
Product Type:
Supply concentration clusters around Paris-based formulation labs serving distinct product categories with varying technical barriers.
- Skincare:High-complexity emulsions and active delivery systems dominate unit economics. Demand concentrates in Paris and Lyon pharmacy channels where trained consultation justifies premium positioning for ceramide-rich vegan moisturizers.
- Fragrance:Alcohol-free botanical extractions require specialized distillation partnerships with Grasse and Provence cooperatives. This category is climbing the fastest as biotechnical extraction methods mature and water-based formats gain shelf space in Sephora and Nocibé flagships.
- Makeup:Color stability and pigment dispersion challenge plant-derived binders. Indie brands source mineral oxides through specialized distributors serving the Île-de-France cluster.
- Haircare:Solid-format shampoo bars reduce preservative load but face microbial stability testing delays. Lamazuna and similar specialists anchor this niche through waterless manufacturing.
Today's leader: Skincare. Tomorrow's challenger: Fragrance.
Formulation:
Cost tier stratification separates mass-market accessible formats from professional-grade delivery systems requiring specialized equipment.
- Creams:Occlusive bases depend on shea and cocoa butter supply chains vulnerable to West African climate variability. Mass retailers in Auchan and Carrefour hypermarkets stock entry-price vegan creams with simplified emulsifier systems.
- Serums:High-actives, low-viscosity formats command the steepest price premiums. Demand concentrates among Gen Z consumers in Paris Marais district concept stores seeking fermented squalane and lab-grown peptide complexes.
- Oils:Single-ingredient or simple blends suit refill station models expanding in Lyon and Marseille zero-waste retailers. Jojoba and rosehip sourcing from Moroccan cooperatives creates traceability narratives.
- Gels:Water-based formats face REACH microplastic restrictions on conventional thickeners. Reformulation toward cellulose-derived alternatives accelerates among contract manufacturers serving mid-tier brands.
Creams and serums split the margin pool: creams capture volume, serums capture value per milliliter.
Distribution Channel:
Volume flows concentrate through consultative environments where staff training investments convert ethical preference into purchase completion.
- Online Retail:Direct-to-consumer platforms bypass wholesale margin stacking. Subscription models from Typology and similar brands build recurring revenue through algorithmic personalization.
- Specialty Stores:Curated assortments in Paris concept stores like Oh My Cream! and Bazar Bio enable discovery of indie vegan lines. Staff expertise justifies 40-60% wholesale margins unavailable through generalist retail.
- Supermarkets:Mass-market placement demands price compression and simplified certification claims. Carrefour and E.Leclerc private-label vegan ranges compete on shelf placement rather than ingredient innovation.
- Pharmacies:ANSM-regulated dermocosmetic positioning requires clinical testing documentation. Pierre Fabre and similar houses leverage this channel for sensitive-skin vegan lines with pharmacy-exclusive SKUs.
Pharmacies defend the premium tier. Online retail is gaining share fastest among acquisition channels.
Customer Type:
Application intensity varies by professional requirement versus personal use, with distinct certification sensitivity thresholds.
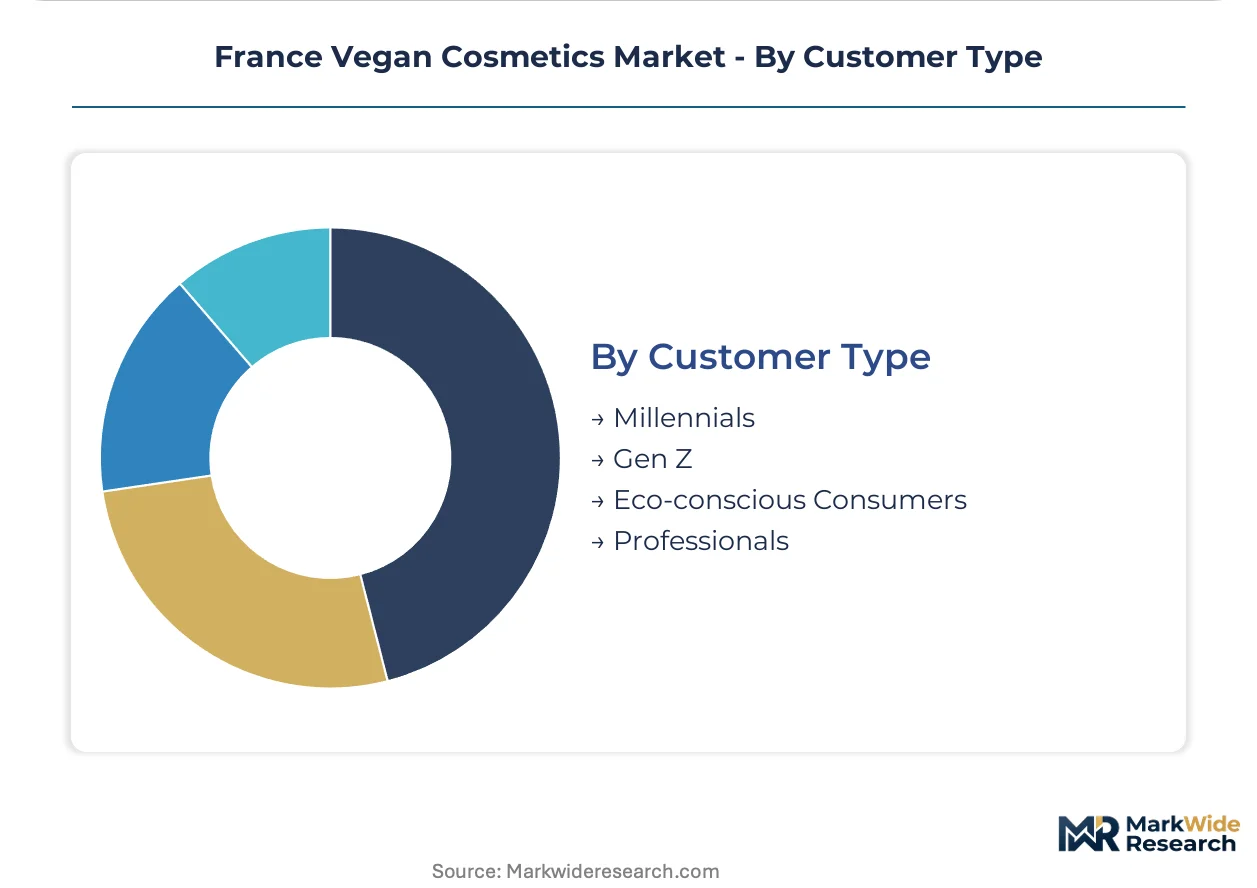
- Millennials:Established purchasing power drives pharmacy channel loyalty for anti-aging vegan actives. This cohort prioritizes COSMOS-Organic and Leaping Bunny co-certification.
- Gen Z:TikTok-discovered brands and solid-format preferences reshape demand toward waterless, packaging-minimal products. Refill station adoption concentrates among this demographic in university cities.
- Eco-conscious Consumers:Carbon footprint and biodegradability claims override price sensitivity. CSRD-aligned disclosure requirements from the EU Green Deal resonate strongly with this segment's pre-purchase screening.
- Professionals:Makeup artists and spa operators require bulk formats with consistent batch performance. B2B procurement channels demand stability documentation exceeding retail consumer requirements.
Millennials anchor current revenue. Gen Z is expanding most quickly as their disposable income matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France outpaces neighboring Germany in vegan fragrance innovation, while Italy's color cosmetics sector adopts plant-derived binders at slower velocity due to heritage formulation preferences.
Île-de-France
Paris anchors national demand through pharmacy channel density and concept store proliferation. ANSM cosmetic safety assessments enforce rigorous documentation standards for dermocosmetic positioning. The Marais district and 8th arrondissement concentrate indie brand flagships where trained consultation converts ethical preference into purchase completion.
Auvergne-Rhône-Alpes
Lyon's zero-waste retail network drives refill station adoption among university-age consumers seeking packaging-minimal formats. EU Green Deal biodegradability mandates reshape supplier qualification criteria for regional contract manufacturers. The city's Presqu'île district hosts independent retailers piloting returnable-container systems that bypass conventional packaging cost structures.
Provence-Alpes-Côte d'Azur
Grasse distillation heritage converges with biotechnical extraction methods for alcohol-free botanical fragrances. REACH restrictions on allergenic chemicals accelerate reformulation toward fermented actives. Alpes-de-Haute-Provence cooperatives supply lavender and immortelle to brands seeking traceability narratives and input cost control.
Hauts-de-France
Lille's logistics infrastructure supports e-commerce fulfillment for direct-to-consumer vegan brands targeting Belgian and Dutch cross-border demand. CSRD-aligned carbon footprint disclosure requirements reshape procurement screening for institutional channels. The Lille metropolitan area hosts distribution centers optimizing last-mile delivery for subscription-based skincare models.
Nouvelle-Aquitaine
Bordeaux pharmacy chains emphasize sensitive-skin vegan lines with COSMOS-Organic co-certification. ECHA REACH administration affects ingredient sourcing decisions for regional formulation labs. The city's Chartrons district concentrates specialty retailers displacing generalist distributors for initial brand discovery among eco-conscious consumer segments.
France Vegan Cosmetics Market Competitive Landscape
Top-tier vendors anchor mass-market scale, while indie specialists occupy premium niches through hyper-local sourcing and format innovation. The vendor base stratifies across multinational houses with formulation infrastructure, mid-tier brands with biotechnology partnerships, and solid-format pioneers with zero-waste positioning. Three archetypes dominate: pharmacy-anchored dermocosmetic players, direct-to-consumer subscription operators, and Provence-sourced artisanal houses. Competitive moves concentrate on biotechnology licensing for active substitutes and vertical control over cooperative supply chains.
Among established French houses, L'Oreal SA exemplifies scale-driven certification across price tiers, while Lamazuna occupies the solid-format niche through waterless manufacturing. Refeel Naturals represents the hyper-local sourcing archetype with Provence cooperative partnerships. These three anchors illustrate how formulation infrastructure, format innovation, and supply chain geography stratify competitive positioning within ANSM-regulated market access requirements.
| Leading Market Players |
|---|
| La Canopée |
| Arbonne International |
| L'Oreal SA |
| Fairglow |
| BYOME LABS |
| Jean-Charles Brosseau |
| Lamazuna |
| Refeel Naturals |
| LEONIA Paris |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal biodegradability mandates gate qualified supply for premium-tier pricing access, as brands lacking certified plant-based packaging or carbon disclosure infrastructure face exclusion from pharmacy channel procurement while mass-market competitors absorb compliance costs through simplified formulation architectures.
Pricing Analysis
Capacity additions in Italian glass furnace operations are reshaping price floors for premium flacon packaging, compressing margins for mid-tier brands locked into fixed retail commitments. Three-tier pricing structure across premium, standard, and economy levels separates pharmacy-anchored dermocosmetic lines from mass-market private-label ranges, with certification grade and volume scale as primary differentiation drivers. Cost compression in the standard tier is intensifying because Moroccan rosehip and Argentine jojoba spot markets face climate-induced supply stress. Eco-conscious consumers in Paris concept stores show least price sensitivity, while supermarket shoppers in Carrefour hypermarkets prioritize unit economics over ingredient provenance.
Supply Chain Analysis
Single-source vulnerability sits with three Italian furnaces supplying the majority of premium cosmetic glass, creating exposure to energy cost spikes that ripple through Île-de-France formulation houses. Raw material dependencies center on Moroccan jojoba cooperatives, Argentine rosehip estates, and Alpes-de-Haute-Provence lavender distilleries. Regulatory restriction risk concentrates in REACH microplastic bans affecting leave-on color cosmetics, forcing immediate reformulation of texture-modifying ingredients. Distribution runs through pharmacy channel wholesalers serving trained consultation environments, with direct-to-consumer platforms capturing growing volume share among Gen Z subscribers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France vegan cosmetics function as a geographic-arbitrage play where Provence cooperative sourcing costs undercut comparable Italian fragrance supply chains while meeting stricter ANSM documentation requirements than German mass-market alternatives.
For Market Incumbents: Hedge against biotechnology active substitution by licensing lab-grown ceramide production partnerships before functional parity eliminates heritage botanical premiums. Defensive consolidation through backward integration into Alpes-de-Haute-Provence immortelle cooperatives secures traceability narratives that emerging entrants cannot replicate. Channel control investments in pharmacy-exclusive SKU development protect margin pools threatened by direct-to-consumer subscription models. For New Entrants and Emerging Players: The price-point gap between premium pharmacy lines and economy supermarket tiers creates white-space opportunity in Lyon and Marseille refill station networks where packaging-minimal formats bypass conventional cost structures. Solid-format haircare represents the most penetrable application segment given microbial stability testing delays that deter established liquid-format specialists. Go-to-market execution should anchor in zero-waste retailer partnerships with trained staff conversion capability. For Investors and Strategic Acquirers: Roll-up economics work for Provence-sourced artisanal houses because ANSM pharmacovigilance compliance costs create fixed burdens that scale favorably across brand portfolios. Long-term viability in the five-to-ten year window hinges on biotechnology licensing positions for fermented active substitutes. Acquisition target archetype: mid-tier brands with existing COSMOS-Organic certification and underutilized cooperative supply contracts. The signal to watch is ECHA REACH restriction expansion beyond microplastics into additional preservative classes.| Strategic Initiative | Industry Significance |
|---|---|
| Provence Cooperative Backward Integration | Captive supply of lavender and immortelle from Alpes-de-Haute-Provence distilleries eliminates spot market exposure. |
| Biotechnology Licensing Partnership | Lab-grown ceramide and fermented squalane access removes performance gaps constraining category expansion. |
| Pharmacy Channel SKU Expansion | ANSM-regulated dermocosmetic positioning anchors margin premiums unavailable through mass retail. |
| Refill Station Network Buildout | Returnable-container systems in Lyon and Marseille bypass conventional packaging cost structures entirely. |
| CSRD-Aligned Carbon Disclosure | Early compliance positions brands for institutional procurement and B2B white-label contract access. |
Research Methodology
Direct dialogue with brand formulation directors, pharmacy chain category buyers, Provence cooperative supply managers, ANSM regulatory consultants, and zero-waste retail operators grounded qualitative insights in operational reality. Secondary validation drew from ANSM cosmetic safety filings, ECHA REACH restriction updates, EU Green Deal implementation guidance, customs records for jojoba and rosehip imports, and CSRD disclosure frameworks. Bottom-up SKU-level revenue estimates triangulated against top-down channel volume assessments.
Bottom-up modeling tracked individual brand revenue contributions across pharmacy, specialty store, online retail, and supermarket channels, while top-down analysis calibrated aggregate market expansion against EU cosmetics sector growth patterns. Segmentation dimensions included product type, formulation complexity, distribution channel margin structure, and customer generational cohort. CAGRs were derived from normalized growth trajectory fitting across the projection horizon, incorporating biotechnological active adoption curves and regulatory compliance timeline assumptions.
Caveats apply where ECHA REACH restriction expansion, climate stress on Moroccan and Argentine growing regions, or Italian glass furnace supply disruption could materially shift the outlook. Forecasts reflect documented assumptions about biotechnology cost reduction curves and generational purchasing power maturation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegan Cosmetics
Australia Vegan Cosmetics Market
Vegan Cosmetics
Organic Cosmetics Market
Vegan Cosmetics
Germany Vegan Cosmetics Market
Vegan Cosmetics
US Vegan Cosmetics Market
Vegan Cosmetics
China Vegan Cosmetics Market
Vegan Cosmetics
Canada Vegan Cosmetics Market
Vegan Cosmetics
Spain Vegan Cosmetics Market
Vegan Cosmetics
Italy Vegan Cosmetics Market
Vegan Cosmetics
Asia-Pacific Vegan Cosmetics Market
Vegan Cosmetics
Functional Cosmetics Market
Vegan Cosmetics
Global Probiotic Cosmetics Market
Vegan Cosmetics
Europe Vegan Cosmetics Market
Vegan Cosmetics
Chile Vegan Cosmetics Market
Vegan Cosmetics
Mexico Vegan Cosmetics Market
Vegan Cosmetics
South Korea Vegan Cosmetics Market
Vegan Cosmetics
Argentina Vegan Cosmetics Market