
 Liquid Lipstick Market | 2026-2036
Liquid Lipstick Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Lipstick Market Analysis
Clean beauty formulation chemistry is rewriting how liquid lipsticks achieve long-wear performance without traditional volatile silicones. L'Oréal Group leverages its integrated R&D pipeline to develop film-forming polymers that replace cyclomethicones. Estée Lauder anchors its prestige positioning through proprietary color-stay technologies developed at its innovation hubs. Fenty Beauty differentiates via inclusive shade-range chemistry that demands customized pigment dispersion processes.
Liquid lipstick is a cosmetic formulation combining saturated pigments with volatile solvents and film-forming agents that dry to a flexible, opaque layer, typically achieving wear times of eight to twelve hours through isododecane or dimethicone bases that evaporate upon application. The matte segment dominates volume due to consumer preference for transfer-resistant, high-impact finishes that reduce reapplication frequency. The online retail channel is expanding fastest as direct-to-consumer platforms enable virtual try-on algorithms and subscription replenishment models that reshape repurchase behavior. High-end brands command disproportionate margin pools through limited-edition releases and ingredient storytelling around hyaluronic acid or vitamin E enrichment.
The US Food and Drug Administration enforces color additive regulations under 21 CFR 73 and 74 that restrict permitted pigments in lip products, while the European Chemicals Agency administers REACH restrictions on cosmetic preservatives and fragrance allergens that force reformulation cycles. India's Central Drugs Standard Control Organization mandates manufacturing licenses and ingredient disclosure for imported cosmetics, adding compliance layers for brands entering that market. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as these compounds have historically enabled oil-repellency in long-wear lip products.
Market Dynamics
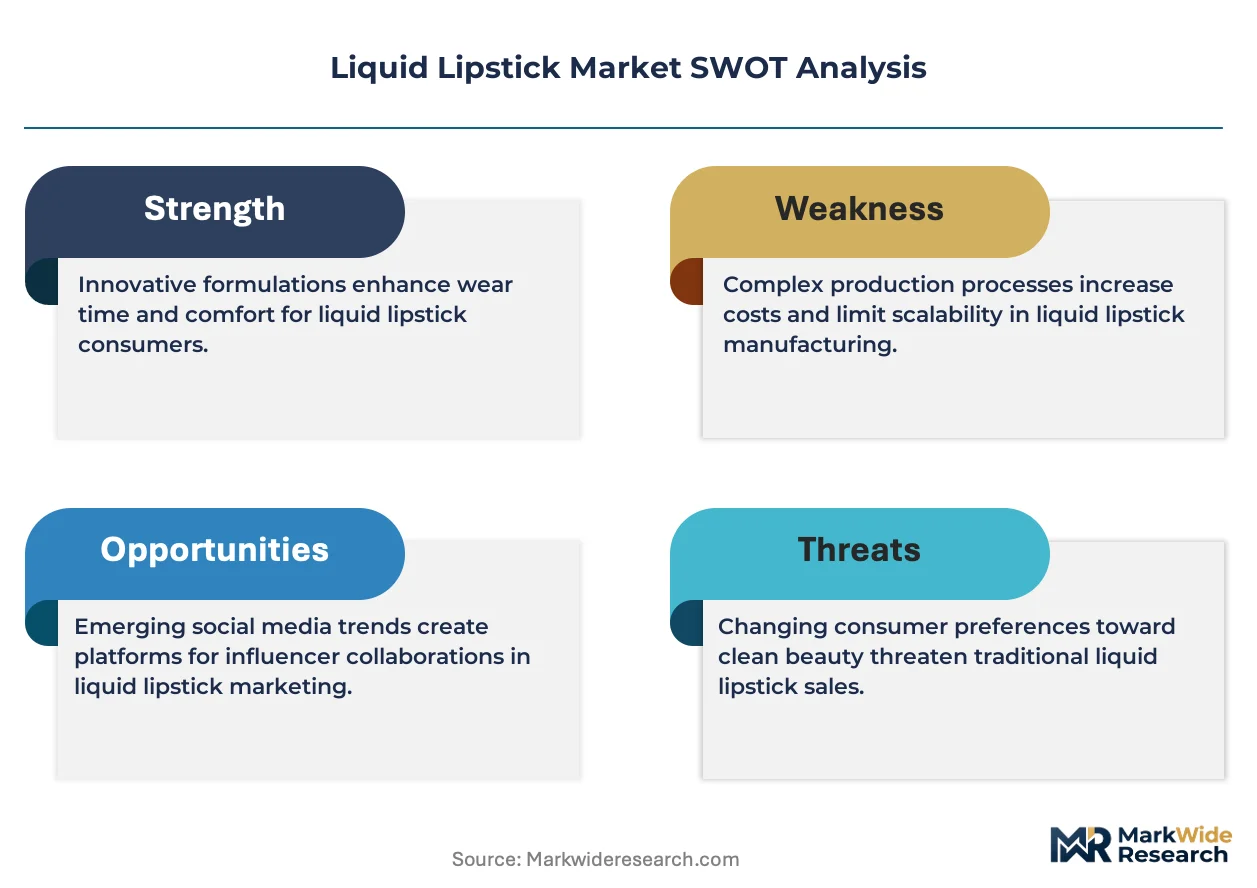
Clean beauty chemistry is forcing wholesale reformulation of long-wear liquid lipsticks as volatile silicones face regulatory phase-outs across major markets. Film-forming polymer R&D now determines competitive survival.
Growth Catalysts
- REACH ingredient restrictions:The European Union's tightening cosmetic safety standards accelerate clean-formulation innovation, creating first-mover advantages for compliant brands in premium channels.
- Professional makeup services:Salon chains and freelance artists standardize liquid lipstick in bridal and editorial workflows, driving bulk procurement and shade-range expansion.
- Isododecane evaporation chemistry:Advanced volatile solvent systems enable eight-to-twelve-hour wear claims that satisfy convenience-driven consumer expectations in United States and Western European markets.
Market Restraints
- Pigment input volatility:Synthetic iron oxide and titanium dioxide supply concentrates in Chinese manufacturing clusters, exposing brands to price swings and export control risks.
- Film-former technical ceiling:Current polymer technology limits flexibility in transfer-resistant formulas, causing cracking and discomfort that suppresses repurchase rates among mature users.
- FDA color additive friction:The United States Food and Drug Administration's 21 CFR 73 and 74 restrictions block novel pigment approvals, constraining shade innovation timelines to multi-year petition cycles.
Strategic Opportunities
- India CDSCO compliance pathway:The Central Drugs Standard Control Organization's manufacturing license requirements create barriers that reward early investment in localized production and ingredient disclosure systems.
- Virtual try-on convergence:Augmented reality shade-matching algorithms paired with direct-to-consumer replenishment subscriptions compress customer acquisition costs and lifetime value gaps.
- Per- and polyfluoroalkyl substance replacement:Regulatory momentum against PFAS in oil-repellency applications opens white space for bio-based barrier technologies in stain-resistant formulations.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise spanning polymer science, color chemistry, and regulatory compliance concentrates at legacy houses, constraining startup innovation velocity.
- Multi-jurisdiction certification timelines:Parallel FDA, REACH, and CDSCO approval processes extend product launch windows by eighteen to thirty-six months, freezing capital in pre-revenue development.
- Legacy shade-matching asset stranding:Existing in-store color consultation infrastructure requires costly retrofitting to integrate with digital skin-tone analysis tools now expected by online purchasers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Lipstick Market |
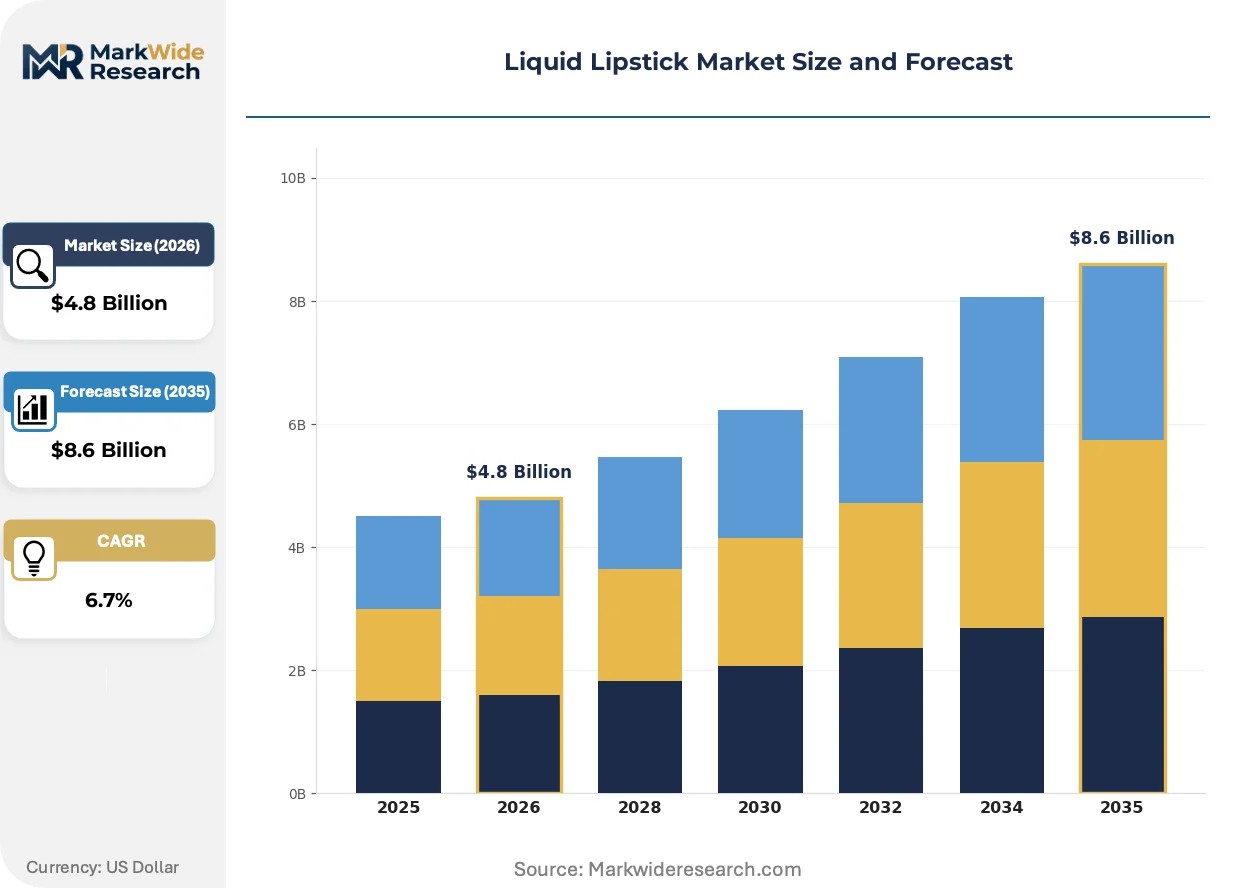
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Matte, Glossy, Satin, Metallic Customer Type: Teenagers, Young Adults, Professionals, Makeup Enthusiasts Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales Brand: High-End, Drugstore, Indie Brands, Luxury |
| Companies Covered | MAC Cosmetics, Shiseido, L'Oréal Group, Maybelline, Fenty Beauty, Chanel, Estée Lauder, Covergirl, DIOR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Lipstick Market Emerging Trajectories
Formulation chemistry, regulatory compliance architecture, and channel digitization are converging to restructure how liquid lipsticks reach consumers and justify premium positioning.
Artificial intelligence-driven skin-tone analysis is digitizing shade-matching precision previously confined to professional makeup artists. Direct-to-consumer platforms deploy these algorithms to reduce return rates and enable personalized subscription replenishment. The technology compresses the traditional color consultation value chain into automated mobile experiences.
The European Chemicals Agency's REACH restrictions on cyclomethicones and D4/D5/D6 siloxanes are forcing reformulation investments across long-wear portfolios. Brands must replace evaporative solvents with bio-based film-formers without sacrificing transfer resistance. Prestige manufacturers with captive R&D facilities absorb these costs faster than contract-dependent challengers.
Salon and freelance artist procurement is consolidating around professional-only distribution channels that bundle education, shade-matching tools, and volume pricing. These business-to-business platforms displace traditional wholesale relationships by embedding inventory management software. The shift concentrates purchasing power among multi-location service chains in United States metropolitan markets.
Liquid Lipstick Market Segmentation
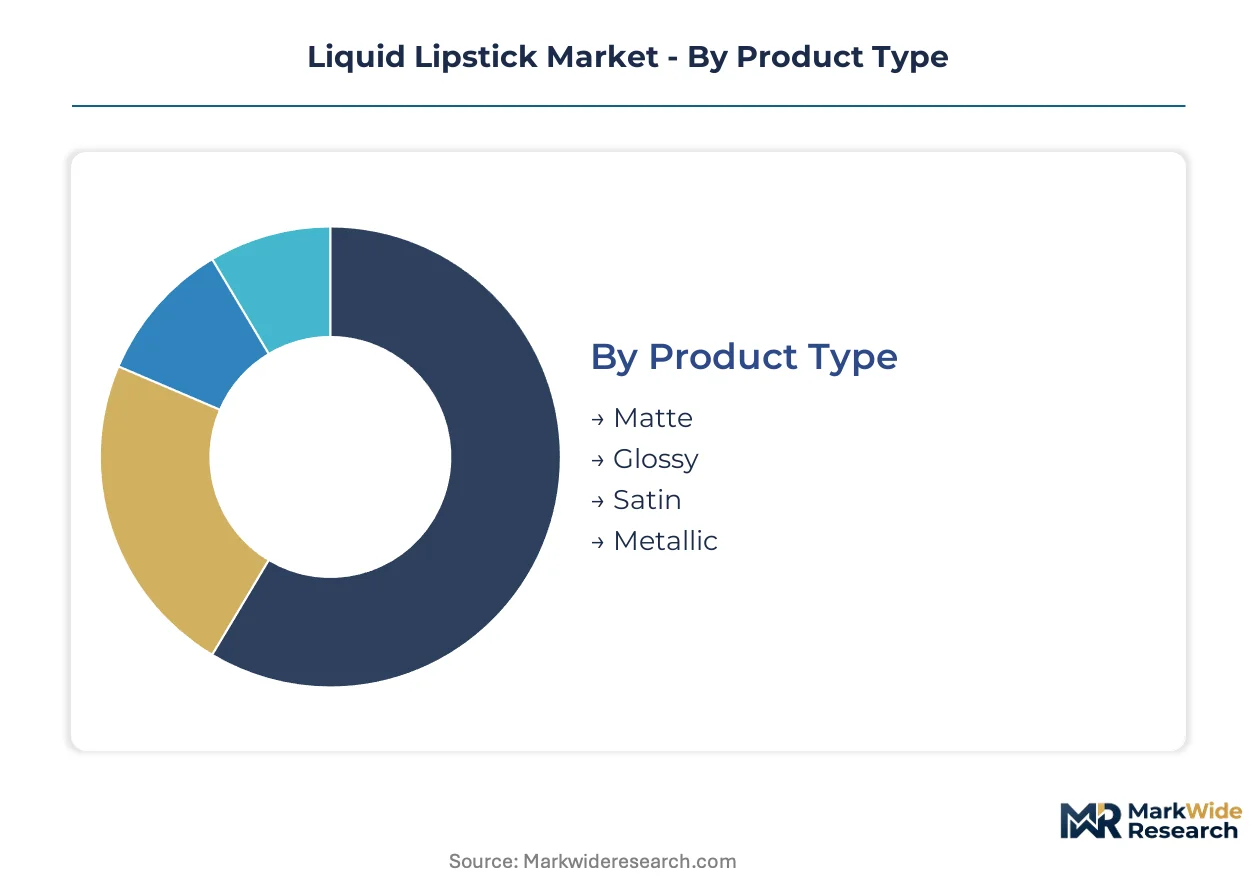
Liquid lipstick segmentation reveals how formulation chemistry, purchase context, and brand positioning create distinct margin pools. Understanding these divides explains why premium channels capture disproportionate value despite volume concentration elsewhere.
Product Type:
Finish chemistry determines wear performance, formulation cost structure, and consumer reapplication frequency across usage occasions.
- Matte:Dense pigment loads suspended in volatile isododecane bases dry to transfer-resistant films. Demand concentrates among professionals and bridal service providers in United States metropolitan markets seeking eight-to-twelve-hour durability without reapplication.
- Glossy:Emollient-rich formulations with lower pigment saturation prioritize comfort and dimensional light reflection. Young adult consumers in digital-native channels drive replenishment cycles through frequent shade experimentation and social media visibility.
- Satin:Hybrid polymer systems balance opacity with flexible wear, occupying mid-tier positioning between performance and comfort.
- Metallic:Pearlescent interference pigments in gel-suspension bases target editorial and entertainment industry applications with limited everyday adoption.
Matte commands the established base. The steepest expansion runs through Glossy.
Customer Type:
Purchase behavior, price sensitivity, and channel preference diverge sharply across generational and occupational cohorts.
- Young Adults:Digital-first discovery patterns prioritize virtual try-on compatibility and subscription replenishment models. Social platform influence accelerates trial of limited-edition releases and influencer collaborations.
- Professionals:Workplace-appropriate shade ranges and reliable wear performance dominate procurement criteria. This segment concentrates purchasing power in department store and specialty retail channels with consultation services.
- Teenagers:Entry-price-point sensitivity drives drugstore and mass-market online retail preference, with shade range breadth outweighing longevity claims.
- Makeup Enthusiasts:Collector behavior supports premium pricing for exclusive formulations and packaging, though absolute population remains constrained.
Young Adults anchor volume growth velocity. Professionals sustain margin concentration.
Distribution Channel:
Channel economics reshape how formulation claims reach consumers and how inventory risk distributes across the value chain.
- Online Retail:Direct-to-consumer platforms deploy AI shade-matching to reduce return rates and capture subscription recurring revenue. Algorithmic personalization compresses customer acquisition costs compared to physical retail.
- Specialty Stores:Sephora and Ulta Beauty anchor prestige brand visibility with in-store color consultation infrastructure that justifies premium price positioning.
- Department Stores:Declining foot traffic has shifted these locations toward gift-set destination purchasing and older demographic retention.
- Direct Sales:Avon and similar networks retain residual share in suburban and rural United States markets through representative relationships.
Specialty Stores defend the premium core. Online Retail is climbing the fastest.
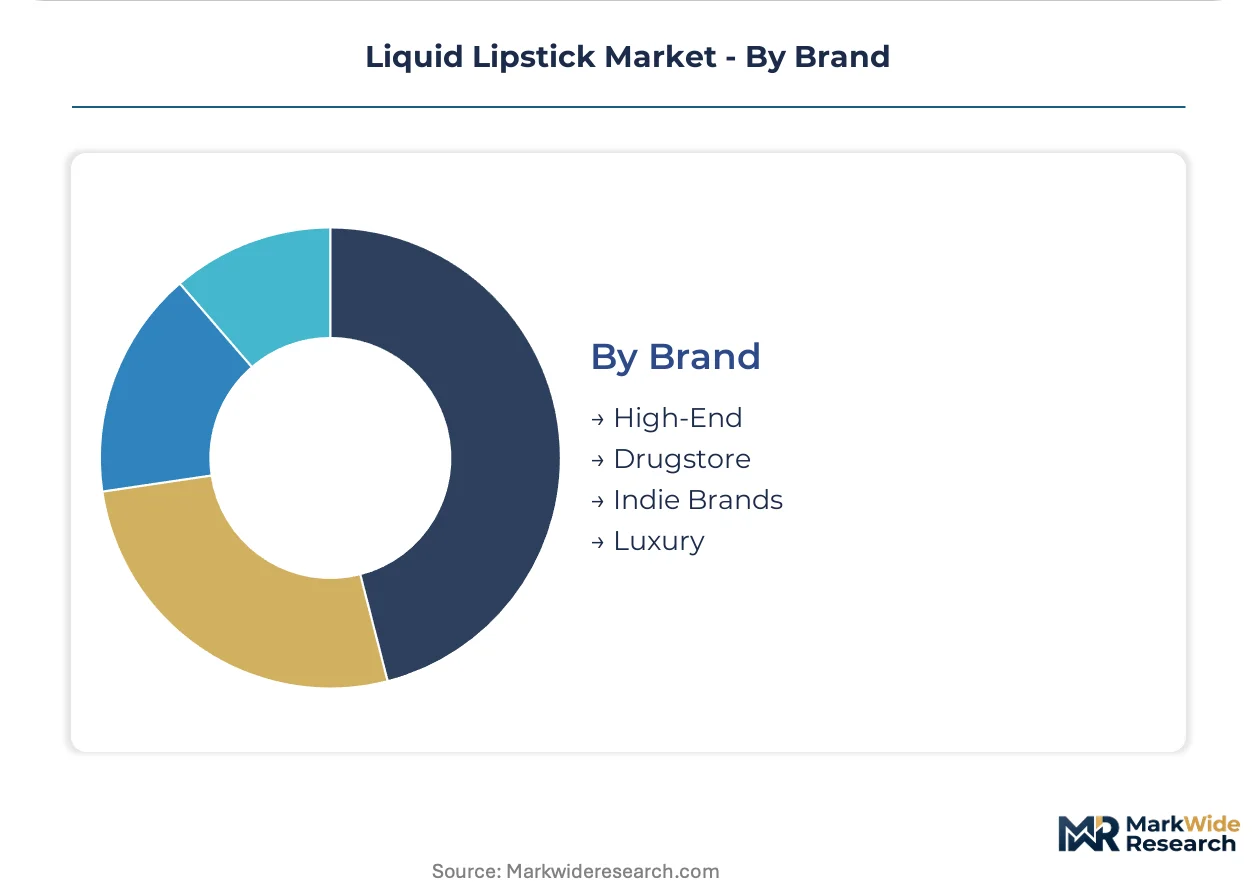
Brand:
Brand tier determines R&D access, ingredient storytelling latitude, and regulatory compliance cost absorption capacity.
- High-End:Captive innovation hubs and film-forming polymer patents support clean-beauty reformulation ahead of regulatory phase-outs. REACH-compliant portfolios open European premium channel access.
- Luxury:Limited production runs and packaging artistry justify price multiples, though absolute volume contribution remains modest.
- Drugstore:Contract manufacturing dependence constrains formulation flexibility, with compliance costs compressing margin structures.
- Indie Brands:Agile supply chains and direct community engagement enable rapid shade-range expansion, though scale limitations restrict polymer R&D investment.
High-End secures the profitability center. Indie Brands show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and French cosmetic manufacturers export reformulated liquid lipstick portfolios to United States premium retailers, navigating divergent regulatory frameworks across the Atlantic trade corridor.
United States
Professional makeup artists in Los Angeles and New York metropolitan markets drive bulk procurement for bridal and editorial workflows. FDA color additive regulations under 21 CFR 73 and 74 constrain novel pigment approvals to multi-year petition cycles. Miami-Dade County beauty service chains standardize liquid lipstick across standardized menu offerings.
Germany
REACH-compliant clean-beauty innovation concentrates in Hamburg and Düsseldorf corporate R&D facilities. ECHA restrictions on cyclomethicones and D4/D5/D6 siloxanes force wholesale solvent system replacement. Bavarian contract manufacturers absorb reformulation costs faster than smaller competitors.
France
Prestige heritage houses anchor global export volumes through Paris-based innovation hubs. ANSM enforces cosmetic ingredient disclosure requirements that exceed baseline EU standards. Île-de-France packaging artisans supply limited-edition release containers to worldwide distribution networks.
India
Maharashtra and Karnataka manufacturing clusters expand capacity to serve domestic premium channels. CDSCO manufacturing license mandates create compliance barriers that reward localized production investment. Mumbai salon chains adopt liquid lipstick for standardized bridal service protocols.
Japan
Metropolitan Tokyo consumers demonstrate preference for hybrid satin finishes balancing comfort with longevity. METI guidelines on cosmetic safety substantiation shape regional formulation claims. Osaka-based polymer suppliers develop bio-based film-forming alternatives to volatile silicones.
Liquid Lipstick Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base fragments between heritage conglomerates with captive R&D pipelines and agile indie challengers dependent on contract manufacturing. Three archetypes dominate: integrated beauty conglomerates with film-forming polymer patents, direct-to-consumer digital natives with algorithmic shade-matching, and professional-channel specialists bundling education with volume pricing. Competitive moves concentrate on clean-beauty reformulation ahead of regulatory phase-outs and augmented reality integration to compress customer acquisition costs.
Within the integrated conglomerate tier, L'Oréal Group and Estée Lauder occupy positions defined by captive innovation infrastructure and REACH-compliant portfolio depth. Shiseido represents the Asia-Pacific heritage anchor with polymer science capabilities concentrated in domestic facilities. Fenty Beauty exemplifies the digital-native archetype, leveraging inclusive shade-range chemistry to compress traditional color consultation timelines.
| Leading Market Players |
|---|
| MAC Cosmetics |
| Shiseido |
| L'Oréal Group |
| Maybelline |
| Fenty Beauty |
| Chanel |
| Estée Lauder |
| Covergirl |
| DIOR |
| Others |
Supply Flow & Price Mechanics
Pigment manufacturing clusters in China anchor cost structures across the liquid lipstick value chain, concentrating margin capture with brands that have secured long-term offtake agreements or captive dispersion capabilities. Film-forming polymer sourcing from German and Japanese specialty chemical suppliers creates tiered input cost profiles that downstream pricing stratifies across premium, standard, and economy levels.
Pricing Analysis
Prior-generation volatile silicone formulations command discount positioning against next-generation bio-based film-former portfolios. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with REACH-compliant clean-beauty SKUs sustaining margin premiums. Cost compression in mass-market tiers intensifies because contract manufacturers face raw material volatility without volume leverage. Teenage consumers exhibit highest price sensitivity, while makeup enthusiasts accept premium multiples for limited-edition releases.
Supply Chain Analysis
Cosmetic contract manufacturers in China, India, and Italy hold the majority of liquid lipstick filling and packaging capacity. Formulation chemistry draws from synthetic iron oxide deposits, titanium dioxide processing, and isododecane refining as critical input dependencies. Single-source vulnerability concentrates in pearlescent interference pigment supply from specialized German producers. Distribution runs through professional salon networks, direct-to-consumer platforms, and specialty retail channels with diverging inventory risk allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liquid lipstick penetration in professional makeup services represents early-cycle expansion, with bridal and editorial workflow standardization driving bulk procurement tailwinds across United States metropolitan markets.
For Market Incumbents: Entrench polymer R&D leadership through captive innovation hub investment ahead of REACH cyclomethicone phase-outs. Secure backward integration into film-forming agent supply to defend against contract-manufacturing cost pass-through. Lock in multi-year professional distribution exclusives with salon chains to forestall indie brand encroachment. For New Entrants and Emerging Players: Build out virtual try-on infrastructure as the primary go-to-market wedge, targeting young adult digital-native segments where algorithmic shade-matching compresses customer acquisition costs. White-space availability concentrates in India's CDSCO-compliant localized production, where manufacturing license barriers reward early facility investment. Subscription replenishment models offer the most penetrable revenue architecture for capital-constrained challengers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed indie brands that have scaled direct-to-consumer channels but lack polymer science capabilities for clean-beauty reformulation. Five-to-ten-year viability hinges on regulatory compliance cost absorption capacity rather than shade-range breadth alone. Monitor ECHA per- and polyfluoroalkyl substance restriction timelines as the critical inflection signal for portfolio repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Beauty Reformulation | REACH-compliant solvent replacement secures European premium channel access ahead of regulatory deadlines. |
| Professional Distribution Expansion | Salon chain partnerships bundle education with volume pricing to displace traditional wholesale relationships. |
| Virtual Try-On Deployment | AI shade-matching algorithms reduce return rates and enable subscription recurring revenue capture. |
| Localized Production Investment | CDSCO manufacturing licenses in India reward early compliance with barrier-protected market position. |
| Film-Former Patent Development | Proprietary polymer chemistry differentiates long-wear claims without volatile silicone dependency. |
Methodological Framework
A spread of perspectives from cosmetic chemists, professional makeup artists, salon chain procurement managers, and direct-to-consumer platform operators converged on the working assumptions. Primary interviews combined with secondary validation from FDA color additive filings, ECHA REACH restriction updates, CDSCO manufacturing license records, and customs trade data. Bottom-up segment sizing triangulated against top-down category spend estimates across the analysis window.
Demand-supply-balance framing anchored the analytical approach throughout the projection horizon. Segmentation dimensions modeled include finish chemistry, customer cohort, distribution channel, and brand tier. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and channel shift velocity. Forecast inputs incorporated polymer R&D pipeline maturity and professional service adoption curves specific to bridal and editorial workflows.
The forecast holds incumbent behavior within observed patterns; aggressive clean-beauty repositioning by heritage conglomerates or rapid PFAS regulatory acceleration would shift outcomes. Quarterly review of ECHA restriction timelines, CDSCO licensing velocity, and virtual try-on adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Israel Cosmetics Products Market
Cosmetics & Skincare
Face Cream Market
Cosmetics & Skincare
Global Cosmetic Jar Market
Cosmetics & Skincare
Beauty Sheet Mask Market
Cosmetics & Skincare
Marine Hyaluronic Water Cream Market
Cosmetics & Skincare
Scalp Scrub Market
Cosmetics & Skincare
Hand Cream Market
Cosmetics & Skincare
Israel Cosmetics Market
Cosmetics & Skincare
South America Cosmetics Products Market
Cosmetics & Skincare
Myanmar Skin Care Products Market
Cosmetics & Skincare
UK Eyelash Serum Market
Cosmetics & Skincare
Face Wash Market
Cosmetics & Skincare
Sweden Cosmetics Products Market
Cosmetics & Skincare
Color Cosmetics OEM and ODM Market
Cosmetics & Skincare
Sun Care Market
Cosmetics & Skincare
Eye Shadow Stick Market