
 North America Hair Conditioner Market | 2026-2036
North America Hair Conditioner Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hair Conditioner Market Insights
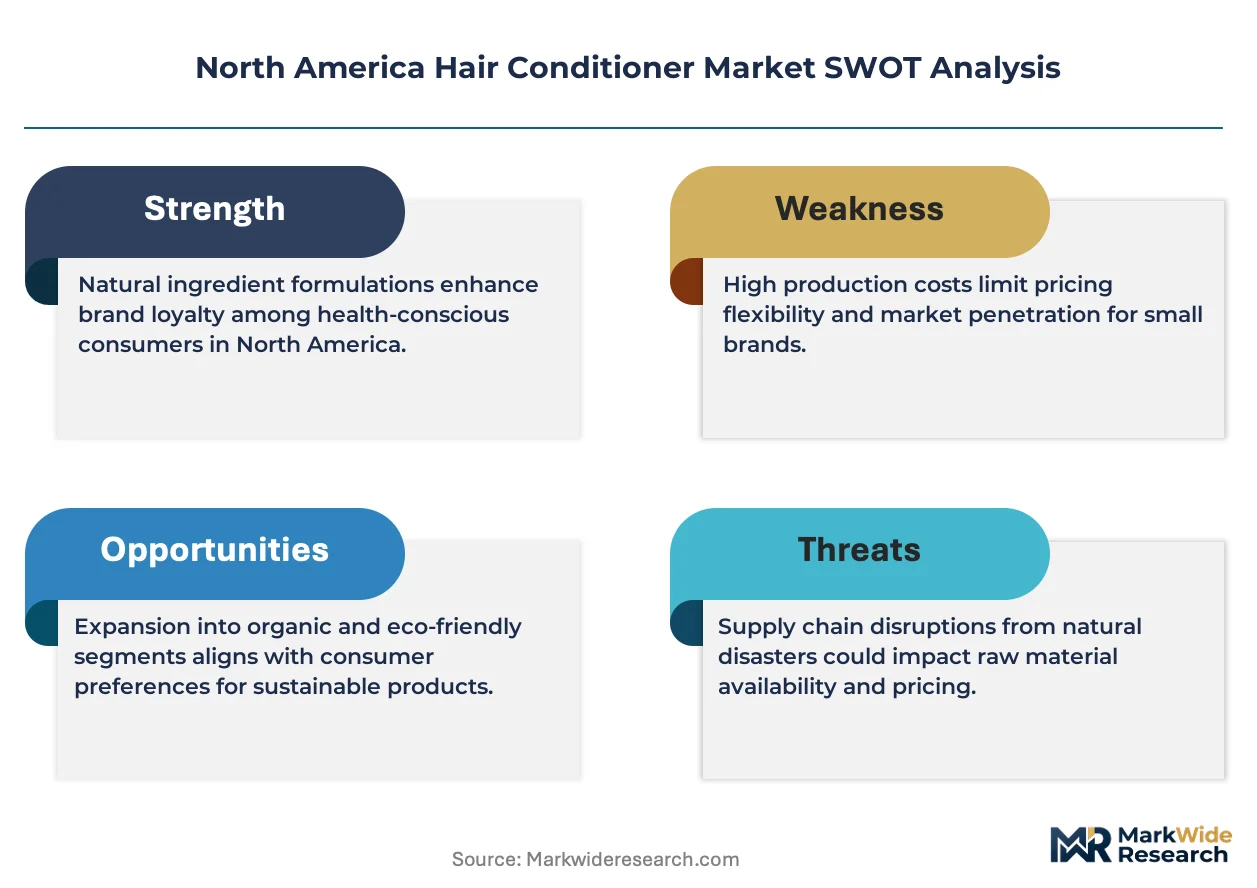
Cosmetic chemist talent scarcity is bifurcating the North America hair conditioner landscape into formulation-rich innovators and brand-dependent marketers. Procter & Gamble Company leverages captive R&D facilities to sustain pipeline velocity for salon-grade rinse-out conditioners. Unilever PLC anchors its North American position through deep conditioner specialization targeting coily and curly hair textures. L'Oréal S.A. competes via vertical control over raw botanical sourcing for its professional treatment lines.
North America hair conditioner encompasses viscous or creamy preparations applied post-shampoo to reduce friction, seal cuticle scales, and restore lipid balance, typically containing cationic surfactants, fatty alcohols, and silicones at pH 3.5–5.5. The product category serves both consumer home-use and professional salon backbar applications, with performance measured by combability reduction, tensile strength recovery, and subjective smoothness indices. Rinse-out formulations dominate unit volume through supermarket and mass retail ubiquity, though leave-in conditioners capture disproportionate margin in specialty and online channels where curl-specific and heat-protectant positioning commands premium pricing. Natural and organic ingredient claims concentrate growth in the clean beauty segment, while synthetic silicone alternatives face reformulation pressure from ingredient-conscious consumers scanning labels in-store.
The U.S. FDA governs cosmetic safety and labeling under the Federal Food, Drug, and Cosmetic Act, requiring ingredient disclosure that shapes consumer trust and reformulation costs for brands operating across state lines. California's Proposition 65 and the Safer Consumer Products regulations add state-level chemical restriction layers that exceed federal baselines, forcing nationwide compliance or SKU fragmentation. Health Canada and the PMRA administer parallel cosmetic oversight for the Canadian market, with divergent hot-list substances creating cross-border formulation complexity. Stakeholders must monitor pending federal fragrance allergen disclosure rules and state-level per- and polyfluoroalkyl substance bans that could disrupt existing silicone replacement chemistries.
Market Dynamics
Cosmetic chemist scarcity across the United States and Canada is splitting the North America hair conditioner landscape into formulation-capable innovators and brand-reliant marketers, forcing divergent capital allocation strategies.
Growth Catalysts
- California Proposition 65 enforcement:Ingredient-conscious consumers in Los Angeles and San Francisco scan labels for banned substances, accelerating clean beauty SKU proliferation.
- Salon backbar professionalization:Licensed cosmetologists in Texas and Florida recommend treatment-grade conditioners, converting retail buyers to premium rinse-out formats.
- Silicone-alternative biotechnology:Plant-derived emollients from Midwest agricultural feedstocks replace dimethicone in mass-market formulations.
Market Restraints
- Cationic surfactant supply concentration:Behentrimonium chloride production clusters with Gulf Coast petrochemical complexes, exposing formulators to hurricane-season disruption.
- FDA cosmetic labeling compliance costs:Small-batch manufacturers face reformulation expenses to meet federal ingredient disclosure mandates.
- Waterless concentrate substitution:Solid conditioner bars from indie brands capture shelf space in Pacific Northwest zero-waste retailers.
Strategic Opportunities
- Canadian Prairie provinces:Saskatchewan and Manitoba salons show underpenetrated demand for curl-specific deep conditioners targeting textured hair communities.
- Health Canada fragrance allergen pre-listing:Early compliance with anticipated disclosure rules positions brands for first-mover advantage in clean-label positioning.
- TikTok Shop distribution integration:Viral tutorial-to-purchase loops bypass traditional beauty retailer gatekeeping for Gen Z trial.
Industry Challenges
- Cosmetic formulation PhD pipeline gaps:University programs in New York and New Jersey produce insufficient cationic chemistry specialists for R&D expansion.
- Cross-border SKU harmonization friction:Divergent Health Canada and FDA hot-list substances force dual-formulation inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hair Conditioner Market |
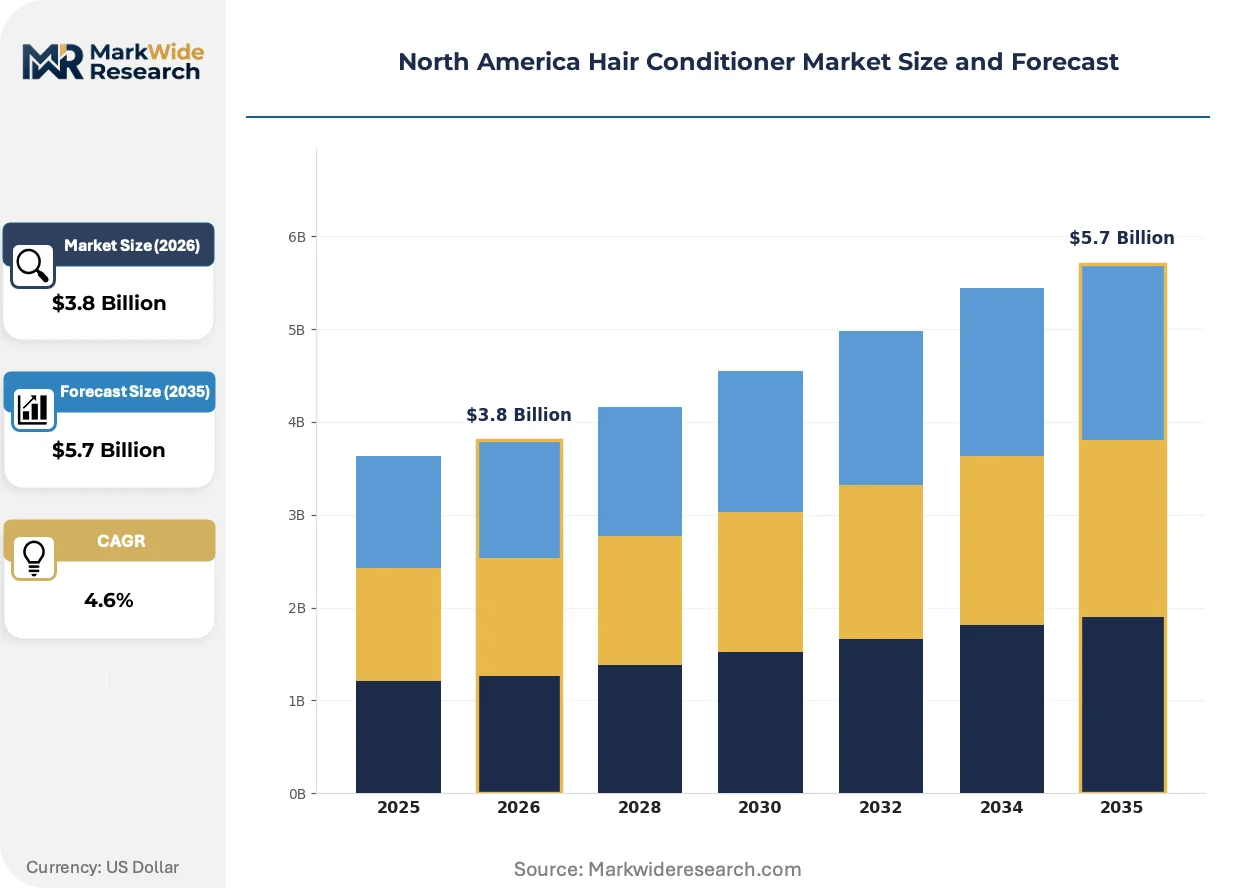
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leave-In, Rinse-Out, Deep Conditioner, Treatment Ingredient Type: Natural, Synthetic, Vegan, Organic Hair Type: Curly, Straight, Wavy, Coily Distribution Channel: Online, Supermarkets, Salons, Specialty Stores |
| Companies Covered | L'Oréal S.A., Unilever PLC, Procter & Gamble Company, Henkel AG & Co. KGaA, The Estée Lauder Companies Inc., Kao Corporation, Kenvue Inc., Church & Dwight Co., Inc., Coty Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hair Conditioner Market Trends and Innovations
Biotechnology-derived conditioning agents are displacing conventional petrochemical feedstocks across North American manufacturing facilities, while regulatory disclosure mandates reshape competitive transparency.
Biomimetic ceramide complexes are fragmenting the damage-repair segment by replicating 18-MEA lipid structures found in virgin hair cuticles. Specialty retailers in Manhattan and Toronto stock these formulations at 40% price premiums over standard silicone conditioners. The technology is fragmenting R&D investment away from quaternary ammonium compound optimization toward lipid-biotechnology partnerships.
The FDA's pending fragrance allergen disclosure rule is forcing reformulation timelines for products containing limonene and linalool. Manufacturers serving California and New York must pre-position compliant labeling before federal adoption. Professional salon lines face the steepest compliance burden due to complex botanical blends in treatment masks.
Subscription-based conditioner replenishment is compressing retail purchase cycles among curly-hair consumers in Atlanta and Houston. Specialty e-commerce platforms replace quarterly supermarket restocking with algorithmic texture-matched deliveries. This pattern concentrates most visibly in coily hair communities where product experimentation rates exceed straight-hair demographics by significant margins.
North America Hair Conditioner Market Segmentation
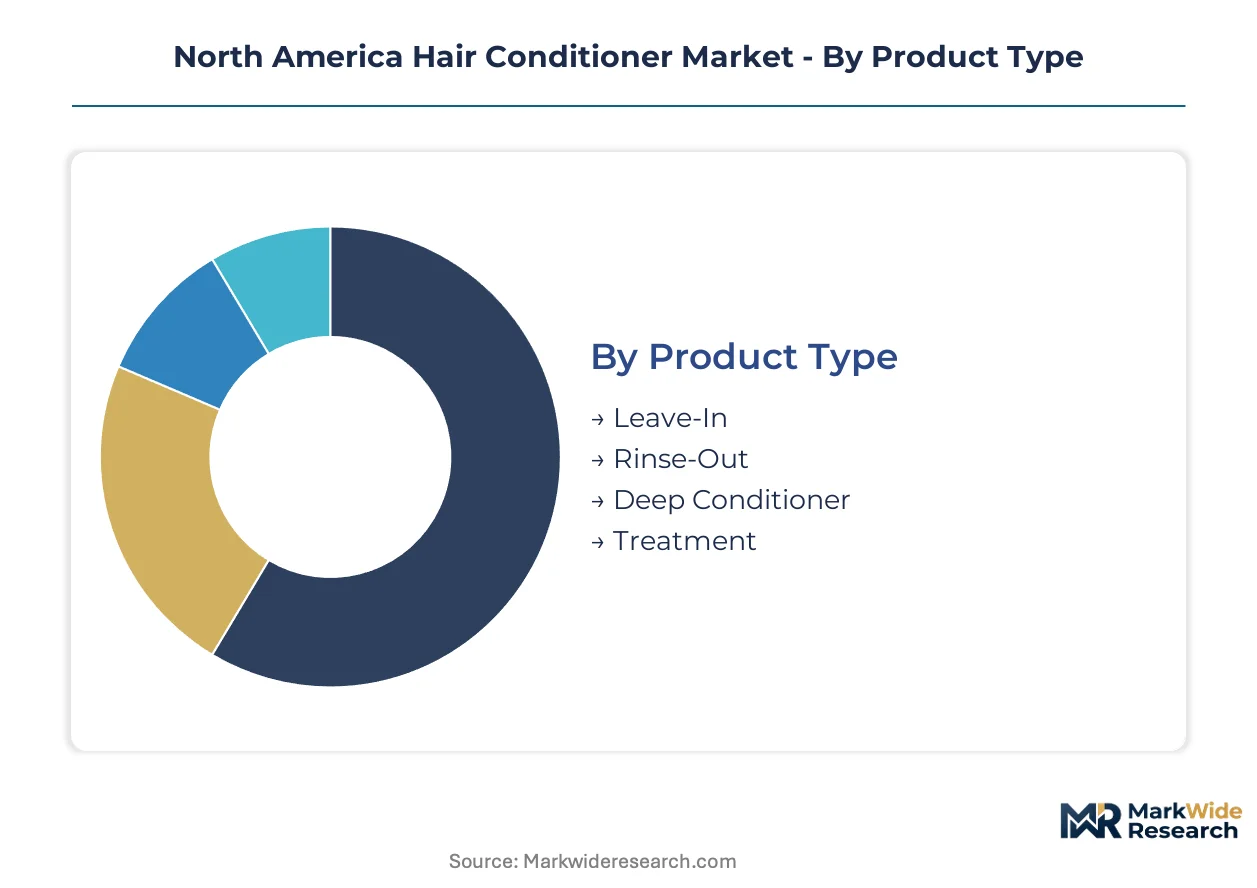
Conditioner formulations fragment across four intersecting dimensions that dictate regulatory exposure, margin architecture, and channel strategy. Each segmentation axis carries distinct compliance burdens and manufacturing constraints that reshape competitive positioning.
Product Type:
FDA labeling stringency varies by formulation chemistry and intended contact duration, with rinse-out and leave-in categories facing divergent substantiation requirements.
- Rinse-Out:Cationic surfactant-based formulations with pH 3.5–5.5 dominate supermarket and mass retail shelf space. California Proposition 65 enforcement drives reformulation away from flagged preservatives in Los Angeles and San Francisco distribution corridors.
- Leave-In:Lower-viscosity preparations with heat-protectant polymers command specialty retailer premiums in Manhattan and Toronto. TikTok Shop distribution integration accelerates trial among Gen Z consumers seeking curl-definition without rinse cycles.
- Deep Conditioner:High-cationic-density masks target coily hair texture recovery in Atlanta and Houston salons.
- Treatment:Professional backbar formulations with concentrated ceramide complexes serve licensed cosmetologists in Texas and Florida.
Rinse-Out handles the majority of throughput; Leave-In is the fastest mover on share.
Ingredient Type:
Raw material sourcing geography determines cost tier and regulatory pre-clearance burden, with Midwest agricultural feedstocks displacing Gulf Coast petrochemical derivatives.
- Natural:Plant-derived emollients from Saskatchewan and Manitoba agricultural processors replace dimethicone in mass-market lines. Health Canada fragrance allergen pre-listing compliance adds formulation lead time for cross-border SKUs.
- Synthetic:Behentrimonium chloride and silicone quaternary compounds remain cost-optimized for high-volume rinse-out production. Hurricane-season disruption risk at Gulf Coast petrochemical complexes elevates working capital requirements.
- Vegan:Certification-compliant formulations exclude animal-derived keratins and honey extracts, concentrating in Pacific Northwest zero-waste retail.
- Organic:USDA NOP or Canada Organic Regime certification commands 40% shelf price premiums in specialty Manhattan and Toronto stores.
Synthetic handles the majority of throughput; Natural is climbing the fastest on share.
Hair Type:
Texture-specific formulation R&D concentrates in New York and New Jersey university pipelines, with insufficient cationic chemistry specialists forcing capability gaps.
- Coily:Tight curl pattern conditioners require maximum cationic charge density for cuticle sealing. Subscription-based replenishment compresses purchase cycles in Atlanta and Houston more aggressively than other texture segments.
- Curly:Loose-to-medium curl definitions drive algorithmic texture-matched e-commerce platform growth. Product experimentation rates exceed straight-hair demographics significantly.
- Wavy:Lightweight conditioning balances volume retention with frizz control in humid Florida climates.
- Straight:Minimal conditioning requirements sustain economy-tier supermarket dominance with lowest per-unit margins.
Straight handles the majority of throughput; Coily is gaining share fastest.
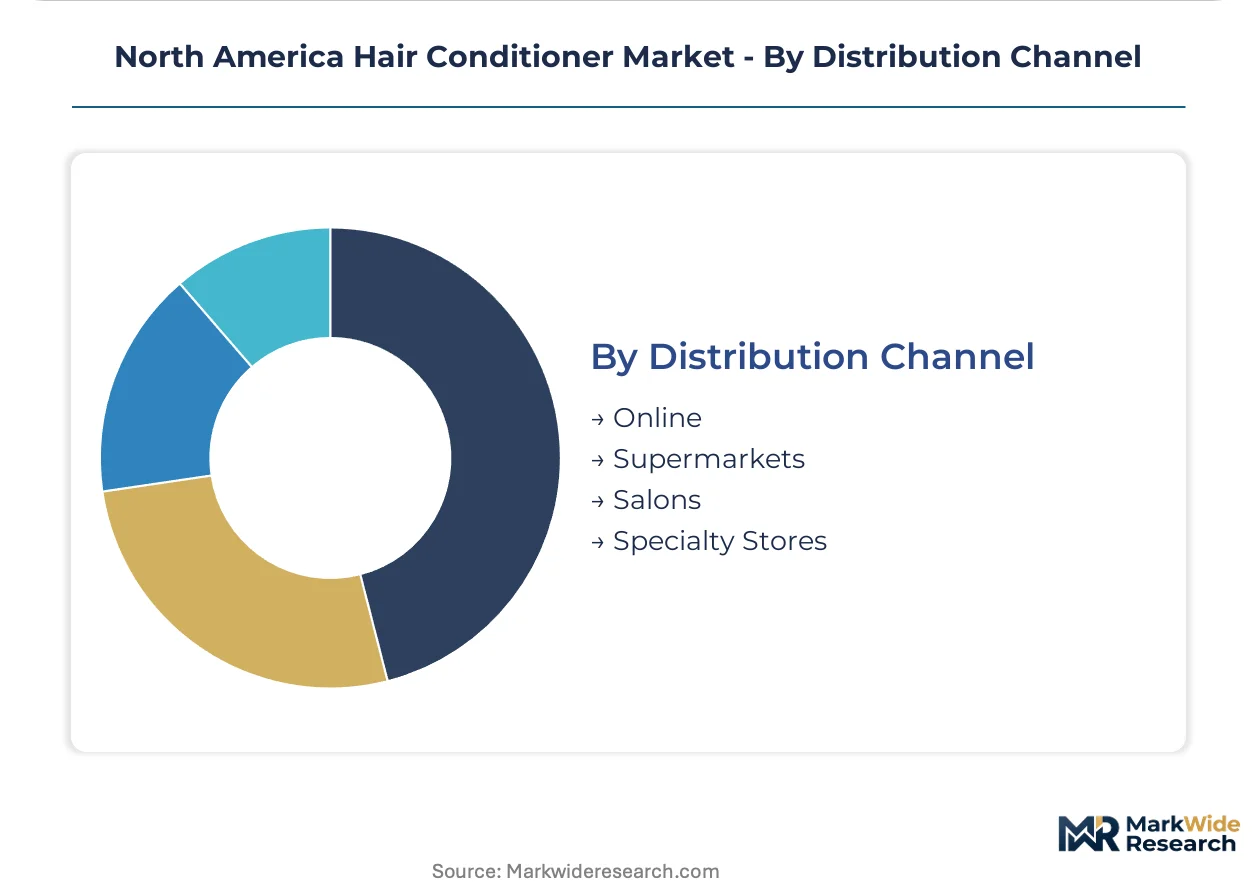
Distribution Channel:
Channel selection dictates margin capture and consumer education intensity, with professional recommendation converting retail buyers to premium formats.
- Supermarkets:Mass-market rinse-out ubiquity depends on slotting fee negotiations with national retail chains. FDA cosmetic labeling compliance costs burden small-batch manufacturers attempting shelf placement.
- Online:Algorithmic replenishment and TikTok Shop integration bypass traditional beauty retailer gatekeeping. Viral tutorial-to-purchase loops concentrate Gen Z trial in curl-specific communities.
- Salons:Licensed cosmetologist recommendation in Texas and Florida converts treatment-grade conditioner adoption. Professional backbar professionalization elevates perceived efficacy versus retail equivalents.
- Specialty Stores:Clean beauty SKU proliferation concentrates in California and New York where ingredient-conscious consumers scan labels in-store. Waterless concentrate substitution from indie brands captures Pacific Northwest zero-waste shelf space.
Supermarkets handles the majority of throughput; Online is expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA's cosmetic labeling requirements under the Federal Food, Drug, and Cosmetic Act anchor formulation standards across the dominant United States market, while Health Canada and the PMRA administer parallel oversight for cross-border compliance.
United States
California Proposition 65 enforcement drives clean beauty SKU proliferation in Los Angeles and San Francisco distribution corridors. The FDA's pending fragrance allergen disclosure rule forces reformulation timelines for products containing limonene and linalool. Licensed cosmetologists in Texas and Florida recommend treatment-grade conditioners, converting retail buyers to premium rinse-out formats.
Canada
Saskatchewan and Manitoba salons show underpenetrated demand for curl-specific deep conditioners targeting textured hair communities. Health Canada fragrance allergen pre-listing compliance adds formulation lead time for cross-border SKUs. Prairie province agricultural processors supply plant-derived emollients that replace dimethicone in mass-market lines.
Mexico
Mexico City Metro anchors mass-market conditioner distribution through national retail chain penetration. The country's national pharmaceutical regulator enforces cosmetic safety standards that align with USMCA trade facilitation. Northern border states concentrate manufacturing facilities serving duty-free export to Texas and California markets.
North America Hair Conditioner Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the North America hair conditioner market. Procter & Gamble Company, Unilever PLC, and L'Oréal S.A. control captive R&D facilities and vertical supply chains that sustain pipeline velocity. Three archetypes dominate: formulation-rich innovators leveraging cosmetic chemist talent, brand-dependent marketers relying on outsourced manufacturing, and professional salon specialists with treatment-grade positioning. Competitive moves concentrate on portfolio diversification into silicone-alternative biotechnology and strategic partnerships with Midwest agricultural feedstock suppliers.
Within the integrated leader tier, Procter & Gamble Company and Unilever PLC exemplify divergent specialization strategies. Procter & Gamble Company occupies a position anchored in salon-grade rinse-out conditioner development through captive research infrastructure. Unilever PLC sits within the deep conditioner specialization archetype targeting coily and curly hair texture segments. L'Oréal S.A. represents vertical control over raw botanical sourcing for professional treatment lines, distinguishing its competitive posture from brand-marketing-dependent challengers.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Unilever PLC |
| Procter & Gamble Company |
| Henkel AG & Co. KGaA |
| The Estée Lauder Companies Inc. |
| Kao Corporation |
| Kenvue Inc. |
| Church & Dwight Co., Inc. |
| Coty Inc. |
| Others |
Pricing and Supply Chain Analysis
Plant-derived emollient substitution for dimethicone simultaneously relocates sourcing toward Midwest agricultural processors and compresses margin structures for Gulf Coast petrochemical-dependent formulators. This input shift fragments pricing power across ingredient tiers while elevating working capital requirements for brands navigating hurricane-season supply disruption.
Pricing Analysis
Long-term offtake contracts with Prairie province agricultural processors anchor natural ingredient pricing for premium-tier conditioners, while spot-market cationic surfactant procurement exposes mass-market lines to Gulf Coast volatility. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with USDA Organic and Health Canada pre-listing compliance commanding 40% shelf premiums. Cost compression in synthetic silicone alternatives is intensifying because biotechnology scale-up lags demand growth. Salon backbar buyers show lowest price sensitivity, while supermarket economy-tier consumers drive hard volume negotiations.
Supply Chain Analysis
Gulf Coast petrochemical complexes constitute a chokepoint for behentrimonium chloride and silicone quaternary compound supply, exposing North American formulators to hurricane-season disruption. Raw material sourcing draws from United States agricultural feedstocks, Canadian Prairie province botanical processors, and Texas-Louisiana chemical manufacturing. Single-source vulnerability concentrates in cationic surfactant production clusters. Distribution runs through professional salon backbars, national retail chain DCs, and algorithmic e-commerce fulfillment centers serving texture-matched subscription replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America hair conditioner sits in early-cycle expansion as silicone-alternative biotechnology penetrates mass-market formulations and curl-specific segments attract new entrant investment.
For Market Incumbents: Secure captive R&D pipelines by acquiring cosmetic chemistry talent from shrinking university programs in New York and New Jersey. Backward integration into Midwest agricultural feedstock contracts defends margin position against Gulf Coast petrochemical volatility and biotechnology scale-up delays. For New Entrants and Emerging Players: Health Canada fragrance allergen pre-listing certification fast-tracks cross-border SKU harmonization, opening white-space penetration in Saskatchewan and Manitoba curl-specific deep conditioner demand. TikTok Shop distribution integration bypasses traditional beauty retailer slotting fee barriers for algorithmic texture-matched trial conversion. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed indie brands holding Pacific Northwest zero-waste retail shelf space and solid conditioner bar manufacturing capabilities. Monitor biotechnology partnership announcements as inflection signal for silicone-alternative formulation viability at mass-market scale.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone-Alternative Biotechnology Partnership | Midwest agricultural feedstock contracts displace Gulf Coast petrochemical dependency for cationic surfactant replacement. |
| Health Canada Pre-Listing Compliance Investment | Early fragrance allergen disclosure positioning captures first-mover advantage in cross-border clean-label SKU proliferation. |
| Salon Backbar Professionalization Program | Licensed cosmetologist recommendation in Texas and Florida converts retail buyers to premium treatment-grade formats. |
| TikTok Shop Distribution Integration | Viral tutorial-to-purchase loops bypass traditional beauty retailer gatekeeping for Gen Z curl-specific trial. |
| Cosmetic Chemist Talent Acquisition | University pipeline gaps in cationic chemistry specialization force competitive bidding for formulation-capable R&D staff. |
Research Methodology
Initial hypotheses were tested against primary input from cosmetic chemists, salon owners, retail category buyers, and agricultural feedstock processors and refined through secondary validation. FDA cosmetic labeling filings, Health Canada PMRA submissions, Nielsen retail audit data, and SEC 10-K disclosures anchored quantitative triangulation. Bottom-up volume modeling and top-down value reconciliation converged on segment-level estimates.
Variance decomposition across product type, ingredient sourcing geography, hair texture segment, and distribution channel isolates growth contribution by dimension. CAGRs were derived from modeled annual progression across the analysis window. Forecast inputs incorporated biotechnology scale-up curves, regulatory adoption timelines for fragrance allergen disclosure, and salon professionalization penetration rates by state.
Decision-makers should treat outputs as directional under base assumptions of sustained silicone-alternative R&D investment and stable Gulf Coast petrochemical supply; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as FDA fragrance allergen rulemaking and state-level per- and polyfluoroalkyl substance bans evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Slimming Cream Market
Beauty & Personal Care
Beauty Products Market
Beauty & Personal Care
GCC Male Grooming Products Market
Beauty & Personal Care
Loofah Bath Sponge Market
Beauty & Personal Care
United States Male Grooming Products Market
Beauty & Personal Care
Premium Cosmetics Market
Beauty & Personal Care
Shaving Foam Market
Beauty & Personal Care
Zero-Waste Shampoo Market
Beauty & Personal Care
Mass Beauty & Personal Care Products Market
Beauty & Personal Care
US Color Cosmetics Market
Beauty & Personal Care
Beard Oil Market
Beauty & Personal Care
Skin Care Luxury Cosmetic Market
Beauty & Personal Care
Organic Shampoo Market
Beauty & Personal Care
Facial Makeup Setting Spray Market
Beauty & Personal Care
Europe Professional Beauty Services Market
Beauty & Personal Care
Salon Products Market