
 Europe Hair and Skincare Market | 2026-2036
Europe Hair and Skincare Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hair and Skincare Market Insights
Capital-intensity divergence between mass-market manufacturers and premium R&D specialists is bifurcating competitive dynamics across the European landscape. L'Oréal S.A. leverages its integrated research infrastructure and brand portfolio depth to sustain innovation pipelines in dermocosmetics. Beiersdorf AG anchors its position through dermatological credibility and concentrated investment in skin barrier science. Unilever competes via scale efficiencies and broad distribution reach across multiple European retail channels.
Europe hair and skincare encompasses topical formulations for scalp and epidermal maintenance, including surfactant-based cleansers, emollient creams, and active-ingredient serums with specified pH ranges and dermatological tolerability profiles; these products serve consumer hygiene, aesthetic conditioning, and protective barrier functions across daily regimens. The ingredient-type dimension shows natural and organic classifications commanding margin premiums as clean-beauty preferences harden, while synthetic segments face reformulation pressure under evolving safety assessments. Distribution through specialty stores and salon channels captures higher per-unit value than mass retail, reflecting service-attached purchasing and professional recommendation dynamics.
REACH registration requirements, the EU Green Deal chemical sustainability framework, and the EU Cosmetics Regulation govern ingredient safety, environmental footprint disclosure, and market access across member states. ECHA substance evaluations and emerging microplastic restrictions are forcing reformulation investments and supply chain requalification. Stakeholders must monitor regulatory amendment timelines and pre-position alternative ingredient portfolios ahead of enforcement thresholds.
Market Dynamics
REACH substance evaluations and ECHA microplastic restrictions are forcing wholesale reformulation investments across European supply chains, compressing margins for synthetic-dependent portfolios while rewarding pre-positioned clean-label specialists.
Growth Catalysts
- EU Green Deal chemical sustainability framework:Mandatory environmental footprint disclosure accelerates procurement of bio-based surfactants and plant-derived emollients across German and French professional salon networks.
- Dermocosmetic channel expansion:Pharmacy and clinic distribution in Italy and Spain commands premium pricing through dermatologist endorsement and reimbursed skin barrier treatments.
- Paris-based beauty cluster concentration:Regulatory leadership in cosmetic safety standards attracts formulation R&D investment and premium brand headquarters migration to Île-de-France.
Market Restraints
- Plant oil input volatility:Shea butter and jojoba oil price swings destabilize cost structures for organic-certified manufacturers dependent on West African and Latin American sourcing.
- Single-source specialty chemical dependence:German and Swiss suppliers dominate high-purity ceramide and peptide production, creating concentration risk for mid-tier formulators.
- Preservative efficacy limitations:Clean-label alternatives to parabens and formaldehyde releasers demonstrate shorter shelf stability, constraining distribution reach.
Strategic Opportunities
- Underpenetrated Eastern European pharmacy channels:Poland and Romania exhibit dermatological product consumption gaps versus Western European per-capita benchmarks.
- Waterless formulation convergence:Solid shampoo bars and anhydrous balms merge sustainability positioning with logistics cost reduction for e-commerce fulfillment.
- CSRD supply chain disclosure mandates:Early compliance with corporate sustainability reporting requirements creates competitive differentiation in B2B procurement decisions.
Industry Challenges
- Cosmetic toxicologist talent scarcity:REACH dossier preparation and safety assessment capabilities concentrate among experienced professionals in France and Germany, inflating recruitment costs.
- Multi-jurisdiction labeling complexity:Divergent national enforcement of EU Cosmetics Regulation claims substantiation creates compliance friction for cross-border e-commerce.
- Legacy ERP integration with batch traceability:Small and mid-sized manufacturers face capital requirements for serialization systems demanded by retailer responsible sourcing programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hair and Skincare Market |
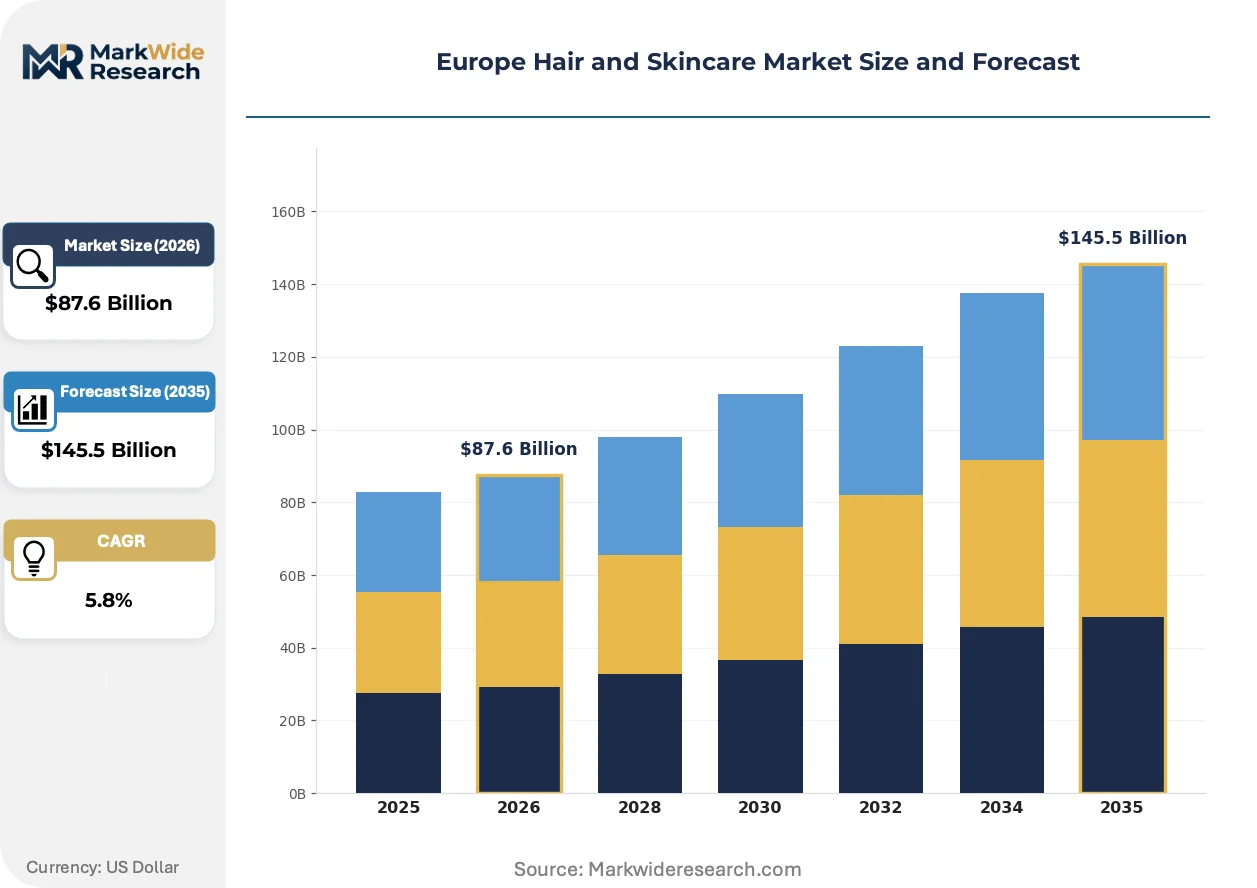
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $145.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Conditioners, Moisturizers, Serums Ingredient Type: Natural, Organic, Synthetic, Herbal End User: Men, Women, Children, Professionals Distribution Channel: Online, Supermarkets, Specialty Stores, Salons |
| Companies Covered | L’Oréal S.A., Beiersdorf AG, Unilever, The Procter & Gamble Company, Coty Inc., Johnson & Johnson Services, Inc., Shiseido Co., Ltd., The Estée Lauder Companies Inc., Avon Products, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hair and Skincare Market Trends and Innovations
Biotechnology-derived actives and fermentation-produced ingredients are displacing conventional extraction methods, while regulatory disclosure requirements and channel fragmentation reshape competitive positioning across the European landscape.
Biosynthetic squalane and lab-cultured collagen are displacing animal-derived and ocean-harvested equivalents in premium serum formulations. German dermocosmetic brands and French pharmacy chains are adopting these inputs at scale. This displacement compresses supply lead times and severs price correlation with agricultural commodity cycles.
REACH authorization requirements for endocrine-disrupting substances and ECHA's emerging restriction proposals on intentionally added microplastics force preemptive reformulation. Manufacturers must requalify alternative rheology modifiers and exfoliants ahead of enforcement timelines. Color cosmetics and rinse-off products face the steepest compliance trajectories, with Nordic markets already advancing stricter national interpretations.
Subscription-based personalized skincare regimens are fragmenting traditional retail purchasing patterns. Direct-to-consumer platforms in France and the United Kingdom capture recurring revenue through algorithm-matched product sequencing. This model concentrates most visibly among urban millennials seeking professional-grade outcomes without salon visitation.
Europe Hair and Skincare Market Segmentation
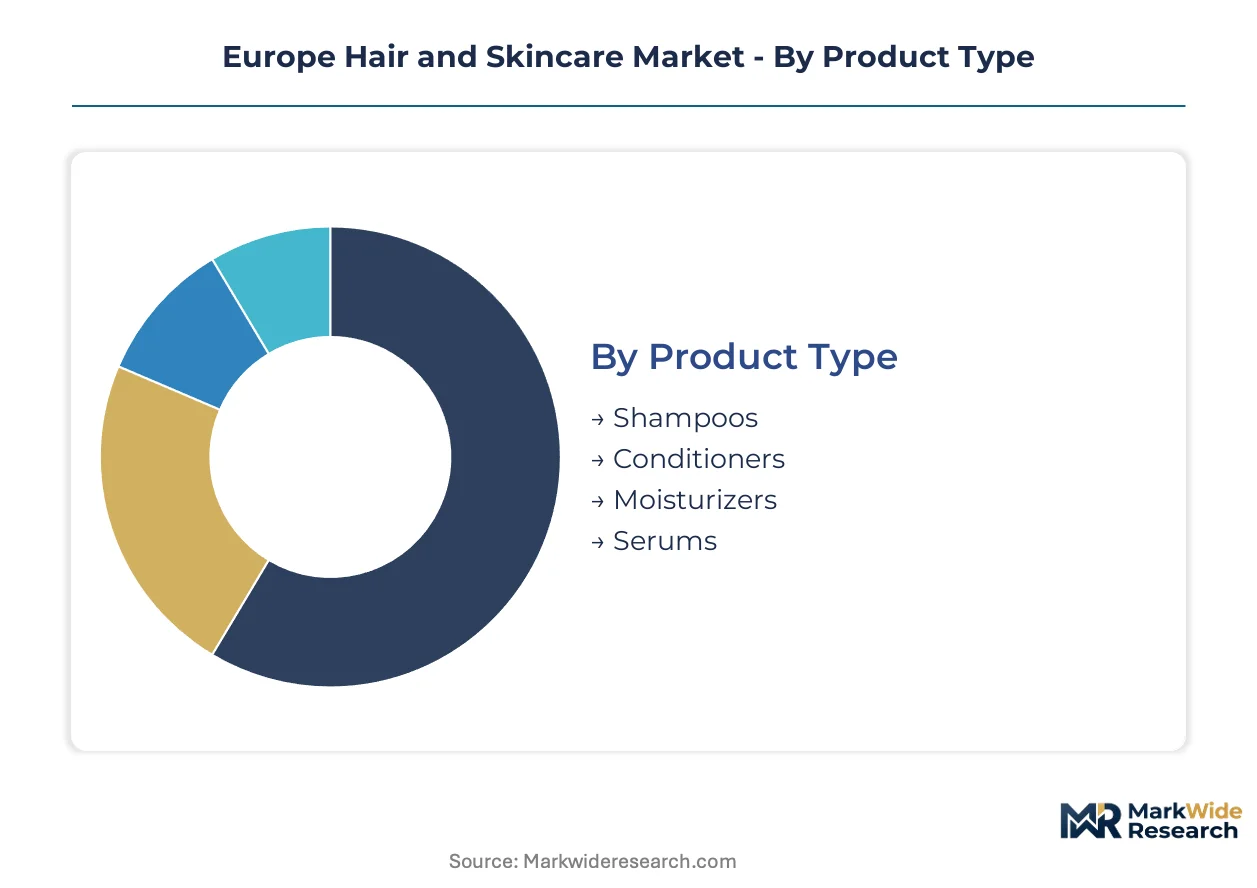
Segmentation in European hair and skincare reveals divergent margin structures across formulation complexity and channel access. Professional-grade products command pricing multiples over mass-market equivalents, while regulatory pressure on ingredient transparency reshapes competitive positioning within each slice.
Product Type:
Margin pools concentrate in leave-on treatments with concentrated active delivery, where R&D amortization spreads across smaller unit volumes but higher per-gram pricing.
- Shampoos:Surfactant-based cleansers with specified pH ranges for scalp microbiome compatibility. French and German professional salon networks are expanding procurement of sulfate-free variants as REACH evaluations tighten on certain surfactant classes.
- Conditioners:Cationic emulsion formulations depositing conditioning agents onto keratin surfaces. Italian pharmacy channels show concentrated demand for silicone-free alternatives driven by clean-beauty positioning among dermatologist-endorsed brands.
- Moisturizers:Occlusive and humectant blends for epidermal barrier maintenance across daily regimens.
- Serums:High-actives concentrates with specified dermatological tolerability profiles and targeted delivery systems.
The dominant share belongs to shampoos, while serums are closing the gap fastest.
Ingredient Type:
Cost tier stratification runs deepest here, with certification-grade organic inputs carrying 3-5x raw material premiums over conventional synthetics.
- Natural:Plant-derived extracts and minimally processed botanicals without synthetic modification. German clean-label specialists are capturing shelf space in DM and Müller drugstore chains as ECHA microplastic restrictions force reformulation of polymer-dependent alternatives.
- Organic:Certified inputs meeting ECOCERT or COSMOS standards with full traceability documentation. French premium brands headquartered in Paris beauty clusters leverage this classification for pharmacy channel placement and reimbursed dermocosmetic positioning.
- Synthetic:Laboratory-engineered molecules including silicones, petrochemical-derived emollients, and preservative systems.
- Herbal:Traditional botanical preparations with historical use documentation in European pharmacopeia.
Organic certification commands the steepest price premiums, though natural-classified inputs are gaining share fastest as formulators seek regulatory pre-positioning ahead of REACH amendments.
End User:
Application context determines formulation specification, with professional-use products requiring higher stability under salon conditions.
- Women:Broadest category spanning daily hygiene through clinical-grade skin barrier treatments. Italian and Spanish dermocosmetic consumption concentrates here, with pharmacy reimbursement policies in Lombardy and Catalonia driving per-capita spending above Eastern European benchmarks.
- Men:Simplified regimens with multi-functional positioning and masculine-coded packaging. British and Scandinavian direct-to-consumer platforms are fragmenting traditional retail patterns through subscription-based personalized sequencing for this segment.
- Children:Hypoallergenic formulations with restricted preservative palettes and tear-free surfactant systems.
- Professionals:Salon-grade products with concentrated actives and extended stability under high-frequency use conditions.
Women's formulations retain the dominant revenue position, while men's dedicated products are expanding most quickly.
Distribution Channel:
Customer type stratification separates service-attached purchasing from self-directed selection, with profound implications for brand building economics.
- Specialty Stores:Curated assortments with trained staff recommendation and sampling infrastructure. Paris-based beauty clusters and German city-center perfumeries sustain premium pricing through experience-attached purchasing.
- Salons:Professional recommendation-dependent channels with highest per-unit value capture. French and German salon networks are expanding clean-label procurement as the EU Green Deal mandates environmental footprint disclosure.
- Online:Direct-to-consumer platforms and marketplace aggregators with algorithm-matched product sequencing.
- Supermarkets:Mass-market volume channels with price-promotional dynamics and limited service attachment.
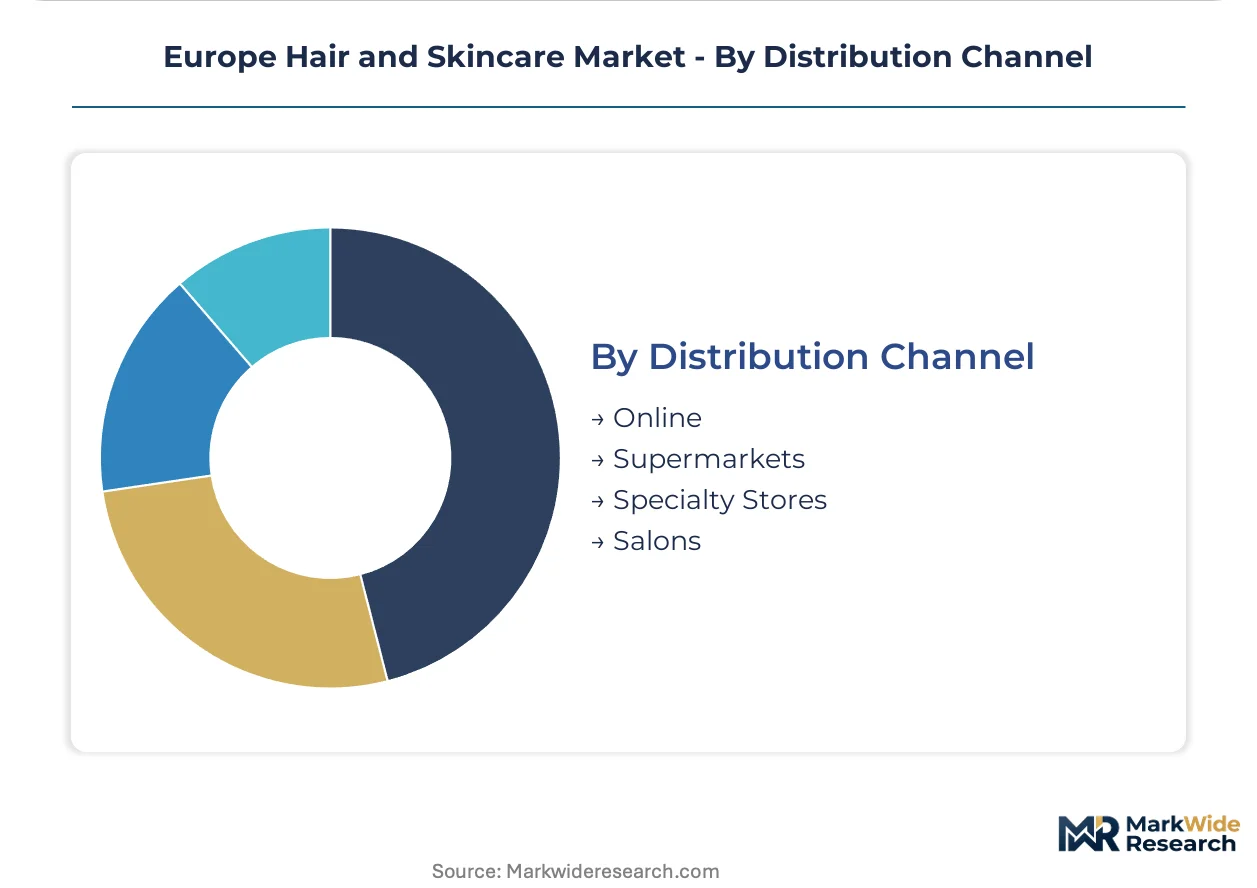
Specialty stores hold the dominant margin pool, while online channels are climbing the fastest as subscription models reshape repurchase patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across European markets. German consumers demand clean-label formulations at accessible price points. French buyers accept substantial premiums for pharmacy-endorsed dermocosmetics. Eastern European markets remain underpenetrated relative to Western per-capita benchmarks.
Germany
Professional salon networks in Berlin and Hamburg are accelerating procurement of sulfate-free shampoos and silicone-free conditioners. REACH substance evaluations on certain surfactant classes are forcing wholesale reformulation investments across domestic supply chains. The Rhine-Ruhr manufacturing corridor hosts concentrated production capacity for biosynthetic squalane and fermentation-derived actives.
France
Pharmacy channel consumption in Paris and Lyon commands premium pricing through dermatologist endorsement and reimbursed skin barrier treatments. ANSM maintains regulatory leadership in cosmetic safety standards that attracts premium brand headquarters migration. The Île-de-France beauty cluster concentrates formulation R&D investment and clean-label specialist headquarters.
Italy
Lombardy and Catalonia-adjacent regions exhibit concentrated dermocosmetic consumption driven by pharmacy reimbursement policies. Italian consumers show elevated demand for silicone-free alternatives among dermatologist-endorsed brands. Milan anchors professional salon procurement networks expanding clean-label formulation adoption.
United Kingdom
Direct-to-consumer platforms in London and Manchester capture recurring revenue through subscription-based personalized skincare sequencing. British consumers in the men's segment increasingly favor simplified multi-functional regimens. The UK regulatory environment post-Brexit maintains alignment with EU Cosmetics Regulation while developing independent enforcement interpretations.
Poland
Pharmacy channel penetration in Warsaw and Kraków remains substantially below Western European per-capita dermatological product consumption benchmarks. Polish consumers demonstrate growing appetite for pharmacy-distributed skin barrier treatments. The domestic market offers expansion terrain for clean-label specialists seeking geographic diversification.
Europe Hair and Skincare Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European hair and skincare landscape. Premium R&D specialists concentrate investment in dermatological credibility and skin barrier science, while mass-market manufacturers compete through scale efficiencies and broad distribution reach. The market structure separates into three strategic archetypes: integrated research conglomerates, dermatological credibility specialists, and scale-driven FMCG operators. Dominant competitive moves include portfolio diversification across price tiers and strategic partnerships with professional salon networks.
Within the integrated research tier, L'Oréal S.A. and Beiersdorf AG exemplify archetypes combining brand portfolio depth with captive formulation infrastructure. Unilever occupies a position at the scale-driven end, representing cost leadership through multi-channel distribution dominance. These three entities anchor the competitive structure, with their respective positions reflecting divergent capital-intensity strategies across mass-market and premium segments.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Beiersdorf AG |
| Unilever |
| The Procter & Gamble Company |
| Coty Inc. |
| Johnson & Johnson Services, Inc. |
| Shiseido Co., Ltd. |
| The Estée Lauder Companies Inc. |
| Avon Products, Inc. |
| Others |
Pricing and Supply Chain Analysis
Biosynthetic squalane displacing shark-liver and olive-derived equivalents redraws European supply geography toward German fermentation facilities while collapsing price correlation with agricultural commodity cycles. This substitution dynamic simultaneously concentrates premium raw material sourcing in the Rhine-Ruhr corridor and compresses margin buffers for formulators still dependent on West African shea butter and Latin American jojoba oil inputs.
Pricing Analysis
Subscription-based recurring revenue now drives lifetime value capture across direct-to-consumer platforms in France and the United Kingdom. Three-tier pricing structure across premium dermocosmetic, standard pharmacy, and economy mass-market levels stratifies according to certification grade and dermatologist endorsement intensity. Pricing pressure stems from REACH-mandated reformulation investments that inflate R&D amortization across smaller batch volumes. Mass-market supermarket buyers exhibit acute price sensitivity, while pharmacy channel consumers accept substantial premiums for reimbursed skin barrier treatments.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg container terminals have intensified cost pressure on West African shea butter and Latin American botanical oil shipments. German, French, and Swiss suppliers dominate high-purity ceramide and peptide production, creating single-source vulnerability for mid-tier formulators dependent on these inputs. Raw material portfolios draw from West African plant butter regions, Latin American jojoba cultivation zones, and domestic fermentation-derived active facilities. Distribution runs through professional salon networks in Paris and Berlin, pharmacy chains in Milan and Lyon, and direct-to-consumer platforms in London and Manchester.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in underpenetrated Eastern European pharmacy channels where per-capita dermatological consumption lags Western benchmarks by substantial margins. Subscription-based personalized regimens are fragmenting traditional retail purchasing patterns, creating niche entry points for specialists with algorithm-matched product sequencing capabilities.
For Market Incumbents: Consolidate formulation R&D infrastructure around biotechnology-derived actives to preempt ECHA microplastic restrictions and REACH authorization timelines. Acquire clean-label specialists with established ECOCERT supply chains to defend margin position against emerging German and French salon-network insurgents. Channel control through exclusive professional distribution agreements in Paris and Berlin remains the priority defensive lever. For New Entrants and Emerging Players: COSMOS certification fast-track through French regulatory consultancies accelerates pharmacy channel placement and reimbursed dermocosmetic positioning. Target Polish and Romanian pharmacy networks where dermatological product consumption gaps versus Western European benchmarks offer white-space expansion terrain. Deploy direct-to-consumer subscription models with algorithm-matched serum sequencing as the primary go-to-market angle for urban millennial acquisition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed French clean-label specialists that have scaled to pharmacy channel dominance but lack global distribution infrastructure. Five-to-ten year viability hinges on regulatory pre-positioning capabilities and biotechnology-derived active pipelines rather than conventional botanical extraction. Monitor ECHA restriction proposal enforcement timelines as the critical inflection signal for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology-Derived Active Scale-Up | Fermentation-produced squalane and lab-cultured collagen displace animal-derived inputs in German dermocosmetic formulations. |
| Clean-Label Certification Investment | ECOCERT and COSMOS accreditation unlocks pharmacy channel placement and reimbursed positioning in French Lombardy networks. |
| Eastern European Pharmacy Expansion | Warsaw and Kraków distribution agreements capture underpenetrated dermatological consumption versus Western benchmarks. |
| Subscription Platform Integration | Algorithm-matched product sequencing concentrates recurring revenue among British and French urban millennial segments. |
| REACH Pre-Positioning Reformulation | Alternative rheology modifier qualification ahead of ECHA microplastic restrictions defends market access in Nordic jurisdictions. |
Research Methodology
Desk research of EU Cosmetics Regulation amendment filings, ECHA substance evaluation databases, and French ANSM safety assessment precedents preceded structured interviews with formulation R&D directors, professional salon procurement managers, pharmacy chain category buyers, and clean-label certification auditors. Secondary validation drew from customs trade data for shea butter and jojoba oil shipments, Nielsen retail audit figures for German drugstore channels, and corporate sustainability disclosure reports under CSRD mandates. Bottom-up demand modeling across product and ingredient segments triangulated against top-down market sizing from regulatory framework analysis.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within each segmentation dimension including product type complexity, certification grade tier, end-user application context, and channel service-attachment level. CAGRs were derived from trend extrapolation of professional salon procurement patterns, pharmacy reimbursement policy trajectories, and direct-to-consumer subscription growth curves. Forecast inputs incorporate REACH authorization timelines, ECHA restriction proposal enforcement thresholds, and EU Green Deal chemical sustainability disclosure phase-in schedules.
Decision-makers should treat outputs as directional under assumptions of continued regulatory alignment between EU member states and stable plant oil commodity input costs; material deviation would warrant model refresh. Specific risk factors include accelerated Nordic national enforcement of microplastic restrictions, shea butter supply disruption from West African sourcing regions, and Brexit-related divergence in UK Cosmetics Regulation interpretation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Germany Beauty Industry Market
Beauty & Personal Care
Europe Hair Conditioner Market
Beauty & Personal Care
Global Hot Air Brushes Market
Beauty & Personal Care
Global and North America Organic and Natural Feminine Care Market
Beauty & Personal Care
Shaving and Hair Removal Products Market
Beauty & Personal Care
At-Home Beauty Devices Market
Beauty & Personal Care
United Kingdom Dermocosmetics Market
Beauty & Personal Care
Organic Shampoo Market
Beauty & Personal Care
Gua Sha Tools Market
Beauty & Personal Care
Europe Halal Cosmetics Market
Beauty & Personal Care
Global Massage Oil Market
Beauty & Personal Care
Curling Irons Market
Beauty & Personal Care
False Eyelashes Market
Beauty & Personal Care
Deodorant Wipes Market
Beauty & Personal Care
Anti-Dandruff Shampoo Market
Beauty & Personal Care
Anti-Aging Cosmetics Market