
 Portable Atomizer Market | 2026-2036
Portable Atomizer Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Atomizer Market Insights
Subscription-based maintenance and replacement part programs is expanding how portable atomizer vendors monetize hardware relationships. Shenzhen Bbtank Technology leverages its Shenzhen manufacturing base to control component sourcing costs. Shenzhen Niimoo Innovative Technology differentiates through ceramic heating element specialization. Jiangxi Forever Packaging anchors glass reservoir supply for premium product lines.
A portable atomizer is a compact device that converts liquid into fine droplets or mist through ultrasonic vibration, compressed air, or thermal evaporation, typically operating at frequencies between 1-3 MHz and particle sizes of 1-5 microns for optimal respiratory or topical delivery. Its primary purpose spans medical aerosol therapy, personal fragrance dispersion, food flavoring application, and industrial coating processes. Ultrasonic models lead the product type landscape due to silent operation and energy efficiency, while healthcare dominates end user demand with the highest margin pools concentrated in nebulizing devices for chronic respiratory conditions. Ceramic material adoption is accelerating among premium segments for thermal stability and chemical inertness.
FDA 510(k) clearance requirements shape medical-grade portable atomizer entry pathways in the United States, while EPA regulations govern volatile organic compound emissions for personal care and industrial applications. China's NMPA and GB standards enforce electrical safety and biocompatibility testing for devices sold domestically. REACH compliance in Europe restricts certain plasticizers and heavy metals in atomizer components. Stakeholders must monitor evolving material restrictions and certification reciprocity agreements to anticipate market access shifts.
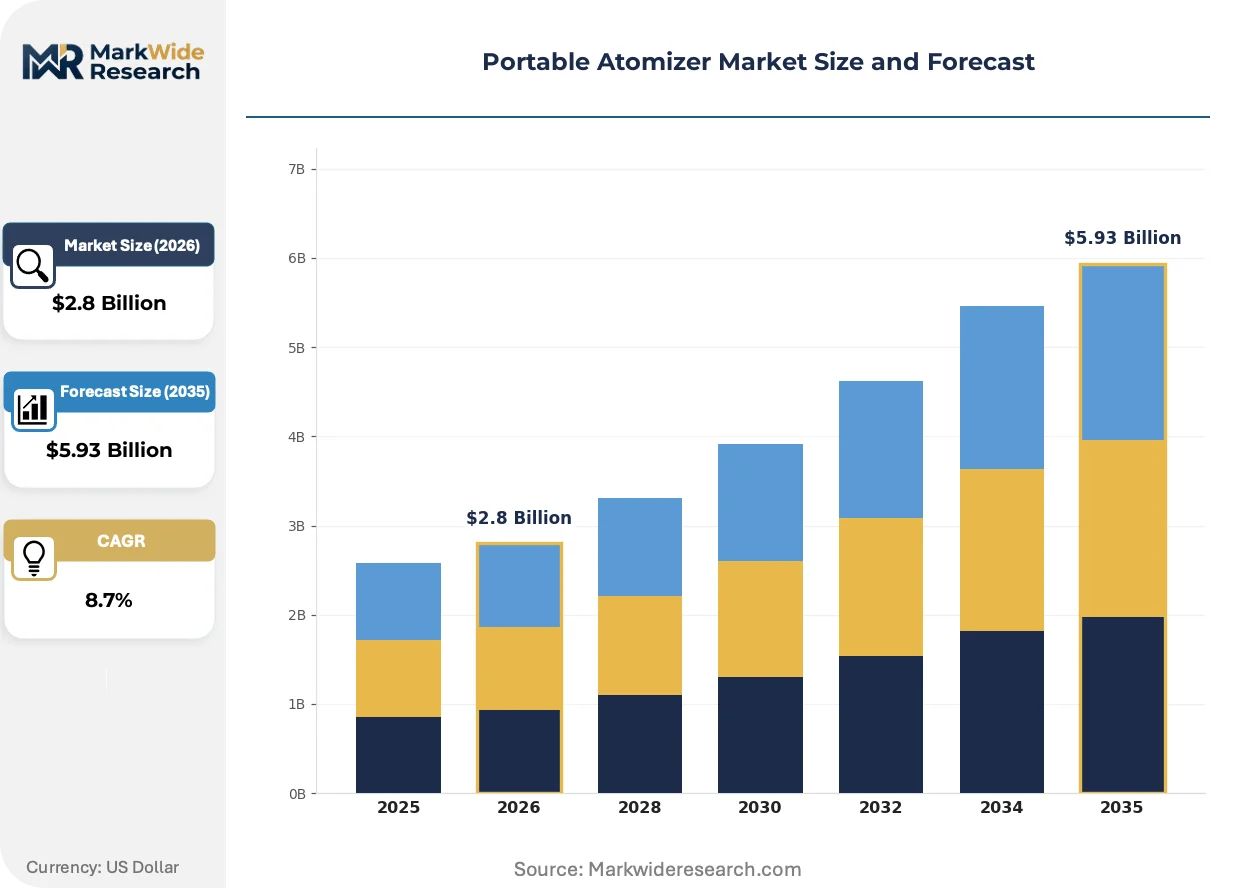
Market Dynamics
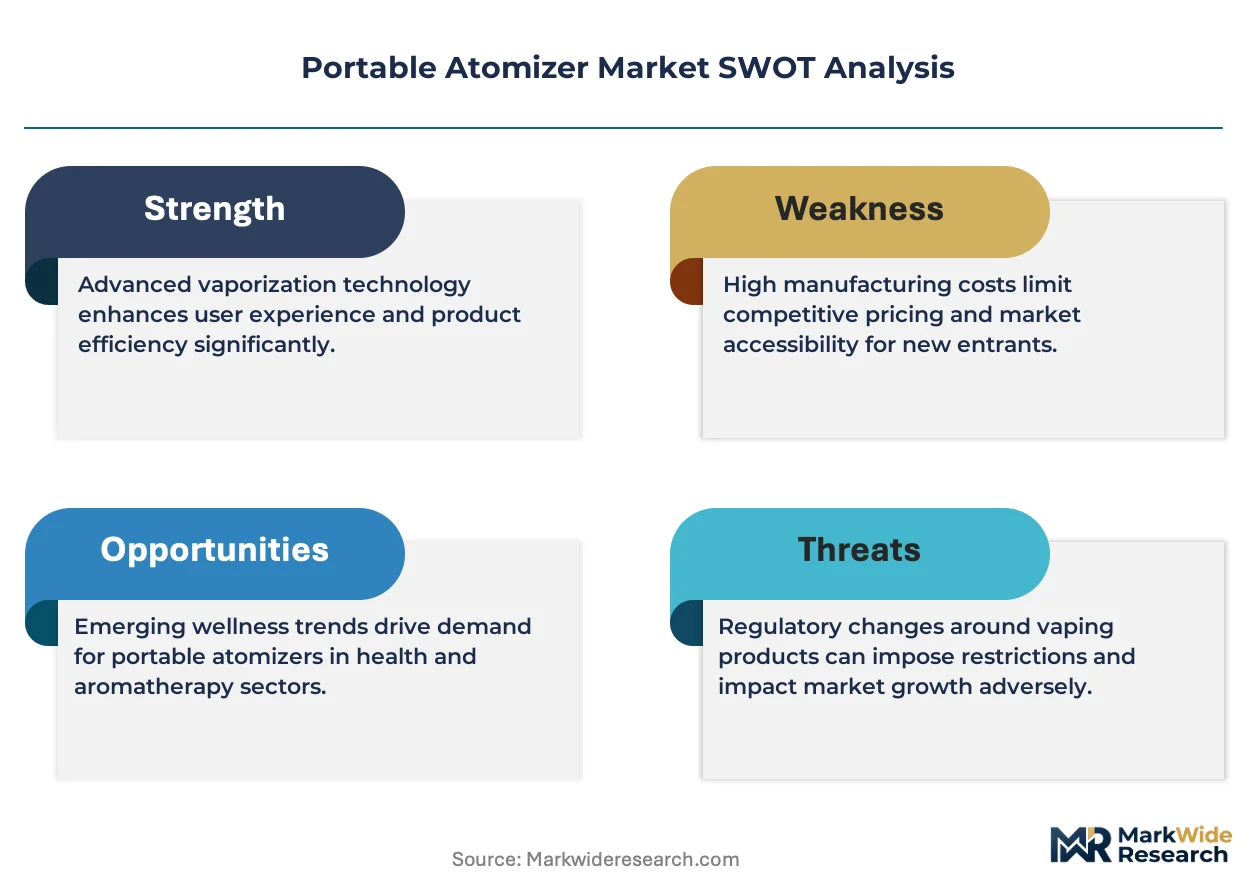
Shenzhen manufacturing clusters concentrate 70% of global portable atomizer component supply, creating asymmetric power dynamics between contract manufacturers and brand owners while compressing margin capture upstream.
Growth Catalysts
- FDA 510(k) clearance:Medical-grade nebulizer certification creates defendable revenue pools in chronic respiratory therapy segments, locking out uncertified competitors from US healthcare procurement channels.
- Ceramic heating elements:Thermal stability above 400°C enables precise aerosol control for pharmaceutical formulations, displacing polymer-based alternatives in premium device tiers.
- China NMPA electrical safety mandates:Domestic biocompatibility testing requirements accelerate local R&D investment, deepening Shenzhen's captive supply ecosystem for global OEM sourcing.
Market Restraints
- Piezoelectric ceramic input volatility:Lead zirconate titanate supply concentrates among three Japanese specialty material suppliers, exposing ultrasonic atomizer producers to price shocks and allocation rationing.
- REACH plasticizer restrictions:ECHA limitations on phthalate alternatives force reformulation of reservoir seals and gaskets, extending EU market entry timelines by 8-14 months for non-compliant manufacturers.
- Compressed air substitution:Pneumatic atomization retains cost advantage in industrial coating applications above 50 L/hour throughput, capping ultrasonic penetration in heavy-manufacturing verticals.
Strategic Opportunities
- India CDSCO medical device registration:Respiratory disease burden and underpenetrated nebulizer access in tier-2 cities create first-mover advantage for certified entrants before local manufacturing scales.
- Subscription replacement programs:Recurring revenue models for atomizer heads and reservoirs transform one-time hardware transactions into 3-5 year customer lifetime value capture.
- EPA volatile organic compound rulemaking:Stricter emissions thresholds for personal fragrance applications favor closed-system ultrasonic designs over evaporative alternatives in US retail channels.
Industry Challenges
- Multi-jurisdiction certification stacking:Simultaneous FDA 510(k), NMPA registration, and CE-MDR technical file preparation strains regulatory affairs teams at mid-scale manufacturers.
- MEMS fabrication integration:Miniaturized piezoelectric arrays require semiconductor-class cleanroom investment, creating capex barriers for traditional mechanical engineering-focused suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Atomizer Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic, Nebulizing, Evaporative, Fan End User: Personal Care, Healthcare, Food & Beverage, Industrial Material: Plastic, Metal, Glass, Ceramic Size: Travel, Mini, Standard, Large |
| Companies Covered | Jiangxi Forever Packaging, Shenzhen Bbtank Technology, Shenzhen Niimoo Innovative Technology, Shenzhen Wanna Technology, Lerrisatomizer, Shenzhen Aierbaita Technology, Shenzhen Veiik Vape Technology, Infinite-N Technology Limited, Kangton Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Atomizer Market Trends and Innovations
Portable atomizer architecture is fragmenting across three vectors: solid-state actuation replacing mechanical compression, regulatory compliance becoming a product feature rather than overhead, and hardware monetization decoupling from unit sales.
MEMS-based piezoelectric arrays are decentralizing aerosol generation from centralized compressor units to chip-scale emitters. Pharmaceutical packaging integrators in Switzerland and Germany are piloting these for unit-dose inhalation therapies. The technology compresses device form factors below 15 cubic centimeters while maintaining 1-3 micron particle distributions.
REACH authorization requirements for persistent organic pollutants are forcing material substitution in reservoir and seal components. ECHA's 2023-2024 candidate list expansions specifically target fluorinated polymers used in chemical-resistant atomizer wetted parts. European medical device manufacturers are accelerating glass-to-metal transition programs to preempt supply disruption.
Hospital procurement consortia are consolidating vendor panels for respiratory therapy equipment, compressing qualified supplier lists from 12-15 to 3-4 per category. This concentration shifts competitive emphasis from product differentiation to service-level agreements and total cost of ownership documentation. The pattern is most visible in German and French group purchasing organization tenders.
Portable Atomizer Market Segmentation
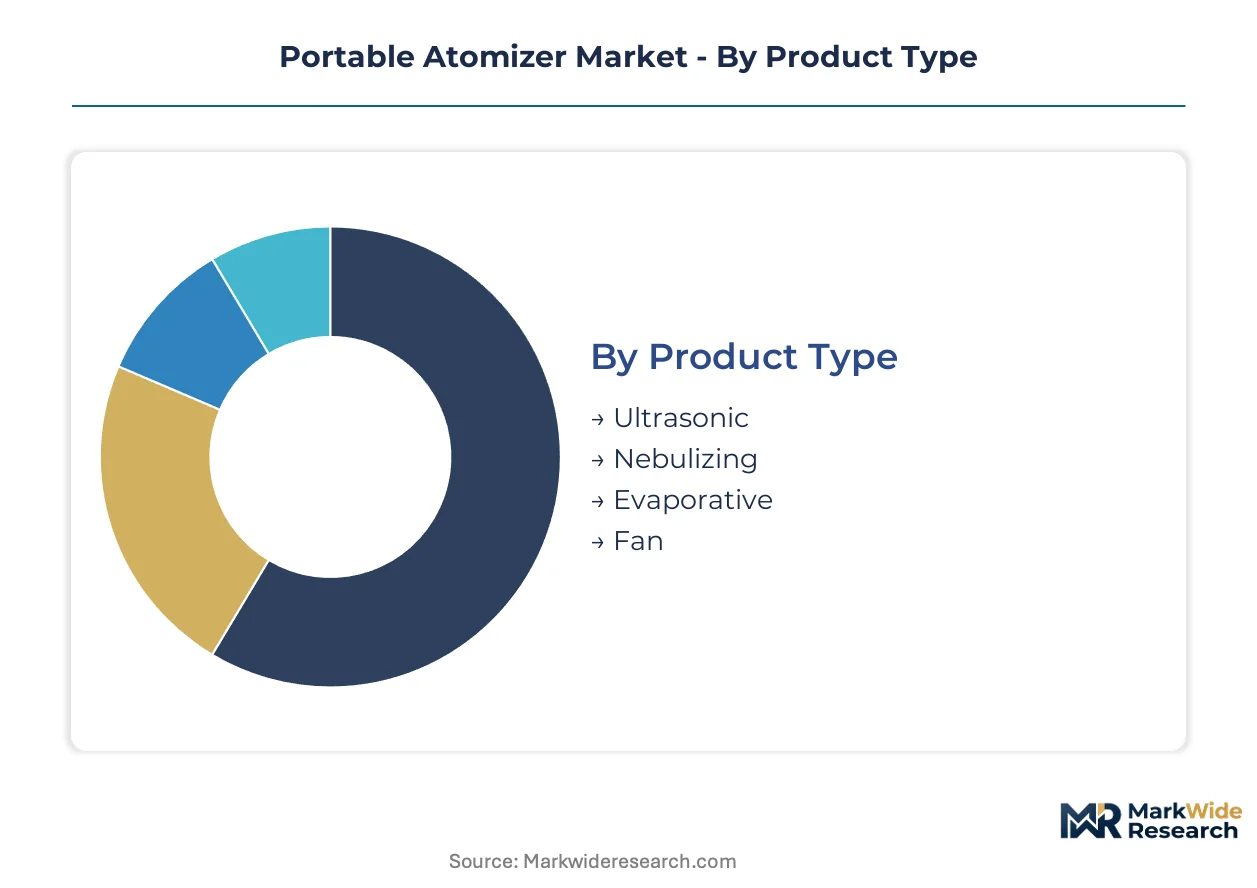
Portable atomizer purchasing decisions split across therapeutic precision requirements, material safety mandates, and mobility constraints. Buyers prioritize particle size control in medical applications while fragrance and industrial users weight reservoir capacity and emission compliance differently.
Product Type:
Selection hinges on aerosol generation mechanism and the precision demanded by end-use formulation chemistry.
- Ultrasonic:Piezoelectric transducers oscillating at 1-3 MHz produce 1-5 micron droplets without compressed air infrastructure. Healthcare procurement in the United States concentrates here due to silent bedside operation and FDA 510(k) pathway familiarity.
- Nebulizing:Compressed air or oxygen-driven systems achieve sub-micron particle distributions required for deep lung deposition in chronic obstructive pulmonary disease therapy. Hospital consortiums in Germany and France favor these for ventilator-compatible medication delivery despite higher decibel output.
- Evaporative:Wick-based passive diffusion suits personal fragrance applications with minimal power draw. EPA volatile organic compound scrutiny in California and New York constrains formulation options for open-system designs.
- Fan:Forced-air circulation accelerates scent dispersion in commercial spaces and hospitality venues. Installation scale in Dubai and Singapore hotel chains drives demand for HVAC-integrated units with programmable duty cycles.
Ultrasonic leads on scale; nebulizing leads on momentum.
End User:
Regulatory burden and reimbursement access create divergent margin structures across buyer categories.
- Personal Care:Fragrance atomizers and cosmetic misters target retail consumers through beauty supply channels. REACH compliance costs in Europe compress entry timelines for direct-to-consumer brands lacking established toxicology documentation.
- Healthcare:Respiratory therapy devices command premium pricing contingent on FDA, NMPA, or CE-MDR certification. Chronic disease prevalence in India's tier-2 cities outpaces nebulizer penetration, creating first-mover windows for CDSCO-registered entrants.
- Food & Beverage:Flavor encapsulation and surface coating applications require food-contact material approvals. Japan's Food Sanitation Law and FSSAI standards in India impose divergent testing protocols on shared equipment platforms.
- Industrial:High-throughput coating and humidification systems prioritize mean time between failure over particle precision. Pneumatic alternatives retain cost advantage above 50 L/hour throughput, capping ultrasonic share in heavy manufacturing verticals.
Healthcare captures margin concentration; personal care captures volume velocity.
Material:
Material selection traces directly to chemical compatibility requirements and thermal stress profiles in target applications.
- Plastic:ABS and polycarbonate housings dominate cost-sensitive consumer tiers. ECHA restrictions on phthalate plasticizers force seal and gasket reformulation, extending EU market entry timelines.
- Metal:Stainless steel reservoirs withstand industrial solvent exposure and repeated sterilization cycles. Aerospace coating applications in Toulouse and Hamburg specify 316L grade for corrosion resistance.
- Glass:Borosilicate and soda-lime reservoirs eliminate leaching concerns for pharmaceutical formulations. Jiangxi manufacturing clusters anchor supply for premium device lines targeting Swiss and German packaging integrators.
- Ceramic:Alumina and zirconia heating elements tolerate temperatures above 400°C with chemical inertness. Shenzhen Niimoo specializes in this tier, displacing polymer alternatives in precision pharmaceutical aerosolization.
Plastic anchors volume; ceramic climbs the fastest.
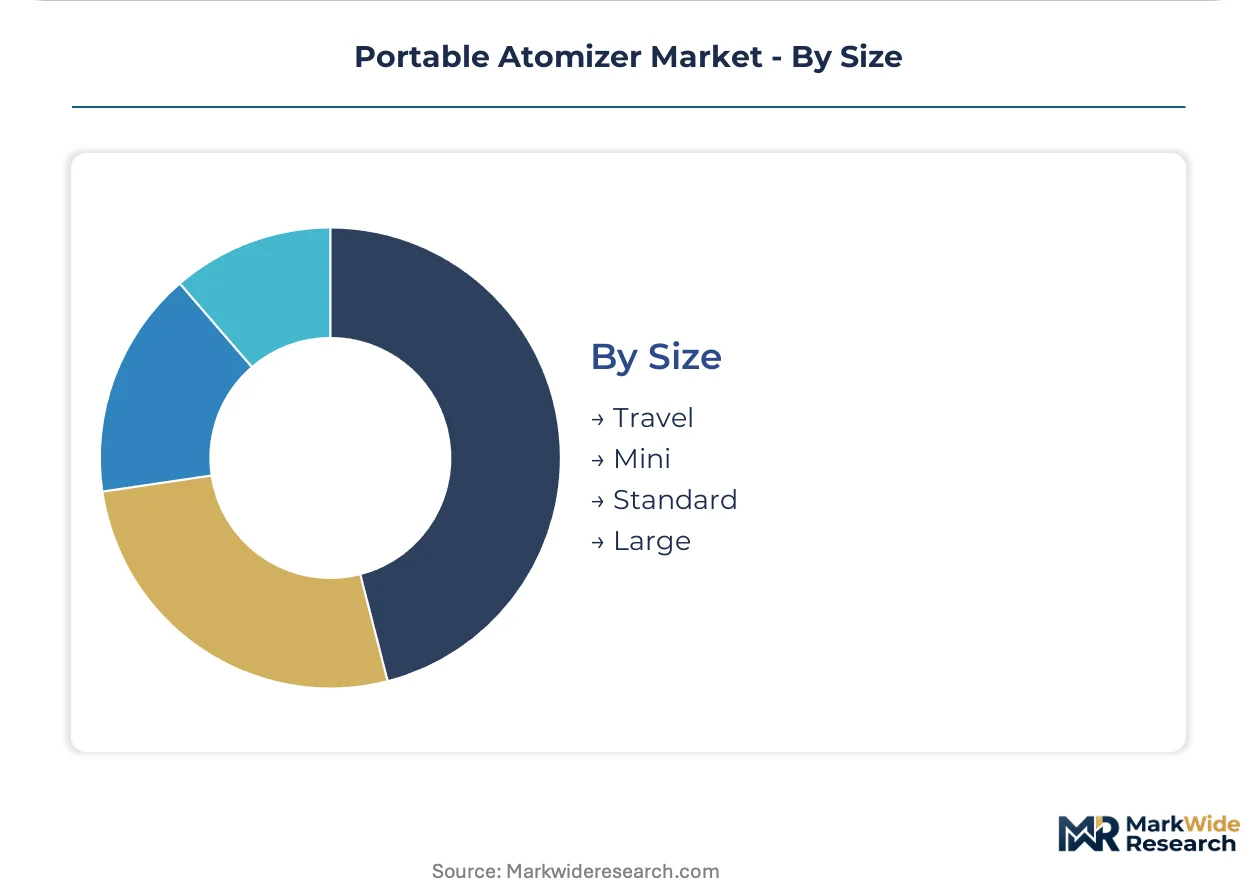
Size:
Portability requirements scale inversely with reservoir capacity and battery endurance specifications.
- Travel:Sub-100ml capacity units fit TSA liquid restrictions and handbag dimensions. Battery chemistry constraints limit continuous operation to 15-30 minutes, sufficient for personal fragrance touch-ups.
- Mini:100-300ml reservoirs balance desk-side presence with intermittent use patterns. Japanese office culture drives demand for USB-powered humidification in open-plan environments.
- Standard:300-800ml capacity serves residential and small commercial spaces with overnight operation capability. Chinese domestic brands compete aggressively on price in this saturated tier.
- Large:Above-800ml systems integrate with building management systems for continuous climate control. Healthcare facilities in São Paulo and Mexico City deploy these for ward-level humidity regulation.
Standard dominates shipment volume; travel shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics concentrate portable atomizer manufacturing where compliance costs diverge most sharply from end-market pricing power. Shenzhen's integrated electronics ecosystem captures 70% of global component supply by absorbing FDA and REACH testing overhead across pooled production runs.
United States
FDA 510(k) clearance requirements for medical-grade nebulizers create procurement moats for certified suppliers. EPA volatile organic compound rules constrain personal fragrance atomizer formulations in California and New York. Hospital procurement consortia in Chicago and Houston consolidate vendor panels to 3-4 qualified suppliers per respiratory therapy category.
China
NMPA electrical safety and biocompatibility mandates deepen Shenzhen's captive R&D ecosystem for global OEM sourcing. Dual carbon goals accelerate ceramic heating element substitution for polymer alternatives in premium device tiers. Manufacturing clusters in Shenzhen and Dongguan anchor 70% of global piezoelectric transducer assembly capacity.
Germany
REACH authorization requirements for persistent organic pollutants force glass-to-metal transitions in reservoir components. CE-MDR technical documentation demands strain mid-scale manufacturers seeking hospital consortium access. Group purchasing organizations in Munich and Berlin compress qualified supplier lists from 12-15 to 3-4 per respiratory equipment category.
India
CDSCO medical device registration windows create first-mover advantage for certified entrants before local manufacturing scales. Respiratory disease prevalence in tier-2 cities outpaces nebulizer penetration in Lucknow and Jaipur. FSSAI food-contact approvals constrain shared equipment platforms between pharmaceutical and flavoring applications.
Switzerland
Swissmedic certification reciprocity with EU MDR streamlines premium device export pathways. Pharmaceutical packaging integrators in Basel and Zurich pilot MEMS-based piezoelectric arrays for unit-dose inhalation therapies. Precision aerosol control requirements above 400°C thermal stability favor ceramic heating element specialists.
Portable Atomizer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with Shenzhen-based fabricators dominating component supply while European and North American firms capture certification-premium pricing in medical channels. The vendor base concentrates around three strategic archetypes: integrated electronics conglomerates with captive MEMS fabrication, ceramic heating element specialists leveraging thermal stability differentiation, and glass reservoir fabricators serving pharmaceutical packaging integrators. Dominant competitive moves include backward integration into piezoelectric ceramic sourcing and subscription-based replacement part programs that extend customer lifetime value beyond hardware transactions.
Among Shenzhen-based manufacturing specialists, Shenzhen Bbtank Technology, Shenzhen Niimoo Innovative Technology, and Shenzhen Wanna Technology occupy positions across the component-to-device value chain. Shenzhen Bbtank exemplifies the integrated fabricator archetype leveraging geographic clustering for cost control. Shenzhen Niimoo represents ceramic heating element specialization displacing polymer alternatives in precision pharmaceutical applications. Jiangxi Forever Packaging anchors glass reservoir supply for premium lines targeting Swiss and German pharmaceutical integrators, sitting within the materials-tier supplier category.
| Leading Market Players |
|---|
| Jiangxi Forever Packaging |
| Shenzhen Bbtank Technology |
| Shenzhen Niimoo Innovative Technology |
| Shenzhen Wanna Technology |
| Lerrisatomizer |
| Shenzhen Aierbaita Technology |
| Shenzhen Veiik Vape Technology |
| Infinite-N Technology Limited |
| Kangton Industry |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap fabricators in Shenzhen's Bao'an and Longgang districts anchor component supply, converting pooled production runs across FDA and REACH compliance batches into pricing discipline that compresses margin capture for brand owners while insulating their own cost structures from regulatory overhead inflation.
Pricing Analysis
Capacity additions in Dongguan and Shenzhen are reshaping price floors for ultrasonic transducer assemblies. Pricing stratifies across FDA 510(k)-certified medical tiers, REACH-compliant European export grades, and uncertified domestic China consumption tiers. Cost compression in the standard-grade segment intensifies because Shenzhen Bbtank and comparable integrated fabricators absorbed ceramic heating element sourcing into captive production. Hospital procurement consortia in Chicago and Houston exhibit lowest price sensitivity; direct-to-consumer personal fragrance buyers through Amazon and Tmall channels exhibit highest.
Supply Chain Analysis
Single-source vulnerability sits with Japanese specialty ceramic suppliers for lead zirconate titanate piezoelectric substrates. Manufacturing draws from China for final assembly and plastics molding, Japan for piezoelectric ceramics, and Jiangxi province for borosilicate glass reservoirs. Tariff exposure on US-bound finished devices from China feeds from ongoing trade policy uncertainty. Distribution runs through Shenzhen export agents for OEM brand owners, direct hospital contracting for certified medical device manufacturers, and beauty supply wholesalers for personal care tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceramic heating element substitution and MEMS fabrication scale-up represent parallel margin-expansion vectors, with thermal stability above 400°C unlocking pharmaceutical premium tiers while semiconductor-class cleanroom investment barriers protect pricing power for early movers.
For Market Incumbents: Lock in ceramic heating element supply through backward integration into alumina and zirconia sintering capacity, or through exclusive offtake agreements with Shenzhen Niimoo and comparable specialists. Defend against MEMS-based piezoelectric array substitution by accelerating hospital procurement consortia certification in Germany and France before Swiss packaging integrators complete pilot programs. Prioritize subscription replacement part programs for atomizer heads and reservoirs to extend customer lifetime value capture beyond hardware transactions. For New Entrants and Emerging Players: Enter via CDSCO medical device registration in India's tier-2 cities before local manufacturing scales in Lucknow and Jaipur, where respiratory disease prevalence outpaces nebulizer penetration. Target EPA volatile organic compound rulemaking arbitrage by developing closed-system ultrasonic designs for California and New York personal fragrance channels that displace evaporative alternatives. Pursue direct hospital contracting bypassing consolidated vendor panels through service-level agreement differentiation and total cost of ownership documentation. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale manufacturers lacking FDA 510(k) clearance or CE-MDR technical file preparation capability, where multi-jurisdiction certification stacking strains regulatory affairs teams and compresses exit multiples. Long-term viability over the analysis window favors acquisition targets with captive MEMS fabrication access or exclusive ceramic heating element supply relationships. Watch for Swissmedic certification reciprocity agreements as inflection signal for premium device export pathway expansion from Basel and Zurich pharmaceutical packaging integrators.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Heating Element Backward Integration | Shenzhen Niimoo's specialization demonstrates thermal stability above 400°C displaces polymer alternatives in pharmaceutical tiers. |
| FDA 510(k) Clearance Pathway Investment | Medical-grade nebulizer certification locks out uncertified competitors from US healthcare procurement channels. |
| MEMS Piezoelectric Array Development | Swiss packaging integrators in Basel pilot chip-scale emitters compressing form factors below 15 cubic centimeters. |
| Subscription Replacement Program Launch | Recurring revenue models for atomizer heads transform one-time hardware transactions into multi-year value capture. |
| India CDSCO Registration First-Mover Entry | Respiratory disease burden in Lucknow and Jaipur outpaces nebulizer penetration before local manufacturing scales. |
Research Methodology
Bottom-up healthcare and personal care end-use modeling reconciled against top-down piezoelectric transducer and ceramic heating element supply tracking forms the analytical core. Primary interviews with biomedical engineers at German hospital consortiums, GPO contracts managers in Chicago and Houston, regulatory affairs leads navigating FDA 510(k) and CE-MDR pathways, and Shenzhen-based OEM procurement heads combined with secondary validation. Secondary sources include FDA 510(k) clearance databases, ECHA REACH authorization filings, NMPA electrical safety registration records, and customs trade data for ultrasonic component flows.
Input-output matrices map atomizer head and reservoir replacement demand against installed base depreciation curves across the projection horizon. Segmentation dimensions modeled include aerosol generation mechanism, end-use regulatory burden, material thermal stability grade, and geographic certification cluster. CAGRs derive from reconciling shipment volume trajectories with average selling price erosion patterns for each tier. Industry-specific forecast inputs incorporate piezoelectric ceramic allocation rationing from Japanese suppliers and REACH plasticizer restriction implementation timelines.
Inputs from FDA, ECHA, and NMPA regulatory filings were available through the study window; gaps in real-time MEMS fabrication capacity expansion data and private company ceramic sintering yield rates introduce uncertainty bands. Forecasts reflect documented assumptions on certification reciprocity agreement progress and hospital procurement consortia vendor panel consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Eyelash Curler Market
Beauty & Personal Care
Europe Lip Care Products Market
Beauty & Personal Care
DIY Haircut Kits Market
Beauty & Personal Care
India Hair Oil Market
Beauty & Personal Care
Anti-Acne Cosmetics Market
Beauty & Personal Care
Beauty and Personal Care Surfactants Market
Beauty & Personal Care
Europe Hair Styling Products Market
Beauty & Personal Care
Europe Hair and Skincare Market
Beauty & Personal Care
Dry Shampoo Market
Beauty & Personal Care
Beauty Salon Market
Beauty & Personal Care
UV Nail Gel Market
Beauty & Personal Care
Shaving and Hair Removal Products Market
Beauty & Personal Care
Online Cosmetics Market
Beauty & Personal Care
United Kingdom Dermocosmetics Market
Beauty & Personal Care
Global Bath Bomb Market
Beauty & Personal Care
North America Hair Removal Wax Market