
 Hair Removal Epilator Market | 2026-2036
Hair Removal Epilator Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Removal Epilator Market Analytics
Professional salon procurement is consolidating around multi-technology platforms that combine mechanical extraction with optical hair reduction. Braun leverages German engineering heritage to dominate precision motor design for rotary systems. Philips sustains broad channel control across European retail and Asian e-commerce platforms. Panasonic anchors Japanese manufacturing scale for cordless lithium-ion configurations.
Hair removal epilators are electromechanical or optical devices designed to extract or disable hair follicles through rotating tweezing discs, coiled springs, concentrated light pulses, or laser diodes operating at wavelengths between 600 and 1200 nanometers, serving consumer grooming and professional aesthetic treatment markets. Rotary epilators occupy the mature volume tier with established margin compression, while IPL and laser technology segments attract premium positioning through dermatological certification requirements. Cordless rechargeable power sources are displacing corded alternatives as lithium-ion energy density improves and consumers prioritize bathroom-counter mobility.
FDA 510(k) clearance pathways and EU MDR Class IIa device classifications shape product development timelines and clinical claim substantiation for optical epilator variants. REACH chemical compliance and IEC 60335 household appliance safety standards further constrain material selection and motor insulation specifications in export-oriented manufacturing. Stakeholders must monitor evolving dermatological device reimbursement codes and salon liability frameworks as professional adoption blurs the line between cosmetic grooming and clinical aesthetic procedures.
Market Dynamics
Professional aesthetic clinics are consolidating procurement around multi-technology platforms that fuse mechanical epilation with optical hair reduction, compressing single-function device margins while elevating certification barriers for new entrants.
Growth Catalysts
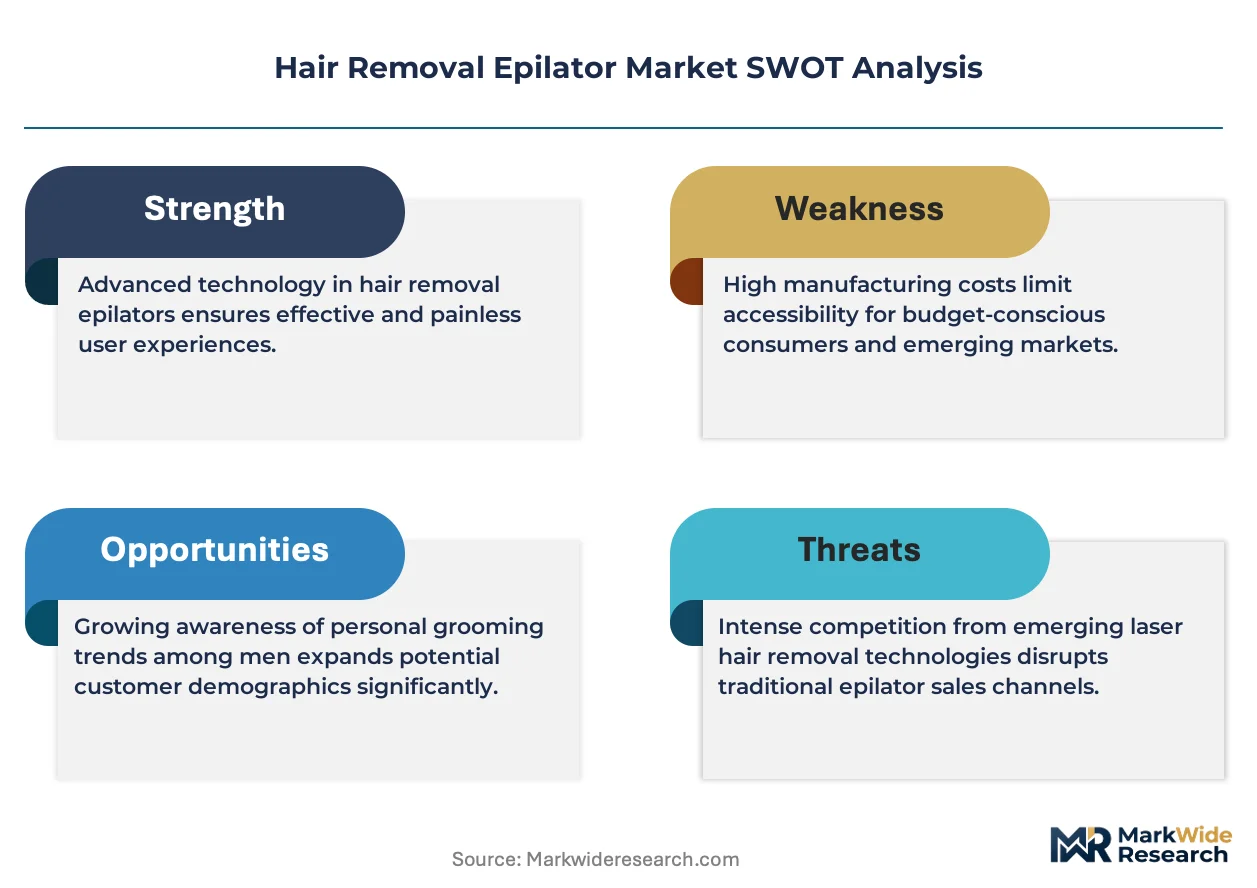
- EU MDR Class IIa pathways:Optical epilator variants now require clinical substantiation, favoring established manufacturers with dermatological testing infrastructure.
- Salon liability frameworks:Professional adoption blurs cosmetic grooming with clinical procedures, expanding reimbursable treatment categories in aesthetic medicine.
- Lithium-ion energy density gains:Cordless rechargeable configurations are displacing corded alternatives as bathroom-counter mobility becomes a priority specification.
Market Restraints
- Precision motor supply concentration:German engineering clusters dominate rotary system manufacturing, creating single-source vulnerability for tier-two assemblers.
- FDA 510(k) clearance timelines:Optical device variants face extended premarket review cycles that delay revenue recognition by 18-24 months.
- Intense pulsed light substitution:At-home IPL devices compete directly with mechanical epilators on convenience and pain perception metrics.
Strategic Opportunities
- India tier-two cities:Underpenetrated personal grooming markets present white-space expansion for mid-tier cordless configurations.
- Japan METI efficiency standards:Regulatory tailwinds favor low-power optical devices that exceed standby power consumption thresholds.
- Subscription accessory models:Blade cartridge replenishment programs through direct-to-consumer channels capture recurring revenue from device base.
Industry Challenges
- Biocompatibility testing capacity:Skin-contact material certification creates bottlenecks as REACH chemical compliance expands testing scope.
- IEC 60335 insulation redesign:Wet-use safety standards force motor housing reengineering that strains legacy manufacturing lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Removal Epilator Market |
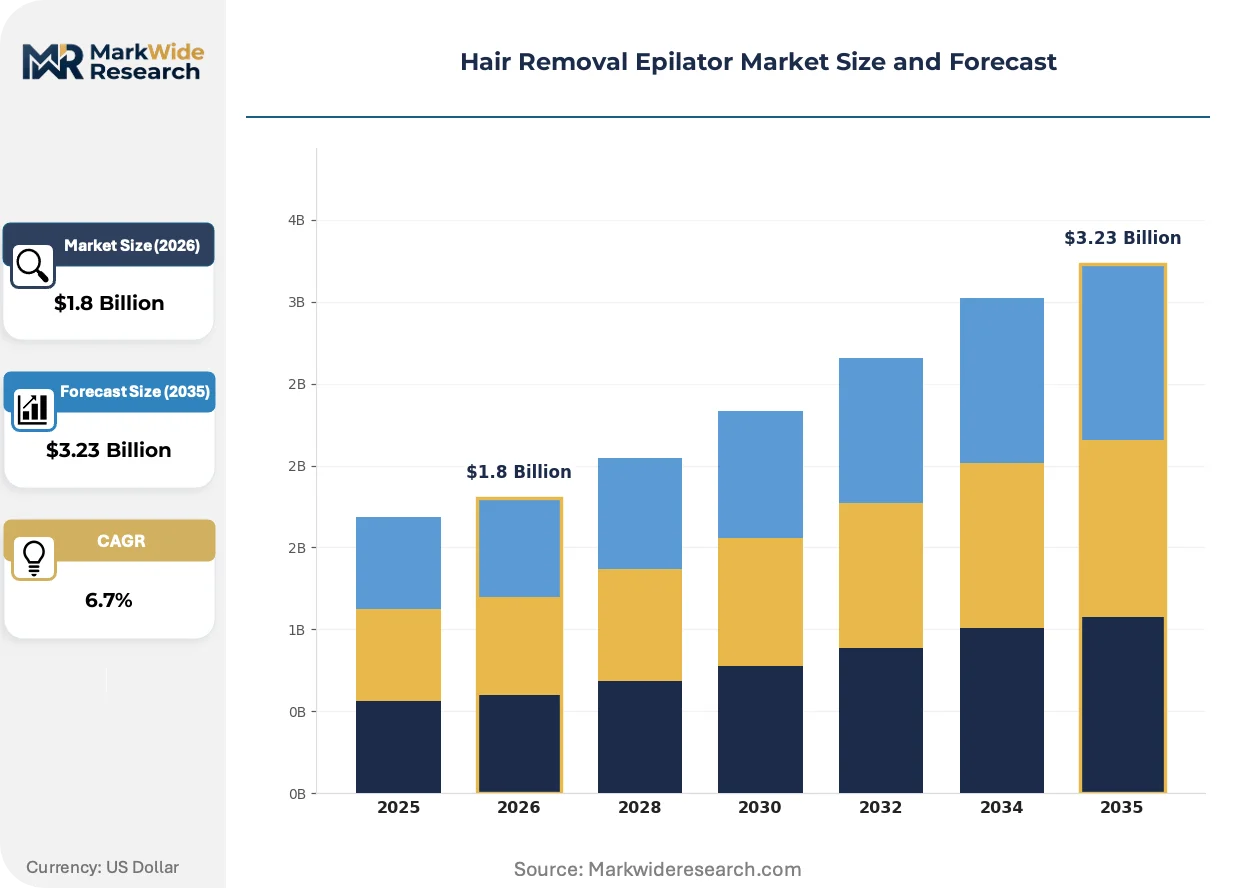
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Epilators, Spring Epilators, Laser Epilators, IPL Epilators End User: Women, Men, Professional Salons, Home Users Technology: Laser Technology, IPL Technology, Optical Technology, Mechanical Technology Power Source: Corded, Cordless, Rechargeable, Battery-operated |
| Companies Covered | Braun, Philips, Panasonic, Remington, Beurer, Emjoi, Conair Corporation, Epilady USA, Havells India, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Removal Epilator Market Evolving Landscape
Optical-mechanical convergence is redefining device architecture, with manufacturers embedding dermatological sensors and adaptive intensity controls to bridge consumer and professional use cases.
Smart skin-tone detection is electrifying safety protocols in at-home laser epilators. The technology adjusts pulse duration based on melanin density readings. Aesthetic clinic chains are adopting these sensor-equipped platforms for pre-treatment screening. This convergence is electrifying the boundary between consumer grooming and clinical-grade hair reduction.
REACH chemical compliance is tightening material selection for skin-contact components. The regulation now restricts certain phthalates in flexible housing polymers. Manufacturers serving European export markets are reformulating ABS blends and resubmitting biocompatibility dossiers. German precision-engineering clusters face the steepest retooling costs given their legacy supply contracts.
Direct-to-consumer trial programs are compressing purchase decision cycles. Subscription-based device testing allows users to evaluate pain tolerance before committing. Asian e-commerce platforms pioneered this model and are now exporting it to European markets. Younger demographics in South Korea and Japan show highest conversion rates from trial-to-purchase.
Hair Removal Epilator Market Segmentation
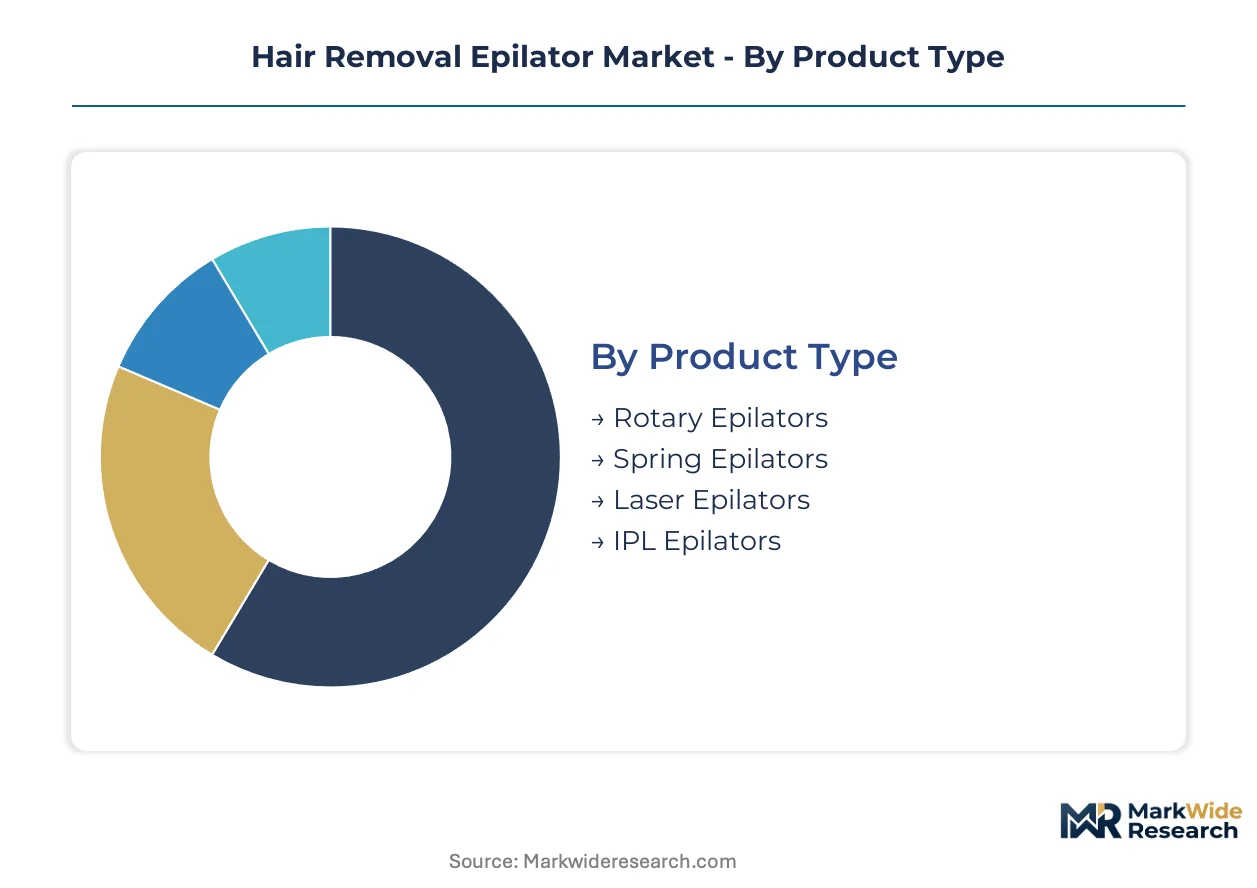
Epilator segmentation reveals divergent capital requirements across mechanical and optical platforms, with laser and IPL variants demanding dermatological certification infrastructure that reshapes competitive entry barriers. Understanding these segment-specific investment profiles illuminates why manufacturing concentration persists in German precision-engineering clusters for rotary systems while optical technologies attract specialized clinical device firms.
Product Type:
Capital intensity escalates sharply from mechanical extraction systems toward optical hair reduction platforms, with laser variants requiring the steepest upfront investment in clinical substantiation and safety testing infrastructure.
- Rotary Epilators:Rotating tweezing discs powered by precision DC motors extract hair through mechanical grasp-and-pull action. German manufacturing clusters in Solingen and Stuttgart dominate global supply, serving both European retail chains and Asian e-commerce platforms with established margin compression from commoditized motor sourcing.
- Laser Epilators:Diode-based systems operating at 600-1200 nanometers disable follicles through selective photothermolysis. FDA 510(k) clearance timelines and EU MDR Class IIa clinical substantiation requirements concentrate demand among dermatological device manufacturers with existing regulatory infrastructure.
- Spring Epilators:Coiled metal mechanisms historically preceded rotary designs but retain niche positioning for travel-sized formats.
- IPL Epilators:Broadband pulsed light systems compete directly with mechanical alternatives on convenience metrics.
Rotary epilators absorb the bulk of installed capacity; laser epilators are expanding most quickly.
End User:
Customer segmentation tracks divergent pain tolerance thresholds and purchase decision cycles, with professional channels demanding multi-technology platforms while home users prioritize bathroom-counter convenience.
- Professional Salons:Aesthetic clinic chains consolidate procurement around sensor-equipped platforms combining mechanical extraction with optical pre-treatment screening. Liability frameworks in Germany and France are expanding reimbursable treatment categories as cosmetic grooming blurs into clinical procedures.
- Women:Precision-engineered devices with ergonomic grip designs dominate this historically core segment. Braun and Philips sustain channel control through direct-to-consumer trial programs that compress purchase decision cycles in South Korea and Japan.
- Men:Coarser hair density requirements are driving demand for wider tweezer arrays and stronger motor torque specifications.
- Home Users:Cordless lithium-ion configurations prioritize mobility over clinical-grade power output.
Women constitute the largest installed user base; professional salons are climbing the fastest.
Technology:
Technology segmentation reflects fundamental divergence between electromechanical extraction and optical follicle disablement, with hybrid architectures emerging at the professional-clinical boundary.
- Mechanical Technology:Rotary and spring-based systems leverage precision motor engineering with established IEC 60335 household appliance safety compliance. Panasonic anchors Japanese manufacturing scale for cordless lithium-ion configurations serving Asian e-commerce platforms.
- IPL Technology:Intense pulsed light systems substitute for mechanical epilation through convenience and reduced pain perception. At-home variants compete directly with rotary devices while professional platforms integrate adaptive intensity controls.
- Laser Technology:Monochromatic coherent light sources require the most stringent biocompatibility testing for skin-contact components.
- Optical Technology:Broad category encompassing both laser and IPL modalities with overlapping regulatory pathways.
Mechanical technology retains the deepest installed base; IPL technology is gaining share fastest.
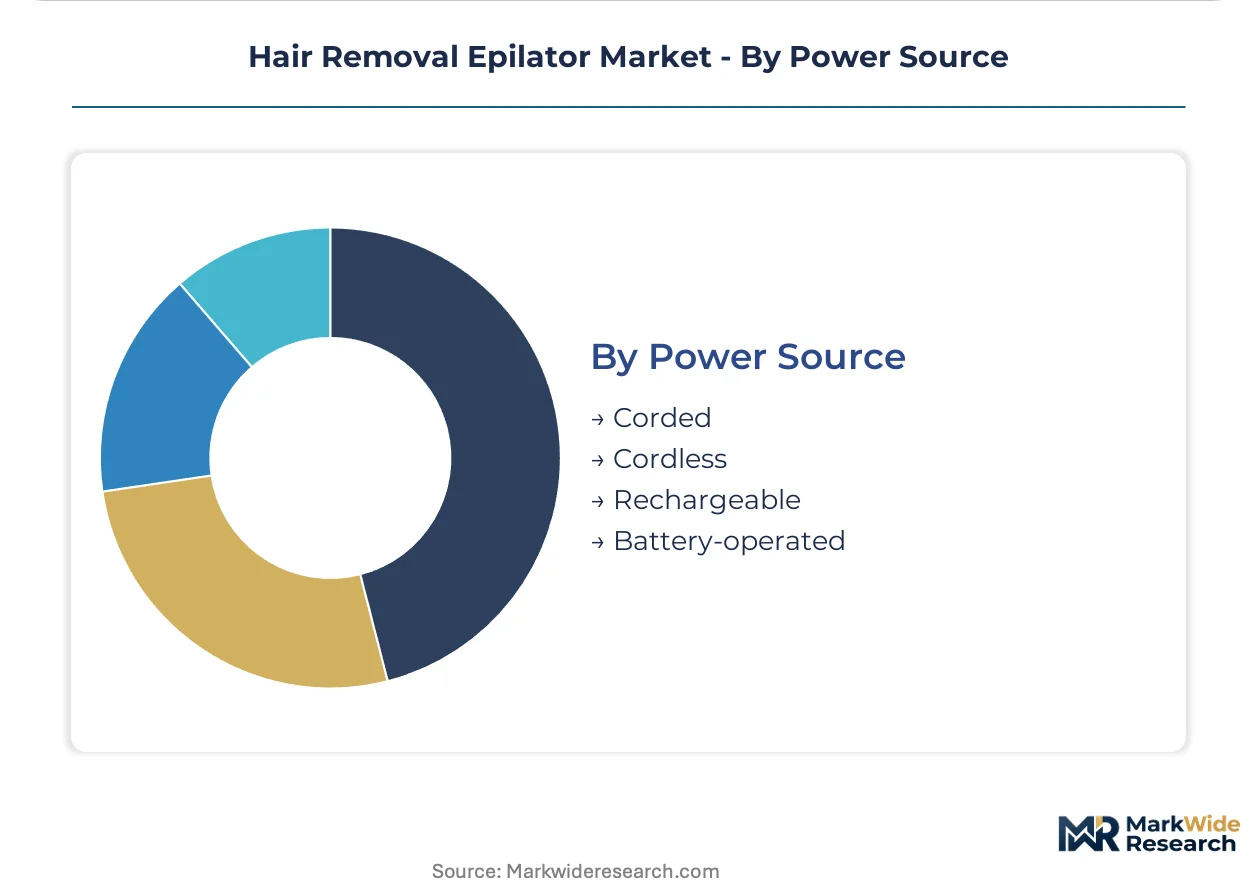
Power Source:
Power architecture segmentation tracks lithium-ion energy density improvements that are displacing corded alternatives across all price tiers.
- Cordless Rechargeable:Lithium-ion configurations with 40-60 minute runtime specifications now dominate premium positioning. Japan METI efficiency standards favor low-power optical devices that exceed standby power consumption thresholds, accelerating cordless adoption in Tokyo and Osaka metropolitan markets.
- Corded:Sustained power output maintains residual demand for professional salon installations where treatment duration exceeds battery limits.
- Battery-operated:Disposable alkaline configurations persist in entry-tier travel formats.
- Rechargeable:Nickel-metal hydride predecessors face displacement from lithium-ion alternatives.
Cordless rechargeable absorbs the bulk of new product development; corded retains professional salon anchoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Dongguan concentrate contract manufacturing for cordless lithium-ion configurations, while German precision-engineering clusters in Solingen anchor premium rotary motor production.
Germany
Professional salon procurement consolidates around multi-technology platforms combining mechanical extraction with optical pre-treatment. EU MDR Class IIa device classifications enforce clinical substantiation requirements that favor established dermatological testing infrastructure. The Stuttgart precision-engineering corridor houses specialized DC motor manufacturers serving both European retail chains and Asian export markets.
United States
FDA 510(k) clearance pathways for optical epilator variants extend premarket review timelines and compress single-function device margins. The agency's dermatological device reimbursement code expansions are blurring cosmetic grooming into clinical aesthetic procedures. California-based aesthetic clinic chains drive sensor-equipped platform adoption for pre-treatment screening protocols.
Japan
METI efficiency standards favor low-power optical devices exceeding standby power consumption thresholds, accelerating cordless adoption in Tokyo and Osaka metropolitan markets. Domestic manufacturers leverage lithium-ion energy density improvements to displace nickel-metal hydride predecessors across premium positioning tiers. The Kansai manufacturing belt anchors scale production for bathroom-counter mobility configurations.
China
GB standards for household appliance safety constrain material selection and motor insulation specifications in export-oriented manufacturing. Yangtze River Delta special economic zones concentrate assembly capacity for mid-tier cordless configurations targeting underpenetrated personal grooming markets. Shenzhen-based contract manufacturers serve direct-to-consumer trial programs pioneered on Asian e-commerce platforms.
India
BIS certification requirements for electrical appliances create compliance bottlenecks for imported optical device variants. Tier-two cities present white-space expansion opportunities as personal grooming penetration lags metropolitan benchmarks. Maharashtra and Gujarat industrial corridors host domestic assemblers sourcing precision motors from German engineering clusters.
Hair Removal Epilator Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated procurement patterns in professional salons contrasting fragmented consumer retail channels. The vendor base organizes around three strategic archetypes: heritage engineering houses with dermatological certification infrastructure, scale-driven electronics conglomerates with lithium-ion supply chain control, and regional assemblers serving price-sensitive entry tiers. Dominant competitive moves include backward integration into precision motor manufacturing and geographic expansion through direct-to-consumer trial programs on Asian e-commerce platforms.
Among heritage German engineering houses, Braun and Beurer occupy positions defined by precision motor design heritage and EU MDR compliance infrastructure. Panasonic anchors the scale-driven electronics tier through Japanese manufacturing scale for cordless configurations. These three exemplify how regulatory certification requirements and lithium-ion supply chain control determine competitive positioning across mechanical and optical technology segments.
| Leading Market Players |
|---|
| Braun |
| Philips |
| Panasonic |
| Remington |
| Beurer |
| Emjoi |
| Conair Corporation |
| Epilady USA |
| Havells India |
| Others |
Value Network & Pricing Analysis
Lithium carbonate price indices cascade through cordless epilator manufacturing, compressing margins on lithium-ion battery packs while amplifying price premiums for German-engineered precision motors that face constrained foundry capacity.
Pricing Analysis
Short lead-time premiums command pricing power for EU MDR-certified optical devices facing 18-24 month FDA clearance delays. Three-tier pricing structure across premium, standard, and economy levels separates dermatological-grade laser systems from cordless rotary units and disposable spring-based travel formats. Pricing pressure stems from at-home IPL substitution eroding mechanical epilator volumes in Asian e-commerce channels. Home users exhibit highest price sensitivity; professional aesthetic clinics absorb premium positioning for multi-technology platforms.
Supply Chain Analysis
Specialized tooling engineer availability in Stuttgart and Solingen anchors German precision motor production, while Shenzhen assembly corridors face technician turnover disrupting cordless configuration ramp-ups. Supply concentrates in Germany for rotary DC motors, Japan for lithium-ion cell integration, and China for mid-tier final assembly. ABS polymer housings, neodymium magnets, and dermatological sensor arrays constitute critical component dependencies. Single-source vulnerability concentrates in German precision-engineering clusters serving tier-two assemblers. Distribution runs through Asian e-commerce platforms for direct-to-consumer trial programs and European retail chains for heritage brand placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision motor foundry capacity constraints prop pricing premiums for EU MDR-compliant manufacturers, creating supply-constrained dynamics favoring incumbents with captive engineering infrastructure.
For Market Incumbents: To counter at-home IPL substitution eroding mechanical device volumes, backward integration into precision motor manufacturing secures component supply against German foundry bottlenecks while accelerating EU MDR clinical substantiation investments differentiates optical platforms from commoditized alternatives. For New Entrants and Emerging Players: Smart skin-tone detection algorithms offer entry pathways through sensor-equipped platforms bridging consumer and clinical use cases. India's tier-two cities present white-space expansion for mid-tier cordless configurations where personal grooming penetration lags metropolitan benchmarks. Direct-to-consumer trial programs on Asian e-commerce platforms compress purchase decision cycles for digital-native demographics. For Investors and Strategic Acquirers: Distressed-cycle entries favor dermatological device manufacturers with existing FDA 510(k) infrastructure in Germany and Japan amid regulatory compliance cost escalation. Long-term viability across the analysis window hinges on optical-mechanical convergence capabilities and lithium-ion supply chain control. Monitor EU MDR Class IIa clearance timeline extensions as inflection indicator for competitive consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Substantiation Investment | Accelerates market access for optical epilator variants against 18-24 month clearance timelines. |
| Backward Integration into Precision Motors | Secures supply from Stuttgart engineering clusters facing capacity constraints and single-source vulnerability. |
| Direct-to-Consumer Trial Program Launch | Compresses purchase cycles on Asian e-commerce platforms pioneered in South Korean and Japanese markets. |
| Smart Skin-Tone Detection Platform Development | Bridges consumer grooming and clinical aesthetic procedures through adaptive intensity controls. |
| India Tier-Two City Distribution Expansion | Captures white-space growth in Maharashtra and Gujarat corridors sourcing German precision motors. |
Research Methodology
Trade databases, EU MDR device registration filings, and lithium-ion supply chain disclosures formed the secondary backbone, cross-referenced against primary interviews with aesthetic clinic procurement directors, dermatological device regulatory affairs leads, precision motor manufacturing engineers, and Asian e-commerce platform category managers. Bottom-up unit economics triangulated against top-down market sizing across mechanical and optical technology segments.
Historical trendline analysis of cordless adoption rates and professional salon procurement patterns anchored the projection framework across product type, end user, technology, and power source dimensions. CAGRs derived from segment-level growth rate convergence modeling incorporated lithium-ion energy density improvement curves and EU MDR compliance cost trajectories as industry-specific inputs.
Several conditions sit outside the modeled scope, including unannounced regulatory pathway amendments, raw material price shocks, and geopolitical trade restrictions. Forecasts reflect documented assumptions regarding certification timeline stability and foundry capacity expansion. Material deviation in FDA 510(k) review velocity or German precision motor supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
North America Lip Care Products Market
Beauty & Personal Care
Japan Aromatherapy Products Market
Beauty & Personal Care
Beauty Salon Market
Beauty & Personal Care
Anti-Dandruff Shampoo Market
Beauty & Personal Care
Herbal Beauty Products Market
Beauty & Personal Care
Middle East and Africa Bath and Shower Products Market
Beauty & Personal Care
Europe Sustainable Personal Care Market
Beauty & Personal Care
Online Beauty and Personal Care Products Market
Beauty & Personal Care
Makeup Egg Market
Beauty & Personal Care
UV Nail Gel Lamp Market
Beauty & Personal Care
Hair Removal Creams for Private Parts Market
Beauty & Personal Care
Magnetic Eyelashes Market
Beauty & Personal Care
Global Personal Care Emollients Market
Beauty & Personal Care
United States Male Grooming Products Market
Beauty & Personal Care
Rice Shampoo Bar Market
Beauty & Personal Care
Brazil Cosmetics Market