
 Middle East and Africa Beauty and Personal Care Products Market | 2026-2036
Middle East and Africa Beauty and Personal Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Beauty and Personal Care Products Market Foresight
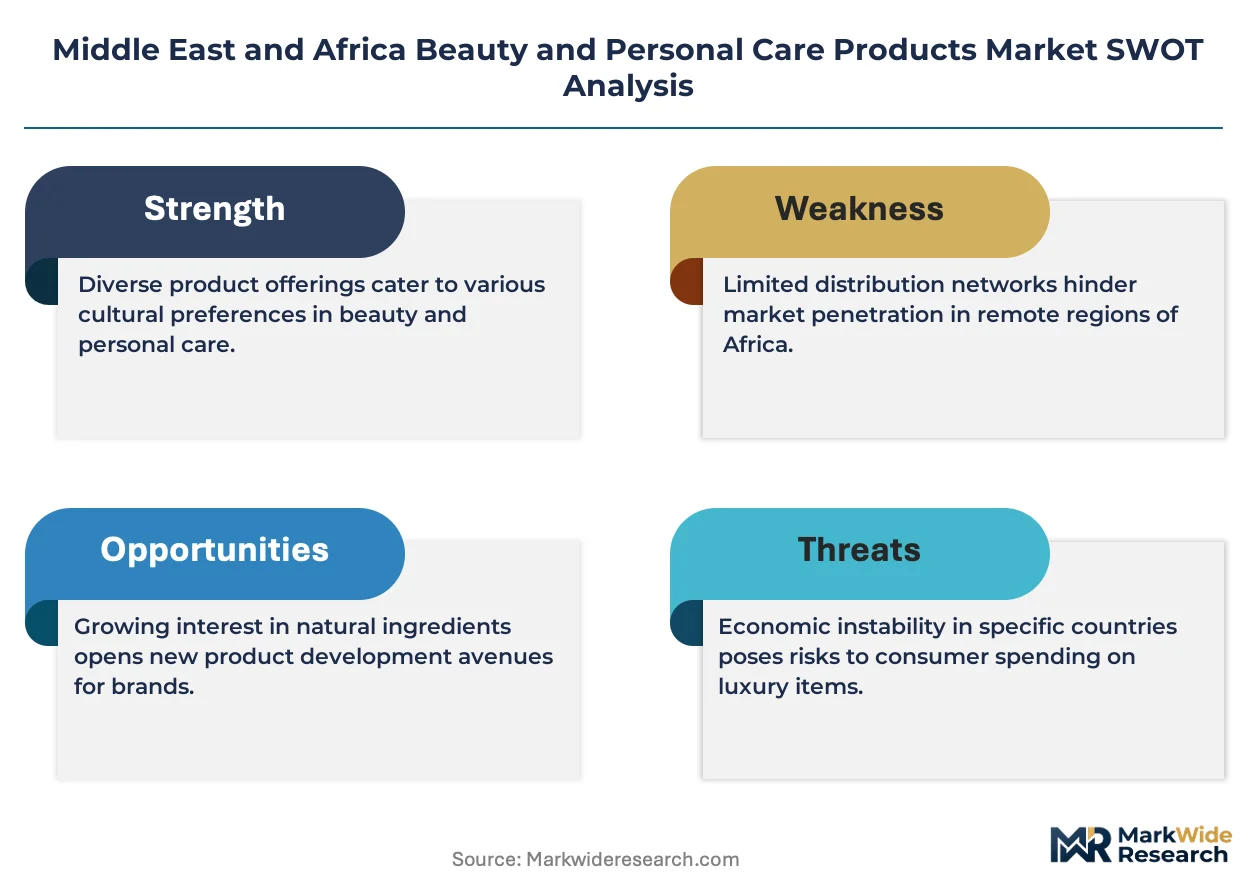
Premium-tier skincare is bifurcating the Middle East and Africa beauty and personal care products market into prestige and mass-market strata. L'Oréal SA leverages its dermatological science heritage to dominate professional-grade facial care across Gulf beauty halls. Unilever PLC anchors mass-market haircare through deep distribution networks in Nigeria and Kenya. Beiersdorf AG differentiates via Nivea's trusted dermocosmetic positioning in South African pharmacies.
Beauty and personal care products encompass topical formulations for skin, hair, color cosmetics, and scent designed for hygiene, aesthetic enhancement, and dermatological maintenance, typically requiring pH-balanced compositions and stability-tested emulsions suitable for tropical to arid climates. Haircare commands substantial shelf space across hypermarkets and salons due to textured-hair specialization needs, while online retail captures the fastest growth trajectory as digital payment infrastructure spreads. Fragrance maintains outsized margin pools reflecting Gulf consumers' preference for oud-based and alcohol-free perfumery variants.
SFDA in Saudi Arabia and MOHAP in the UAE enforce ingredient disclosure and halal compliance standards that determine market access for international brands. SASO technical regulations and South Africa's national standards body further shape packaging safety and labeling requirements across the trade corridor. Stakeholders must monitor evolving Gulf harmonization protocols and local content incentives as regulatory fragmentation risks complicate pan-regional scaling strategies.
Market Dynamics
Halal certification mandates from Gulf standardization bodies are forcing reformulation across entire product portfolios, compressing time-to-market timelines while opening premium positioning for compliant brands.
Growth Catalysts
- SFDA Ingredient Disclosure Mandates:Saudi Arabia's strict labeling requirements are accelerating transparency investments by international manufacturers seeking pharmacy and retail access.
- Textured-Hair Specialization:Salon-grade haircare tailored to African hair types commands dedicated shelf space and professional endorsement across Nigeria and Kenya.
- E-commerce Payment Infrastructure:Digital wallet penetration in the UAE and South Africa enables direct-to-consumer subscription models for skincare regimens.
Market Restraints
- Petrochemical Feedstock Volatility:Synthetic emulsifier and surfactant costs fluctuate with oil-indexed pricing, squeezing mass-market margin structures.
- Import Dependency Concentration:Gulf markets rely on concentrated European and Asian manufacturing hubs for finished formulations and active ingredients.
- Water-Scarcity Formulation Constraints:Arid-climate water restrictions limit traditional aqueous product development in Saudi Arabia and UAE production facilities.
Strategic Opportunities
- Ethiopian Retail Infrastructure:Underdeveloped modern trade in Addis Ababa and secondary cities offers first-mover positioning for organized beauty retail formats.
- Oud-Based Alcohol-Free Perfumery:Traditional Gulf scent preferences align with halal compliance requirements, creating distinctive export positioning.
- Dermocosmetic Pharmacy Channels:South African and Saudi pharmacy networks reward clinically positioned skincare with professional recommendation access.
Industry Challenges
- Halal Certification Timeline Compression:Gulf standardization bodies require extended testing protocols that delay product launches by 8-14 months.
- Formulation Chemist Scarcity:Specialized expertise in pH-stable emulsions for tropical-to-arid climate adaptation remains concentrated in European technical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Beauty and Personal Care Products Market |
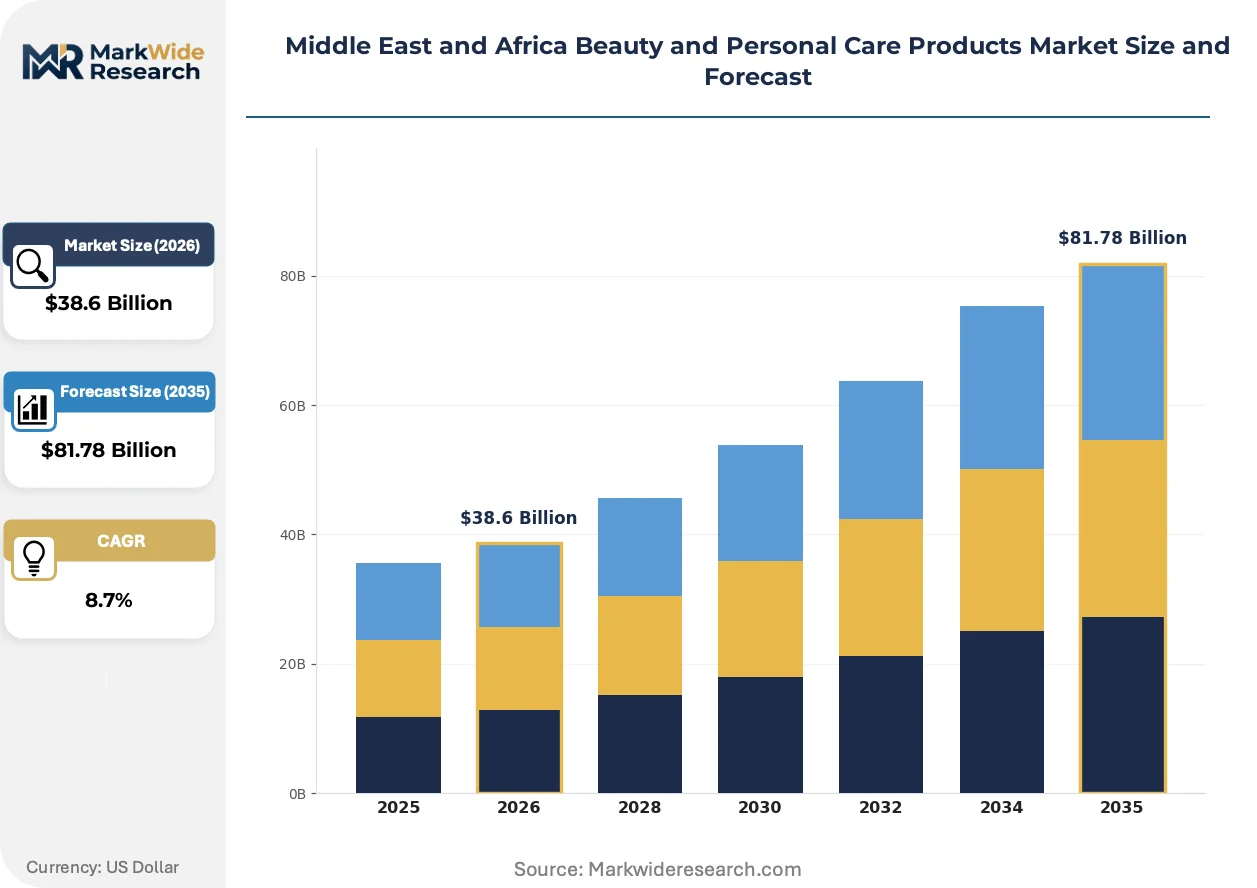
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance End User: Women, Men, Children, Unisex Distribution Channel: Hypermarkets, Specialty Stores, Online Retail, Salons Packaging Type: Tube, Bottle, Jar, Box |
| Companies Covered | The Estée Lauder Companies Inc, Coty Inc, L'Oréal SA, Oriflame Cosmetics Global SA, LVMH Moët Hennessy Louis Vuitton SE, Unilever PLC, Procter & Gamble, PZ Cussons Plc, Beiersdorf AG, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Beauty and Personal Care Products Market Shifts & Advancements
Biotechnology-derived actives and AI-enabled personalization are converging with regulatory transparency demands to reshape product development cycles and consumer relationship models across Middle East and Africa markets.
Biotechnology fermentation platforms for hyaluronic acid and peptide production is supplanting traditional animal-derived sourcing methods. Gen Z consumers in Saudi Arabia and the UAE adopt these bio-identical alternatives at accelerated rates. This shift compresses supply chains while enabling cruelty-free and halal-compliant claims that unlock premium pharmacy placement.
MOHAP in the UAE and SASO technical regulations are mandating blockchain-traceable ingredient provenance for imported cosmetics. Manufacturers must retrofit supply chain documentation systems to satisfy granular disclosure requirements. Professional-grade skincare segments face the steepest compliance costs, passing investments through to prestige-tier pricing.
Subscription-based replenishment models displace traditional retail stocking behaviors among millennial consumers in South Africa and Nigeria. Direct-to-consumer platforms capture recurring revenue while bypassing fragmented wholesale distribution. This channel shift concentrates customer data ownership with brands, enabling predictive formulation development tailored to regional climate exposure patterns.
Middle East and Africa Beauty and Personal Care Products Market Segmentation
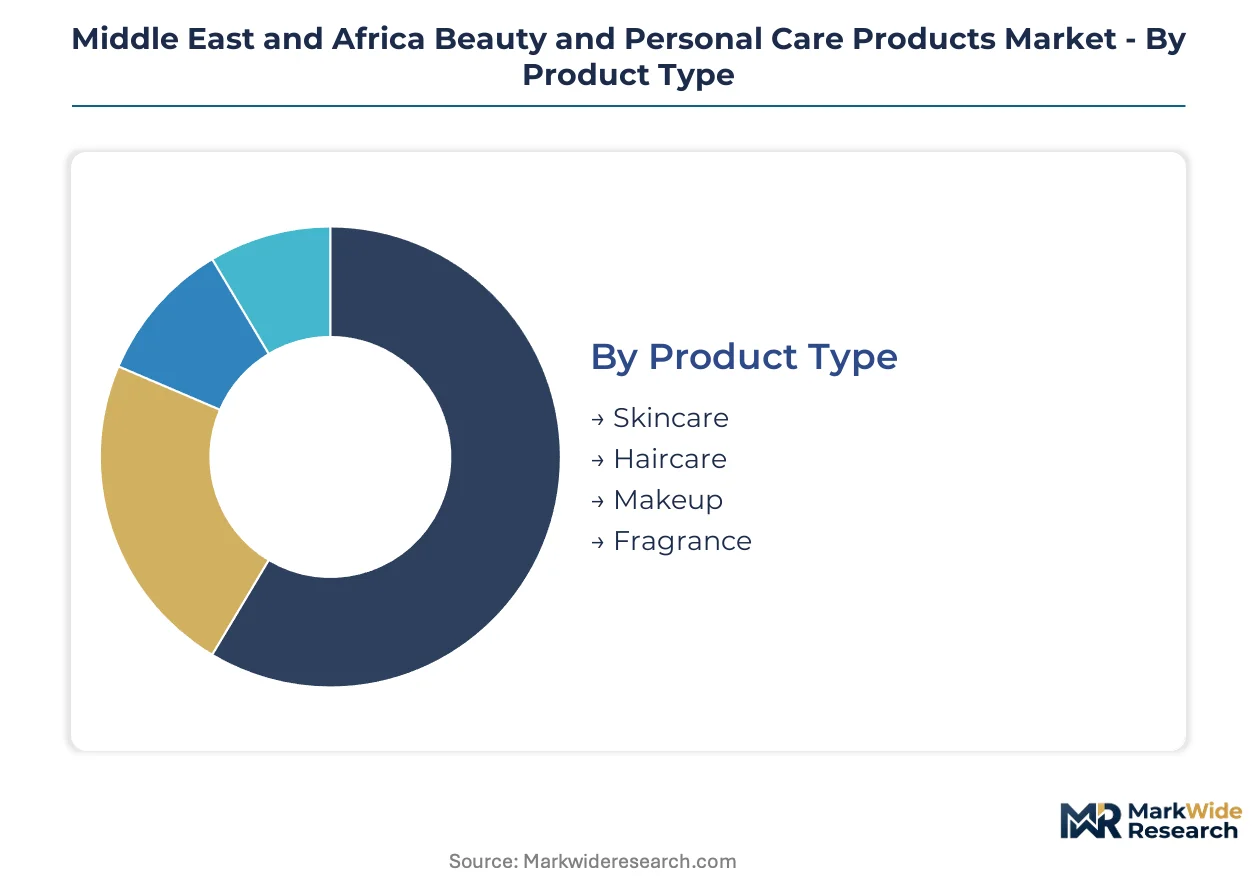
Segmentation across the Middle East and Africa beauty and personal care products market reveals distinct channel affinities and formulation requirements. Each dimension shapes procurement patterns, pricing architecture, and regulatory compliance burdens differently across Gulf and sub-Saharan markets.
Product Type:
Channel-mix patterns diverge sharply across product categories, with prestige skincare concentrating in pharmacy and specialty retail while mass haircare dominates hypermarket shelf space.
- Skincare:Dermatologically tested serums, moisturizers, and sun protection formulations with pH-balanced emulsions for arid climates. Demand concentrates in Saudi Arabian and UAE pharmacy networks where SFDA and MOHAP compliance unlocks professional recommendation access. Halal-certified biotechnology-derived actives command premium positioning among millennial consumers in Dubai and Riyadh.
- Haircare:Textured-hair specialized shampoos, conditioners, and styling treatments formulated for African curl patterns and Gulf humidity exposure. Nigerian and Kenyan salon channels drive professional-grade volume, while mass-market variants distribute through Lagos and Nairobi hypermarket chains. Import dependency for synthetic surfactants creates margin pressure when petrochemical feedstock costs fluctuate.
- Makeup:Color cosmetics including foundation, eye products, and lip formulations with halal-compliant ingredient profiles. South African specialty stores and UAE duty-free corridors capture prestige-tier transactions.
- Fragrance:Oud-based and alcohol-free perfumery variants aligned with Gulf consumer preferences and religious compliance requirements. Dubai mall anchors and Jeddah luxury retail concentrate high-margin prestige sales.
By volume, Haircare leads. By growth pace, Skincare is ahead.
End User:
Cost-tier stratification separates mass-market children's formulations from prestige unisex positioning, with men's grooming commanding intermediate pricing in urban Gulf markets.
- Women:Comprehensive product portfolios spanning skincare regimens, color cosmetics, and fine fragrance with the highest per-capita spending concentration. Saudi Arabian and Emirati female consumers drive premium-tier pharmacy and specialty store traffic.
- Men:Grooming-focused skincare, beard care, and masculine-coded fragrance with accelerating adoption among young professionals in Johannesburg and Casablanca. E-commerce subscription models capture recurring replenishment demand.
- Children:Hypoallergenic, mild-formulation bath and skincare products with stringent safety testing requirements. Mass-market pricing dominates through Nigerian and Kenyan supermarket channels.
- Unisex:Gender-neutral skincare and fragrance positioning with minimalist packaging aesthetics. South African urban millennials and Gen Z consumers in Dubai adopt these variants fastest.
Women's segments generate the largest revenue pool. Unisex positioning is expanding most quickly.
Distribution Channel:
Volume concentration favors hypermarket infrastructure, while margin capture shifts toward direct-to-consumer platforms as digital payment penetration deepens.
- Hypermarkets:High-footfall retail formats with extensive haircare and mass skincare shelf space across Lagos, Nairobi, and Cairo. South African chains anchor volume throughput with promotional pricing cycles.
- Specialty Stores:Curated beauty halls and dedicated brand boutiques in Dubai Mall, Riyadh Park, and Johannesburg Sandton City. Prestige fragrance and professional-grade skincare concentrate here with trained beauty advisor support.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators leveraging UAE and South African digital wallet infrastructure. Subscription replenishment models for skincare regimens gain traction among millennial consumers.
- Salons:Professional-only haircare and treatment products with stylist endorsement driving textured-hair specialization sales across Nigeria and Kenya.
Hypermarkets move the most units. Online retail is gaining share fastest.
Packaging Type:
Supply concentration for primary packaging materials shapes formulation-to-format matching, with water-scarcity constraints favoring concentrated and solid formats.
- Tube:Flexible polyethylene or aluminum-laminate containers for creams, lotions, and cleansers with precise dispensing control. Saudi Arabian production facilities favor tubes for travel-size and halal-certified skincare exports.
- Bottle:Rigid PET or glass containers for shampoos, conditioners, and liquid skincare with pump or flip-cap closures. Nigerian hypermarket haircare relies heavily on family-size bottle formats.
- Jar:Wide-mouth glass or polypropylene containers for thick creams, masks, and balms requiring finger or spatula application. Premium skincare in UAE specialty stores adopts weighted glass jars for tactile luxury signaling.
- Box:Secondary cartons and rigid packaging for fragrance sets, gift configurations, and multi-product kits. Dubai duty-free corridors drive seasonal box-format volume for oud-based perfumery.
Bottles dominate unit volume. Tubes show the steepest expansion trajectory in water-constrained formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
French and German exporters dominate premium skincare shipments into Gulf retail corridors, while South African distributors anchor sub-Saharan supply networks through Johannesburg logistics hubs.
Saudi Arabia
Millennial consumers in Riyadh and Jeddah drive prestige facial care adoption through pharmacy and specialty retail channels. SFDA enforces ingredient disclosure mandates that compress time-to-market for international brands. The Eastern Province industrial zone hosts localized production facilities adapting European formulations for halal compliance requirements.
United Arab Emirates
Dubai Mall and Abu Dhabi luxury corridors concentrate high-margin fragrance transactions among tourists and resident expatriates. MOHAP mandates blockchain-traceable ingredient provenance for all imported cosmetics entering UAE ports. Jebel Ali free trade zone serves as the regional redistribution hub for Gulf Cooperation Council markets.
South Africa
Johannesburg Sandton City and Cape Town V&A Waterfront anchor prestige skincare and color cosmetics demand among urban professionals. The country's national standards body enforces packaging safety and labeling requirements that align with broader Southern African Development Community protocols. Durban chemical manufacturing clusters supply surfactant inputs to regional haircare formulators.
Nigeria
Lagos and Abuja hypermarket chains drive mass-market haircare volume for textured-hair specialization needs. The country's national standards organization maintains import inspection protocols for personal care products entering through Apapa port. Ikeja industrial district hosts secondary packaging and labeling operations serving West African distribution networks.
Kenya
Nairobi salon channels professional-grade haircare sales supported by stylist endorsement networks. The Kenya Bureau of Standards regulates cosmetic product registration and quality certification for East African Community trade compliance. Mombasa port logistics facilities handle bulk surfactant imports destined for regional formulation plants.
Middle East and Africa Beauty and Personal Care Products Market Competitive Landscape
Listed leaders compete with private specialists across distribution reach and formulation heritage, creating a tiered structure where scale advantages meet localized agility. European-headquartered multinationals anchor pharmacy and prestige retail through dermatological science positioning. Mass-market penetration depends on deep wholesale networks across fragmented sub-Saharan trade corridors. Two dominant competitive moves are reshaping positioning: halal certification investments that unlock Gulf market access, and direct-to-consumer platform development that bypasses traditional distributor relationships.
Within the prestige-tier vector, L'Oréal SA and The Estée Lauder Companies Inc occupy positions anchored by dermatological heritage and luxury fragrance portfolios. Beiersdorf AG exemplifies the dermocosmetic specialist archetype through pharmacy-focused distribution models. Unilever PLC represents scale-driven mass-market penetration across emerging African economies. These three anchors illustrate how competitive positioning splits between science-backed premium claims and volume-driven accessibility strategies.
| Leading Market Players |
|---|
| The Estée Lauder Companies Inc |
| Coty Inc |
| L'Oréal SA |
| Oriflame Cosmetics Global SA |
| LVMH Moët Hennessy Louis Vuitton SE |
| Unilever PLC |
| Procter & Gamble |
| PZ Cussons Plc |
| Beiersdorf AG |
| Others |
Supply & Pricing Matrix
Biotechnology-derived actives substituting animal-sourced ingredients simultaneously relocate supply geography toward European fermentation hubs and compress premium-tier pricing power as halal-compliant claims become table stakes rather than differentiators.
Pricing Analysis
Next-generation biotechnology actives command 40-60% premiums over conventional synthetic alternatives, while legacy petrochemical-based formulations face accelerating price erosion. Three-tier pricing structure across prestige dermocosmetic, mass-market functional, and economy basic tiers separates pharmacy-endorsed brands from hypermarket staples. Cost compression in mass-market haircare intensifies because Nigerian and Kenyan distributors demand promotional depth to move volume. Small-format sachet buyers in West African open markets exhibit extreme price sensitivity, whereas Saudi pharmacy consumers prioritize halal certification and clinical positioning over unit economics.
Supply Chain Analysis
Germany and France anchor active ingredient production for prestige skincare, while China and India supply synthetic surfactants and packaging materials for mass-market formulations. Regional formulation depends on imported hyaluronic acid, peptide complexes, and halal-certified emulsifiers. Single-source vulnerability concentrates in European biotechnology fermentation capacity for premium actives. Distribution runs through Jebel Ali free trade zone for Gulf markets and Johannesburg logistics hubs for sub-Saharan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Halal certification requirements create regulatory entrenchment moats for compliant incumbents, as SFDA and MOHAP testing protocols impose 8-14 month barriers that new entrants cannot circumvent without dedicated compliance infrastructure.
For Market Incumbents: Compound pharmacy channel dominance by embedding clinical advisory relationships with Saudi and South African dermatologists that switching costs protect. Expand backward integration into halal-certified raw material sourcing to defend margin position against petrochemical feedstock volatility. Prioritize blockchain-traceable supply chain documentation as MOHAP mandates harden disclosure requirements.
For New Entrants and Emerging Players: Subscription-based replenishment service gaps where incumbents under-serve millennial consumers in Lagos and Nairobi offer white-space entry with direct-to-consumer platforms. Target Ethiopian modern trade infrastructure before organized retail formats consolidate. Pursue textured-hair specialization partnerships with Nairobi salon networks as the go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a certification-intensification phase that favors vertically integrated specialists with captive halal-compliant supply chains. Long-term viability hinges on regulatory compliance infrastructure rather than brand equity alone. Acquisition targets should demonstrate established SFDA/MOHAP approval track records. Watch halal certification timeline compression as the inflection signal—accelerating approval speeds would erode incumbent moats.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Investment | SFDA and MOHAP compliance unlocks pharmacy channel access across Gulf markets. |
| Direct-to-Consumer Platform Launch | Subscription models bypass fragmented Nigerian and Kenyan wholesale distribution layers. |
| Biotechnology Active Sourcing | Fermentation-derived ingredients satisfy cruelty-free and halal positioning requirements simultaneously. |
| Textured-Hair Specialization Partnership | Salon endorsement networks in Nairobi and Lagos drive professional-grade haircare volume. |
| Blockchain Supply Chain Documentation | MOHAP-mandated ingredient provenance traceability becomes competitive compliance differentiator. |
Research Methodology
Desk research of customs trade databases, SFDA regulatory filings, and MOHAP import documentation preceded structured interviews with brand managers at multinational beauty companies, pharmacy chain procurement directors, and Nairobi salon distribution network operators. Primary fieldwork with UAE specialty retail buyers and South African dermocosmetic brand managers combined with secondary validation against SASO technical regulations and Kenya Bureau of Standards certification records. Bottom-up volume modeling across product categories triangulated with top-down value estimates from trade flow analysis.
Variance decomposition across the projection horizon isolates pricing, volume, and mix effects within each segmentation dimension—product type, end user, distribution channel, and packaging format. Modeled inputs include halal certification penetration rates, digital wallet adoption curves in South Africa and Nigeria, and petrochemical feedstock cost indices. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion constraints.
Material uncertainties—regulatory timeline shifts, biotechnology fermentation capacity bottlenecks, and Gulf currency peg adjustments—sit outside the modeled envelope. Forecasts reflect assumptions about sustained SFDA and MOHAP disclosure mandate enforcement and continued e-commerce payment infrastructure deepening. Recalibration cycles align with material shifts in halal standard harmonization protocols and regional trade corridor development.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Germany Cosmetics for Pregnancy Market
Beauty & Personal Care
Body Firming Creams Market
Beauty & Personal Care
Sunless Tanners Market
Beauty & Personal Care
Beeswax for Cosmetics Market
Beauty & Personal Care
Natural Hair Care Product Market
Beauty & Personal Care
Frizz Control Shampoo Market
Beauty & Personal Care
Middle East and Africa Hair Conditioner Market
Beauty & Personal Care
Soap Market
Beauty & Personal Care
Beauty Salon Market
Beauty & Personal Care
Luxury Hair Care Market
Beauty & Personal Care
Canada Dermocosmetics Market
Beauty & Personal Care
North America Setting Spray Market
Beauty & Personal Care
In-Wash Scent Booster Market
Beauty & Personal Care
Hair Styling Equipment Market
Beauty & Personal Care
Brazil Sustainable Personal Care Market
Beauty & Personal Care
Gua Sha Tools Market