
 Body Care Products Market | 2026-2036
Body Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Body Care Products Market Outlook
Southeast Asia is narrowing the gap between regional formulation capacity and export-grade quality standards. Beiersdorf AG leverages its dermatological R&D heritage to sustain premium positioning across European and Asian markets. Unilever PLC anchors volume production through distributed manufacturing networks that serve mass-market retail channels. L'Oréal S.A. differentiates via science-backed ingredient storytelling that commands shelf space in specialty stores.
Body care products encompass topical formulations—emulsions, anhydrous systems, and hydroalcoholic gels—designed to cleanse, moisturize, protect, or fragrance the skin surface, typically incorporating active concentrations between one and five percent for functional claims. The lotion and cream categories dominate value generation due to higher per-unit pricing and repeat purchase frequency, while gel formats lead growth velocity among male and teenage demographics seeking non-residue textures. Natural and organic ingredient types command disproportionate margin pools as clean-label certification becomes a prerequisite for pharmacy and specialty store placement.
FDA cosmetic regulations and the EU REACH framework govern ingredient safety thresholds, while ECHA's ongoing microplastic restrictions are forcing reformulation of exfoliating body washes and glitter-containing products. The EU Green Deal's packaging waste directives are compressing conventional plastic use in body care containers. Stakeholders must monitor evolving biopolymer packaging economics and pre-market safety data requirements to preserve market access across regulated jurisdictions.
Market Dynamics
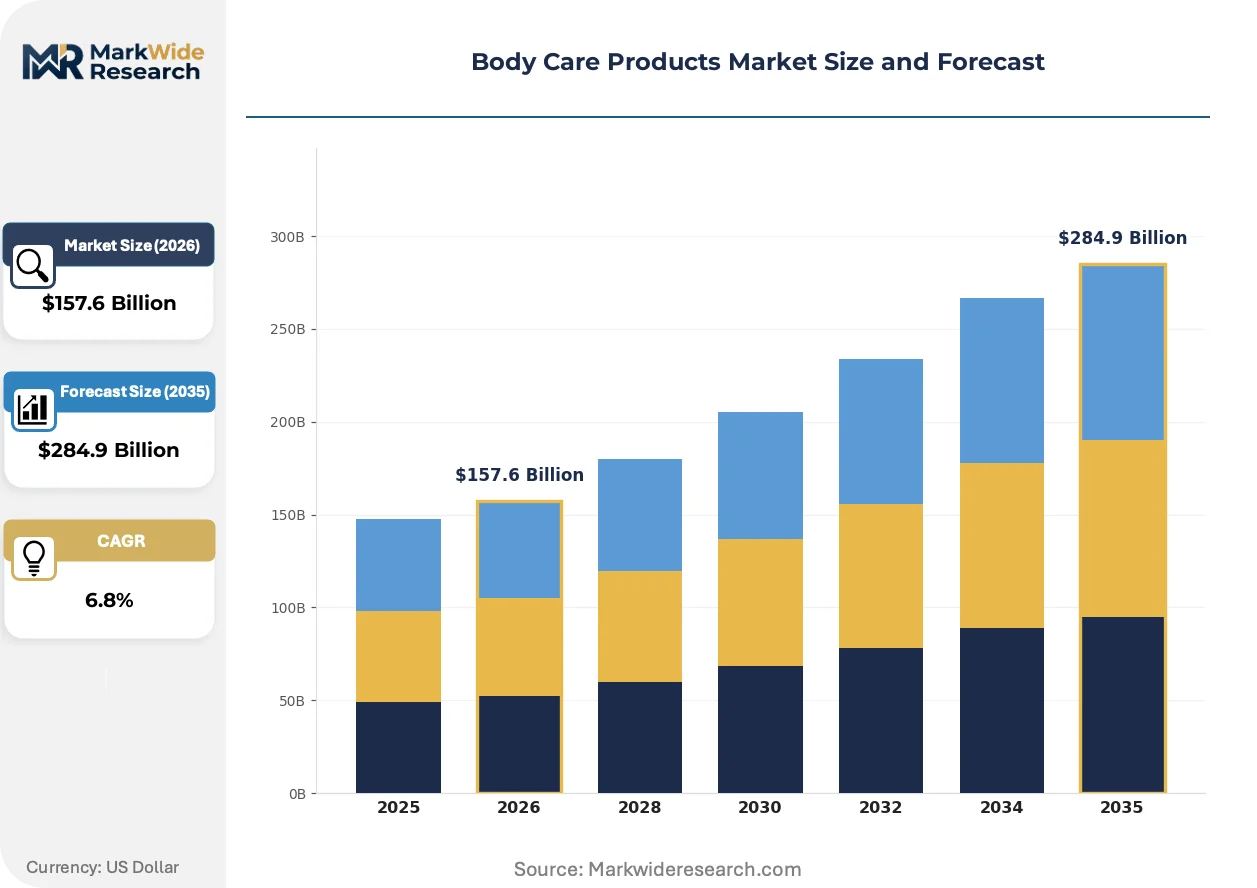
Clean-label certification requirements are compressing conventional formulation margins while forcing rapid supplier base consolidation across raw material networks. REACH microplastic restrictions and FDA safety data mandates are simultaneously raising compliance thresholds and reshaping competitive entry barriers.
Growth Catalysts
- EU Green Deal packaging directives:Biopolymer container demand is accelerating as brands race to secure pharmacy shelf placement ahead of 2030 waste reduction targets.
- Working professional demographics:Premium skincare routine adoption among urban employed adults is expanding per-capita spend and repeat purchase frequency in developed markets.
- Southeast Asian manufacturing upgrades:Export-grade quality capability investments in Indonesia and Vietnam are unlocking duty-advantaged supply to European and North American distributors.
Market Restraints
- Natural ingredient input volatility:Cold-pressed botanical oil prices fluctuate with harvest yields and climate disruption, compressing margin predictability for organic-positioned brands.
- Specialty chemical supplier concentration:Three German and Swiss firms control majority supply of pharmaceutical-grade emulsifiers, creating bottleneck risk for mid-tier formulators.
- Preservative system technical limitations:Clean-label alternatives to parabens demonstrate shorter shelf stability, forcing accelerated inventory turnover and cold-chain investments.
Strategic Opportunities
- Men's non-residue gel formats:Underpenetrated male grooming segments in South Korea and Australia present whitespace for texture-innovative product lines.
- Pharmacy channel expansion:Dermatologist-endorsed positioning is opening dedicated shelf space in European apothecary networks previously reserved for Rx-adjacent skincare.
- Post-consumer recycled content mandates:California and New York packaging laws are creating first-mover advantage for brands with verified closed-loop container supply chains.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise bridging natural ingredient stability and regulatory compliance commands premium compensation, constraining R&D team scaling.
- Pre-market safety data capex:FDA Modernization Act requirements for substantiated ingredient safety dossiers demand multi-year investment before revenue generation.
- Legacy ERP integration friction:Batch-level traceability systems for clean-label verification often conflict with decades-old manufacturing software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Body Care Products Market |
| Market Size in 2026 | $157.6 Billion |
| Market Size in 2035 | $284.9 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lotion, Cream, Gel, Oil Customer Type: Adults, Teenagers, Seniors, Children Distribution Channel: Online, Supermarkets, Pharmacies, Specialty Stores Ingredient Type: Natural, Organic, Synthetic, Herbal |
| Companies Covered | Beiersdorf AG, The Procter & Gamble Company, Unilever PLC, L'Oréal S.A., Colgate-Palmolive Company, Johnson & Johnson Services Inc., Kao Corporation, The Estée Lauder Companies Inc., Bath & Body Works Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Body Care Products Market Strategic Shifts
Biotechnology-derived actives and precision fermentation are displacing conventional extraction methods while waterless formulation formats are compressing shipping volumes and preservative loads. Regulatory fragmentation between jurisdictions is accelerating regional formulation specialization.
Biotech-derived squalane and hyaluronic acid produced via microbial fermentation are rendering obsolete traditional shark-liver and rooster-comb extraction supply chains. Premium and pharmacy-positioned brands in Germany and Japan are adopting these inputs at accelerated procurement cycles. The shift is compressing reliance on wild-harvested marine and animal derivatives while stabilizing raw material costs.
REACH Annex XVII microplastic restrictions are forcing exfoliating body wash reformulations across European manufacturing facilities. ECHA's 2023 glitter and microbead prohibitions have eliminated polyethylene-based scrub agents from rinse-off products. Brands are responding with cellulose, silica, and seed-based mechanical exfoliants that require redesigned stability testing protocols.
Ingredient transparency apps and blockchain-verified sourcing claims are reshaping purchase decisions among millennial and Gen-Z cohorts. Direct-to-consumer channels and specialty retailers are capturing share from mass-market supermarkets by offering batch-traceable product lines. This behavior shift concentrates in urban coastal United States markets and Scandinavian capitals where digital literacy and sustainability concern intersect.
Body Care Products Market Segmentation
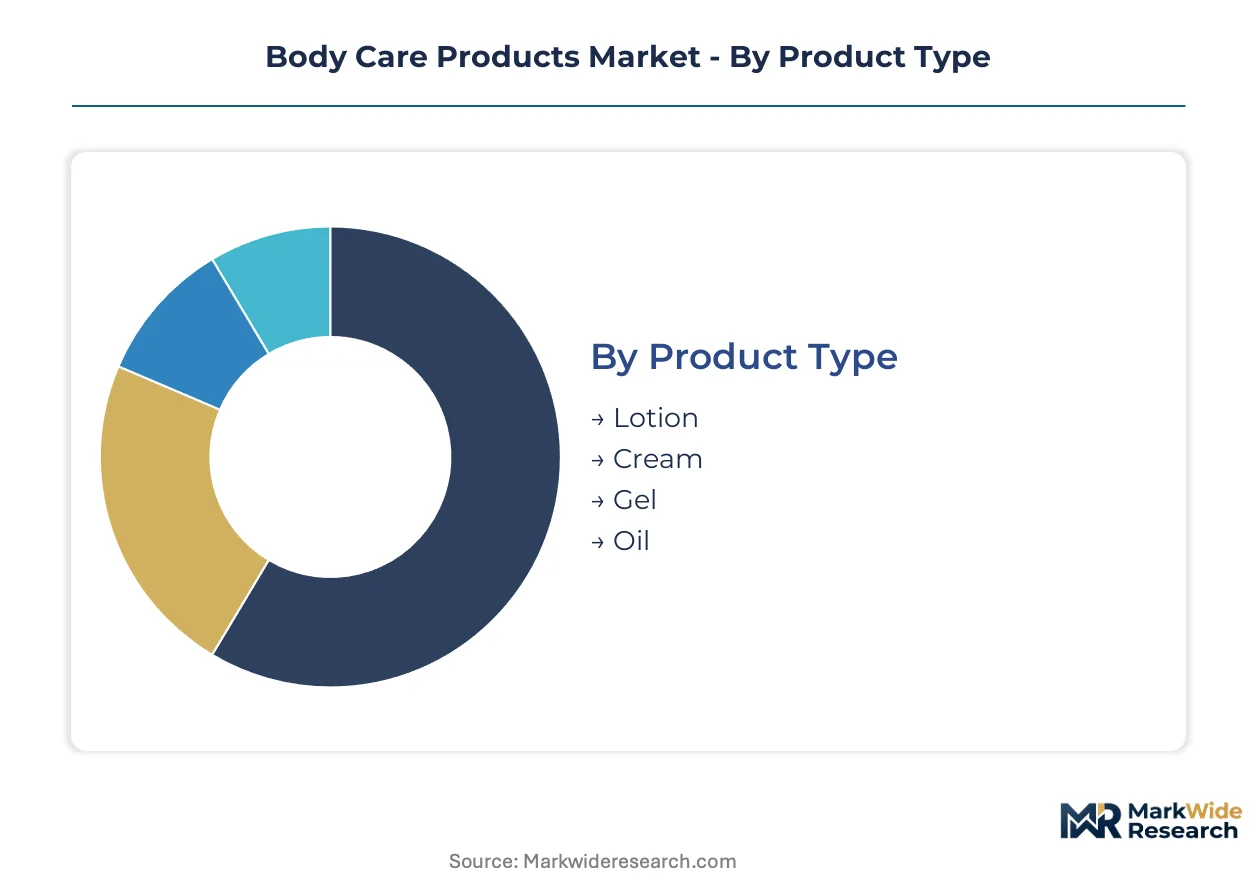
Segmentation in body care products reveals distinct performance profiles across formulation chemistry, demographic targeting, and channel economics. Each dimension carries unique margin structures and regulatory exposure that shape portfolio allocation decisions for manufacturers.
Product Type:
After-sales service intensity varies sharply across product formats, with emulsion-based systems requiring formulation troubleshooting support that gel and oil formats rarely demand.
- Lotion:Water-in-oil or oil-in-water emulsions with 60-80% aqueous content deliver lightweight hydration suited for daily application and large-surface coverage. Working professionals in the United States drive repeat purchase frequency for pump-dispensed workplace and gym bag formats. Lotion holds the largest share; momentum sits with gel formats among male demographics.
- Cream:Higher viscosity anhydrous or low-water formulations incorporate occlusive agents like petrolatum or shea butter for barrier repair in compromised skin conditions. Pharmacy channels in Germany and France allocate dedicated shelf space to dermatologist-endorsed cream lines for atopic and mature skin presentations.
- Gel:Hydroalcoholic or carbomer-thickened aqueous systems provide rapid absorption without residue, aligning with male grooming preferences in South Korea and Australia. Non-comedogenic claims support facial-body dual-use positioning.
- Oil:Anhydrous lipid blends—squalane, jojoba, or fractionated coconut—serve massage and bath rituals with premium per-unit economics. Clean-label positioning requires cold-pressed extraction verification and accelerated rancidity testing protocols.
Cream and lotion dominate pharmacy and mass retail shelf space; oil formats are climbing fastest through direct-to-consumer subscription models.
Customer Type:
Cost tier stratification separates premium anti-aging investments from price-sensitive family purchase decisions across household demographics.
- Adults:Working professionals aged 25-55 represent concentrated per-capita spend through premium routine adoption and ingredient literacy. Urban employed cohorts in coastal United States markets demonstrate willingness to pay for blockchain-verified sourcing claims and batch-level traceability.
- Teenagers:Acne-prone skin concerns drive benzoyl peroxide and salicylic acid formulation demand, with texture preferences favoring lightweight gels over occlusive creams. Social media discovery patterns concentrate purchase intent in TikTok-native brands with microbiome-friendly positioning.
- Seniors:Thinning epidermal barriers and xerosis prevalence elevate demand for ceramide-enriched and urea-based barrier repair formulations. European apothecary networks provide consultation-driven channel access for this risk-averse segment.
- Children:Hypoallergenic and fragrance-free requirements govern formulation standards, with pediatric dermatologist endorsement serving as critical purchase gate. Preservative system selection faces heightened scrutiny from parent advocacy networks monitoring ECHA safety assessments.
Adults command the largest revenue pool; teenagers are gaining share fastest through digital-native brand discovery and texture innovation.
Distribution Channel:
Volume concentration in mass retail contrasts with margin accretion from specialty and pharmacy channels that demand differentiated service capabilities.
- Online:Direct-to-consumer platforms capture subscription-driven recurring revenue with batch-traceable product lines and ingredient transparency apps. California and New York packaging compliance investments create first-mover advantage for verified closed-loop container supply chains.
- Supermarkets:Mass-market retail anchors volume production through distributed manufacturing networks serving high-velocity replenishment cycles. Price competition compresses margins for mid-tier formulators lacking private label manufacturing scale.
- Pharmacies:European apothecary networks and United States drugstore chains allocate premium shelf space to dermatologist-endorsed positioning previously reserved for Rx-adjacent skincare. EMA and FDA regulatory familiarity becomes table stakes for pharmacy channel access.
- Specialty Stores:Sephora, Ulta, and equivalent prestige retailers command science-backed ingredient storytelling and experiential sampling investments. Clean-label certification serves as prerequisite for placement in this high-touch environment.
Supermarkets retain the largest volume share; specialty stores and online channels are expanding fastest through premiumization and subscription mechanics.
Ingredient Type:
Supply concentration in pharmaceutical-grade emulsifiers and natural botanical networks creates divergent sourcing risk profiles across ingredient positioning strategies.
- Natural:Cold-pressed botanical oils and plant-derived actives command certification premiums from ECOCERT and COSMOS bodies, with harvest yield volatility compressing margin predictability. Climate disruption in Mediterranean and Southeast Asian growing regions exacerbates input cost instability.
- Organic:USDA Organic and EU Organic logo requirements mandate supply chain segregation and documentation systems that elevate formulation costs. Parent purchasers for children and sensitive-skin adults demonstrate inelastic demand for verified organic positioning.
- Synthetic:Petrochemical-derived emollients, silicones, and preservative systems offer cost stability and formulation consistency that natural alternatives cannot match. REACH and FDA safety data requirements apply equally, without the harvest risk exposure.
- Herbal:Traditional medicine system ingredients—ayurvedic, TCM, or kampo-derived—serve niche positioning in Asian domestic markets and diaspora communities. Regulatory substantiation challenges limit pharmacy channel expansion for these heritage-positioned lines.
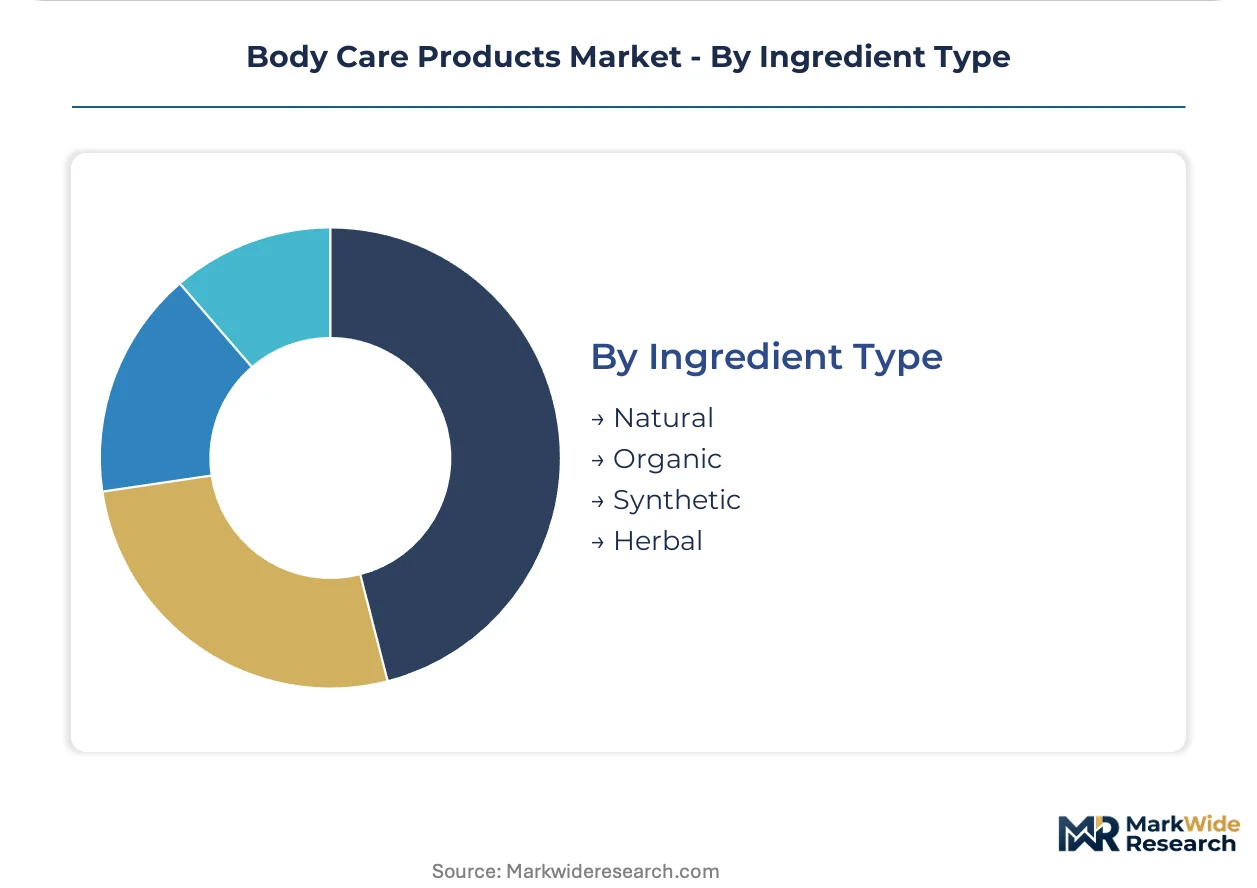
Synthetic ingredients hold the largest formulation share; natural and organic segments are climbing fastest through clean-label certification mandates in pharmacy and specialty retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA oversight on cosmetic ingredient safety anchors United States demand concentration, while REACH compliance and EU Green Deal directives reshape European formulation and packaging standards across manufacturing networks.
United States
Clean-label body care with verifiable ingredient sourcing drives coastal urban demand, particularly among working professionals in California and New York. FDA Modernization Act safety data requirements elevate pre-market investment thresholds for new entrants. The Northeast corridor hosts specialty retailers capturing share from mass-market supermarkets through batch-traceable product lines.
Germany
Dermatologist-endorsed positioning opens pharmacy channel access for barrier repair formulations targeting mature skin demographics. ECHA microplastic restrictions under REACH Annex XVII force exfoliating body wash reformulations across domestic manufacturing facilities. The Rhine-Ruhr industrial cluster concentrates pharmaceutical-grade emulsifier supply serving mid-tier European formulators.
France
Premium skincare routine adoption among urban employed adults expands per-capita spend through science-backed ingredient storytelling. EU Green Deal packaging waste directives compress conventional plastic use in body care containers ahead of 2030 targets. The Île-de-France region anchors prestige retailer headquarters demanding clean-label certification for shelf placement.
Japan
Biotechnology-derived actives produced via precision fermentation displace traditional extraction methods in premium and pharmacy-positioned brands. METI standards govern cosmetic safety thresholds alongside international alignment pressures. The Kanto region around Tokyo concentrates R&D investment in microbial fermentation capacity for squalane and hyaluronic acid production.
South Korea
Non-residue gel formats align with male grooming preferences seeking lightweight textures for facial-body dual-use positioning. MFDS cosmetic regulations enforce ingredient disclosure standards matching export market requirements. Seoul Capital Area manufacturers supply duty-advantaged output to Australian and Southeast Asian distributors seeking texture-innovative product lines.
Body Care Products Market Competitive Environment
Capability concentration sits with dermatological R&D heritage players; scale advantage sits with distributed manufacturing networks serving mass-market retail channels. The market structures around three tiers: premium science-backed positioning, pharmacy-endorsed specialty lines, and high-velocity mass-market replenishment. Dominant competitive moves include geographic expansion into Southeast Asian manufacturing zones and portfolio diversification toward clean-label certification requirements.
Within the premium-tier vector, Beiersdorf AG and L'Oréal S.A. occupy positions anchored by dermatological credibility and science-backed ingredient storytelling respectively. Unilever PLC exemplifies scale-driven manufacturing architecture through distributed networks serving supermarket replenishment cycles. Kao Corporation represents Asia-Pacific formulation expertise bridging texture innovation with regulatory compliance across multiple jurisdictions.
| Leading Market Players |
|---|
| Beiersdorf AG |
| The Procter & Gamble Company |
| Unilever PLC |
| L'Oréal S.A. |
| Colgate-Palmolive Company |
| Johnson & Johnson Services Inc. |
| Kao Corporation |
| The Estée Lauder Companies Inc. |
| Bath & Body Works Inc. |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp freight corridors transmit cold-pressed botanical oil cost volatility from Mediterranean harvest zones directly into European formulation economics, amplifying price spreads between mass-market emulsion tiers and pharmacy-positioned premium lines. This logistics-cost compression forces mid-tier brands toward synthetic emollient substitution or biopolymer packaging premiums that downstream buyers absorb unevenly across channel archetypes.
Pricing Analysis
Coastal United States markets command 15-25 percent premiums over inland distribution zones for identical clean-label SKUs, reflecting cold-chain logistics and specialty retailer slotting investments. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and batch-traceability depth, with ECOCERT-verified organic lines anchoring the top tier. Pricing pressure stems from natural ingredient input volatility that compresses margin predictability for organic-positioned brands. Mass-market supermarket buyers exhibit highest price sensitivity, while pharmacy channel purchasers demonstrate inelastic demand for dermatologist-endorsed barrier repair formulations.
Supply Chain Analysis
Contract manufacturing concentration sits with German and Swiss pharmaceutical-grade emulsifier specialists serving mid-tier European formulators, alongside Indonesian and Vietnamese facilities upgrading toward export-grade quality capability. Raw material dependencies center on cold-pressed shea butter from West African cooperatives, precision-fermentation squalane from Japanese biotech facilities, and pharmaceutical-grade carbomers from Rhine-Ruhr chemical clusters. Single-source vulnerability concentrates in three German-Swiss firms controlling majority emulsifier supply. Distribution runs through supermarket replenishment networks for volume tiers, direct-to-consumer platforms for subscription models, and European apothecary chains for pharmacy-positioned lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Body care products sit in early-cycle expansion as biotechnology-derived actives displace conventional extraction methods and clean-label certification becomes prerequisite for pharmacy and specialty shelf placement. Working professional demographics adopting premium skincare routines provide durable demand tailwinds across developed markets.
For Market Incumbents: Build formulation expertise moats bridging natural ingredient stability and regulatory compliance to defend against mid-tier competitors lacking cosmetic chemist talent depth. Invest in backward integration into precision fermentation capacity for squalane and hyaluronic acid production to reduce wild-harvested marine derivative exposure. Secure dedicated shelf space in European apothecary networks through dermatologist endorsement programs that emerging players cannot replicate.
For New Entrants and Emerging Players: Male grooming whitespace in South Korea and Australia offers texture-innovative gel format entry points with lower incumbent saturation than European pharmacy channels. Target direct-to-consumer subscription mechanics with blockchain-verified sourcing claims that resonate with millennial and Gen-Z cohorts in coastal United States markets. Leverage Southeast Asian duty-advantaged manufacturing to undercut established brands on landed cost in Australian distribution.
For Investors and Strategic Acquirers: Boutique clean-label formulators with verified closed-loop container supply chains represent attractive acquisition targets as California and New York packaging mandates tighten. Long-term viability favors players with regulatory dossier depth spanning FDA Modernization Act requirements and REACH Annex XVII compliance. Monitor biopolymer packaging economics and pre-market safety data capex trajectories as inflection indicators for competitive moat durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Investment | Biotech-derived squalane from Japanese facilities stabilizes raw material costs against harvest volatility. |
| Clean-Label Certification Acceleration | ECOCERT and COSMOS verification opens pharmacy channel access previously reserved for Rx-adjacent skincare. |
| Biopolymer Packaging Transition | EU Green Deal directives compress conventional plastic use ahead of 2030 waste reduction targets. |
| Direct-to-Consumer Platform Launch | Subscription mechanics with batch-traceable lines capture recurring revenue from ingredient-literate urban professionals. |
| Dermatologist Endorsement Program | European apothecary networks allocate premium shelf space to barrier repair formulations for mature skin demographics. |
Study Parameters
The analysis maps emulsion-based systems, hydroalcoholic gels, anhydrous oils, and waterless formats, each validated through formulation chemists, pharmacy category buyers, specialty retailer procurement leads, and clean-label certification auditors. Primary interviews with brand managers and supply planners at distributed manufacturing networks combined with secondary validation from FDA cosmetic filings, ECHA REACH registrations, ECOCERT audit databases, and Nielsen retail audit data. Bottom-up SKU-level volume builds triangulated against top-down category expenditure models.
Assumptions held regulatory frameworks constant across the projection horizon while varying biotechnology adoption rates and clean-label certification penetration by demographic cohort. Segmentation dimensions modeled include formulation chemistry, customer life-stage, distribution channel economics, and ingredient sourcing positioning. CAGRs derived from trend-line extrapolation of per-capita spend patterns and repeat purchase frequency data, with biotechnology input cost curves and biopolymer packaging scale economics as industry-specific forecast inputs.
Practitioners should monitor ECHA microplastic restriction enforcement, FDA Modernization Act implementation timelines, and natural ingredient harvest yield volatility for early signals of forecast revision. Forecasts reflect assumptions about regulatory stability and biotechnology cost reduction trajectories. Quarterly review of certification body audit backlogs and biopolymer supplier capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Mexico Beauty and Personal Care Market
Beauty & Personal Care
LAMEA Hair Removal Wax Market
Beauty & Personal Care
Europe Professional Beauty Services Market
Beauty & Personal Care
Nail Art Tools and Accessories Market
Beauty & Personal Care
Premium Cosmetics Market
Beauty & Personal Care
Europe Hair and Skincare Market
Beauty & Personal Care
Advanced Night Repair Serum Market
Beauty & Personal Care
France Sustainable Personal Care Market
Beauty & Personal Care
Facial Makeup Setting Spray Market
Beauty & Personal Care
Face Oil Market
Beauty & Personal Care
Beauty Fridge Market
Beauty & Personal Care
Beauty Pillowcases Market
Beauty & Personal Care
Sunless Tanners Market
Beauty & Personal Care
Global Bath Salts Market
Beauty & Personal Care
Bath Oil Market
Beauty & Personal Care
Medicated Personal Care Products Market