
 China Antibacterial Soap Market | 2026-2036
China Antibacterial Soap Market Size, Share, and Industry Trends Forecast 2026-2036
China Antibacterial Soap Market Insights
Skilled cosmetic chemists with antimicrobial formulation expertise is redrawing competitive boundaries in China's antibacterial soap sector. Shanghai Soap Corporation leverages its century-old manufacturing infrastructure to sustain bulk supply contracts with institutional buyers. Longrich BioScience anchors its position through direct-selling networks that penetrate county-level markets. Poleview Biotech Co., Ltd. specializes in biosurfactant-based formulations that differentiate against legacy chemical producers.
Antibacterial soap denotes a cleansing formulation incorporating antimicrobial agents—typically triclosan alternatives, quaternary ammonium compounds, or plant-derived bactericides—engineered to reduce skin flora populations below baseline levels during washing. Manufacturers employ cold-process saponification or synthetic detergent blending to preserve active ingredient stability across pH ranges of 5.5 to 8.0. Liquid soap commands the largest volume position due to dispenser compatibility in healthcare and food-processing environments, while bar soap retains cost-sensitive household penetration in lower-tier cities. Natural extracts represent the fastest-growing ingredient category as GB 27951 compliance pressures and consumer preference shift away from synthetic chemicals.
SAMR enforces cosmetic safety assessments under the CSAR framework, while NMPA-aligned provincial bureaus monitor antimicrobial claim substantiation. GB 27951 technical standards for disinfectants directly constrain permissible active concentrations and labeling assertions. MEE environmental discharge rules add compliance costs for manufacturers employing phosphorus-heavy surfactants. Stakeholders must track evolving biosafety classifications that could reclassify certain antibacterial actives as restricted cosmetic ingredients.
Market Dynamics
GB 27951 technical standards are forcing domestic manufacturers to abandon legacy triclosan formulations and rebuild supply chains around plant-derived bactericides and biosurfactant alternatives, compressing margins while opening premium positioning for compliant producers.
Growth Catalysts
- Healthcare procurement expansion:Hospital infection control protocols now mandate antibacterial soap in all patient contact zones, institutional buyers in tier-one cities scaling volume commitments.
- SAMR cosmetic safety framework:CSAR-aligned assessments create barrier to entry for non-compliant imports, sheltering domestic reformulators with established NMPA provincial bureau relationships.
- Natural extract innovation:Tea polyphenol and chitosan formulations achieve GB 27951 efficacy thresholds without synthetic residues, unlocking green-label premiums in Shanghai and Beijing retail channels.
Market Restraints
- Palm kernel oil price volatility:Surfactant input costs swing with Malaysian export duties, squeezing bar soap margins in cost-sensitive county markets where Longrich BioScience dominates.
- MEE discharge compliance:Phosphorus-heavy synthetic detergent manufacturers face wastewater treatment capex of 15-20% of facility investment, advantaging biosurfactant specialists with lower environmental loads.
- Hand sanitizer substitution:Alcohol-based rubs capture outpatient clinic and food-processing hand hygiene occasions where speed trumps residual antimicrobial protection.
Strategic Opportunities
- County-level direct-selling penetration:Lower-tier cities in Henan and Sichuan provinces show per-capita hygiene spending growth double coastal rates, channel innovation through social commerce networks bypasses traditional retail.
- Dual carbon policy alignment:Beijing's 2060 net-zero targets steer state procurement toward carbon-neutral production certifications, creating preferential access for manufacturers with renewable energy captive supply.
- Biosurfactant-quaternary ammonium convergence:Hybrid formulations combining Poleview Biotech's rhamnolipid platforms with cationic actives deliver hospital-grade efficacy with skin-mildness claims for pediatric segments.
Industry Challenges
- Antimicrobial formulation chemist scarcity:Skilled talent capable of optimizing active stability across pH 5.5-8.0 ranges commands 40% salary premiums, constraining mid-tier manufacturer R&D velocity.
- GB standard revision timeline uncertainty:Pending reclassification of certain quaternary ammonium compounds as restricted cosmetic ingredients forces dual-track formulation development without clarity on grandfathering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Antibacterial Soap Market |
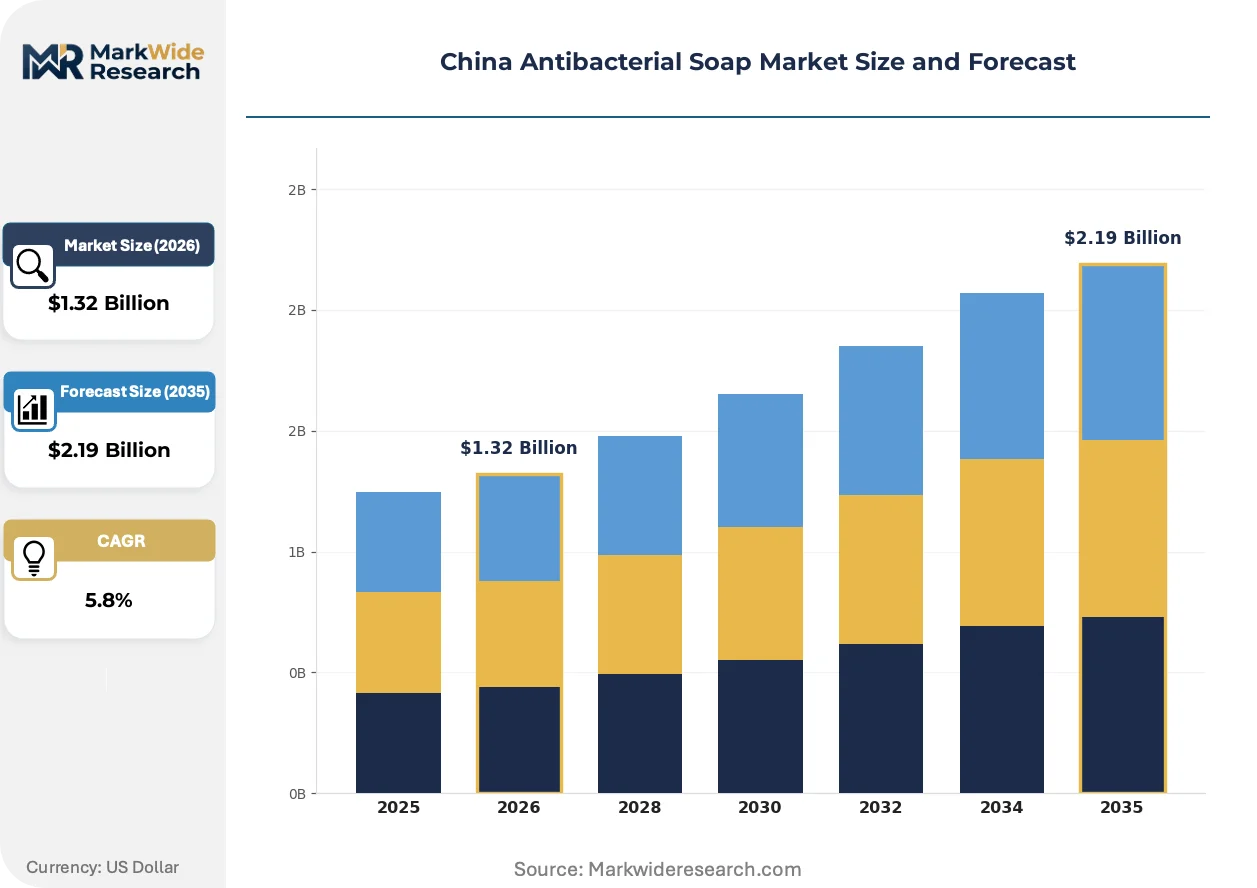
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.19 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Soap, Foaming Soap, Bar Soap, Gel Soap Ingredient Type: Natural Extracts, Synthetic Chemicals, Essential Oils, Antimicrobial Agents End User: Households, Healthcare Facilities, Food Industry, Educational Institutions Sales Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Safeguard, Shanghai Soap Corporation, Jiangsu Daily Chemical Factory, Guangzhou Baiyun Soap Factory, Poleview Biotech Co., Ltd., Longrich BioScience, Liushen, Lux, Proya, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Antibacterial Soap Market Trends and Innovations
Reformulation pressure under tightening GB standards is compressing legacy chemical supply chains while accelerating biotechnology adoption and procurement centralization among institutional buyers.
Encapsulated essential oil delivery systems are miniaturizing active ingredient payloads to sub-micron lipid vesicles that penetrate skin surface irregularities more uniformly than conventional suspensions. Shanghai-based cosmetic laboratories are licensing this platform to hospital suppliers seeking 99.9% kill-rate documentation for surgical scrub applications. The technology is miniaturizing production batch requirements, enabling mid-scale manufacturers to serve niche institutional contracts without capital-intensive continuous processing lines.
SAMR's CSAR framework implementation through 2024-2025 is eliminating antimicrobial claim substantiation shortcuts that previously allowed cosmetic-grade products to carry disinfectant-adjacent labeling. Provincial bureaus aligned with NMPA now demand complete dermal sensitization and ecotoxicology dossiers before market authorization, extending new product launch timelines by 8-14 months. Liquid soap categories in healthcare and food-processing segments are absorbing the bulk of compliance costs through price stratification across premium-certified and economy-unverified tiers.
Hospital procurement consortia in Guangdong and Jiangsu provinces are consolidating antibacterial soap sourcing through centralized e-procurement platforms that bypass traditional distributor markups. Tier-three county hospitals previously served by fragmented wholesale networks now access direct manufacturer pricing through provincial health commission tender systems. This channel compression is most visible in the Pearl River Delta, where municipal health bureaus aggregate demand across 40-60 facilities to extract volume discounts exceeding 25% from legacy supplier contracts.
China Antibacterial Soap Market Segmentation
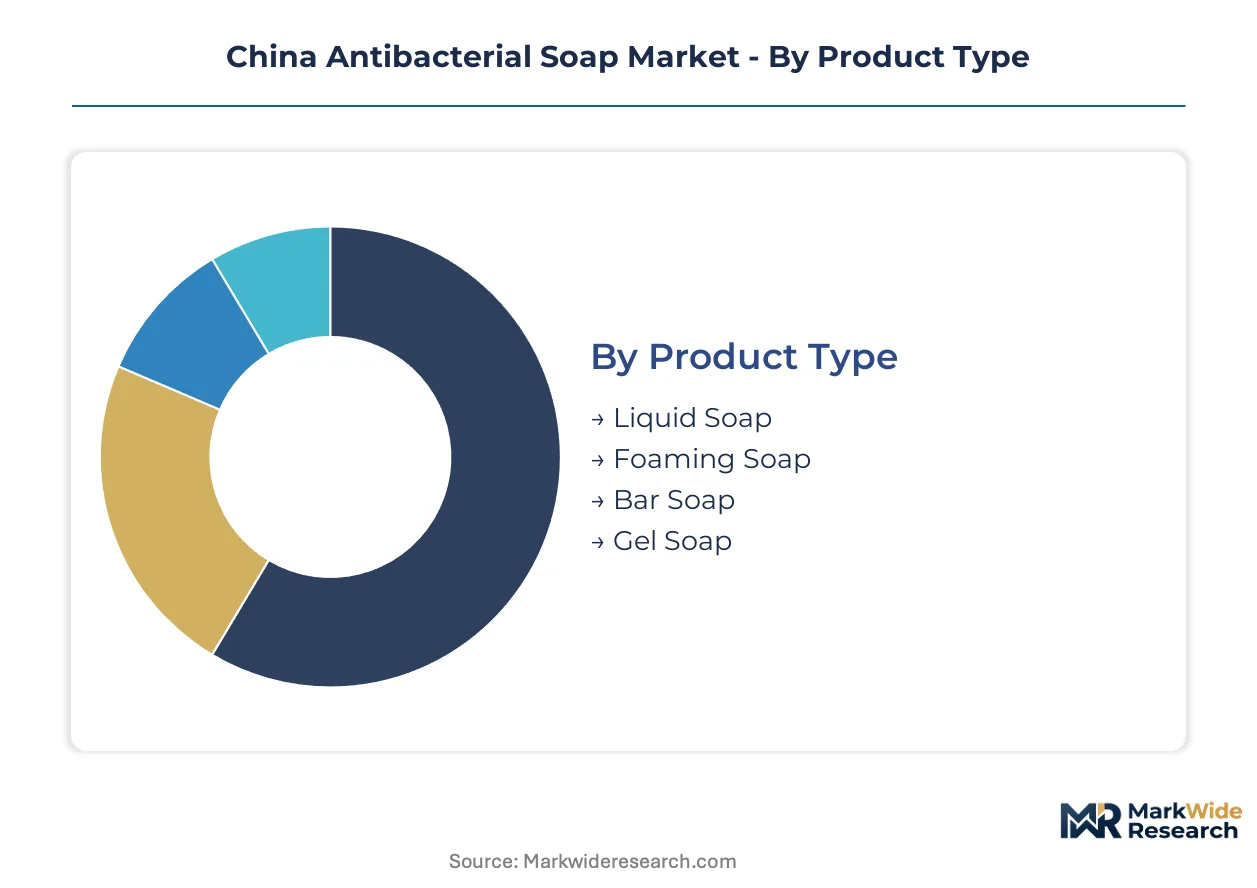
Segmentation in China's antibacterial soap market reveals divergent growth vectors between institutional procurement channels and household consumption patterns. Understanding these divides enables manufacturers to align reformulation investments with the specific compliance and performance thresholds each segment demands.
Product Type:
Liquid soap dominates hospital and food-processing procurement concentrated in Beijing, Shanghai, and Guangzhou. Bar soap retains cost-sensitive household penetration across Henan and Sichuan provinces where per-capita hygiene spending lags coastal benchmarks.
- Liquid Soap:Synthetic detergent-based formulations engineered for dispenser compatibility in healthcare environments. Demand concentrates in tier-one city hospital systems where GB 27951 compliance documentation is mandatory for tender participation, with municipal procurement consortia extracting volume discounts exceeding 25% from suppliers.
- Foaming Soap:Pre-aerated emulsions that reduce per-use active ingredient consumption while maintaining efficacy thresholds. Pediatric wards in Jiangsu province hospitals are standardizing foaming dispensers to minimize skin irritation claims, driving specialized formulation development.
- Bar Soap:Cold-process saponified bars serving price-sensitive county-level households. Longrich BioScience's direct-selling networks dominate distribution in lower-tier cities where unit economics favor solid formats over liquid packaging costs.
- Gel Soap:Thickened aqueous formulations with visual clarity for premium positioning. Specialty retail channels in Shanghai and Beijing stock gel variants targeting consumers seeking aesthetic differentiation from institutional-grade products.
Liquid soap commands the established base. The steepest expansion runs through foaming soap.
Ingredient Type:
Cost tiers separate premium natural formulations from economy synthetic chemistry, with regulatory pressure compressing the middle ground.
- Natural Extracts:Tea polyphenol, chitosan, and plant-derived bactericides achieving GB 27951 efficacy without synthetic residues. Shanghai and Beijing retail channels absorb 15-20% price premiums for green-label positioning as consumer preference shifts away from legacy chemicals.
- Synthetic Chemicals:Quaternary ammonium compounds and triclosan alternatives reformulated under tightening GB standards. Domestic manufacturers face margin compression as supply chain rebuilding around compliant actives adds 8-14 months to new product launch timelines.
- Essential Oils:Encapsulated lipid vesicle delivery systems penetrating skin surface irregularities. Shanghai-based cosmetic laboratories license this platform to hospital suppliers seeking documented kill rates for surgical scrub applications.
- Antimicrobial Agents:Biosurfactant-based actives combining rhamnolipid platforms with cationic compounds. Poleview Biotech specializes in these hybrid formulations that deliver hospital-grade efficacy with skin-mildness claims.
Synthetic chemistry retains volume leadership. Natural extracts are climbing the fastest.
End User:
Application requirements diverge sharply between residual antimicrobial protection demands and speed-priority hygiene occasions.
- Households:Cost-conscious consumption concentrated in bar soap formats across county-level markets. Social commerce networks bypass traditional retail to capture double-digit per-capita hygiene spending growth in interior provinces.
- Healthcare Facilities:Hospital infection control protocols mandating antibacterial soap in all patient contact zones. Tier-one city institutions scale volume commitments through centralized e-procurement platforms that compress distributor markups.
- Food Industry:Processing plants requiring rapid hand hygiene without compromising food safety. Alcohol-based rubs capture occasions where speed trumps residual protection, constraining antibacterial soap penetration.
- Educational Institutions:Kindergartens and primary schools driving mild-formulation demand. Pediatric segments favor biosurfactant-quaternary ammonium hybrids that balance efficacy with skin sensitivity claims.
Healthcare facilities anchor procurement volume. Educational institutions show the steepest expansion trajectory.
Sales Channel:
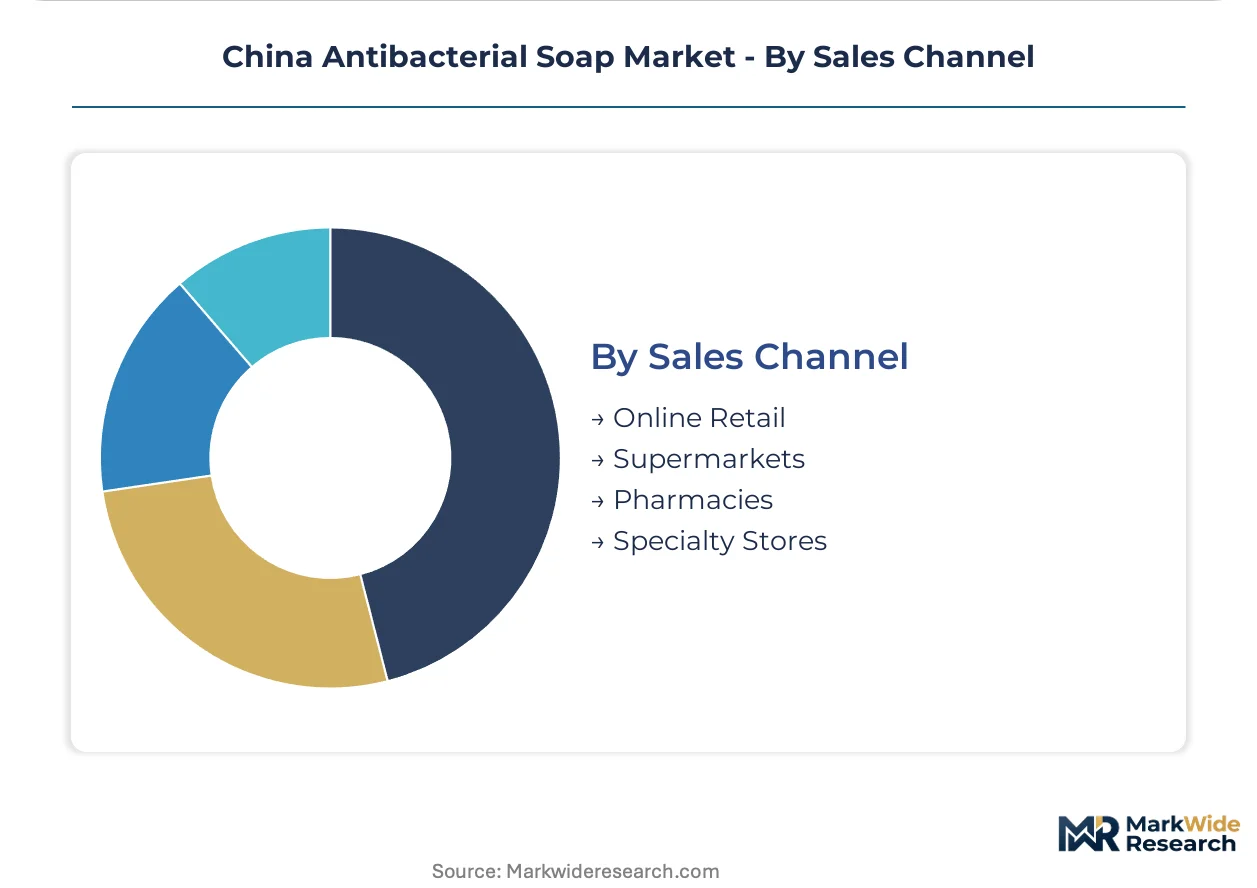
Customer type determines channel strategy, with institutional buyers consolidating through tenders while households fragment across digital and physical touchpoints.
- Online Retail:E-commerce platforms capturing premium natural extract sales in tier-one cities. Direct-to-consumer models enable mid-scale manufacturers to serve niche segments without capital-intensive continuous processing lines.
- Supermarkets:Mass-market liquid and bar soap distribution with economy-standard pricing stratification. GB 27951 compliance pressures are eliminating antimicrobial claim substantiation shortcuts previously tolerated in cosmetic-grade products.
- Pharmacies:Clinically positioned formulations with dermal sensitization documentation. SAMR's CSAR framework implementation extends authorization timelines, advantaging established players with provincial bureau relationships.
- Specialty Stores:Curated premium and pediatric segments in Shanghai and Beijing. Encapsulated essential oil delivery systems and gel formats target consumers seeking differentiation from institutional-grade alternatives.
Supermarkets maintain the broadest reach. Online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's CSAR framework and GB standards enforcement create divergent growth conditions across China's provincial markets. Coastal provinces absorb compliance costs through premium positioning, while interior regions exploit channel innovation to capture hygiene spending growth.
Yangtze River Delta
Shanghai and Jiangsu province hospitals drive institutional procurement volume through centralized e-procurement platforms. Municipal health bureaus aggregate demand across 40-60 facilities to extract volume discounts exceeding 25% from suppliers. Shanghai-based cosmetic laboratories license encapsulated essential oil delivery systems to hospital suppliers seeking documented kill rates for surgical scrub applications.
Pearl River Delta
Guangdong province food-processing plants require rapid hand hygiene without compromising safety standards. Alcohol-based rubs capture outpatient clinic occasions where speed trumps residual protection, constraining antibacterial soap penetration in Shenzhen and Guangzhou medical corridors. Provincial health commissions steer state procurement toward carbon-neutral production certifications under Beijing's dual carbon policy.
Beijing-Tianjin-Hebei
Capital region healthcare facilities mandate antibacterial soap in all patient contact zones as infection control protocols tighten. Tier-one city institutions scale volume commitments through tender systems that compress distributor markups. SAMR-aligned provincial bureaus demand complete dermal sensitization dossiers before market authorization, extending new product launch timelines.
Sichuan-Chongqing
Interior province households show per-capita hygiene spending growth double coastal rates. Social commerce networks bypass traditional retail to capture this expansion in Chengdu and Chongqing county-level markets. Longrich BioScience's direct-selling penetration anchors bar soap distribution where unit economics favor solid formats over liquid packaging costs.
Shandong Peninsula
Qingdao and Jinan manufacturing clusters face MEE environmental discharge rules adding compliance costs for phosphorus-heavy surfactant producers. Biosurfactant specialists with lower environmental loads gain advantage as wastewater treatment capex reaches 15-20% of facility investment. Provincial industrial policy favors biotechnology adoption in antimicrobial formulation development.
China Antibacterial Soap Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across China's antibacterial soap sector. State-affiliated manufacturers leverage century-old infrastructure for bulk institutional contracts, while biotechnology specialists command premium positioning through biosurfactant innovation. The market structure tiers into legacy chemical producers, natural extract reformulators, and hybrid formulation developers. Competitive moves concentrate on supply chain rebuilding around GB 27951 compliance and direct-selling channel expansion into county-level markets.
Among heritage manufacturers, Shanghai Soap Corporation anchors the institutional procurement tier through established NMPA provincial bureau relationships. Longrich BioScience exemplifies the direct-selling archetype penetrating lower-tier cities where traditional retail coverage remains thin. Poleview Biotech Co., Ltd. occupies the biotechnology specialist position, representing the convergence of biosurfactant platforms with cationic actives for pediatric and premium segments. These three player types illustrate how reformulation pressure under tightening GB standards is compressing legacy chemical supply chains while accelerating biotechnology adoption.
| Leading Market Players |
|---|
| Safeguard |
| Shanghai Soap Corporation |
| Jiangsu Daily Chemical Factory |
| Guangzhou Baiyun Soap Factory |
| Poleview Biotech Co., Ltd. |
| Longrich BioScience |
| Liushen |
| Lux |
| Proya |
| Others |
Pricing and Supply Chain Analysis
Century-old manufacturing infrastructure in Shanghai and Jiangsu provinces generates 30-40% unit cost advantages over greenfield entrants, compressing price floors for institutional-grade liquid soap while forcing reformulators toward premium natural extract positioning to escape margin erosion. This scale concentration simultaneously empowers municipal procurement consortia to extract steep volume discounts and strands mid-tier manufacturers without backward integration into surfactant production.
Pricing Analysis
Shanghai-Beijing retail channels absorb 15-20% premiums over Sichuan-Chongqing county markets for identical GB 27951-compliant formulations. Three-tier pricing structure across premium-certified, standard-compliant, and economy-unverified levels separates hospital tender participants from cosmetic-grade supermarket tiers. Pricing pressure stems from palm kernel oil input volatility under Malaysian export duty regimes. Healthcare facilities show lowest price sensitivity due to protocol mandates, while county-level households drive bar soap demand through unit economics favoring solid formats.
Supply Chain Analysis
Strategic stockpiling of tea polyphenol and chitosan extracts dominates reformulation planning as GB 27951 transition timelines compress, replacing just-in-time procurement of legacy triclosan precursors. Manufacturing concentration centers on Shandong Peninsula surfactant clusters and Yangtze River Delta formulation facilities. Raw material dependencies rest on Malaysian palm kernel oil, domestic rhamnolipid biotechnology feedstocks, and imported quaternary ammonium precursors. Single-source vulnerability runs through biosurfactant specialist capacity constraints. Distribution feeds from provincial health commission tender platforms directly to hospital systems, bypassing traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's antibacterial soap sector functions as a regulatory entrenchment market where SAMR's CSAR framework and GB 27951 compliance documentation create switching costs that shelter established players with provincial bureau relationships from import competition.
For Market Incumbents: Compound defensive positioning by deepening backward integration into biosurfactant production and securing captive supply of GB 27951-compliant natural extracts before reclassification deadlines. Expand capacity in Yangtze River Delta clusters to serve consolidated municipal procurement consortia. Threat vector: biotechnology specialists capturing pediatric segment premiums through rhamnolipid-cationic hybrid formulations. For New Entrants and Emerging Players: Differentiate on encapsulated essential oil delivery systems licensed from Shanghai cosmetic laboratories, targeting surgical scrub documentation requirements that incumbent chemical producers cannot meet without reformulation investment. White-space targets: county-level direct-selling penetration in Henan and Sichuan provinces where per-capita hygiene spending growth doubles coastal rates, and pediatric mild-formulation segments favoring skin-sensitivity claims. Go-to-market: social commerce networks bypassing traditional retail infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among institutional procurement suppliers with multi-year hospital system contracts under provincial health commission frameworks. Long-term viability rests on regulatory compliance moats deepening through anticipated quaternary ammonium reclassification. Acquisition target archetype: biotechnology specialists with rhamnolipid platforms and established NMPA provincial bureau relationships. Signal to watch: GB standard revision timelines clarifying grandfathering provisions for existing formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biosurfactant Production | Captive rhamnolipid supply secures MEE compliance cost advantage over phosphorus-heavy synthetic detergent competitors. |
| Provincial Health Commission Tender Participation | Direct manufacturer access to tier-three county hospitals bypasses 25% distributor markups in fragmented wholesale networks. |
| Encapsulated Essential Oil Platform Licensing | Sub-micron lipid vesicle technology unlocks surgical scrub documentation requirements for mid-scale manufacturers. |
| Direct-Selling Channel Expansion | Social commerce penetration captures double-digit hygiene spending growth in interior province county markets. |
| Carbon-Neutral Production Certification | Dual carbon policy alignment steers state procurement toward renewable energy-captive manufacturers. |
Research Methodology
Cross-validation between primary interviews with antimicrobial formulation chemists, hospital procurement managers, and SAMR-aligned provincial bureau officials anchors the qualitative findings against secondary validation from GB standards documentation, customs surfactant trade records, and municipal health commission tender disclosures. Bottom-up demand modeling triangulates against top-down sectoral expenditure benchmarks.
Sensitivity analysis across formulation input cost scenarios and regulatory timeline assumptions shapes the projection framework. Segmentation dimensions span product type, ingredient category, end-user application, and sales channel, with regional procurement policy clusters as an industry-specific overlay. CAGRs derive from installed base erosion rates for legacy chemical formulations and adoption curves for GB 27951-compliant natural extracts. Forecast inputs incorporate palm kernel oil price volatility bands and biosurfactant capacity buildout timelines.
Material uncertainties — GB 27951 reclassification grandfathering clarity, quaternary ammonium compound biosafety redesignation, and MEE discharge rule enforcement intensity — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation pacing and supply chain reformulation velocity. Revision becomes warranted when antimicrobial formulation chemist scarcity crosses thresholds that constrain mid-tier manufacturer R&D velocity beyond modeled ranges.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Facial Rollers Market
Beauty & Personal Care
Anti-Dandruff Shampoo Market
Beauty & Personal Care
Spas and Beauty Salons Market
Beauty & Personal Care
Dry Shampoo Market
Beauty & Personal Care
South America Deodorants Market
Beauty & Personal Care
Global Cosmetics Market
Beauty & Personal Care
Underarm Antiperspirant and Deodorant Market
Beauty & Personal Care
Cosmetic Wax Market
Beauty & Personal Care
Colombia Cosmetics Products Market
Beauty & Personal Care
US Color Cosmetics Market
Beauty & Personal Care
Bangladesh Hair Oil Market
Beauty & Personal Care
Europe Hair Styling Products Market
Beauty & Personal Care
Intimate Hygiene Products Market
Beauty & Personal Care
Deodorant Roll-Ons Market
Beauty & Personal Care
Malaysia Aromatherapy Products Market
Beauty & Personal Care
UAE Beauty Industry Market