
 Dog Vitamins Market | 2026-2036
Dog Vitamins Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Vitamins Market Analytics
Asset-light contract manufacturing and private-label financing is reshaping how mid-tier brands enter the dog vitamins space without capital-intensive production facilities. Nestlé Purina Petcare leverages its captive supply chain to control ingredient sourcing and finished goods distribution across mass retail. Zesty Paws competes through direct-to-consumer subscription models that reduce customer acquisition costs over time. Nutramax Laboratories anchors its position in veterinary-exclusive channels, sustaining premium pricing through clinician endorsement.
Dog vitamins comprise formulated nutritional supplements containing specific micronutrients, fat-soluble compounds, and microbial cultures designed to address dietary gaps in canine metabolism, typically manufactured through cold-press extrusion or spray-drying to preserve bioactive stability. These products serve commercial and household end users seeking to support joint mobility, digestive function, immune response, or coat condition in domestic dogs. Multivitamins and omega fatty acid formulations occupy the largest share of current revenue, reflecting established consumer familiarity and broad applicability across life stages. Soft chews represent the fastest-growing delivery format, driven by palatability engineering that improves compliance among discerning or medicating-averse animals. Senior dog targeting commands disproportionate margin contribution, as aging-related condition management justifies sustained premium expenditure from owners.
FDA Center for Veterinary Medicine oversight and AAFCO model bill compliance requirements shape product formulation standards, labeling accuracy, and interstate market access for dog vitamin manufacturers. State-level feed control officials enforce these frameworks through registration and inspection protocols that vary in stringency across jurisdictions. Stakeholders must monitor evolving probiotic classification debates and potential prescription-status reclassifications that could restructure channel economics and competitive barriers.
Market Dynamics
Veterinary endorsement requirements and FDA Center for Veterinary Medicine labeling enforcement are tightening quality thresholds, forcing manufacturers to reformulate and re-register products across state jurisdictions. This regulatory compression favors incumbents with dedicated compliance infrastructure.
Growth Catalysts
- AAFCO Model Bill Harmonization:Interstate feed control standardization reduces registration friction for multi-state distributors, accelerating product launches in high-population corridors.
- Condition-Specific Formulation:Joint mobility and digestive health targeting commands sustained premium expenditure from aging dog owners seeking therapeutic adjuncts to veterinary care.
- Soft Chew Palatability Engineering:Cold-press extrusion advances improve compliance among medicating-averse animals, expanding addressable pet populations previously excluded from supplement regimens.
Market Restraints
- Animal-Derived Ingredient Volatility:Marine-sourced omega fatty acid supply fluctuates with fishery quota restrictions, compressing margin stability for omega-focused portfolios.
- State-Level Registration Fragmentation:Individual state feed control officials enforce divergent inspection protocols, creating compliance cost stacking for national distribution ambitions.
- Probiotic Classification Uncertainty:Pending FDA determinations on live microbial culture status threaten channel restructuring and potential prescription reclassification.
Strategic Opportunities
- Veterinary-Exclusive Channel Expansion:Clinician endorsement protocols in the United States sustain pricing power unavailable in mass retail environments.
- Subscription Commerce Infrastructure:Direct-to-consumer recurring revenue models reduce customer acquisition cost amortization and improve lifetime value predictability.
- Senior Dog Condition Management:Geriatric canine populations justify sustained premium positioning through age-related therapeutic need articulation.
Industry Challenges
- Veterinary Nutrition Specialist Scarcity:Formulation expertise combining companion animal metabolism with regulatory science commands compensation premiums that strain mid-tier R&D budgets.
- Legacy ERP Integration Friction:Batch record systems designed for feed manufacturing require expensive customization to accommodate supplement-specific traceability mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Vitamins Market |
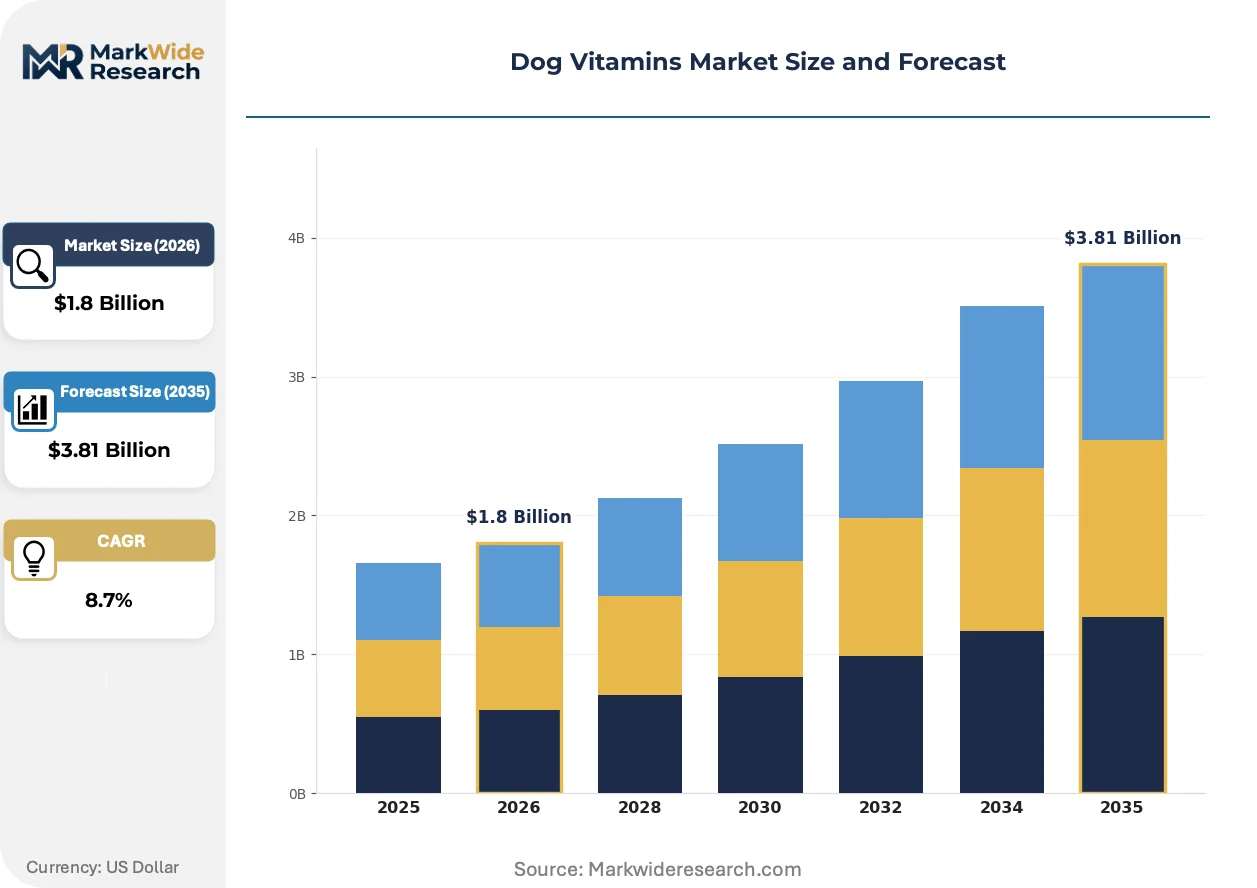
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chewable Tablets, Soft Chews, Powders, Liquids Formulation: Multivitamins, Omega Fatty Acids, Probiotics, Antioxidants Distribution Channel: Online Retail, Pet Stores, Veterinary Clinics, Pharmacies Target Age Group: Puppies, Adult Dogs, Senior Dogs, Working Dogs |
| Companies Covered | Nestlé Purina Petcare, Nutramax Laboratories, Virbac, Zoetis, Mars, Zesty Paws, NOW Foods, Bayer AG, Ark Naturals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Vitamins Market Evolving Landscape
Formulation science and distribution architecture are converging to reshape how canine nutritional supplements reach end users. Three distinct vectors are compressing development timelines and reconfiguring channel economics.
Near-infrared spectroscopy is digitizing raw material identity verification workflows, replacing wet chemistry assays with real-time compositional analysis. Contract manufacturers in the United States are adopting inline sensors to accelerate batch release and reduce quarantine inventory. This compression of quality control cycles is enabling just-in-time production models previously incompatible with supplement stability requirements.
AAFCO ingredient definition updates are forcing reformulation of legacy products containing novel microbial strains or plant-derived actives lacking established nutritional profiles. Manufacturers must submit new feeding trial data or secure Generally Recognized As Safe determinations to maintain interstate market access. Senior-focused formulations containing condition-specific botanicals face the steepest compliance burden under these evolving standards.
Urban pet owners are consolidating purchase decisions through veterinary clinic portals and specialty retailer subscription programs, displacing episodic mass retail buying. This concentration of demand through endorsed channels privileges brands with established clinician relationships. The United States exhibits the most pronounced shift, where veterinary recommendation drives supplement selection more than price comparison.
Dog Vitamins Market Segmentation
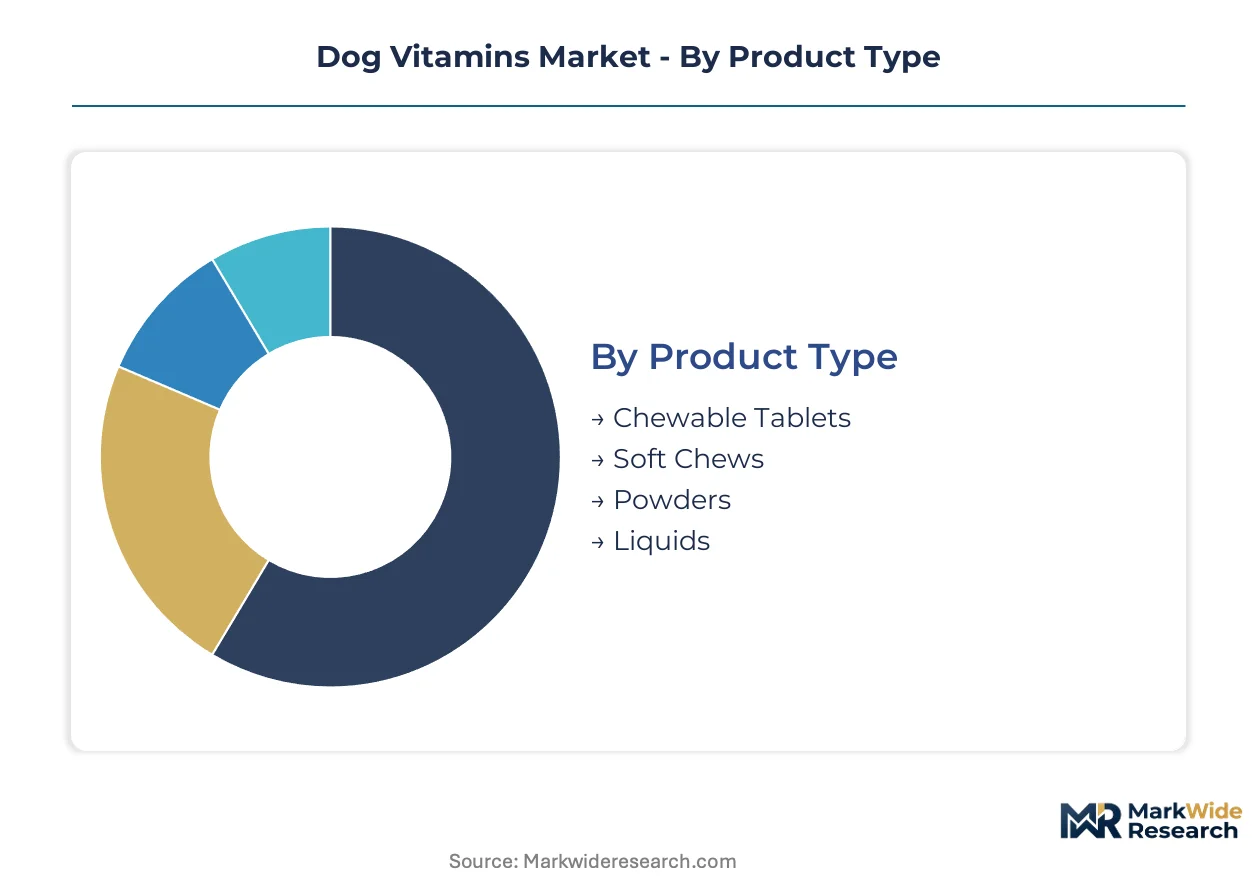
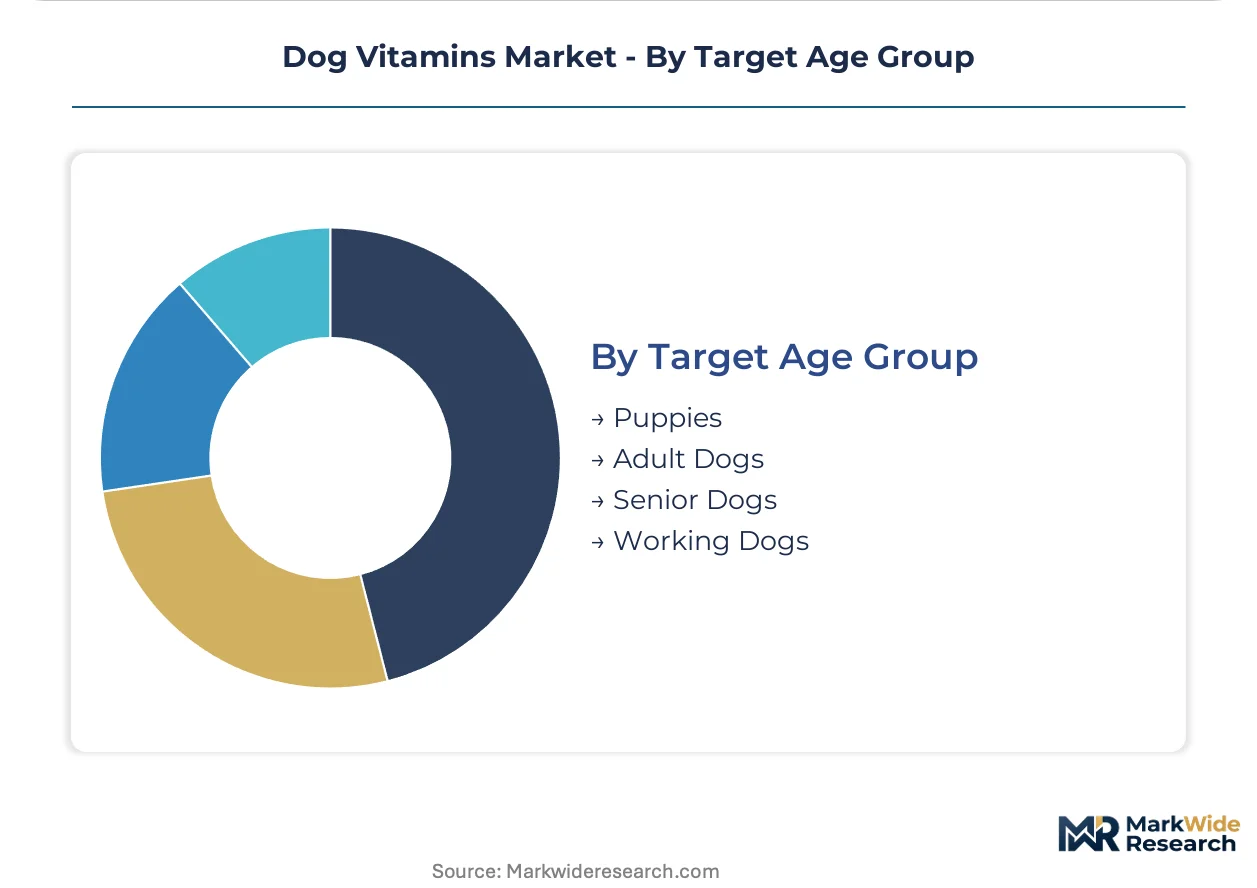
Segmentation in dog vitamins determines formulation complexity, palatability engineering investments, and channel economics. Manufacturers calibrate production scale and regulatory submission strategies around specific delivery formats and life-stage targeting.
Product Type:
After-sales intensity varies sharply across delivery formats, with chewable and soft-chew categories demanding ongoing palatability troubleshooting and compliance documentation support.
- Chewable Tablets:Compressed formulations combining binders with micronutrient matrices suit high-volume manufacturing and extended shelf stability. Veterinary clinics in the United States prescribe these for precise dosing protocols in working dog populations, though palatability limitations restrict household compliance.
- Soft Chews:Cold-press extrusion preserves bioactive stability while enabling flavor masking that improves medicating-averse animal compliance. Urban pet owners in the United States drive disproportionate demand through subscription programs targeting senior dogs with joint mobility formulations.
- Powders:Spray-dried micronutrient blends allow flexible dosing across multiple dog sizes. Kennel operators and commercial breeders favor bulk packaging economics.
- Liquids:Emulsion-based delivery suits digestive health applications requiring rapid absorption. Limited shelf stability constrains distribution radius.
Soft chews hold the largest share; momentum sits with palatability-engineered formats expanding addressable pet populations.
Formulation:
Cost tier stratification separates commodity multivitamins from premium condition-specific blends, with R&D intensity determining margin capture.
- Multivitamins:Broad-spectrum micronutrient coverage addresses general dietary gaps across life stages. Mass retail channels in the United States move high volumes at compressed margins.
- Omega Fatty Acids:Marine and plant-derived EPA/DHA formulations target coat condition and inflammatory response modulation. Supply volatility from fishery quota restrictions pressures margin stability.
- Probiotics:Live microbial cultures require cold-chain integrity and stability testing beyond conventional supplement standards. FDA classification uncertainty threatens channel restructuring.
- Antioxidants:Botanical and synthetic free-radical scavengers address cellular aging in geriatric canine populations. Veterinary endorsement sustains premium positioning unavailable in mass retail.
Multivitamins dominate volume; antioxidants are climbing the fastest as senior dog populations expand.
Distribution Channel:
Customer type concentration shapes channel selection, with clinician-loyal owners diverging from price-sensitive mass retail buyers.
- Online Retail:Direct-to-consumer platforms enable subscription automation and lifetime value optimization. Zesty Paws and comparable brands reduce customer acquisition cost amortization through recurring revenue infrastructure.
- Pet Stores:Specialty retailers provide tactile evaluation and staff consultation for format selection. Chains consolidate shelf space around private-label and national brand portfolios.
- Veterinary Clinics:Exclusive distribution through clinician endorsement protocols sustains pricing power. Nutramax Laboratories anchors this channel with prescription-adjacent positioning.
- Pharmacies:Human health retail crossover expands accessibility for owners seeking convenience. Regulatory alignment with human supplement standards varies by state jurisdiction.
Veterinary clinics command premium positioning; online retail is expanding most quickly through subscription infrastructure deployment.
Target Age Group:
Application severity and therapeutic need intensity differentiate life-stage targeting, with geriatric populations justifying sustained premium expenditure.
- Puppies:Growth-phase formulations emphasize skeletal development and immune system maturation. Breeders and first-time owners drive initial purchase decisions.
- Adult Dogs:Maintenance-level micronutrient coverage supports metabolic function and coat condition. Volume concentration in this segment reflects population demographics.
- Senior Dogs:Condition-specific blends address joint mobility, cognitive function, and digestive efficiency. Aging-related therapeutic need articulation sustains margin contribution.
- Working Dogs:Performance-optimized formulations support endurance, recovery, and stress response. Law enforcement and agricultural end users prioritize batch consistency and third-party verification.
Adult dogs anchor volume; senior dogs show steepest expansion trajectory as premium positioning aligns with therapeutic need intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban pet owners with aging dogs dominate purchase decisions across developed markets, channeling demand through veterinary-endorsed and subscription-based platforms. Regulatory frameworks vary sharply by jurisdiction, reshaping formulation standards and interstate commerce logistics.
United States
Veterinary endorsement protocols drive premium positioning among clinician-loyal owners seeking condition-specific supplements. FDA Center for Veterinary Medicine labeling enforcement tightens quality thresholds, forcing reformulation of legacy products. Kansas City and Omaha host contract manufacturing clusters serving private-label brands with asset-light production models.
Germany
Specialty retailers consolidate shelf space around premium European brands targeting digestive health and joint mobility. EFSA guidelines on novel botanical ingredients shape reformulation requirements for senior-focused products. Bavaria's industrial corridor anchors spray-drying facilities supplying omega fatty acid formulations across the European Union.
United Kingdom
Subscription commerce penetration accelerates among London and Southeast England pet owners seeking automated replenishment. The Veterinary Medicines Directorate monitors supplement claims alongside FSA feed safety protocols. Midlands distribution hubs service direct-to-consumer brands with cold-chain infrastructure for probiotic stability.
Japan
Aging companion animal populations justify sustained premium expenditure for cognitive function and mobility formulations. METI standards on functional food labeling extend to pet supplements, requiring substantiated health claims. Osaka-Kansai manufacturers specialize in palatability-engineered soft chews for medicating-averse small breeds.
Australia
Working dog populations in rural Queensland and Western Australia drive demand for performance-optimized formulations. TGA oversight of complementary medicines creates parallel compliance pathways for veterinary-exclusive distribution. Sydney and Melbourne veterinary clinic networks consolidate supplement procurement through group purchasing organizations.
Dog Vitamins Market Competitive Landscape
Channel-controlling players compete with product-specialist players across mass retail, veterinary-exclusive, and direct-to-consumer vectors. The market structures around three tiers: multinational CPG conglomerates with captive supply chains, mid-tier brands leveraging contract manufacturing, and veterinary-exclusive specialists sustaining premium through clinician endorsement. Dominant competitive moves include subscription infrastructure deployment and state-level registration consolidation for national distribution.
Among captive supply chain operators, Nestlé Purina Petcare exemplifies backward integration into ingredient sourcing and finished goods distribution. Nutramax Laboratories and Zesty Paws occupy contrasting positions—one anchoring veterinary-exclusive channels through prescription-adjacent positioning, the other deploying direct-to-consumer recurring revenue models that reduce customer acquisition cost amortization over time.
| Leading Market Players |
|---|
| Nestlé Purina Petcare |
| Nutramax Laboratories |
| Virbac |
| Zoetis |
| Mars |
| Zesty Paws |
| NOW Foods |
| Bayer AG |
| Ark Naturals |
| Others |
Value Network & Pricing Analysis
Interstate freight corridors connecting Kansas City contract manufacturing clusters to veterinary distribution networks transmit input cost volatility directly into tiered pricing structures. Marine-sourced omega fatty acid freight surcharges and cold-chain probiotic logistics compress margins for mid-tier brands while consolidating pricing power among vertically integrated operators with captive ingredient sourcing.
Pricing Analysis
Cost-plus contracts indexed to marine lipid commodity benchmarks dominate omega fatty acid formulations, passing fishery quota volatility through to veterinary clinic buyers. Three-tier pricing structure across premium, standard, and economy levels separates clinician-endorsed antioxidant blends from mass retail multivitamins and private-label economy chews. Pricing pressure stems from state-level registration fee stacking that disadvantages national distribution ambitions. Mass retail channels exhibit highest price sensitivity; veterinary-exclusive positioning sustains premium capture through recommendation-driven purchase decisions.
Supply Chain Analysis
Tariff exposure between Peru and the United States on anchovy meal concentrates threatens omega fatty acid input stability for condition-specific formulations. Supply concentration in Nebraska spray-drying facilities, Bavaria botanical extraction sites, and Osaka-Kansai palatability engineering workshops creates geographic dependency for soft chew production. Raw material flows draw from Antarctic krill fisheries, cold-pressed flaxseed cultivars, and fermentation-derived microbial cultures. Single-source vulnerability in marine lipid supply chains intensifies margin compression. Distribution runs through veterinary group purchasing organizations, direct-to-consumer subscription platforms, and mass retail consolidation networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dog vitamins market tracks the companion animal healthcare spending cycle, with premium supplement purchases accelerating as veterinary service utilization recovers from cyclical downturns.
For Market Incumbents: Pre-empt subscription commerce disruption by acquiring direct-to-consumer infrastructure or building proprietary recurring revenue platforms before mid-tier brands achieve scale. Consolidate state-level registration capabilities to neutralize compliance cost stacking that threatens national distribution economics. Defensive moves should prioritize captive supply chain control over marine lipid inputs and cold-chain probiotic logistics. For New Entrants and Emerging Players: Rural working dog populations in Australia and agricultural regions of the United States represent underpenetrated segments where performance-optimized formulations command premium positioning absent mass retail price competition. Subscription-based senior dog condition management offers the most penetrable entry vector given aging canine demographics and sustained therapeutic need articulation. Go-to-market execution should anchor in veterinary clinic portal partnerships rather than mass retail shelf space contests. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational CPG conglomerates seeking to divest non-core pet supplement portfolios amid portfolio rationalization pressures. Long-term viability hinges on regulatory science capabilities that navigate evolving FDA probiotic classification and AAFCO ingredient definition updates. Monitor AAFCO model bill harmonization progress as inflection indicator for multi-state distribution scalability and registration friction reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Partnership | Clinician endorsement protocols in the United States sustain pricing power unavailable through mass retail. |
| Subscription Infrastructure Deployment | Direct-to-consumer recurring revenue models reduce customer acquisition cost amortization for Zesty Paws-type operators. |
| Cold-Chain Logistics Investment | Probiotic stability requirements demand specialized distribution infrastructure beyond conventional supplement standards. |
| State Registration Consolidation | Multi-state feed control compliance capabilities neutralize cost stacking that fragments national distribution ambitions. |
| Marine Lipid Supply Security | Backward integration into Antarctic krill and anchovy meal sourcing insulates margin stability from fishery quota restrictions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA Center for Veterinary Medicine registration databases, AAFCO ingredient definition updates, and state feed control official inspection protocols. Conversations with veterinary nutrition specialists, contract manufacturing plant managers, pet specialty retailer category buyers, and companion animal pharmaceutical regulatory affairs directors inform formulation trend and channel dynamics assessment. Customs records on marine lipid imports and Nielsen retail audit data on supplement velocity provide volume calibration. Bottom-up SKU-level analysis triangulates against top-down spending estimates from veterinary service utilization surveys.
Forecast inputs span delivery format adoption curves, life-stage demographic shifts, and channel migration patterns across the projection horizon. Segmentation dimensions modeled include product type, formulation complexity, distribution channel concentration, and target age group therapeutic intensity. CAGRs derive from logistic diffusion curves fitted to historical supplement penetration rates and veterinary recommendation incidence data. Industry-specific inputs incorporate AAFCO model bill adoption timelines and FDA probiotic classification determination probabilities.
Practitioners should monitor fishery quota restrictions, state feed control harmonization progress, and subscription commerce penetration rates for early signals of forecast revision necessity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Bird Toy Market
Pet Care Products
Saudi Arabia Dog Food Market
Pet Care Products
Automatic and Smart Pet Feeder Market
Pet Care Products
UAE Pet Food Market
Pet Care Products
Dog Collars Market
Pet Care Products
Cat Harness Market
Pet Care Products
Dog Food for Small Breeds Dogs Market
Pet Care Products
Dog Hoodies Market
Pet Care Products
United Kingdom Pet Food Market
Pet Care Products
North America Pet Food Market
Pet Care Products
Canned Dog Food Market
Pet Care Products
Asia-Pacific Pet Clothing Market
Pet Care Products
Pet Hair Brush Market
Pet Care Products
Pet Grooming Gloves Market
Pet Care Products
North America Pet Food Nutraceuticals Market
Pet Care Products
Cat Condos and Indoor Houses Market