
 Luxury Beauty Devices Market | 2026-2036
Luxury Beauty Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Beauty Devices Market Insights
Subscription-based filter replenishment and software-locked treatment protocols is expanding the addressable revenue per unit beyond the initial hardware sale. L'Oréal leverages its dermatological science heritage to sustain premium positioning across multi-generational buyer cohorts. Koninklijke Philips anchors its position through clinical partnerships that validate at-home efficacy claims. FOREO competes on compact industrial design and direct-to-consumer channel control, bypassing traditional retail margin structures.
Luxury beauty devices encompass electronically powered instruments engineered to deliver controlled energy outputs—typically between 1-20 MHz for radiofrequency modalities or specific nanometer wavelengths for LED therapy—to modify skin appearance, hair growth patterns, or muscular tone. These instruments deploy biocompatible electrode materials, medical-grade silicone sealing, and precision thermal sensors to ensure repeatable dosing across consumer and professional environments. LED masks and microcurrent devices command the highest margin pools due to lower per-unit component costs and stronger brand storytelling potential, while hair removal systems face maturity pressure from salon-based laser alternatives and intensifying competition from energy-based professional equipment. Radiofrequency and light therapy segments attract disproportionate R&D allocation as manufacturers pursue FDA 510(k) clearances that unlock dermatology clinic procurement channels and justify premium price architecture.
The FDA's 510(k) premarket notification framework and the EU Medical Device Regulation (MDR) classify many laser and intense pulsed light devices as Class II medical instruments, compelling manufacturers to submit clinical performance data and establish post-market surveillance systems before commercial distribution. Japan's Ministry of Health, Labour and Welfare (MHLW) imposes additional quarantine inspection requirements on radiofrequency equipment, creating non-tariff barriers that favor domestic incumbents like YA-MAN Ltd. Stakeholders must monitor how China's National Medical Products Administration (NMPA) reconciles its cosmetic device registration pathway with emerging home-use energy device categories, as this determination will reshape market access rules for imported premium hardware.
Market Dynamics
Clinic-grade efficacy expectations migrating into home-use environments are compressing development cycles and forcing manufacturers to reconcile consumer accessibility with medical-grade safety documentation under FDA 510(k) and EU MDR frameworks.
Growth Catalysts
- Subscription filter replenishment models:Hardware manufacturers now capture recurring revenue through locked treatment protocols requiring authenticated consumables, extending customer lifetime value beyond initial device purchase.
- FDA 510(k) clearance acceleration:Dermatology clinics in the United States are expanding procurement of cleared radiofrequency and light therapy systems as patient demand for documented clinical outcomes intensifies.
- Radiofrequency engineering clusters:Domestic brands in South Korea and China command premium positioning through proprietary microcurrent and multi-polar RF architectures that reduce treatment time while maintaining thermal safety margins.
Market Restraints
- Medical-grade component sourcing:Precision thermal sensors and biocompatible electrode materials face supply concentration among Japanese and German specialty component suppliers, creating input cost volatility.
- Salon-based laser substitution:Professional diode and alexandrite hair removal systems in dermatology practices and medical spas are capturing patients who might otherwise purchase at-home IPL devices.
- Japan MHLW quarantine inspections:Radiofrequency equipment faces extended customs clearance protocols that favor domestic incumbents and delay market entry for foreign manufacturers.
Strategic Opportunities
- Software-locked treatment ecosystems:Firmware updates and geofenced protocol activation create captive aftermarket revenue streams while enabling real-time safety monitoring.
- China NMPA cosmetic device pathway clarification:Pending regulatory determinations on home-use energy device classification will reshape import access rules for premium hardware manufacturers.
- LED-microcurrent convergence:Multi-modal devices combining nanometer-specific light therapy with facial muscle stimulation are opening premium price tiers in direct-to-consumer channels.
Industry Challenges
- Clinical validation talent scarcity:Manufacturers struggle to recruit biostatisticians and dermatological researchers capable of designing trials that satisfy FDA premarket notification requirements for Class II medical device designation.
- Post-market surveillance infrastructure:EU MDR mandates for active device monitoring demand investment in adverse event tracking systems that many consumer-facing brands lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Beauty Devices Market |
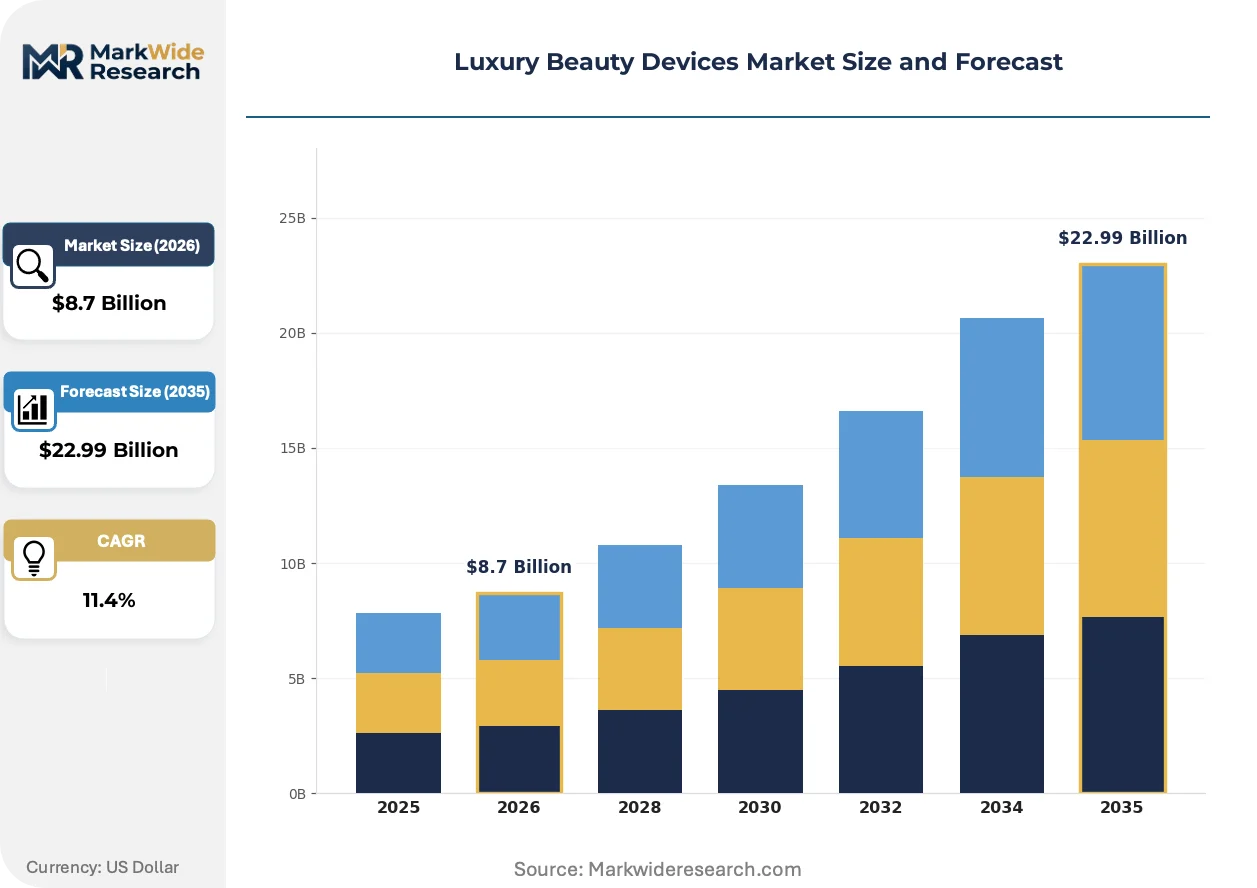
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Facial Cleansing Brushes, LED Masks, Microcurrent Devices, Hair Removal Systems Technology: Ultrasound, Radiofrequency, Laser, Light Therapy End User: Consumers, Salons, Dermatology Clinics, Spa Centers Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | L'Oréal, Nu Skin Enterprises, Estée Lauder Companies, Koninklijke Philips, FOREO, Procter & Gamble, YA-MAN Ltd., Candela Corporation, Tria Beauty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Beauty Devices Market Trends and Innovations
Energy-based modalities are converging with connected health infrastructure, creating treatment ecosystems where hardware, consumables, and clinical validation data circulate through unified digital platforms rather than discrete product sales.
Radiofrequency systems are integrating precision thermal feedback loops that adjust energy delivery in real-time based on skin impedance readings. Dermatology clinics in Germany and the United States are adopting these closed-loop architectures to reduce operator training requirements while maintaining treatment consistency. This convergence of sensor hardware and adaptive firmware is integrating clinical safety protocols into devices previously positioned as pure consumer electronics.
The EU Medical Device Regulation's post-market surveillance requirements are forcing manufacturers to establish pharmacovigilance-style reporting systems for energy-based devices previously regulated as cosmetics. Industrial consequence includes mandatory clinical follow-up studies and periodic safety updates that extend product development timelines by 12-18 months. Hair removal and skin resurfacing categories face the steepest compliance burden, with several manufacturers withdrawing marginal product lines rather than absorbing surveillance infrastructure costs.
Direct-to-consumer brands are displacing traditional retail distribution through owned-channel subscription models that bundle hardware with personalized treatment plans and remote dermatologist consultations. This channel shift concentrates customer data ownership with manufacturers while reducing margin leakage to specialty retailers. South Korea and China's domestic markets exhibit the most advanced execution of this model, where social commerce integration enables real-time treatment customization based on user-reported outcomes.
Luxury Beauty Devices Market Segmentation
Segmentation in luxury beauty devices reveals how technical specifications, regulatory pathways, and channel economics create divergent margin profiles across otherwise similar hardware categories. Manufacturers must align R&D allocation, certification strategy, and distribution investment with the specific dynamics of each segment cluster.
Product Type:
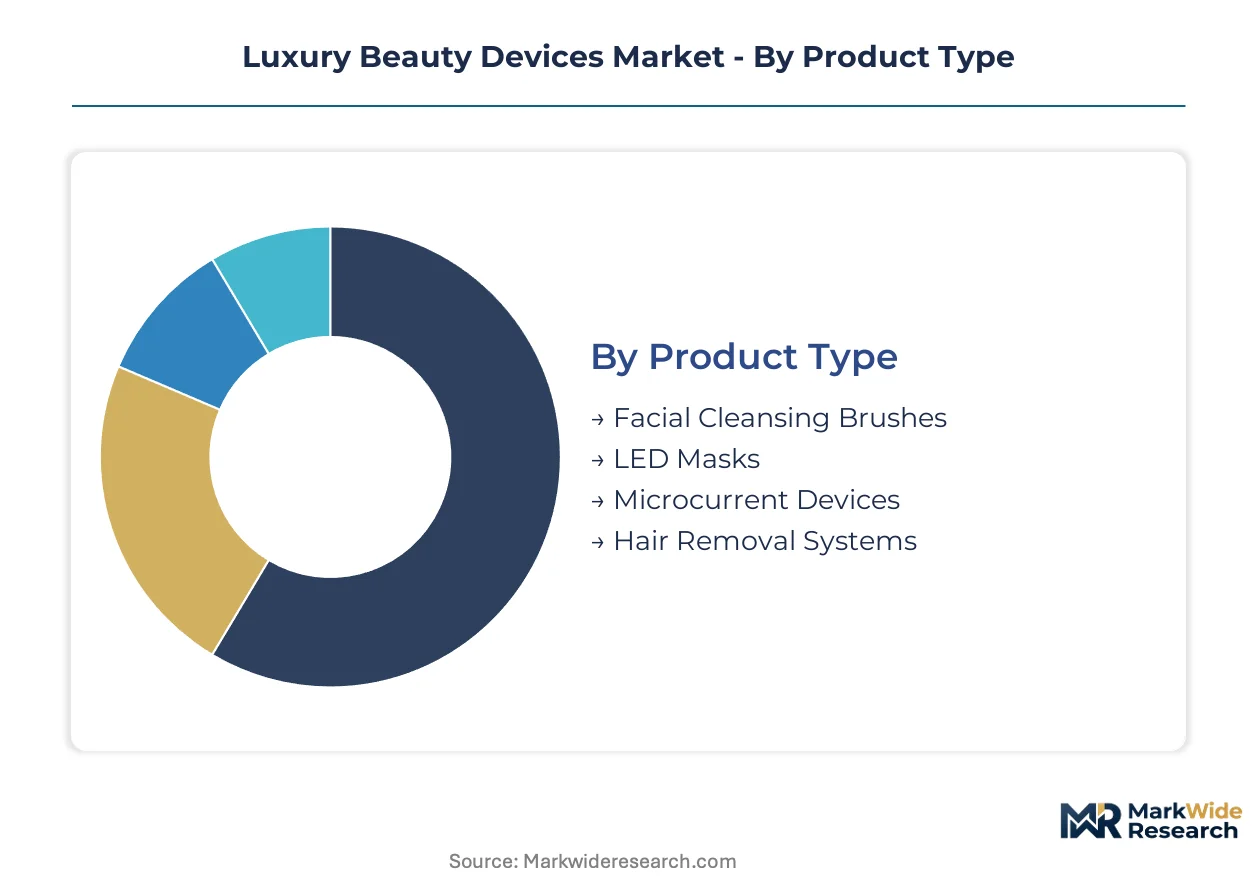
LED masks and microcurrent devices command outsized margin pools due to lower component costs and stronger direct-to-consumer storytelling potential, while facial cleansing brushes and hair removal systems face distinct competitive pressures.
- LED Masks:Nanometer-specific diode arrays deliver controlled light therapy through flexible silicone substrates. Demand concentrates in South Korea and China's social commerce channels where K-beauty influencers drive premium positioning through clinical efficacy narratives. The segment benefits from minimal thermal regulation burden compared to energy-based alternatives.
- Microcurrent Devices:Low-level electrical stimulation between 1-400 microamperes targets facial muscle toning through biocompatible metal electrodes. Dermatology clinics in Germany and the United States are expanding procurement as patients seek documented alternatives to injectable treatments. Firmware-locked treatment protocols create recurring authentication revenue streams.
- Facial Cleansing Brushes:Sonic vibration systems with silicone or fiber bristle heads dominate mass-market penetration but face margin compression from private-label alternatives and smartphone-connected competitors.
- Hair Removal Systems:IPL and diode laser devices for home use confront substitution pressure from professional alexandrite and Nd:YAG systems in medical spa environments.
Today's leader: LED masks. Tomorrow's challenger: Microcurrent devices.
Technology:
Radiofrequency and light therapy modalities attract disproportionate R&D investment as manufacturers pursue FDA 510(k) clearances that unlock clinic procurement channels and justify premium price architecture.
- Radiofrequency:Multi-polar and fractional RF systems operating between 1-20 MHz generate controlled dermal heating through impedance-matched electrodes. South Korean engineering clusters lead proprietary architectures that reduce treatment duration while maintaining thermal safety margins. The technology faces Japan MHLW quarantine inspection barriers that favor domestic incumbents.
- Light Therapy:LED and laser systems emitting specific nanometer wavelengths target photobiomodulation pathways. China's NMPA cosmetic device registration pathway remains unresolved for home-use energy categories, creating regulatory uncertainty for import-dependent brands.
- Ultrasound:High-frequency mechanical vibration devices enhance topical penetration through cavitation effects, finding niche positioning in premium facial treatment protocols.
- Laser:Diode and fractional laser systems for hair removal and skin resurfacing carry the heaviest FDA Class II medical device compliance burden, extending development timelines through clinical validation requirements.
Radiofrequency systems currently capture the steepest expansion trajectory as clinic-grade efficacy migrates into home-use environments.
End User:
Consumer-facing channels dominate unit volume while professional segments concentrate value through certified clinical outcomes and equipment financing arrangements.
- Dermatology Clinics:Medical practices require FDA 510(k) cleared or EU MDR Class IIa certified devices with documented safety profiles and operator training protocols. Procurement decisions prioritize liability protection and treatment consistency over unit economics.
- Consumers:Direct purchasers respond to influencer validation, subscription bundling, and app-connected treatment personalization. China's social commerce integration enables real-time outcome-based protocol adjustments.
- Spa Centers:Wellness facilities seek differentiated treatment menus with shorter payback periods than clinical equipment, favoring lease-friendly hardware with minimal maintenance requirements.
- Salons:Hair and beauty establishments concentrate demand for hair removal systems but face competitive pressure from dedicated laser clinics with superior device specifications.
Professional segments anchor premium pricing; consumer channels drive scale economics.
Distribution Channel:
Channel strategy determines margin retention, customer data ownership, and regulatory compliance burden across geographically divergent market access rules.
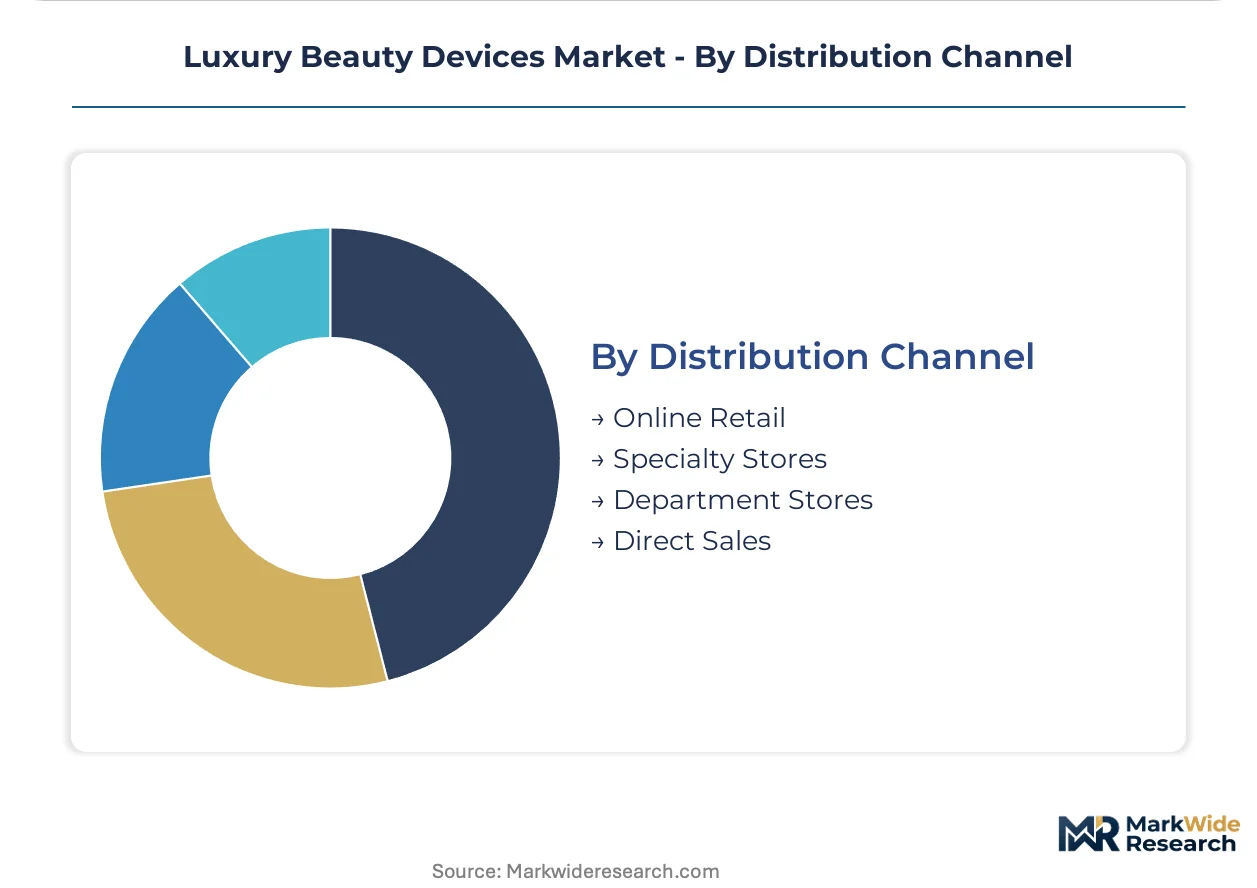
- Online Retail:Brand-owned direct-to-consumer platforms and marketplace presence enable subscription filter replenishment and firmware-locked treatment ecosystems. South Korean and Chinese domestic brands execute the most advanced social commerce integration.
- Direct Sales:Manufacturer-controlled channels capture full margin while establishing pharmacovigilance infrastructure for EU MDR post-market surveillance compliance.
- Specialty Stores:Beauty retailers provide tactile product experience but extract significant wholesale discounts and demand promotional support that erodes profitability.
- Department Stores:Prestige positioning through heritage retail formats sustains brand equity for established players but requires substantial counter investment and staffing costs.
Owned digital channels are gaining share fastest as manufacturers prioritize recurring revenue and safety monitoring infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's domestic brands command premium positioning through proprietary radiofrequency architectures, while the United States concentrates clinic-grade procurement demand as dermatology practices expand device programs. Regulatory divergence across major markets is reshaping competitive access rules and R&D location decisions.
United States
Dermatology clinics in New York, Los Angeles, and Miami are accelerating procurement of FDA 510(k) cleared radiofrequency and light therapy systems as patients demand documented clinical outcomes. The FDA's evolving oversight of laser and light-based products is compelling manufacturers toward stricter safety documentation and clinical validation protocols. Boston-area medical device clusters host biostatisticians and dermatological researchers designing trials for Class II medical device designation.
China
Domestic brands in Shanghai and Shenzhen capture premium positioning through advanced radiofrequency and microcurrent engineering for social commerce channels. The National Medical Products Administration's pending determination on home-use energy device classification will reshape import access rules for premium hardware manufacturers. The Yangtze River Delta concentrates LED mask manufacturing with K-beauty influencer-driven demand validation.
South Korea
Seoul-based engineering clusters lead proprietary multi-polar RF architectures that reduce treatment duration while maintaining thermal safety margins. The Ministry of Food and Drug Safety regulates cosmetic devices with frameworks that favor domestic incumbents familiar with local compliance pathways. Busan-Ulsan manufacturing corridors supply precision thermal sensors to regional device assemblers.
Germany
Dermatology practices in Munich and Hamburg adopt closed-loop radiofrequency systems with real-time thermal feedback to reduce operator training requirements. The EU Medical Device Regulation mandates pharmacovigilance-style reporting systems that extend product development timelines through post-market surveillance infrastructure. Baden-Württemberg precision component suppliers concentrate biocompatible electrode material production.
Japan
Tokyo and Osaka clinics favor domestic RF equipment brands due to Ministry of Health, Labour and Welfare quarantine inspection protocols that delay foreign manufacturer market entry. YA-MAN Ltd. and other domestic incumbents leverage extended customs clearance barriers to defend market position. Nagoya-area industrial clusters specialize in medical-grade silicone sealing components for device manufacturers.
Luxury Beauty Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium-tier players consolidating around clinical validation assets while mass-market entrants compete on direct-to-consumer channel efficiency. The vendor base organizes into three archetypes: heritage beauty conglomerates with dermatological science legacies, electronics specialists with clinical partnership networks, and digitally native disruptors with owned-channel subscription models. M&A activity concentrates on software-locked treatment ecosystem capabilities, while strategic partnerships with dermatology clinics validate at-home efficacy claims for premium positioning.
Within the heritage conglomerate tier, L'Oréal and Estée Lauder Companies occupy positions sustained by multi-generational buyer cohort trust and dermatological science heritage. Koninklijke Philips anchors the electronics specialist archetype through clinical partnerships that validate efficacy documentation. FOREO exemplifies the digitally native disruptor model with direct-to-consumer channel control and compact industrial design differentiation. YA-MAN Ltd. represents domestic incumbent defense strategies in Japan's inspection-favored market structure.
| Leading Market Players |
|---|
| L'Oréal |
| Nu Skin Enterprises |
| Estée Lauder Companies |
| Koninklijke Philips |
| FOREO |
| Procter & Gamble |
| YA-MAN Ltd. |
| Candela Corporation |
| Tria Beauty |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between FDA 510(k) cleared devices and cosmetic-grade alternatives manifests in both premium pricing architectures and concentrated component sourcing from Japanese and German specialty suppliers. This bifurcation creates distinct margin pools where clinical validation investments justify three-tier pricing structures across premium, standard, and economy levels while locking in supply relationships with precision thermal sensor and biocompatible electrode manufacturers.
Pricing Analysis
Capacity additions in South Korea and China are reshaping price floors for LED masks and microcurrent devices as domestic engineering clusters achieve scale economies in multi-polar RF architectures. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared clinic-grade systems from direct-to-consumer cosmetic devices and private-label alternatives. Pricing pressure stems from salon-based laser substitution in hair removal categories where professional alexandrite systems capture patients seeking documented outcomes. Dermatology clinics exhibit lowest price sensitivity due to liability protection requirements, while mass-market consumers respond aggressively to influencer-promoted alternatives.
Supply Chain Analysis
Precision thermal sensor supply rests on Japanese specialty component producers like those in the Nagoya industrial corridor and Baden-Württemberg precision engineering clusters in Germany. Biocompatible electrode materials, medical-grade silicone sealing, and impedance-matched RF components draw from concentrated supplier bases in Japan, Germany, and select South Korean manufacturing corridors. Single-source vulnerability intensifies around FDA-validated component grades where alternative qualification timelines extend development cycles. Distribution runs through brand-owned direct-to-consumer platforms and dermatology clinic procurement channels, with social commerce integration gaining share fastest in South Korea and China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The luxury beauty devices market reads as a late-cycle quality story where patient demand for documented clinical outcomes is shifting procurement decisions toward FDA 510(k) cleared and EU MDR certified systems with established safety profiles.
For Market Incumbents: Extend clinical validation assets into software-locked treatment ecosystems that capture recurring authentication revenue and enable real-time safety monitoring. Deepen backward integration into precision thermal sensor supply through partnerships with Japanese and German specialty component suppliers to defend margin position against emerging RF engineering clusters in South Korea and China.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models bundled with remote dermatologist consultations to bypass traditional retail margin extraction and establish owned-channel customer data. Target China's pending NMPA cosmetic device pathway clarification as the most penetrable regulatory opening, positioning multi-modal LED-microcurrent convergence devices for premium social commerce positioning before import rules solidify.
For Investors and Strategic Acquirers: Consolidation pressure builds where clinical validation talent scarcity and EU MDR post-market surveillance infrastructure requirements outstrip capital availability for mid-tier consumer-facing brands. Acquisition targets include digitally native disruptors with firmware-locked protocol capabilities and established pharmacovigilance systems. Watch FDA 510(k) clearance acceleration timelines and China NMPA classification determinations as inflection indicators for premium hardware import access.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Locked Treatment Ecosystem Development | Firmware authentication creates captive aftermarket revenue streams while satisfying EU MDR traceability mandates. |
| FDA 510(k) Premarket Notification Acceleration | Clearance unlocks dermatology clinic procurement channels and justifies premium price architecture against cosmetic-grade alternatives. |
| Clinical Partnership Network Expansion | Collaborations with Boston-area medical device clusters validate at-home efficacy claims for multi-generational buyer cohort trust. |
| Social Commerce Integration | Real-time outcome-based protocol adjustments in South Korea and China enable personalized treatment customization at scale. |
| Backward Integration into Precision Components | Captive supply of biocompatible electrodes and thermal sensors reduces input cost volatility from Japanese and German suppliers. |
Research Methodology
Multiple input streams — primary interviews with dermatology clinic procurement managers, biomedical engineers at device manufacturers, and regulatory affairs specialists at FDA 510(k) submission consultancies, plus secondary validation through FDA premarket notification databases, EU MDR technical documentation filings, and South Korean MFDS cosmetic device registration records — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured treatment protocol adoption patterns, certification investment timelines, and channel economics across professional and consumer segments. Secondary sources included customs trade data for precision component flows, hospital procurement database extracts for clinic-grade device purchasing patterns, and social commerce analytics for direct-to-consumer demand validation.
Historical volume trajectories were cross-referenced against panel input from device engineering heads and dermatology practice administrators to construct analytical frameworks across the analysis window. Segmentation dimensions modeled include product type, technology modality, end-user category, and distribution channel structure. CAGRs were derived from fitted growth curves applied to verified baseline data, with inputs from radiofrequency engineering cluster capacity announcements, LED mask manufacturing scale disclosures from Yangtze River Delta facilities, and clinic procurement program expansion plans from major US metropolitan dermatology networks.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt FDA reclassification of home-use energy devices or sudden NMPA pathway restrictions in China. Forecasts reflect assumptions around regulatory stability, component supply continuity, and sustained patient demand for clinic-grade outcomes in home-use environments. A small set of named triggers — FDA 510(k) backlog clearance rates, EU MDR notified body capacity constraints, and China NMPA cosmetic device classification determinations — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Face Makeup Market
Beauty & Personal Care
Nail Care Market
Beauty & Personal Care
Asia-Pacific Bath and Shower Products Market
Beauty & Personal Care
France Dermocosmetics Market
Beauty & Personal Care
Middle East and Africa Hair Styling Products Market
Beauty & Personal Care
Cosmetics Face Serum Market
Beauty & Personal Care
Global Personal Care Emollients Market
Beauty & Personal Care
Beauty Products Market
Beauty & Personal Care
UAE Beauty Industry Market
Beauty & Personal Care
Beauty and Wellness Products Market
Beauty & Personal Care
Global Electric Head and Scalp Massager Market
Beauty & Personal Care
Saudi Arabia Beauty and Personal Care Market
Beauty & Personal Care
Sunless Tanners Market
Beauty & Personal Care
Personal Care Products Market
Beauty & Personal Care
Body Mist Market
Beauty & Personal Care
Global Cosmetic Products Market