
 Deodorant Wipes Market | 2026-2036
Deodorant Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
Deodorant Wipes Market Analysis
Buyer fragmentation across fitness studios, travel retailers, and direct-to-consumer channels is repositioning how manufacturers allocate production capacity and brand investment. Procter & Gamble leverages its established personal care infrastructure to sustain shelf presence across mass retail formats. Diamond Wipes International specializes in contract manufacturing and private-label programs, anchoring supply relationships with emerging brands seeking speed-to-market.
Deodorant wipes are pre-moistened nonwoven substrates impregnated with antimicrobial agents, aluminum compounds, or botanical extracts designed for axillary and body odor control without water access; substrates typically span 40-80 gsm viscose-polyester blends with pH-balanced formulations between 4.5 and 5.5. The natural product type commands premium shelf positioning as consumers scrutinize ingredient transparency and paraben-free claims. Travel pack configurations dominate impulse purchase occasions at airports and convenience locations, while bulk packs anchor recurring household demand through club and online retail channels.
FDA oversight of cosmetic safety claims and EPA registration requirements for antimicrobial active ingredients shape product development timelines and labeling compliance for US market entrants. The EU REACH regulation and concurrent ECHA substance evaluations restrict certain preservative chemistries, compelling reformulation investments across export-oriented manufacturers. Stakeholders must monitor evolving state-level chemical disclosure mandates and retailer-specific clean beauty standards that increasingly gate market access before federal rulemaking crystallizes.
Market Dynamics
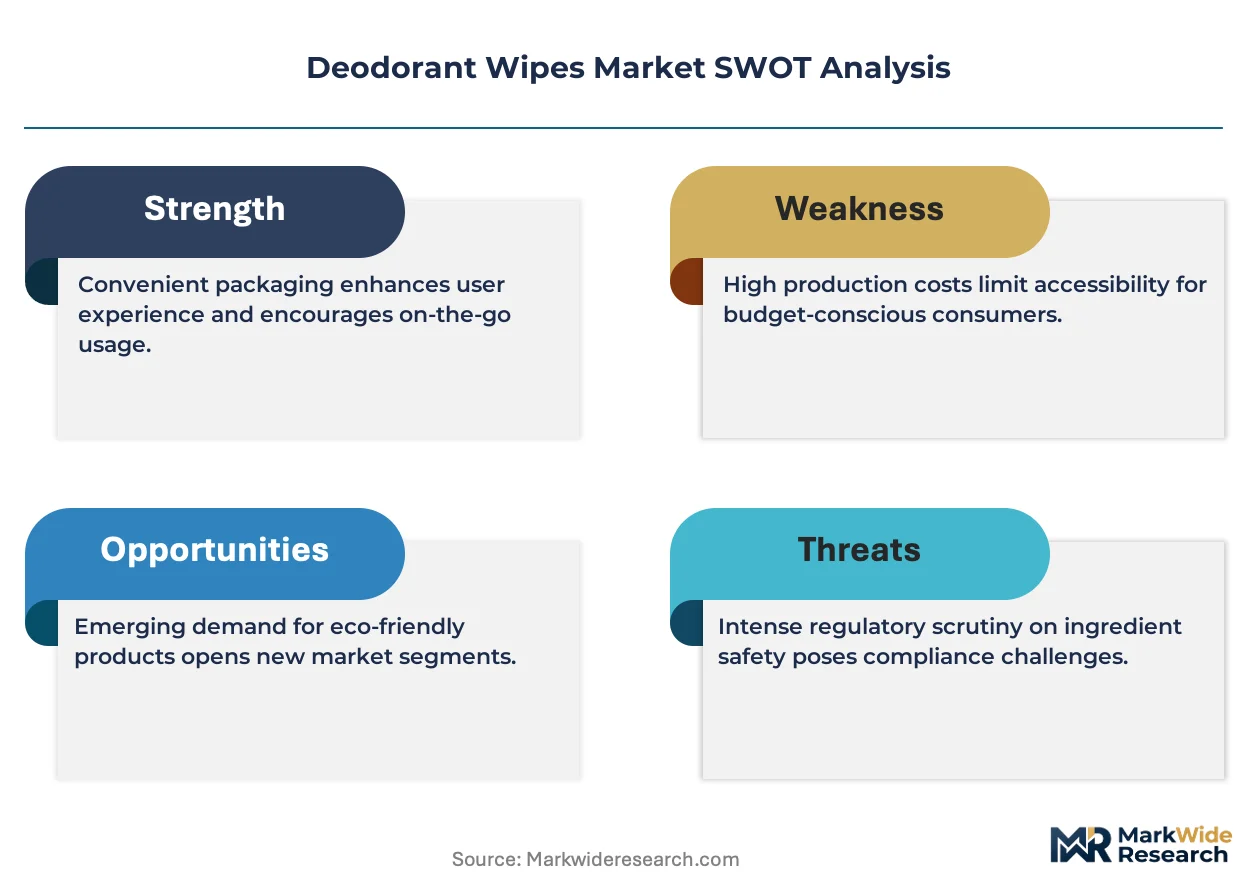
EU REACH substance evaluations are forcing wholesale reformulation of preservative systems across deodorant wipe portfolios, compressing development timelines and elevating compliance costs for export-oriented manufacturers while simultaneously opening premium positioning for verified clean-label alternatives.
Growth Catalysts
- Fitness studio penetration:Post-workout hygiene protocols at boutique cycling and HIIT chains are normalizing single-use wipe consumption among urban millennials, creating habitual purchase patterns that extend beyond gym environments into daily commuting routines.
- REACH-compliant botanical actives:ECHA-approved plant-derived antimicrobial extracts are replacing restricted synthetic biocides in premium formulations, satisfying clean beauty criteria without sacrificing efficacy claims in EU member states.
- Airport retail expansion:Travel-pack SKUs at duty-free and convenience locations in Frankfurt, Dubai, and Singapore are capturing impulse purchases from business travelers seeking TSA-compliant personal care solutions.
Market Restraints
- Viscose feedstock volatility:Wood pulp price swings and rayon supply concentration in Southeast Asian integrated producers are squeezing substrate margins for nonwoven converters serving the personal care sector.
- Aluminum salt scrutiny:Pending EPA reviews of antimicrobial active ingredient registrations are extending product launch timelines and forcing contingency formulation investments among US market entrants.
- Reusable substitute emergence:Washable microfiber body cloths and refillable spray formats are capturing environmentally conscious consumers in Nordic markets where single-use plastic levies apply.
Strategic Opportunities
- Subscription direct-to-consumer models:Auto-replenishment programs targeting gym enthusiasts and frequent travelers are bypassing slotting fee pressures at mass retail while capturing lifetime value through personalized scent profiles.
- Men's grooming aisle expansion:Underpenetrated masculine-positioned SKUs at club retailers and specialized barbershop channels represent whitespace as male personal care routines incorporate more frequent on-the-go refreshment.
- State-level chemical disclosure mandates:California's Cleaning Product Right to Know Act and emerging New York transparency requirements are creating first-mover advantage for brands with pre-positioned ingredient transparency infrastructure.
Industry Challenges
- Preservative system validation:Demonstrating 24-month shelf stability for paraben-free and phenoxyethanol-free formulations requires extended accelerated aging protocols that compress margin recovery timelines.
- Cross-border labeling complexity:Concurrent compliance with FDA cosmetic regulations, EU CLP hazard classification, and divergent state-level fragrance allergen disclosure rules multiplies SKU proliferation and inventory management overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deodorant Wipes Market |
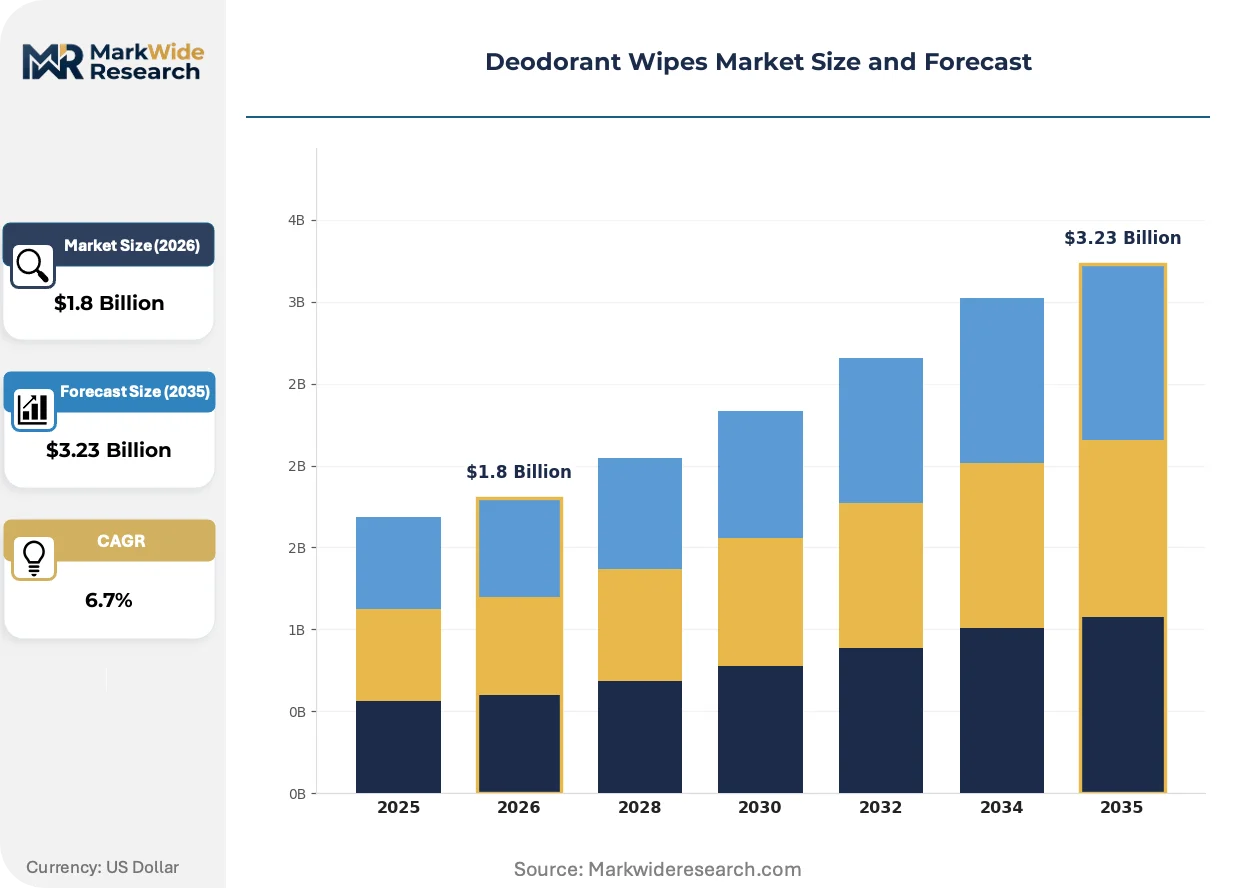
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unscented, Scented, Antiperspirant, Natural End User: Adults, Teens, Seniors, Children Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Pharmacies Packaging Type: Travel Pack, Bulk Pack, Refillable, Resealable |
| Companies Covered | Nice-Pak Products, Shiseido, Johnson & Johnson, Diamond Wipes International, Svenska Cellulosa Aktiebolaget (SCA), Procter & Gamble, Rockline Industries, Unilever, Kimberly-Clark, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deodorant Wipes Market Emerging Trajectories
Biodegradable substrate technologies and waterless formulation science are converging to redefine performance benchmarks, while regulatory pressure on chemical transparency accelerates investment in supply chain traceability infrastructure.
Dissolvable nonwoven technologies incorporating polylactic acid and regenerated cellulose fibers are decentralizing disposal infrastructure requirements for deodorant wipe products. Fitness chains and outdoor recreation retailers are piloting these formats in markets with limited composting facilities but stringent marine plastic regulations. The structural consequence is decentralizing waste management liability from municipal systems toward product-level end-of-life design accountability.
EU F-Gas Regulation phase-down schedules are indirectly pressuring aerosol deodorant alternatives, creating regulatory tailwinds for wet wipe formats as propellant-dependent products face supply constraints and carbon footprint penalties. German and French mass retailers are reallocating shelf space toward pump-spray and wipe alternatives in response. Personal care buyers in Benelux markets are responding fastest, with private-label programs accelerating reformulation timelines to capture switching demand.
Ingredient traceability demands from Sephora, Ulta, and Target clean beauty certification programs are compressing supplier qualification cycles for deodorant wipe brands. Contract manufacturers must now provide batch-level documentation for botanical sourcing and preservative origin, displacing opaque supply relationships. This verification burden is most visible among emerging direct-to-consumer brands seeking rapid retailer distribution expansion without established quality infrastructure.
Deodorant Wipes Market Segmentation
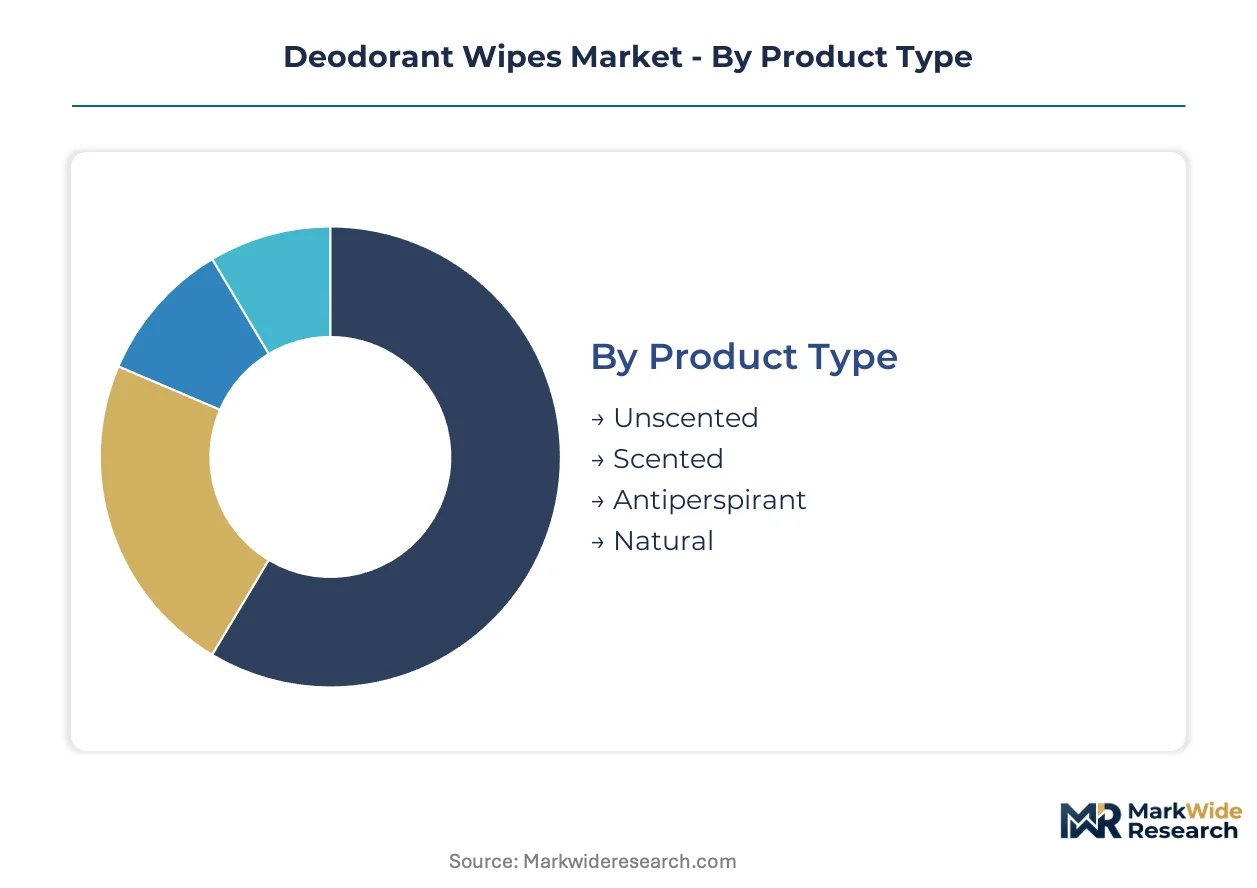
Deodorant wipe manufacturers calibrate formulation chemistry, substrate weight, and packaging formats against distinct usage occasions and buyer willingness-to-pay thresholds. Segment boundaries blur as fitness studios stock travel packs for impulse purchase while subscription services push bulk configurations with personalized scent profiles.
Product Type:
Ingredient transparency and efficacy claims separate buyers across this dimension, with clean-label scrutiny reshaping R&D allocation and shelf positioning strategies.
- Natural:Botanical antimicrobial extracts and aluminum-free formulations target Sephora and Ulta clean beauty certification programs. EU REACH-compliant preservative systems command premium positioning as ECHA substance evaluations restrict synthetic biocide alternatives.
- Antiperspirant:Aluminum salt complexes deliver clinical-grade sweat reduction for hyperhidrosis sufferers and high-intensity athletes. Pending EPA registration reviews extend launch timelines and force contingency investments among US market entrants.
- Scented:Fragrance-forward formulations leverage essential oil blends and synthetic perfumery for mood-positioning at airport retail and boutique fitness chains.
- Unscented:Hypoallergenic formulations serve fragrance-sensitive consumers and clinical settings where odor-masking conflicts with medical protocols.
Volume sits with Antiperspirant; growth tilts toward Natural.
End User:
Life stage determines application frequency, skin sensitivity tolerance, and channel preference across this category.
- Adults:Urban millennials in boutique cycling and HIIT chains normalize post-workout wipe consumption, extending habitual purchase patterns into daily commuting routines. Subscription auto-replenishment captures lifetime value through personalized scent profiles.
- Teens:Back-to-school promotional cycles and social anxiety around body odor drive trial-heavy purchasing at mass retail and drugstore channels. Influencer marketing on TikTok and Instagram accelerates brand discovery.
- Seniors:Limited mobility and reduced shower accessibility elevate dependence on bedside and travel hygiene solutions. Medicare Advantage supplemental benefit programs in Florida and Arizona pilot coverage for dermatologist-recommended formulations.
- Children:Pediatric dermatologist approval and tear-free pH specifications gate market entry. School backpack formats and cartoon-branded packaging compete for parental trust at Target and Walmart.
Adults anchor current revenue; Teens show steepest expansion trajectory.
Distribution Channel:
Fulfillment speed and purchase context—planned replenishment versus impulse refresh—determine channel economics and packaging format.
- Online Retail:Direct-to-consumer subscription models bypass slotting fee pressures while capturing behavioral data for scent personalization. Amazon's Subscribe & Save and brand-owned Shopify storefronts dominate recurring household demand.
- Convenience Stores:Single-unit travel packs at 7-Eleven and Wawa capture unplanned purchase occasions during commute and workout schedules. Placement near checkout counters drives trial among new category entrants.
- Supermarkets:Club pack configurations at Costco and Kroger anchor pantry-loading behavior with per-wipe cost minimization. End-cap displays during summer months and New Year fitness resolutions spike seasonal velocity.
- Pharmacies:CVS and Walgreens leverage pharmacist recommendation authority for clinical-positioned antiperspirant variants. Co-location with deodorant sticks and prescription dermatology treatments reinforces efficacy credibility.
Supermarkets move the most units; Online Retail gains share fastest.
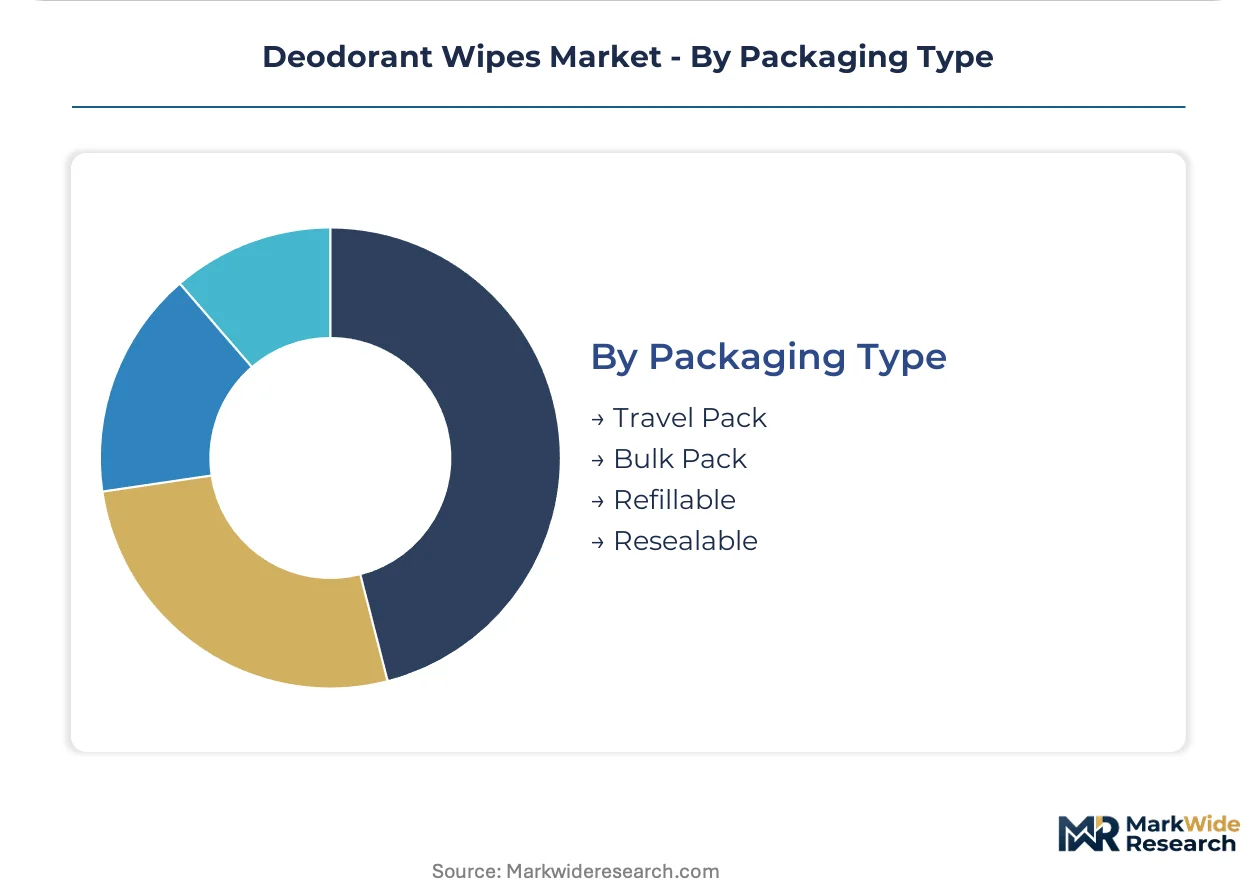
Packaging Type:
Portability requirements and sustainability priorities clash across this dimension, forcing material science trade-offs.
- Travel Pack:TSA-compliant 10-count sachets and slim pouches dominate airport duty-free and gym bag contexts. Dissolvable nonwoven pilots in German and French markets address marine plastic regulations.
- Bulk Pack:30- to 100-count resealable tubs minimize per-use cost for household stockpiling. Refill pouch compatibility reduces rigid plastic consumption for sustainability-committed buyers.
- Resealable:Zip-lock and adhesive-strip closures preserve moisture integrity across intermittent usage patterns. Premium substrates with higher viscose content justify elevated price points.
- Refillable:Hard-shell dispensers with cartridge replacement systems target zero-waste households in Nordic markets with single-use plastic levies. Washable microfiber body cloths compete for this environmentally conscious segment.
Bulk Pack captures household volume; Travel Pack climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wood pulp supply from Swedish and Finnish forests anchors substrate sourcing for nonwoven converters serving personal care wipe production across developed markets.
United States
Urban commuting culture and boutique fitness studio proliferation drive post-workout wipe consumption among millennials in New York and Los Angeles. FDA cosmetic safety claims oversight and EPA antimicrobial registration requirements shape formulation compliance timelines. Procter & Gamble maintains shelf presence across mass retail formats through established personal care infrastructure.
Germany
Benelux personal care buyers respond fastest to EU F-Gas Regulation phase-down schedules pressuring aerosol alternatives. ECHA substance evaluations under REACH restrict preservative chemistries, compelling reformulation investments by export-oriented manufacturers. Frankfurt airport retail expansion captures impulse purchases from business travelers seeking TSA-compliant hygiene solutions.
China
Rising gym membership rates and active lifestyle adoption among urban middle-class consumers expand addressable demand in Shanghai and Beijing. SAMR oversight of cosmetic safety and dual carbon goals influence manufacturing facility emissions compliance. Zhengzhou-based machinery suppliers serve domestic wipe converter capacity expansion.
Japan
Hyperhidrosis-conscious consumers and humid climate conditions sustain clinical-grade antiperspirant wipe demand in Tokyo and Osaka metropolitan areas. PMDA cosmetic regulations govern efficacy claim substantiation and labeling requirements. METI industrial standards influence substrate quality specifications for premium personal care applications.
United Kingdom
Post-pandemic hygiene habit persistence and travel recovery sustain airport and gym channel velocity in London and Manchester. Divergent post-Brexit chemical regulations from EU REACH create parallel compliance obligations for UK market entrants. Svenska Cellulosa Aktiebolaget (SCA) pulp supply relationships anchor substrate sourcing for domestic converters.
Deodorant Wipes Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue clean-label certification and subscription direct-to-consumer channels. The vendor base clusters around three strategic archetypes: diversified consumer goods conglomerates with personal care infrastructure, specialized contract manufacturers with private-label capabilities, and pulp-to-product integrated substrate suppliers. Competitive moves concentrate on M&A for geographic footprint expansion and strategic partnerships for sustainable substrate sourcing.
Within the diversified conglomerate tier, Procter & Gamble and Unilever exemplify mass retail anchoring through established hygiene product portfolios. Diamond Wipes International represents specialized contract manufacturing archetype, occupying a position in private-label and speed-to-market supply relationships. Svenska Cellulosa Aktiebolaget (SCA) anchors the integrated substrate supplier vector, with Swedish pulp production backing nonwoven feedstock security.
| Leading Market Players |
|---|
| Nice-Pak Products |
| Shiseido |
| Johnson & Johnson |
| Diamond Wipes International |
| Svenska Cellulosa Aktiebolaget (SCA) |
| Procter & Gamble |
| Rockline Industries |
| Unilever |
| Kimberly-Clark |
| Others |
Supply Flow & Price Mechanics
EU REACH substance evaluations and concurrent ECHA preservative restrictions gate qualified supply access for deodorant wipe manufacturers while simultaneously segmenting pricing tiers between compliant clean-label portfolios and legacy formulations facing reformulation cost burdens. Premium-tier pricing access concentrates with brands possessing pre-positioned ingredient transparency infrastructure and verified botanical supply chains.
Pricing Analysis
Volume concentrates with antiperspirant variants at club retailers and mass drugstore channels where per-wipe cost minimization drives household stockpiling behavior, while margin accrues to natural-positioned SKUs commanding shelf space at Sephora and Ulta under clean beauty certification programs. Price differentiation separates aluminum-free botanical formulations from clinical-grade antiperspirant alternatives, with certification tier and substrate quality grade as primary drivers. Pricing pressure stems from viscose feedstock volatility squeezing converter margins, particularly for nonwoven suppliers serving private-label programs. Mass retail buyers exhibit highest price sensitivity, whereas subscription direct-to-consumer subscribers prioritize scent personalization and convenience over per-unit cost.
Supply Chain Analysis
Viscose-polyester nonwoven substrate supply rests on Swedish and Finnish wood pulp producers, with Svenska Cellulosa Aktiebolaget anchoring feedstock security for European and North American converters. Key inputs span regenerated cellulose fibers, antimicrobial active compounds, and moisture-barrier packaging films. Supply chain risk centers on single-source vulnerability for rayon production concentrated among Southeast Asian integrated producers, compounded by pending EPA registration reviews extending active ingredient qualification timelines. Distribution runs through mass retail slotting agreements, direct-to-consumer fulfillment centers, and fitness studio replenishment contracts with divergent packaging format requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The deodorant wipes category sits at a formulation technology transition phase, with biodegradable substrate science and waterless antimicrobial chemistry displacing legacy petroleum-based nonwovens and synthetic biocide preservatives.
For Market Incumbents: Deploy backward integration into Swedish pulp supply relationships to secure viscose feedstock allocation amid rayon supply concentration. Incumbent manufacturers must accelerate paraben-free preservative system validation protocols to defend shelf positioning against emerging clean-label entrants, while expanding subscription infrastructure to capture lifetime value from fitness studio partnerships. For New Entrants and Emerging Players: Boutique fitness chains represent the most penetrable channel partner type for new entrants seeking habitual purchase pattern establishment among urban millennials. White-space targets concentrate on men's grooming aisle expansion at club retailers and specialized barbershop channels, alongside dissolvable nonwoven pilots in German and French markets with marine plastic regulations. Go-to-market execution should prioritize TSA-compliant travel pack formats for airport retail placement. For Investors and Strategic Acquirers: First-mover certification under California's Cleaning Product Right to Know Act is the leading indicator that ingredient transparency infrastructure will command acquisition premiums as state-level disclosure mandates proliferate. Long-term viability over the next decade hinges on supply chain traceability capabilities and sustainable substrate sourcing relationships. Acquisition targets should emphasize contract manufacturers with pre-positioned REACH-compliant formulation libraries and established private-label speed-to-market protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Substrate Transition | Polylactic acid and regenerated cellulose fibers address EU marine plastic regulations while differentiating premium positioning. |
| Subscription Infrastructure Buildout | Auto-replenishment programs bypass slotting fee pressures at mass retail while capturing behavioral data for scent personalization. |
| REACH-Compliant Preservative Investment | ECHA-approved botanical antimicrobial extracts satisfy clean beauty criteria without sacrificing efficacy claims in member states. |
| Men's Grooming Channel Expansion | Underpenetrated masculine-positioned SKUs at club retailers and barbershop channels represent whitespace as male routines evolve. |
| Ingredient Traceability Infrastructure | Batch-level documentation for botanical sourcing displaces opaque supply relationships demanded by Sephora and Target certification programs. |
Methodological Framework
Document review covered FDA cosmetic safety filings, EPA antimicrobial registration databases, ECHA substance evaluation records, and EU REACH compliance documentation, complemented by interviews with brand managers at diversified consumer goods conglomerates, category buyers at mass retailers, procurement leads at nonwoven converters, and regulatory affairs specialists at contract manufacturers. Secondary validation drew from customs trade data, SEC 10-K disclosures from listed personal care companies, and Nielsen retail audit information. Bottom-up volume modeling triangulated against top-down market sizing across product type, end user, and distribution channel dimensions.
Historical shipment data cross-referenced against panel input from supply chain participants anchored the analytical framework across the projection horizon. Segmentation modeling incorporated product type differentiation, end user life stage, channel fulfillment economics, and packaging format sustainability attributes. CAGRs were derived from trend extrapolation moderated by regulatory compliance timeline constraints and substrate technology adoption curves. Forecast inputs included viscose price trajectory assumptions and fitness studio penetration rates by metropolitan market.
Caveats apply where pending EPA antimicrobial active ingredient registration reviews or accelerated EU REACH substance evaluations could materially shift the outlook for formulation-compliant supply availability. Forecasts reflect assumptions regarding clean beauty certification program expansion and state-level chemical disclosure mandate adoption. A small set of named triggers—specifically viscose feedstock disruption, aluminum salt regulatory restriction, and single-use plastic levy proliferation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Cosmetics and Toiletries Market
Beauty & Personal Care
Facial Oil Market
Beauty & Personal Care
Facial Makeup Setting Spray Market
Beauty & Personal Care
Colombia Cosmetics Products Market
Beauty & Personal Care
India Hair Oil Market
Beauty & Personal Care
South America Hair Conditioner Market
Beauty & Personal Care
Men's Personal Care Market
Beauty & Personal Care
Global Body Wash and Shower Gel Market
Beauty & Personal Care
UAE Beauty Industry Market
Beauty & Personal Care
Men's Skincare Products Market
Beauty & Personal Care
US Personal Care Contract Manufacturing Market
Beauty & Personal Care
Nail Care Market
Beauty & Personal Care
Natural Deodorant Crystal Market
Beauty & Personal Care
Italy Beauty and Personal Care Products Market
Beauty & Personal Care
Middle East and Africa Hair Conditioner Market
Beauty & Personal Care
Hair Gel Market