
 Global Pipe Coatings Market | 2026-2036
Global Pipe Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pipe Coatings Market Foresight
Project finance tied to long-term offtake agreements is narrowing the competitive field for large-diameter pipeline coating contracts. PPG Industries leverages its integrated resin supply chain to sustain margin stability across volatile petrochemical cycles. Akzo Nobel anchors its position through marine-grade polyurethane systems that dominate North Sea and Caspian offshore projects. Shawcor competes via factory-applied fusion bonded epoxy capacity positioned near US and Middle East pipe mills.
Pipe coatings encompass thermoset and thermoplastic barrier systems applied to steel, ductile iron, or concrete substrates to prevent corrosion, abrasion, and chemical degradation in fluid transport infrastructure. Fusion bonded epoxy formulations cure at 230-250°C to form 250-500 micron dry-film thicknesses that deliver cathodic disbondment resistance below 10 mm² in standardized testing. Epoxy coatings occupy the largest value share due to their dominance in oil and gas transmission pipelines requiring decades of service life. Polyethylene coatings represent the fastest-expanding category as water distribution utilities in water-stressed regions prioritize flexible, trenchless rehabilitation solutions over full pipe replacement.
The US EPA enforces integrity management rules under 49 CFR Part 192 and 195 that mandate specific coating performance standards for natural gas and hazardous liquid pipelines. REACH and the EU F-Gas Regulation restrict solvent-based formulations and certain blowing agents used in polyurethane insulation coatings, redirecting R&D toward waterborne and high-solids alternatives. China's MEE enforces GB standards for buried steel pipeline corrosion protection that align with international NACE SP0169 practices. ISO 21809 provides the unified testing framework that governs qualification protocols across export markets. Stakeholders must monitor how carbon border adjustment mechanisms and evolving methane accounting rules reshape coating specification priorities in cross-border pipeline projects.
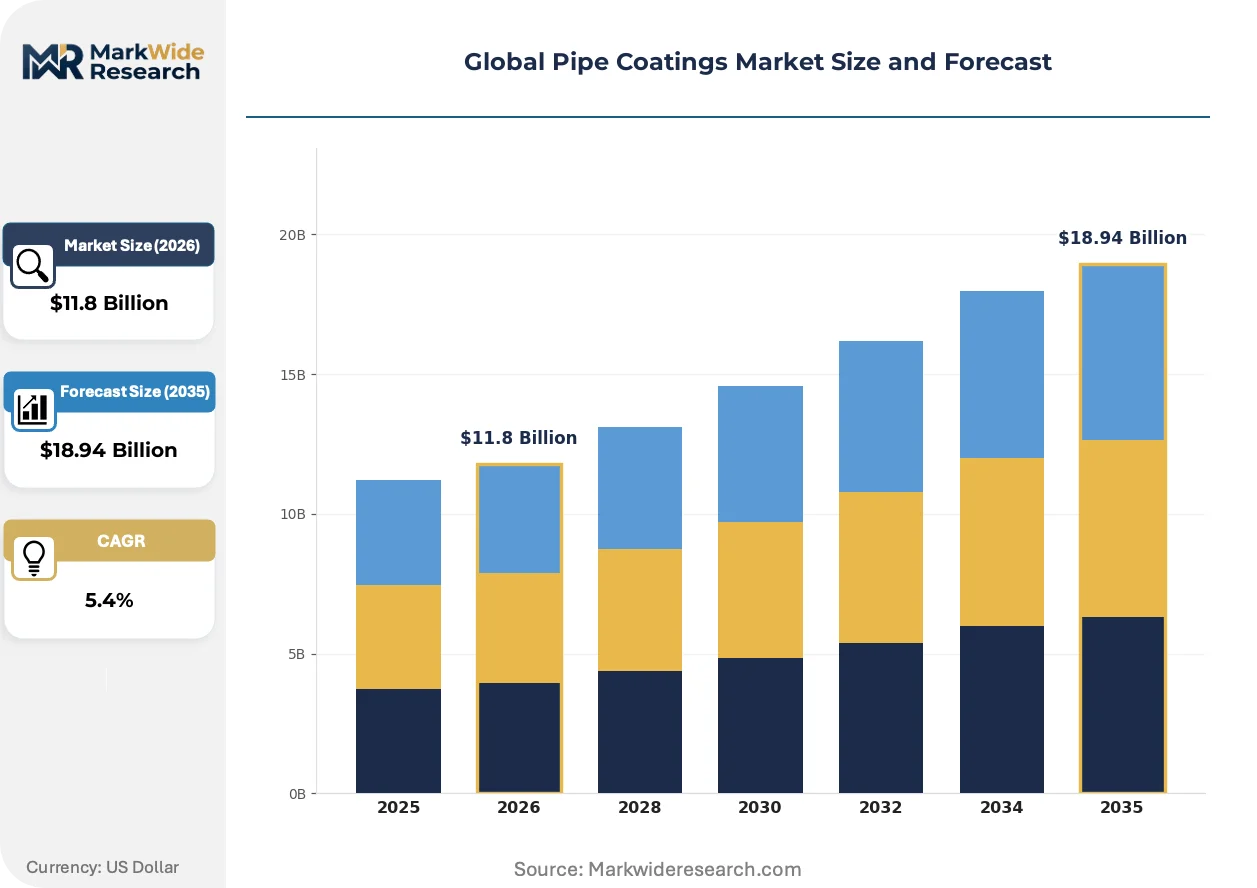
Market Dynamics
Integrity management mandates from the US EPA are compressing coating specification cycles while offshore operators in Brazil and West Africa demand simultaneous cathodic protection and fusion bonded epoxy performance. This dual-pressure environment favors suppliers with integrated resin production and marine-grade certification capabilities.
Growth Catalysts
- EPA Methane Rules:Updated 49 CFR Part 192 and 195 requirements are forcing pipeline operators to accelerate recoating schedules on buried transmission infrastructure, expanding addressable demand for high-performance epoxy systems.
- Shale Gas Development:China's Sichuan province shale zones require extensive gathering line networks, concentrating demand for corrosion-resistant coatings in high-pressure, high-temperature downhole conditions.
- Fusion Bonded Epoxy:Offshore projects in the Caspian and North Sea specify factory-applied FBE for cathodic disbondment resistance below 10 mm², pulling capacity investments toward pipe mill-adjacent coating facilities.
Market Restraints
- Petrochemical Volatility:Epoxy resin prices fluctuate with benzene and propylene feedstock cycles, compressing margin stability for coating formulators without captive raw material supply.
- REACH Solvent Restrictions:ECHA limitations on solvent-based formulations force reformulation investments, extending R&D timelines for polyurethane insulation coatings used in subsea applications.
- Concrete Substrate Substitution:Water distribution utilities in water-stressed regions increasingly specify trenchless polyethylene liners over full steel pipe replacement, constraining growth in traditional steel coating volumes.
Strategic Opportunities
- Hydrogen Pipeline Adaptation:Emerging hydrogen transport infrastructure requires coatings compatible with embrittlement risks and permeation barriers, creating specification white space ahead of codified standards.
- Carbon Border Adjustments:EU CBAM implementation is redirecting coating procurement toward low-carbon epoxy production pathways, rewarding suppliers with verified Scope 3 emissions data.
- Trenchless Rehabilitation:Flexible polyethylene slip-lining systems for aging municipal water networks represent the fastest-expanding application category as utilities prioritize capital efficiency over full pipe replacement.
Industry Challenges
- ISO 21809 Qualification Bottlenecks:Unified testing protocols for export markets require extensive third-party validation, extending time-to-revenue for new coating formulations by 12-18 months.
- Cathodic Protection Integration:Coating suppliers must coordinate performance specifications with CP system designers across divergent national standards, complicating project execution in cross-border pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pipe Coatings Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Epoxy, Polyethylene, Asphalt, Fusion Bonded Epoxy, Polyurethane, Zinc Application: Oil & Gas Transmission, Water Distribution, Sewage Treatment, Electrical Conduit Protection, HVAC Systems, Marine Lines Installation Method: Field Applied, Factory Applied, Electrostatic Spray, Hot Spray, Dipping, Roll Coating End User Industry: Energy Extraction, Municipal Infrastructure, Chemical Processing, Construction Sector, Power Generation, Transportation |
| Companies Covered | PPG Industries, Inc., Akzo Nobel N.V., The Sherwin-Williams Company, BASF SE, Axalta Coating Systems, 3M, Shawcor, Jotun, Arkema Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pipe Coatings Market Shifts & Advancements
Coating formulation chemistry is pivoting toward waterborne and high-solids alternatives as regulatory pressure compounds with end-user sustainability commitments. Three interconnected developments are restructuring competitive positioning.
High-solids epoxy formulations are eliminating solvent-based alternatives in marine and offshore specifications. Brazilian pre-salt operators and North Sea platform contractors now mandate coatings above 80% volume solids to satisfy both REACH restrictions and internal carbon reduction targets. This shift is rendering obsolete traditional low-solids spray applications that dominated maintenance coating contracts through 2020.
EU F-Gas Regulation phase-down schedules are constraining blowing agents in polyurethane insulation systems used for deepwater flowlines. ECHA restrictions on hydrofluorocarbons are forcing reformulation toward hydrocarbon or water-blown alternatives, with qualification testing concentrated in Norwegian and UK North Sea projects where thermal insulation performance is non-negotiable.
Long-term offtake agreements are consolidating buyer power among integrated oil companies and national oil companies. Procurement teams at Petrobras and major Middle East NOCs now bundle coating specifications into multi-year EPC contracts, squeezing spot-market suppliers and favoring formulators with balance sheet capacity to underwrite performance guarantees across decade-long service intervals.
Global Pipe Coatings Market Segmentation
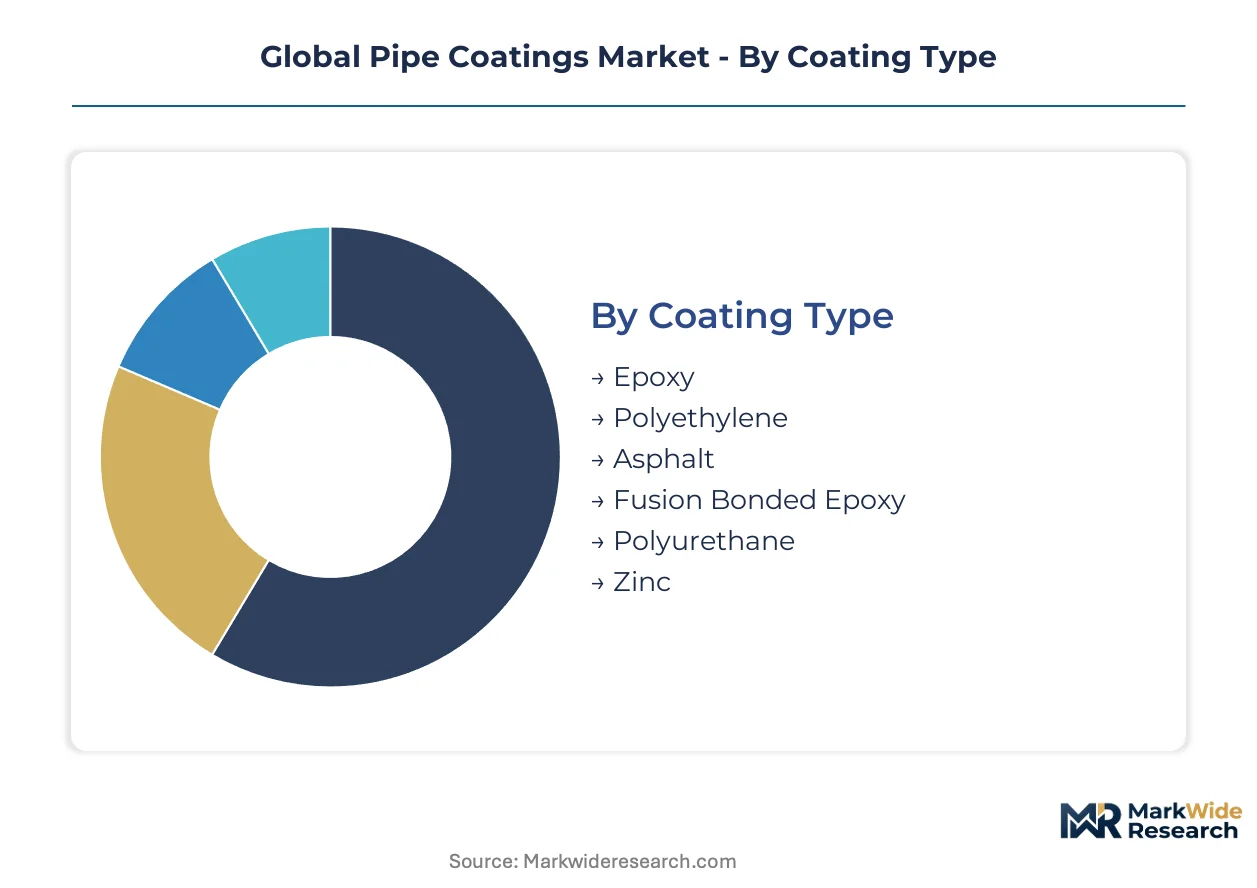
Coating specification in pipeline infrastructure splits across four distinct dimensions: material chemistry, service environment, application technique, and end-use sector. Each dimension carries different margin profiles, qualification barriers, and regional concentration patterns that reshape supplier positioning.
Coating Type:
Material chemistry determines cure temperature, film thickness, and service life in specific corrosion regimes.
- Epoxy:Thermoset formulations cure at ambient to elevated temperatures, delivering chemical resistance against hydrocarbons and aqueous solutions. Demand concentrates in US Gulf Coast petrochemical corridors where 49 CFR Part 192 mandates specific performance standards for natural gas transmission.
- Polyethylene:Thermoplastic barrier systems provide flexible, trenchless rehabilitation solutions for aging municipal networks. Sichuan province shale gas development zones and water-stressed Middle Eastern utilities are rotating procurement toward slip-lining applications over full pipe replacement.
- Asphalt:Bituminous coatings deliver cost-effective moisture barriers for below-ground electrical conduit and secondary containment.
- Fusion Bonded Epoxy:Factory-applied systems cure at 230-250°C to achieve cathodic disbondment resistance below 10 mm². Brazilian pre-salt and North Sea offshore operators specify FBE for combined cathodic protection compatibility.
- Polyurethane:Insulation-grade formulations face REACH solvent restrictions, forcing reformulation toward high-solids alternatives for subsea flowlines.
- Zinc:Sacrificial metallic coatings provide galvanic protection for atmospheric and immersion service in marine environments.
Fusion bonded epoxy holds installed capacity. Polyethylene is rotating up the share rankings.
Application:
Service environment dictates film thickness requirements, thermal cycling tolerance, and regulatory qualification protocols.
- Oil & Gas Transmission:High-pressure steel pipelines require 250-500 micron dry-film thicknesses with decades of service life. EPA methane emission rules under 49 CFR Part 195 are compressing recoating schedules on buried hazardous liquid infrastructure.
- Water Distribution:Municipal networks prioritize flexible rehabilitation over replacement. Trenchless polyethylene liners are gaining share fastest in water-stressed regions facing capital efficiency constraints.
- Sewage Treatment:Concrete and steel substrates in anaerobic environments require chemical-resistant barriers against hydrogen sulfide attack.
- Electrical Conduit Protection:Below-ground cable enclosures specify moisture barriers and mechanical damage resistance.
- HVAC Systems:Insulated piping networks in commercial and industrial buildings demand thermal efficiency and condensation control.
- Marine Lines:Splash zone and subsea pipelines require cathodic protection integration and marine-grade certification under ISO 21809.
Oil & gas transmission maintains the largest installed base. Water distribution is climbing the fastest in new contract volumes.
Installation Method:
Application technique separates field-service margins from factory-scale efficiency.
- Field Applied:Spray and brush applications dominate maintenance recoating on in-service pipelines. US EPA integrity management mandates are accelerating demand for high-solids epoxies that cure under ambient conditions.
- Factory Applied:Automated lines at pipe mill facilities achieve consistent film thickness and cure control. Capacity concentrates near US and Middle East steel production centers.
- Electrostatic Spray:Charged particle deposition delivers uniform coverage on complex geometries for fusion bonded epoxy specifications.
- Hot Spray:Heated plural-component systems enable high-build application in cold-weather field conditions.
- Dipping:Immersion coating suits small-diameter fittings and threaded connections with complete surface coverage.
- Roll Coating:Continuous film application for flat stock and large-diameter pipe exteriors in factory settings.
Factory applied commands the efficiency premium. Field applied is expanding most quickly on maintenance schedules.
End User Industry:
Customer type determines contract structure, from spot maintenance to multi-decade performance guarantees.
- Energy Extraction:Upstream and midstream operators bundle coating specifications into long-term offtake agreements. Petrobras and Middle East NOCs now require decade-long service warranties that favor suppliers with balance sheet capacity.
- Municipal Infrastructure:Water utilities prioritize capital efficiency over full replacement. Trenchless rehabilitation contracts are displacing traditional steel coating volumes in aging network districts.
- Chemical Processing:Aggressive service environments specify high-performance epoxies and fluoropolymer topcoats for process piping.
- Construction Sector:Commercial and residential building codes drive demand for fire-resistant and potable water-certified coatings.
- Power Generation:Cooling water systems and flue gas desulfurization ducts require chemical and thermal resistance.
- Transportation:Pipeline networks for refined products and LNG distribution specify integrity management compliance.
Energy extraction holds the deepest contract backlog. Municipal infrastructure is ascending fastest in specification activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated oil companies and national oil companies concentrate procurement power in Brazil, the United States, China, and Saudi Arabia, where long-term offtake agreements bundle coating specifications into multi-year EPC contracts.
United States
Gulf Coast petrochemical corridor operators demand factory-applied fusion bonded epoxy for new transmission infrastructure. EPA methane emission rules under 49 CFR Part 192 and 195 compress recoating schedules on buried pipelines in Texas and Louisiana. Houston-area coating facilities serve pipe mills supplying Permian Basin gathering networks.
Brazil
Pre-salt offshore operators specify cathodic protection alongside fusion bonded epoxy for subsea flowlines. ANVISA and environmental licensing processes align with international NACE standards for deepwater projects. Rio de Janeiro and Espírito Santo state clusters concentrate marine-grade coating procurement for Petrobras-led developments.
China
Sichuan province shale gas zones require corrosion-resistant coatings for high-pressure gathering lines in mountainous terrain. MEE enforces GB standards for buried steel pipeline protection that mirror ISO 21809 testing protocols. Chengdu and Chongqing industrial corridors anchor domestic coating formulation capacity for western development.
Germany
REACH solvent restrictions redirect polyurethane insulation R&D toward waterborne alternatives for chemical processing infrastructure. ECHA limitations on hydrofluorocarbon blowing agents force reformulation of subsea thermal insulation systems. North Rhine-Westphalia chemical clusters drive specification demand for high-solids epoxy systems.
Saudi Arabia
National oil company procurement bundles coating warranties into decade-long service agreements for desert transmission infrastructure. Domestic content requirements under Vision 2030 incentivize local production of fusion bonded epoxy formulations. Eastern Province industrial cities concentrate pipe mill and coating facility co-location investments.
Global Pipe Coatings Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Vertically integrated resin producers capture margin stability through captive feedstock supply, while marine-grade certification specialists dominate offshore qualification protocols. The competitive terrain rewards balance sheet capacity to underwrite long-term performance guarantees and pipe mill-adjacent factory application infrastructure.
Within the integrated chemical producer tier, BASF SE and Arkema Group exemplify European-based formulators with upstream control over specialty resin supply. PPG Industries anchors the North American channel-control position through factory-applied capacity positioned near US steel production centers. Akzo Nobel N.V. occupies the marine-grade specialist archetype with polyurethane systems dominating North Sea and Caspian offshore specifications.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| Akzo Nobel N.V. |
| The Sherwin-Williams Company |
| BASF SE |
| Axalta Coating Systems |
| 3M |
| Shawcor |
| Jotun |
| Arkema Group |
| Others |
Supply & Pricing Matrix
Houston-Rotterdam freight corridors carry epoxy resin feedstocks that concentrate pricing power among Gulf Coast formulators with captive benzene supply, while downstream buyers face tiered cost structures tied to ISO 21809 qualification tiers and cathodic protection bundling requirements.
Pricing Analysis
Cost-plus contracts indexed to benzene and propylene benchmarks dominate long-term offtake agreements between pipe mill operators and fusion bonded epoxy suppliers. Price differentiation rests on ISO 21809 certification grade and factory-applied versus field-applied service models. Cost compression in standard-grade epoxy formulations is intensifying because REACH-compliant high-solids alternatives require reformulation investments. Municipal water utilities exhibit the highest price sensitivity due to capital efficiency mandates, while Petrobras and Middle East NOCs prioritize performance guarantees over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates raw material sourcing strategies for specialty resin producers. Supply concentrates in the United States, Germany, and China, with epoxy formulation capacity anchored in Gulf Coast petrochemical clusters. The supply chain draws from benzene derivatives, propylene oxide, and amine curing agents as critical inputs. Single-source vulnerability persists in marine-grade polyurethane systems qualified for North Sea subsea specifications. Distribution runs through pipe mill-adjacent coating facilities and regional distribution centers serving maintenance contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-term offtake agreements are transforming pipe coatings procurement into platform economics where certification interoperability and decade-long performance warranties determine supplier survival, mirroring the shift toward bundled EPC contracting in offshore developments.
For Market Incumbents: Build regulatory moats through accelerated ISO 21809 qualification pipelines and captive resin production capacity. PPG Industries and Akzo Nobel should expand factory-applied fusion bonded epoxy capacity near Permian Basin pipe mills to defend against spot-market competitors. Integrating cathodic protection system design capabilities creates switching costs for Petrobras and Middle East NOC procurement teams. For New Entrants and Emerging Players: Build out trenchless polyethylene rehabilitation service capabilities in water-stressed US municipalities and Sichuan province shale zones where capital efficiency priorities favor slip-lining over steel replacement. Hydrogen pipeline coating specifications represent the most penetrable white space ahead of codified embrittlement standards. Partner with regional EPC contractors to bypass direct qualification bottlenecks. For Investors and Strategic Acquirers: Marine-grade certification specialists with Norwegian and UK North Sea project track records command scarcity premiums as EU F-Gas Regulation phase-downs constrain qualified supplier pools. Balance sheet capacity to underwrite decade-long performance guarantees serves as the primary viability filter across the investment horizon. Watch for hydrogen infrastructure pilot project announcements as inflection indicators for specification standardization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin Production | Captive benzene supply insulates PPG Industries and BASF from petrochemical volatility cycles. |
| ISO 21809 Qualification Acceleration | Third-party validation compression reduces time-to-revenue for fusion bonded epoxy formulations. |
| Hydrogen Compatibility R&D Investment | Embrittlement-resistant coating development positions suppliers ahead of infrastructure buildouts. |
| Factory-Applied Capacity Expansion | Pipe mill-adjacent facilities capture efficiency premiums from automated fusion bonded epoxy lines. |
| Trenchless Rehabilitation Service Buildout | Polyethylene slip-lining capabilities address municipal capital efficiency constraints in water-stressed regions. |
Research Methodology
Desk research of customs trade databases, EPA enforcement records, and ISO 21809 qualification registries preceded structured interviews with coating formulator R&D directors, pipe mill procurement managers, and cathodic protection system designers. Primary fieldwork with Brazilian pre-salt project engineers and Sichuan shale zone EPC contractors validated secondary estimates. Bottom-up volume modeling triangulated against top-down petrochemical consumption data.
Forecast assumptions held regulatory enforcement timelines and benzene-propylene spread relationships fixed while varying shale gas development pace and hydrogen infrastructure commitment levels. Segmentation modeling spanned coating chemistry, application method, end-use sector, and regional production hub intensity. CAGRs were derived from installed base replacement cycles and new pipeline kilometer projections. Industry-specific inputs included cathodic protection bundling rates and REACH reformulation cost curves.
Stress conditions across feedstock price volatility, EPA methane rule enforcement intensity, and EU carbon border adjustment implementation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding qualification timeline compression and offtake agreement structuring. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Polyurethane Powder Coatings Market
Coatings
Powder Coating Booth Market
Coatings
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market
Coatings
Transparent Conductive Coatings Market
Coatings
Asia-Pacific Floor Coatings Market
Coatings
Polyester Coatings Market
Coatings
Mold Release Coatings Market
Coatings
Germany Protective Coatings Market
Coatings
Waterborne Automobile Coating Market
Coatings
Hull Coatings Market
Coatings
US Industrial Coatings Market
Coatings
Europe Super Hydrophobic Coatings Market
Coatings
Global Fluorinated Ethylene Propylene (FEP) Coatings Market
Coatings
Polysiloxane Coatings Market
Coatings
Bio-Based Coatings Market
Coatings
Textile Coatings Market