
 Europe Outdoor Furniture Market | 2026-2036
Europe Outdoor Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Outdoor Furniture Market Analysis
Market Context
Multi-source resin procurement is pivoting toward captive polymer recycling as virgin plastic costs fluctuate. Kettal leverages Mediterranean craft partnerships to sustain design differentiation in premium lounge collections. IKEA anchors volume positioning through flat-pack logistics and circular material take-back programs. Fermob competes via powder-coated steel specialization that extends product lifespan against coastal corrosion.
Technical Definition and Segment Structure
Europe outdoor furniture comprises weather-resistant seating, tables, shade systems, and storage designed for exterior residential, hospitality, and commercial environments, typically employing thermally modified hardwoods, die-cast aluminum, or UV-stabilized polyethylene rattan woven over powder-coated steel frames. Metal and wood material categories command established margin pools due to durability premiums and repairability credentials, while plastic segments face margin compression from recyclate quality inconsistency. Distribution through specialty stores and home improvement channels dominates volume, though online retail captures growing replacement-cycle purchases as consumers prioritize delivery convenience over tactile material assessment.
Regulatory Frame and Outlook
REACH chemical restrictions and EU Green Deal carbon-border adjustments constrain coating chemistries and tropical hardwood sourcing, while ECHA substance evaluations pressure preservative treatments in timber segments. The F-Gas Regulation indirectly shapes demand by accelerating outdoor heat-pump adoption that reconfigures terrace spatial planning. Stakeholders must monitor evolving ecodesign criteria and digital product passport requirements that will determine market access and material specification compliance.
Market Dynamics
EU Green Deal carbon-border adjustments and REACH chemical restrictions are compressing coating chemistries and tropical hardwood sourcing, forcing manufacturers toward recycled aluminum and FSC-certified timber supply chains.
Growth Catalysts
- Al fresco dining expansion:Hospitality operators across Germany, France, and Italy are expanding terrace investments. Coastal municipalities in Spain and Portugal are streamlining outdoor seating permits.
- F-Gas Regulation:The regulation accelerates outdoor heat-pump adoption that reconfigures terrace spatial planning. This creates demand for modular furniture systems.
- Captive polymer recycling:Virgin plastic cost volatility pushes manufacturers toward multi-source resin procurement. Recycled polyethylene rattan production is scaling in Mediterranean craft clusters.
Market Restraints
- Recyclate quality inconsistency:Plastic segments face margin compression from batch-to-batch material variation. UV-stabilization performance degrades with mixed polymer feedstocks.
- ECHA substance evaluations:Preservative treatments in timber segments face regulatory friction. Thermally modified hardwood certification timelines extend by 8-14 months.
- Aluminum alloy supply concentration:Die-cast frame production depends on smelter capacity in Norway and Iceland. Energy price spikes transmit directly to frame costs.
Strategic Opportunities
- Alpine resort municipalities:Underpenetrated premium lodging in Austria and Switzerland demands weather-resistant lounge systems. Ski-to-terrace hospitality concepts require specialized product development.
- Digital product passports:Ecodesign criteria will mandate material traceability. First-movers capturing blockchain-verified supply chain data secure retail shelf access.
- Flat-pack logistics convergence:Circular material take-back programs meet consumer delivery convenience expectations. Direct-to-consumer channels capture replacement-cycle purchases.
Industry Challenges
- Powder-coating technician scarcity:Coastal corrosion-resistant finishing requires specialized application skills. Vocational training pipelines in Portugal and Turkey lag demand.
- Legacy distribution integration:Specialty stores resist online retail platform onboarding. Inventory synchronization between physical showrooms and digital channels creates working capital strain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Outdoor Furniture Market |
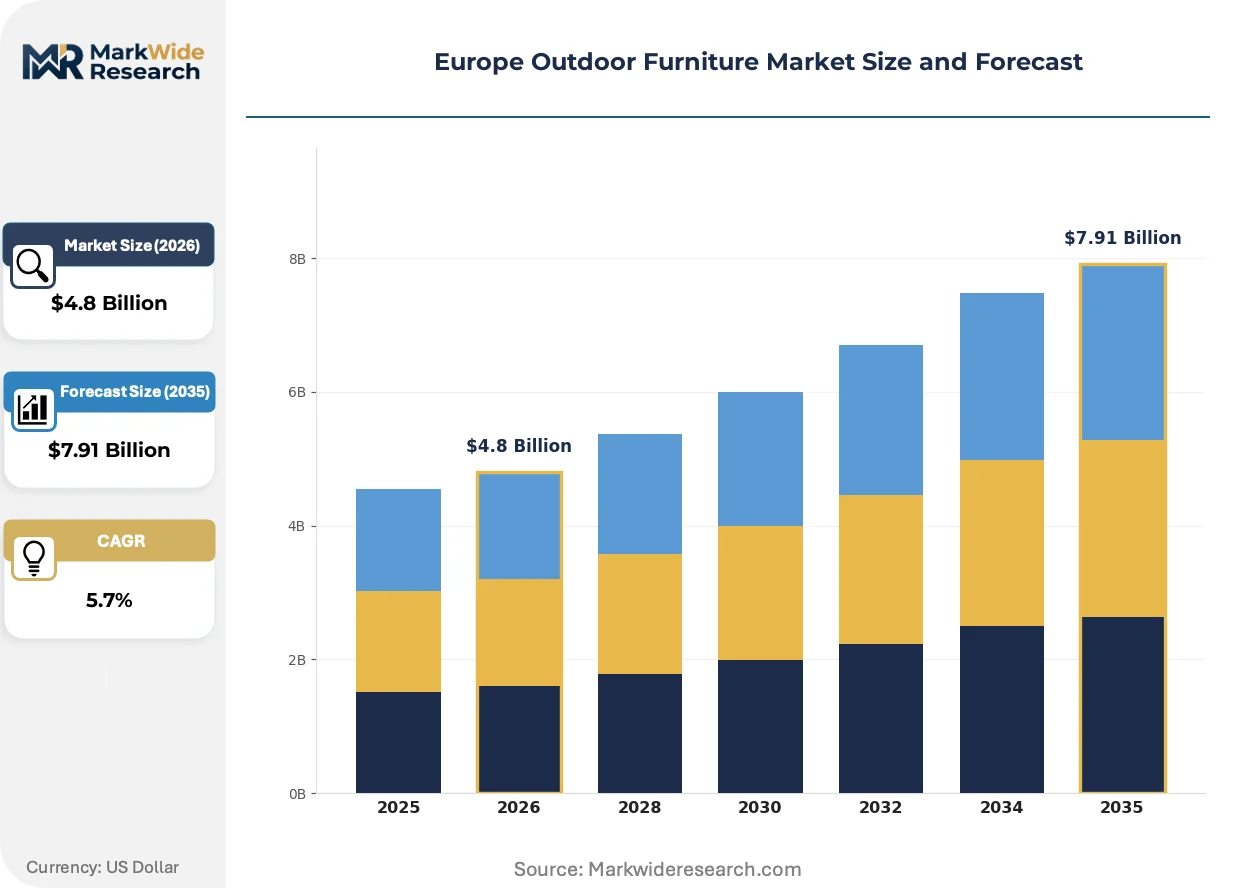
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wood, Metal, Plastic, Wicker Product Type: Tables, Chairs, Lounge Sets, Umbrellas Distribution Channel: Online Retail, Specialty Stores, Home Improvement, Direct Sales End User: Residential, Commercial, Hospitality, Garden Centers |
| Companies Covered | IKEA, Fermob, Kettal, Keter Group, Hartman Outdoor Products, Gloster Furniture, EMU Group, Dedon, Royal Botania, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Outdoor Furniture Market Emerging Trajectories
Automation in material processing and regulatory-driven material substitution are compressing traditional manufacturing economics. Design differentiation now depends on craft partnerships and circular logistics rather than virgin material specifications.
Thermally modified hardwood treatment is automating kiln-control precision that standardizes dimensional stability across batch production. Alpine furniture manufacturers in Austria and Bavaria are adopting sensor-driven curing protocols at scale. This is automating quality variance reduction that previously required manual grading and selective sourcing.
REACH chemical restrictions are banning chromated copper arsenate preservatives from tropical hardwood applications. ECHA substance evaluations now cover boron-based alternatives, compressing treatment options for teak and iroko imports. Mediterranean coastal manufacturers are pivoting toward thermally modified domestic ash and oak to maintain market access.
Replacement-cycle purchasing is compressing traditional seasonal buying patterns. German and Dutch consumers now order outdoor seating in February-March delivery windows rather than May-June showroom visits. Online retail platforms capture this demand rotation through augmented-reality material visualization that substitutes for tactile assessment.
Europe Outdoor Furniture Market Segmentation
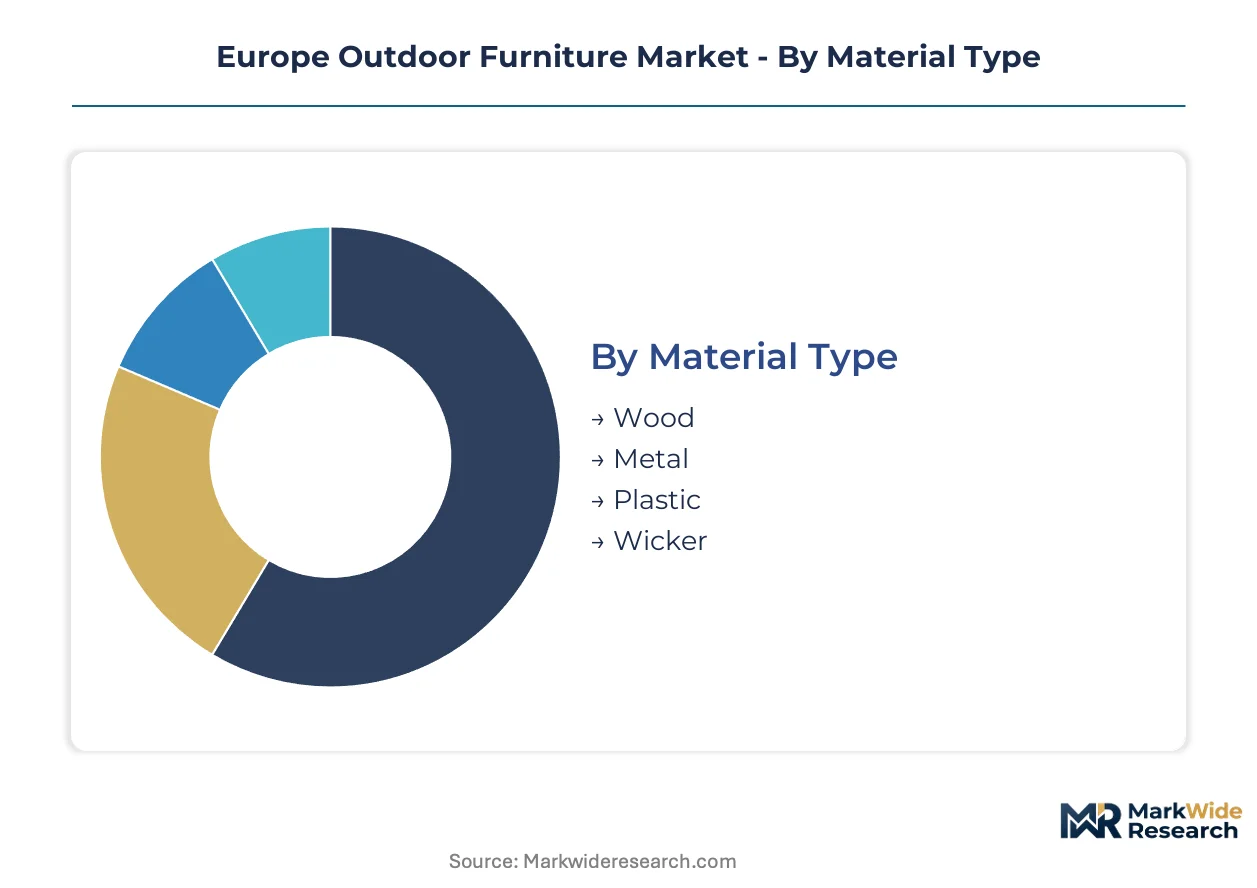
Material specifications and distribution logistics determine margin capture across European outdoor furniture. Segmentation reveals where REACH compliance costs concentrate and which channels capture replacement-cycle purchasing shifts.
Material Type:
Thermal modification chemistry and alloy composition define durability credentials against coastal corrosion and alpine UV exposure.
- Wood:Thermally modified ash and oak from Austrian and Bavarian kilns replace tropical hardwoods facing ECHA preservative restrictions. Alpine resort municipalities specify domestic timber for ski-to-terrace hospitality concepts requiring dimensional stability across freeze-thaw cycles.
- Metal:Die-cast aluminum frames with powder-coated finishes dominate premium lounge collections. Norway and Iceland smelter capacity concentration transmits energy price volatility directly to frame production economics.
- Plastic:UV-stabilized polyethylene rattan from Mediterranean craft clusters scales through captive polymer recycling. Batch-to-batch recyclate quality inconsistency compresses margins versus virgin resin alternatives.
- Wicker:Natural fiber variants from Portuguese and Turkish weaving cooperatives sustain design differentiation in terrace dining segments. Vocational training pipeline gaps constrain corrosion-resistant finishing technician supply.
Metal leads on scale; wood leads on momentum as thermal modification automates quality standardization.
Product Type:
Application intensity and replacement frequency separate commercial-grade specifications from residential convenience priorities.
- Tables:Modular systems with integrated heating accommodation capture F-Gas Regulation-driven terrace reconfiguration demand. German and French hospitality operators specify expandable configurations for al fresco dining capacity management.
- Chairs:Stackable steel and aluminum frames dominate volume through flat-pack logistics efficiency. Online retail platforms capture February-March delivery window demand rotation from traditional May-June showroom purchasing.
- Lounge Sets:Premium collections leverage Mediterranean craft partnerships for design differentiation. Coastal corrosion resistance requires specialized powder-coating application skills concentrated in Portugal and Turkey.
- Umbrellas:Shade systems integrate with modular furniture configurations for spatial planning flexibility. Spanish and Portuguese coastal municipalities streamline outdoor seating permits that specify integrated shade requirements.
Chairs dominate volume throughput; lounge sets command margin expansion through craft premiumization.
Distribution Channel:
Inventory synchronization requirements and consumer convenience expectations separate channel economics.
- Online Retail:Augmented-reality material visualization substitutes for tactile assessment in replacement-cycle purchasing. Direct-to-consumer channels capture circular material take-back program participation.
- Specialty Stores:Physical showrooms resist digital platform onboarding due to working capital strain from inventory synchronization requirements. Tactile material assessment remains decisive for premium thermally modified hardwood selection.
- Home Improvement:Volume positioning through flat-pack logistics anchors mass-market penetration. IKEA's circular material take-back programs meet delivery convenience expectations.
- Direct Sales:Hospitality procurement contracts specify custom modular configurations for terrace spatial planning. Alpine resort municipalities in Austria and Switzerland demand specialized weather-resistant lounge system development.
Specialty stores retain premium positioning; online retail gains share fastest through convenience capture.
End User:
Procurement scale and specification complexity separate institutional buyers from individual consumers.
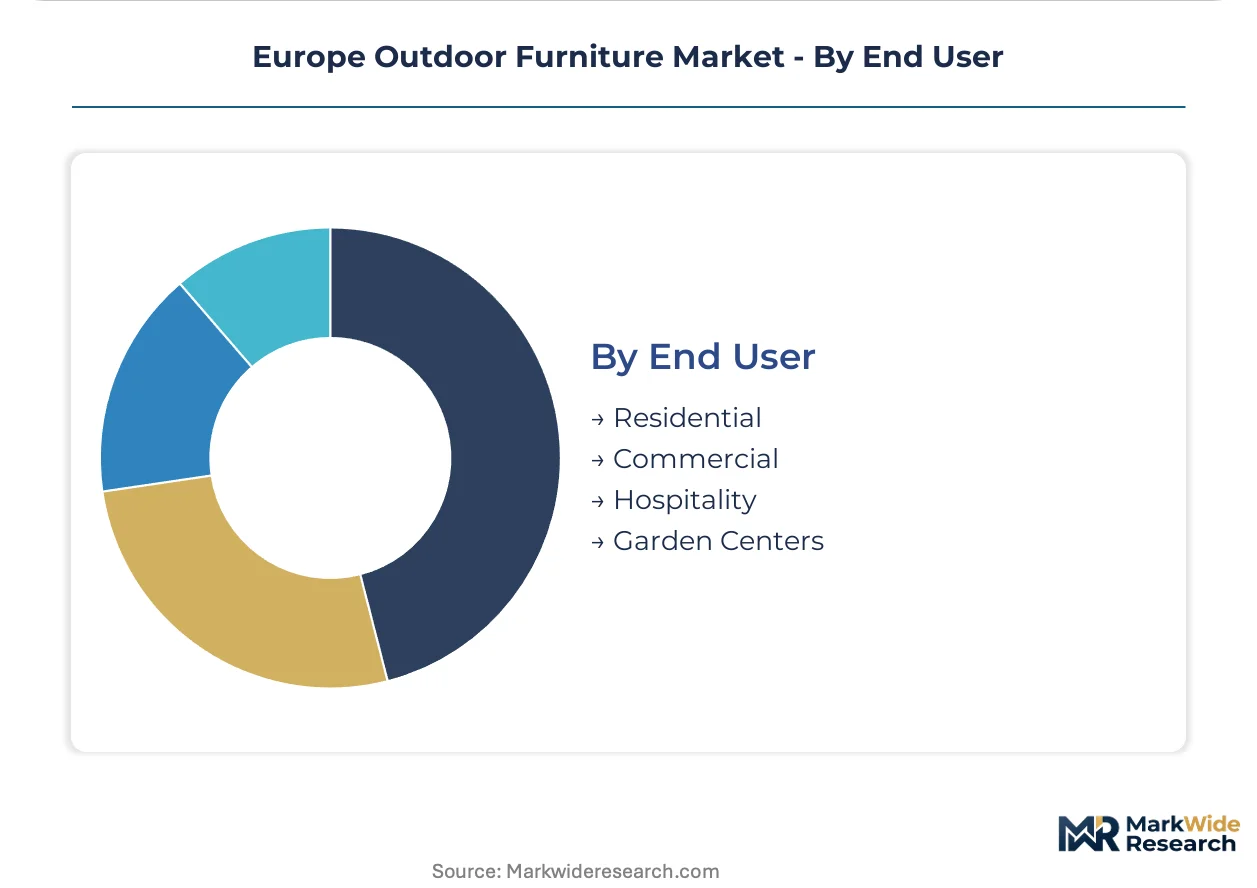
- Residential:German and Dutch consumers advance February-March delivery expectations that compress traditional seasonal buying patterns. Augmented-reality tools reduce showroom dependency for material assessment.
- Commercial:Corporate terrace investments specify modular systems for flexible spatial reconfiguration. F-Gas Regulation heat-pump adoption drives outdoor heating integration requirements.
- Hospitality:Ski-to-terrace concepts in Alpine municipalities demand specialized weather-resistant lounge systems. Al fresco dining expansion across Germany, France, and Italy concentrates terrace investment.
- Garden Centers:Seasonal inventory cycles align with traditional May-June purchasing peaks. Working capital constraints limit online platform integration for multi-channel synchronization.
Hospitality drives specification innovation; residential expands most quickly through channel convenience rotation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers relocate thermally modified hardwood processing to Austria and Bavaria to circumvent ECHA preservative restrictions on tropical imports. Compliance cost gaps between Mediterranean craft clusters and Nordic smelter-dependent metal fabricators are widening margin dispersion across the continent.
Germany
Al fresco dining investments by hospitality operators in Berlin and Munich are driving terrace furniture specifications. REACH chemical restrictions constrain coating chemistries for powder-coated steel frames produced in North Rhine-Westphalia. The Bavarian kiln clusters around Rosenheim are automating thermal modification protocols for domestic ash and oak exports.
France
Parisian hospitality groups are expanding modular terrace configurations ahead of F-Gas Regulation heat-pump adoption timelines. EU Green Deal carbon-border adjustments pressure Lyon-based metal fabricators toward recycled aluminum sourcing. The Provence craft cooperatives around Marseille sustain powder-coating specialization for coastal corrosion resistance.
Italy
Milanese design houses are contracting Mediterranean rattan weaving partnerships for premium lounge collections. ECHA substance evaluations extend certification timelines for thermally modified hardwood imports through Trieste port logistics. The Alpine resort municipalities in South Tyrol are specifying ski-to-terrace weather-resistant systems from domestic manufacturers.
Spain
Barcelona and Valencia coastal municipalities are streamlining outdoor seating permits for hospitality terrace expansion. REACH restrictions on chromated copper arsenate preservatives redirect sourcing toward thermally modified European timber. The Alicante polymer recycling clusters are scaling UV-stabilized polyethylene rattan production from captive resin feedstocks.
Netherlands
Amsterdam and Rotterdam consumers are advancing February-March delivery expectations that compress traditional seasonal purchasing patterns. Ecodesign criteria for digital product passports pressure inventory traceability systems at Utrecht distribution hubs. The flat-pack logistics specialists around Eindhoven are integrating circular material take-back programs with direct-to-consumer channels.
Europe Outdoor Furniture Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue circular logistics and craft premiumization as differentiation vectors. The vendor base stratifies across three maturity tiers: mass-market flat-pack specialists, mid-scale metal and timber fabricators, and boutique design houses leveraging Mediterranean craft partnerships. Three strategic archetypes dominate: scale-driven logistics optimizers, compliance-first material specialists, and design-led craft integrators. Capacity expansion and portfolio diversification toward modular terrace systems represent the dominant competitive moves as F-Gas Regulation reconfigures spatial planning requirements.
Among Nordic-origin flat-pack logistics anchors, IKEA exemplifies scale-driven circular material take-back integration. Within the powder-coated steel specialization tier, Fermob occupies a position representing coastal corrosion-resistant finishing expertise. On the Mediterranean craft partnership vector, Kettal represents design differentiation through regional weaving cooperatives and thermal modification sourcing relationships.
| Leading Market Players |
|---|
| IKEA |
| Fermob |
| Kettal |
| Keter Group |
| Hartman Outdoor Products |
| Gloster Furniture |
| EMU Group |
| Dedon |
| Royal Botania |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon-border adjustments gate qualified supply and premium-tier pricing access by imposing compliance costs that only certified manufacturers can absorb. REACH chemical restrictions and F-Gas Regulation timelines concentrate pricing power among producers with verified recycled aluminum and FSC-certified timber sourcing, while marginal players face exclusion from hospitality procurement contracts.
Pricing Analysis
Input-cost pass-through from Norwegian and Icelandic smelter energy price volatility transmits directly to die-cast aluminum frame pricing. Three-tier pricing structure across premium, standard, and economy levels separates powder-coated steel lounge collections from flat-pack chair volumes and plastic segment alternatives. Cost compression in the plastic segment is intensifying because batch-to-batch recyclate quality inconsistency degrades UV-stabilization performance. Hospitality procurement teams show lowest price sensitivity due to terrace investment durability requirements, while residential replacement-cycle buyers prioritize delivery convenience over material grade.
Supply Chain Analysis
Workforce-availability constraints in Portuguese and Turkish powder-coating technician pools limit corrosion-resistant finishing capacity for coastal-grade metal frames. Supply concentrates in Austria and Bavaria for thermally modified hardwood, Norway and Iceland for primary aluminum, and Mediterranean craft clusters for polyethylene rattan weaving. Raw material dependencies draw from FSC-certified timber feedstocks, die-cast aluminum alloys, and captive polymer recyclate streams. Single-source vulnerability runs through Nordic smelter capacity for premium frame production. Distribution runs through specialty store showrooms for tactile material assessment, online retail for replacement-cycle convenience, and direct sales for hospitality contract specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where F-Gas Regulation heat-pump adoption timelines are restructuring terrace spatial planning and mandating modular furniture system procurement.
For Market Incumbents: To counter margin compression from ECHA substance evaluation delays on tropical hardwood imports, deepen captive supply of thermally modified domestic timber through Austrian and Bavarian kiln partnerships. Secure powder-coating technician pipelines in Portugal and Turkey through vocational training alliances to defend coastal corrosion-resistant finishing capacity against craft labor scarcity. For New Entrants and Emerging Players: Launch via direct-to-consumer online retail platforms with augmented-reality material visualization to capture February-March replacement-cycle purchasing rotation from traditional showroom channels. Target Alpine resort municipalities in Austria and Switzerland with specialized ski-to-terrace weather-resistant lounge systems, exploiting underpenetrated premium lodging demand and direct sales contract accessibility. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale metal and timber fabricators with REACH compliance infrastructure because regulatory barriers protect certified producers from price-based competition. Over the projection horizon, prioritize acquisition targets with established FSC certification and thermal modification kiln automation. Monitor ECHA substance evaluation timelines for thermally modified hardwood as the inflection signal for timber segment supply reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Terrace System Development | F-Gas Regulation heat-pump adoption reconfigures spatial planning requirements for hospitality operators. |
| Circular Material Take-Back Program | IKEA's flat-pack logistics integration meets EU Green Deal waste reduction mandates and consumer convenience expectations. |
| Thermal Modification Kiln Automation | Austrian and Bavarian manufacturers standardize dimensional stability for ECHA-compliant domestic timber substitution. |
| Mediterranean Craft Partnership Expansion | Kettal leverages regional weaving cooperatives for design differentiation in premium polyethylene rattan collections. |
| Digital Product Passport Implementation | Blockchain-verified supply chain data secures retail shelf access under forthcoming ecodesign criteria mandates. |
Methodological Framework
Coverage spans Germany, France, Italy, Spain, and the Netherlands, with primary inputs from each market cluster combined with secondary validation. Primary interviews engaged hospitality procurement directors, outdoor furniture manufacturing plant managers, specialty store category buyers, thermal modification kiln operators, and powder-coating vocational training coordinators. Secondary sources drew from EU ECHA substance evaluation databases, FSC certification registries, REACH compliance filings, customs trade data on aluminum alloy imports, and hospitality terrace permit filings in Barcelona and Valencia. Bottom-up demand modeling triangulated against top-down macroeconomic indicators.
Rate-of-change decomposition structured the analytical framework across material type, product category, distribution channel, and end-user segment dimensions. CAGRs derived from regression analysis of replacement-cycle purchasing pattern shifts, regulatory compliance cost trajectories, and hospitality investment cycles. Industry-specific forecast inputs incorporated F-Gas Regulation implementation timelines, ECHA evaluation queue projections, and Alpine resort municipality development pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under energy price spike scenarios affecting Nordic smelter economics or accelerated ECHA restrictions on preservative chemistries. Forecasts reflect documented assumptions regarding regulatory timeline adherence and hospitality sector capital expenditure continuity. Material deviation in EU Green Deal carbon-border adjustment implementation or F-Gas Regulation terrace reconfiguration adoption rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
GCC Luxury Furniture Market
Furniture
GCC Smart Furniture Market
Furniture
Bar Stools Market
Furniture
Brazil Furniture Market
Furniture
Asia-Pacific Contract Furniture Market
Furniture
Germany Home Furniture Market
Furniture
Netherlands Home Furniture Market
Furniture
Europe High-End Furniture Market
Furniture
North America High-End Furniture Market
Furniture
North America Furniture Market
Furniture
Fireplace Mantels Market
Furniture
Global Folding Furniture Market
Furniture
Study Carrels Market
Furniture
Upholstered Furniture Market
Furniture
Asia-Pacific Home Furniture Market
Furniture
Italy Luxury Furniture Market