
 Exam Tables Market | 2026-2036
Exam Tables Market Size, Share, and Industry Trends Forecast 2026-2036
Exam Tables Market Foresight
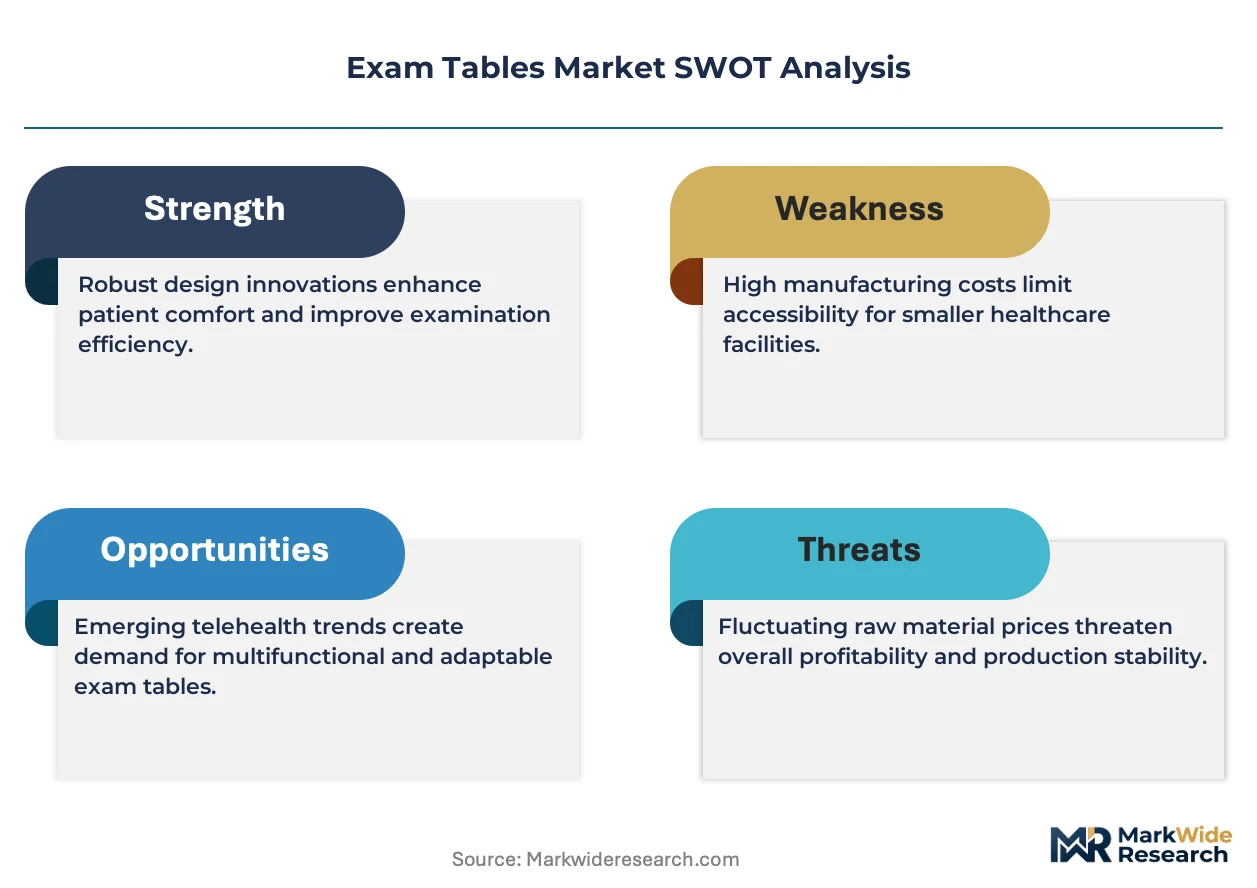
EU MDR is restructuring the cost-of-entry calculus for exam table manufacturers selling into European healthcare systems. Stryker Corporation leverages its established notified body relationships to sustain CE marking compliance across powered table portfolios. Midmark Corporation anchors its competitive stance through domestic manufacturing scale in North American clinic segments. Lemi Group specializes in aesthetic and wellness table configurations that differentiate its catalog from acute-care competitors.
Exam tables are height-adjustable patient support platforms engineered with steel or aluminum frames, powered by electric motors or hydraulic actuators, and surfaced with antimicrobial upholstery rated for clinical cleaning protocols. Electric exam tables command the widest installed base in hospital settings where staff ergonomics and patient transfer safety drive procurement decisions. Folding exam tables occupy the most price-sensitive tier, serving mobile health outreach and temporary clinic deployments where storage density outweighs feature depth.
FDA 510(k) clearance requirements govern powered table introductions in the United States, while ISO 13485 quality management standards shape supplier qualification across OECD procurement channels. EPA antimicrobial coating regulations and state-level OSHA ergonomic mandates further constrain material selection and design specifications for manufacturers targeting multi-jurisdiction contracts. Stakeholders must monitor how tightening energy efficiency standards for medical devices will reshape motor and actuator sourcing decisions across product lines.
Market Dynamics
Powered exam table adoption is accelerating as CMS reimbursement rules tighten documentation requirements for patient positioning equipment in United States outpatient settings. Electric motor systems with integrated scale functionality are displacing manual hydraulic alternatives where staff ergonomics and transfer safety drive capital allocation decisions.
Growth Catalysts
- CMS Documentation Mandates:United States outpatient clinics must demonstrate precise patient positioning records to secure reimbursement, forcing replacement of aging manual tables with powered models that log height and tilt parameters automatically.
- ISO 13485 Procurement Gates:Hospital systems in Germany and Japan now require quality management certification for all new patient-handling devices, filtering out uncertified suppliers and consolidating demand around compliant manufacturers.
- Steel Frame Durability Standards:Antimicrobial upholstery rated for clinical cleaning protocols has become a non-negotiable specification in acute-care procurement, extending replacement cycles and favoring premium construction over folding alternatives.
Market Restraints
- Electric Motor Cost Volatility:Permanent magnet and copper winding prices fluctuate with energy transition demand, compressing margins on mid-range powered tables where price elasticity is highest.
- Notified Body Bottlenecks:EU MDR designation delays for medical device manufacturers have extended CE marking timelines from 6 to 18 months, freezing new product introductions for smaller portfolio holders.
- Mobile Folding Substitution:Temporary clinic deployments and mobile health outreach programs prioritize storage density over feature depth, capping premium table penetration in price-sensitive segments.
Strategic Opportunities
- Aesthetic and Wellness Expansion:Medical spa and cosmetic surgery practices in South Korea and Brazil seek specialized table configurations with enhanced patient comfort features, creating white space distinct from acute-care competitors.
- Energy Efficiency Incentives:Tightening medical device efficiency standards in California and the European Union are reshaping motor and actuator sourcing, rewarding early adopters of low-consumption drive systems.
- Telehealth-Integrated Diagnostics:Tables with embedded scale systems and Bluetooth-enabled data transmission enable remote patient monitoring workflows, opening ambulatory surgery center contracts seeking digital infrastructure compatibility.
Industry Challenges
- FDA 510(k) Submission Backlogs:Premarket notification reviews for powered table modifications now average 180 days, delaying feature upgrades and competitive responses to shifting specifications.
- Legacy Hydraulic Integration:Hospital facilities with mixed equipment fleets face interoperability failures when connecting new electric tables to existing patient lift and transfer systems, requiring costly infrastructure overhauls.
- Antimicrobial Coating Compliance:EPA registration requirements for clinical surface treatments add 12-24 months to material qualification timelines, constraining rapid design iteration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Exam Tables Market |
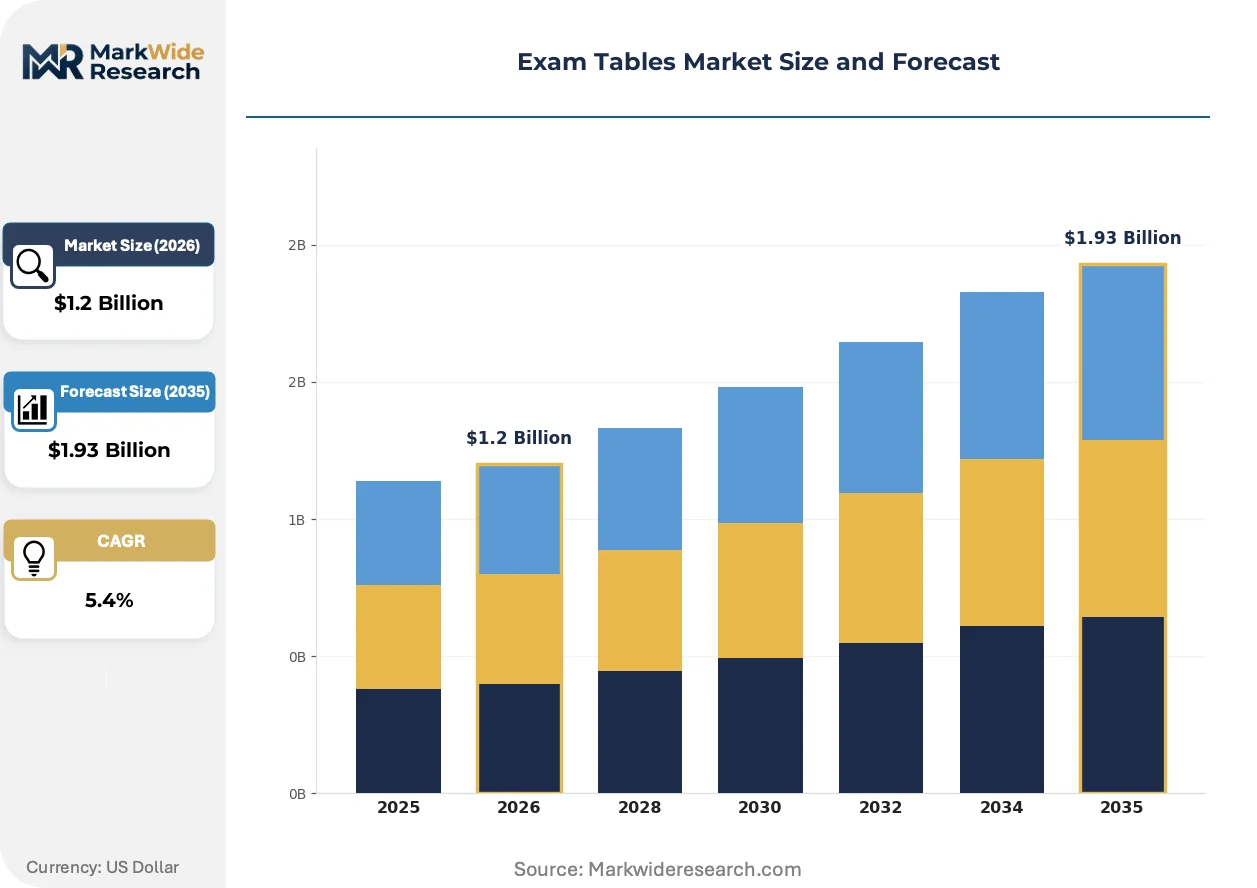
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $1.93 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Exam Tables, Electric Exam Tables, Hydraulic Exam Tables, Folding Exam Tables End User: Hospitals, Clinics, Ambulatory Surgical Centers, Educational Institutions Material: Stainless Steel, Plastic, Wood, Aluminum Features: Adjustable Height, Portable Design, Storage Compartments, Easy-to-Clean Surface |
| Companies Covered | Stryker Corporation, STERIS plc, Midmark Corporation, Getinge AB, Skytron LLC, Cardinal Health, Inc., United Metal Fabricators, Inc., Invacare Corporation, Lemi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Exam Tables Market Shifts & Advancements
Examination table engineering is converging around automated positioning systems, regulatory-driven material compliance, and procurement models that bundle equipment with service contracts. These forces are compressing product lifecycles while elevating certification requirements for market access.
Sensor-integrated electric actuation is automating height, tilt, and Trendelenburg adjustments through programmable presets stored by clinician preference. Outpatient surgery centers in Texas and Florida are deploying these systems to reduce staff injury claims and accelerate room turnover. The technology is automating documentation workflows by transmitting positioning data directly to electronic health records, eliminating manual logging errors.
EU MDR Article 10 technical documentation requirements are mandating clinical evidence for all powered patient-handling devices, including retrospective data on adverse events. Manufacturers must now maintain post-market surveillance systems that track table performance across installed bases, adding 15-20% to regulatory compliance costs. Mid-tier suppliers without established notified body relationships are exiting the European market entirely, consolidating share among entrenched competitors.
Acute-care buyers are consolidating vendor relationships through multi-year equipment leases that bundle preventive maintenance and upholstery replacement. This arrangement displaces traditional capital purchase models in United States health systems facing constrained capital expenditure budgets. The shift is most visible in integrated delivery networks spanning multiple states, where standardization across facilities overrides local procurement autonomy.
Exam Tables Market Segmentation
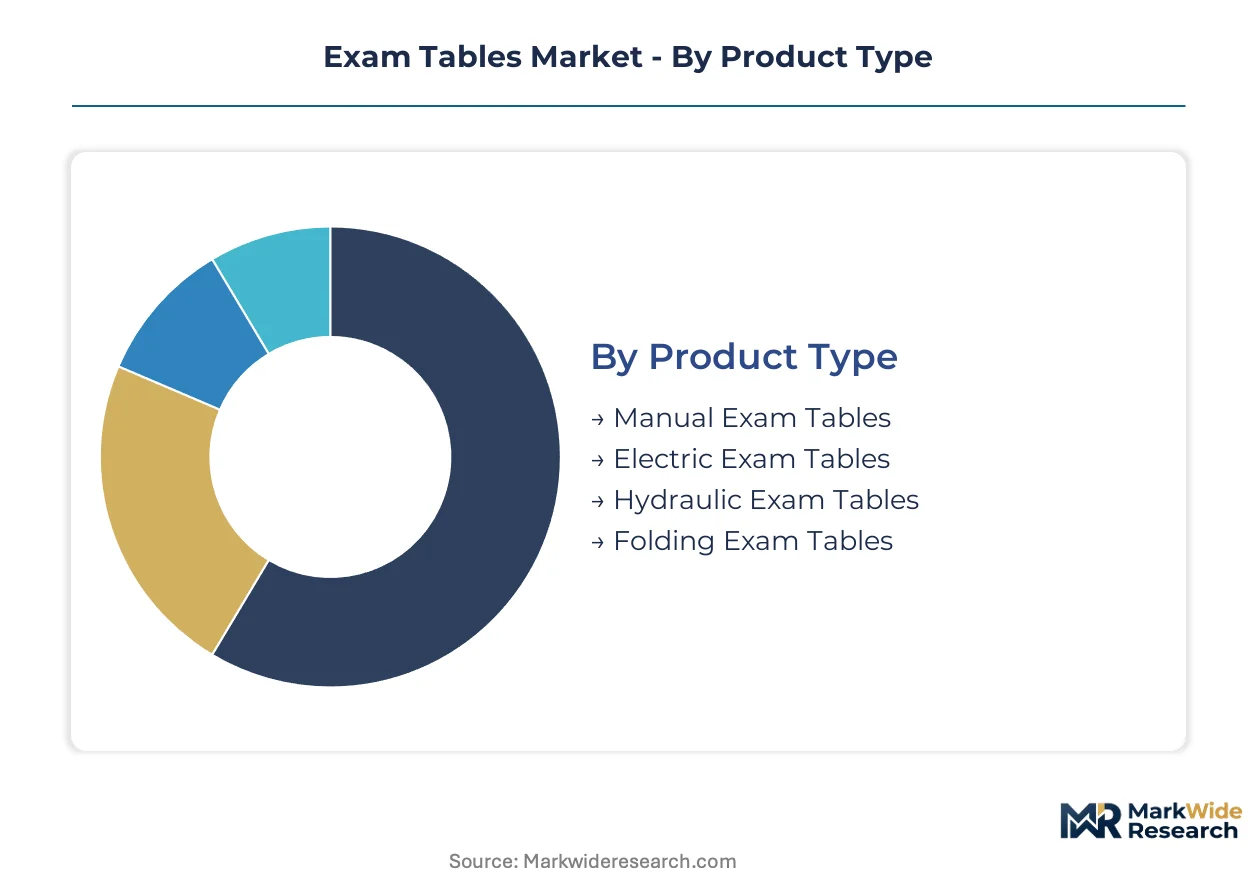
Exam table procurement decisions split across power source preferences, institutional scale requirements, and infection control protocols. Each segmentation dimension reveals distinct buyer priorities that reshape competitive positioning and margin structures across manufacturer portfolios.
Product Type:
Power source selection separates buyers by capital intensity, staff ergonomics priorities, and documentation compliance requirements.
- Manual Exam Tables:Hand-crank or fixed-height steel frames dominate price-sensitive clinic segments and legacy facility upgrades. Demand concentrates in rural United States outpatient settings where CMS documentation mandates have not yet displaced aging installed bases.
- Electric Exam Tables:Motor-driven positioning systems with programmable presets capture preference in hospital settings where OSHA ergonomic mandates and staff injury liability drive capital allocation. German and Japanese procurement channels require ISO 13485 certification for these powered systems, filtering supplier pools.
- Hydraulic Exam Tables:Fluid-actuated height adjustment serves mixed-fleet facilities seeking compatibility with existing patient lift infrastructure.
- Folding Exam Tables:Collapsible aluminum frames prioritize storage density for mobile health outreach and temporary clinic deployments.
Volume sits with Electric Exam Tables; growth tilts toward Folding Exam Tables in emerging telehealth and community health segments.
End User:
Institutional scale and reimbursement exposure determine feature depth requirements and replacement cycle timing.
- Hospitals:Acute-care systems mandate antimicrobial upholstery ratings, integrated scale systems, and Trendelenburg positioning for surgical preparation. United States integrated delivery networks bundle these purchases with multi-year service contracts.
- Clinics:Outpatient facilities face the steepest CMS documentation pressure, accelerating powered table adoption to automate patient positioning logs for reimbursement.
- Ambulatory Surgical Centers:Texas and Florida facilities prioritize room turnover speed through preset positioning programs.
- Educational Institutions:Medical and nursing schools value durability and standardized controls for training consistency.
Revenue concentrates in Hospitals; expansion accelerates most quickly in Ambulatory Surgical Centers seeking digital infrastructure compatibility.
Material:
Surface composition and frame metallurgy trade off between infection control ratings, weight capacity, and total cost of ownership.
- Stainless Steel:Surgical-grade 304 and 316 alloys dominate acute-care procurement where EPA-registered antimicrobial coatings and steam-cleaning compatibility are mandatory. Extended replacement cycles favor premium construction despite higher upfront capital.
- Plastic:Polymer composite surfaces reduce weight for portable and pediatric configurations where frequent repositioning outweighs load-bearing requirements.
- Wood:Laminate finishes persist in wellness and aesthetic medicine segments where patient comfort perception overrides clinical sterility signaling.
- Aluminum:Lightweight extruded frames enable folding and mobile designs without sacrificing structural integrity for bariatric capacity.
Procurement volume clusters in Stainless Steel; substitution pressure builds fastest against Plastic as durability standards tighten.
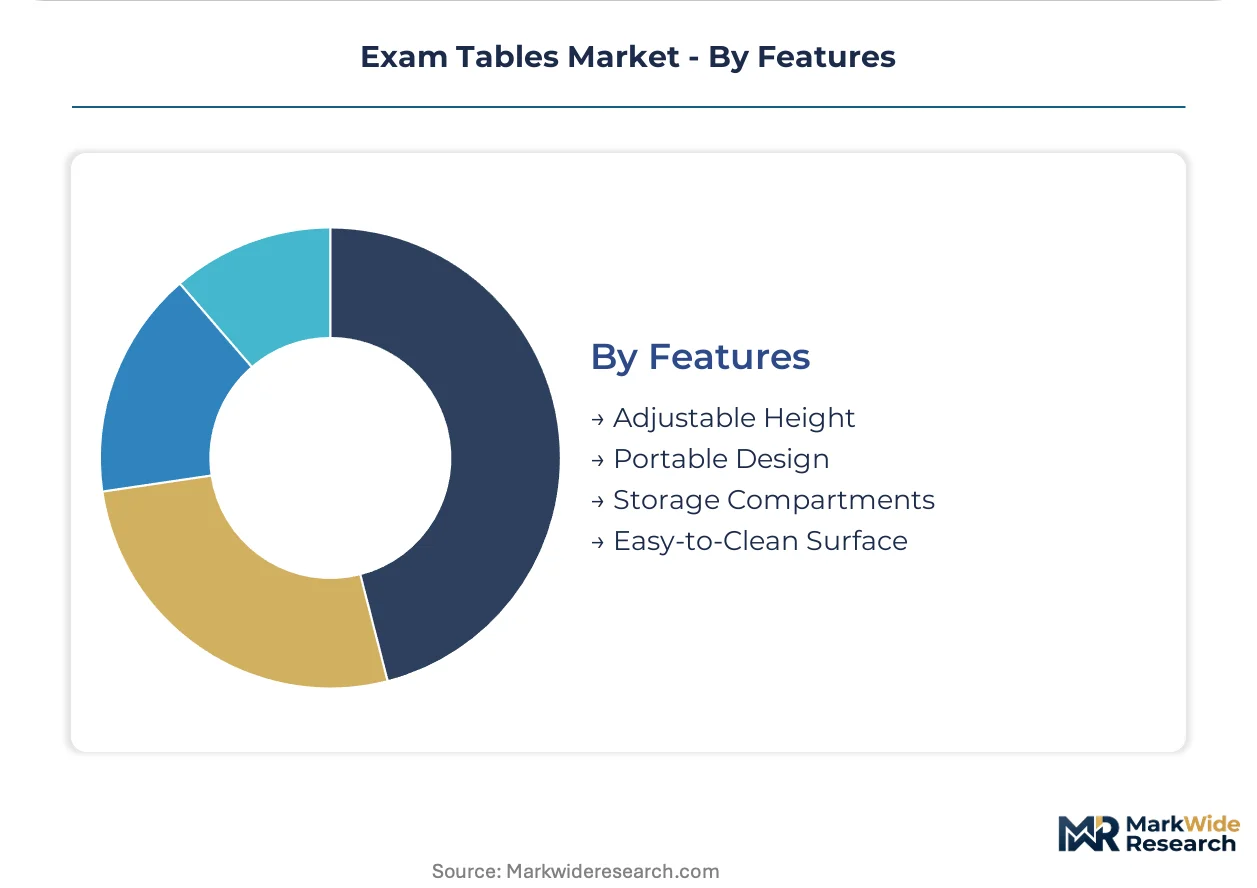
Features:
Functional specifications separate commodity purchases from premium configurations that command service contract bundling.
- Adjustable Height:Electric or hydraulic vertical travel ranges from 18 to 40 inches accommodate seated, standing, and wheelchair transfer positions. Staff injury reduction claims drive specification in United States facilities facing state-level OSHA enforcement.
- Portable Design:Castor-mounted or collapsible frames serve mobile vaccination programs and disaster response deployments where rapid site establishment outweighs fixed infrastructure investment.
- Storage Compartments:Integrated drawers and shelving reduce room clutter in space-constrained urban clinics.
- Easy-to-Clean Surface:Seamless upholstery welding and chemical-resistant coatings satisfy Joint Commission inspection protocols.
Specification frequency peaks with Adjustable Height; feature bundling expands most rapidly around Easy-to-Clean Surface as infection control audits intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States outpatient facilities concentrate replacement demand as CMS documentation mandates force powered table upgrades across aging clinic infrastructure.
United States
Texas and Florida ambulatory surgery centers drive specification for automated positioning systems that accelerate room turnover. FDA 510(k) clearance timelines averaging 180 days delay competitive feature introductions. Cleveland Clinic and Mayo Clinic procurement networks standardize electric table configurations across multi-state integrated delivery networks.
Germany
Hospital procurement offices mandate ISO 13485 certification for all powered patient-handling devices, filtering supplier pools to established manufacturers. EU MDR Article 10 technical documentation requirements extend CE marking timelines from 6 to 18 months. Baden-Württemberg medical device clusters concentrate notified body relationships that sustain market access for compliant portfolio holders.
Japan
METI efficiency standards reshape motor and actuator sourcing decisions for electric table manufacturers. PMDA quality management alignment with ISO 13485 creates parallel certification pathways for hospital procurement qualification. Osaka and Nagoya medical equipment distribution hubs consolidate vendor relationships through multi-year preventive maintenance bundling.
South Korea
Medical spa and cosmetic surgery practices in Seoul seek specialized table configurations with enhanced patient comfort features distinct from acute-care specifications. MFDS medical device registration requirements govern powered table introductions for clinical settings. Gangnam district aesthetic medicine clusters generate demand for wellness-oriented upholstery and positioning systems.
Brazil
Mobile health outreach programs prioritize folding table configurations for temporary clinic deployments and vaccination campaigns. ANVISA medical device registration creates compliance thresholds for electric table imports. São Paulo state health department procurement concentrates demand for portable aluminum-frame designs serving community health programs.
Exam Tables Market Competitive Landscape
United States producers anchor premium-tier supply; European specialists hold certification-dependent positions in regulated procurement channels. The vendor base splits between diversified medical device conglomerates with notified body relationships and mid-tier domestic fabricators serving price-sensitive clinic segments. Three archetypes dominate: integrated conglomerates with full patient-handling portfolios, regional specialists in aesthetic and wellness configurations, and scale-driven manufacturers with captive North American production. Consolidation pressure intensifies through multi-year equipment lease bundling and vertical integration into upholstery and actuator supply chains.
Among diversified medical device conglomerates, Stryker Corporation and STERIS plc exemplify archetypes with established regulatory compliance infrastructure. Midmark Corporation represents domestic manufacturing scale advantages in North American clinic procurement channels. These three anchors illustrate how certification depth, geographic production positioning, and service contract bundling separate sustainable market presence from marginal supplier status.
| Leading Market Players |
|---|
| Stryker Corporation |
| STERIS plc |
| Midmark Corporation |
| Getinge AB |
| Skytron LLC |
| Cardinal Health, Inc. |
| United Metal Fabricators, Inc. |
| Invacare Corporation |
| Lemi Group |
| Others |
Supply & Pricing Matrix
Copper winding and permanent magnet price indices cascade through electric motor production costs, compressing margins on mid-range powered tables where German and Japanese hospital procurement mandates ISO 13485 certification as a non-negotiable gate. This raw-material volatility stratifies pricing power: certified manufacturers with notified body relationships defend premium positioning through service-contract bundling, while uncertified fabricators absorb cost spikes in price-sensitive clinic segments.
Pricing Analysis
Volume concentrates in economy-tier folding tables for Brazilian mobile health programs and rural United States clinics, while margins accrue to premium electric configurations with integrated scale systems and automated documentation. Price differentiation hinges on ISO 13485 certification grade and after-sales service bundling. Cost compression in mid-range hydraulic segments is intensifying because electric motor substitution accelerates where CMS documentation mandates drive replacement cycles. Price sensitivity peaks among temporary clinic deployments prioritizing storage density over feature depth; least sensitivity sits with integrated delivery networks standardizing electric configurations across multi-state hospital systems.
Supply Chain Analysis
Direct-to-hospital channels handle integrated delivery network demand in Texas and Florida, while distributor-mediated flows serve fragmented clinic procurement in rural United States markets. Manufacturing concentrates in the United States for domestic regulatory proximity, Germany for EU MDR compliance infrastructure, and China for aluminum frame and electric actuator component sourcing. Steel frame production draws from domestic mills, antimicrobial upholstery from specialized coating facilities, and programmable control systems from industrial automation clusters. Single-source vulnerability concentrates in notified body relationships for CE marking, where EU MDR designation delays extend compliance timelines. Distribution runs through GPO contracts for hospital systems and direct manufacturer relationships for ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric exam tables with sensor-integrated actuation and Bluetooth-enabled data transmission are displacing legacy manual and hydraulic alternatives as CMS reimbursement rules harden documentation requirements across United States outpatient settings.
For Market Incumbents: Deploy multi-year equipment lease bundling to lock in ambulatory surgery center contracts before smaller competitors secure notified body relationships. Defend margin position by anchoring domestic manufacturing scale in North American clinic segments where FDA 510(k) clearance timelines deter rapid competitive response. Deepen backward integration into antimicrobial upholstery supply to constrain mid-tier fabricator access to EPA-registered coating technologies. For New Entrants and Emerging Players: Begin with aesthetic and wellness table configurations in Seoul's Gangnam district medical spa clusters, where acute-care certification requirements do not apply and patient comfort perception commands premium positioning. Target Brazilian mobile health outreach programs with portable aluminum-frame designs that bypass ANVISA registration complexity for electric imports. Lead with direct-to-clinic digital marketing rather than GPO channel dependence. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier domestic fabricators with established North American clinic relationships but lagging EU MDR compliance infrastructure, particularly in United States manufacturing corridors facing capital expenditure constraints. Long-term viability hinges on certification depth rather than volume scale, as procurement gates consolidate demand around ISO 13485-compliant portfolios. Monitor notified body designation timelines as the critical inflection signal for European market access viability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 compliance sustains market access for powered table portfolios in German hospital procurement. |
| Hospital System Partnership | Multi-year service contracts with Cleveland Clinic and Mayo Clinic networks standardize electric configurations across facilities. |
| Software Companion Development | Bluetooth-enabled data transmission to electronic health records automates CMS documentation workflows for reimbursement. |
| Reimbursement Strategy | Patient positioning equipment logs align with tightening CMS outpatient clinic mandates in United States markets. |
| Backward Integration | In-house antimicrobial upholstery production constrains EPA registration timelines and accelerates design iteration cycles. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and outpatient clinic administrators. FDA 510(k) premarket notification databases, CMS Medicare reimbursement documentation, EU MDR technical filing records, and ISO 13485 certification registries provided structured validation points. Bottom-up shipment data from electric motor and actuator suppliers reconciled against top-down hospital capital expenditure surveys across the analysis window.
Data-stream reconciliation between procurement database extracts and manufacturer shipment reports shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include power source technology, institutional end-user scale, frame material metallurgy, and integrated feature bundling. CAGRs derived from logistic diffusion curves fitted to powered table replacement cycles and regulatory mandate implementation timelines. Motor efficiency standards from METI and California energy commissions, plus antimicrobial coating EPA registration pipelines, informed scenario-weighted outputs.
Underlying measurement precision varies by segment; electric exam tables with integrated scale systems carry tighter precision than folding alternatives where temporary deployment patterns fragment demand signals. Forecasts reflect assumptions regarding CMS documentation enforcement intensity, EU MDR notified body capacity expansion, and copper-magnet commodity price stabilization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Europe Upholstered Furniture Market
Furniture
Global Folding Furniture Market
Furniture
Poland Home Furniture Market
Furniture
Japan Home Furniture Market
Furniture
Germany Home Furniture Market
Furniture
Canada Home Furniture Market
Furniture
High End Furnitures Market
Furniture
Europe Sustainable Home Furniture Market
Furniture
Taiwan Home Furniture Market
Furniture
Furniture & Cabinet Hardware Market
Furniture
Spain Furniture Market
Furniture
UAE Luxury Furniture Market
Furniture
Asia-Pacific Home Furniture Market
Furniture
Global Multifunctional Home Furniture Market
Furniture
UK Multifunctional Furniture Market
Furniture
Portering Chair Market